
 Dozer Blade Market | 2026-2036
Dozer Blade Market Size, Share, and Industry Trends Forecast 2026-2036
Dozer Blade Market Analytics
Aftermarket service contracts and predictive maintenance subscriptions is consolidating revenue streams around uptime guarantees rather than pure equipment sales. Caterpillar leverages its dealer network to lock in long-term service agreements across North American mining accounts. Komatsu sustains competitive pressure through its KOMTRAX telematics platform that ties blade wear data to replacement scheduling. Deere & Company anchors its position in agricultural applications with seasonal service bundles that reduce downtime during planting and harvest windows.
A dozer blade is a hydraulically actuated earthmoving attachment mounted to the front of a crawler tractor, typically fabricated from high-tensile steel plate with hardened cutting edges and tilt/pitch mechanisms to control material flow. The assembly functions to push, spread, and grade soil, rock, or overburden across construction sites, surface mines, and land development projects. Universal blade configurations command the largest share of product type demand due to their versatility in both carrying and rolling material across varied terrain. Heavyweight capacity segments generate disproportionate margin pools as mining customers prioritize durability and load-bearing specifications over initial procurement cost. Composite material adoption remains nascent but is expanding in lightweight applications where fuel efficiency penalties from steel mass prove prohibitive.
EPA emission regulations and EU Stage V standards compel manufacturers to reduce implement weight as a pathway to meeting tractor-level fuel consumption targets, directly influencing blade design priorities. China's MIIT enforces GB standards for construction machinery structural integrity that blade suppliers must certify before domestic market entry. ISO 7135 and SAE J729 define dimensional and performance baselines that govern cross-border equipment compatibility and aftermarket parts interchangeability. Stakeholders should monitor how emission compliance timelines in Europe and North America accelerate material substitution decisions that could displace conventional steel fabrication.
Market Dynamics
Emission compliance deadlines in North America and Europe are compressing product development cycles and forcing material substitution decisions that redefine blade weight-to-performance ratios. OEMs must now certify lighter designs without sacrificing structural integrity under ISO 7135 and SAE J729 standards.
Growth Catalysts
- EPA Tier 4 Final:Mining operators in Australia face fleet replacement mandates that accelerate procurement of high-capacity blades meeting the latest emission thresholds.
- Telematics integration:Blade wear monitoring systems enable predictive maintenance contracts that lock in recurring revenue streams across Chilean surface operations.
- China's western provinces:State-funded infrastructure corridors in Xinjiang and Sichuan require expanded earthmoving capacity, concentrating demand for universal blade configurations.
Market Restraints
- High-tensile steel price volatility:Input cost swings for specialized alloy plate compress margin buffers for fabricators serving price-sensitive construction segments.
- Supply concentration:Hardened cutting edge production clusters in select East Asian forging centers create vulnerability to regional logistics disruptions.
- Technical limitation:Composite material fatigue resistance under extreme impact loading remains unproven for heavyweight mining applications, slowing substitution.
Strategic Opportunities
- Underpenetrated agriculture:Brazilian soybean expansion regions present untapped demand for seasonal blade service bundles tied to planting windows.
- EU Stage V tailwind:European emission mandates create first-mover advantage for suppliers with certified lightweight blade designs.
- Channel innovation:Direct-to-fleet digital procurement platforms in North American mining bypass traditional dealer markups and compress sales cycles.
Industry Challenges
- Welding automation skill gap:Shortage of certified operators for robotic fabrication of high-tensile steel assemblies limits production scaling.
- Certification timeline compression:Simultaneous GB standard compliance for China and EPA certification for North America strains engineering bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dozer Blade Market |
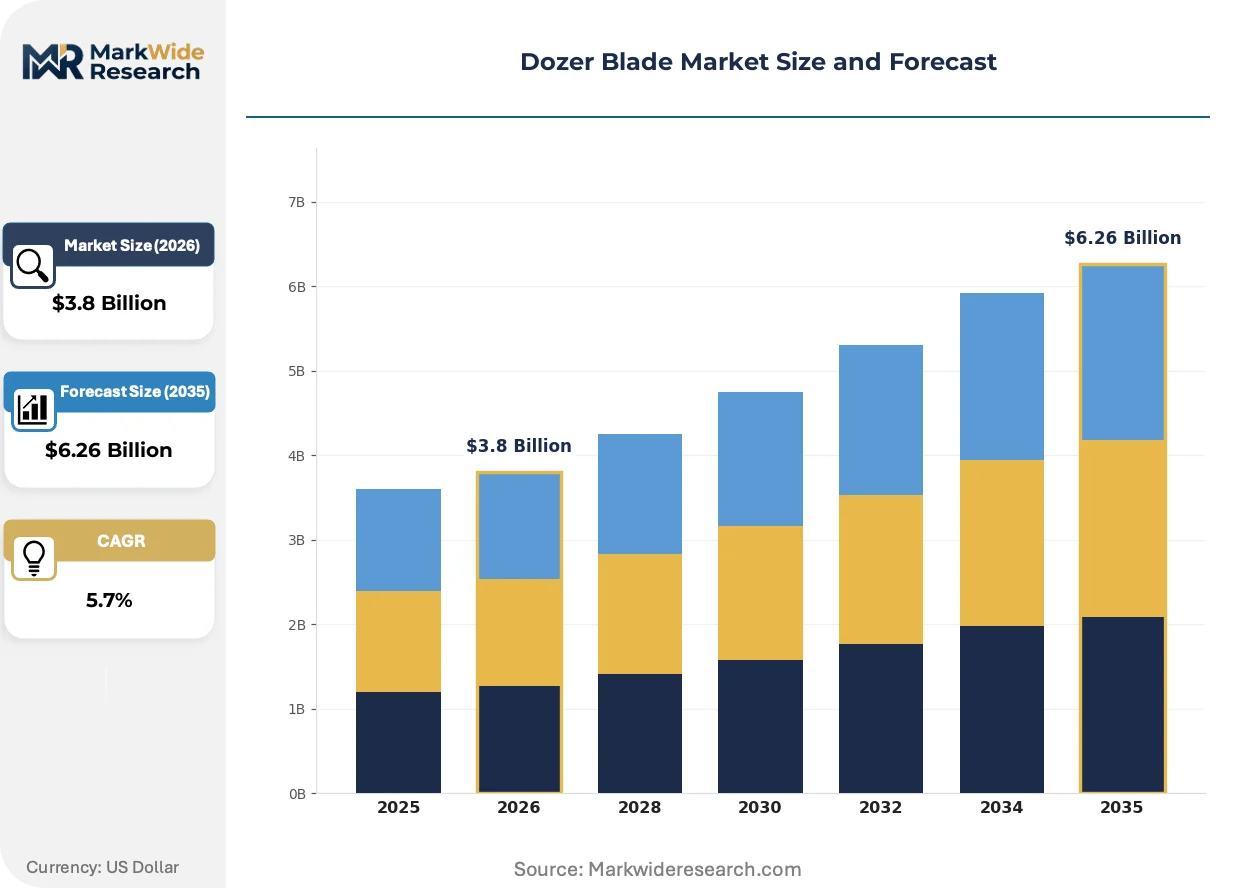
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Box Blade, Straight Blade, Universal Blade, Angle Blade Material: Steel, Durable Alloy, Plastic, Composite Application: Construction, Mining, Agriculture, Land Clearing Capacity: Lightweight, Medium, Heavyweight, Ultra Heavy |
| Companies Covered | Caterpillar, Komatsu, Deere & Company, Liebherr Group, XCMG Group, Sany Construction, Shantui Construction Machinery, Volvo Construction Equipment, Hitachi Construction Machinery, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dozer Blade Market Evolving Landscape
Digital integration and material science advances are redefining how blade performance is measured, monetized, and maintained across the equipment lifecycle. The shift from hardware-only sales to outcome-based relationships is accelerating.
Telematics-enabled wear tracking is decentralizing maintenance scheduling away from fixed-hour intervals toward condition-based interventions. Mining operators in Australia and Chile now receive automated replacement alerts tied to actual cutting edge degradation rather than calendar estimates. This compression of information asymmetry between operators and service providers is flattening traditional dealer hierarchies and enabling direct manufacturer-to-fleet relationships.
REACH substance restrictions in Europe are forcing reformulation of surface coatings and hydraulic fluids used in blade tilt mechanisms. The regulation's industrial consequence is a supply chain scramble for compliant alternatives that meet SAE J729 performance baselines. Surface mining OEMs serving EU markets are responding by dual-sourcing certified component streams and accelerating in-house coating capability development.
Buyer consolidation among North American mining conglomerates is compressing vendor qualification timelines and demanding unified fleet data standards. Traditional equipment dealers are losing exclusivity as procurement teams centralize blade specification authority at corporate headquarters. This pattern is most visible in copper and iron ore operations where parent companies mandate cross-site parts interchangeability to reduce inventory duplication.
Dozer Blade Market Segmentation
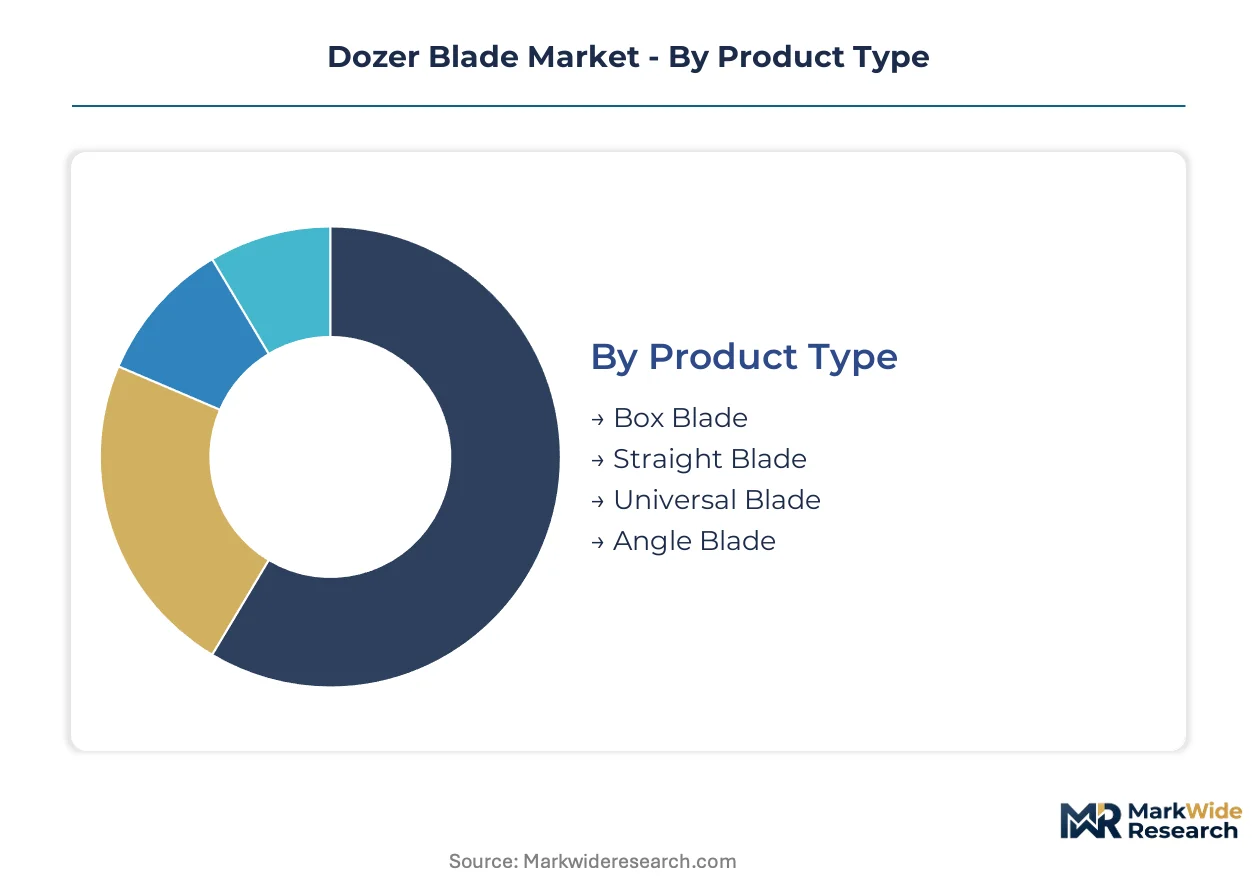
Dozer blade procurement decisions hinge on matching implement specifications to tractor power classes, soil abrasiveness, and duty cycle intensity. Segmentation reveals where engineering complexity translates to pricing power versus commoditized volume plays.
Product Type:
Customization intensity varies sharply across this category, from purpose-built mining configurations to generalist designs serving mixed fleets.
- Universal Blade:Fabricated with curved moldboard geometry and reinforced side plates to enable both carrying and rolling material. Demand concentrates in China's western provinces where state-funded infrastructure corridors require versatile earthmoving across variable terrain from Xinjiang desert to Sichuan highlands.
- Box Blade:Enclosed end plates create contained material transport for precision grading. Australian surface mining operators specify these for haul road maintenance where spillage control reduces rework cycles.
- Straight Blade:Flat moldboard profile optimized for forward pushing and dozing in confined construction sites.
- Angle Blade:Tilt-capable design for side-casting material in land clearing and right-of-way maintenance.
Most installed capacity flows through Universal Blade configurations. Expansion is steepest in Box Blade specifications for precision mining applications.
Material:
Cost tiers separate commodity fabrications from performance-optimized alloys and experimental composites.
- Steel:High-tensile plate construction dominates volume production with proven fatigue resistance under cyclic loading. Construction segments in price-sensitive markets resist substitution despite weight penalties.
- Durable Alloy:Hardened through-thickness plate with enhanced wear characteristics extends cutting edge replacement intervals. Mining fleets in Chile prioritize these specifications where abrasive volcanic rock accelerates component degradation.
- Composite:Fiber-reinforced polymer matrices reduce implement mass for fuel efficiency compliance with EPA Tier 4 Final and EU Stage V tractor standards.
- Plastic:Limited to agricultural finishing applications where impact loading remains minimal and corrosion resistance matters.
Steel retains the largest installed base. Composite adoption is climbing fastest where emission regulations penalize implement mass.
Application:
Customer type determines margin structure, from capital-intensive mining procurement teams to seasonal agricultural buyers.
- Mining:High-impact, continuous-duty specifications with hardened cutting edges and structural reinforcement. Australian iron ore and Chilean copper operations drive demand for heavyweight configurations with predictive maintenance integration.
- Construction:Mixed fleet deployments requiring rapid attachment interchangeability across grading, excavation, and backfilling tasks.
- Agriculture:Seasonal intensity patterns in Brazilian soybean expansion regions create demand for service-bundled procurement during planting windows.
- Land Clearing:Vegetation and debris handling with specialized guarding against stump impact damage.
Mining absorbs the highest absolute volume. Agriculture is gaining share fastest through mechanization in previously manual clearing regions.
Capacity:
Maturity gradients separate established lightweight and heavyweight categories from emerging ultra-heavy specifications.
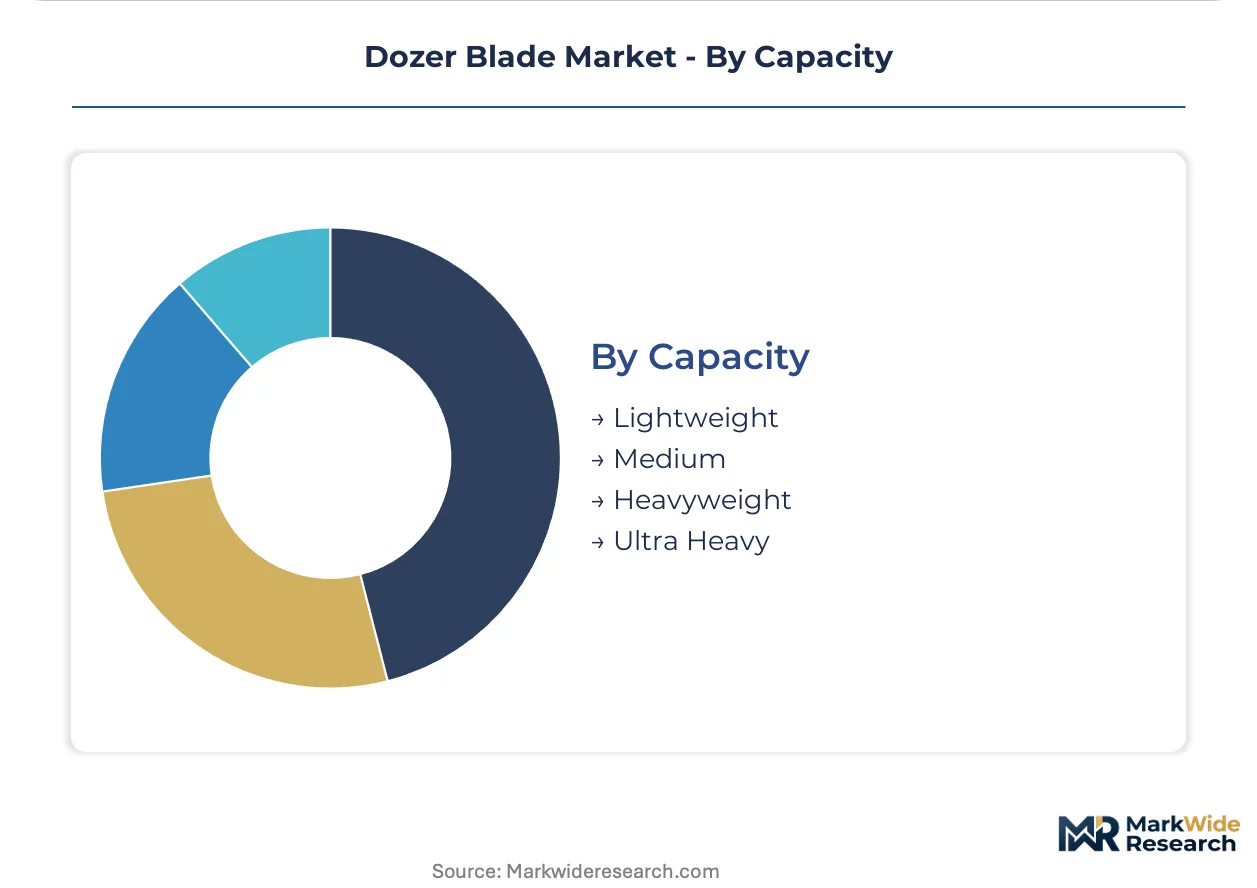
- Heavyweight:Reinforced frame structures and thickened moldboard plate for sustained loading in surface mining. These specifications command disproportionate margin pools as durability trumps first-cost in procurement evaluations.
- Ultra Heavy:Custom-engineered for the largest crawler tractor classes in iron ore and oil sands operations where single-pass volume determines fleet productivity.
- Medium:General-purpose balancing of maneuverability and material capacity for mixed construction fleets.
- Lightweight:Reduced mass for fuel efficiency and transportability in agricultural and utility applications.
Heavyweight capacity represents the dominant revenue pool. Ultra Heavy is expanding most quickly as mining tractor power classes climb.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage pressures are redistributing dozer blade fabrication capacity toward jurisdictions where emission compliance costs remain manageable. Fabricators in lower-cost compliance zones now supply components to OEMs facing EU Stage V and EPA Tier 4 Final mandates in their home markets.
United States
Surface mining conglomerates in Arizona and Minnesota are consolidating fleet procurement authority at corporate headquarters. EPA Tier 4 Final deadlines are accelerating replacement cycles for high-capacity blades in copper and iron ore operations. Fabrication clusters in the Great Lakes region specialize in hardened cutting edge assemblies for extreme-abrasion applications.
China
State-funded infrastructure corridors in Xinjiang and Sichuan are driving universal blade demand across variable terrain from desert to highland. MIIT enforces GB standards for structural integrity certification before domestic market entry. Xuzhou and Changzhou manufacturing bases supply both domestic OEMs and export markets with reinforced moldboard assemblies.
Australia
Iron ore operators in Western Australia's Pilbara region are expanding predictive maintenance integration for blade wear monitoring. Fleet replacement mandates tied to emission thresholds are compressing procurement timelines. Perth-based service hubs coordinate blade specification standardization across multinational mining parent companies.
Germany
EU Stage V compliance is forcing material substitution toward lighter blade designs without sacrificing ISO 7135 structural baselines. REACH substance restrictions are reformulating surface coatings for tilt mechanism hydraulic systems. Engineering centers in Munich and Stuttgart specialize in simulation-driven weight reduction for premium tractor classes.
Chile
Copper surface mining in the Atacama Desert prioritizes durable alloy specifications where volcanic rock accelerates cutting edge degradation. Telematics-enabled wear tracking is enabling condition-based replacement scheduling. Antofagasta and Santiago procurement offices are centralizing blade specification authority for multinational mining groups.
Dozer Blade Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments. Mining procurement teams favor integrated OEM blade systems with predictive maintenance bundling, while construction fleets source interchangeable attachments through dealer networks. Three archetypes dominate: full-line construction equipment OEMs with captive blade production, specialized attachment fabricators serving mixed fleets, and regional steel processors supplying raw components. Capacity expansion and strategic partnerships represent the primary competitive vectors as fabricators seek certified lightweight designs.
Among diversified construction equipment manufacturers, Caterpillar, Komatsu, and Deere & Company exemplify contrasting strategic positions. Caterpillar represents the integrated OEM archetype with dealer-networked service bundling. Komatsu occupies a position emphasizing telematics-enabled lifecycle management. Deere & Company anchors the agricultural-specialist vector with seasonal service integration.
| Leading Market Players |
|---|
| Caterpillar |
| Komatsu |
| Deere & Company |
| Liebherr Group |
| XCMG Group |
| Sany Construction |
| Shantui Construction Machinery |
| Volvo Construction Equipment |
| Hitachi Construction Machinery |
| Others |
Value Network & Pricing Analysis
Robotic welding automation for high-tensile steel assemblies is compressing fabrication labor costs while concentrating certified production capacity in select East Asian forging centers. This simultaneous cost reduction and geographic clustering reshapes how OEMs negotiate blade procurement terms across emission-regulated markets.
Pricing Analysis
Dealer markup layers absorb margin in traditional distribution channels serving price-sensitive construction segments. Three-tier pricing structure across premium, standard, and economy levels separates mining-grade durable alloy specifications from agricultural utility configurations. Cost compression in standard-grade steel blades intensifies because high-tensile alloy plate volatility erodes fabricator buffers. Agricultural buyers in Brazilian expansion zones exhibit highest price sensitivity, while Australian iron ore operators prioritize durability over first-cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale mining fleet demand, bypassing traditional distributor hierarchies. Hardened cutting edge production clusters in China, South Korea, and Japan. Fabrication draws from specialized high-tensile steel plate, hardened alloy bar stock, and hydraulic cylinder subassemblies. Single-source vulnerability concentrates in East Asian forging centers for critical wear components. Distribution runs through captive OEM networks for mining accounts and independent dealer channels for mixed construction fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA Tier 4 Final and EU Stage V emission deadlines compound procurement urgency, forcing fleet replacement decisions that favor suppliers with certified lightweight designs and predictive maintenance integration.
For Market Incumbents: Anticipate margin compression from composite material substitution by locking in long-term service contracts that monetize uptime guarantees rather than hardware margins. Defend position through backward integration into hardened cutting edge production, reducing exposure to East Asian forging center volatility. Prioritize certification bandwidth for simultaneous GB standard compliance and EPA Tier 4 Final approval.
For New Entrants and Emerging Players: Independent telematics platforms offer partnership pathways to bypass entrenched dealer networks and capture direct fleet relationships. Brazilian agricultural expansion regions present the most penetrable white space, with seasonal service bundling as the viable go-to-market angle. Target precision mining applications in Chilean copper operations where condition-based replacement scheduling commands premium positioning.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional steel processors with certified robotic welding capacity and dormant OEM relationships. Long-term viability hinges on regulatory tailwinds persisting across emission compliance timelines. Acquisition target archetype: mid-cap fabricators with GB standard certification and underutilized capacity in China's western manufacturing bases. Signal to monitor: mining procurement team consolidation accelerating direct manufacturer-to-fleet contracting.
| Strategic Initiative | Industry Significance |
|---|---|
| Certification Investment | Dual GB standard and EPA Tier 4 Final approval unlocks China and North American mining procurement simultaneously. |
| Predictive Maintenance Platform | KOMTRAX-style telematics integration transforms blade sales into recurring revenue through wear-data subscriptions. |
| Backward Integration | In-house hardened cutting edge production insulates margins from East Asian forging center supply shocks. |
| Lightweight Material R&D | Composite fatigue resistance breakthroughs enable EPA Tier 4 Final compliance without sacrificing ISO 7135 structural integrity. |
| Direct-to-Fleet Digital Channel | Bypassing dealer markups compresses sales cycles for North American mining conglomerates with centralized procurement authority. |
Research Methodology
Coverage spans North America, Europe, Asia-Pacific, and Latin America, with primary inputs from each region combined with secondary validation. Primary interviews incorporated maintenance directors at Australian iron ore operations, OEM procurement teams at Caterpillar and Komatsu, aftermarket service heads at Chilean copper mines, and plant engineers at Chinese manufacturing bases. Secondary sources included SEC 10-K filings, customs and trade data for steel plate imports, MIIT GB standard documentation, and EPA certification records. Bottom-up blade shipment data triangulated against top-down mining fleet replacement schedules.
Rate-of-change decomposition separated volume growth from price-mix effects across the projection horizon. Segmentation dimensions modeled include product type, material grade tier, application intensity, and regional regulatory cluster. CAGRs derived from equipment replacement cycle analysis, emission compliance deadline mapping, and infrastructure spending trajectory assessment. Industry-specific inputs incorporated tractor power class evolution and telematics penetration curves.
Revisions become necessary when emission compliance timelines shift, steel alloy prices experience sustained volatility, or composite material fatigue resistance achieves mining-grade certification. Forecasts reflect assumptions about regulatory enforcement consistency and infrastructure spending continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Stud Welding Machine Market
Construction Equipment
Commercial Laundry Machines Market
Construction Equipment
Concrete Placing Booms Market
Construction Equipment
Global Crane Market
Construction Equipment
Drone-Based Solutions in Construction Market
Construction Equipment
Walform Machines Market
Construction Equipment
Vietnam Crane Market
Construction Equipment
Gear Shaping Machine Market
Construction Equipment
Mill Pulverizer Market
Construction Equipment
PU Casting Machine Market
Construction Equipment
China Elevator Ropes Market
Construction Equipment
Winch Market
Construction Equipment
Middle East and Africa Rough Terrain Cranes Market
Construction Equipment
Solar Pile Driving Equipment Market
Construction Equipment
Global Welding Market
Construction Equipment
Malaysia Plastic Injection Molding Machine Market