
 Mobile Elevating Work Platform (MEWP) Market | 2026-2036
Mobile Elevating Work Platform (MEWP) Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Elevating Work Platform (MEWP) Market Insights
China is reshaping competitive dynamics through expanded domestic manufacturing capacity for boom and scissor lift platforms. JLG Industries leverages extensive North American distribution networks to sustain aftermarket service revenue. XCMG Machinery anchors cost-competitive positioning across Asia-Pacific rental channels. Haulotte Group specializes in compact electric vertical mast lifts for European urban job sites where emissions restrictions tighten.
A mobile elevating work platform is a motorized, vehicle-mounted or self-propelled aerial device designed to lift personnel, tools, and materials to elevated work positions, with working heights typically spanning 20 to 185 feet depending on boom or scissor configuration. Scissor lifts dominate volume sales across warehousing and manufacturing end users due to straightforward vertical trajectory and stable platform geometry. Boom lifts capture premium pricing in infrastructure development and maintenance operations where horizontal outreach and up-and-over capability prove essential. Electric power sources are displacing diesel in indoor applications as lithium-ion battery density improves and facility managers prioritize zero-emission fleet standards.
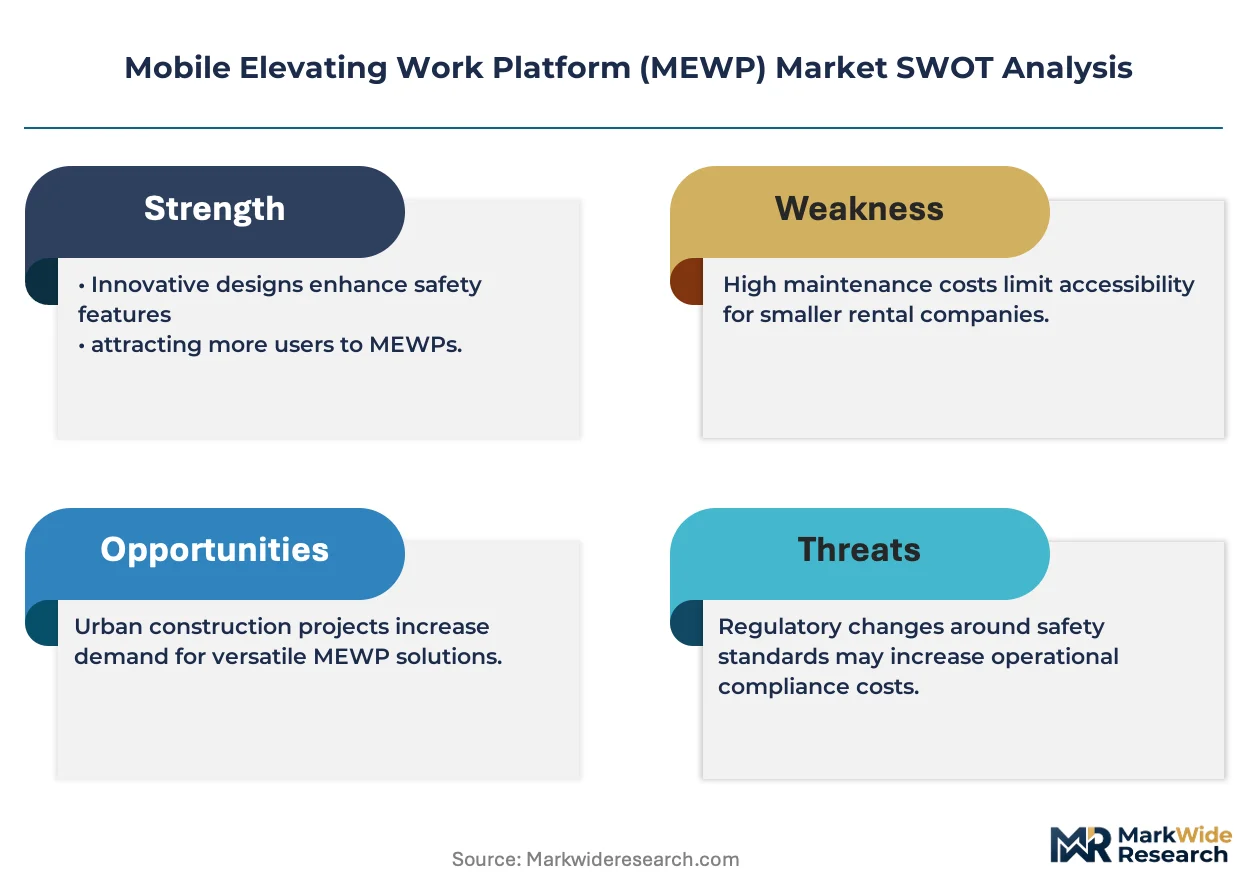
OSHA standards in the United States mandate guardrail systems and fall arrest compatibility, while the EU Machinery Directive and CE marking requirements enforce stability testing and emergency lowering protocols across European sales. China's GB standards and MIIT equipment certification shape product specifications for domestic manufacturers and import eligibility. Stakeholders must monitor evolving battery safety regulations and regional carbon-border adjustments that will redefine total cost of ownership calculations for fleet operators.
Market Dynamics
Electric powertrain conversion is compressing fleet replacement cycles across rental and contractor segments as lithium-ion energy density climbs and indoor emissions mandates harden.
Growth Catalysts
- OSHA Fall-Protection Mandates:Tightening guardrail and fall-arrest requirements in the United States are accelerating scissor lift refresh rates among construction firms and facility managers.
- Data Center Construction:Hyperscale cloud infrastructure builds in Northern Virginia and Dallas-Fort Worth are generating concentrated demand for compact vertical mast lifts with zero-emission operation.
- Lithium-Ion Battery Chemistry:Improved cell energy density is extending runtime per charge for electric scissor lifts, enabling full-shift operation without midday swapping.
Market Restraints
- Steel and Aluminum Input Volatility:Platform chassis fabrication depends on rolled steel and extruded aluminum pricing, which fluctuates with commodity exchange movements and energy costs.
- Supply Concentration in Hydraulic Systems:Precision hydraulic cylinder manufacturing clusters in Germany and Japan, creating lead-time exposure for boom lift producers.
- Substitution from Drone Inspection:Aerial photography and thermal imaging drones are capturing some routine infrastructure survey work previously requiring manned platform access.
Strategic Opportunities
- India Warehouse Automation:E-commerce fulfillment center construction in Mumbai and Delhi-NCR remains underpenetrated for MEWP rental penetration relative to parcel volume growth.
- EU Green Deal Procurement Rules:Public infrastructure tenders across France and Germany now embed carbon-footprint scoring that favors electric and hybrid platform fleets.
- Telematics-Converged Fleet Management:IoT-enabled utilization tracking and predictive maintenance algorithms are opening subscription revenue streams for equipment lessors.
Industry Challenges
- Certified Technician Shortage:MEWP operator training and annual recertification requirements outpace vocational program throughput in several state markets.
- Legacy Fleet Integration:Rental companies managing mixed diesel-electric inventories face charging infrastructure capex and depot electrical upgrade complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Elevating Work Platform (MEWP) Market |
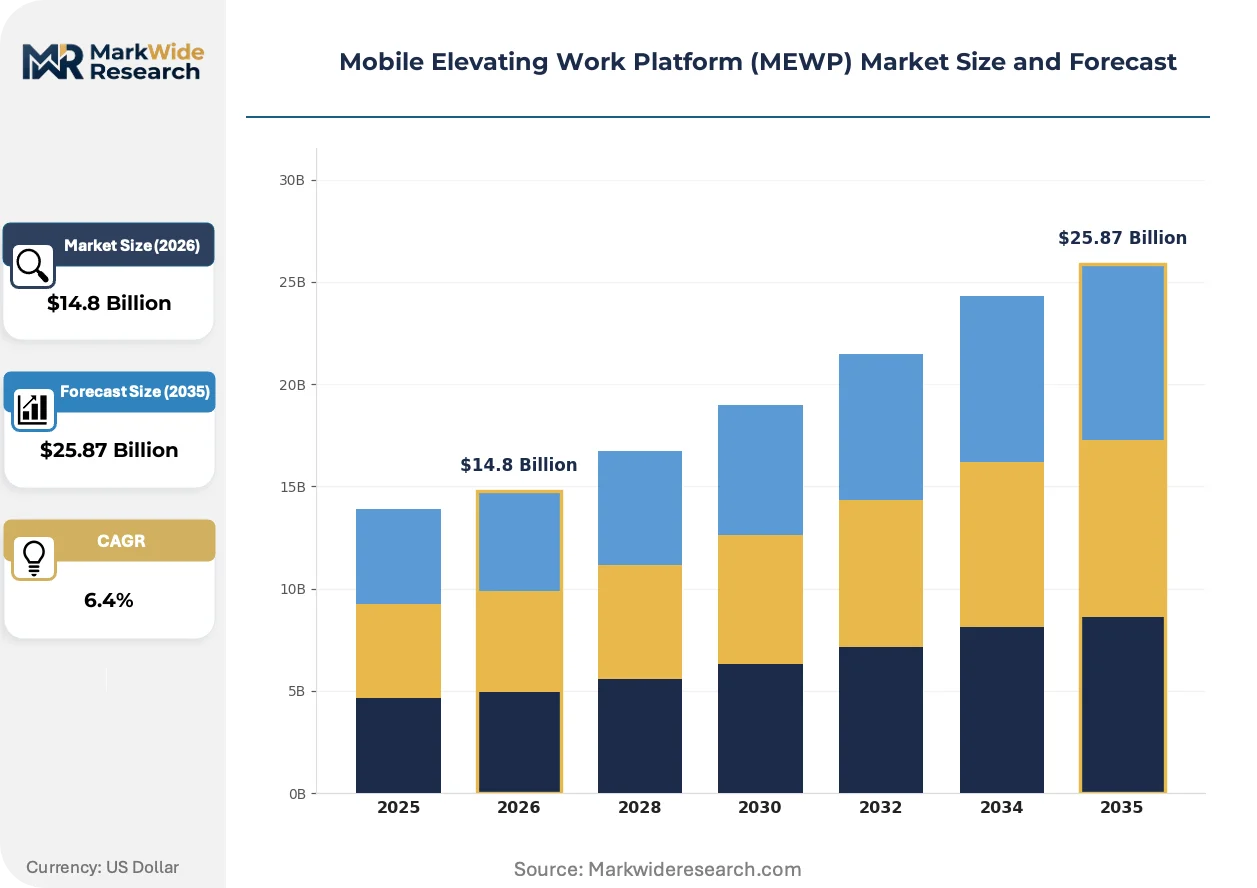
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $25.87 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Scissor Lifts, Boom Lifts, Trailer Mounted Lifts, Vertical Mast Lifts End User: Construction, Manufacturing, Maintenance, Warehousing Power Source: Electric, Diesel, Hybrid, Gas Application: Maintenance Operations, Construction Work, Infrastructure Development, Industrial Cleaning |
| Companies Covered | JLG Industries, Genie, Terex, Haulotte Group, Skyjack, XCMG Machinery, Sinoboom Intelligent Equipment, Aichi Corporation, MEC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Elevating Work Platform (MEWP) Market Trends and Innovations
Platform intelligence and powertrain electrification are converging to redefine fleet economics and operator safety protocols across rental and direct-purchase channels.
Lithium-ion battery systems are migrating from niche indoor applications to mainstream outdoor construction fleets as fast-charging infrastructure spreads and total cost of ownership calculations favor electric over diesel maintenance. Mid-size rental companies in California and Texas are piloting all-electric boom lift deployments on solar farm and warehouse projects. This transition is compressing residual value premiums for late-model diesel units and accelerating auction market segmentation.
CE marking requirements under the EU Machinery Directive are tightening stability testing protocols and emergency descent verification for all aerial work platforms sold in member states. Manufacturers must now submit third-party witnessed tilt-table testing documentation before market entry. Scissor lift producers serving German municipal customers report six-month certification timeline extensions and expanded documentation costs.
Rental channel consolidation is compressing regional independent operator margins as national fleet lessors deploy telematics-enabled yield management and dynamic pricing algorithms. Equipment procurement committees at multi-site logistics firms now favor single-source national contracts with guaranteed uptime service level agreements over fragmented local supplier relationships. This concentration is most visible in United States distribution center corridors along Interstate 35 and Interstate 95.
Mobile Elevating Work Platform (MEWP) Market Segmentation
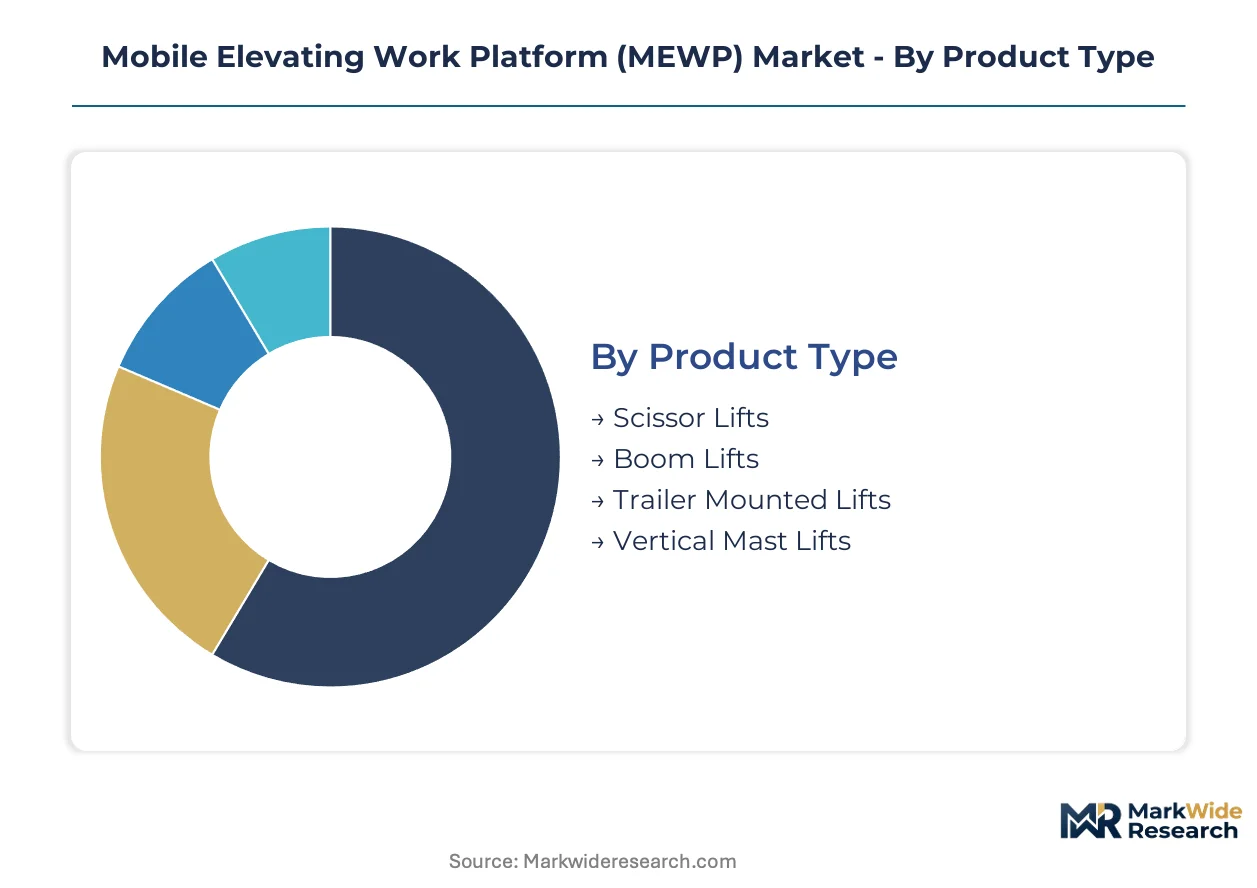
MEWP procurement patterns diverge sharply across product configurations and powertrain choices, with rental fleet managers optimizing for utilization rates while direct purchasers prioritize specification matching for fixed infrastructure cycles.
Product Type:
Scissor lifts turn over fastest in rental fleets due to standardized specifications and high depreciation schedules, while boom lifts retain residual value longer through specialized application lock-in.
- Scissor Lifts:These platforms deploy crossed-linked hydraulic arms to deliver purely vertical elevation with stable rectangular deck geometry. Demand concentrates in United States warehouse automation corridors around Dallas-Fort Worth and Central Valley California, where lithium-ion runtime improvements now enable full-shift operation without battery swaps.
- Boom Lifts:Articulating or telescopic booms provide horizontal outreach and up-and-over clearance for complex access geometries. Infrastructure maintenance contracts across German highway networks and French rail systems drive premium pricing for all-terrain diesel-electric hybrid variants with 150-foot working envelopes.
- Trailer Mounted Lifts:Compact towable units serve intermittent maintenance needs for municipal parks departments and small commercial contractors with limited capital budgets.
- Vertical Mast Lifts:Narrow single-mast configurations navigate tight aisles in European urban logistics facilities where emissions restrictions and doorway width constraints apply simultaneously.
Scissor lifts dominate installed base. Boom lifts are where expansion concentrates.
End User:
Cost tier stratification separates capital-intensive construction procurement from operational-expense-driven warehousing contracts, with maintenance operations occupying a hybrid middle ground.
- Construction:General contractors and specialty trades deploy mixed fleets across project phases, with earthwork and structural phases demanding rough-terrain diesel units while interior fit-out shifts to electric scissor lifts. OSHA fall-protection mandate compliance accelerates refresh cycles for guardrail-compatible platforms.
- Manufacturing:Automotive assembly plants and aerospace fabrication facilities specify explosion-proof electric variants for paint booth and fuel system work, with procurement committees favoring single-source national service agreements over fragmented regional suppliers.
- Maintenance:Facility management firms balance scheduled preventive access against emergency repair scenarios, creating demand volatility that favors rental channel flexibility over ownership.
- Warehousing:E-commerce fulfillment center operators in India and Southeast Asia are expanding vertical storage density faster than MEWP rental penetration, creating whitespace for equipment lessors.
Construction commands the largest equipment pool. Warehousing is climbing the fastest.
Power Source:
Volume concentration now favors electric platforms as total cost of ownership calculations incorporate carbon-border adjustments and indoor emissions enforcement.
- Electric:Lithium-ion battery systems now deliver sufficient energy density for outdoor construction shifts, with fast-charging infrastructure spreading across California solar farm projects and Texas distribution center builds.
- Diesel:Rough-terrain boom lifts for infrastructure development retain diesel dominance where torque requirements and refueling logistics outweigh electrification benefits.
- Hybrid:Dual-power units bridge indoor-outdoor applications for municipal fleets and utility contractors facing mixed regulatory environments.
- Gas:Propane and gasoline variants serve niche markets with limited electrical infrastructure or cold-weather battery performance concerns.
Electric dominates new order intake. Hybrid is gaining share fastest.
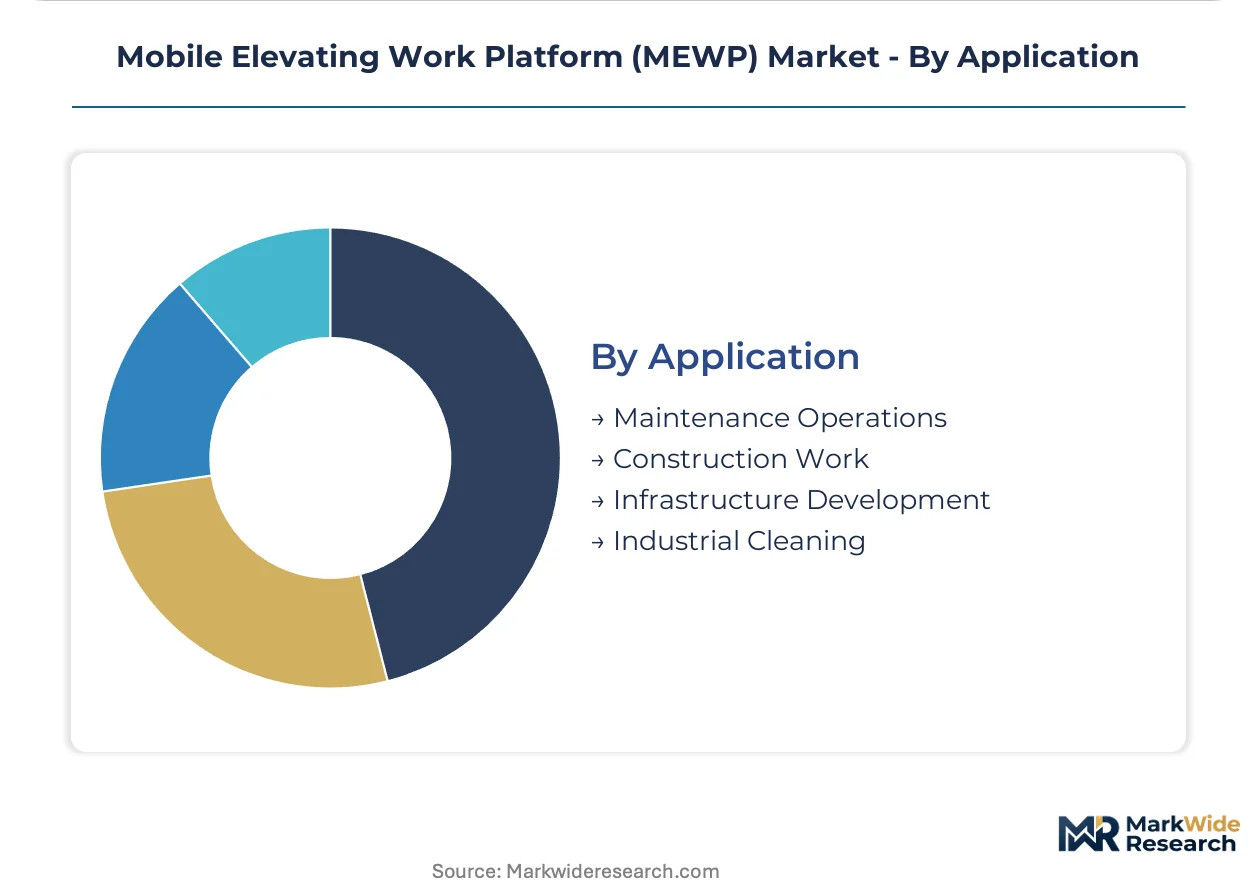
Application:
Customer type segmentation separates scheduled facility maintenance from project-based construction procurement, with industrial cleaning emerging as a specialized vertical.
- Maintenance Operations:Scheduled HVAC, lighting, and roofing access drives recurring rental demand with high telematics value capture potential through utilization tracking.
- Construction Work:Project-based procurement cycles create demand lumpiness that rental yield management algorithms increasingly smooth through dynamic pricing.
- Infrastructure Development:Highway, bridge, and utility scale projects specify heavy-lift boom capacities with extended horizontal reach for span crossing applications.
- Industrial Cleaning:Tank, silo, and facade cleaning operations require washdown-rated platforms with corrosion-resistant finishes and enclosed drive systems.
Maintenance Operations anchor recurring revenue. Infrastructure Development shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OSHA fall-protection mandates in the United States anchor the dominant geography, while construction booms and warehouse automation reshape demand patterns across specific national markets. Fleet procurement concentrates where regulatory enforcement tightens and infrastructure investment accelerates.
United States
Data center construction in Northern Virginia and Dallas-Fort Worth drives concentrated demand for compact vertical mast lifts with zero-emission operation. OSHA guardrail and fall-arrest requirements accelerate refresh cycles for construction firms and facility managers. Warehouse automation corridors along Interstate 35 and Interstate 95 favor single-source national rental contracts with guaranteed uptime service level agreements.
Germany
Highway network maintenance contracts and rail system upgrades generate premium pricing for all-terrain diesel-electric hybrid boom lifts with extended working envelopes. CE marking requirements under the EU Machinery Directive enforce tilt-table stability testing and emergency descent verification protocols. Industrial clusters in Bavaria and North Rhine-Westphalia host municipal procurement committees embedding carbon-footprint scoring into public infrastructure tenders.
China
Domestic manufacturing capacity expansion for boom and scissor lift platforms reshapes competitive dynamics across Asia-Pacific rental channels. MIIT equipment certification and GB standards shape product specifications for local producers and import eligibility. Yangtze River Delta and Pearl River Delta production bases supply cost-competitive platforms to Southeast Asian and Middle Eastern markets.
India
E-commerce fulfillment center construction in Mumbai and Delhi-NCR outpaces MEWP rental penetration relative to parcel volume growth, creating whitespace for equipment lessors. BIS safety standards and state-level factory regulations govern platform deployment in manufacturing zones. Karnataka and Tamil Nadu automotive assembly plants specify explosion-proof electric variants for paint booth and fuel system applications.
France
Public infrastructure tenders embed EU Green Deal procurement rules favoring electric and hybrid platform fleets for bridge and utility maintenance. ANSM workplace safety protocols align with CE marking requirements for aerial work platform stability verification. Urban logistics facilities in Île-de-France deploy narrow vertical mast lifts navigating tight aisles where emissions restrictions and doorway width constraints apply simultaneously.
Mobile Elevating Work Platform (MEWP) Market Competitive Landscape
Capability concentration sits with specialized engineering houses; scale advantage sits with diversified industrial conglomerates. The vendor base separates into three tiers: integrated multinationals with full product portfolios, regional champions dominating specific geographies, and niche specialists addressing compact or electrified configurations. Strategic moves center on telematics-enabled fleet management subscriptions and lithium-ion powertrain platform standardization.
Among North American-based fabricators, JLG Industries and Genie exemplify integrated multinational positioning with extensive distribution networks sustaining aftermarket service revenue. XCMG Machinery anchors cost-competitive manufacturing scale serving Asia-Pacific rental channels. Haulotte Group occupies a specialist position in compact electric vertical mast lifts for European urban job sites where emissions restrictions tighten.
| Leading Market Players |
|---|
| JLG Industries |
| Genie |
| Terex |
| Haulotte Group |
| Skyjack |
| XCMG Machinery |
| Sinoboom Intelligent Equipment |
| Aichi Corporation |
| MEC |
| Others |
Pricing and Supply Chain Analysis
Precision hydraulic cylinder manufacturing clusters in Germany and Japan concentrate upstream supply leverage, directing margin pools toward boom lift producers with captive forging partnerships or long-term offtake agreements with Bosch Rexroth and KYB Corporation.
Pricing Analysis
Geographic price spreads of 15-25% separate North American list pricing from Asia-Pacific procurement costs for equivalent working-height specifications. Three-tier pricing structure across premium, standard, and economy levels segments by CE marking certification depth and telematics bundling intensity. Cost compression in mid-size rental channels intensifies as national fleet lessors deploy dynamic yield algorithms. Construction contractors exhibit highest price sensitivity due to project-based procurement, while data center operators prioritize uptime guarantees over unit economics.
Supply Chain Analysis
Upstream feedstock dependence on rolled steel from China, South Korea, and Turkey shapes chassis fabrication economics for platform OEMs. Lithium-ion cell supply draws from CATL and BYD manufacturing bases in Fujian and Shenzhen provinces. Tariff exposure on aluminum extrusions from Russian Federation sources creates input cost volatility for mast fabrication. Distribution runs through regional rental fleet aggregators with depot-level service capability rather than direct OEM-to-contractor fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric powertrain conversion constitutes a high-growth disruption as OSHA indoor emissions enforcement and lithium-ion density improvements converge to compress fleet replacement cycles.
For Market Incumbents: Insulate service revenue streams by embedding telematics-enabled predictive maintenance subscriptions into national rental contracts. Deepen backward integration into lithium-ion battery pack assembly to capture margin migrating from hydraulic systems toward power electronics. Defend against Chinese cost-competitive entrants by accelerating CE marking certification timelines for European municipal procurement.
For New Entrants and Emerging Players: Pursue India warehouse automation whitespace where e-commerce fulfillment construction outpaces MEWP rental penetration relative to parcel volume growth. Target compact vertical mast configurations for European urban logistics facilities facing simultaneous emissions restrictions and doorway width constraints. Anchor go-to-market strategy through equipment-as-a-service subscription models with guaranteed uptime SLAs.
For Investors and Strategic Acquirers: Capital is best deployed toward telematics-converged fleet management platforms with recurring revenue visibility across multi-site logistics contracts. Long-term viability over a 5-10 year window favors asset-light software layer providers over capital-intensive manufacturing footprints. Monitor carbon-border adjustment implementation schedules as the critical inflection signal for electric fleet valuation premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Lithium-Ion Platform Standardization | CATL and BYD cell supply agreements enable full-shift outdoor runtime for electric boom lifts. |
| Telematics Fleet Integration | IoT utilization tracking opens subscription revenue streams for rental yield management platforms. |
| CE Marking Acceleration | Third-party witnessed tilt-table testing documentation compresses six-month certification timelines. |
| India Distribution Partnership | Mumbai and Delhi-NCR fulfillment center construction creates whitespace for equipment lessors. |
| Aftermarket Service Expansion | JLG Industries leverages North American distribution networks to sustain parts and maintenance revenue. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with rental fleet managers, construction procurement officers, and aftermarket service directors; and secondary validation through OSHA enforcement records, EU Machinery Directive filings, customs trade data, and SEC equipment manufacturer disclosures. Bottom-up triangulation against top-down macroeconomic indicators anchored volume and value estimates.
Forecast inputs span product type, power source architecture, end-use industry, and regional regulatory cluster across the modeling period. CAGRs derive from segment-level growth rate blending with macroeconomic elasticity coefficients. Specific inputs include lithium-ion battery cost curves, steel and aluminum commodity price trajectories, and data center construction pipeline tracking.
Macroeconomic conditions sit as an overlay; deviation in interest rate environments, construction spending cycles, or carbon-border adjustment implementation would shift the trajectory. Cross-checking against rental fleet utilization benchmarks and auction market residual value indices is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Cement Consistometer Market
Construction Equipment
Electric Excavators Market
Construction Equipment
Rotary Blasthole Drilling Rig Market
Construction Equipment
Utility Locator Market
Construction Equipment
Heavy Construction Equipment Market
Construction Equipment
GCC Crane Market
Construction Equipment
Thailand Construction Equipment Market
Construction Equipment
India Construction Equipment Market
Construction Equipment
Truck Mounted Concrete Pump Market
Construction Equipment
Industrial Steam Washer Market
Construction Equipment
Welding and Cutting Equipment Market
Construction Equipment
US Welding Consumables Market
Construction Equipment
Hybrid Excavator Market
Construction Equipment
Europe Construction Equipment Rental Market
Construction Equipment
Cold Forming Equipment Market
Construction Equipment
Stud Welding Guns Market