
 Metalworking Machinery Market | 2026-2036
Metalworking Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
Metalworking Machinery Market Analysis
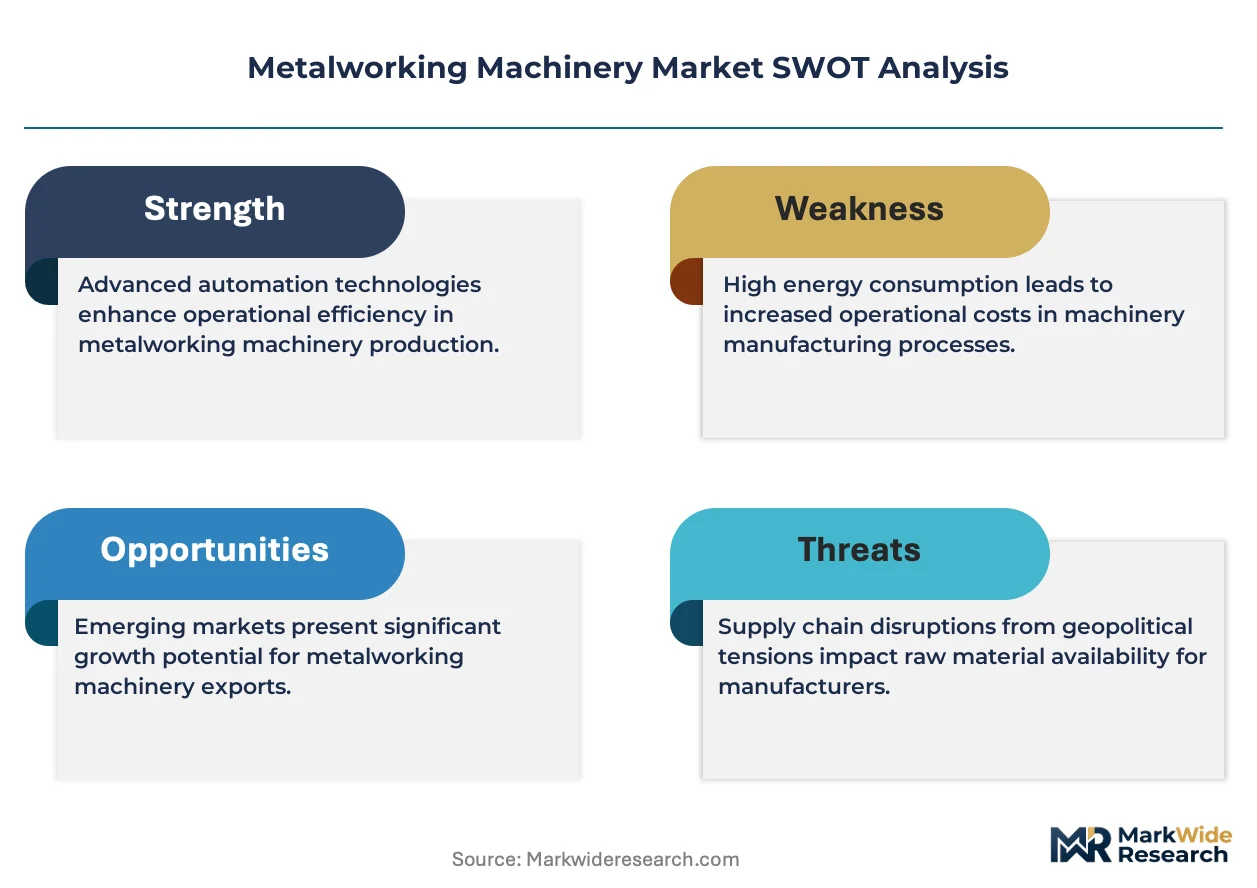
The premium-commodity split in metalworking machinery is rebalancing as high-precision CNC systems command widening margin premiums over standard lathes and milling equipment. TRUMPF Group leverages its laser-integration expertise to dominate advanced sheet-metal processing lines. Yamazaki Mazak Corporation anchors multi-axis turning centers across North American and European distributor networks. DMG Mori Co. Limited differentiates through digital twin integration and subscription-based spindle monitoring services.
Metalworking machinery encompasses powered equipment that shapes, cuts, or forms metal workpieces through controlled mechanical, thermal, or electrochemical processes, typically achieving tolerances of ±0.001 mm in precision configurations. These systems serve as capital backbone for discrete manufacturing, converting raw metal stock into finished components across industrial supply chains. CNC Machines capture the dominant share of replacement cycles as factories modernize toward unattended machining cells. Electric drive technology is displacing hydraulic systems in new installations where energy efficiency and positional accuracy determine total cost of ownership. Mass Production applications retain volume leadership, though Prototyping segments are expanding fastest among job shops serving aerospace and medical device supply chains.
ISO 23125 safety standards, the EU Machinery Directive with CE marking requirements, and China's GB/T certification protocols for CNC equipment collectively elevate barrier thresholds for new entrants while accelerating replacement demand among non-compliant installed bases. OSHA lockout-tagout enforcement in US fabrication facilities adds compliance-driven upgrade pressure. Stakeholders must monitor divergence between regional certification regimes and assess captive retrofit capabilities against full system replacement economics.
Market Dynamics
Electric drive technology is displacing hydraulic systems in precision metalworking installations, compressing energy consumption benchmarks while tightening positional accuracy tolerances across automotive and aerospace supply chains.
Growth Catalysts
- ISO 23125 Machinery Safety Standards:Tightening compliance thresholds in Europe and North America force replacement of legacy installed bases, accelerating upgrade cycles for non-compliant equipment.
- Automotive OEM Capital Expenditure:Precision forming equipment procurement is expanding as electric vehicle architectures demand tighter tolerance metal components for battery enclosures and structural assemblies.
- China's GB Certification Requirements:Domestic CNC equipment mandates elevate barrier thresholds for imported machinery while stimulating captive domestic manufacturing capacity expansion.
Market Restraints
- High-Precision Ball Screw and Linear Guide Supply Concentration:Japanese and German specialty component suppliers control critical feed mechanism supply, creating input bottlenecks during demand surges.
- CE Marking Compliance Costs:EU Machinery Directive conformity assessment expenses disproportionately burden mid-tier equipment manufacturers seeking European market access.
- Additive Manufacturing Substitution:Metal 3D printing systems capture low-volume, high-complexity workpiece applications previously requiring multi-axis machining centers.
Strategic Opportunities
- India's PLI Scheme for Manufacturing:Production-linked incentive frameworks for capital goods stimulate domestic machine tool demand and localized assembly partnerships.
- Digital Twin Convergence:Integration of real-time spindle monitoring with predictive maintenance platforms enables subscription-based service revenue models.
- Medical Device Supply Chain Expansion:Orthopedic implant and surgical instrument manufacturing drives demand for micromachining centers with sub-micron repeatability specifications.
Industry Challenges
- CNC Programming and Mechatronics Skill Shortage:Factory automation expertise gaps constrain unattended machining cell deployment across North American job shops.
- Legacy Hydraulic System Integration Complexity:Retrofit of electric drives into existing press brake and stamping line architectures demands costly mechanical redesign.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metalworking Machinery Market |
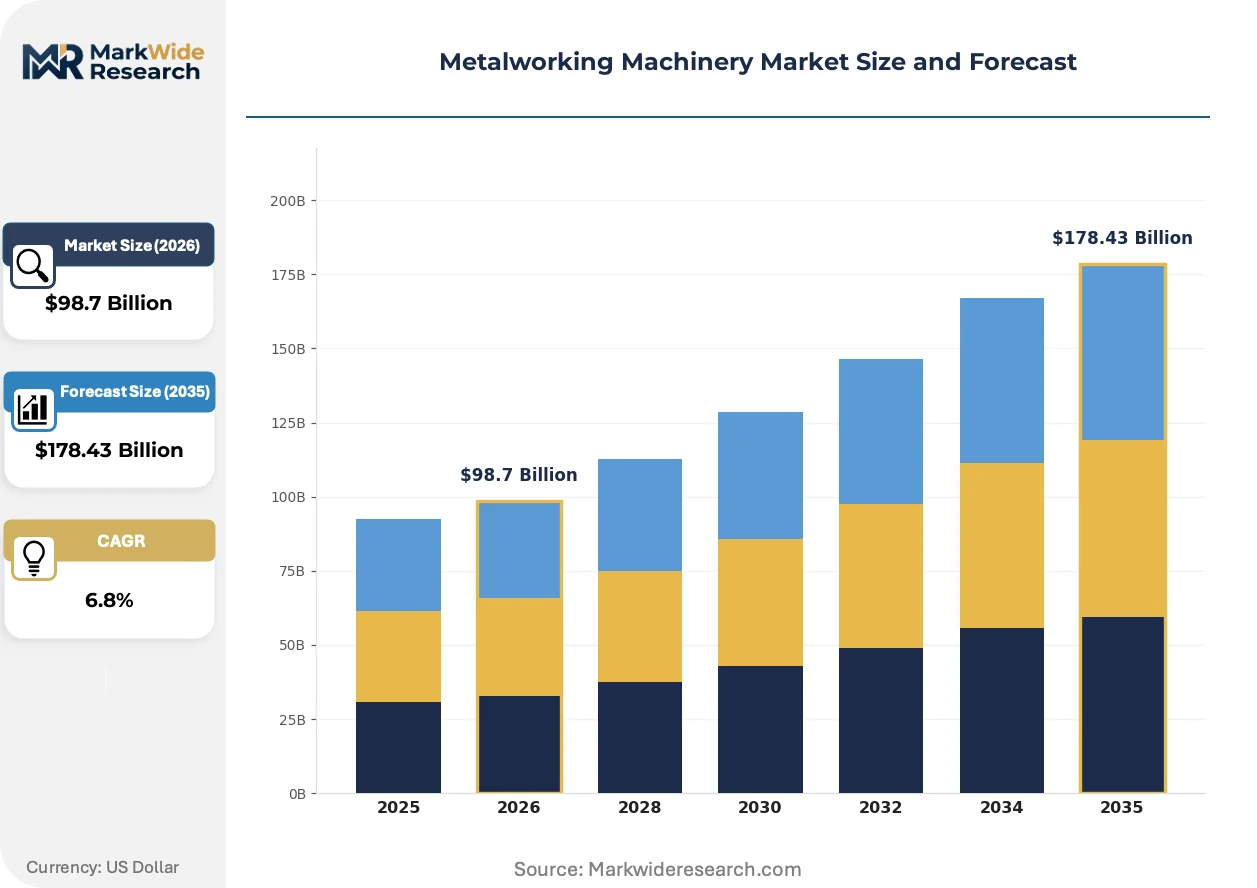
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $178.43 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CNC Machines, Lathes, Milling Machines, Grinding Machines End User: Aerospace, Automotive OEMs, Medical Device Manufacturers, Tooling Suppliers Technology: Hydraulic, Pneumatic, Electric, Hybrid Application: Precision Engineering, Fabrication, Prototyping, Mass Production |
| Companies Covered | Amada Co. Limited, Fanuc Corporation, TRUMPF Group, Yamazaki Mazak Corporation, Okuma Corporation, Sandvik Aktiebolag, DMG Mori Co. Limited, Schuler Aktiengesellschaft, Mitsubishi Heavy Industries Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metalworking Machinery Market Emerging Trajectories
Artificial intelligence and edge computing architectures are penetrating machine tool control systems, enabling real-time tool wear prediction and autonomous process parameter adjustment without operator intervention.
Hybrid manufacturing platforms combining directed energy deposition with subtractive finishing operations are consolidating multi-process workflows into single-machine footprints. Aerospace tier-one suppliers adopt these systems to reduce work-in-process inventory and eliminate inter-facility material transport. The technology is consolidating formerly separate capital equipment procurement decisions into unified platform selections.
REACH substance restrictions and EU Green Deal carbon border adjustment mechanisms are tightening material sourcing requirements for machine tool builders. Manufacturers must document full supply chain embodied carbon for structural castings and rare earth magnet content in spindle motors. German and Italian OEMs are restructuring supplier qualification protocols to maintain CE marking eligibility under evolving environmental compliance frameworks.
Buyers are unbundling after-sales service contracts from initial equipment purchases, selecting third-party maintenance providers or developing in-house spindle rebuild capabilities. This pattern compresses OEM service revenue streams while expanding independent spare parts distributor market presence. The shift is most pronounced among high-volume automotive stamping operations in the US Midwest and Mexico's Bajío manufacturing corridor.
Metalworking Machinery Market Segmentation
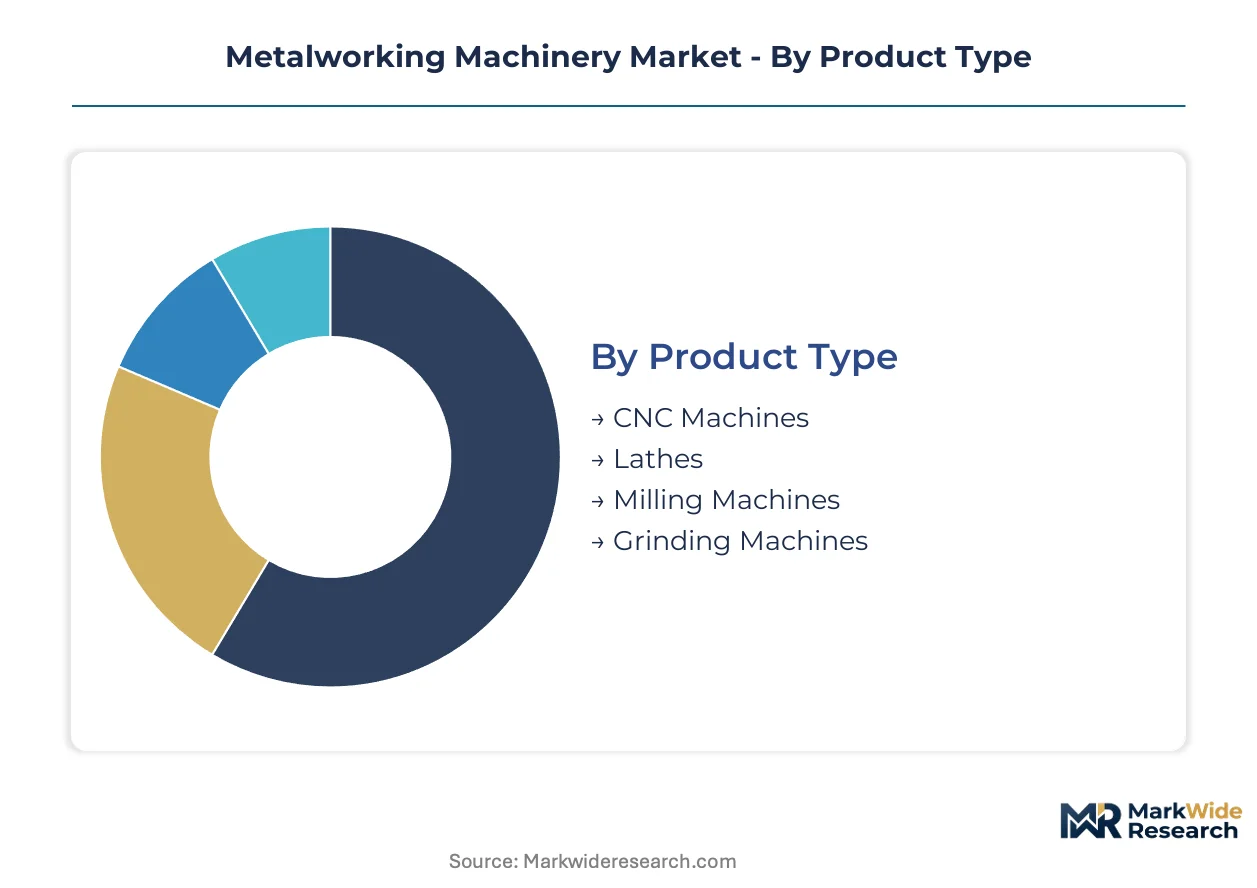
Segmentation in metalworking machinery separates capital procurement patterns across precision requirements, automation intensity, and end-use tolerance specifications. Each dimension reveals distinct margin structures and replacement cycle dynamics that shape vendor positioning strategies.
Product Type:
The customization-standardization spectrum spans from fully configurable CNC architectures to commodity lathe configurations with fixed specification envelopes.
- CNC Machines:Computer numerical control systems integrate multi-axis interpolation with programmable tool changers for unattended machining cells. Demand concentrates in Germany's Baden-Württemberg automotive supply corridor where electric vehicle battery enclosure machining requires ±0.001 mm repeatability. ISO 23125 safety compliance accelerates replacement of legacy control architectures.
- Lathes:Rotational workpiece processing equipment ranges from two-axis manual models to seven-axis turning-milling composites. Japanese and German specialty component suppliers control critical ball screw and linear guide feed mechanisms, creating input bottlenecks during demand surges for high-precision configurations.
- Milling Machines:Stationary workpiece rotary cutting systems dominate general fabrication throughput.
- Grinding Machines:Abrasive finishing equipment achieves sub-micron surface specifications for bearing and medical implant applications.
Most installed capacity flows through Lathes. Expansion is steepest in CNC Machines.
End User:
Cost tier stratification separates aerospace qualification-intensive procurement from automotive volume-scale purchasing.
- Automotive OEMs:Tier-one vehicle manufacturers deploy capital expenditure on precision forming equipment for structural assemblies and powertrain components. Electric vehicle architectures demand tighter tolerance metal components for battery enclosures, compressing energy consumption benchmarks while tightening positional accuracy tolerances.
- Aerospace:Airframe and engine manufacturers specify AS9100-certified equipment with full process traceability. Hybrid manufacturing platforms combining directed energy deposition with subtractive finishing consolidate multi-process workflows into single-machine footprints for titanium structural components.
- Medical Device Manufacturers:Orthopedic implant and surgical instrument production drives micromachining center specifications.
- Tooling Suppliers:Cutting tool and die producers serve as secondary equipment demand channel.
Procurement volume concentrates in Automotive OEMs. Medical Device Manufacturers are gaining share fastest.
Technology:
Application intensity varies from continuous-duty mass production to intermittent prototyping workflows.
- Electric:Servo motor drive systems displace hydraulic actuation in precision installations where energy efficiency and positional accuracy determine total cost of ownership. Real-time spindle monitoring with predictive maintenance platforms enables subscription-based service revenue models.
- Hydraulic:Fluid power systems retain installed base in heavy-duty press brake and stamping line architectures. Retrofit complexity demands costly mechanical redesign when upgrading to electric alternatives.
- Pneumatic:Compressed air actuation serves light-duty positioning and clamping functions.
- Hybrid:Combined electric-hydraulic architectures balance power density with control precision.
Most new installations specify Electric technology. Hybrid configurations are climbing the fastest.
Application:
Customer type separation distinguishes high-mix job shops from dedicated production facilities.
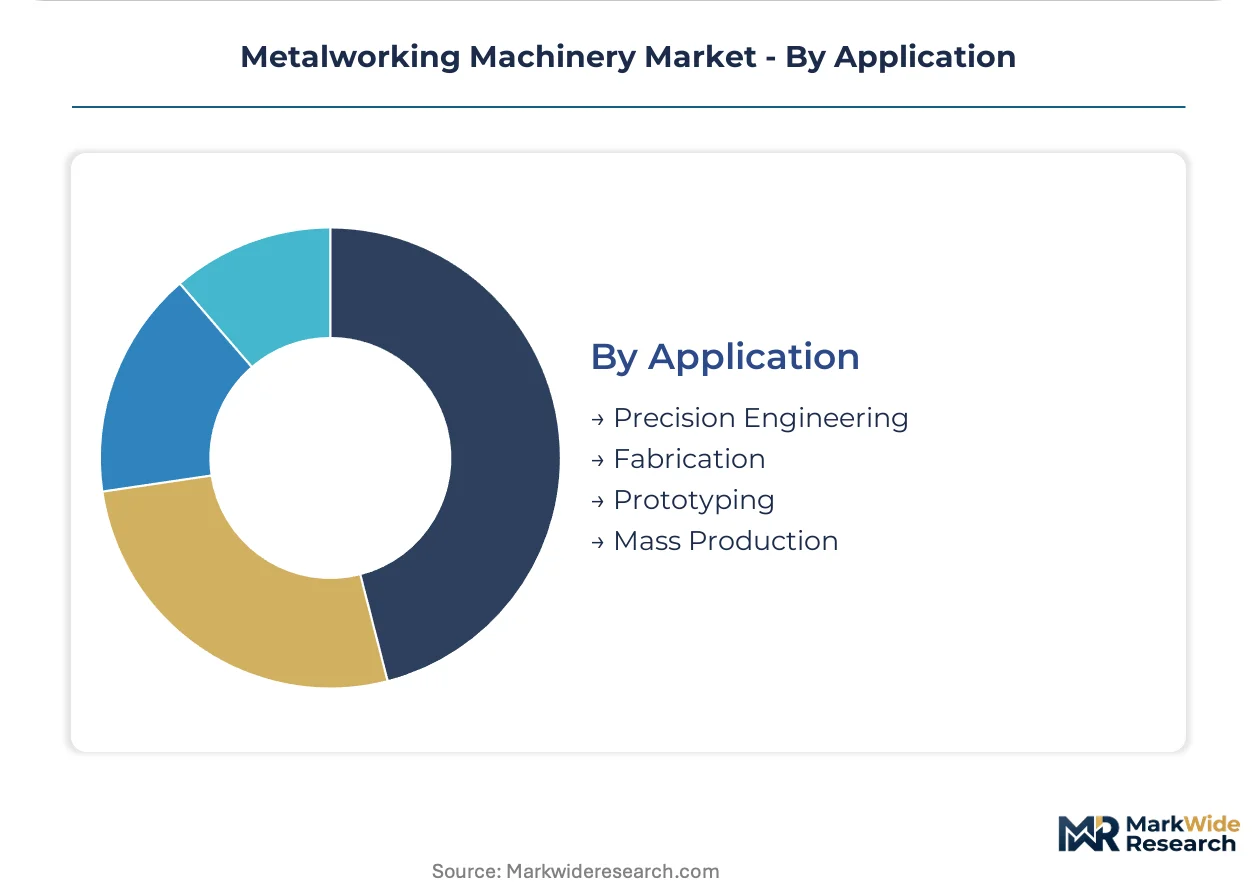
- Mass Production:High-volume continuous processing retains volume leadership among automotive stamping operations and consumer appliance manufacturers. Buyers unbundle after-sales service contracts from initial equipment purchases, selecting third-party maintenance providers.
- Prototyping:Low-volume, high-mix workpiece processing expands fastest among job shops serving aerospace and medical device supply chains. Additive manufacturing substitution captures high-complexity applications previously requiring multi-axis machining centers.
- Precision Engineering:Tight-tolerance component manufacturing for instrumentation and metrology equipment.
- Fabrication:General sheet metal and structural steel processing for construction and industrial equipment.
Most revenue derives from Mass Production. Prototyping exhibits the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands premium-tier precision machinery demand while China scales domestic CNC capacity through state-directed industrial policy. Japan maintains specialized component supply dominance. India's production-linked incentive frameworks attract assembly partnerships. Mexico's automotive corridor absorbs North American nearshoring flows.
Germany
Automotive OEM capital expenditure on electric vehicle battery enclosure machining drives precision forming equipment procurement. EU Machinery Directive CE marking requirements and REACH substance restrictions tighten compliance thresholds for structural castings. Baden-Württemberg's machine tool cluster concentrates multi-axis turning center demand from tier-one suppliers.
China
Domestic CNC equipment mandates under GB/T certification protocols stimulate captive manufacturing capacity expansion. MIIT industrial upgrading directives prioritize high-end machine tool localization. Yangtze River Delta manufacturing bases absorb imported technology transfer partnerships for five-axis machining centers.
Japan
Specialty ball screw and linear guide feed mechanism supply concentrates among precision component manufacturers serving global OEMs. METI technology roadmaps guide next-generation servo motor development. Aichi Prefecture's manufacturing corridor anchors multi-axis turning center production for North American and European distributor networks.
United States
OSHA lockout-tagout enforcement in fabrication facilities accelerates compliance-driven equipment upgrades. IRA clean energy manufacturing incentives redirect capital expenditure toward electric drive press brake installations. Midwest automotive stamping operations and Mexico's Bajío corridor drive unbundled third-party maintenance contract adoption.
India
PLI scheme frameworks for capital goods stimulate domestic machine tool demand and localized assembly partnerships. BIS certification requirements for imported CNC equipment elevate barrier thresholds for non-compliant machinery. Maharashtra and Gujarat industrial corridors concentrate job shop prototyping capacity serving aerospace supply chains.
Metalworking Machinery Market Vendor Landscape
Top-tier vendors anchor premium precision segments, while mid-tier fabricators compete on delivery speed and customization flexibility. The vendor base stratifies across laser-integration specialists, multi-axis turning center providers, and digital twin platform developers. Two dominant competitive moves are reshaping positioning: captive spindle monitoring subscription services and hybrid manufacturing platform consolidation of multi-process workflows.
Within the laser-integration tier, TRUMPF Group and Amada Co. Limited exemplify precision sheet-metal processing specialization. Yamazaki Mazak Corporation occupies a position among multi-axis turning center providers with established distributor network presence. DMG Mori Co. Limited anchors the digital convergence archetype through control architecture integration. These three Japanese and German-origin entities represent distinct capability vectors without overlapping strategic positioning.
| Leading Market Players |
|---|
| Amada Co. Limited |
| Fanuc Corporation |
| TRUMPF Group |
| Yamazaki Mazak Corporation |
| Okuma Corporation |
| Sandvik Aktiebolag |
| DMG Mori Co. Limited |
| Schuler Aktiengesellschaft |
| Mitsubishi Heavy Industries Limited |
| Others |
Supply Flow & Price Mechanics
EU Green Deal carbon border adjustment mechanisms gate qualified supply access and premium-tier pricing eligibility for machine tool builders. REACH substance restrictions on structural castings and rare earth magnet documentation requirements compress margin structures for non-compliant fabricators while widening price premiums for certified OEMs serving automotive and aerospace supply chains.
Pricing Analysis
Capacity additions in China's Yangtze River Delta manufacturing bases are reshaping price floors for mid-tier CNC equipment. Three-tier pricing structure across premium, standard, and economy levels separates ISO 23125-certified architectures from legacy hydraulic configurations. Cost compression in standard lathe segments intensifies because domestic Chinese OEMs expand five-axis machining center output. Automotive OEMs exhibit lowest price sensitivity for battery enclosure machining cells; job shops serving prototyping applications demonstrate highest sensitivity to upfront capital outlay.
Supply Chain Analysis
Single-source vulnerability sits with Japanese and German specialty component suppliers controlling ball screw and linear guide feed mechanisms. Critical inputs draw from high-precision castings, rare earth spindle magnets, and servo motor windings. Tariff exposure runs through EU-China machinery trade flows and US Section 301 enforcement on Chinese CNC controllers. Distribution runs through authorized distributor networks in Baden-Württemberg and Aichi Prefecture, with direct OEM relationships dominating high-volume automotive procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The metalworking machinery market compounds steadily as electric vehicle battery enclosure machining mandates replacement cycles across automotive supply chains. Capital expenditure on precision forming equipment anchors predictable demand visibility for qualified vendors.
For Market Incumbents: Acquire captive spindle monitoring and predictive maintenance software capabilities to defend service revenue streams against third-party maintenance unbundling. Backward integration into ball screw and linear guide production reduces input bottlenecks from Japanese and German specialty suppliers. ISO 23125 compliance investments widen margin premiums as regulatory thresholds tighten across European and North American installed bases. For New Entrants and Emerging Players: AI-driven tool wear prediction algorithms offer technology-first wedge positioning against legacy control architecture vendors. India's PLI scheme for capital goods presents the most penetrable geography for localized assembly partnerships with minimal incumbent distributor saturation. Medical device micromachining specifications provide white-space targeting with sub-micron repeatability requirements underserved by commodity lathe producers. For Investors and Strategic Acquirers: Roll-up economics work for regional aftermarket service specialists because buyer unbundling of maintenance contracts fragments vendor relationships across Midwest automotive stamping corridors. Long-term viability frames around five-to-ten year replacement cycles driven by compliance mandates rather than discretionary upgrades. Monitor GB/T certification protocol enforcement as inflection indicator for Chinese domestic capacity expansion versus import dependency.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Platform Integration | Real-time spindle monitoring enables subscription-based service revenue models for DMG Mori and competing OEMs. |
| Hybrid Manufacturing Platform Development | Directed energy deposition combined with subtractive finishing consolidates aerospace titanium structural workflows. |
| Electric Drive Retrofit Services | Energy efficiency mandates in EU Machinery Directive accelerate hydraulic-to-servo motor conversion demand. |
| Localized Assembly Partnerships | India's PLI scheme attracts captive production for five-axis machining centers serving domestic job shops. |
| GB/T Certification Compliance Investment | China's domestic CNC equipment mandates elevate barrier thresholds for imported machinery from German and Japanese OEMs. |
Methodological Framework
Bottom-up automotive and aerospace OEM procurement modeling reconciled against top-down machine tool production tracking forms the analytical core. Primary interviews with plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads combine with secondary validation from SEC 10-K filings, customs trade data, and national machine tool association production statistics. Triangulation across stakeholder input and documentary sources ensures segmentation integrity across CNC machines, lathes, milling equipment, and grinding systems.
Historical trendline analysis of replacement cycle patterns and capital expenditure trajectories informs projection methodology across the analysis window. Segmentation dimensions modeled include product type precision tier, end-use industry qualification intensity, electric-hydraulic-pneumatic technology architecture, and mass production versus prototyping application intensity. CAGRs derive from installed base age profiles, compliance-driven replacement elasticity, and regional industrial policy incentive structures including India's PLI scheme and China's MIIT localization directives.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to additive manufacturing substitution rates and geopolitical trade restriction severity. Forecasts reflect documented assumptions regarding electric vehicle production scaling, ISO 23125 enforcement timelines, and rare earth magnet supply continuity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment and Machinery
Briquetting Machine Market
Construction Equipment and Machinery
ASEAN Construction Machinery Market
Construction Equipment and Machinery
Woodworking Machines Market
Construction Equipment and Machinery
Engineering Machinery Counterweight Iron Market
Construction Equipment and Machinery
Parallel-Shaft Gear Reducer Market
Construction Equipment and Machinery
Concrete Finishing Equipment Market
Construction Equipment and Machinery
Latin America Paper Making Machine Market
Construction Equipment and Machinery
Universal Milling Machine Market
Construction Equipment and Machinery
Latin America Injection Molding Machines Market
Construction Equipment and Machinery
Cold Forging Machines Market
Construction Equipment and Machinery
Global Metal Embossing Machine Market
Construction Equipment and Machinery
Metal Fabrication Equipment Market
Construction Equipment and Machinery
India Lathe Machines Market
Construction Equipment and Machinery
Road Construction Machinery Market
Construction Equipment and Machinery
Shaper & Shaping Machine Market
Construction Equipment and Machinery
Grader Machinery Market