
 Autonomous Construction Equipment Market | 2026-2036
Autonomous Construction Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Autonomous Construction Equipment Market Analysis
SAE Level 4 autonomy certification is unwinding legacy equipment replacement cycles across heavy civil and mining fleets. Caterpillar leverages its integrated autonomy platform to control mine-site workflows from pit to crusher, sustaining high machine utilization rates in Pilbara iron ore operations. Komatsu Ltd. anchors its competitive position through in-house production of sensor fusion modules and drive-by-wire actuators, while Volvo Construction Equipment differentiates via its northern European dealer network and connected fleet telematics.
Autonomous construction equipment denotes self-operating earthmoving and material-handling machinery capable of executing pre-programmed work cycles without continuous human intervention, relying on LiDAR point-cloud mapping, real-time kinematic GPS positioning, and neural-network-based obstacle detection to achieve centimeter-grade accuracy in grading and excavation tasks. Excavators dominate current deployment volumes owing to their versatility across site preparation and demolition workflows, whereas computer vision adoption is accelerating fastest as convolutional neural networks enable real-time terrain classification without expensive spinning LiDAR arrays. Contractors represent the most contested end-user segment, with margin pools shifting toward fleet management software subscriptions bundled with autonomous machine leases.
OSHA workplace safety mandates and the EU AI Act's risk-classification framework for autonomous industrial systems are reshaping product validation requirements and liability structures for OEMs seeking North American and European market access. China's MIIT GB standards for intelligent connected vehicles are extending to off-highway autonomous machinery, creating divergent compliance pathways that favor regionally anchored engineering teams. Stakeholders must monitor whether MEE emissions enforcement tightens sufficiently to make diesel-hybrid autonomous fleets non-viable before battery energy density improves for the heaviest equipment classes.
Market Dynamics
SAE Level 4 autonomy certification is compressing replacement cycles across heavy civil and mining fleets as contractors face simultaneous pressure from labor scarcity and emissions compliance deadlines.
Growth Catalysts
- OSHA workplace mandates:US contractors accelerate autonomous adoption to reduce site injury liability and satisfy stricter federal safety inspection protocols.
- Chilean copper belt labor shortages:Mining operators deploy fully autonomous haul fleets to sustain pit-to-port throughput where skilled equipment operator availability has collapsed.
- Battery-electric convergence:OEMs integrate solid-state battery architectures with autonomous control stacks to satisfy EU Green Deal emissions thresholds for off-highway machinery.
Market Restraints
- LiDAR sensor supply concentration:German and Israeli photonics suppliers control 80% of industrial-grade solid-state LiDAR output, creating single-source vulnerability for tier-one OEMs.
- EU AI Act risk classification:Autonomous earthmovers fall under high-risk AI system designation, imposing documentation and human-oversight requirements that extend product validation timelines.
- Diesel-hybrid stranded asset risk:Battery energy density limitations for 100-ton-plus excavators force premature capital retirement as MEE enforcement tightens in China's western provinces.
Strategic Opportunities
- India's National Infrastructure Pipeline:State-backed highway and tunnel megaprojects lack domestic autonomous equipment suppliers, opening procurement channels for certified foreign OEMs.
- 5G-enabled teleoperation:Low-latency private cellular networks allow human-in-the-loop supervision of autonomous fleets in hazardous terrain applications previously requiring on-site operators.
- CSRD sustainability disclosure:European contractors face Scope 3 emissions reporting requirements that favor autonomous electric fleets with granular fuel-consumption telemetry.
Industry Challenges
- Functional safety engineer scarcity:ISO 26262 and ISO/TS 15066 certification expertise concentrates in Stuttgart and Tokyo, forcing OEMs to compete for limited validation talent.
- Retrofit integration complexity:Legacy hydraulic actuators in ten-year-old excavator fleets resist drive-by-wire conversion, fragmenting autonomous upgrade economics for mid-tier contractors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Autonomous Construction Equipment Market |
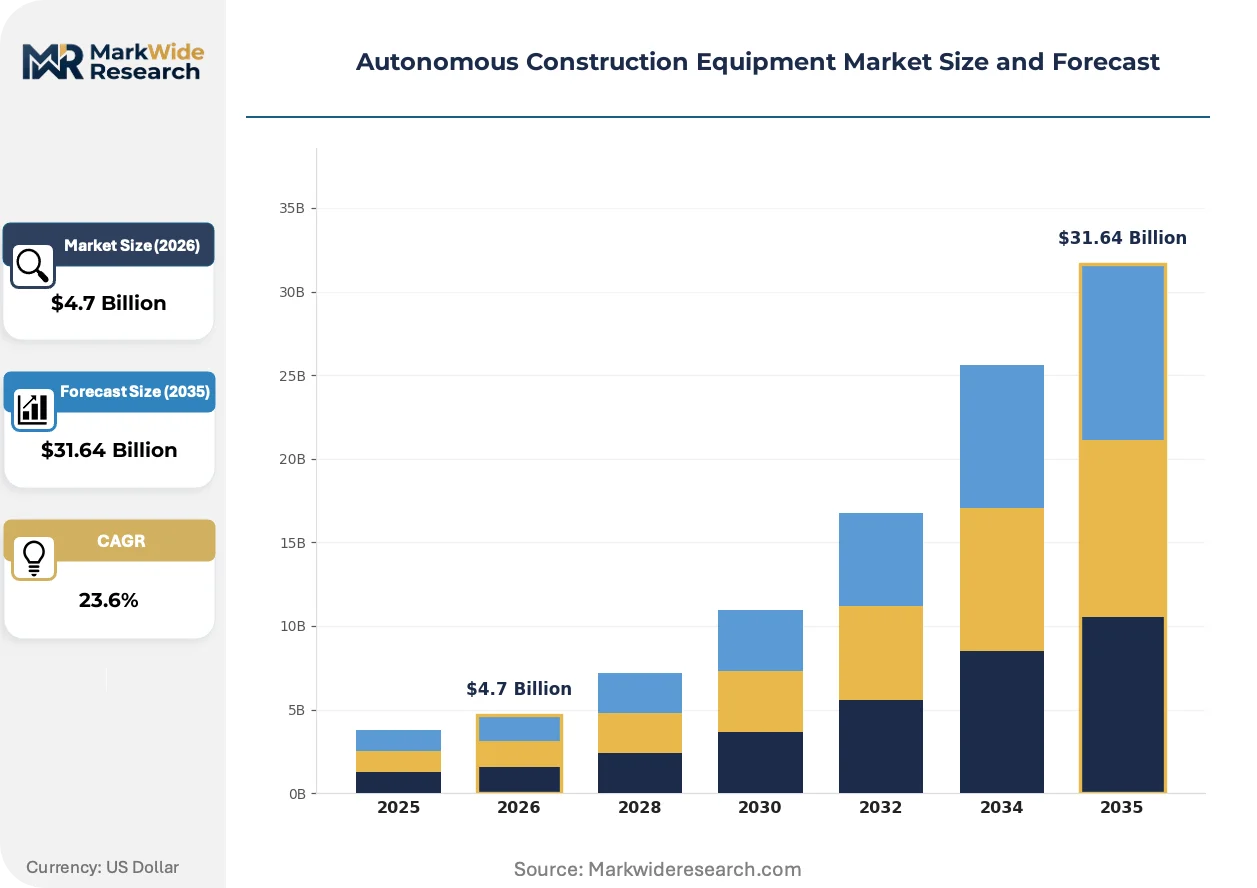
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $31.64 Billion |
| CAGR (2026 – 2036) | 23.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Excavators, Loaders, Dozers, Graders Technology: LiDAR, GPS, AI, Computer Vision End User: Contractors, Builders, Developers, Government Agencies Application: Site Preparation, Demolition, Landscaping, Material Handling |
| Companies Covered | Hitachi Construction Machinery Co. Ltd., Built Robotics Inc., Caterpillar, Sany Group, Doosan Infracore Co. Ltd., Volvo Construction Equipment, Liebherr Group, XCMG, Komatsu Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Autonomous Construction Equipment Market Emerging Trajectories
Convolutional neural networks are displacing spinning LiDAR arrays for terrain classification, while regulatory fragmentation across EPA, EU AI Act, and MIIT GB standards forces parallel engineering tracks.
Solid-state LiDAR arrays are miniaturizing from roof-mounted spinning domes to embedded bumper and cabin-edge modules. Australian iron ore operators now specify these compact sensor packages for dust-resistant pit environments. The form-factor reduction is miniaturizing equipment redesign costs and enabling retrofits on mid-size wheel loaders previously excluded from autonomous programs.
The EU AI Act's high-risk system classification for autonomous industrial machinery imposes conformity assessment procedures through notified bodies. German construction firms now require CE-marked autonomy stacks with documented algorithmic bias testing. This regulatory architecture favors OEMs with captive European engineering centers capable of sustained regulatory liaison.
Equipment-as-a-service contracting is displacing traditional capital purchase and residual-value risk for mid-size contractors. Australian and Chilean mining services firms now lease autonomous fleets bundled with predictive maintenance telemetry and guaranteed availability clauses. This financing rotation concentrates most acutely in Western Australia's Pilbara region where iron ore volume contracts reward uptime guarantees over asset ownership.
Autonomous Construction Equipment Market Segmentation
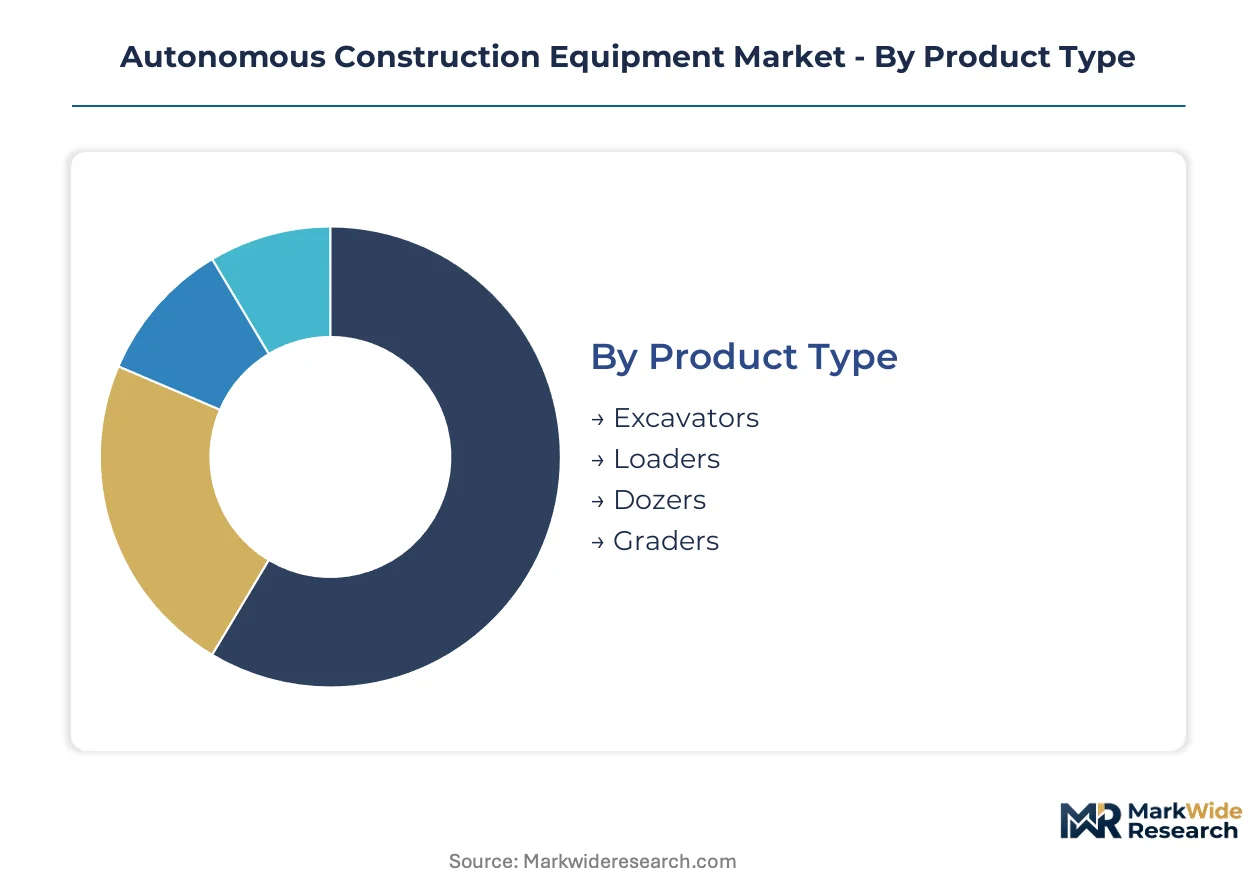
Segmentation in autonomous construction equipment reveals how technology choices and customer economics fragment procurement patterns. Equipment buyers prioritize different autonomy stacks based on site complexity, regulatory exposure, and fleet integration requirements.
Product Type:
Substitution pressure runs strongest against conventional hydraulic machines as autonomy-enabled units displace standard fleet purchases in high-utilization environments.
- Excavators:Articulated boom machines with integrated drive-by-wire hydraulics and bucket-positioning algorithms dominate current deployment volumes. Australian iron ore operators specify these for pit-to-crusher material movement where continuous operation justifies autonomy premiums.
- Loaders:Wheel loaders with real-time payload optimization and autonomous tramming capabilities concentrate demand in Chilean copper belt stockpile management. Labor scarcity at remote mine sites accelerates conversion from operator-controlled to supervised-autonomous loading cycles.
- Dozers:Track-type tractors with blade-control automation serve fine-grading applications requiring centimeter-level elevation precision.
- Graders:Motor graders with cross-slope and profile-matching autonomy see procurement concentration in highway megaprojects across China's western provinces.
Excavators retain volume leadership; loaders hold the steepest expansion curve.
Technology:
Cost tier stratification separates premium sensor fusion stacks from commoditized positioning modules, with mid-tier buyers mixing technologies to balance capability against capital constraints.
- LiDAR:Solid-state photonic arrays generating dense point clouds for obstacle detection and terrain mapping anchor high-specification autonomy platforms. German and Israeli suppliers control industrial-grade solid-state output, creating supply concentration for OEMs targeting SAE Level 4 certification.
- GPS:Real-time kinematic positioning systems delivering centimeter-grade location accuracy enable geofenced operation and progress tracking. These modules see broad adoption across mid-size contractor fleets where precision earthworks justify hardware investment.
- AI:Neural-network inference engines processing sensor fusion inputs for path planning and hazard classification concentrate development resources in Stuttgart and Tokyo engineering centers.
- Computer Vision:Convolutional neural networks performing terrain classification without spinning LiDAR arrays are gaining share fastest in dust-intensive mining environments where mechanical sensor reliability degrades.
LiDAR retains volume leadership; computer vision holds the steepest expansion curve.
End User:
Application maturity varies sharply across customer types, with risk tolerance and capital access determining autonomy adoption sequencing.
- Contractors:Mid-size construction firms leasing equipment-as-a-service bundles now specify autonomous fleets with guaranteed availability clauses. Australian mining services firms pioneered this procurement model in Western Australia's Pilbara region.
- Builders:Residential and commercial developers deploy autonomous compact equipment for repetitive site preparation tasks where labor cost inflation erodes project margins.
- Developers:Large-scale infrastructure developers integrate autonomous fleets into multi-year earthworks contracts with productivity-linked payment structures.
- Government Agencies:Public works departments in China and India specify unmanned equipment for hazardous tunneling and remote highway construction where operator safety protocols constrain conventional deployment.
Contractors retain volume leadership; government agencies hold the steepest expansion curve.
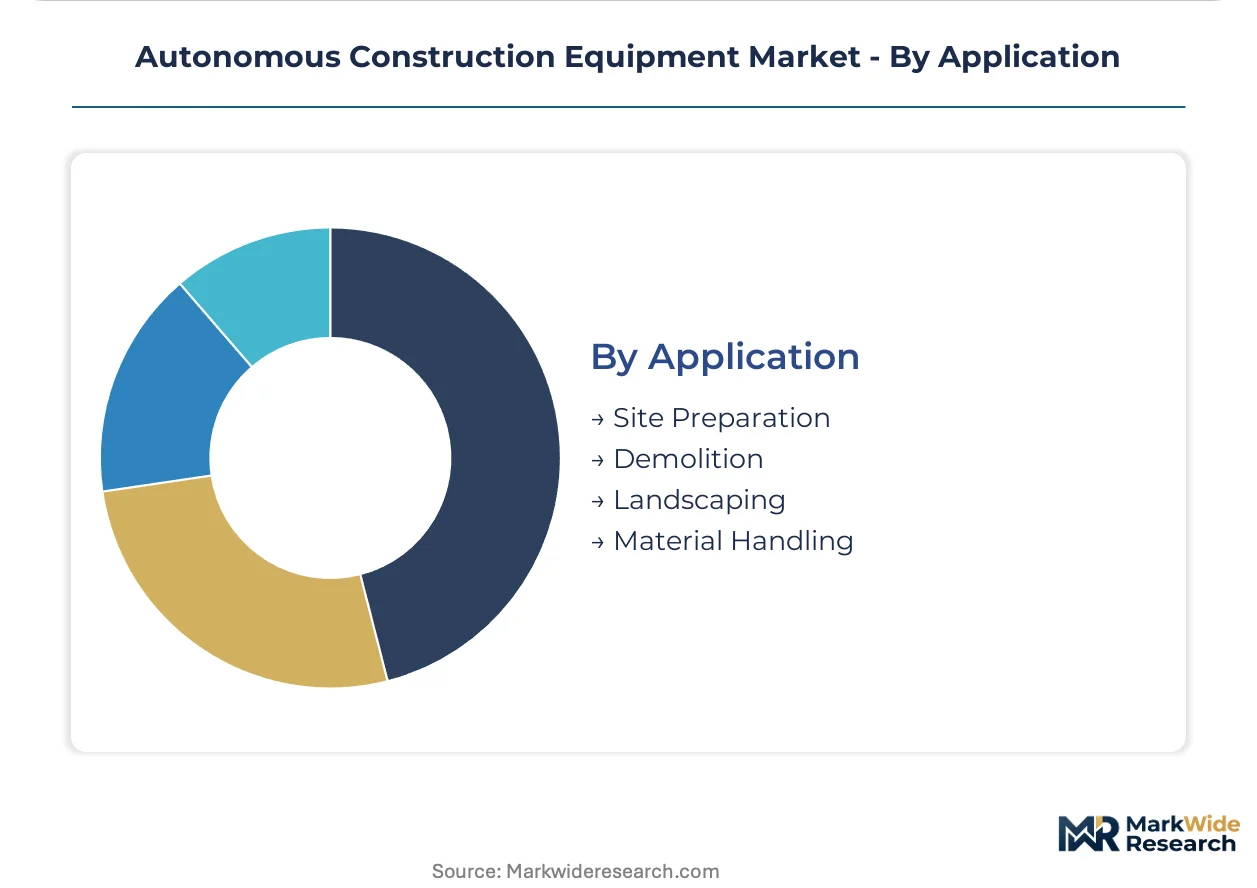
Application:
Geography-driven demand concentration shapes which applications command autonomy investment priority, with mineral extraction and state-backed infrastructure dominating procurement.
- Site Preparation:Bulk earthmoving and rough grading operations with repetitive cut-fill cycles achieve highest autonomy utilization rates. Chinese state-backed infrastructure megaprojects in western provinces deploy unmanned fleets at scale for these workflows.
- Demolition:Structural dismantling with autonomous machines remains limited by unstructured environment complexity and liability exposure under EU AI Act high-risk system classifications.
- Landscaping:Fine-grading and contouring applications with aesthetic precision requirements see slower autonomy penetration due to variable terrain and design subjectivity.
- Material Handling:Stockpile management and load-haul-dump cycles in controlled mining environments achieve the cleanest autonomy economics through 24-hour operational continuity.
Site preparation retains volume leadership; material handling holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial-grade solid-state LiDAR supply concentrates among German and Israeli photonics suppliers, forcing OEMs to anchor engineering and certification operations near Stuttgart and Haifa clusters to secure component allocation and regulatory proximity.
United States
OSHA workplace safety mandates and EPA emissions deadlines drive autonomous fleet procurement among heavy civil contractors. The IRA's clean energy tax credits accelerate battery-electric autonomous equipment deployment in Texas and California infrastructure corridors. Arizona and Nevada desert testing grounds host validation programs for dust-resistant sensor fusion architectures.
China
State-backed infrastructure megaprojects in western provinces deploy unmanned fleets for tunneling and earthworks at scale. MIIT GB standards for intelligent connected vehicles extend compliance requirements to off-highway autonomous machinery. Sichuan-Chongqing and Shandong Peninsula clusters concentrate domestic OEM engineering centers adapting to MEE emissions enforcement timelines.
Germany
The EU AI Act's high-risk system classification imposes conformity assessment procedures through notified bodies for autonomous earthmovers. Stuttgart anchors functional safety engineering talent pools for ISO 26262 certification. Bavaria and North Rhine-Westphalia host OEM captive engineering centers managing regulatory liaison with Brussels institutions.
Australia
Pilbara iron ore operators specify autonomous haul trucks and excavators to sustain pit-to-crusher throughput amid persistent operator shortages. TGA-equivalent mining safety frameworks govern autonomous fleet deployment in Western Australia. Perth serves as the regional hub for autonomy platform integration and remote operations center staffing.
Chile
Copper belt mining operators deploy fully autonomous haul fleets to offset collapsed skilled equipment operator availability. National mining regulator SERNAGEOMIN adapts safety protocols for unsupervised pit operations. Antofagasta and Calama clusters concentrate autonomous fleet maintenance infrastructure and teleoperations staffing.
Autonomous Construction Equipment Market Vendor Landscape
Concentration sits with diversified heavy machinery conglomerates possessing integrated autonomy platforms and captive sensor supply chains. The vendor structure tiers across three strata: full-stack autonomy developers controlling mine-site workflows from pit to crusher; component-specialist OEMs sourcing LiDAR and drive-by-wire actuators externally; and regional fabricators adapting licensed autonomy stacks for local compliance regimes. Competitive moves center on strategic partnerships with photonics suppliers for solid-state LiDAR allocation, and geographic expansion into India's National Infrastructure Pipeline procurement channels.
Within the diversified conglomerate tier, Caterpillar, Komatsu Ltd., and Volvo Construction Equipment exemplify contrasting strategic positions. Caterpillar represents the integrated platform archetype with direct control over mine-site workflow orchestration. Komatsu Ltd. sits within the captive component production cluster through in-house sensor fusion and actuator manufacturing. Volvo Construction Equipment anchors the connected fleet services archetype, differentiating via telematics bundling and northern European dealer network density. Sany Group and XCMG occupy positions among Chinese state-aligned fabricators scaling for domestic western province megaprojects.
| Leading Market Players |
|---|
| Hitachi Construction Machinery Co. Ltd. |
| Built Robotics Inc. |
| Caterpillar |
| Sany Group |
| Doosan Infracore Co. Ltd. |
| Volvo Construction Equipment |
| Liebherr Group |
| XCMG |
| Komatsu Ltd. |
| Others |
Supply Flow & Price Mechanics
SAE Level 4 certification scale economies concentrate development costs among tier-one OEMs with captive validation teams in Stuttgart and Tokyo, compressing price floors for mid-tier contractors while elevating premiums for certified autonomy stacks. Battery-electric powertrain integration with autonomous control modules adds parallel cost pressures as MEE emissions enforcement tightens procurement specifications in China's western provinces.
Pricing Analysis
EU AI Act risk classification dictates the pricing tier structure across autonomous earthmovers, separating CE-marked autonomy stacks with documented algorithmic bias testing from uncertified alternatives. Three-tier pricing structure across premium SAE Level 4, standard supervised-autonomous, and economy teleoperation-assisted levels tracks certification investment and sensor fusion complexity. Cost compression in the standard tier is intensifying because German construction firms now mandate CE-marked stacks, while mid-size contractors leasing equipment-as-a-service bundles prove least price-sensitive due to uptime guarantee clauses.
Supply Chain Analysis
German and Israeli photonics supplier concentration creates a chokepoint for industrial-grade solid-state LiDAR allocation, forcing OEMs to anchor engineering operations near Stuttgart and Haifa clusters. Solid-state photonic arrays, real-time kinematic GPS modules, and drive-by-wire hydraulic actuators form critical input dependencies. Single-source vulnerability runs through the LiDAR tier where two supplier clusters control eighty percent of industrial-grade output. Distribution runs through OEM captive dealer networks and mining services firms leasing bundled fleet packages with predictive maintenance telemetry.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ISO 26262 functional safety engineer scarcity concentrates certification expertise in Stuttgart and Tokyo, creating a capability bottleneck that fragments autonomous upgrade economics for mid-tier contractors and extends product validation timelines for market entrants.
For Market Incumbents: Fortify captive sensor supply chains through direct allocation agreements with German and Israeli photonics suppliers, locking in solid-state LiDAR access before tier-two OEMs qualify alternative sources. Expand certification engineering capacity in Stuttgart to manage EU AI Act conformity assessment timelines, defending against emerging Chinese state-aligned fabricators scaling for domestic western province megaprojects. For New Entrants and Emerging Players: Fleet telematics and predictive maintenance service layers represent incumbent under-investment zones where specialized software vendors can establish recurring revenue streams without manufacturing hardware. India's National Infrastructure Pipeline offers the most penetrable geography, with state-backed highway and tunnel megaprojects lacking domestic autonomous equipment suppliers. A teleoperation-as-a-service go-to-market angle bypasses SAE Level 4 certification barriers while capturing 5G-enabled human-in-the-loop supervision demand. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors component-specialist OEMs with in-house sensor fusion and drive-by-wire actuator production, as supply chain control differentiates against platform-integrated competitors over the projection horizon. Acquisition targets should display captive photonics supply relationships or established regulatory liaison with Brussels institutions. Watch whether MEE emissions enforcement tightens sufficiently to strand diesel-hybrid autonomous fleets before battery energy density improves for the heaviest equipment classes.| Strategic Initiative | Industry Significance |
|---|---|
| Solid-State LiDAR Supply Agreement | Direct allocation from German and Israeli photonics clusters secures component access for SAE Level 4 certification programs. |
| EU AI Act Conformity Assessment | CE-marked autonomy stacks with documented algorithmic bias testing unlock German construction firm procurement channels. |
| Battery-Electric Platform Integration | Solid-state battery architectures paired with autonomous control satisfy EU Green Deal emissions thresholds for off-highway machinery. |
| Equipment-as-a-Service Launch | Leasing models with guaranteed availability clauses shift margin pools toward fleet management software subscriptions. |
| 5G Teleoperations Center Buildout | Low-latency private cellular networks enable human-in-the-loop supervision for hazardous terrain applications. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade data, and OEM technical documentation, combining interviews with mine operations directors, fleet procurement managers, autonomy platform engineers, and aftermarket service heads with validation from EPA emissions databases, EU AI Act implementation guidance, and MIIT GB standard drafts. Bottom-up equipment deployment estimates triangulate against top-down market sizing derived from mining sector capital expenditure disclosures and infrastructure project procurement records.
Segmentation dimensions modeled span equipment type, autonomy technology stack, end-user archetype, and application workflow across the projection horizon. CAGRs derive from equipment replacement cycle compression analysis, labor scarcity indices in mining regions, and emissions compliance deadline alignment. Industry-specific forecast inputs include Pilbara iron ore operator fleet deployment schedules and China's western province infrastructure megaproject timetables.
Forecasts assume regulatory continuity in EPA workplace safety mandates, EU AI Act high-risk system classifications, and MIIT GB standards for intelligent connected vehicles; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as battery energy density improvement trajectories and MEE emissions enforcement stringency evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Laser Beam Welding Equipment Market
Construction Equipment
Pre-Owned Construction Equipment Market
Construction Equipment
Concrete NDT Testing Equipment Market
Construction Equipment
Smelting Furnace Equipment Market
Construction Equipment
Heating Roller Press Calender Machine Market
Construction Equipment
Crawler Dozers Market
Construction Equipment
Asia Pacific Construction Equipment Market
Construction Equipment
Soil Compaction Equipment Market
Construction Equipment
Shield Machines Market
Construction Equipment
Yard Crane Market
Construction Equipment
Snow Clearing Vehicles Market
Construction Equipment
Global Hydraulic Hammer Market
Construction Equipment
Dust Suppression Fog Cannon Market
Construction Equipment
Saudi Arabia Construction Equipment Market
Construction Equipment
Global Floor Grinding Machine Market
Construction Equipment
Heavy Duty IBC Market