
 Explosion Proof Motor Market | 2026-2036
Explosion Proof Motor Market Size, Share, and Industry Trends Forecast 2026-2036
Explosion Proof Motor Market Foresight
Buyer concentration in the oil and gas sector is consolidating as supermajors and national energy companies centralize motor procurement through framework agreements with approved vendor lists. ABB Ltd. leverages its IECEx-certified manufacturing footprint across Europe and Asia to anchor long-term supply contracts with integrated operators. Siemens AG competes through its digital twin integration for predictive maintenance of hazardous-area motors. WEG S.A. specializes in large-frame custom units for offshore platforms, sustaining its position in Brazilian and West African deepwater projects.
An explosion proof motor is an electric drive engineered with reinforced enclosures, sealed terminal boxes, and temperature-limited windings to prevent ignition of flammable gases, vapors, or dusts in classified hazardous locations. These motors typically carry T-code temperature ratings and IP66 ingress protection, with cast iron or aluminum housings machined to contain internal explosions without transmitting flame to the surrounding atmosphere. AC Motors dominate installed base value due to their prevalence in continuous-process industries, while Servo Motors represent the fastest-expanding product category as precision motion control penetrates automated chemical batching and pharmaceutical packaging lines. DC Motors retain niche dominance in mining haulage applications where variable torque at low speed remains essential.
ATEX directives in Europe, IECEx schemes across Asia-Pacific and Middle East markets, and OSHA's NRTL requirements in the United States collectively mandate third-party certification for equipment deployed in explosive atmospheres, creating compliance barriers that favor established manufacturers with in-house testing laboratories. The EU F-Gas Regulation and parallel EPA restrictions on fluorinated greenhouse gases are also influencing enclosure sealing material specifications and thermal management designs. Stakeholders must monitor evolving harmonization gaps between IECEx and national certification regimes when configuring regional product portfolios and service networks.
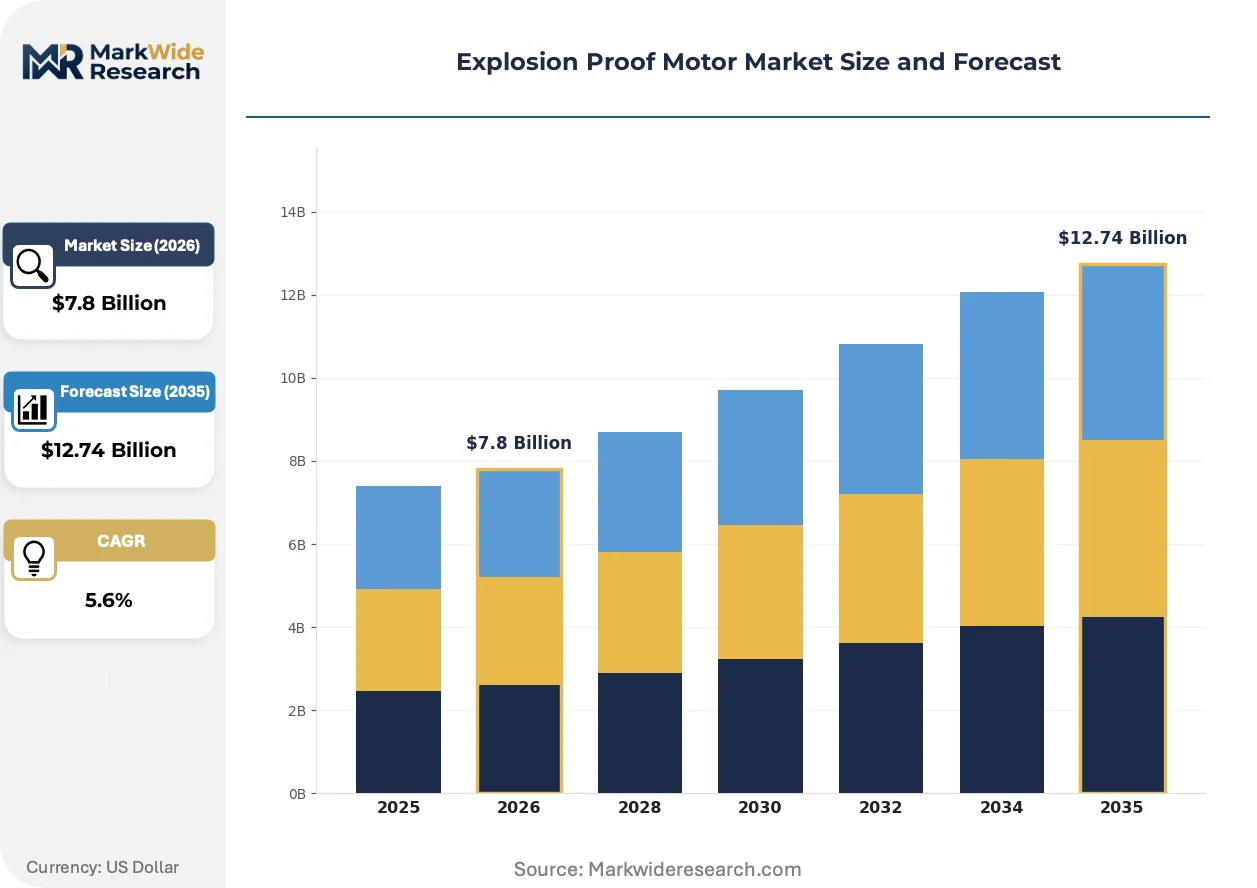
Market Dynamics
Refinery operators on the United States Gulf Coast are consolidating motor procurement through multi-year framework agreements, compressing vendor margins while locking in capacity for LNG export terminal expansions and petrochemical complex upgrades.
Growth Catalysts
- IECEx Certification Harmonization:Unified testing protocols across Asia-Pacific markets are reducing duplicate certification costs for manufacturers supplying offshore platforms in Australian and Malaysian waters.
- LNG Export Infrastructure:Cryogenic gas processing facilities in Qatar and the United States require Class I Division 1 motors for compressor trains and cryogenic pumps handling liquefied natural gas.
- Copper Rotor Die-Casting:Advanced conductor materials are improving thermal efficiency in high-horsepower units deployed in Middle Eastern desalination plants operating at sustained loads.
Market Restraints
- Cast Iron Input Volatility:Foundry-grade pig iron prices fluctuate with Chinese steel output curbs, squeezing enclosure manufacturing margins for European producers.
- Testing Laboratory Concentration:IECEx certification capacity clusters in Germany and the United Kingdom, creating bottlenecks for Asian manufacturers seeking market entry.
- Permanent Magnet Substitution:Rare-earth magnet motors threaten AC induction designs in variable-speed applications below 200 horsepower.
Strategic Opportunities
- West African Deepwater:Pre-salt discoveries off Angola and Nigeria lack established hazardous-area motor supply chains, favoring early entrants with local service depots.
- Hydrogen Electrolyzer Integration:Green hydrogen production facilities require explosion-proof motors for electrolyzer compression and hydrogen liquefaction skids.
- Digital Twin Convergence:Vibration monitoring and thermal modeling software bundled with motor sales are creating recurring revenue streams for OEMs.
Industry Challenges
- IECEx-ATEX Divergence:Harmonization gaps between international and European certification regimes force manufacturers to maintain parallel testing documentation for cross-border projects.
- Legacy System Integration:Retrofitting flameproof motors into 1980s-era refinery motor control centers requires custom adapter kits and extended commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Explosion Proof Motor Market |
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $12.74 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AC Motors, DC Motors, Servo Motors, Synchronous Motors Installation: Hazardous Locations, Marine Environments, Industrial Facilities, Oil & Gas Setup End User: Manufacturing, Chemical Processing, Pharmaceuticals, Mining Service Type: Maintenance, Repair, Customization, Consultation |
| Companies Covered | Emerson Electric Co., Nidec Corporation, ABB Ltd., Rockwell Automation Inc., WEG S.A., Siemens AG, Schneider Electric SE, Toshiba Corporation, General Electric Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Explosion Proof Motor Market Shifts & Advancements
Condition-based monitoring and predictive analytics are penetrating hazardous-area motor fleets, shifting maintenance from calendar-based intervals to failure-mode-driven interventions that reduce unplanned shutdowns in continuous-process industries.
Intelligent motor protection relays with embedded edge computing are automating fault detection in petrochemical pump stations. Shell and BP are deploying these systems across North Sea and Gulf of Mexico assets. The technology is automating workforce redeployment from routine inspection rounds to exception-based intervention.
The EU F-Gas Regulation is tightening restrictions on fluorinated greenhouse gases used in motor terminal box sealing compounds. German and Italian manufacturers are reformulating gaskets and potting materials to comply with phasedown schedules. High-voltage wound-rotor designs face the steepest reformulation costs due to larger sealing volumes.
Integrated operators are unbundling aftermarket service from initial equipment purchases, awarding multi-site maintenance contracts to third-party specialists. This procurement model is displacing traditional OEM service monopolies in United States refineries. The shift is most pronounced among supermajors with centralized reliability engineering functions.
Explosion Proof Motor Market Segmentation
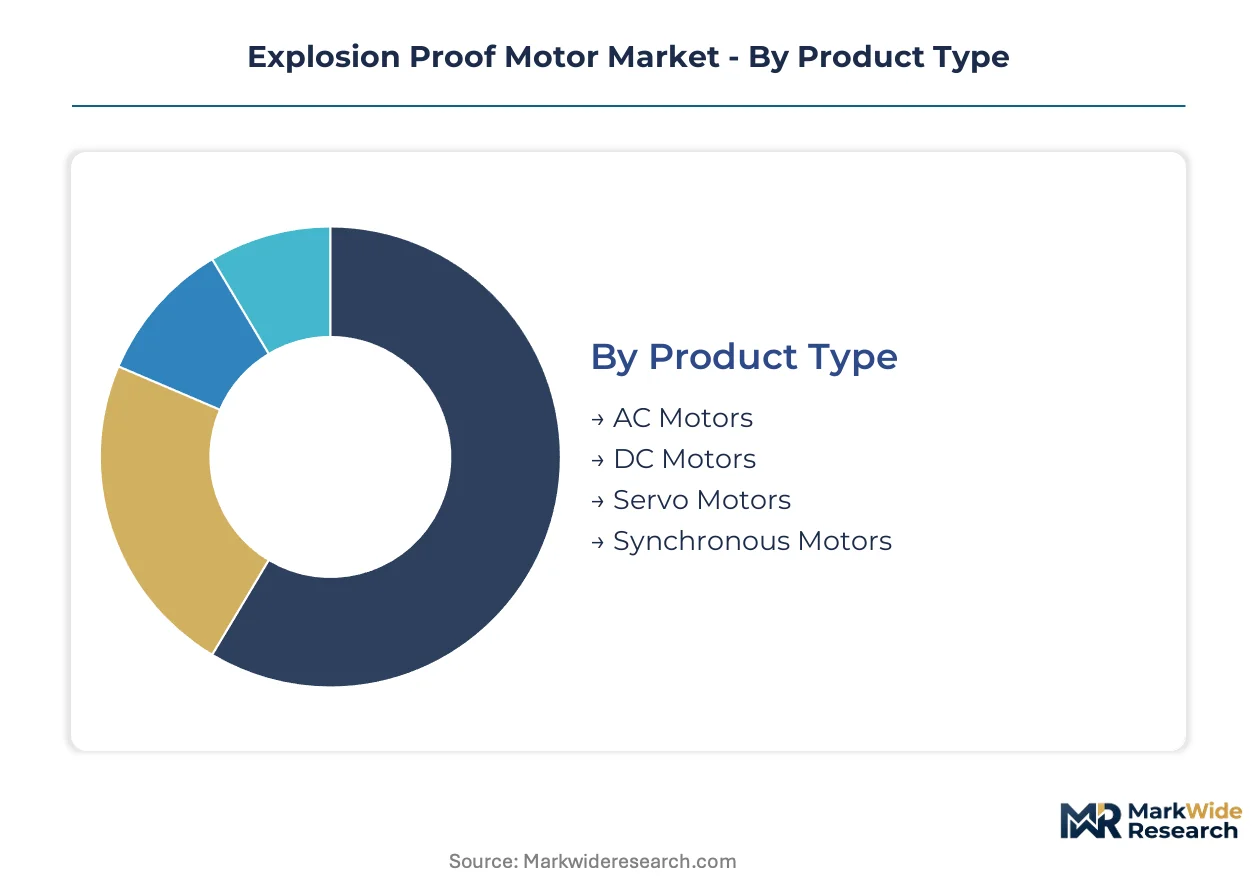
Explosion proof motor procurement splits across multiple technical and commercial axes. Specification requirements vary sharply between continuous-process industries and intermittent-duty applications. Certification complexity and service intensity create distinct margin profiles across each segment cluster.
Product Type:
AC induction architectures dominate hazardous-area installations due to thermal stability and certification familiarity.
- AC Motors:Squirrel-cage and wound-rotor designs with T-code temperature ratings anchor refinery and petrochemical demand. IECEx-certified foundries in Germany and Italy concentrate production for North Sea and Middle Eastern upstream projects. Copper rotor die-casting advances are improving efficiency in sustained-load desalination applications.
- Servo Motors:Precision motion control units with integrated encoders penetrate automated chemical batching and pharmaceutical packaging lines. Closed-loop positioning requirements in sterile filling operations drive specification toward IP66 ingress protection and stainless steel housings.
- DC Motors:Retain mining haulage dominance where variable torque at low speed remains essential for dragline and shovel applications.
- Synchronous Motors:Deploy in compressor trains requiring power factor correction across LNG liquefaction facilities.
Mature deployment sits with AC Motors. Newer deployment is concentrated in Servo Motors.
Installation:
Environmental classification determines enclosure engineering and certification pathway costs.
- Oil & Gas Setup:Class I Division 1 and Zone 0/1 rated equipment for drilling rigs, production platforms, and pipeline compressor stations. Gulf Coast petrochemical corridor demand concentrates procurement through supermajor framework agreements. ATEX and IECEx dual certification requirements inflate documentation costs for cross-border projects.
- Hazardous Locations:General-purpose flameproof installations in chemical processing and solvent handling facilities. OSHA NRTL mandates govern United States deployment, creating compliance barriers for Asian manufacturers without domestic testing partnerships.
- Marine Environments:Salt-resistant coatings and sealed terminal boxes for offshore platforms and LNG carriers.
- Industrial Facilities:Dust-ignition-proof variants for grain handling and powder processing operations.
Volume concentration favors Oil & Gas Setup. Margin expansion is strongest in Hazardous Locations.
End User:
Process intensity and safety culture shape replacement cycles and specification sophistication.
- Chemical Processing:Continuous-duty pumps and agitators in corrosive atmospheres require Hastelloy or duplex stainless steel enclosures. European REACH compliance and EPA TSCA restrictions on sealing compounds force material reformulation cycles.
- Pharmaceuticals:Cleanroom-compatible servo drives with washdown ratings for tablet pressing and sterile filling. FDA validation requirements extend commissioning timelines and favor established OEMs with documentation libraries.
- Mining:Underground coal and metal operations specify explosion-proof haulage motors with MSHA or national mining authority approval.
- Manufacturing:Paint spraying and coating operations deploy Zone 1 motors with integrated variable frequency drives.
Specification complexity peaks in Chemical Processing. Procurement consolidation is advancing fastest in Pharmaceuticals.
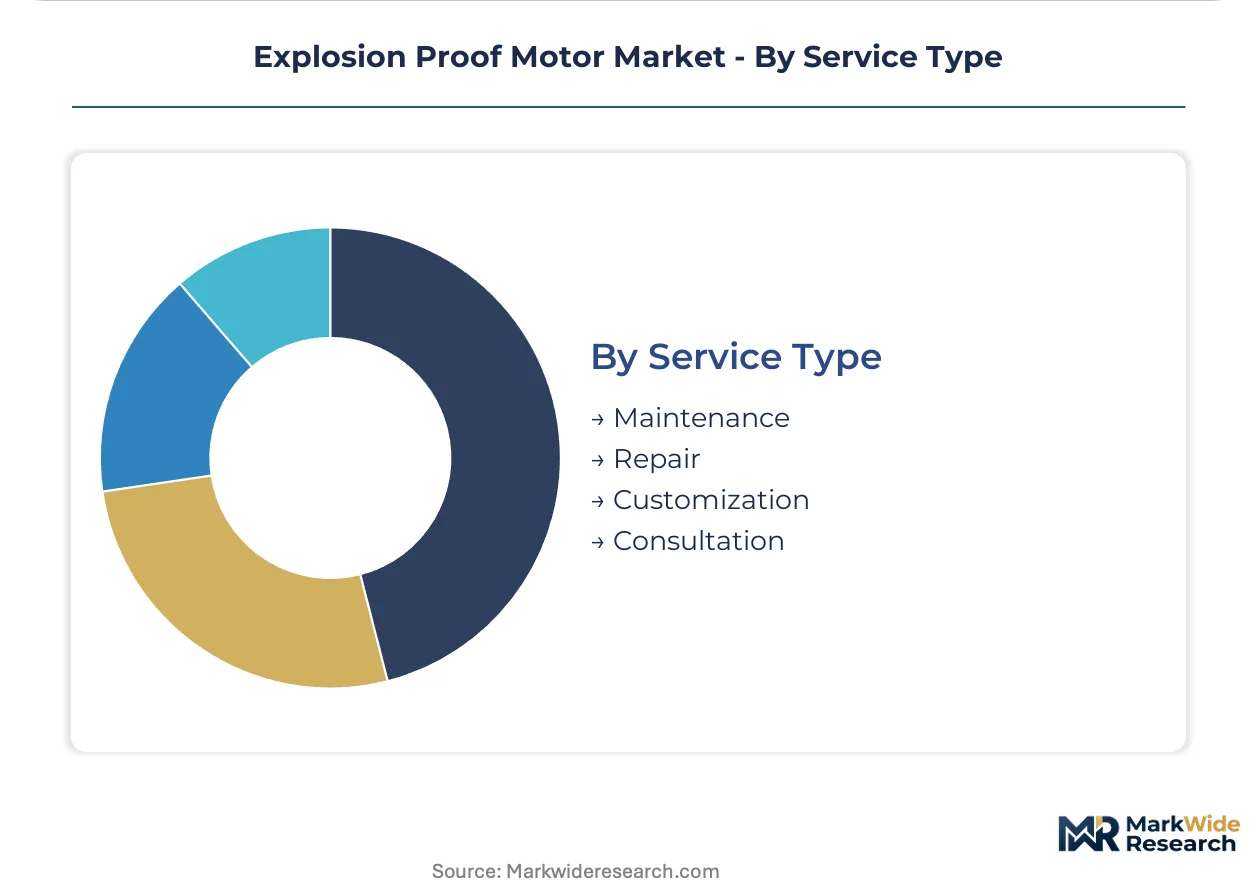
Service Type:
Aftermarket revenue models are unbundling from equipment sales across integrated operator portfolios.
- Maintenance:Condition-based monitoring contracts with vibration analysis and thermal imaging. Shell and BP are deploying predictive analytics across North Sea and Gulf of Mexico motor fleets.
- Repair:Rewinding and recertification services for large-frame units where replacement lead times exceed outage windows.
- Customization:Adapter kits for legacy motor control center retrofits and special shaft configurations.
- Consultation:Hazardous area classification studies and specification auditing for greenfield projects.
Recurring revenue potential is highest in Maintenance. Project-based demand concentrates in Consultation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Upstream oil and gas investment concentrates procurement of Class I Division 1 rated equipment along the United States Gulf Coast, where refinery expansions and LNG export terminal construction drive sustained demand for flameproof drives.
United States
Gulf Coast petrochemical corridor operators consolidate motor procurement through multi-year framework agreements with approved vendor lists. OSHA's NRTL requirements govern hazardous-area equipment deployment, creating compliance barriers for manufacturers without domestic testing partnerships. Corpus Christi and Lake Charles anchor demand for large-frame compressor train motors serving LNG liquefaction facilities.
Germany
IECEx-certified foundries in Bavaria and North Rhine-Westphalia concentrate production for North Sea offshore platforms and Middle Eastern upstream projects. The EU F-Gas Regulation tightens restrictions on fluorinated sealing compounds, forcing material reformulation cycles for terminal box gaskets. Ruhr industrial clusters supply wound-rotor designs for sustained-load desalination applications across the Persian Gulf.
China
State-owned refiners expand procurement of explosion-proof drives for petrochemical complex upgrades along the Yangtze River Delta. GB standards and MIIT industrial safety mandates shape enclosure specifications for domestic hazardous-location installations. Shanghai and Ningbo manufacturing bases serve both domestic demand and export markets across Southeast Asian offshore developments.
Saudi Arabia
Aramco's offshore and downstream expansion programs require Class I Division 1 motors for drilling rigs and gas processing facilities. The country's national industrial safety regulator mandates third-party certification for equipment deployed in explosive atmospheres at Jubail and Yanbu industrial cities. Eastern Province clusters concentrate demand for copper rotor designs operating at sustained loads in desalination and petrochemical applications.
Brazil
Pre-salt discoveries off Angola and Nigeria lack established hazardous-area motor supply chains, positioning Brazilian fabricators with deepwater project experience for regional export. ANVISA and national mining authority approvals govern underground coal and metal operations equipment specifications. Rio de Janeiro and São Paulo engineering centers support offshore platform motor customization for West African developments.
Explosion Proof Motor Market Competitive Landscape
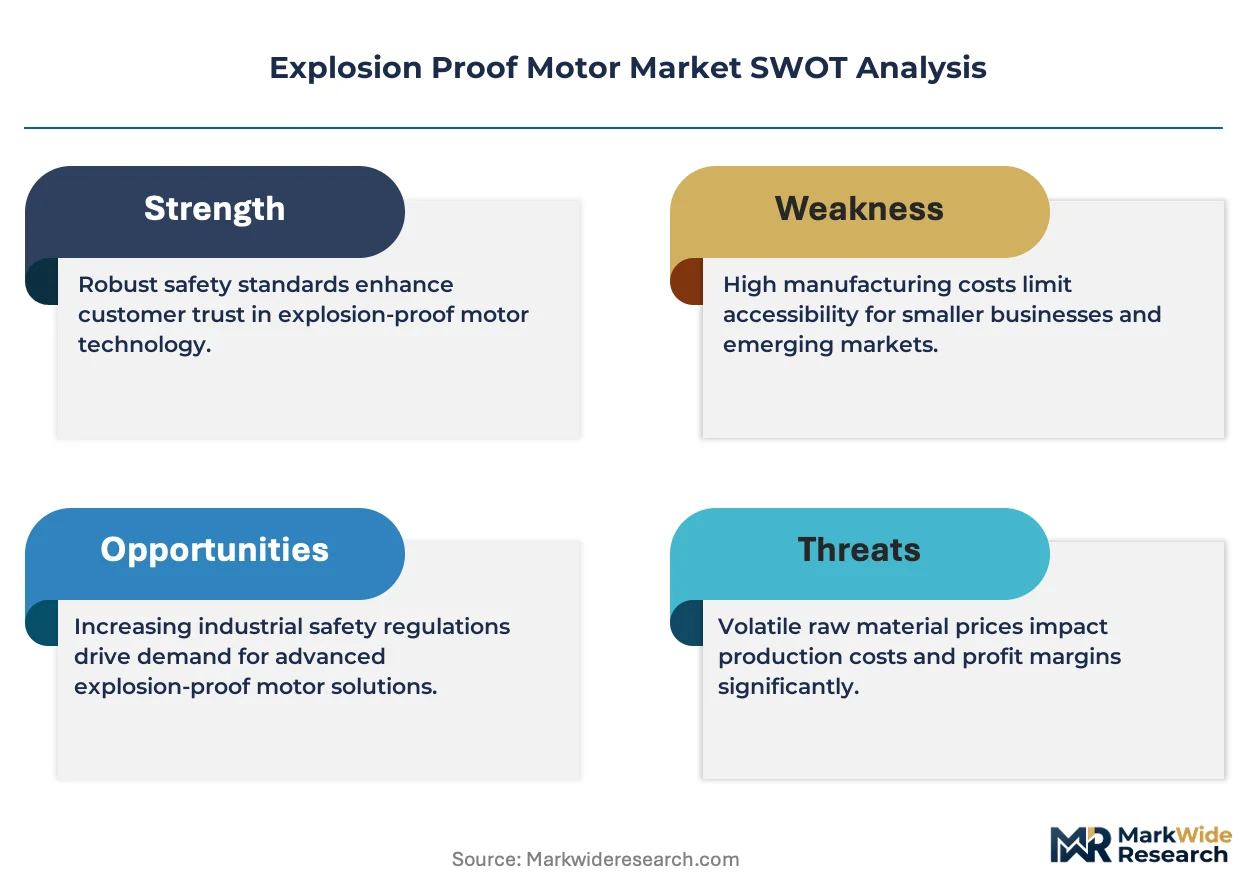
Established producers occupy the standard tier; emerging entrants pursue digital twin integration and predictive maintenance services as differentiation vectors. The vendor base stratifies across three tiers: integrated electrical conglomerates with in-house certification laboratories, regional specialists in large-frame custom units, and component suppliers seeking downstream assembly partnerships. Competitive positioning hinges on IECEx and ATEX dual certification capabilities, aftermarket service network density, and bundling of condition-based monitoring software with hardware sales. Capacity expansion and strategic technology licensing represent the dominant competitive moves, particularly for hydrogen electrolyzer and carbon capture applications.
Within the integrated tier, ABB Ltd. and Siemens AG exemplify archetypes combining hazardous-area manufacturing footprints with digital service portfolios. WEG S.A. occupies a specialist position anchored in large-frame custom fabrication for offshore environments. These three entities represent distinct strategic postures: European certification leadership, predictive maintenance convergence, and deepwater project execution respectively.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| Nidec Corporation |
| ABB Ltd. |
| Rockwell Automation Inc. |
| WEG S.A. |
| Siemens AG |
| Schneider Electric SE |
| Toshiba Corporation |
| General Electric Company |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between IECEx-ATEX dual-certified premium units and single-certification economy motors manifests in both pricing power and supply chain configuration. Premium tier manufacturers command pricing leverage through captive testing laboratory capacity in Germany and the United Kingdom, while economy producers face margin compression from foundry-grade pig iron volatility tied to Chinese steel output curbs.
Pricing Analysis
Volume-mass split concentrates margin in large-frame custom units above 500 horsepower for offshore platforms, while standardized sub-200 horsepower induction motors compete on procurement efficiency through supermajor framework agreements. Price differentiation rests on IECEx-ATEX dual certification status and bundled digital twin services, with Gulf Coast petrochemical operators least sensitive due to outage cost exposure and Asian trading houses most price-sensitive in spot procurement. Cost compression in the standard tier is intensifying as permanent magnet motors threaten AC induction designs below 200 horsepower.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Houston anchor hub-and-spoke patterns for spare parts and emergency replacement units serving offshore platforms. Manufacturing concentration centers on Germany, Italy, and China for foundry and winding operations, with copper rotor die-casting and rare-earth magnet sourcing drawing from Chilean mining and Chinese processing clusters. Single-source vulnerability concentrates in IECEx certification capacity clustered in German and British testing laboratories. Distribution runs through OEM-direct channels for large-frame units and authorized distributor networks for standardized replacements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Permanent magnet motor architectures are displacing AC induction designs in variable-speed applications below 200 horsepower, compressing the addressable market for legacy explosion-proof motor configurations and forcing incumbents to restructure R&D allocation toward servo and synchronous motor platforms.
For Market Incumbents: Acquire IECEx-certified testing laboratory capacity to defend certification moats against Asian manufacturers seeking European market entry. Consolidate aftermarket service networks through multi-site maintenance contract aggregation, displacing third-party specialists that supermajors increasingly favor. Permanent magnet substitution in sub-200 horsepower segments threatens volume-margin pools in standard induction motor lines. For New Entrants and Emerging Players: Capture hydrogen electrolyzer integration demand for explosion-proof motors in electrolyzer compression and hydrogen liquefaction skids, where certification requirements remain fluid and early entrant positioning is achievable. West African deepwater developments off Angola and Nigeria lack established hazardous-area motor supply chains, offering white-space entry for fabricators with offshore platform execution experience. Partner with regional EPC contractors on greenfield LNG export terminals to bypass incumbent OEM service monopolies. For Investors and Strategic Acquirers: Re-rating potential sits with digital twin-integrated motor OEMs given predictive maintenance bundling creating recurring revenue streams and customer switching costs. Long-term viability favors specialists with in-house certification laboratories and hydrogen electrolyzer application expertise over commodity induction motor producers. Watch IECEx-ATEX harmonization progress as inflection signal—convergence would compress certification barriers and accelerate Asian manufacturer market share gains.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Copper Rotor Die-Casting | Captures thermal efficiency gains for sustained-load desalination applications in Middle Eastern plants. |
| Digital Twin Platform Integration | Shell and BP deployments across North Sea assets demonstrate predictive maintenance revenue potential. |
| Hydrogen Electrolyzer Certification Investment | Green hydrogen production facilities require Class I Division 1 motors for compression train applications. |
| West African Service Depot Expansion | Pre-salt discoveries off Angola and Nigeria lack established hazardous-area motor supply infrastructure. |
| F-Gas Compliant Sealing Material Reformulation | German and Italian manufacturers face EU Regulation mandates on fluorinated terminal box compounds. |
Research Methodology
Multi-period observation of IECEx certification queue volumes, foundry-grade pig iron pricing, and supermajor framework agreement award patterns anchored the trend analysis, supplemented by interviews with maintenance directors at Gulf Coast refineries, OEM procurement teams at integrated oil and gas operators, aftermarket service heads at European motor manufacturers, and plant engineers at Middle Eastern desalination facilities. Secondary validation drew from OSHA NRTL registry data, EU F-Gas Regulation implementation notices, SEC filings of listed electrical equipment manufacturers, and customs records of explosion-proof motor trade flows. Bottom-up unit demand modeling and top-down industry spend estimates were triangulated to constrain forecast variance.
Input-output matrix framing connected raw material cost indices and certification capacity utilization to regional demand projections across the analysis window. Segmentation dimensions modeled include product architecture, installation classification, end-use process intensity, and service revenue attachment rate. CAGRs were derived from slope-intercept fitting of observed procurement volumes against capital expenditure cycles in petrochemical and LNG infrastructure. Industry-specific forecast inputs incorporated hydrogen electrolyzer deployment pipelines and West African deepwater project sanctioning timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to IECEx-ATEX harmonization gaps, permanent magnet motor substitution rates, and Chinese steel output policy shifts affecting foundry input costs. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Motors
Power Scraper Market
Industrial Motors
North America Induction Motor Market
Industrial Motors
Europe Hazardous Location Motors Market
Industrial Motors
Latin America Electric Drives Market
Industrial Motors
US Electric Motor Market
Industrial Motors
AC Servo Motors and Drives Market
Industrial Motors
Industrial Personnel and Burden Carriers [Electric] Market
Industrial Motors
Global Parallel Shaft Geared Motors Market
Industrial Motors
Explosion Proof Electric Motors and Actuators Sales Market
Industrial Motors
Smart Motors Market
Industrial Motors
Vertical Gear Motor Market
Industrial Motors
Industrial Motor Market
Industrial Motors
Germany AC Motor Market
Industrial Motors
Global Sliding Vane Air Motor Market
Industrial Motors
Industrial Motor Brakes Market
Industrial Motors
Middle East and Africa Variable Frequency Drive (VFD) Market