
 Global Parallel Shaft Geared Motors Market | 2026-2036
Global Parallel Shaft Geared Motors Market Size, Share, and Industry Trends Forecast 2026-2036
Global Parallel Shaft Geared Motors Market Intelligence
Market Dynamics
Buyer concentration among automation integrators and conveyor OEMs is realigning procurement toward suppliers with modular platform architectures. Siemens AG leverages its integrated automation portfolio to anchor large manufacturing accounts across Europe and Asia. NORD Drivesystems specializes in decentralized drive concepts that reduce cabinet complexity for material handling end users. SEW-EURODRIVE dominates in heavy-duty configurations for mining and bulk handling applications where torque density requirements are severe.
Technical Profile and Segment Structure
Global Parallel Shaft Geared Motors transmit rotational power through offset input and output shafts, typically achieving reduction ratios from 1.5:1 to 10,000:1 through helical or worm gear stages housed in cast iron or aluminum enclosures. Helical configurations lead unit volumes due to their efficiency and noise advantages in continuous-duty conveyor systems, while worm gear variants retain strong positions in packaging equipment where self-locking and high reduction in single stages justify lower mechanical efficiency. Servo motor integration represents the fastest-growing technology segment as robotics and precision positioning applications displace traditional induction motor pairings. Manufacturing plants and automation firms constitute the deepest margin pools among end user industries, driven by lifecycle service contracts and retrofit demand.
Regulatory Environment and Outlook
The EU Ecodesign Directive and IEC 60034-30-1 efficiency classes constrain motor selection across European manufacturing plants, while China's GB 18613 standards and the US Department of Energy minimum efficiency regulations impose comparable technical barriers in their respective markets. Japan's METI Top Runner program and India's BIS certification requirements add further compliance dimensions for multinational suppliers. Stakeholders must monitor evolving efficiency tier transitions and carbon border adjustment mechanisms that will reshape total cost of ownership calculations for geared motor procurement.
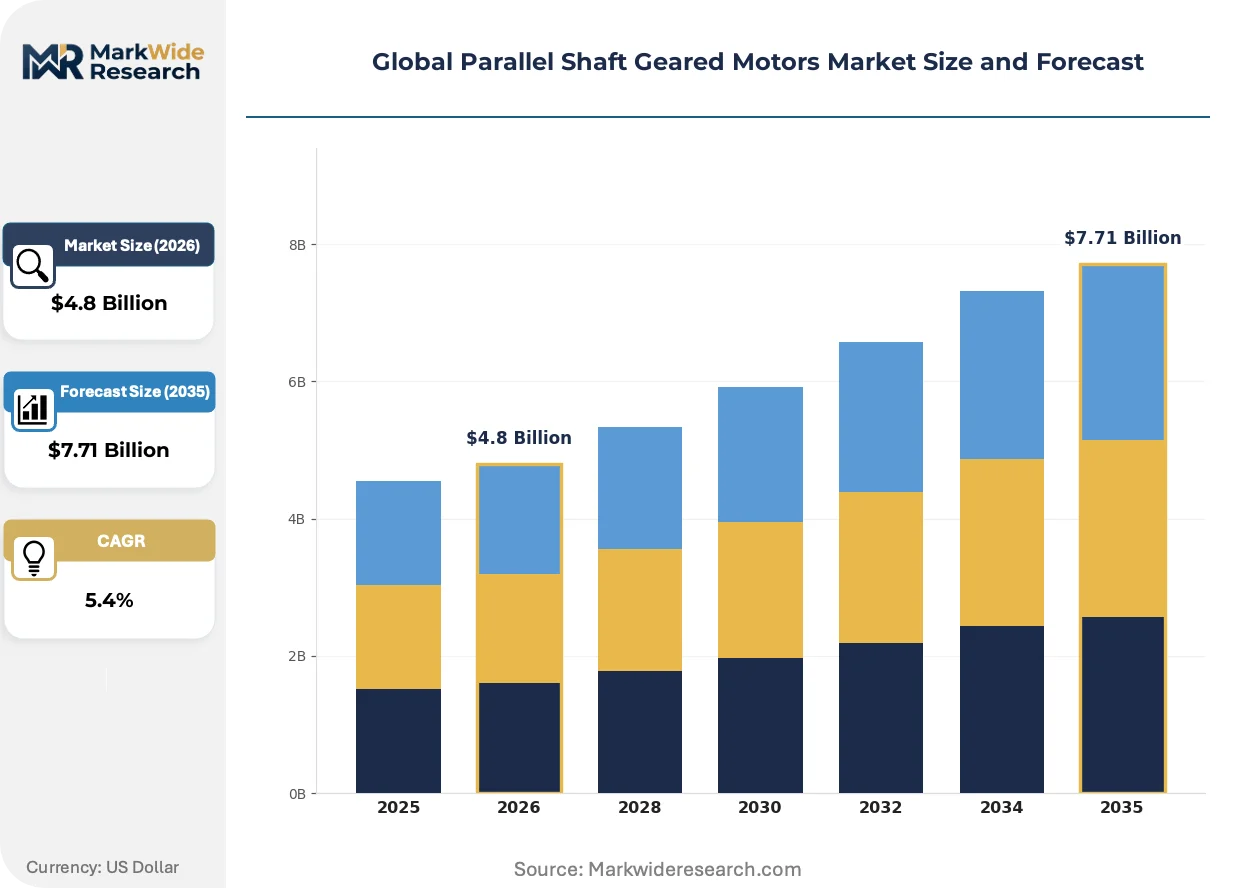
Market Dynamics
EU Ecodesign Directive efficiency tiers and China's GB 18613 standards are compressing induction motor viability while servo-integrated architectures capture specification share in automated material handling systems.
Growth Catalysts
- EU Ecodesign Directive:IE4 and IE5 efficiency mandates are eliminating lower-tier motor inventories from European manufacturing procurement lists, forcing upgrade cycles across conveyor OEMs and automation integrators.
- Helical gear configurations:Continuous-duty warehouse automation and e-commerce fulfillment centers specify helical stages for noise attenuation and energy recovery in 24-hour operational environments.
- Reshoring manufacturing investments:Germany, the United States, and China are expanding domestic production capacity, directly lifting demand for localized geared motor supply with rapid spare parts availability.
Market Restraints
- Copper and rare earth magnet volatility:Servo motor integration depends on neodymium supply concentrated in Chinese processing facilities, exposing cost structures to export quota fluctuations.
- Cast iron enclosure lead times:Foundry capacity constraints in India and Southeast Asia extend delivery schedules for heavy-duty mining configurations beyond 16 weeks.
- Worm gear efficiency ceiling:Single-stage worm variants face displacement in high-cycle applications where helical-bevel combinations deliver 15-20 point efficiency advantages.
Strategic Opportunities
- India BIS certification expansion:Domestic manufacturing incentives under the PLI scheme are creating captive demand for locally certified drive systems in automotive and pharmaceutical packaging lines.
- Decentralized drive architectures:Cabinet-free motor-mounted electronics reduce installation labor and panel footprint, opening specification wins in retrofit brownfield facilities.
- Predictive maintenance integration:Vibration and temperature sensors embedded in gear housings enable condition-based service contracts with lifecycle revenue capture.
Industry Challenges
- Servo tuning expertise scarcity:Precision positioning applications require controls engineering capabilities that diverge from traditional induction motor commissioning skill bases.
- Legacy system protocol fragmentation:Fieldbus compatibility layers for PROFINET, EtherCAT, and DeviceNet extend integration timelines and erode margin on brownfield retrofit projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Parallel Shaft Geared Motors Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.71 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Helical, Worm, Spur, Bevel, Hypoid, Others Technology: Induction, Synchronous, Servo, DC Brushless, Stepper, Universal Application: Conveyor Systems, Material Handling, Textile Machinery, Packaging Equipment, Food Processing, Robotics End User Industry: Manufacturing Plants, Automation Firms, Mining Operations, Agricultural Equipment Builders, Shipyards |
| Companies Covered | Siemens AG, NORD Drivesystems, Mitsubishi Electric Corporation, SEW-EURODRIVE, Bonfiglioli, Bodine Electric Company, Toledo Gearmotor, WEG, Bison Gear, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Parallel Shaft Geared Motors Market Strategic Shifts & Innovations
Servo motor integration is compressing the traditional boundary between mechanical power transmission and motion control, collapsing procurement decisions into unified automation platform selections.
Permanent magnet synchronous motors paired with helical gear stages are absorbing specification share from induction motor pairings in precision positioning applications. Robotics OEMs and automated guided vehicle manufacturers specify these configurations for torque density and dynamic response. The technology is absorbing margin from standalone gearbox suppliers as integrated motion control platforms capture specification authority.
China's GB 18613-2020 efficiency standards and the US Department of Energy minimum efficiency regulations are synchronizing technical barriers across the two largest manufacturing economies. Motor manufacturers must maintain parallel certification streams for IE4/IE5 equivalence and NEMA Premium efficiency tiers. Heavy-duty configurations for mining and bulk handling face the steepest compliance cost escalation due to thermal management requirements in high-reduction ratios.
Lifecycle service contracts are displacing transactional equipment sales among automation integrators and conveyor OEMs. Predictive maintenance subscriptions and guaranteed uptime agreements now anchor vendor selection criteria in German automotive manufacturing and US e-commerce fulfillment networks. Japanese automotive parts suppliers pioneered this procurement model, which is now compressing pricing transparency as total cost of ownership calculations subsume upfront capital expenditure comparisons.
Global Parallel Shaft Geared Motors Market Segmentation
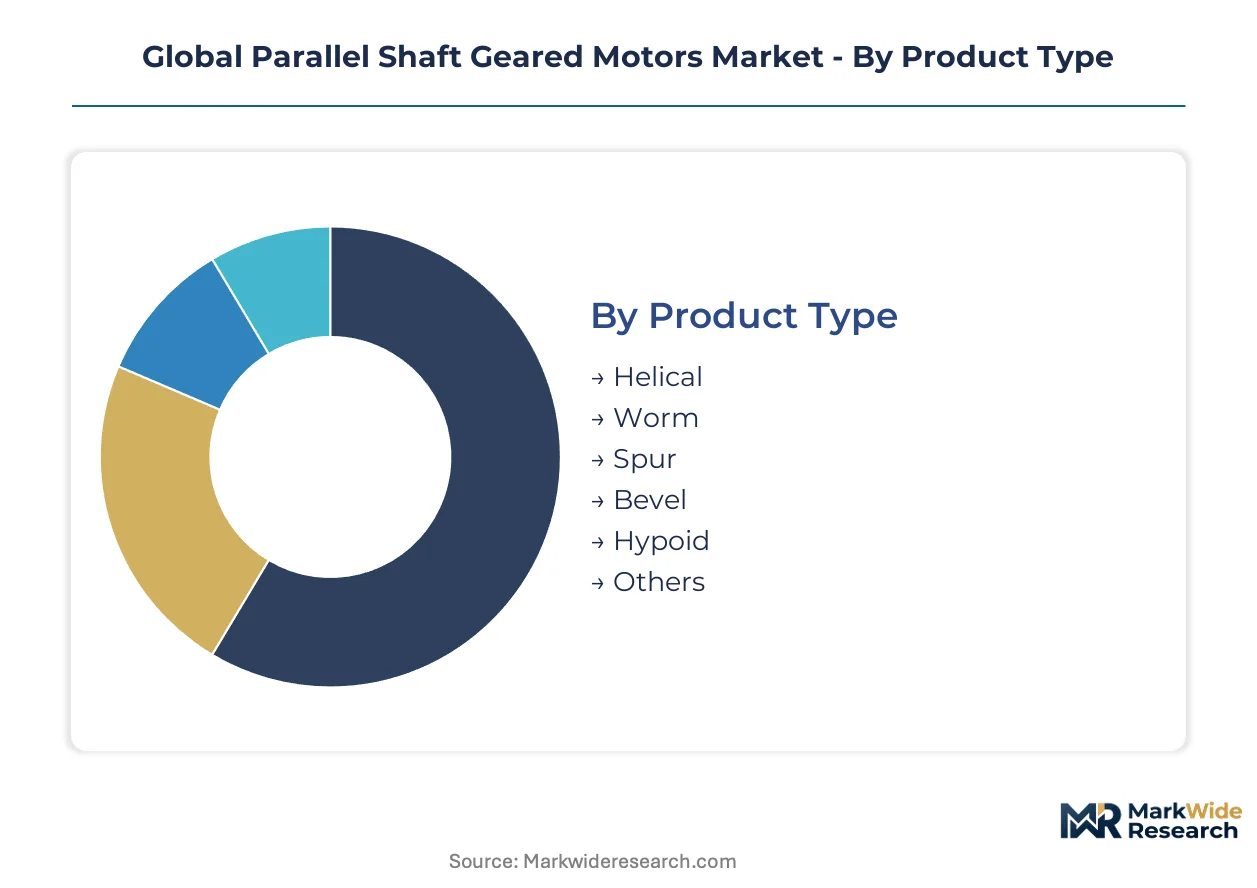
Procurement patterns in parallel shaft geared motors diverge sharply across gear geometries, motor technologies, and end-use intensity. Specification authority rests with automation integrators who prioritize efficiency tiers, noise profiles, and lifecycle service integration over upfront capital cost.
Product Type:
Buyer selection hinges on duty cycle severity and acoustic constraints rather than initial purchase price.
- Helical:Helical gear stages employ angled tooth engagement to distribute load across multiple contact points, achieving 96-98% mechanical efficiency with noise levels 10-15 dB lower than spur alternatives. Demand concentrates in German automotive manufacturing and US e-commerce fulfillment centers where 24-hour conveyor operation mandates energy recovery and acoustic compliance. Continuous-duty warehouse automation specifications favor helical configurations for their thermal stability under sustained load.
- Worm:Single-stage worm gears deliver high reduction ratios through screw-and-wheel meshing, providing intrinsic self-locking that eliminates braking hardware in vertical lifting applications. Packaging equipment OEMs in Japan and Italy specify worm variants for compact footprint and holding torque security despite 50-90% efficiency ceilings. High-cycle material handling systems are displacing worm configurations where helical-bevel combinations recover energy.
- Spur:Straight-cut spur gears offer lowest-cost entry points for intermittent-duty machinery with modest speed reduction requirements.
- Bevel:Right-angle power transmission suits constrained installation envelopes in textile machinery and agricultural conveyors.
- Hypoid:Offset bevel geometry permits larger pinion diameters for torque density in mining crusher drives.
- Others:Planetary and cycloidal variants serve specialized indexing and precision positioning niches.
Volume sits with Helical configurations across automated material handling; growth tilts toward Hypoid in heavy-duty extraction applications requiring maximum torque density.
Technology:
Regulatory efficiency mandates are compressing induction motor viability while integrated motion control architectures capture specification share.
- Induction:Squirrel-cage induction motors dominate installed base volumes through proven reliability and maintenance simplicity, but EU Ecodesign Directive IE4/IE5 tiers and China's GB 18613-2020 standards are eliminating lower-efficiency inventories from procurement lists. Retrofit demand persists in brownfield manufacturing plants where controls infrastructure cannot accommodate encoder feedback systems.
- Servo:Permanent magnet synchronous motors with integrated encoders deliver closed-loop positioning accuracy within 0.01 degrees, collapsing the boundary between mechanical power transmission and motion control. Robotics OEMs and automated guided vehicle manufacturers specify servo-integrated architectures for dynamic response and torque density. The technology is absorbing margin from standalone gearbox suppliers as unified automation platforms capture specification authority.
- Synchronous:Reluctance and permanent magnet synchronous designs bridge efficiency gaps for mid-tier automation without full servo complexity.
- DC Brushless:Electronic commutation suits battery-powered mobile equipment and hazardous environment installations.
- Stepper:Open-loop positioning serves low-cost indexing and dispensing machinery with moderate precision requirements.
- Universal:Series-wound commutator motors retain niche positions in portable tools and adjustable-speed applications.
Installed base remains concentrated in Induction; steepest expansion trajectory belongs to Servo as precision positioning displaces traditional pairings.
Application:
Operational intensity and uptime guarantees determine gear motor specification tier across machinery categories.
- Conveyor Systems:Belt and roller conveyor drives constitute the deepest volume pool, with helical configurations specified for 24-hour e-commerce fulfillment operations in the United States and Germany. Predictive maintenance subscriptions and guaranteed uptime agreements anchor vendor selection criteria.
- Material Handling:Crane, hoist, and automated storage retrieval systems demand high starting torque and thermal reserves for intermittent peak loads.
- Textile Machinery:Spinning and weaving applications prioritize noise attenuation and vibration isolation for operator working environments.
- Packaging Equipment:Cartoning, filling, and labeling lines specify compact right-angle drives for confined machinery envelopes.
- Food Processing:Stainless steel enclosures and sanitary washdown ratings dominate procurement criteria for meat, dairy, and beverage processing.
- Robotics:Articulated arm and gantry systems require servo-integrated precision for path repeatability and collision recovery.
Volume concentrates in Conveyor Systems; Packaging Equipment is climbing the fastest as pharmaceutical and consumer goods automation accelerates.
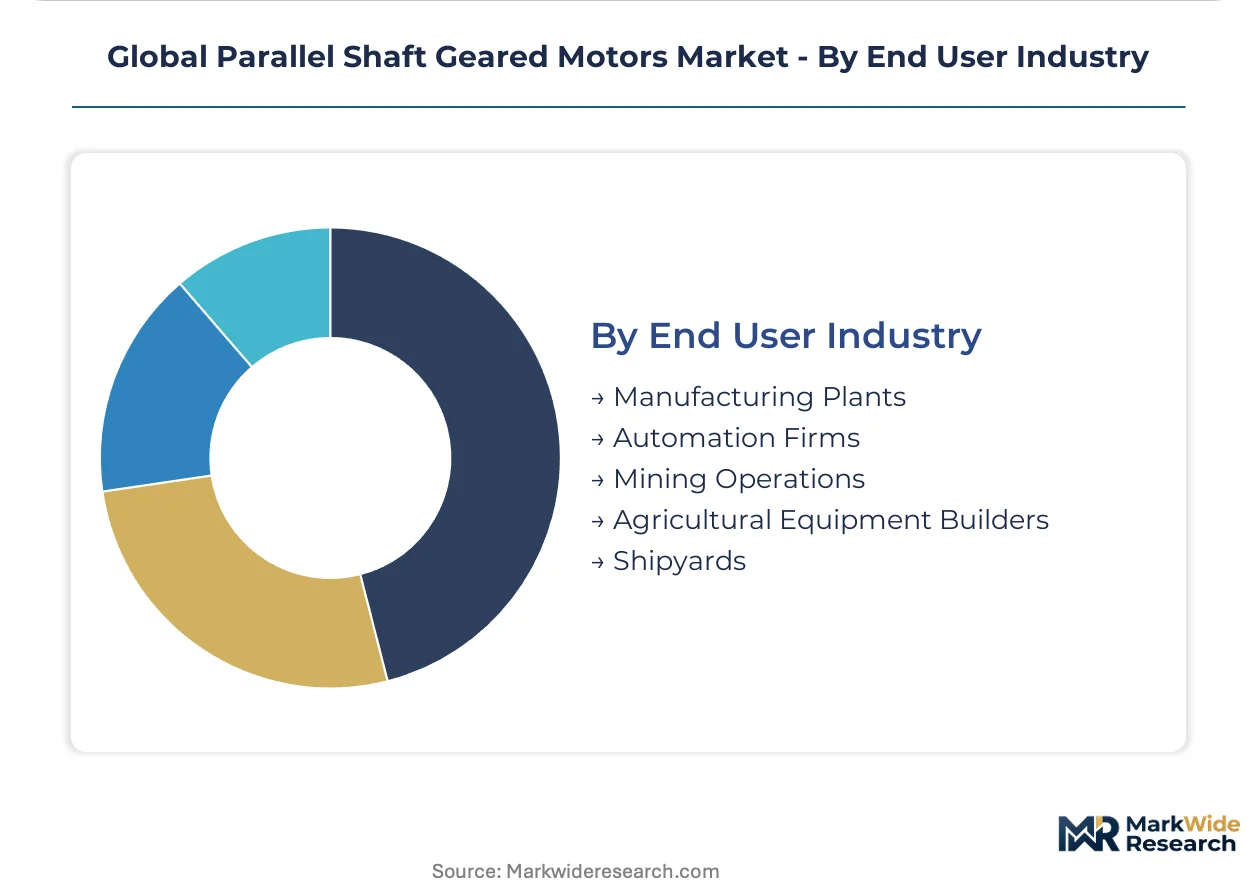
End User Industry:
Lifecycle service contract penetration varies dramatically by sector capital intensity and maintenance outsourcing maturity.
- Manufacturing Plants:Automotive assembly and general machinery production facilities constitute the deepest margin pool through comprehensive service agreements covering vibration monitoring, lubrication analysis, and scheduled rebuild programs. German automotive parts suppliers pioneered outcome-based procurement models now compressing pricing transparency.
- Automation Firms:System integrators and conveyor OEMs consolidate procurement authority, favoring suppliers with modular platform architectures and rapid spare parts availability across multiple geographies.
- Mining Operations:Bulk handling and mineral processing applications specify heavy-duty cast iron configurations with 50,000+ hour bearing life ratings.
- Agricultural Equipment Builders:Seasonal duty cycles and cost-sensitive procurement favor standardized induction motor pairings.
- Shipyards:Marine classification society approvals and salt corrosion resistance constrain supplier qualification.
Revenue concentrates in Manufacturing Plants; Automation Firms are gaining share fastest as system integration consolidates specification authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Neodymium processing clusters in China and foundry capacity in India anchor supply-side geography for parallel shaft geared motors, while demand concentrates in manufacturing automation corridors across Germany, the United States, and Japan.
Germany
Automotive assembly plants in Stuttgart and Wolfsburg drive helical gear motor procurement for 24-hour conveyor operations. The EU Ecodesign Directive IE4/IE5 efficiency tiers eliminate lower-tier motor inventories from procurement lists. Bavaria's industrial automation corridor concentrates specification authority among system integrators favoring modular platform architectures.
China
E-commerce fulfillment centers in Shanghai and Shenzhen specify servo-integrated architectures for AGV and robotics applications. GB 18613-2020 efficiency standards compress induction motor viability while elevating permanent magnet synchronous motor pairings. Yangtze River Delta manufacturing clusters absorb the deepest volume of locally certified drive systems.
United States
Reshoring investments in Michigan and Ohio automotive facilities lift demand for localized geared motor supply with rapid spare parts availability. Department of Energy minimum efficiency regulations impose technical barriers comparable to EU and Chinese standards. Southeast distribution hubs prioritize predictive maintenance subscriptions and guaranteed uptime agreements.
Japan
Packaging equipment OEMs in Osaka and Nagoya specify worm gear variants for compact footprint and holding torque security. METI Top Runner program adds compliance dimensions for multinational suppliers serving precision positioning applications. Kanto region robotics manufacturers anchor specification share for servo-integrated configurations.
India
Automotive and pharmaceutical packaging lines in Maharashtra and Gujarat create captive demand under PLI scheme domestic manufacturing incentives. BIS certification requirements constrain supplier qualification for locally certified drive systems. Tamil Nadu industrial corridors concentrate brownfield retrofit demand where legacy induction motor pairings persist.
Global Parallel Shaft Geared Motors Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue servo-integrated and decentralized architectures. The vendor base stratifies across three tiers: diversified industrial conglomerates with integrated automation portfolios, specialized drive system manufacturers with modular platform expertise, and regional fabricators serving cost-sensitive intermittent-duty applications. Strategic archetypes include efficiency-tier compliance specialists, lifecycle service contract providers, and decentralized drive architecture pioneers. Competitive moves center on geographic certification expansion and predictive maintenance capability integration.
Among Germany-based industrial conglomerates, Siemens AG and SEW-EURODRIVE exemplify the diversified tier with integrated automation portfolios spanning multiple geographies. NORD Drivesystems GmbH & Co. KG occupies a position within the specialized tier, representing decentralized drive architecture expertise. These three anchors illustrate how specification authority concentrates with suppliers capable of modular platform delivery and rapid spare parts availability across German, Chinese, and United States manufacturing corridors.
| Leading Market Players |
|---|
| Siemens AG |
| NORD Drivesystems |
| Mitsubishi Electric Corporation |
| SEW-EURODRIVE |
| Bonfiglioli |
| Bodine Electric Company |
| Toledo Gearmotor |
| WEG |
| Bison Gear |
| Others |
Cost & Logistics Intelligence
Copper LME spot pricing and neodymium oxide export quotas from Chinese processing facilities cascade directly into three-tier pricing structure across premium, standard, and economy levels for parallel shaft geared motors. Procurement officers at automation integrators face widening spreads between servo-integrated premium tiers and induction-based economy configurations as rare earth magnet volatility feeds through bill-of-materials adjustments.
Pricing Analysis
Warranty and lifecycle service bundling separates premium suppliers from transactional competitors in this market. Siemens AG and SEW-EURODRIVE anchor the premium tier through guaranteed uptime agreements and predictive maintenance subscriptions, while regional fabricators compete on unbundled equipment-only pricing for intermittent-duty applications. Price differentiation hinges on IE4/IE5 efficiency certification attainment and localized spare parts inventory depth. Cost compression in the economy tier is intensifying because foundry capacity constraints in India extend delivery schedules beyond acceptable windows for just-in-time manufacturers. Small-scale agricultural equipment builders exhibit the highest price sensitivity, whereas German automotive manufacturers prioritize total cost of ownership over upfront capital expenditure.
Supply Chain Analysis
Ocean freight rate volatility from Shanghai to Rotterdam and Hamburg directly impacts landed cost calculations for cast iron enclosures and finished gear motor assemblies. Manufacturing concentration rests on China for rare earth magnet processing and permanent magnet synchronous motor production, Germany for precision helical gear cutting and automation platform integration, and India for foundry-based cast iron housing fabrication. Raw material dependencies draw from copper windings, neodymium-iron-boron magnets, and gray cast iron feedstock. Single-source vulnerability in Chinese rare earth processing exposes cost structures to export quota fluctuations and environmental compliance shutdowns. Distribution runs through authorized distributor networks with regional stocking locations, supplemented by direct OEM relationships for large automation integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around suppliers with integrated automation portfolios and lifecycle service capabilities, as EU Ecodesign Directive efficiency tier transitions force smaller induction-motor specialists into exit or acquisition scenarios.
For Market Incumbents: Hedge against servo-integrated margin erosion by acquiring decentralized drive architecture specialists and expanding IE5-equivalent certification coverage across Asian regulatory frameworks. Siemens AG and NORD Drivesystems demonstrate how modular platform depth defends position against emerging motion-control entrants. Capacity addition in Maharashtra and Gujarat captures PLI-scheme automotive demand before local competitors achieve BIS certification scale. For New Entrants and Emerging Players: Brownfield retrofit specialists in Tamil Nadu industrial corridors represent the most penetrable buyer archetype, where legacy induction motor pairings persist and controls infrastructure constraints delay full servo adoption. Pharmaceutical packaging lines under India's PLI scheme offer white-space entry with less entrenched incumbent relationships than German automotive. Go-to-market positioning as BIS-certified local assembly with rapid spare parts availability outflanks multinational delivery schedules. For Investors and Strategic Acquirers: Distressed-cycle entries favor induction-motor specialists with established foundry relationships in India and Southeast Asia, where efficiency regulation lags create cash-flow windows before compliance deadlines. Long-term viability favors platforms with servo-integration capability and predictive maintenance subscription infrastructure. Watch for GB 18613-2020 enforcement acceleration in Yangtze River Delta manufacturing clusters as the inflection signal for Chinese market premiumization.| Strategic Initiative | Industry Significance |
|---|---|
| Efficiency Certification Acceleration | IE5-equivalent attainment across EU, Chinese, and US regulatory tiers secures specification authority in automotive procurement. |
| Decentralized Drive Architecture Expansion | Cabinet-free motor-mounted electronics reduce installation labor and capture retrofit brownfield demand in aging manufacturing plants. |
| Predictive Maintenance Platform Development | Vibration and temperature sensor integration enables condition-based service contracts with lifecycle revenue capture from German automotive customers. |
| Rare Earth Magnet Supply Hedging | Dual-sourcing agreements with Japanese and Australian magnet processors mitigate Chinese export quota exposure in servo motor cost structures. |
| Regional Certification Localization | BIS certification in India and METI compliance in Japan unlock specification access to PLI-scheme automotive and precision packaging equipment OEMs. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by structured interviews with maintenance directors at German automotive plants, OEM procurement teams at conveyor system manufacturers, aftermarket service heads at drive system distributors, and plant engineers at US e-commerce fulfillment centers. Secondary validation drew from EU Ecodesign Directive implementation reports, Chinese GB 18613-2020 efficiency tier databases, US Department of Energy appliance standards filings, and foundry capacity surveys from Indian industrial associations. Bottom-up unit economics triangulated against top-down manufacturing investment flows to establish market size boundaries.
Granularity-level modeling operated at gear geometry, motor technology, and end-user industry dimensions across the projection horizon, with separate trajectory assumptions for helical, worm, and servo-integrated configurations. CAGRs derived from regression analysis against manufacturing automation capital expenditure indices and warehouse construction permitting data. Forecast inputs incorporated reshoring investment announcements in Michigan, Ohio, and Bavaria, plus e-commerce fulfillment center buildout timelines in Shanghai and Shenzhen.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to rare earth magnet supply disruptions, foundry capacity expansion delays in India, and synchronization of efficiency tier enforcement across EU, Chinese, and US regulatory regimes. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Motors
Industrial Motor Brakes Market
Industrial Motors
Servo Motors and Drives Market
Industrial Motors
Cryogenic Air Separation Units (Asus) Market
Industrial Motors
United Kingdom AC Motors Market
Industrial Motors
Middle East and Africa Variable Frequency Drive (VFD) Market
Industrial Motors
Global Permanent Magnet Motor Market
Industrial Motors
Industrial Personnel and Burden Carriers [Electric] Market
Industrial Motors
Global Induction Motors Market
Industrial Motors
Variable Speed Drive Market
Industrial Motors
Explosion Proof Electric Motors and Actuators Sales Market
Industrial Motors
Global Explosion-Proof Motor Casting Market
Industrial Motors
High Voltage Motor Sleeve Bearing Market
Industrial Motors
Submersible Pump Motor Market
Industrial Motors
Food Grade Hydraulic Oil Market
Industrial Motors
Nuclear Polar Crane Market
Industrial Motors
Spargers Market