
 Hydraulic Motors Market | 2026-2036
Hydraulic Motors Market Size, Share, and Industry Trends Forecast 2026-2036
Hydraulic Motors Market Analysis
High-pressure specification tiers above 350 bar is collapsing the cost-performance gap between premium and mid-market hydraulic motors. Bosch Rexroth AG leverages its captive foundry network to anchor supply security for large-displacement radial units. Eaton Corporation plc competes through integrated electro-hydraulic architectures that sustain aftermarket service revenue across North American fleet operators.
Hydraulic motors are positive-displacement rotary actuators that convert fluid pressure into mechanical torque, typically operating at pressures from 100 to 450 bar with displacement ranges from 5 to 10,000 cubic centimeters per revolution. Piston motors dominate margin pools in high-pressure, high-speed applications where volumetric efficiency exceeds ninety-five percent, while radial motors capture specialized demand in low-speed, high-torque mining and offshore winch systems. Gear motors retain volume leadership in cost-sensitive agricultural and material handling equipment where operating pressures remain below 200 bar.
EPA Tier 4 Final emissions standards and the EU F-Gas Regulation are forcing OEMs to specify hydraulic motors with reduced internal leakage and higher mechanical efficiency to compensate for engine after-treatment parasitic loads. ISO 4406 cleanliness codes and China GB/T 14039 standards shape filter and seal specifications that determine warranty eligibility and aftermarket parts compatibility. Stakeholders must monitor how electrification of auxiliary functions in construction and agricultural platforms reallocates torque requirements between dedicated hydraulic circuits and centralized power-distribution architectures.
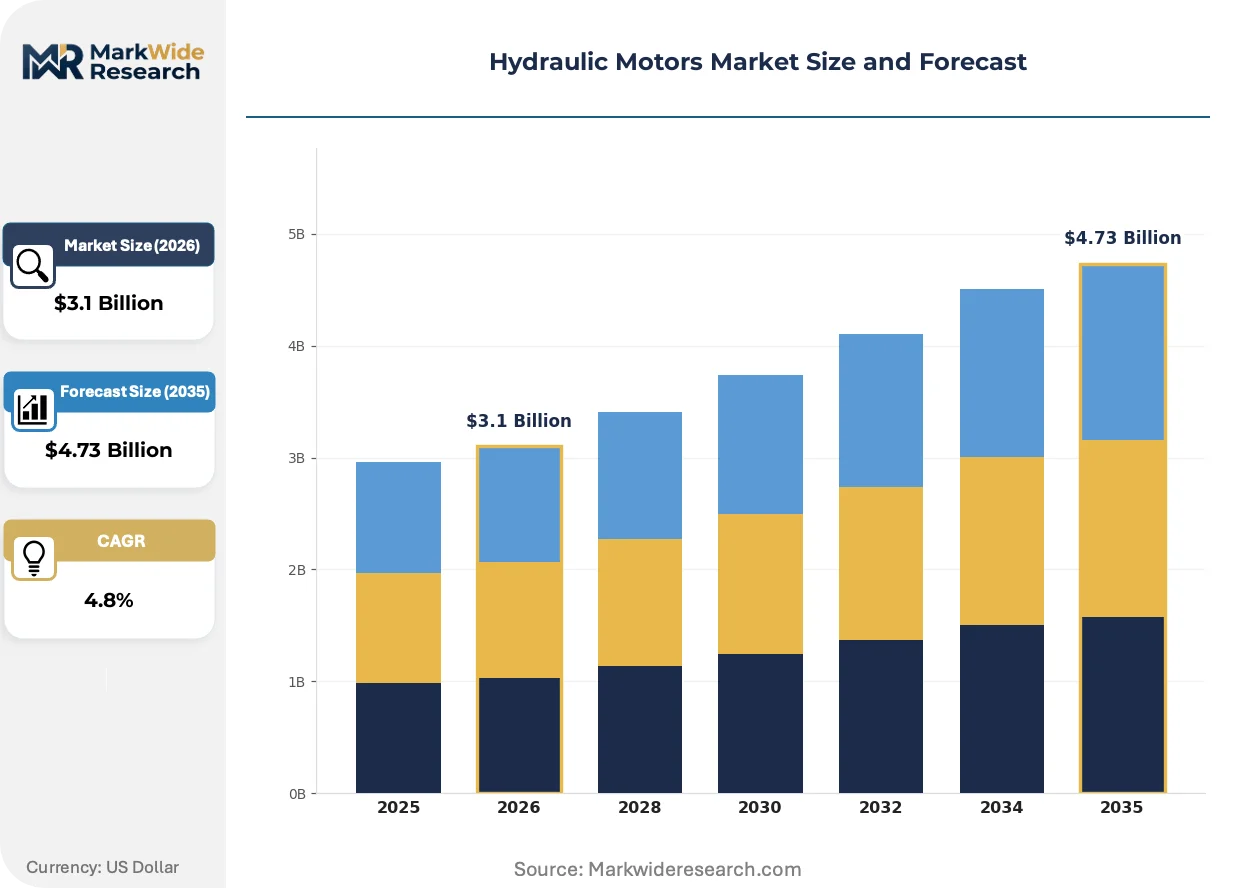
Market Dynamics
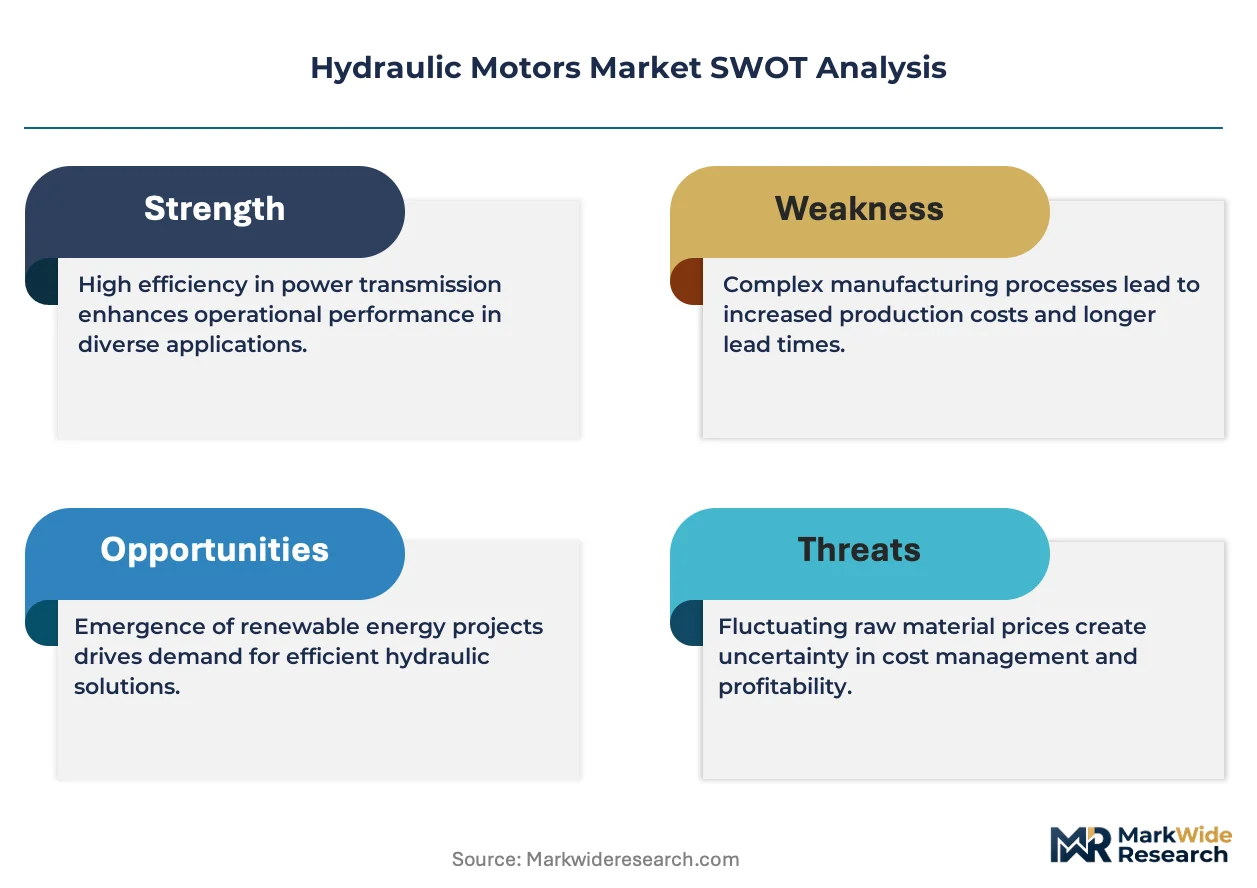
High-pressure hydraulic architectures above 350 bar are compressing replacement cycles across construction and mining fleets, forcing OEMs to rebalance torque density against parasitic engine loads from after-treatment systems.
Growth Catalysts
- Infrastructure renewal mandates:Germany's federal transport investment program accelerates procurement of high-torque radial units for tunnel boring and bridge construction equipment.
- EPA Tier 4 Final:The standard forces hydraulic motor specification upgrades to recover mechanical efficiency lost to diesel after-treatment parasitic drag in mobile machinery.
- Electro-hydraulic integration:Variable displacement piston motors with onboard sensor arrays enable predictive maintenance contracts that extend OEM aftermarket capture.
Market Restraints
- Specialized casting capacity:Large-displacement radial motor housings require nodular iron foundries concentrated in Germany and China, creating supply bottlenecks during demand surges.
- Fluid compatibility costs:Biodegradable hydraulic fluids meeting EU Ecolabel specifications command 40-60% price premiums over mineral oil basestocks, compressing fleet operator maintenance budgets.
- Electrification substitution:Battery-electric auxiliary drives in material handling equipment are eliminating dedicated hydraulic circuits for conveyor and lift functions below 50 kW.
Strategic Opportunities
- India infrastructure buildout:National highway expansion and metro rail projects create unmet demand for low-speed high-torque motors in piling rigs and segment erection gantries.
- EU F-Gas Regulation phase-down:The mandate for lower-GWP hydraulic fluids drives retrofit demand for seal-compatible motors in existing European mobile machinery fleets.
- Sensor-embedded architectures:Integration of pressure and temperature telemetry with cloud-based fleet management platforms enables subscription-based uptime guarantees for mining contractors.
Industry Challenges
- Cleanliness code compliance:ISO 44018/14/11 targets for piston motors require filtration infrastructure investments that smaller rental fleet operators struggle to justify.
- Electro-hydraulic skill gaps:Maintenance technicians trained on purely mechanical systems lack diagnostics capability for CAN-bus integrated motor controllers, extending downtime events.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydraulic Motors Market |
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $4.73 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gear Motors, Vane Motors, Piston Motors, Radial Motors Application: Construction Equipment, Agricultural Machinery, Material Handling, Marine Applications End User: Aerospace, Automotive OEMs, Industrial Manufacturing, Oil & Gas Installation: Mobile Equipment, Fixed Installation, Custom Retrofit, Stationary Machinery |
| Companies Covered | Bosch Rexroth AG, Eaton Corporation plc, Parker Hannifin Corporation, Danfoss Power Solutions, Kawasaki Heavy Industries, Ltd., Poclain Hydraulics, Rotary Power, Permco, Inc., HYDRO LEDUC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydraulic Motors Market Emerging Trajectories
Digitalization of fluid power systems is redefining how torque delivery is monitored, optimized, and monetized across equipment life cycles.
Digital displacement pump-motor units with individually controlled pistons are supplanting conventional swashplate architectures in hybrid excavator drivelines. Komatsu and Volvo CE have deployed these systems in 20-ton class machines since 2022. The technology is compressing fuel consumption by 25% while enabling engine downsizing that reduces after-treatment capital cost.
China's GB/T 14039 cleanliness standard is converging with ISO 4406 to create unified filter specifications for motors exported to Belt and Road infrastructure projects. The harmonization reduces OEM inventory complexity but forces seal material upgrades to handle synthetic ester fluids. Domestic Chinese manufacturers are responding with fluorocarbon seal compounds validated to 10,000-hour life targets.
Fleet operators are consolidating hydraulic motor procurement through integrated powertrain agreements with construction equipment OEMs rather than component-level sourcing. The bundled model displaces independent distributor networks in North American rental channels. Mining contractors in Western Australia and Chile's Atacama region have pioneered this structure, trading component choice for guaranteed availability and fixed maintenance cost.
Hydraulic Motors Market Segmentation
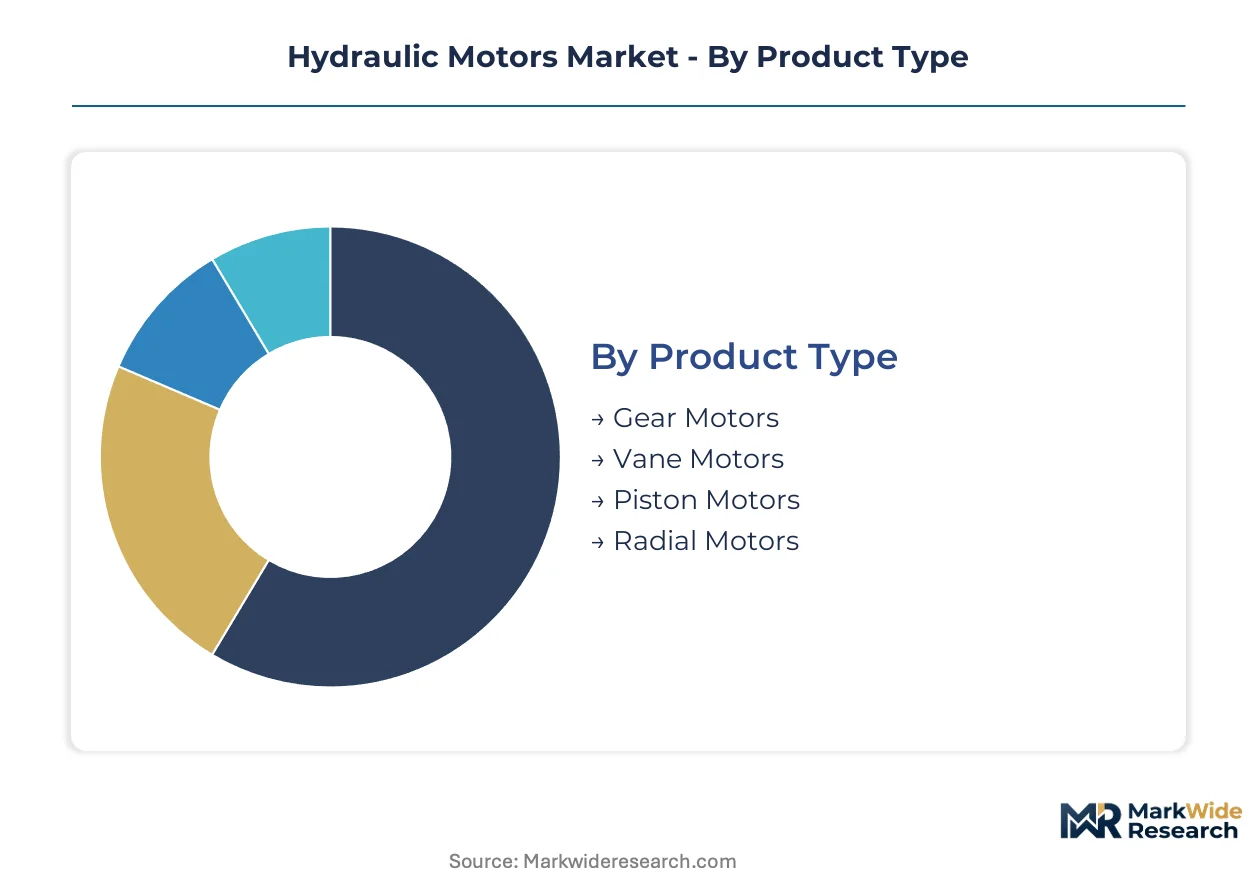
Hydraulic motor segmentation reveals where electrification pressure concentrates and where fluid power retains irreplaceable torque density. Product architecture and installation context determine vulnerability to substitution by electric drives.
Product Type:
Gear and vane motors face the strongest electrification threat in sub-50 kW auxiliary applications, while piston and radial architectures defend their position through pressure ratings that electric alternatives cannot match.
- Gear Motors:External and internal gear configurations deliver fixed displacement from 5 to 250 cc/rev at pressures below 200 bar. Demand concentrates in agricultural equipment across the US Corn Belt and Indian Punjab, where cost-sensitive tractor hydraulics resist electrification due to battery weight penalties in tillage operations.
- Piston Motors:Axial and bent-axis designs achieve volumetric efficiency above 95% at continuous pressures to 450 bar. Construction equipment OEMs in Germany and China specify these units for excavator swing drives and wheel motor applications where high-speed torque density justifies the premium over gear alternatives.
- Vane Motors:Balanced vane architectures offer smooth low-speed operation with inherent pressure compensation. Material handling conveyor systems in US distribution centers represent the primary demand pocket, though this segment is contracting fastest as DC electric roller motors displace centralized hydraulic power units.
- Radial Motors:Multi-stroke cam-lobe or crankshaft designs generate extreme torque at speeds below 100 rpm. Mining automation projects in Western Australia's Pilbara region and Chile's Atacama Desert anchor procurement for crawler drives and winch systems where stall torque requirements exceed 50,000 Nm.
Gear motors anchor the volume base while radial motors gain share at the steepest rate through mining electrification-resilient applications.
Application:
Construction and material handling applications diverge sharply in electrification exposure, with the latter experiencing accelerated circuit elimination.
- Construction Equipment:Excavators, loaders, and cranes require motors rated for shock loads and contaminated fluid conditions. China's Belt and Road infrastructure contracts and Germany's federal transport investment program sustain demand for high-pressure piston units in 20-ton class machines.
- Material Handling:Forklifts, conveyors, and automated storage systems historically represented high-volume hydraulic consumption. Battery-electric auxiliary drives are eliminating dedicated circuits below 50 kW across North American warehouse fleets, compressing this segment's growth trajectory.
- Agricultural Machinery:Tractor implement circuits and combine harvester header drives operate in dust-laden environments where sealed hydraulic systems outperform exposed electric motors. India's PLI scheme for farm mechanization is expanding procurement for low-cost gear motor configurations.
- Marine Applications:Deck winches, anchor handling, and fishing equipment demand corrosion-resistant housings and biodegradable fluid compatibility. EU Ecolabel specifications and MARPOL regulations are forcing seal material upgrades to synthetic ester basestocks in North Sea and Mediterranean fleets.
Construction equipment anchors the volume base while marine applications expand most quickly through offshore wind installation vessel procurement.
End User:
Oil and gas operators prioritize uptime guarantees over first cost, while automotive OEMs drive standardization to reduce supplier complexity.
- Oil & Gas:Drilling rigs, well intervention systems, and pipeline maintenance equipment operate in hazardous environments requiring explosion-proof motor enclosures. North American shale operators and Middle East national oil companies specify radial motors for top drive and iron roughneck applications where failure costs exceed equipment value.
- Industrial Manufacturing:Metal forming presses, injection molding machines, and rolling mills integrate hydraulic motors into synchronized multi-axis systems. Japanese automotive tier suppliers and German machinery builders are consolidating procurement through integrated powertrain agreements rather than component-level sourcing.
- Aerospace:Flight control actuation and landing gear systems demand motors with extreme power-to-weight ratios and FAA certification traceability. This segment represents minimal volume but commands the highest specification tiers and qualification barriers.
- Automotive OEMs:Vehicle assembly plant automation and test stand applications consume standardized motor configurations. Stellantis and Volkswagen Group facilities in Europe are specifying ISO 4406 cleanliness-compliant units to align with warranty requirements for production equipment.
Industrial manufacturing anchors the volume base while oil and gas climbs the fastest through offshore project reactivation.
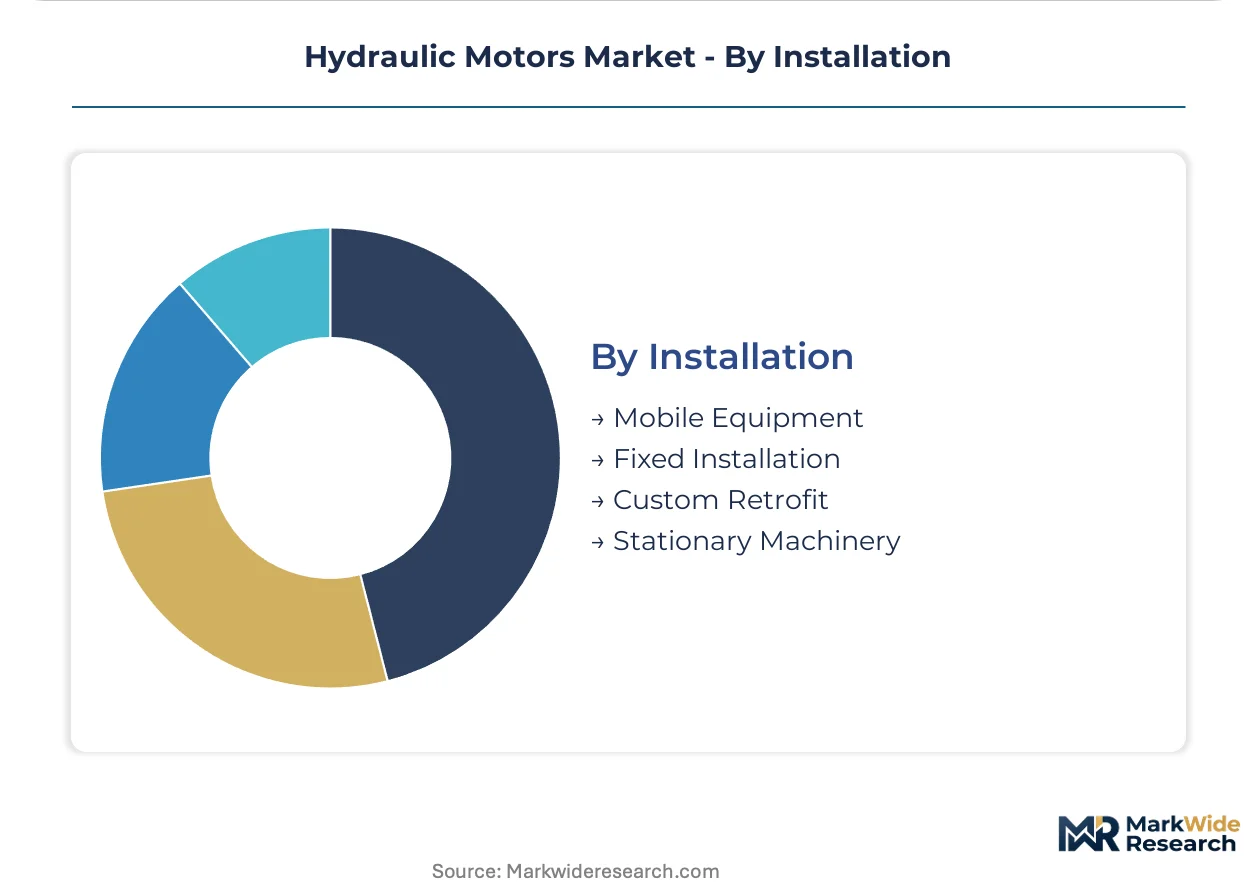
Installation:
Mobile equipment installations dominate unit volume but face the most severe electrification pressure, while stationary machinery defends its position through power density requirements.
- Mobile Equipment:Construction, agriculture, and mining vehicles integrate motors into engine-driven hydraulic circuits. EPA Tier 4 Final after-treatment parasitic loads are forcing specification upgrades to recover mechanical efficiency, particularly in US and EU fleet replacements.
- Stationary Machinery:Factory-based presses, mills, and test equipment connect to centralized power units with controlled fluid conditioning. This installation mode is expanding most quickly as reshoring initiatives in the US and EU drive capital equipment investment.
- Fixed Installation:Permanently mounted winches, capstans, and process equipment in marine and energy infrastructure. The segment benefits from long service intervals and predictable maintenance scheduling that amortizes higher first costs.
- Custom Retrofit:Existing fleet motor replacement and seal upgrades to accommodate biodegradable fluids. EU F-Gas Regulation phase-down is accelerating retrofit demand across European mobile machinery fleets as operators seek to extend asset life without full equipment replacement.
Mobile equipment anchors the volume base while stationary machinery gains share at the steepest rate through manufacturing reshoring investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in hydraulic motors track the geography of heavy equipment manufacturing, with Germany and China running structural surpluses while the United States and India remain net importers. Export concentration in precision-casting clusters creates supply vulnerability during infrastructure stimulus cycles.
Germany
Federal transport investment programs are accelerating procurement of radial hydraulic units for tunnel boring machinery. The EU F-Gas Regulation is forcing seal material upgrades across mobile machinery fleets. The Ruhr industrial corridor hosts foundry clusters supplying nodular iron housings to construction equipment OEMs.
China
Belt and Road infrastructure contracts are sustaining demand for high-pressure piston motors in 20-ton excavator classes. GB/T 14039 cleanliness standards are converging with ISO 4406 to harmonize filter specifications for export-bound equipment. The Yangtze River Delta concentration of hydraulic component fabricators is expanding capacity for synthetic ester-compatible seal compounds.
United States
EPA Tier 4 Final after-treatment parasitic loads are forcing specification upgrades to recover mechanical efficiency in fleet replacements. Infrastructure Investment and Jobs Act funding is compressing replacement cycles for construction equipment across the Midwest and Southeast. Houston anchors oil and gas sector procurement for explosion-proof radial motors in drilling applications.
India
PLI scheme incentives for farm mechanization are expanding procurement of low-cost gear motor configurations for tractor hydraulics. National highway expansion and metro rail projects are creating unmet demand for low-speed high-torque motors in piling rigs. The Pune-Nashik industrial belt is emerging as a fabrication hub for construction equipment subassemblies.
Japan
Automotive tier suppliers are consolidating hydraulic motor procurement through integrated powertrain agreements for press and rolling mill applications. METI reshoring incentives are expanding domestic capacity for precision piston units. The Nagoya industrial corridor maintains specialized foundry capacity for high-horsepower marine winch motors.
Hydraulic Motors Market Vendor Landscape
Listed leaders compete with private specialists across technology licensing and captive foundry control, creating a tiered structure where scale advantages in radial motor casting concentrate among German and Chinese players. Three archetypes dominate: diversified fluid power conglomerates with full-system integration capabilities, mid-size specialists focused on low-speed high-torque architectures, and regional fabricators serving cost-sensitive agricultural equipment. Competitive moves center on electro-hydraulic integration partnerships and backward integration into nodular iron casting capacity.
Among diversified fluid power conglomerates, Bosch Rexroth AG and Eaton Corporation plc exemplify the integrated-systems archetype, anchoring positions through captive supply networks and aftermarket service platforms. Parker Hannifin Corporation occupies a position spanning component supply and system integration. Danfoss Power Solutions represents the Danish-German engineering tradition in mobile hydraulics. These entities sit within a competitive matrix where sensor-embedded architectures and predictive maintenance contracts are becoming primary differentiation vectors.
| Leading Market Players |
|---|
| Bosch Rexroth AG |
| Eaton Corporation plc |
| Parker Hannifin Corporation |
| Danfoss Power Solutions |
| Kawasaki Heavy Industries, Ltd. |
| Poclain Hydraulics |
| Rotary Power |
| Permco, Inc. |
| HYDRO LEDUC |
| Others |
Supply Flow & Price Mechanics
EPA Tier 4 Final emissions compliance gates both supplier qualification and price differentiation in hydraulic motors, forcing OEMs to specify higher-efficiency units that recover mechanical losses from diesel after-treatment systems while compressing margins on legacy designs. Fluid cleanliness standards under ISO 4406 and China's GB/T 14039 further bifurcate the supply base between certified premium suppliers and uncertified economy producers, embedding certification costs into delivered pricing.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on ISO 4406 cleanliness certification tiers and captive foundry control over nodular iron casting capacity. Cost compression in economy gear motors is intensifying because battery-electric auxiliary drives below 50 kW are eliminating dedicated hydraulic circuits in material handling equipment. Agricultural fleet operators in India and the US Corn Belt exhibit the highest price sensitivity, while oil and gas contractors in the Permian Basin and North Sea prioritize uptime guarantees over first cost.
Supply Chain Analysis
Strategic stockpiling of large-displacement radial motor housings dominates inventory strategy, as nodular iron foundry capacity concentrates in Germany's Ruhr corridor and China's Yangtze River Delta. Raw material dependencies draw from high-grade nodular iron, fluorocarbon seal compounds, and synthetic ester fluid formulations. Single-source vulnerability in specialized casting capacity creates supply bottlenecks during infrastructure stimulus surges. Distribution runs through integrated powertrain agreements with construction equipment OEMs, displacing independent distributor networks in North American rental channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hydraulic motors constitute a defensive-moat market where regulatory entrenchment through EPA Tier 4 Final and EU F-Gas compliance creates switching costs that lock OEMs into validated supplier relationships.
For Market Incumbents: Fortify backward integration into nodular iron foundry capacity in Germany and China to secure supply during demand surges. Deepen sensor-embedded motor architectures with predictive maintenance contracts to capture aftermarket revenue streams. Electrification substitution in sub-50 kW material handling applications threatens volume in gear motor tiers.
For New Entrants and Emerging Players: Anchor in India's unmet demand for low-speed high-torque motors in national highway piling rigs and metro segment erection gantries. Target marine winch applications for offshore wind installation vessels where EU Ecolabel specifications force seal upgrades and create qualification barriers for established suppliers. Pursue synthetic ester-compatible seal compounds as a technical differentiation angle.
For Investors and Strategic Acquirers: EU F-Gas Regulation phase-down reshapes the acquisition landscape toward retrofit specialists with seal compatibility expertise for existing European mobile machinery fleets. Long-term viability centers on electro-hydraulic integration capabilities across the 5-10 year electrification transition. Target mid-size radial motor specialists with captive foundry access. Watch battery-electric auxiliary drive penetration rates in material handling as the inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nodular Iron Casting | Captive foundry capacity in Germany's Ruhr corridor secures supply during infrastructure stimulus surges. |
| Sensor-Embedded Motor Architectures | Pressure and temperature telemetry enable subscription-based uptime guarantees for mining contractors in Western Australia. |
| Synthetic Ester Seal Compound Development | Fluorocarbon formulations validated to 10,000-hour life targets unlock EU Ecolabel-compliant marine applications. |
| Integrated Powertrain Agreements | Bundled procurement models with construction OEMs displace independent distributors in North American rental channels. |
| Retrofit Service Platforms | EU F-Gas seal upgrade programs extend asset life for European mobile machinery fleets without full equipment replacement. |
Methodological Framework
Initial hypotheses were tested against primary input from hydraulic OEM procurement teams, aftermarket service directors at mining contractors, foundry operations managers in Germany and China, and fluid power distribution channel heads, then refined against secondary validation from customs trade data, SEC 10-K filings of listed fluid power conglomerates, ISO 4406 certification registries, and Belt and Road infrastructure contract disclosures. Bottom-up unit demand modeling triangulated against top-down equipment production forecasts.
Variance decomposition across the projection horizon isolates volume drivers by product architecture, application exposure to electrification substitution, and regional regulatory cluster. Segmentation dimensions modeled include motor type, installation mode, pressure specification tier, and end-use industry vulnerability to battery-electric displacement. CAGRs were derived from equipment replacement cycle compression and infrastructure stimulus timing. Forecast inputs incorporate foundry capacity utilization rates and synthetic ester fluid adoption curves.
Decision-makers should treat outputs as directional under base assumptions of sustained infrastructure investment and phased electrification transition; material deviation would warrant model refresh. Revision becomes warranted when battery-electric auxiliary drive penetration in material handling crosses thresholds that accelerate hydraulic circuit elimination.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Motors
Variable Speed Drive Market
Industrial Motors
United Kingdom DC Motor Market
Industrial Motors
HVAC Motors Market
Industrial Motors
Elevator Motors Market
Industrial Motors
Power Scraper Market
Industrial Motors
Air Heater Tubes Market
Industrial Motors
Asia-Pacific Induction Motor Market
Industrial Motors
Servo Motors and Drives Market
Industrial Motors
Europe Induction Motor Market
Industrial Motors
Vietnam Air Compressor Market
Industrial Motors
Global Medium and High Power Motors Market
Industrial Motors
Safety Drives and Motors Market
Industrial Motors
North America Hazardous Location Motors Market
Industrial Motors
Power Stacker Market
Industrial Motors
Industrial Personnel and Burden Carriers [Electric] Market
Industrial Motors
Smart Motors Market