
 North America Industrial Motors Market | 2026-2036
North America Industrial Motors Market Size, Share, and Industry Trends Forecast 2026-2036
North America Industrial Motors Market Outlook
The US Department of Energy's amended motor efficiency standards is decoupling legacy product lines from profitable aftermarket service. ABB Ltd. leverages integrated drives-and-motors portfolios to capture retrofit cycles across Midwest manufacturing plants. Siemens AG anchors its position through in-house production of rare-earth permanent magnets for premium servo lines. Regal Rexnord Corporation dominates fractional-horsepower replacement demand through distributor channel control.
Industrial motors are electromechanical machines converting electrical energy into mechanical rotation, typically rated from fractional horsepower to tens of thousands of horsepower with operating efficiencies now governed by NEMA Premium and IE4 designations. Their primary purpose is driving mechanical loads across fixed and variable-speed industrial processes. AC Motors sustain the largest revenue pool due to ubiquity in pumps and fans, though Servo Motors represent the fastest-expanding segment as packaging and robotics applications demand precise position control. The End User dimension shows Water Treatment outpacing Oil & Gas in unit growth as utilities modernize aging infrastructure.
The EPA enforces efficiency minimums under the Energy Policy Act, while NEMA publishes consensus standards that manufacturers must meet for US market access. Canada's Natural Resources Canada administers parallel regulations through the Energy Efficiency Act, creating a harmonized but distinct compliance landscape. Stakeholders must monitor how impending DOE rulemakings for medium-voltage machines reshape R&D allocation between induction and permanent-magnet topologies.
Market Dynamics
Brushless DC architectures are consolidating powertrain decisions across Canadian mining and US petrochemical corridors, compressing the installed base of induction designs while EPA effluent mandates force water utilities into accelerated motor fleet replacement cycles.
Growth Catalysts
- EPA Effluent Mandates:Water treatment utilities across Texas and the US Gulf Coast are expanding motor fleets to meet tightening discharge standards, creating sustained replacement demand for premium-efficiency units.
- Permanent-Magnet Topology Migration:Rare-earth servo architectures are capturing packaging and robotics applications as position-control precision becomes non-negotiable in automated lines.
- Canadian Mining Electrification:Underground operations in Ontario and British Columbia are retrofitting ventilation and hoisting systems with compact, high-torque brushless DC alternatives to induction motors.
Market Restraints
- Rare-Earth Supply Concentration:Neodymium and dysprosium processing capacity concentrates in limited overseas jurisdictions, exposing premium servo lines to input cost volatility and geopolitical friction.
- NEMA Premium Compliance Burden:The DOE's amended efficiency standards force manufacturers to sunset legacy induction platforms, stranding R&D investments and compressing aftermarket service margins.
- Copper-Winding Cost Exposure:Stator and rotor winding materials face commodity price swings that erode margin stability across fractional-horsepower replacement channels.
Strategic Opportunities
- Integrated Drive-Motor Systems:Variable-frequency drive and motor combination units offer retrofit penetration in Midwest manufacturing plants where space constraints and wiring complexity deter standalone upgrades.
- Mexican Nearshoring Corridors:Automotive and appliance assembly expansion in Querétaro and Nuevo León creates greenfield demand for IE4-rated servo lines in precision positioning roles.
- Water Infrastructure Modernization:Aging lift stations and treatment plants across the Great Lakes region present untapped volume for submersible and vertical hollow-shaft motor replacements.
Industry Challenges
- Servo Commissioning Expertise Gap:Encoder alignment and tuning protocols require specialized field technicians that distributor networks struggle to retain and certify.
- Legacy Control Integration Friction:Digital drive interfaces often conflict with existing PLC architectures in brownfield installations, extending project timelines and eroding retrofit economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Industrial Motors Market |
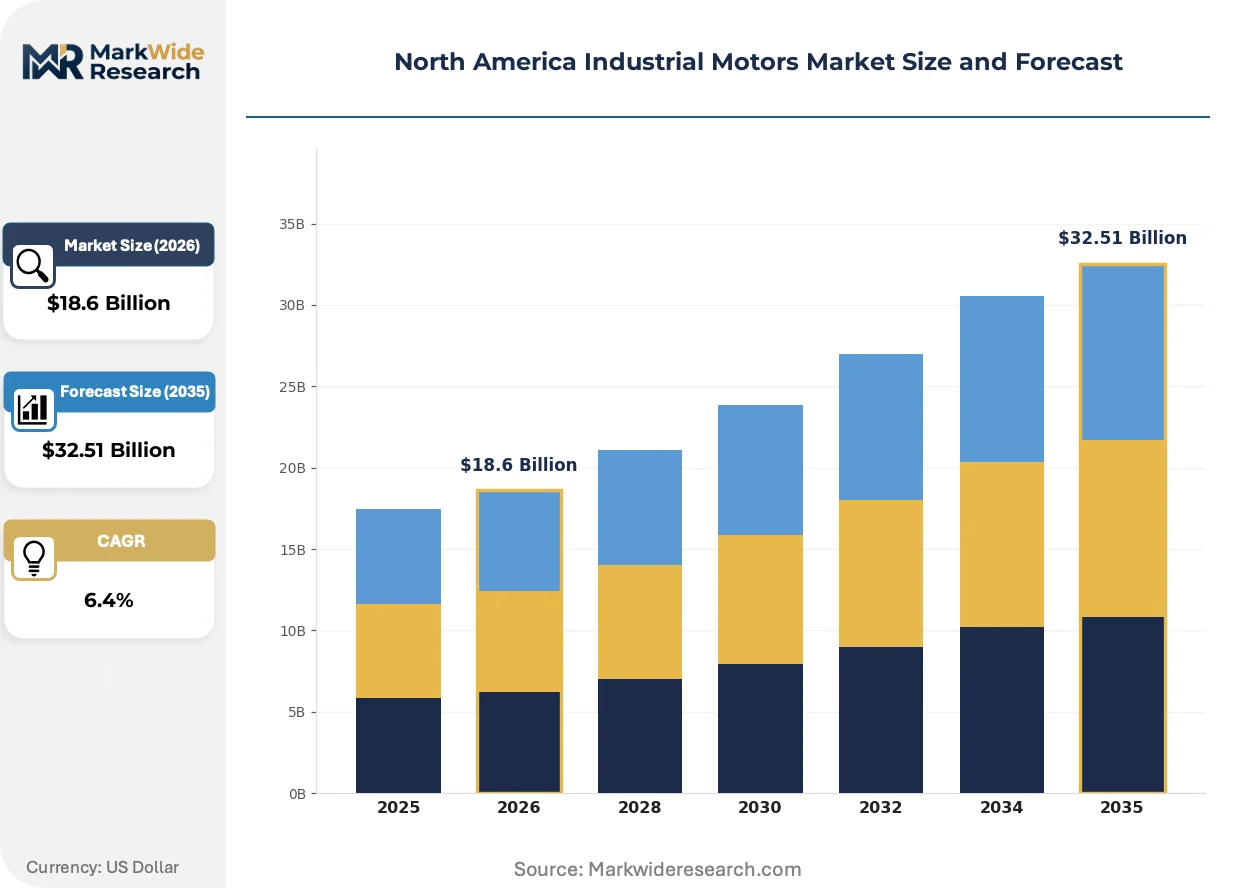
| Market Size in 2026 | $18.6 Billion |
| Market Size in 2035 | $32.51 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AC Motors, DC Motors, Servo Motors, Stepper Motors End User: Manufacturing, Oil & Gas, Mining, Water Treatment Technology: Brushless, Induction, Synchronous, Asynchronous Application: Conveyor Systems, Pumps, Fans, Compressors |
| Companies Covered | Siemens AG, ABB Ltd., Rockwell Automation, Inc., General Electric Company, Nidec Corporation, Schneider Electric SE, Emerson Electric Co., Regal Rexnord Corporation, WEG S.A., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Industrial Motors Market Strategic Shifts
Permanent-magnet synchronous motor designs are compressing the performance gap between standard induction and precision servo platforms, while regulatory pressure on efficiency and emissions accelerates technology refresh cycles across heavy process industries.
Brushless DC architectures with integrated power electronics are consolidating position in Canadian hard-rock mining and US petrochemical processing. Rio Tinto's Diavik operation and ExxonMobil's Baytown complex have both standardized on frameless torque motors for direct-drive hoisting and extruder applications. This consolidation is eliminating gearbox maintenance burdens and reducing footprint requirements in space-constrained underground headings and offshore platform modules.
Natural Resources Canada's Energy Efficiency Act amendments are tightening minimum performance standards for medium-voltage machines above 375 kW, paralleling anticipated DOE rulemakings for equivalent US equipment classes. The regulatory convergence is forcing manufacturers to bifurcate R&D budgets between advanced induction designs and permanent-magnet alternatives. Oil sands operators in Alberta face compressed procurement timelines as 2027 compliance deadlines approach for new capital projects.
After-sales service contracts are unbundling from hardware procurement across water treatment and power generation verticals. Municipal utilities in California and Texas are negotiating performance-based maintenance agreements that transfer operational risk to OEM service arms, displacing traditional distributor-led spare parts and repair models. This reconfiguration concentrates service revenue with manufacturers possessing captive technical support infrastructure and remote diagnostic capabilities.
North America Industrial Motors Market Segmentation
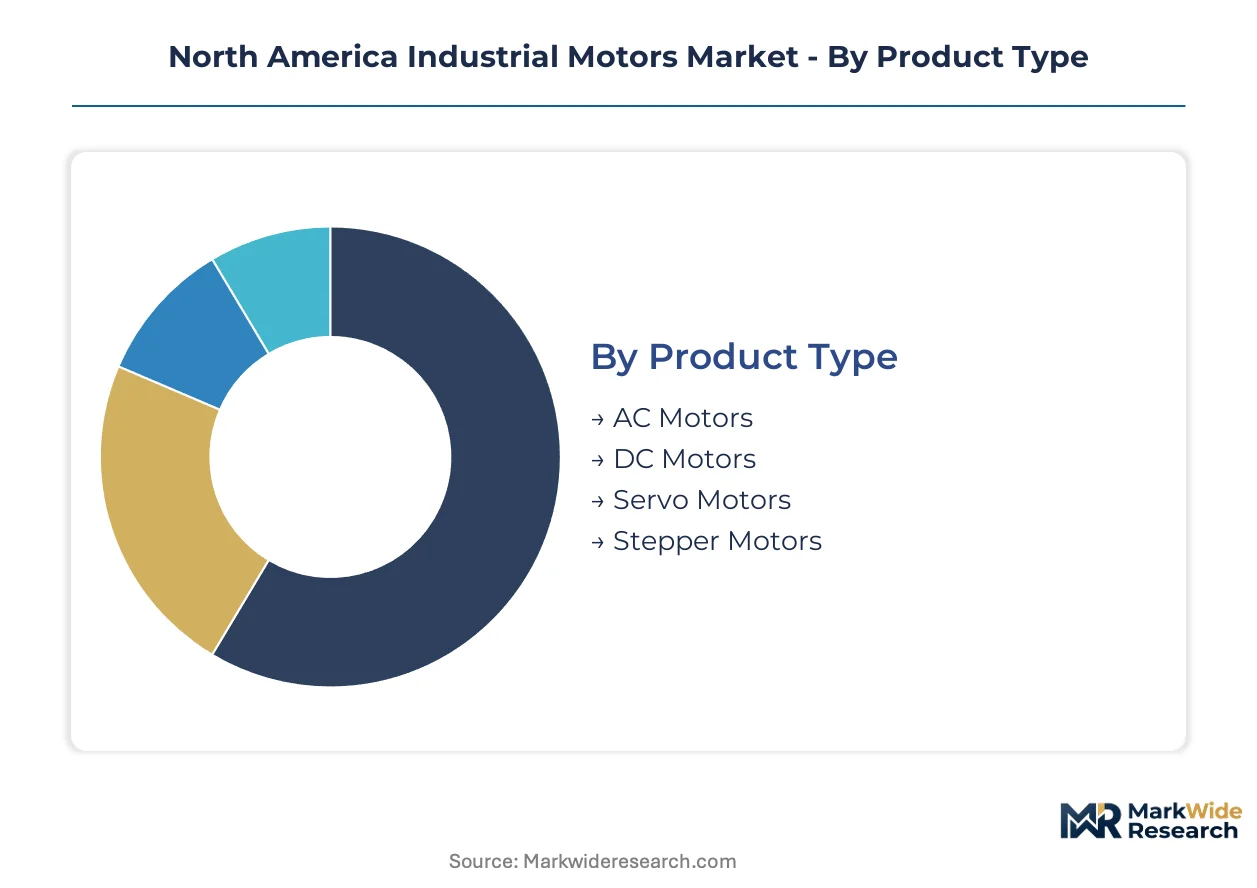
Industrial motor procurement decisions in North America increasingly hinge on efficiency tier alignment with DOE rulemakings and torque density requirements for process-specific loads. Segmentation reveals where technology migration concentrates investment and where legacy platforms retain replacement economics.
Product Type:
Power conversion architectures define performance ceilings, operating cost profiles, and retrofit compatibility across installed bases.
- AC Motors:Polyphase induction and permanent-magnet synchronous designs dominate pump and fan applications across Texas petrochemical corridors. DOE efficiency mandates are compressing the viable product mix toward NEMA Premium and IE4-rated platforms in continuous-duty process roles.
- Servo Motors:Rare-earth permanent-magnet architectures with integrated encoders deliver precise position control for packaging lines and robotic cells. Demand concentrates in Querétaro automotive assembly and Midwest food processing where throughput precision governs line economics.
- DC Motors:Wound-field and permanent-magnet designs persist in crane hoists and rolling mill drives requiring high starting torque. Legacy traction applications in Great Lakes steel operations sustain aftermarket demand despite AC displacement trends.
- Stepper Motors:Hybrid permanent-magnet steppers with microstepping drives occupy low-cost positioning roles in 3D printing and small-format CNC equipment. Volume concentrates in California and Ontario electronics manufacturing clusters.
AC Motors lead on scale; Servo Motors lead on momentum.
End User:
Capital expenditure cycles and regulatory exposure create divergent procurement patterns across verticals.
- Manufacturing:Discrete automation and process lines in Midwest metalworking and Southeast automotive assembly drive variable-frequency retrofit demand. Integrated drive-motor systems penetrate where floor space constraints limit standalone drive enclosures.
- Water Treatment:Municipal utilities across the US Gulf Coast and Great Lakes region are replacing aging lift station motors to meet EPA effluent mandates. Submersible and vertical hollow-shaft designs dominate procurement specifications.
- Oil & Gas:Upstream drilling and downstream refining operations in Alberta oil sands and Texas Permian Basin specify explosion-proof enclosures and severe-duty ratings. Capital project timelines compress as Canadian efficiency deadlines approach.
- Mining:Underground hard-rock operations in Ontario and British Columbia electrify ventilation and hoisting systems. Brushless DC torque motors displace gearbox-coupled induction drives in space-constrained headings.
Manufacturing commands the largest installed base; Water Treatment exhibits the steepest replacement trajectory.
Technology:
Rotor topology selection determines efficiency band, power density, and control system complexity.
- Induction:Squirrel-cage designs with copper or aluminum rotor bars remain the default for constant-speed pump and fan loads. NEMA Premium compliance is forcing redesigns of legacy platforms across fractional to medium-voltage power ranges.
- Brushless:Electronically commutated permanent-magnet motors with integrated inverters achieve highest-in-class efficiency for variable-speed duty. Canadian mining and US petrochemical operators standardize on frameless torque variants for direct-drive extruder and hoist applications.
- Synchronous:Wound-rotor and permanent-magnet designs provide power-factor correction and precise speed holding for large compressor and generator drives. Applications concentrate in Alberta gas processing and Gulf Coast LNG facilities.
- Asynchronous:Reluctance and slip-energy recovery motors occupy niche roles in high-inertia loads requiring soft-start characteristics. Limited penetration outside specialized material handling and crushing applications.
Induction retains volume dominance; Brushless gains share fastest in premium efficiency tiers.
Application:
Load torque profiles and duty cycle intensity dictate motor specification and maintenance economics.
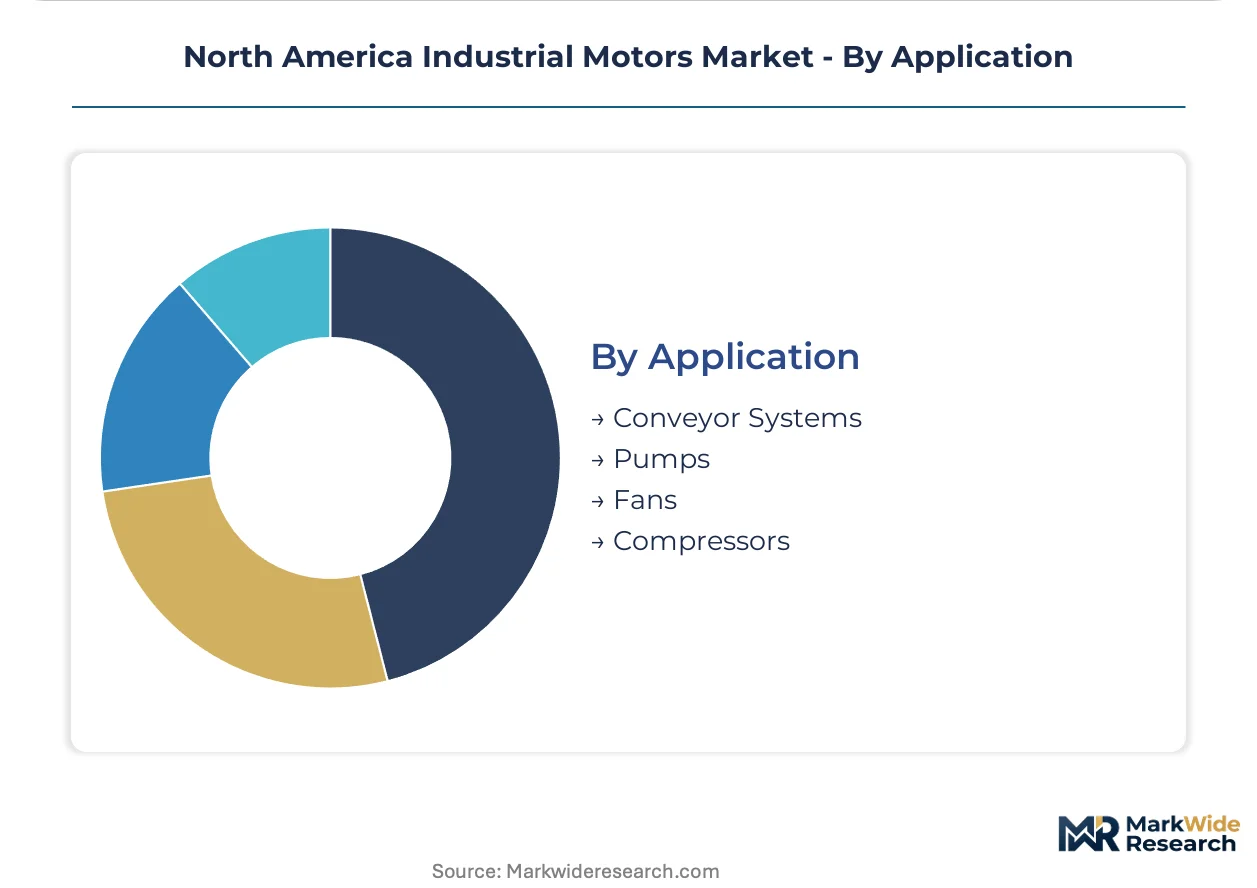
- Pumps:Centrifugal and positive displacement pump drives constitute the largest motor application category across water treatment and oil & gas verticals. DOE pump efficiency standards are cascading into motor procurement specifications.
- Fans:Axial and centrifugal ventilation systems in mining and HVAC applications favor high-pole-count induction designs. Variable-frequency control penetration is displacing damper-based flow regulation.
- Conveyor Systems:Belt and bulk material handling drives require high starting torque and controlled acceleration profiles. Mining and logistics operations in British Columbia and Mexico prioritize compact brushless DC alternatives.
- Compressors:Rotary screw and centrifugal air and gas compression demand continuous-duty ratings with precise speed control. Oil & gas processing and manufacturing facilities specify premium efficiency synchronous designs.
Pumps anchor unit volume; Compressors command premium pricing tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent pools in Detroit, Houston, and Toronto anchor North American motor design and manufacturing capabilities. These workforce concentrations support specialized application engineering for petrochemical, automotive, and mining verticals. Proximity to end-use clusters shapes regional competitive advantages.
United States
Texas and Louisiana petrochemical corridors drive severe-duty motor demand for refinery and chemical processing applications. EPA effluent mandates under the Clean Water Act accelerate water utility modernization across Gulf Coast municipalities. Houston anchors the largest concentration of explosion-proof motor specification activity.
Canada
Ontario and British Columbia mining operations electrify ventilation and hoisting systems with high-torque brushless alternatives. Natural Resources Canada's Energy Efficiency Act amendments tighten medium-voltage efficiency standards above 375 kW. Alberta oil sands projects face compressed procurement timelines approaching 2027 compliance deadlines.
Mexico
Querétaro and Nuevo León automotive assembly expansion creates greenfield demand for precision servo positioning systems. Mexican federal energy efficiency programs align with NEMA Premium benchmarks for cross-border equipment certification. Monterrey industrial parks attract Tier 1 supplier motor fabrication facilities.
North America Industrial Motors Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across the North American industrial motors landscape. The vendor base organizes into three tiers: integrated automation giants with captive magnet supply, mid-scale motor specialists with distributor channel dominance, and regional fabricators serving replacement demand. Consolidation pressure intensifies as efficiency regulations sunset legacy platforms. Strategic moves concentrate on integrated drive-motor system development and rare-earth supply chain positioning.
Among European-based diversified industrials, Siemens AG and ABB Ltd. occupy positions reflecting integrated automation portfolios. Regal Rexnord Corporation exemplifies the North American specialist archetype with fractional-horsepower replacement channel strength. These three anchors represent distinct competitive vectors: magnet-integrated premium servo lines, combined drive-motor retrofit systems, and distributor-controlled aftermarket access.
| Leading Market Players |
|---|
| Siemens AG |
| ABB Ltd. |
| Rockwell Automation, Inc. |
| General Electric Company |
| Nidec Corporation |
| Schneider Electric SE |
| Emerson Electric Co. |
| Regal Rexnord Corporation |
| WEG S.A. |
| Others |
Value Chain & Pricing Dynamics
Rare-earth permanent-magnet costs cascade through servo motor pricing tiers as neodymium and dysprosium processing concentrates in limited overseas jurisdictions, compressing margins on premium-efficiency units while copper-winding commodity swings erode stability across fractional-horsepower replacement channels serving Midwest manufacturing plants.
Pricing Analysis
Hardware-service bundling splits the North American industrial motors landscape into divergent pricing models. After-sales contracts unbundle from equipment procurement across water treatment and power generation verticals, with municipal utilities negotiating performance-based maintenance agreements that transfer operational risk to OEM service arms. Three-tier pricing structure across premium, standard, and economy levels separates NEMA Premium and IE4-certified platforms from legacy induction designs and unbranded replacement units. Cost compression in fractional-horsepower tiers is intensifying because distributor channel consolidation limits price negotiation leverage for small-batch buyers. Water treatment utilities exhibit highest price sensitivity due to municipal budget constraints, while oil sands operators in Alberta show lowest sensitivity given compressed procurement timelines approaching regulatory deadlines.
Supply Chain Analysis
Domestic-content mandates under the US Inflation Reduction Act and Canada's Energy Efficiency Act amendments are reshaping sourcing decisions for medium-voltage machines above 375 kW. Rare-earth magnet supply concentrates in China, with secondary processing capacity in Japan and emerging alternatives in Australia and Vietnam. Stator copper windings and rotor aluminum castings feed from Chilean mining operations and domestic US smelters. Single-source vulnerability in neodymium supply exposes premium servo lines to geopolitical friction and input cost volatility. Distribution runs through authorized distributor networks for replacement demand and direct OEM engagement for greenfield capital projects in petrochemical and mining verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America Industrial Motors Market functions as a geographic-arbitrage play where Canadian mining electrification timelines run 18-24 months ahead of US medium-voltage rulemakings, creating procurement timing advantages for operators with cross-border project portfolios.
For Market Incumbents: Deepen captive rare-earth magnet supply through upstream partnerships or in-house production to defend servo margins against commodity volatility. Anchor aftermarket position by acquiring specialized field service capabilities in encoder alignment and tuning protocols, addressing the commissioning expertise gap that threatens distributor channel retention. Compress R&D allocation toward integrated drive-motor systems where Midwest manufacturing retrofit demand concentrates.
For New Entrants and Emerging Players: Frameless torque motor architectures for direct-drive mining hoisting offer a technology-first wedge against gearbox-coupled induction incumbents in Ontario and British Columbia underground operations. White-space targets concentrate in Mexican nearshoring corridors where Querétaro automotive assembly expansion creates greenfield servo demand, and in Great Lakes water infrastructure modernization where aging lift stations require vertical hollow-shaft replacements. Pursue OEM co-development partnerships rather than distributor channel competition.
For Investors and Strategic Acquirers: Consolidation pressure builds where NEMA Premium compliance burdens strand legacy induction R&D investments and compress aftermarket service margins. Mid-scale motor specialists with fractional-horsepower distributor control represent prime acquisition targets as efficiency regulations sunset non-compliant platforms. Watch DOE rulemaking announcements for medium-voltage machines as the inflection signal determining permanent-magnet versus advanced induction topology winners.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare-Earth Magnet Supply | Captive neodymium sourcing insulates servo margins from geopolitical supply disruptions. |
| Integrated Drive-Motor System Development | Combined units penetrate Midwest manufacturing retrofits where floor space constraints limit standalone enclosures. |
| Performance-Based Service Contract Expansion | Risk-transfer agreements displace distributor-led repair models in Texas and California municipal utilities. |
| Mexican Manufacturing Footprint Establishment | Monterrey industrial parks position suppliers for Querétaro automotive servo demand growth. |
| Medium-Voltage Efficiency Certification Investment | Early IE4 platform readiness captures Alberta oil sands procurement ahead of 2027 deadlines. |
Study Parameters
Direct dialogue with plant engineers at petrochemical facilities, procurement leads at water treatment utilities, aftermarket service heads at distributor networks, and technical R&D directors at motor manufacturers grounded qualitative findings. Secondary validation drew from DOE efficiency standard filings, EPA effluent mandate documentation, Natural Resources Canada regulatory amendments, SEC 10-K disclosures from listed industrial conglomerates, and customs trade data on rare-earth magnet imports. Bottom-up unit economics triangulated against top-down sector expenditure patterns.
Bottom-up modeling aggregated segment-level unit shipments and average selling prices across AC, servo, DC, and stepper architectures, while top-down verification cross-checked against capital expenditure disclosures from oil sands operators and municipal utility bond issuances. The analytical framework projected growth across the analysis window by technology migration curves, regulatory compliance deadlines, and end-user replacement cycles. Forecast inputs incorporated rare-earth price volatility indices and NEMA efficiency tier adoption rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to DOE rulemaking timing, rare-earth supply disruption scenarios, and Canadian mining electrification project delays. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Motors
Hydraulic Motors Market
Industrial Motors
Smart Motors Market
Industrial Motors
AC Servo Motors and Drives Market
Industrial Motors
Food Grade Hydraulic Oil Market
Industrial Motors
Vertical Gear Motor Market
Industrial Motors
Global Permanent Magnet Motor Market
Industrial Motors
Global Explosion-Proof Motor Casting Market
Industrial Motors
US Electric Motor Market
Industrial Motors
United Kingdom DC Motor Market
Industrial Motors
AC Motor Market
Industrial Motors
Variable Speed Drive Market
Industrial Motors
Industrial Motor Brakes Market
Industrial Motors
Global Medium and High Power Motors Market
Industrial Motors
Gearless Elevator Traction Motor Market
Industrial Motors
Global Induction Motors Market
Industrial Motors
Global Parallel Shaft Geared Motors Market