
 Fractional Horsepower Motor Market | 2026-2036
Fractional Horsepower Motor Market Size, Share, and Industry Trends Forecast 2026-2036
Fractional Horsepower Motor Market Foresight
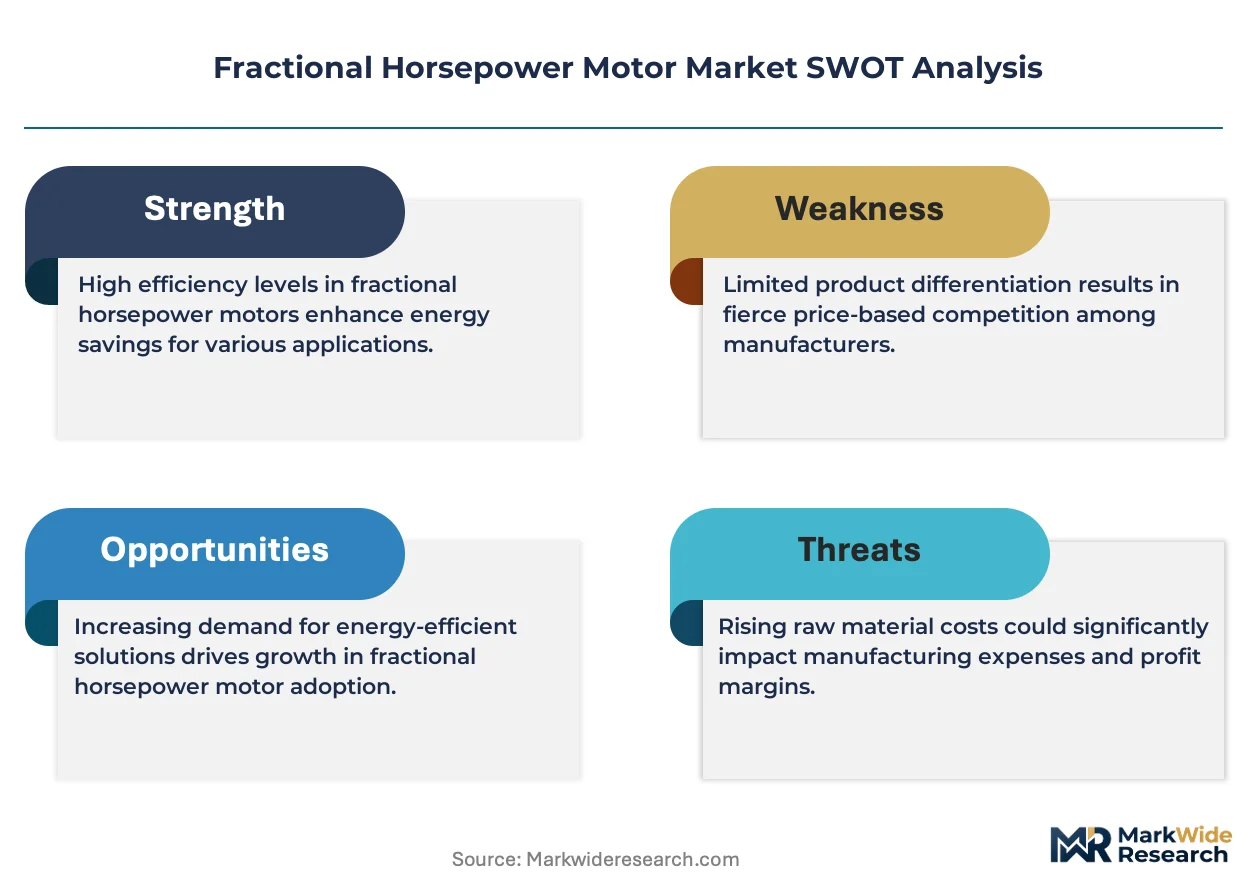
Copper winding substitution by aluminum conductors is decoupling raw material costs from finished motor pricing in the fractional horsepower segment. Nidec Corporation leverages vertical integration across rare-earth magnet supply chains to protect margin pools in brushless DC lines. ABB Ltd anchors its European production footprint with IEC efficiency-class compliance embedded at the design stage. Siemens Aktiengesellschaft differentiates through digital twin integration in motor control systems for HVAC and power tool OEMs.
A fractional horsepower motor converts electrical energy into mechanical motion at outputs below one horsepower, typically operating at speeds from 1,000 to 3,600 RPM with frame sizes standardized under NEMA and IEC dimensional codes; these units serve as the electromechanical backbone of appliances, climate equipment, and light industrial machinery where compact torque delivery governs system performance. Brushless motors command premium positioning as permanent magnet architectures displace shaded pole designs in refrigerator compressors and automotive HVAC blowers, while AC induction units retain volume dominance in washing machines and pumps where cost sensitivity overrides efficiency gains. Stepper motor technology occupies specialized niches in precision positioning equipment, though switched reluctance variants are gaining design wins in variable-speed fan applications.
EPA appliance efficiency standards and DOE furnace fan regulations in the United States compel manufacturers to redesign winding configurations and magnetic circuits, while REACH substance restrictions in Europe constrain insulation varnish chemistries and lamination coatings. China's GB 18613 motor efficiency standards and India's BIS compulsory registration scheme create parallel compliance pathways that fragment certification requirements for exporters. Stakeholders must monitor divergence between regional efficiency test protocols and material substance limits when configuring product platforms for multi-territory deployment.
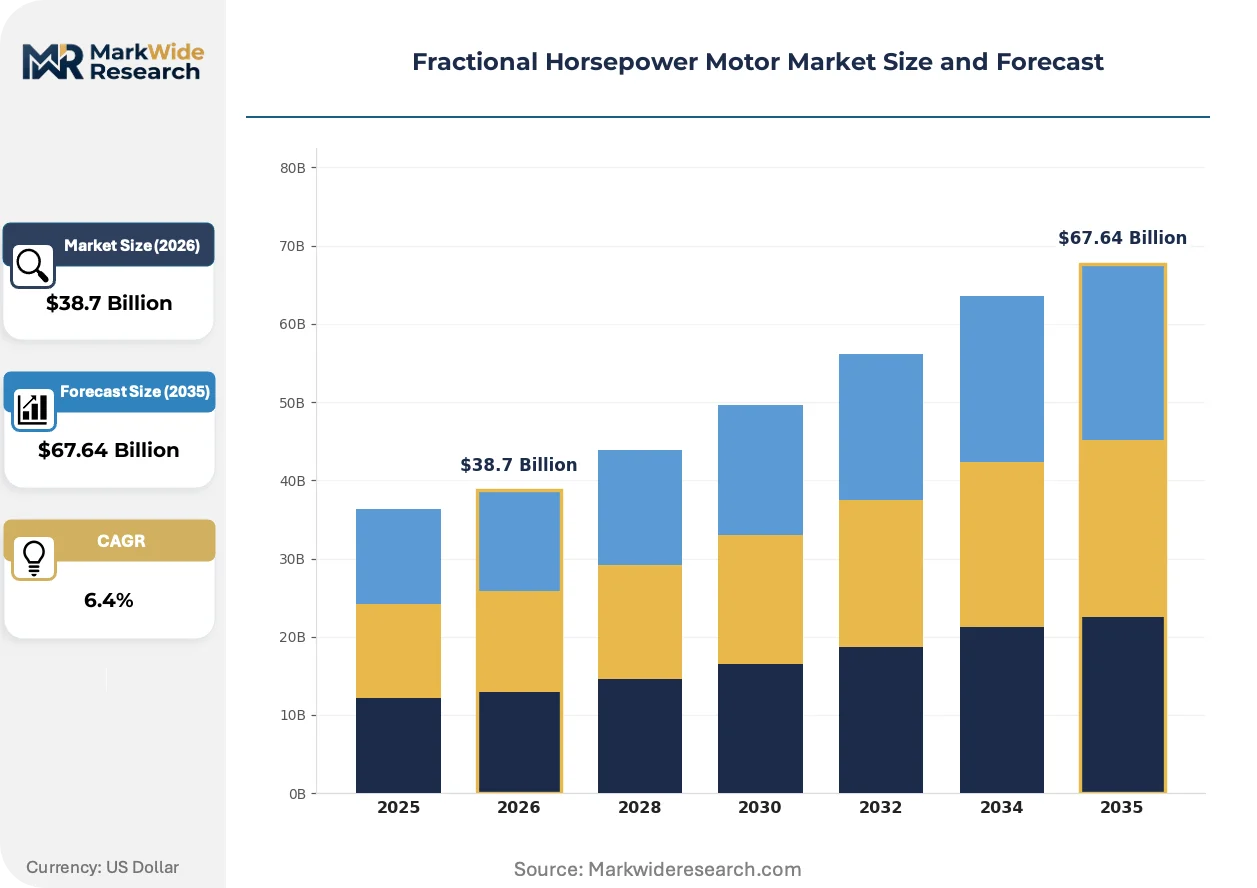
Market Dynamics
Brushless DC architectures are electrifying motor system design across HVAC and appliance lines, while rare-earth magnet supply concentration and efficiency mandates compress design cycles and sourcing strategies simultaneously.
Growth Catalysts
- EPA Appliance Efficiency Standards:DOE furnace fan regulations in the United States force winding redesigns and magnetic circuit upgrades, pulling demand toward premium efficiency tiers in residential climate equipment.
- Permanent Magnet Substitution:Ferrite and rare-earth magnet architectures displace shaded pole induction in refrigerator compressors and automotive HVAC blowers, enabled by falling magnet costs and compact form factors.
- China-India-Germany Procurement Cluster:Industrial automation and consumer appliance manufacturing concentrates in these three markets, anchoring volume contracts for fractional horsepower units across multiple duty cycles.
Market Restraints
- Rare-Earth Supply Concentration:Neodymium and dysprosium refining concentrates in China's upstream processing infrastructure, exposing brushless motor margins to export quota volatility and geopolitical friction.
- Copper-Aluminum Substitution Limits:Aluminum conductors reduce raw material costs but sacrifice thermal performance and winding density, constraining high-torque applications in power tools and industrial pumps.
- REACH Substance Restrictions:ECHA constraints on insulation varnish chemistries and lamination coatings force reformulation cycles that extend certification timelines for European market entry.
Strategic Opportunities
- India BIS Compulsory Registration:India's efficiency labeling mandate creates a compliance-driven upgrade cycle in residential pumps and agricultural equipment, favoring exporters with pre-certified IEC platforms.
- Digital Twin Convergence:Motor control systems integrating real-time thermal modeling and predictive maintenance algorithms open premium pricing in commercial HVAC and precision automation.
- Automotive Accessory Electrification:48V mild-hybrid architectures expand addressable market for compact brushless blowers and cooling fans in passenger vehicle thermal management.
Industry Challenges
- Magnet Engineer Scarcity:Permanent magnet motor design expertise concentrates in a narrow talent pool across Japan, Germany, and China, lengthening R&D staffing cycles for new entrants.
- Multi-Territory Certification Fragmentation:Divergent efficiency test protocols between GB 18613, BIS, and DOE standards force redundant testing investments for global product platforms.
- Legacy Induction Footprint Stranding:Appliance OEMs face sunk-cost pressure from existing shaded pole and capacitor-start tooling lines, slowing brushless transition despite efficiency gains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fractional Horsepower Motor Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $67.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AC Motors, DC Motors, Brushless Motors, Shaded Pole Motors, Universal Motors Technology: Permanent Magnet, Induction, Synchronous, Stepper, Switched Reluctance Application: Home Appliances, Office Equipment, Automotive Accessories, HVAC Systems, Power Tools End User: Consumer Electronics Manufacturers, HVAC Contractors, Vehicle Component Suppliers, Industrial Equipment Builders, DIY Retailers |
| Companies Covered | Nidec Corporation, ABB Ltd, Siemens Aktiengesellschaft, WEG S.A., Johnson Electric Holdings Limited, Regal Rexnord Corporation, Rockwell Automation, Inc., Allied Motion, Inc., AMETEK, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fractional Horsepower Motor Market Shifts & Advancements
Permanent magnet brushless architectures, digital control integration, and efficiency-driven procurement recalibration are compressing traditional motor design paradigms across multiple end-use verticals.
Switched reluctance motor technology is electrifying variable-speed fan and pump applications where rare-earth magnet exposure creates supply risk. HVAC OEMs in Germany and Japan are piloting these designs for commercial ventilation systems. The technology is electrifying a pathway to magnet-free efficiency compliance in markets with strict local content requirements.
China's GB 18613 motor efficiency standards and parallel carbon neutrality targets are forcing lamination steel upgrades and copper reduction strategies in domestic manufacturing. Exporters face dual certification burdens aligning IEC test methods with Chinese sampling protocols. The appliance and pump segments bear the heaviest compliance costs, with redesign cycles compressed to 18-month windows.
Buyer concentration among multi-national HVAC and appliance OEMs is compressing supplier margins and accelerating direct sourcing from motor specialists. Distributor intermediaries lose volume share as procurement teams consolidate spend with vertically integrated manufacturers. The shift is most visible in China's Yangtze River Delta manufacturing cluster, where OEMs negotiate frame-size standardization in exchange for volume commitments.
Fractional Horsepower Motor Market Segmentation
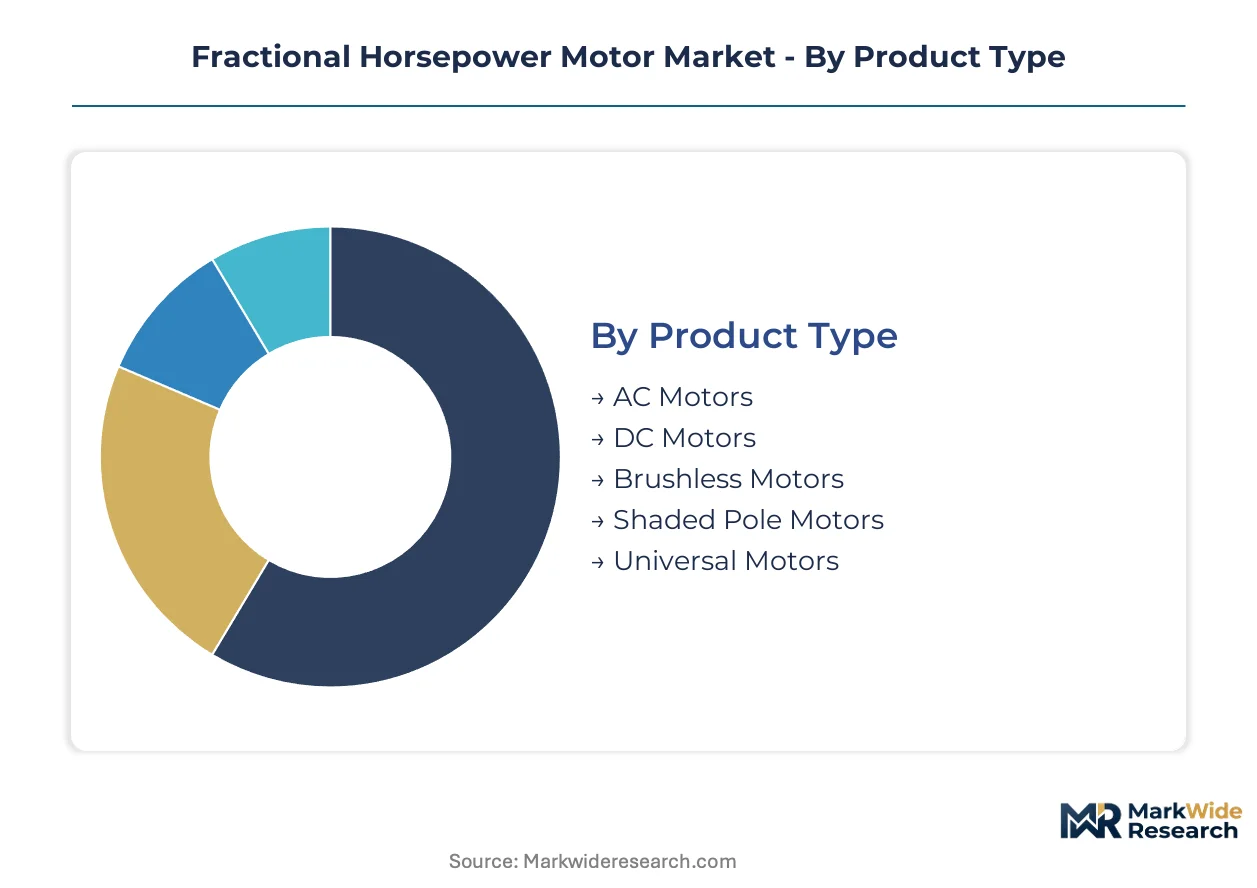
Fractional horsepower motor segmentation reveals divergent technology lifecycles and procurement patterns across end-use verticals. Product architecture choices determine compliance pathways, while application-specific duty cycles dictate margin structures and sourcing strategies.
Product Type:
Brushless architectures capture premium positioning as efficiency mandates tighten, while AC induction units retain volume dominance in cost-sensitive applications.
- AC Motors:Single-phase induction designs dominate washing machines, pumps, and compressors where capacitor-start configurations balance torque delivery against manufacturing simplicity. Demand concentrates in China's Yangtze River Delta appliance cluster as OEMs negotiate frame-size standardization for volume commitments.
- Brushless Motors:Permanent magnet synchronous architectures with electronic commutation displace shaded pole units in refrigerator compressors and automotive HVAC blowers. Germany's automotive component suppliers anchor procurement for 48V mild-hybrid cooling systems where compact form factors justify magnet costs.
- DC Motors:Series-wound and permanent magnet designs serve power tools and automotive actuators requiring high starting torque. India's power tool OEMs drive specification upgrades as BIS efficiency labeling extends to cordless equipment categories.
- Shaded Pole Motors:Single-phase induction with auxiliary winding displacement persists in low-torque fan applications. Cost pressure from brushless substitution accelerates consolidation among legacy manufacturers in China's Shandong province.
- Universal Motors:Series-wound AC/DC compatibility suits high-speed applications in vacuum cleaners and food processors. European appliance brands specify these units for product lines requiring multi-voltage export flexibility.
Today's leader: AC Motors. Tomorrow's challenger: Brushless Motors.
Technology:
Magnet-based architectures command design attention as rare-earth supply concentration reshapes sourcing risk profiles across motor categories.
- Permanent Magnet:Neodymium-iron-boron and ferrite magnet rotors enable highest efficiency tiers in brushless DC platforms. China's magnet refining concentration exposes margins to export quota volatility, prompting Japanese OEMs to diversify ferrite sourcing to Vietnam.
- Induction:Squirrel-cage rotor designs without permanent magnets retain cost advantage in fixed-speed pump and compressor applications. Indian agricultural pump manufacturers specify these units for BIS-mandated efficiency upgrades in rural electrification programs.
- Synchronous:Reluctance and hysteresis variants serve precision timing applications in office equipment and medical devices. German industrial automation specialists integrate these motors with encoder feedback for positioning accuracy.
- Stepper:Hybrid and variable reluctance configurations provide discrete angular positioning without closed-loop control. 3D printer manufacturers in Shenzhen and Boston specify these for extruder drive mechanisms.
- Switched Reluctance:Magnet-free architectures with salient pole rotors gain traction in variable-speed HVAC fans where supply security outweighs acoustic performance tradeoffs. Japanese commercial ventilation OEMs pilot these designs for export to markets with local content requirements.
Permanent magnet systems anchor current revenue pools. Switched reluctance technology climbs fastest as supply security concerns intensify.
Application:
Climate equipment and appliance verticals split procurement between efficiency-driven redesigns and cost-optimized legacy platforms.
- HVAC Systems:Furnace blowers, condenser fans, and heat pump compressors face DOE efficiency regulations forcing winding redesigns and electronic control integration. US residential equipment manufacturers consolidate supplier bases to vertically integrated motor specialists.
- Home Appliances:Refrigeration compressors, washing machine drives, and dishwasher pumps span efficiency tiers from shaded pole to brushless permanent magnet. China's appliance export hub in Hefei drives specification convergence across white goods categories.
- Automotive Accessories:48V mild-hybrid architectures expand demand for compact brushless blowers, cooling fans, and electric power steering pumps. German vehicle component suppliers specify these for European CO2 fleet compliance pathways.
- Power Tools:Cordless drill and angle grinder motors balance torque density against battery pack weight constraints. Milwaukee and Bosch professional tool divisions drive brushless adoption in premium product tiers.
- Office Equipment:Printer fuser drives and document feeder mechanisms require precise speed control at reduced acoustic signatures. Japanese multifunction device manufacturers source these from dedicated precision motor suppliers in Nagano prefecture.
HVAC Systems command the largest procurement volumes. Automotive Accessories expand most quickly as vehicle electrification penetrates accessory subsystems.
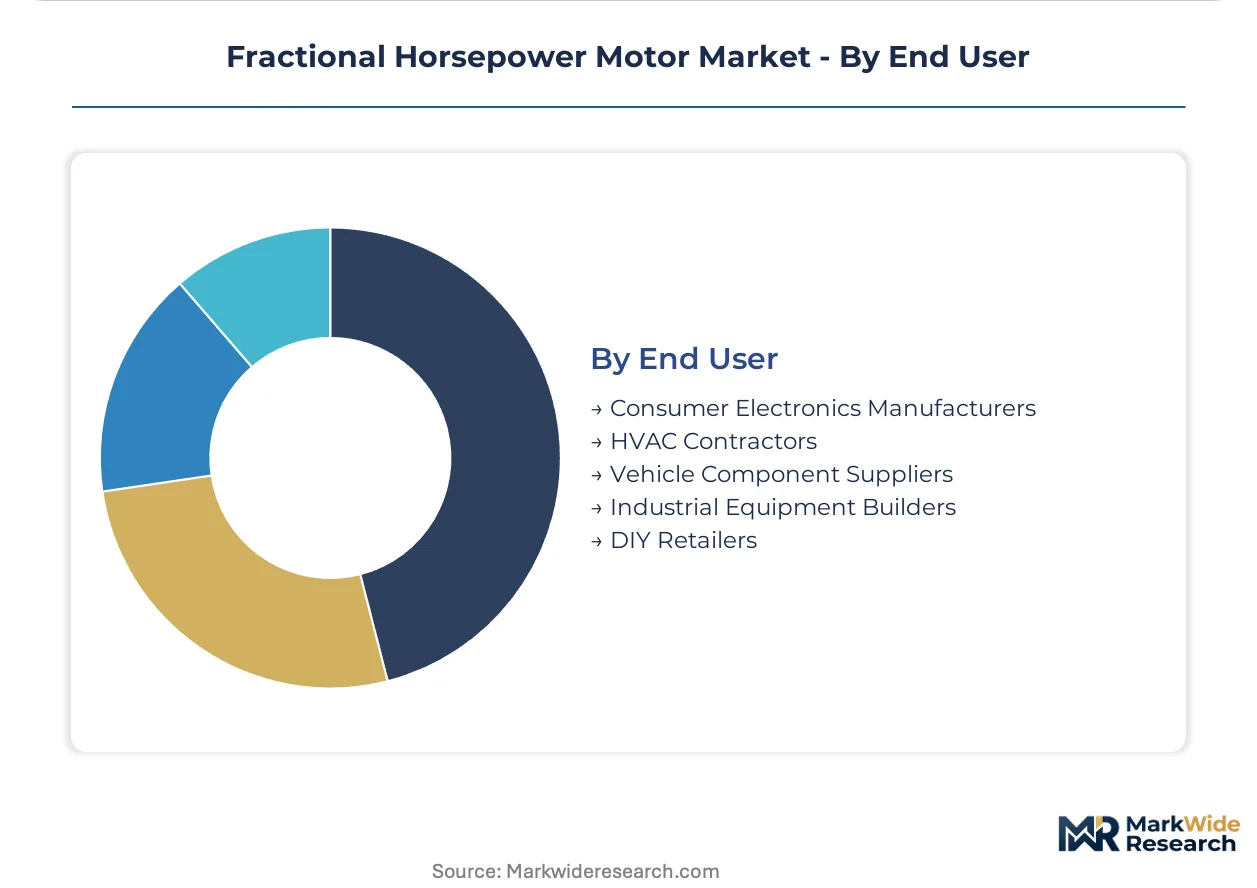
End User:
Buyer concentration among multinational OEMs compresses intermediary margins and accelerates direct sourcing relationships with motor specialists.
- HVAC Contractors:Commercial and residential installation firms specify replacement motors from distributor inventories, with efficiency tier selection driven by local utility rebate programs. US regional contractors increasingly source direct from manufacturers for large retrofit projects.
- Consumer Electronics Manufacturers:Appliance OEMs in China, South Korea, and Mexico consolidate spend with vertically integrated suppliers offering frame-size standardization. These buyers negotiate multi-year volume commitments against dedicated production lines.
- Vehicle Component Suppliers:Tier-1 thermal management and engine cooling specialists integrate compact brushless units for 48V and high-voltage electric vehicle platforms. German and Japanese suppliers dominate specification influence.
- Industrial Equipment Builders:Pump, conveyor, and material handling OEMs select motors based on duty cycle severity and environmental protection ratings. Indian textile machinery manufacturers drive demand for tropicalized insulation systems.
- DIY Retailers:Home improvement chains stock replacement motors for consumer repair applications, with private label programs sourcing from Chinese contract manufacturers. These channels lose share to e-commerce direct-to-consumer fulfillment.
Consumer Electronics Manufacturers anchor procurement scale. Vehicle Component Suppliers gain purchasing power fastest as automotive electrification accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta manufacturing cluster concentrates the world's largest fractional horsepower motor procurement volumes, with appliance OEMs in Hefei and Shanghai driving specification standardization across refrigeration and washing machine platforms.
China
Domestic appliance manufacturers in Hefei and Qingdao upgrade compressor motor specifications to meet GB 18613 efficiency mandates and carbon neutrality targets. MIIT enforcement of motor efficiency standards forces lamination steel upgrades and copper reduction strategies. The Yangtze River Delta cluster anchors volume contracts as OEMs negotiate frame-size standardization with vertically integrated suppliers.
Germany
Automotive component suppliers in Stuttgart and Munich specify compact brushless units for 48V mild-hybrid thermal management systems. KBA oversight of CO2 fleet compliance pathways accelerates electrification of accessory subsystems. The Baden-Württemberg industrial corridor concentrates procurement for European HVAC and power tool OEMs demanding IEC efficiency-class compliance.
United States
Residential HVAC equipment manufacturers consolidate supplier bases to meet DOE furnace fan efficiency regulations. EPA appliance standards compel winding redesigns and magnetic circuit upgrades in climate equipment. The Southeast manufacturing belt, particularly Georgia and Tennessee, hosts expanded motor assembly capacity serving domestic appliance brands.
India
Agricultural pump and residential appliance manufacturers in Gujarat and Maharashtra face BIS compulsory registration mandates for efficiency labeling. CEA rural electrification programs drive specification upgrades in irrigation equipment. The Pune-Nashik industrial corridor attracts motor specialists establishing certified IEC platforms for export competitiveness.
Japan
Commercial ventilation OEMs in Nagano and Osaka prefectures pilot switched reluctance motor designs for magnet-free efficiency compliance. METI energy conservation standards push precision motor suppliers toward digital control integration. The Chubu region anchors development of thermal modeling algorithms for predictive maintenance applications.
Fractional Horsepower Motor Market Competitive Landscape
Backward integration into rare-earth magnet supply chains dominates the current landscape as brushless motor specialists defend margin pools against raw material volatility. The vendor base stratifies across three tiers: multinational conglomerates with captive magnet sourcing, mid-cap motor specialists with regional manufacturing footprints, and contract assemblers serving price-sensitive appliance segments. Strategic archetypes include vertically integrated magnet-to-motor manufacturers, IEC-certified platform specialists, and automotive-tier component suppliers. Capacity expansion in Southeast Asian lamination facilities and strategic partnerships for digital twin control systems represent the dominant competitive moves.
Among Japanese-based manufacturers, Nidec Corporation exemplifies the vertically integrated archetype through upstream control over magnet supply chains. ABB Ltd and Siemens Aktiengesellschaft occupy positions within the European industrial automation tier, representing the IEC-certified platform specialist model. These three entities anchor distinct strategic vectors: magnet supply security, efficiency compliance integration, and digital control system convergence.
| Leading Market Players |
|---|
| Nidec Corporation |
| ABB Ltd |
| Siemens Aktiengesellschaft |
| WEG S.A. |
| Johnson Electric Holdings Limited |
| Regal Rexnord Corporation |
| Rockwell Automation, Inc. |
| Allied Motion, Inc. |
| AMETEK, Inc. |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up specialists in North American motor assembly anchor pricing discipline through captive lamination stamping capacity, while their sourcing concentration in Chinese rare-earth refining exposes margin pools to quota volatility and forces contract restructuring toward indexed magnet pricing.
Pricing Analysis
Input-cost pass-through from neodymium and copper markets dominates pricing structures across brushless and induction architectures. Three-tier pricing separates IEC Premium Efficiency from Standard and Economy tiers, with certification grade and volume scale as primary differentiation drivers. Pricing pressure stems from buyer consolidation among multinational HVAC OEMs negotiating frame-size standardization. Appliance manufacturers exhibit highest price sensitivity, while automotive Tier-1 suppliers absorb premiums for magnet-secured supply.
Supply Chain Analysis
Rare-earth magnet supply rests on Chinese upstream processing infrastructure, with secondary concentration in Japanese ferrite production and Vietnamese separation facilities. Lamination steel draws from Chinese and Indian cold-rolling mills, while copper winding wire sources from Chilean and Zambian concentrate. Single-source vulnerability in neodymium refining creates tariff exposure and quota risk. Distribution runs through direct OEM contracts consolidating intermediary distributor roles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where efficiency mandates in the United States, Europe, and Asia-Pacific force repeated equipment replacement cycles and specification upgrades.
For Market Incumbents: Deepen backward integration into lamination steel and magnet supply chains to offset rare-earth price volatility. Secure IEC efficiency pre-certification for multi-territory platforms before BIS and GB 18613 divergence accelerates. Add capacity in India's Pune-Nashik corridor to capture agricultural pump upgrade demand.
For New Entrants and Emerging Players: Begin with switched reluctance motor architectures for HVAC fan applications where magnet-free designs address supply security concerns. Target German commercial ventilation OEMs piloting these technologies for export markets with local content requirements. Pursue joint development agreements rather than component supply relationships.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap motor specialists with IEC-certified platforms but limited magnet supply control. Long-term viability hinges on regulatory enforcement durability across efficiency standards. Watch China's export quota announcements as the critical inflection signal for brushless motor margin compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Magnet Supply Security Investment | Captive rare-earth sourcing protects margin pools against Chinese export quota volatility. |
| IEC Efficiency Pre-Certification | Early compliance with BIS and GB 18613 standards accelerates multi-territory market entry. |
| Digital Twin Control Integration | Predictive maintenance algorithms command premium pricing from HVAC and power tool OEMs. |
| Switched Reluctance R&D Scale-Up | Magnet-free architectures address supply risk in markets with strict local content requirements. |
| India Manufacturing Footprint Expansion | Pune-Nashik corridor positioning captures BIS-mandated pump and appliance upgrade cycles. |
Research Methodology
Coverage spans China, India, Germany, the United States, and Japan, with primary inputs from each market. The approach combines interviews with motor procurement directors at HVAC OEMs, appliance manufacturing engineers, automotive Tier-1 thermal management specialists, and rare-earth magnet trading desks. Secondary validation draws from MIIT efficiency standard filings, DOE furnace fan rulemaking dockets, BIS registration databases, and IEC test protocol documentation. Bottom-up unit shipment estimates triangulate against top-down value projections.
Rate-of-change decomposition separates volume effects from mix shifts and pricing dynamics across the projection horizon. The analytical framework models motor architecture, magnet technology, application vertical, end-user category, and regional regulatory cluster as core segmentation dimensions. CAGRs derive from fitted growth curves incorporating efficiency mandate phase-in schedules, OEM platform redesign cycles, and raw material cost trajectories. Industry-specific inputs include lamination steel pricing indices and rare-earth oxide spot market trends.
Caveats apply where Chinese export quota announcements or REACH substance restriction expansions could materially shift the outlook. Forecasts reflect assumptions about regulatory enforcement consistency and OEM redesign cycle timing. A small set of named triggers—magnet supply disruption, BIS-GB 18613 test protocol divergence, and automotive 48V platform adoption rates—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Motors
Industrial Personnel and Burden Carriers [Electric] Market
Industrial Motors
Global Low Voltage Motors Market
Industrial Motors
Global Direct Current (DC) Motor Market
Industrial Motors
Europe Induction Motor Market
Industrial Motors
North America Industrial Motors Market
Industrial Motors
Elevator Motors Market
Industrial Motors
Crude Heater Market
Industrial Motors
Hoist and Elevator Motors Market
Industrial Motors
North America Induction Motor Market
Industrial Motors
Safety Drives and Motors Market
Industrial Motors
Spargers Market
Industrial Motors
Cryogenic Air Separation Units (Asus) Market
Industrial Motors
Seamless Steel Gas Cylinders Market
Industrial Motors
HVAC Motors Market
Industrial Motors
Smart Motors Market
Industrial Motors
Global Medium and High Power Motors Market