
 Air Heater Tubes Market | 2026-2036
Air Heater Tubes Market Size, Share, and Industry Trends Forecast 2026-2036
Air Heater Tubes Market Analytics
EPA emissions standards for industrial boilers is decoupling legacy carbon steel tube demand from new project economics, forcing utilities to recalculate lifecycle replacement costs. Alfa Laval leverages its heat transfer engineering depth to anchor premium positions in corrosive-duty specifications. Kelvion Holding GmbH competes through modular air preheater architectures that reduce field installation complexity. Mersen specializes in graphite-composite tube alternatives for extreme acid-dewpoint applications.
Air heater tubes are hollow metallic conduits, typically fabricated from carbon steel, alloy steel, or stainless steel in diameters ranging from one to four inches, designed to transfer thermal energy from combustion exhaust gases to incoming combustion air in boiler and furnace systems. Their primary industrial purpose centers on improving thermal efficiency by recovering waste heat, thereby reducing fuel consumption and lowering stack temperatures in power generation, petrochemical, and steel manufacturing operations. Steel material grades dominate installed base volumes across coal-fired and biomass boiler fleets, while aluminum tubes capture share in lighter-duty commercial HVAC heat recovery wheels where weight and conductivity trade-offs favor non-ferrous construction. Electric type configurations lead the technology mix in precision process heating environments, though gas-fired and infrared variants occupy distinct niches in metal treating and drying applications where rapid ramp rates matter.
EPA boiler MACT rules and OSHA process safety management requirements shape material selection, inspection intervals, and replacement procurement across US industrial boiler operators. In Europe, Ecodesign directives and the EU Green Deal carbon border adjustments push operators toward higher-grade alloys that withstand deeper heat recovery without corrosion failure. Stakeholders must monitor how tightening efficiency thresholds in multiple jurisdictions redirect procurement toward predictive maintenance contracts and tube-bundle upgrade cycles rather than standalone component sales.
Market Dynamics
Stainless steel alloys with enhanced corrosion resistance are systematically displacing carbon steel in flue gas environments as efficiency mandates tighten across power generation facilities. This material transition recalibrates procurement economics and lifecycle replacement schedules for boiler operators.
Growth Catalysts
- EPA boiler MACT rules:US industrial operators face accelerated tube replacement cycles as emissions standards harden, redirecting capital toward corrosion-resistant specifications.
- Biomass boiler fleet expansion:Agricultural waste-to-energy plants in Southeast Asia generate sustained demand for acid-resistant tube bundles.
- China's state-backed boiler upgrades:Procurement volumes concentrate in the industrial corridor as state-owned utilities execute efficiency retrofit programs.
Market Restraints
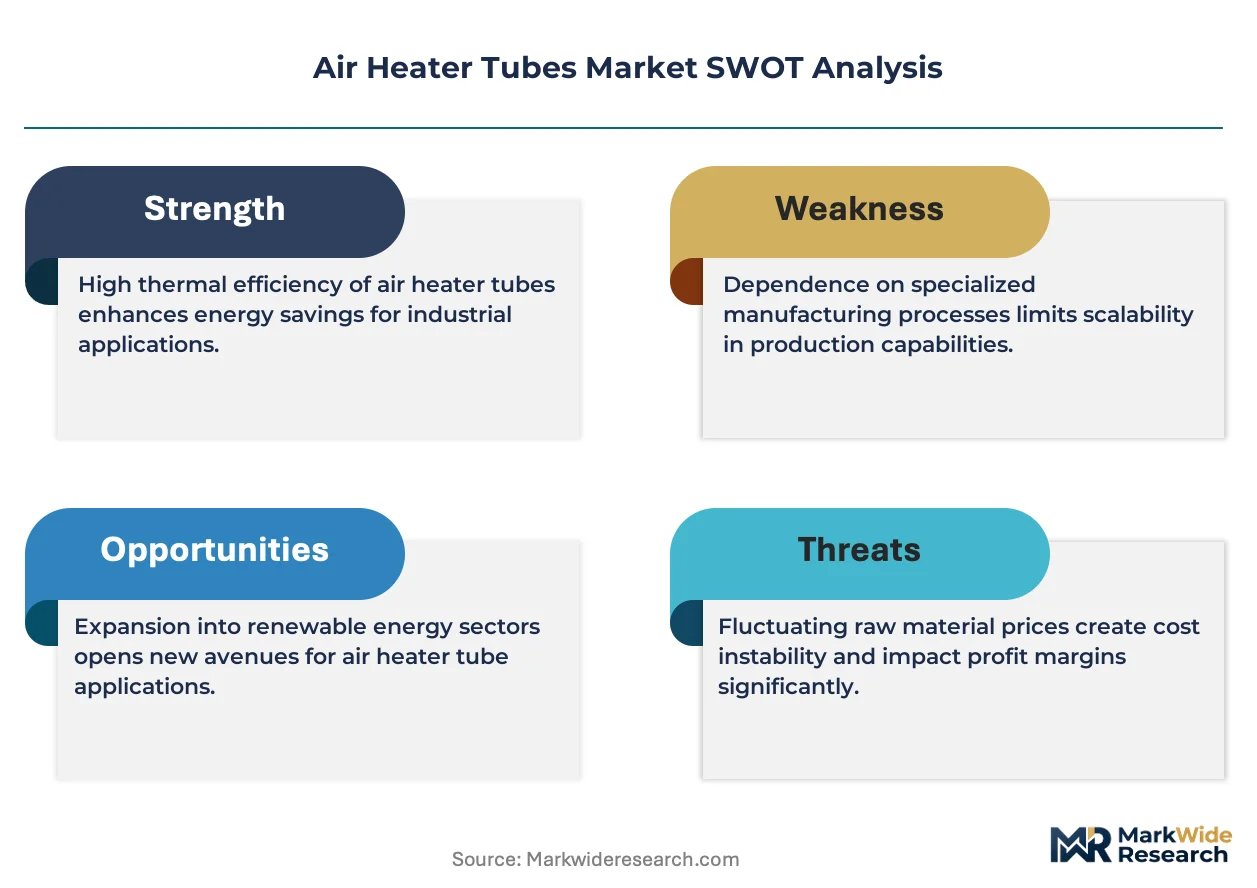
- Nickel and chromium price volatility:Stainless steel input costs swing with mining supply disruptions, compressing fabricator margins.
- Specialty alloy supply concentration:Premium corrosion-resistant grades depend on a limited supplier base in Germany and Japan.
- Acid dewpoint corrosion threshold:Deep heat recovery hits material limits regardless of alloy grade, capping efficiency gains.
Strategic Opportunities
- India's coal fleet modernization:Central Electricity Authority mandates create replacement demand in aging thermal plants.
- Graphite-composite tube convergence:Extreme acid-dewpoint applications open to non-metallic alternatives.
- Predictive maintenance contracts:Sensor-integrated tube bundles enable recurring revenue models beyond component sales.
Industry Challenges
- Welding certification bottlenecks:ASME Section IX qualified welders for exotic alloys remain scarce, extending lead times.
- Legacy system integration:New tube bundles must interface with decades-old boiler architectures without full rebuilds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Heater Tubes Market |
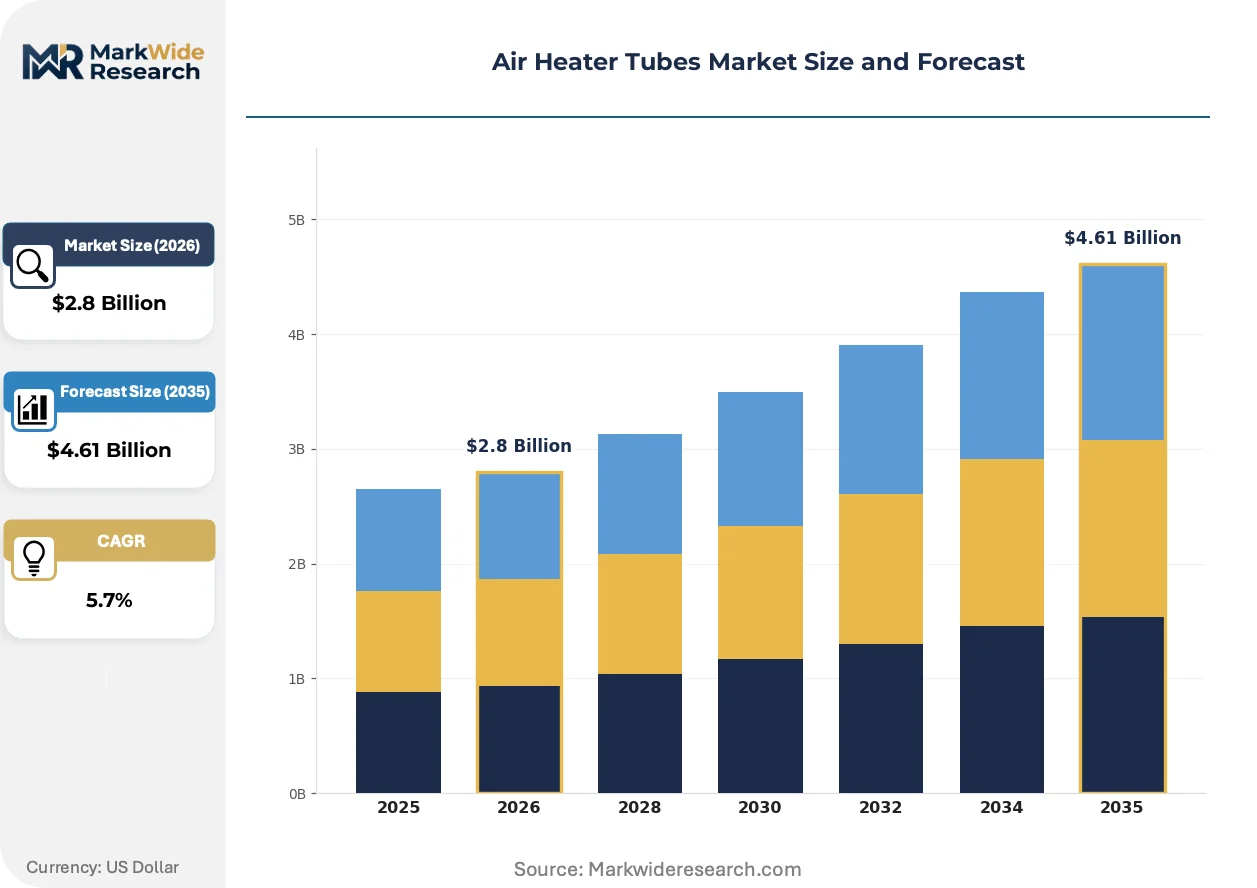
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Electric, Gas, Infrared, Induction Material: Steel, Aluminum, Copper, Plastic Application: Residential Heating, Industrial Processes, Commercial Spaces, Vehicle Heating Design: Compact, Modular, Wall-mounted, Ceiling-mounted |
| Companies Covered | Alfa Laval, Kelvion Holding GmbH, API Heat Transfer, Mersen, Danfoss, SPX Flow, Watlow, Chromalox, GEA Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Heater Tubes Market Evolving Landscape
Digital monitoring systems and advanced materials are restructuring how tube assets are managed and replaced. Operators now optimize around total lifecycle cost rather than upfront capital expenditure.
Corrosion-resistant coating technologies are converging with base material advances to extend tube service intervals in aggressive flue gas chemistries. Power generators in coastal China adopt plasma-sprayed ceramic overlays to combat chloride attack. This convergence is compressing the traditional five-year replacement cycle toward predictive, condition-based swaps.
EU Ecodesign directives and carbon border adjustment mechanisms are elevating material grade requirements for imported boiler components. European operators now specify duplex stainless steels for heat recovery depths previously served by standard grades. German TÜV certification timelines have lengthened, forcing procurement teams to front-load specification work.
Service unbundling is fragmenting the traditional equipment-plus-installation bundle. Indonesian and Vietnamese power developers now procure tube bundles separately from field erection, sourcing installation through local contractors. This pattern concentrates specification authority with consulting engineers rather than turnkey suppliers.
Air Heater Tubes Market Segmentation
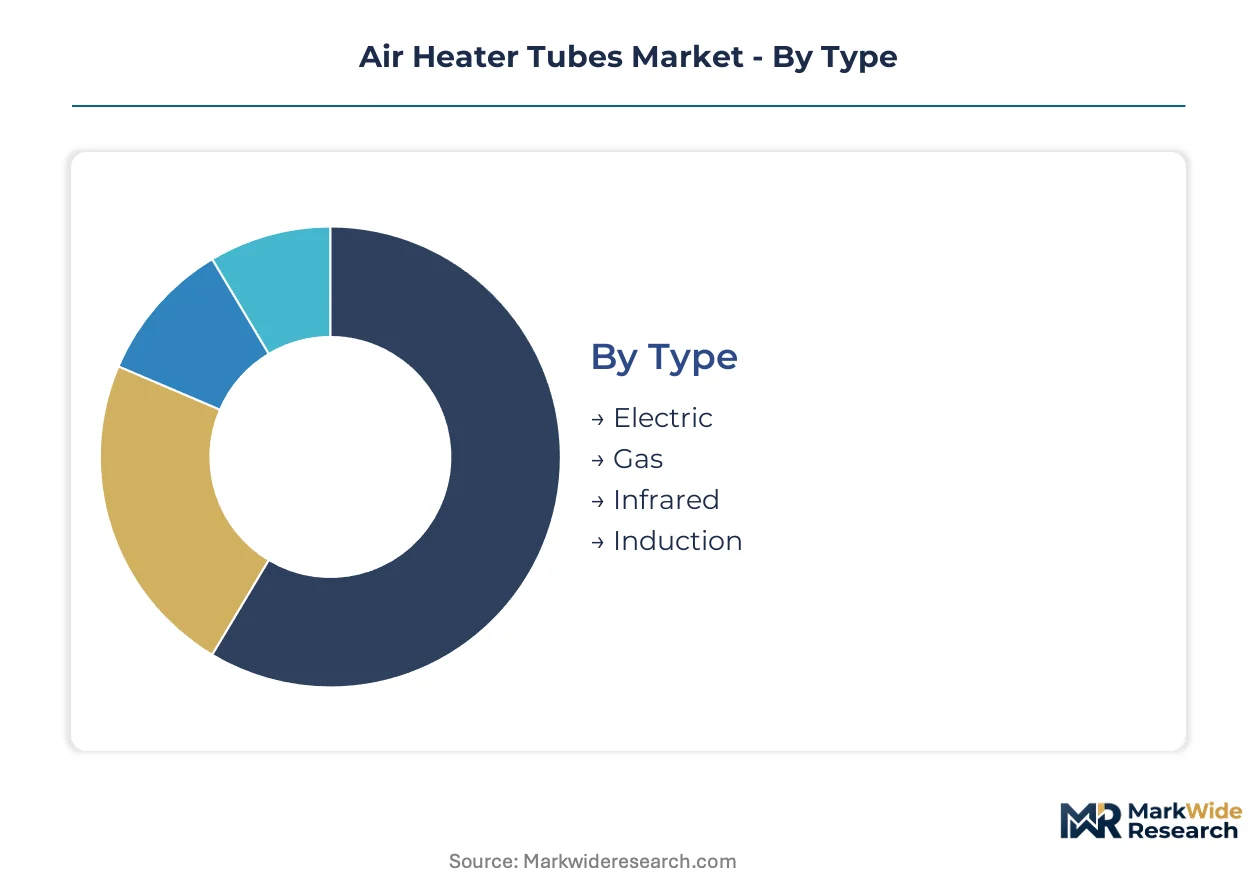
Air heater tube procurement diverges sharply across operating environments, with material grade and thermal duty requirements driving specification splits. Upgrade cycles and replacement economics reshape how fabricators prioritize segment investment and inventory positioning.
Type:
Replacement schedules for aging boiler systems favor technologies that minimize retrofit complexity while meeting tightened efficiency mandates.
- Electric:Precision resistance heating elements deliver controlled temperature profiles for laboratory and pharmaceutical process lines. China's pharmaceutical corridor specifies electric configurations to satisfy MEE emissions monitoring requirements in clean manufacturing zones.
- Gas:Direct-fired combustion tubes achieve rapid thermal ramp rates in metal treating and drying operations. Southeast Asian biomass processors favor gas-fired systems for agricultural waste-to-energy plants where fuel flexibility offsets infrastructure constraints.
- Infrared:Radiant heat transfer suits spot-heating applications in automotive paint curing.
- Induction:Electromagnetic field heating enables non-contact thermal processing for semiconductor wafer fabrication.
Volume placements concentrate in Gas configurations; the faster expansion belongs to Electric.
Material:
Lifecycle cost calculations now dominate material selection as corrosion failures accelerate replacement frequencies in aggressive flue gas environments.
- Steel:Carbon and alloy grades retain dominance in coal-fired boiler fleets due to weldability and pressure vessel code compliance. India's Central Electricity Authority mandates drive steel tube procurement for aging thermal plant retrofits across the National Capital Region.
- Aluminum:Lightweight extrusions capture commercial HVAC heat recovery applications where conductivity-to-weight ratios outweigh pressure containment needs. Indonesian shopping mall developers specify aluminum for rooftop air handling unit retrofits in Jakarta's humid coastal climate.
- Copper:Superior thermal conductivity serves residential hydronic heating manifolds.
- Plastic:Polymer composites address low-temperature corrosive exhaust in laboratory fume hoods.
Steel commands the installed base; aluminum gains share fastest in new lightweight specifications.
Application:
End-use thermal duty severity determines tube wall thickness, alloy grade, and inspection interval requirements across procurement categories.
- Residential Heating:Standard carbon steel tubes in finned configurations serve forced-air furnace heat exchangers. US HVAC replacement demand concentrates in Midwestern states where EPA boiler MACT compliance deadlines approach for residential-scale biomass conversions.
- Industrial Processes:High-pressure alloy specifications withstand continuous duty in petrochemical crackers and steel reheating furnaces. German Ruhr Valley operators specify duplex stainless grades under EU Ecodesign directive pressure to deepen heat recovery without acid dewpoint failure.
- Commercial Spaces:Mid-duty aluminum and steel hybrids balance first cost with efficiency in office building air handlers.
- Vehicle Heating:Compact brazed aluminum designs address weight constraints in electric bus thermal management.
Industrial Processes absorb the premium alloy volume; Vehicle Heating climbs fastest on electrification tailwinds.
Design:
Installation geometry constraints in legacy boiler houses and new construction sites fragment demand across architectural form factors.
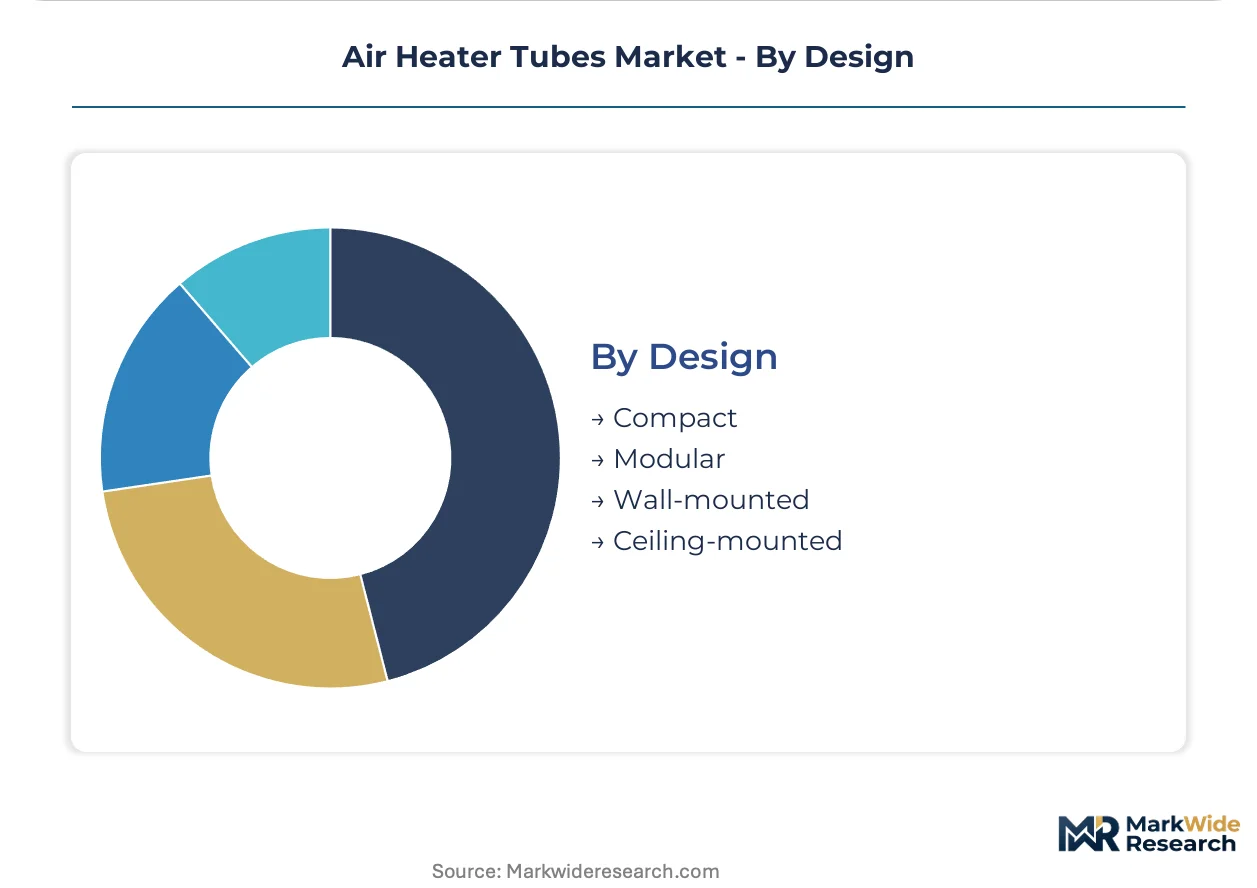
- Compact:Space-constrained tube bundles integrate into marine boiler rooms and offshore platform steam generators. Singapore shipyard retrofits specify compact designs to satisfy MPA safety clearances in engine room rebuilds.
- Modular:Field-assembled sections reduce crane requirements and accelerate outage schedules. Vietnamese independent power producers favor modular configurations to bypass scarce ASME-certified welding capacity during seasonal maintenance windows.
- Wall-mounted:Vertical orientation suits commercial building perimeter heating with minimal footprint.
- Ceiling-mounted:Overhead radiant panels address warehouse and manufacturing floor spot heating.
Modular designs capture the replacement project volume; Compact configurations expand most quickly in marine and offshore applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's coastal industrial zones concentrate procurement through state-backed efficiency mandates, while India's thermal corridor and Germany's Ruhr Valley drive replacement cycles under tightening emissions frameworks.
China
Provincial energy bureaus in Jiangsu and Shandong accelerate boiler retrofit timelines under MEE emissions monitoring protocols. State-owned utilities in the Yangtze River Delta specify duplex stainless grades for deep heat recovery applications without acid dewpoint failure.
India
The Central Electricity Authority mandates tube replacement across aging National Capital Region thermal plants under national efficiency targets. Fabricators in Gujarat and Maharashtra scale alloy steel capacity to serve coal fleet modernization programs.
Germany
Ruhr Valley operators specify premium corrosion-resistant specifications under EU Ecodesign directive pressure. TÜV certification timelines for duplex grades have lengthened, forcing procurement teams in North Rhine-Westphalia to front-load specification work.
United States
EPA boiler MACT compliance deadlines approach for Midwestern biomass conversions and industrial operators. Texas and Ohio petrochemical clusters face accelerated replacement cycles as emissions standards harden, redirecting capital toward corrosion-resistant specifications.
Vietnam
Independent power producers in the Mekong Delta favor modular air preheater configurations to bypass scarce ASME-certified welding capacity. Indonesian and Vietnamese developers increasingly unbundle tube procurement from field erection, sourcing installation through local contractors.
Air Heater Tubes Market Competitive Landscape
German and Swedish producers anchor the premium alloy tier; Chinese fabricators hold volume positions in standard carbon steel specifications. The vendor base splits between consolidated heat transfer engineering groups and regional tube specialists serving replacement cycles. Three archetypes dominate: diversified thermal equipment conglomerates, corrosion-resistant alloy specialists, and modular system integrators. Capacity expansion and predictive maintenance service bundling represent the dominant competitive moves reshaping procurement relationships.
Within the premium engineering tier, Alfa Laval and Kelvion Holding GmbH exemplify heat transfer depth positioning, while Mersen occupies a specialist niche in non-metallic alternatives for extreme duty cycles. These three anchors illustrate how specification authority concentrates with engineering-intensive vendors capable of integrating material science with outage scheduling optimization.
| Leading Market Players |
|---|
| Alfa Laval |
| Kelvion Holding GmbH |
| API Heat Transfer |
| Mersen |
| Danfoss |
| SPX Flow |
| Watlow |
| Chromalox |
| GEA Group |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap fabricators in Germany and Japan anchor premium alloy supply, translating concentrated technical certification capacity into pricing discipline that resists spot-market volatility. Their ownership structure prioritizes long-term customer relationships over volume share, compressing margin pressure downward through the supply chain.
Pricing Analysis
Short lead-time premiums dominate pricing negotiations as outage windows tighten across power generation fleets. Three-tier pricing structure across premium, standard, and economy levels separates ASME-certified duplex grades from standard stainless and carbon steel alternatives. Cost compression in standard grades is intensifying because Chinese fabricators are expanding export capacity. Industrial process operators show least price sensitivity given failure costs; residential HVAC contractors absorb most pressure.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Houston feed hub-and-spoke patterns serving maintenance contractors with 48-hour turnaround requirements. Supply concentrates in China for carbon steel tubes, Germany and Japan for specialty alloys, and India for intermediate alloy grades. Nickel and chromium feedstock draws from Indonesian mining concessions and Russian refining capacity. Single-source vulnerability sits with ASME-certified welding consumables. Distribution runs through authorized stocking distributors holding mill-direct relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The air heater tubes sector sits in a material-transition phase as graphite-composite and ceramic-coated alternatives displace legacy carbon steel in extreme acid-dewpoint environments. Procurement teams now optimize around total lifecycle cost rather than upfront capital expenditure.
For Market Incumbents: Anchor specification authority through predictive maintenance service bundling that locks in replacement cycles. Invest in backward integration into nickel alloy supply to offset feedstock volatility from Indonesian mining disruptions. Defend against modular system integrators by embedding sensor diagnostics into tube bundles. For New Entrants and Emerging Players: Direct-to-utility digital procurement platforms offer the lowest-friction entry path around established distributor relationships. Target Vietnamese independent power producers with unbundled tube-plus-installation offerings that bypass scarce ASME-certified welding capacity. Lead with modular field-assembly configurations that reduce crane requirements during seasonal maintenance windows. For Investors and Strategic Acquirers: Distressed-cycle entries favor corrosion-resistant alloy specialists in Germany's Ruhr Valley facing elongated TÜV certification timelines. Long-term viability centers on service revenue attachment rates rather than component margins. Watch for inflection when state-backed boiler retrofit programs in China's Yangtze River Delta accelerate specification shifts toward duplex grades.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Service Bundling | Sensor-integrated tube bundles enable recurring revenue models beyond standalone component sales. |
| Backward Integration into Nickel Alloy Supply | Captive feedstock sourcing insulates margins from Indonesian mining disruption volatility. |
| Modular Field-Assembly Configuration | Pre-fabricated sections reduce crane requirements and accelerate outage schedules in Vietnam. |
| Graphite-Composite Tube Development | Non-metallic alternatives capture extreme acid-dewpoint applications beyond steel limits. |
| ASME Certification Capacity Expansion | Qualified welder pipelines address lead-time bottlenecks for exotic alloy specifications. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with maintenance directors at power generation facilities, plant engineers in petrochemical clusters, OEM procurement teams at boiler fabricators, and aftermarket service heads at regional distributors combined with EPA boiler MACT compliance databases, EIA power plant inventory records, EU Ecodesign directive implementation reports, and Chinese MEE emissions monitoring disclosures. Bottom-up tube replacement volume estimates triangulated against top-down boiler fleet capacity assessments.
Data-stream reconciliation across procurement transaction records, import-export manifests, and facility-level outage schedules shaped the analytical framework. Segmentation dimensions modeled include material grade tier, thermal duty severity, design configuration, and regional regulatory cluster. CAGRs derived from replacement cycle acceleration curves and efficiency mandate compliance timelines. Industry-specific forecast inputs incorporated nickel price volatility scenarios and ASME-certified welding capacity constraints.
The model holds under steady regulatory enforcement intensity; deviation in emissions standard rollback or alloy supply disruption would shift replacement timing and material mix outcomes. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Motors
Charging Nitrogen Gas Systems Market
Industrial Motors
North America Refrigeration Oil Market
Industrial Motors
Seamless Steel Gas Cylinders Market
Industrial Motors
Global Explosion-Proof Motor Casting Market
Industrial Motors
Global Refrigeration Oil Market
Industrial Motors
Industrial Motor Brakes Market
Industrial Motors
Global Linear Motors Market
Industrial Motors
Global Brushed DC Motor Market
Industrial Motors
Vietnam Air Compressor Market
Industrial Motors
US Electric Motor Market
Industrial Motors
Latin America Hazardous Location Motors Market
Industrial Motors
Synchronous Electric Motor Market
Industrial Motors
Elevator Motors Market
Industrial Motors
Flatwire & HAIR-PIN Motor Market
Industrial Motors
Gearless Elevator Traction Motor Market
Industrial Motors
HVAC Motors Market