
 Middle East and Africa Positive Displacement Pumps Market | 2026-2036
Middle East and Africa Positive Displacement Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Positive Displacement Pumps Market Foresight
Aftermarket service contracts and predictive maintenance subscriptions is broadening revenue streams beyond unit sales for pump OEMs serving the Middle East and Africa. Flowserve Corporation leverages its regional service hub network to capture recurring revenue from rotating equipment fleets. Grundfos Holding A/S anchors its position through digital monitoring platforms that reduce unplanned downtime for water treatment operators. Schlumberger Limited dominates artificial lift and surface pumping packages through its integrated project execution model across Saudi Arabia and the UAE.
Positive displacement pumps mechanically trap fixed fluid volumes within cavities, then force discharge through sealed chamber reduction driven by gears, screws, lobes, or reciprocating elements; these units handle viscous, shear-sensitive, or multiphase fluids at pressures exceeding 10,000 psi in upstream hydrocarbon applications. Diaphragm pumps lead product type demand in chemical processing due to leak-free containment of aggressive reagents, while screw pumps capture margin pools in heavy crude transfer where viscosity tolerance differentiates performance. Electric technology commands the technology segment through energy efficiency mandates, though pneumatic alternatives persist in offshore platforms where explosion-proof requirements restrict electrical infrastructure.
Saudi Standards, Metrology and Quality Organization (SASO) technical regulations and UAE's Emirates Authority for Standardization and Metrology (ESMA) conformity schemes enforce material certification and pressure equipment safety protocols that filter non-compliant suppliers from procurement lists. South Africa's National Regulator for Compulsory Specifications (NRCS) applies similar pressure equipment standards that shape import qualification timelines for European and Asian manufacturers. Stakeholders must monitor how Gulf states integrate carbon intensity benchmarks into industrial equipment procurement criteria, as this will redirect capital toward efficiency-optimized pump architectures and away from legacy specifications.
Market Dynamics
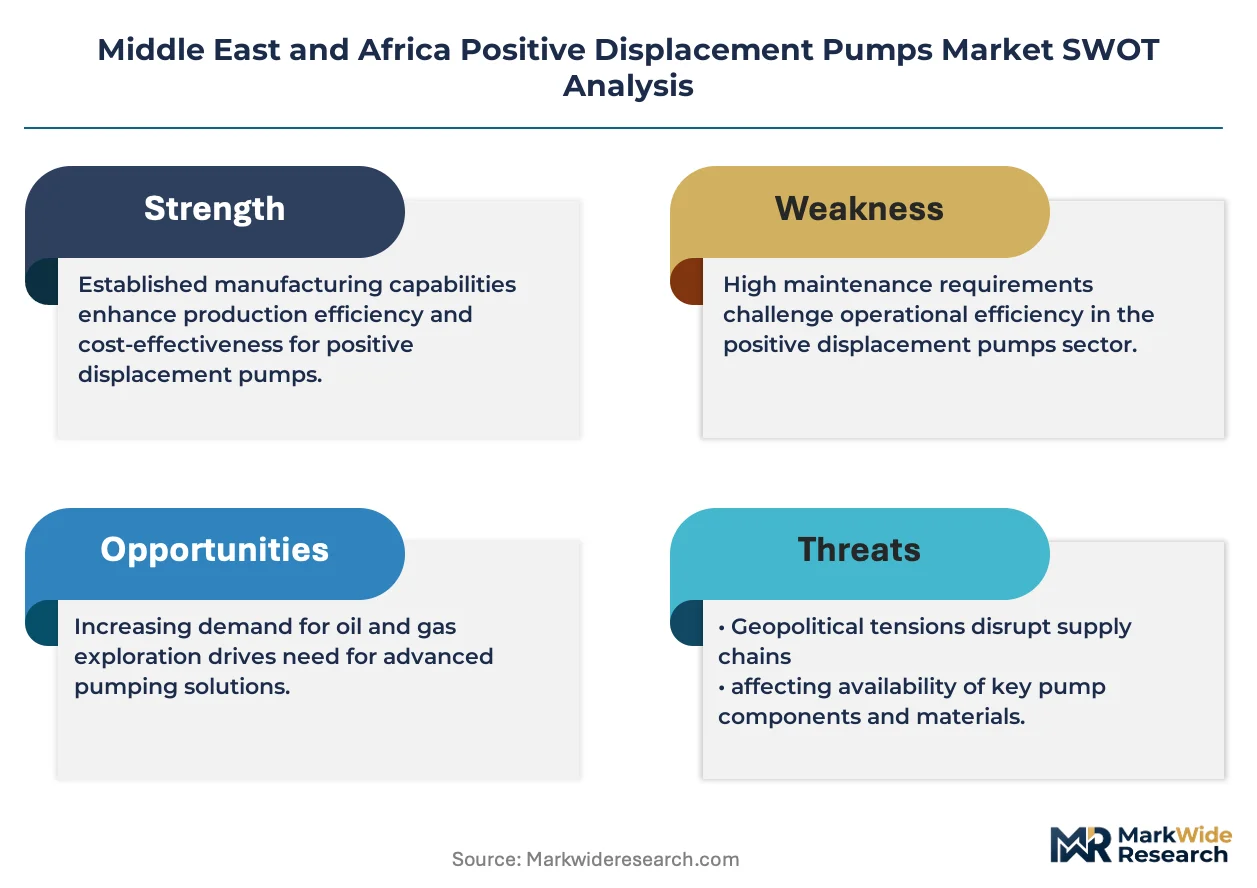
Enhanced oil recovery mandates across Saudi Arabia and the UAE are compressing replacement cycles for high-pressure pumping equipment, forcing operators to retire legacy reciprocating systems ahead of scheduled depreciation timelines.
Growth Catalysts
- SASO Technical Regulations:Saudi Arabia's material certification protocols for pressure equipment are disqualifying non-compliant Asian suppliers, creating procurement windows for certified OEMs.
- Heavy Crude Viscosity Tolerance:Screw pump architectures are capturing transfer applications in Kuwait's Ratqa field where multiphase fluid handling exceeds centrifugal pump operational envelopes.
- Eastern Province Concentration:Aramco's megaproject pipeline sustains continuous demand for metering pumps across downstream processing clusters near Jubail Industrial City.
Market Restraints
- Specialized Alloy Input Volatility:Duplex stainless steel price fluctuations for pump housings compress margin predictability for manufacturers serving offshore platform specifications.
- European Component Concentration:High-precision gear and lobe pump element sourcing remains concentrated in German and Italian precision machining suppliers, exposing lead time vulnerability.
- Diaphragm Material Temperature Limits:PTFE and elastomer diaphragm degradation above 150°C restricts chemical processing applications in high-temperature hydrocarbon service.
Strategic Opportunities
- Nigeria Delta Underpenetration:Onshore marginal field operators present untapped demand for portable progressive cavity pump skids in crude evacuation applications.
- UAE Carbon Intensity Benchmarking:Emirates Authority for Standardization and Metrology draft procurement criteria will redirect capital toward efficiency-optimized electric drive architectures.
- Predictive Maintenance Convergence:Vibration analytics platforms fused with pump OEM service networks are enabling subscription revenue models displacing transactional spare parts sales.
Industry Challenges
- Pressure Equipment Certification Timelines:ESMA conformity assessment delays in the UAE extend qualification periods for new pump models by four to six months.
- Multiphase Flow Simulation Expertise:Computational fluid dynamics competency gaps among local engineering firms complicate custom pump specification for heavy oil applications.
- Legacy Control System Integration:Digital monitoring retrofits face interoperability friction with existing SCADA infrastructure at mature Saudi processing facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Positive Displacement Pumps Market |
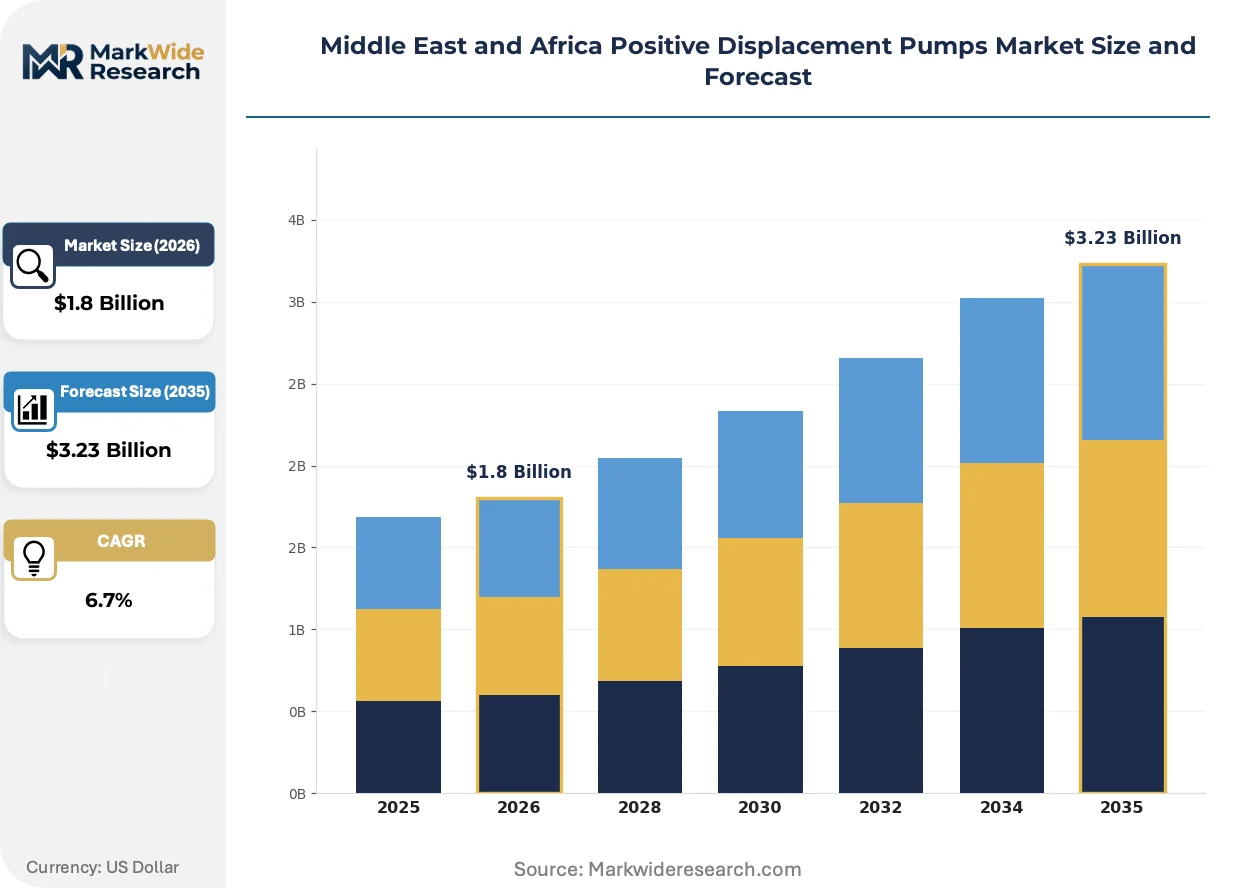
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gear Pumps, Diaphragm Pumps, Screw Pumps, Peristaltic Pumps End User: Oil & Gas, Water Treatment, Food & Beverage, Chemical Processing Application: Hydraulic System, Wastewater Treatment, Transfer, Metering Technology: Electric, Pneumatic, Hydraulic, Manual |
| Companies Covered | Flowserve Corporation, Grundfos Holding A/S, Schlumberger Limited, Dover Corporation, Ingersoll Rand Inc., Sulzer Ltd., Xylem Inc., Alfa Laval AB, KSB SE & Co. KGaA, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Positive Displacement Pumps Market Shifts & Advancements
Digitalization of rotating equipment fleets is compressing maintenance intervals and unbundling service revenue from hardware sales across Middle Eastern hydrocarbon operations.
Smart pump systems with embedded vibration and temperature sensors are integrating cloud-based analytics platforms to enable condition-based maintenance. Saudi Aramco's downstream operators are deploying these architectures across refinery circulation loops. This convergence is integrating predictive algorithms directly into procurement specifications, disqualifying non-connected pump offerings from tender shortlists.
SASO and ESMA alignment with ISO 13709 centrifugal pump standards is tightening material traceability requirements for positive displacement equipment. The industrial consequence is mandatory third-party inspection of casting and forging documentation for all pressure-retaining components. Downstream chemical processors in Jubail and Ruwais are absorbing compliance costs through extended supplier qualification timelines.
Service contract unbundling is fragmenting traditional OEM revenue streams across the Gulf. Operators are separating predictive maintenance subscriptions from original equipment purchases, engaging independent service providers for fleet monitoring. This behavioral shift is most visible in UAE water treatment facilities where Grundfos and local competitors now compete purely on monitoring platform functionality rather than pump unit pricing.
Middle East and Africa Positive Displacement Pumps Market Segmentation
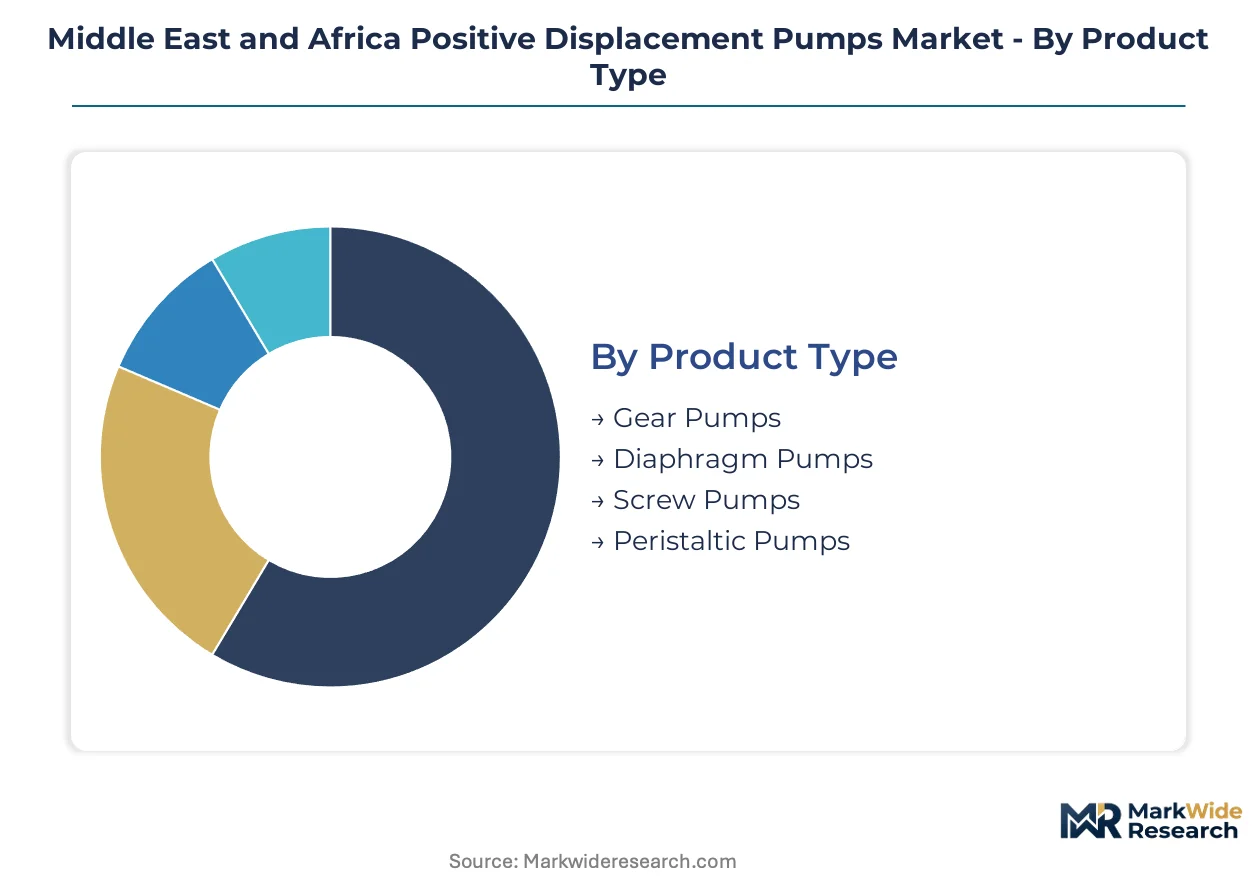
Positive displacement pump specifications diverge sharply across Middle East and Africa hydrocarbon, water, and chemical processing installations. Procurement patterns in this market track fluid viscosity demands, pressure ratings, and regional regulatory compliance burdens rather than uniform technology preferences.
Product Type:
Technical specifications around cavity geometry and sealing architecture differentiate competitive positioning across upstream and downstream applications.
- Diaphragm Pumps:Leak-free containment architectures isolate aggressive reagents through elastomer or PTFE membrane separation. Chemical processors across Jubail Industrial City specify these units for corrosive duty cycles where mechanical seal failure risks exceed containment budgets.
- Screw Pumps:Intermeshing helical rotors handle viscosity ranges from light distillates to heavy crude above 1000 cSt without shear degradation. Kuwait's Ratqa field operators deploy these for multiphase transfer where centrifugal pump operational envelopes collapse.
- Gear Pumps:Precision-machined meshing elements deliver pulseless flow for lubrication and hydraulic power units at pressures below 3000 psi.
- Peristaltic Pumps:Hose compression mechanisms isolate fluid from mechanical components, suiting abrasive slurry handling in mining and wastewater pre-treatment.
Diaphragm pumps lead on scale through chemical processing standardization; screw pumps lead on momentum through heavy crude recovery expansion.
End User:
Capital deployment intensity and equipment replacement cycles concentrate demand in hydrocarbon extraction and processing clusters.
- Oil & Gas:Upstream artificial lift, surface transfer, and downstream hydrocracking circulation sustain procurement volumes across Saudi Arabia's Eastern Province. Aramco's megaproject pipeline compresses replacement timelines for high-pressure reciprocating and progressive cavity systems.
- Water Treatment:Desalination brine recirculation and municipal distribution networks drive demand for corrosion-resistant metering and transfer architectures. UAE operators specify smart monitoring integration for unplanned downtime reduction.
- Chemical Processing:Aggressive reagent handling and precise additive injection requirements favor diaphragm and metering pump specifications.
- Food & Beverage:Hygienic design standards and CIP compatibility constrain material selection to 316L stainless and FDA-compliant elastomers.
Oil and gas commands absolute procurement volume; water treatment is expanding most quickly through desalination capacity additions.
Application:
Operational duty cycles and precision requirements segment specifications across continuous versus intermittent service profiles.
- Transfer:Bulk fluid movement between storage, processing, and loading facilities dominates unit deployment across hydrocarbon value chains. Heavy crude viscosity tolerance requirements favor positive displacement architectures over centrifugal alternatives in Kuwait and Saudi heavy oil fields.
- Metering:Precision additive injection and chemical dosing demand pulsation dampening and flow control integration. Downstream processors specify these for catalyst injection and corrosion inhibitor programs.
- Hydraulic System:Power transmission circuits require pressure-compensated flow delivery for drilling rig and construction equipment actuation.
- Wastewater Treatment:Sludge handling and chemical precipitation processes deploy peristaltic and progressive cavity units for abrasive and fibrous media.
Transfer applications anchor installed base scale; metering commands premium pricing through precision engineering requirements.
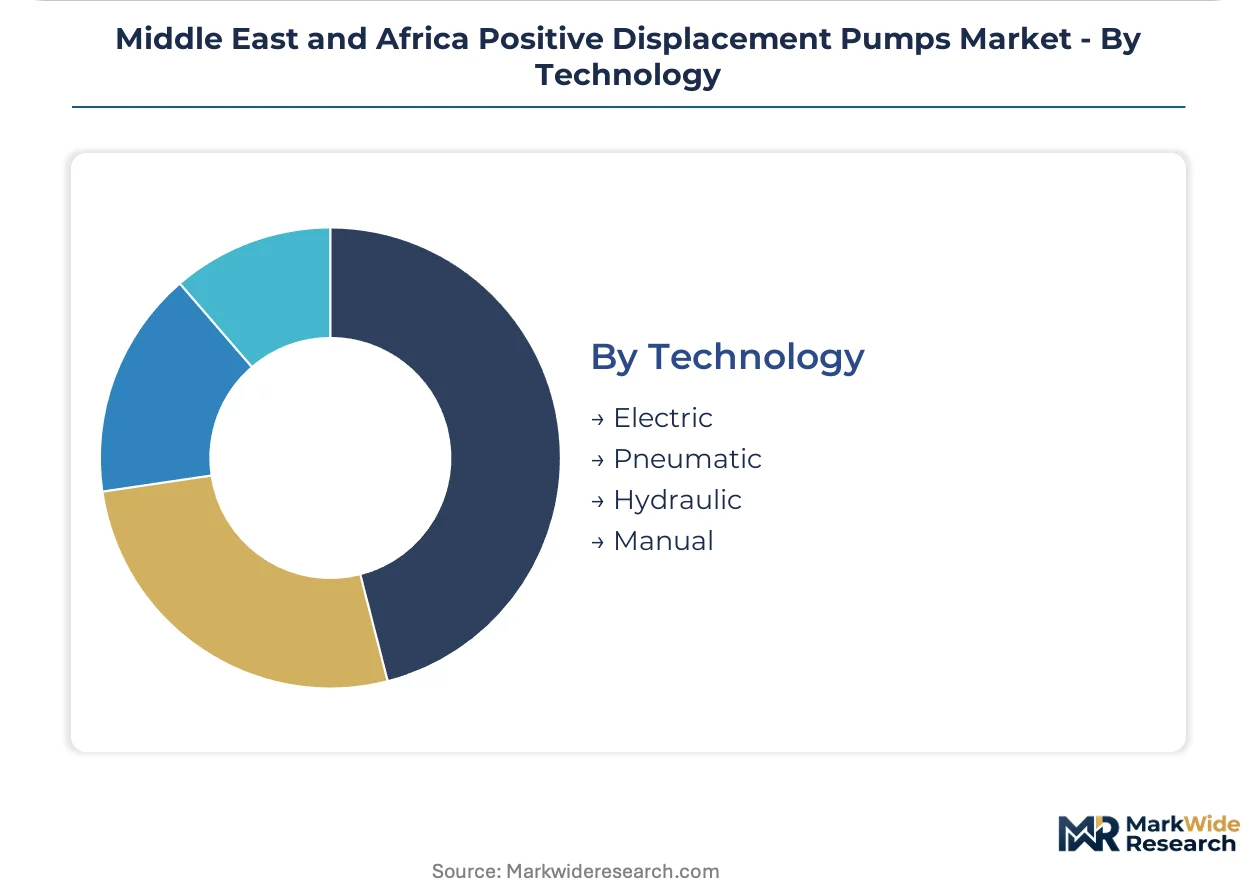
Technology:
Energy efficiency mandates and hazardous area classifications drive technology selection across onshore and offshore installations.
- Electric:Variable frequency drive integration and IE4 motor efficiency standards dominate new procurement across UAE and Saudi downstream facilities. ESMA draft procurement criteria redirect capital toward efficiency-optimized drive architectures.
- Pneumatic:Explosion-proof operation without electrical infrastructure sustains demand for offshore platform and Zone 1 hazardous area deployment.
- Hydraulic:High power density and stall tolerance suit mobile equipment and subsea applications where electric motor sizing constraints apply.
- Manual:Backup operation and remote location serviceability persist in marginal field and maintenance bypass applications.
Electric technology leads on scale through efficiency mandate compliance; pneumatic retains defensive positioning in offshore specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory divergence between Gulf Cooperation Council states and sub-Saharan markets creates compliance-cost arbitrage that redirects procurement toward certified suppliers in high-standard jurisdictions. Equipment qualification timelines vary by four to six months across national borders, reshaping vendor selection criteria for multinational operators.
Saudi Arabia
Aramco's megaproject pipeline sustains procurement volumes for high-pressure metering and transfer applications across the Eastern Province. SASO technical regulations enforce material certification protocols that disqualify non-compliant Asian suppliers from tender shortlists. Jubail Industrial City hosts downstream processing clusters where compliance-driven replacement cycles compress equipment depreciation timelines.
United Arab Emirates
ESMA conformity schemes accelerate procurement criteria shifts toward efficiency-optimized electric drive architectures in downstream facilities. Dubai and Abu Dhabi desalination operators specify smart monitoring integration for unplanned downtime reduction. Ruwais chemical processing complexes absorb extended supplier qualification timelines through mandatory third-party inspection requirements.
Kuwait
Ratqa field operators deploy screw pump architectures for multiphase fluid handling where centrifugal pump operational envelopes collapse. Heavy crude viscosity tolerance requirements favor positive displacement specifications in northern oilfield developments. The country's national petroleum company sustains capital deployment for artificial lift system modernization.
South Africa
NRCS pressure equipment standards shape import qualification timelines for European and Asian manufacturers serving mining and petrochemical applications. Johannesburg and Durban industrial corridors concentrate demand for abrasive slurry handling in platinum and gold extraction operations. Local engineering firms face computational fluid dynamics competency gaps that complicate custom pump specification.
Nigeria
Onshore marginal field operators present demand for portable progressive cavity pump skids in crude evacuation applications across the Niger Delta. Regulatory fragmentation between federal and state authorities extends equipment certification timelines for international suppliers. Lagos and Port Harcourt serve as procurement hubs where independent service providers compete with OEM-affiliated distributors.
Middle East and Africa Positive Displacement Pumps Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated project execution models commanding premium positioning in upstream hydrocarbon applications. The vendor base organizes around three strategic archetypes: full-service OEMs with regional service hub networks, digital platform specialists monetizing predictive maintenance subscriptions, and precision component fabricators supplying gear and lobe pump elements. Competitive moves concentrate on predictive maintenance convergence through vibration analytics integration and service contract unbundling that fragments traditional revenue streams.
Within the full-service OEM tier, Flowserve Corporation, Grundfos Holding A/S, and Schlumberger Limited occupy positions that exemplify divergent strategic vectors. Flowserve leverages its regional service hub network to capture recurring revenue from rotating equipment fleets. Grundfos anchors its market presence through digital monitoring platforms that reduce unplanned downtime. Schlumberger dominates artificial lift and surface pumping packages through integrated project execution models across Saudi Arabia and the UAE. These three represent the competitive spectrum from hardware-centric to subscription-based revenue architectures.
| Leading Market Players |
|---|
| Flowserve Corporation |
| Grundfos Holding A/S |
| Schlumberger Limited |
| Dover Corporation |
| Ingersoll Rand Inc. |
| Sulzer Ltd. |
| Xylem Inc. |
| Alfa Laval AB |
| KSB SE & Co. KGaA |
| Others |
Supply & Pricing Matrix
Sovereign-backed producers and family-owned mid-caps across Saudi Arabia and the UAE anchor supply behavior through long-term offtake commitments, while pricing discipline tightens around ESMA and SASO certification tiers that filter non-compliant competitors from tender shortlists. Procurement officers at Aramco and ADNOC affiliates increasingly bundle predictive maintenance subscriptions into capital expenditure decisions, compressing pure hardware margins while elevating lifecycle service pricing.
Pricing Analysis
Capacity additions in the UAE and Saudi Arabia are reshaping price floors for electric-drive positive displacement pumps as local assembly operations reduce import duty burdens on certified OEMs. Pricing stratifies across premium certified tiers, standard compliance-grade units, and economy alternatives lacking regional conformity marks, with differentiation driven by material traceability documentation and aftermarket service bundling. Cost compression in the economy tier intensifies because Asian manufacturers absorb SASO inspection fees to retain procurement access. National oil companies exhibit lowest price sensitivity due to total cost of ownership mandates, while marginal field operators in Nigeria and South Africa prioritize upfront capital minimization.
Supply Chain Analysis
Regional distribution centers in Dubai's Jebel Ali Free Zone and Dammam's King Abdulaziz Port anchor hub-and-spoke patterns serving Eastern Province hydrocarbon clusters and West African offshore installations. Manufacturing concentrates in Germany, Italy, and China for precision-machined gear and lobe pump elements, while duplex stainless steel castings draw from specialized foundries in Sweden and Japan. Single-source vulnerability persists for high-pressure metering pump heads rated above 10,000 psi, where only two European suppliers maintain ESMA-approved quality systems. Distribution runs through OEM-affiliated service hubs and independent aftermarket distributors competing on spare parts availability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa positive displacement pumps market functions as a regulatory compounder, where SASO and ESMA technical regulations accelerate compliance-driven replacement cycles and disqualify uncertified suppliers from national oil company procurement lists.
For Market Incumbents: Deploy predictive maintenance platform integration to capture recurring revenue from Aramco and ADNOC rotating equipment fleets. Consolidate position by acquiring regional service providers in Nigeria and South Africa where independent competitors fragment aftermarket capture. Certification investment in SASO and NRCS pressure equipment protocols defends against emerging Asian entrants exploiting price gaps in economy-tier specifications. For New Entrants and Emerging Players: Enter via portable progressive cavity pump skids targeting Nigeria's Niger Delta marginal field operators, where regulatory fragmentation delays incumbent qualification timelines. White-space concentrates in sub-Saharan mining slurry applications and UAE desalination smart monitoring retrofits. Go-to-market leverage rests on vibration analytics partnerships with existing industrial automation distributors. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier European component fabricators lacking direct Gulf service presence but holding precision machining capabilities applicable to heavy crude viscosity tolerance requirements. Long-term viability hinges on carbon intensity benchmarking integration into procurement criteria across the analysis window. Monitor ESMA draft efficiency mandates as the signal indicating accelerated capital redirection toward electric drive architectures.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Investment in SASO and ESMA Protocols | Qualifies suppliers for Aramco megaproject procurement and filters Asian price competitors. |
| Predictive Maintenance Platform Integration | Enables Grundfos and Flowserve subscription models displacing transactional spare parts sales. |
| Regional Service Hub Expansion | Compresses response times for Saudi Eastern Province downstream processing clusters. |
| Backward Integration into Duplex Stainless Castings | Reduces margin exposure to Swedish and Japanese foundry price volatility. |
| Joint Venture with Local Engineering Firms | Addresses CFD competency gaps complicating custom pump specification in South Africa. |
Research Methodology
Coverage spans the Gulf Cooperation Council, sub-Saharan Africa, and North Africa, with primary inputs from each region combining interviews with maintenance directors at Saudi downstream facilities, OEM procurement teams in the UAE, aftermarket service heads at Flowserve and Grundfos regional hubs, and plant engineers at Kuwait's Ratqa field operations. Secondary validation drew from customs and trade data, SASO and ESMA regulatory filings, SEC 10-K disclosures from listed pump manufacturers, and hydrocarbon project development databases. Bottom-up unit demand estimates triangulated against top-down capital expenditure projections from national oil companies.
Rate-of-change decomposition across the projection horizon modeled volume and value trajectories through segmentation across product type, end-use industry, application duty cycle, and technology architecture, with additional granularity on regional regulatory cluster effects. CAGRs derived from regression analysis against upstream capital deployment intensity and downstream replacement cycle compression. Industry-specific forecast inputs included Aramco megaproject pipeline phasing and ESMA draft procurement criteria evolution.
Inputs from primary stakeholder interviews and regulatory authority publications were available through the study window; gaps in real-time project delay announcements and commodity price volatility introduce uncertainty bands around near-term capital expenditure assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Membrane Pump Market
Pumps and Control Devices
Solar Pump Inverter Market
Pumps and Control Devices
Single-Use Pump Market
Pumps and Control Devices
Chemical Metering Pumps Market
Pumps and Control Devices
Fuel Transfer Pump Market
Pumps and Control Devices
Wind Powered Water Pumps Market
Pumps and Control Devices
Global Piston Pumps Market
Pumps and Control Devices
Plunger Pumps Market
Pumps and Control Devices
Jetting Pumps Market
Pumps and Control Devices
High Precision Microfluidic Pump Market
Pumps and Control Devices
Global Pumps Market
Pumps and Control Devices
Europe Asia Submerged Pump Market
Pumps and Control Devices
Asia Pacific Side Channel Pumps Market
Pumps and Control Devices
Vertical Immersion Pumps Market
Pumps and Control Devices
Multistage Pump Market
Pumps and Control Devices
Vertical Turbine Pumps Market