
 Global Single Use Bioprocessing Probes and Sensors Market | 2026-2036
Global Single Use Bioprocessing Probes and Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Global Single Use Bioprocessing Probes and Sensors Market Intelligence
A multi-source procurement model for individual components is consolidating toward integrated, pre-sterilized sensor assemblies from fewer strategic suppliers. This shift favors large-scale providers who offer comprehensive portfolios and can guarantee supply chain stability. Thermo Fisher Scientific leverages its extensive bioprocess solutions to offer bundled systems. Sartorius AG specializes in integrated single-use platforms, while Danaher Corporation competes through its life sciences subsidiaries with a focus on filtration integration.
Single use bioprocessing probes and sensors are disposable devices designed for real-time monitoring of critical process parameters inside a bioreactor. These pre-calibrated, gamma-sterilized instruments eliminate cleaning and validation between batches, reducing contamination risks. While pH probes and temperature sensors represent mature product types, optical sensors for biomass and viability are gaining share rapidly. Biopharmaceutical companies constitute the largest end-user base, but contract manufacturing organizations represent the fastest-growing segment due to outsourcing trends.
Regulatory frameworks from the United States' FDA and Europe's EMA heavily influence product design and validation requirements for extractables and leachables. These agencies' emphasis on Process Analytical Technology (PAT) and data integrity under GMP guidelines drives the need for reliable, single-use monitoring. The next frontier for vendors involves integrating sensor data streams into advanced process control and predictive analytics platforms for fully automated biomanufacturing.
Market Dynamics
The imperative for continuous biomanufacturing, heavily endorsed by regulatory bodies like the FDA through its Process Analytical Technology initiative, is the central force shaping the market. This push compels the adoption of real-time monitoring solutions to ensure process consistency and product quality.
Growth Catalysts
- Optical Sensor Advancement:The development of non-invasive optical sensors for real-time biomass and cell viability measurement provides superior process control, accelerating their adoption in monoclonal antibody and vaccine production workflows.
- Regulatory Endorsement of PAT:The FDA's Process Analytical Technology (PAT) framework encourages the use of in-line sensors to build quality into the manufacturing process, directly stimulating demand for validated single-use probes.
- Biologic Drug Pipeline Expansion:A burgeoning pipeline of monoclonal antibodies and cell therapies, particularly within biopharma clusters in the United States and Ireland, creates sustained demand for single-use systems to enable flexible, multi-product manufacturing.
Market Restraints
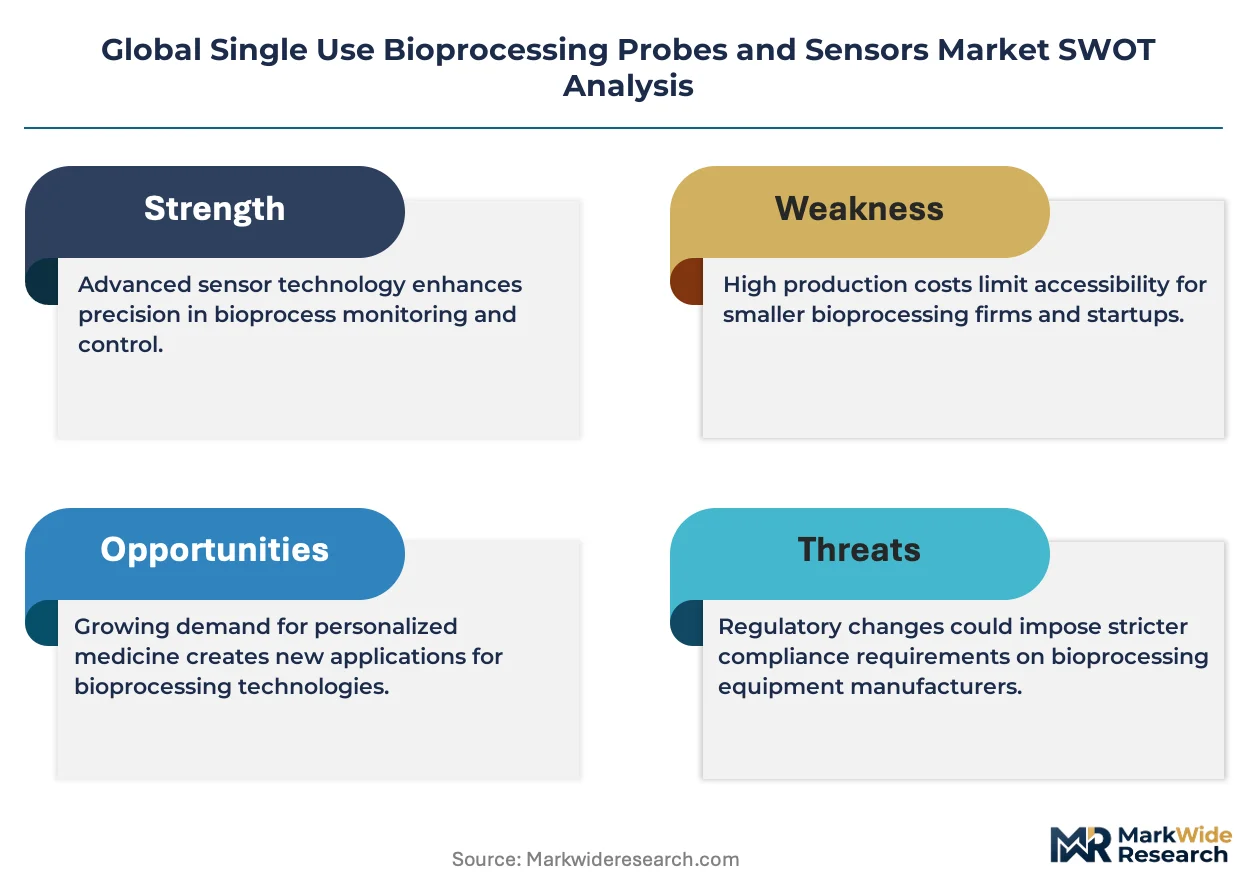
- Extractables and Leachables Concerns:The potential for materials from single-use sensors to leach into the bioprocess stream creates a significant regulatory and validation burden, requiring extensive testing that can delay product adoption.
- Supplier Consolidation Risk:A procurement model consolidating toward a few strategic suppliers of integrated assemblies creates dependency, exposing end-users to supply chain disruption risk if a major provider experiences production issues.
- Sensor Calibration and Drift:Despite being pre-calibrated, some single-use sensors can experience drift during long-duration continuous bioprocesses, posing a risk to data accuracy and batch-to-batch consistency without secondary verification methods.
Strategic Opportunities
- AI and Predictive Analytics Integration:The convergence of sensor data streams with artificial intelligence platforms offers an opportunity to develop predictive models for process optimization, failure detection, and automated control in biomanufacturing.
- Cell and Gene Therapy Applications:The rapid growth of autologous and allogeneic cell therapies presents a new frontier for single-use sensors, which are critical for monitoring small-batch, patient-specific manufacturing processes.
- Standardization Initiatives:Industry-led efforts to standardize sensor connectors, data communication protocols, and material qualifications could unlock significant growth by simplifying integration and reducing validation costs for end-users.
Industry Challenges
- Data Integrity and Cybersecurity:Ensuring the integrity and security of data generated by a high volume of disposable sensors, in compliance with GMP guidelines, presents a significant operational challenge for biopharmaceutical companies.
- Lack of Universal Connectivity Standards:The absence of standardized physical connectors and data output formats across different vendor platforms complicates the integration of sensors into bioreactors and control systems, creating friction for users.
- Sustainable Waste Management:The increasing volume of plastic waste generated by single-use systems poses a sustainability challenge, pressuring vendors and end-users to develop viable recycling or disposal pathways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Single Use Bioprocessing Probes and Sensors Market |
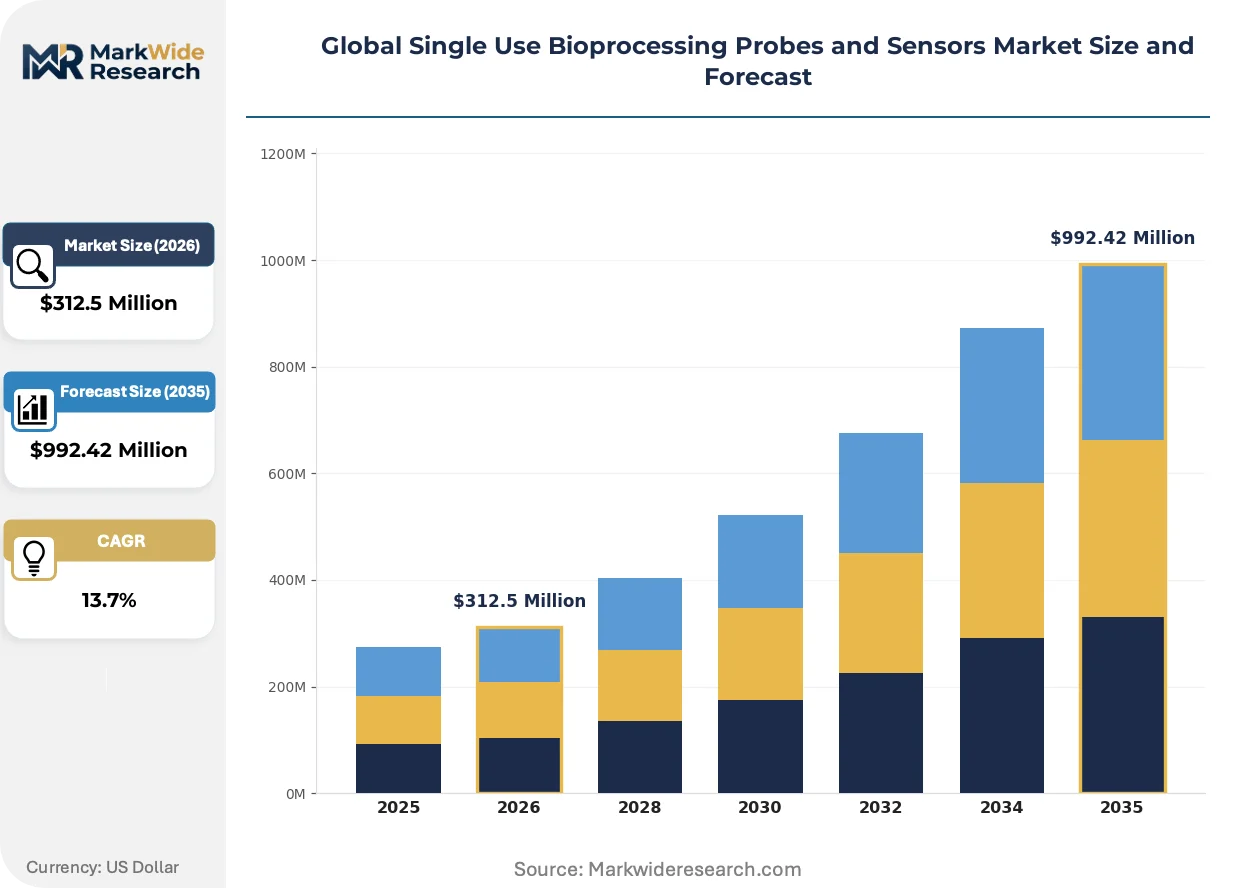
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $992.42 Million |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: pH Probes, Conductivity Sensors, Optical Sensors, Temperature Sensors End User: Biopharmaceutical Companies, Academic Research Institutions, Contract Manufacturing Organizations, Quality Control Labs Technology: Electrochemical, Optical, Spectroscopic, Thermal Application: Process Monitoring, Quality Assurance, Research & Development, Compliance Testing |
| Companies Covered | PreSens Precision Sensing, Parker Hannifin, Thermo Fisher Scientific, Danaher Corporation, Broadley-James, Sartorius AG, Mettler-Toledo, Polestar Technologies, Hamilton Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Single Use Bioprocessing Probes and Sensors Market Strategic Shifts & Innovations
The evolution of single-use sensors is defined by a push toward greater integration and intelligence. This movement transforms disposable probes from passive monitoring devices into active components within automated, data-driven biomanufacturing ecosystems, aligning with the industry's continuous processing goals.
Integrated sensor assemblies are a key product evolution. These pre-sterilized, plug-and-play units combine multiple sensors, such as pH, dissolved oxygen, and temperature, into a single disposable component. Contract manufacturing organizations adopt these systems to accelerate process development and tech transfer between clients. This integration of pre-calibrated sensors into a single disposable unit is modularizing process analytical technology deployment within facilities.
Regulatory frameworks from Europe's EMA, mirroring the FDA's stance, promote Quality by Design (QbD) principles. This guidance necessitates a deep, data-driven understanding of manufacturing processes, which single-use sensors directly facilitate through real-time data acquisition. Biologics producers, especially those in European hubs like Ireland and Switzerland, are consequently compelled to embed advanced monitoring technologies to meet regulatory expectations for process control and validation.
A clear behavioral shift is visible in how biopharmaceutical firms acquire these technologies. The practice of sourcing individual sensor components from various specialized vendors is yielding to a preference for single-source procurement of complete, pre-validated assemblies. This change disrupts the business model of component-level distributors, favoring large bioprocess suppliers. This trend is most apparent in the United States, where large drug manufacturers prioritize supply chain simplification and reduced validation burdens.
Global Single Use Bioprocessing Probes and Sensors Market Segmentation
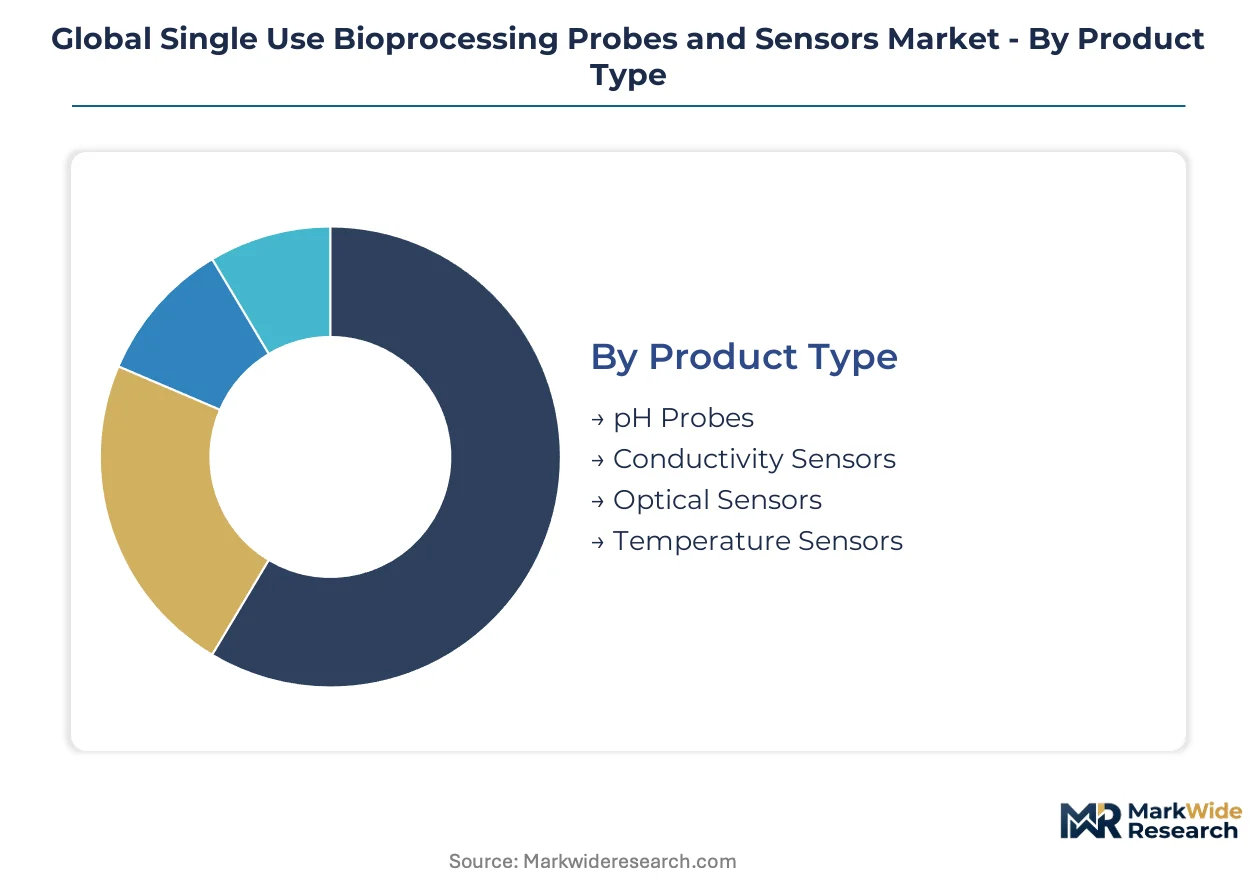
Understanding the varied segments within the single use bioprocessing probes and sensors market allows stakeholders to identify specific growth vectors and address distinct user requirements. This granular view highlights where innovation and investment are most impactful for biopharmaceutical manufacturing.
Product Type:
Purchasing decisions for single-use sensors often hinge on the specific process parameter requiring real-time measurement and the necessary level of data precision.
- Optical Sensors:These non-invasive sensors measure biomass, cell viability, and dissolved oxygen without direct contact with the bioprocess fluid. Their advancement offers superior process control for complex monoclonal antibody and vaccine production workflows.
- pH Probes:Essential for maintaining optimal cell culture conditions, these pre-calibrated, gamma-sterilized devices monitor acidity and alkalinity within bioreactors. They eliminate cleaning and validation steps, reducing contamination risks in biopharmaceutical operations.
- Conductivity Sensors:These sensors measure the ionic concentration of solutions, critical for media preparation and monitoring buffer exchanges during downstream processing. They ensure consistent quality control in biomanufacturing.
- Temperature Sensors:Integral for maintaining optimal reaction temperatures, these disposable sensors provide continuous thermal monitoring within single-use bioreactors. They are fundamental for process consistency across various bioprocesses.
pH Probes lead on scale; Optical Sensors lead on momentum.
End User:
The operational models and strategic priorities of different end-user groups dictate their specific demand for single-use bioprocessing sensors.
- Biopharmaceutical Companies:These entities represent the largest consumer base, integrating single-use sensors into their large-scale production of biologics, particularly for monoclonal antibodies. Their focus remains on process efficiency, regulatory compliance, and reducing cross-contamination risks.
- Contract Manufacturing Organizations:CMOs adopt these systems to accelerate process development and facilitate rapid tech transfer between diverse client projects. Their need for flexibility and quick turnaround times makes single-use technology highly advantageous.
- Academic Research Institutions:These institutions utilize single-use sensors for early-stage research and development, often in smaller-scale bioreactors for proof-of-concept studies. They value ease of use and reduced cleaning protocols.
- Quality Control Labs:Quality control laboratories employ single-use sensors for in-process testing and final product release, ensuring adherence to strict regulatory guidelines. They prioritize data integrity and reliable validation.
Biopharmaceutical Companies represent the largest volume; Contract Manufacturing Organizations are expanding most quickly.
Technology:
The underlying technological principle of the sensor directly influences its measurement capabilities, accuracy, and suitability for specific bioprocessing applications.
- Optical:Optical technology involves non-invasive methods like fluorescence and absorbance to measure parameters such as dissolved oxygen, CO2, biomass, and cell viability. This approach minimizes contamination risks and provides real-time data for advanced process control.
- Electrochemical:Electrochemical sensors, primarily used for pH and conductivity measurements, rely on changes in electrical potential or current. These are mature technologies, offering robust and reliable performance for fundamental process monitoring in bioreactors.
- Spectroscopic:Spectroscopic methods, including Near-Infrared (NIR) and Raman spectroscopy, provide comprehensive compositional analysis of bioprocess fluids. These technologies offer deeper insights into complex biological reactions and product quality attributes.
- Thermal:Thermal sensors measure temperature using thermistors or thermocouples, which are critical for maintaining precise environmental conditions in bioprocesses. They offer direct and accurate temperature readings within single-use systems.
Electrochemical technology maintains broad utility; Optical solutions are experiencing the steepest expansion trajectory.
Application:
The specific application of single-use sensors within the bioprocessing workflow dictates the required sensor type, integration, and data output for optimal utility.
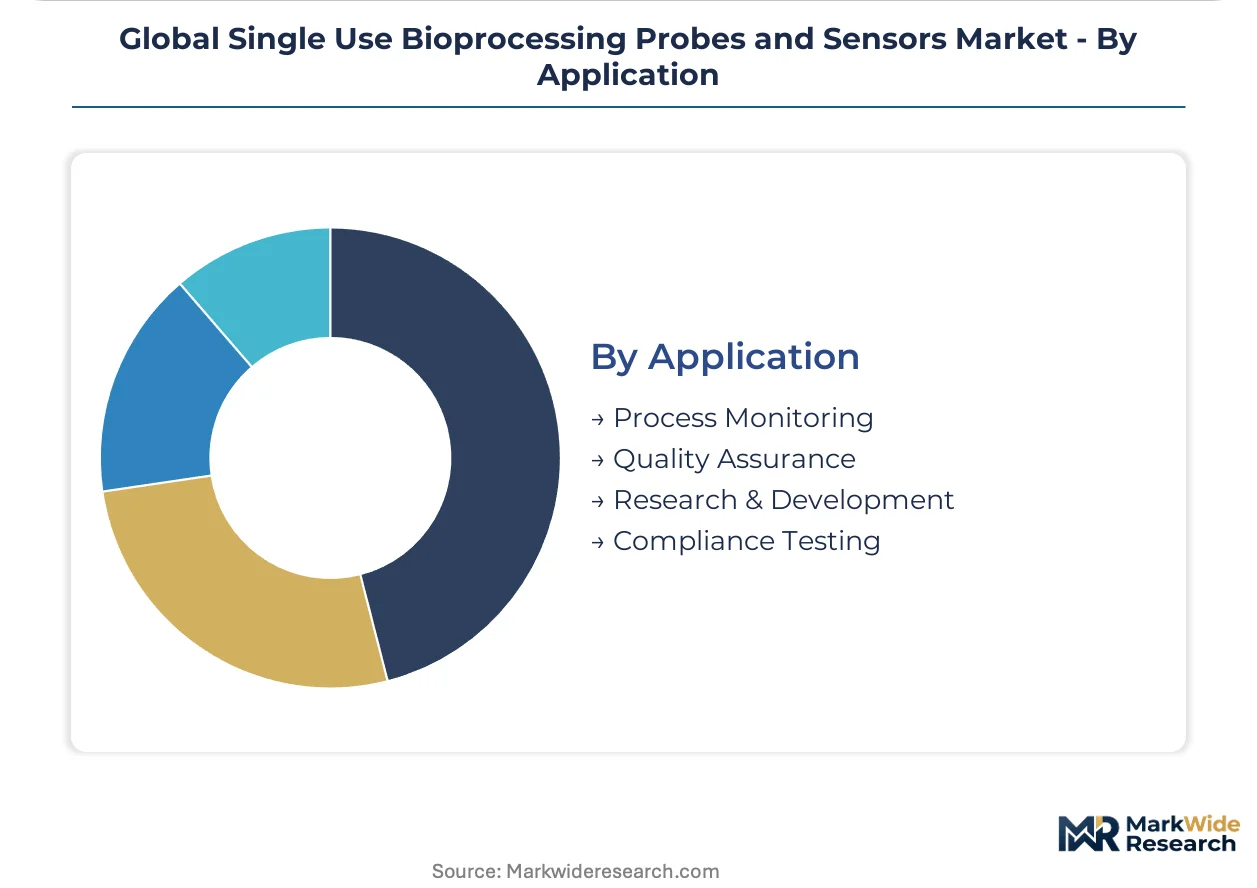
- Process Monitoring:This application involves real-time tracking of critical process parameters like pH, dissolved oxygen, and temperature to ensure consistent operating conditions. It is essential for continuous biomanufacturing endorsed by the FDA's PAT initiative.
- Quality Assurance:Single-use sensors contribute to quality assurance by providing continuous data for product consistency and adherence to regulatory standards. This is vital for meeting GMP guidelines from agencies like the EMA and FDA.
- Research & Development:In R&D, these sensors facilitate rapid experimentation and process optimization in early-stage drug discovery and development. They enable quick iteration and scale-up studies for new biologics.
- Compliance Testing:Sensors are used for verifying process parameters against regulatory requirements, supporting validation efforts and documentation for market approval. This ensures that biopharmaceutical products meet stringent safety and efficacy standards.
Process Monitoring drives core demand; Quality Assurance applications are gaining share rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory scrutiny often creates a cost-of-compliance gap, compelling biopharmaceutical production to migrate toward regions with robust but adaptable frameworks. This dynamic influences where single-use bioprocessing probes and sensors find the strongest demand and fastest integration. Market growth concentrates in established biopharma hubs that prioritize both innovation and stringent quality control.
United States
The United States drives demand for single-use sensors through its extensive biopharmaceutical pipeline, particularly in monoclonal antibodies and cell therapies. The FDA's Process Analytical Technology (PAT) initiative strongly encourages real-time monitoring, embedding these sensors into manufacturing workflows. Major biopharma clusters in Boston, Massachusetts, and the San Francisco Bay Area actively integrate advanced single-use systems for process optimization.
Germany
German biopharmaceutical manufacturers increasingly adopt single-use sensors to enhance efficiency and maintain high quality standards in biologics production. The EMA's emphasis on Quality by Design (QbD) principles necessitates comprehensive process understanding, which these sensors facilitate. Key bioprocessing hubs in Bavaria and North Rhine-Westphalia are at the forefront of implementing integrated sensor assemblies for advanced biomanufacturing.
Ireland
Ireland's strong biopharmaceutical manufacturing sector, particularly for large-scale biologics, fuels significant demand for single-use bioprocessing probes and sensors. The European Medicines Agency (EMA) guidelines for Good Manufacturing Practice (GMP) drive the need for validated, real-time process monitoring solutions. Dublin and Cork host numerous biopharma plants that prioritize single-use technologies for rapid tech transfer and contamination control.
Switzerland
Swiss biopharmaceutical companies, known for high-value biologics and precision manufacturing, are early adopters of advanced single-use sensor technologies. Swissmedic, the national regulatory authority, aligns with EMA standards, promoting stringent process control and data integrity. The Basel region, a prominent pharmaceutical cluster, sees continuous investment in integrated single-use platforms for both R&D and commercial production.
Japan
Japan's growing biopharmaceutical industry, with a focus on regenerative medicine and novel biologics, necessitates robust single-use sensor adoption. The Pharmaceuticals and Medical Devices Agency (PMDA) promotes advanced manufacturing techniques that benefit from real-time process analytics. Bioprocessing facilities in the Kanto region, including Tokyo, increasingly implement these sensors to streamline operations and ensure product quality.
Global Single Use Bioprocessing Probes and Sensors Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue specialized optical sensing and data integration capabilities for next-generation bioprocessing. The market structure exhibits a tiered consolidation, with a few large players offering comprehensive portfolios alongside specialized innovators. Dominant competitive moves include strategic partnerships for technology integration and continuous portfolio diversification to meet evolving regulatory demands.
On the premium-tier vector, Thermo Fisher Scientific exemplifies a broad solutions provider, leveraging its extensive bioprocess offerings for bundled systems. Sartorius AG, a Germany-based company, sits within the integrated single-use platforms archetype, emphasizing end-to-end bioprocessing solutions. Danaher Corporation, through its life sciences subsidiaries, represents a diversified player with a focus on filtration integration and complementary bioprocess technologies.
| Leading Market Players |
|---|
| PreSens Precision Sensing |
| Parker Hannifin |
| Thermo Fisher Scientific |
| Danaher Corporation |
| Broadley-James |
| Sartorius AG |
| Mettler-Toledo |
| Polestar Technologies |
| Hamilton Company |
| Others |
Cost & Logistics Intelligence
Performance-based sensor differentiation between advanced optical sensors and commodity pH probes shapes both pricing power and supply chain resilience. This bifurcation reflects varying R&D investments and specialized manufacturing capabilities across global biopharma hubs.
Pricing Analysis
Distributor margin structures reflect the complexity and validation requirements of single-use sensors. Contract-based long-term offtake agreements dominate for integrated assemblies, while per-unit transactional models apply to individual components. Price differentiation stems from PAT-validated quality grades and established brand premiums, alongside customization levels for specific bioreactor integrations. Pricing softness emerges from supplier consolidation, as large providers bundle solutions. Contract Manufacturing Organizations exhibit higher price sensitivity compared to large biopharmaceutical companies.
Supply Chain Analysis
Certification and qualification gating by regulatory bodies like the FDA and EMA are critical supply chain bottlenecks. Supply concentrates in biopharma manufacturing hubs including the United States, Germany, and Ireland, where specialized plastics and microelectronics are sourced. Single-source vulnerability for integrated, pre-sterilized assemblies poses a significant risk if a major provider experiences production issues. Distribution runs primarily direct-to-manufacturer for large biopharmaceutical companies, while specialized distributors serve Contract Manufacturing Organizations and academic research institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with the FDA's Process Analytical Technology (PAT) initiative consistently driving demand for real-time monitoring solutions. Regulatory emphasis on data integrity and process control underpins sustained investment in single-use sensors.
For Market Incumbents:Extend comprehensive portfolios to include advanced optical sensors and predictive analytics integration capabilities. This defends against emerging entrants specializing in niche sensing technologies and mitigates margin pressure from component-level suppliers. Strategic partnerships for data stream integration into advanced process control platforms offer significant leverage. Invest in R&D for next-generation sensor materials to address extractables and leachables concerns.
For New Entrants and Emerging Players:Autologous cell therapy developers represent an underserved buyer archetype seeking highly specialized, small-batch monitoring solutions. Target Contract Manufacturing Organizations focused on cell and gene therapy applications, which require flexible and patient-specific bioprocessing. Focus on developing standardized sensor connectors and data protocols to simplify integration for these users. A value proposition centered on rapid validation and ease of use will resonate strongly.
For Investors and Strategic Acquirers:Consolidation pressure builds where comprehensive, pre-validated single-use systems become industry standard. This market is essential for biomanufacturing evolution over the next decade, driven by continuous processing and advanced analytics. Seek acquisition targets specializing in optical sensor technology or data integration platforms for predictive analytics. The signal to watch is the increasing regulatory encouragement for automated, AI-driven process control in biopharmaceutical production.
| Strategic Initiative | Industry Significance |
|---|---|
| Portfolio Diversification | Broadens market reach for Thermo Fisher Scientific by offering complete bioprocess solutions. |
| Standardization Initiatives | Simplifies integration for Contract Manufacturing Organizations, reducing validation burdens. |
| AI/Predictive Analytics Integration | Enhances process optimization and failure detection for biopharmaceutical companies. |
| Material Science R&D | Addresses extractables and leachables concerns for FDA and EMA regulatory compliance. |
| Geographic Manufacturing Expansion | Secures supply chain resilience for Sartorius AG in key biopharma hubs like Ireland. |
Research Approach
Bottom-up biopharmaceutical end-user modeling reconciled against top-down single-use sensor supply-side tracking forms the analytical core of this study. Primary interviews with bioprocess engineers, regulatory affairs leads, and procurement managers informed market dynamics. Secondary validation involved FDA filings, EMA submissions, biopharmaceutical company 10-K reports, and specialized industry association publications. This comprehensive approach ensures robust data triangulation.
An input-output matrix framework projects market evolution across the analysis window, integrating volume and value drivers. Segmentation dimensions modeled include product type, end user, technology, application, and regional regulatory cluster. Compound annual growth rates were calculated from projected market values, reflecting the impact of biologic drug pipeline expansion and continuous manufacturing adoption rates. This framework provides granular market insights.
Underlying measurement precision varies by segment; pH probes and temperature sensors carry tighter precision than newer optical sensor applications. Forecasts reflect assumptions regarding regulatory changes and biopharmaceutical R&D expenditure. A model refresh is warranted upon material change in continuous biomanufacturing adoption or new material science breakthroughs.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Engineering
Tissue Engineering Market
Biomedical Engineering
Global Bionic Ear Market
Biomedical Engineering
Self-Inflating Tissue Expander Market
Biomedical Engineering
Bioink Market
Biomedical Engineering
Biocompatible 3D Printing Market
Biomedical Engineering
Bioactive Bone Grafts Market
Biomedical Engineering
Global Bionics Market
Biomedical Engineering
Bioimplants Market
Biomedical Engineering
Bioresorbable Scaffolds Market
Biomedical Engineering
3D Bioprinted Organ Transplants Market
Biomedical Engineering
Non-Surgical Bio-Implants Market
Biomedical Engineering
Biological Implants Market
Biomedical Engineering
Tissue Extraction System Market
Biomedical Engineering
Large and Small-Scale Bioprocessing Market
Biomedical Engineering
Bio-Engineered Stent Market
Biomedical Engineering
3D Bioprinted Human Tissue Market