
 Single Use Bioprocessing Market | 2026-2036
Single Use Bioprocessing Market Size, Share, and Industry Trends Forecast 2026-2036
Single Use Bioprocessing Market Intelligence
Cell and gene therapy manufacturing is rebalancing the end-use mix toward biotechnology firms and contract manufacturing organizations. Sartorius AG leverages its filtration specialization to anchor European bioprocessing supply chains. Danaher Corporation sustains broad portfolio coverage across liquid handling and automation workflows. Thermo Fisher Scientific dominates North American distribution through integrated channel control.
Single-use bioprocessing encompasses disposable vessels, transfer lines, and containment systems constructed from multilayer polymer films such as ethylene vinyl acetate and low-density polyethylene, designed for aseptic fluid handling without cleaning validation cycles. Bags and tubing capture recurring consumable revenue through per-batch replacement schedules, while bioreactors command premium positioning via scale-out configurations. Filtration devices compete on pore-size precision and gamma-irradiation compatibility, with membrane surface area density serving as a key performance parameter.
FDA process validation guidance and EMA GMP Annex 1 revisions are elevating extractables and leachables testing to mandatory status for all polymer contact materials. The EU MDR and ISO 13485 convergence is forcing suppliers to maintain dual quality management systems for biopharma and medical device pathways. Stakeholders must monitor regulatory divergence between US and European polymer qualification standards when designing multi-site manufacturing templates.
Market Dynamics
Contract Manufacturing Organizations are consolidating biologics production around single-use architectures, displacing stainless-steel infrastructure as batch flexibility outweighs unit cost economics in multi-product facilities.
Growth Catalysts
- EMA GMP Annex 1 Revisions:The updated sterile manufacturing guidance mandates closed-system processing, accelerating facility retrofits toward disposable containment technologies.
- Cell Therapy Manufacturing:Autologous and allogeneic production workflows demand rapid turnaround between patient batches, making clean-in-place cycles economically untenable.
- China Biologics Clustering:Suzhou and Shanghai development zones are attracting CDMO investment, creating concentrated demand for modular single-use bioreactor installations.
Market Restraints
- Polymer Resin Concentration:Ethylene vinyl acetate and low-density polyethylene supply chains concentrate among Korean and Saudi petrochemical producers, exposing film manufacturers to feedstock volatility.
- Extractables Testing Burden:FDA process validation guidance requires comprehensive leachables profiling for every polymer contact material, extending qualification timelines by twelve to eighteen months.
- Stainless-Steel Residual Preference:High-volume monoclonal antibody facilities above ten-thousand-liter scale retain economic advantage with traditional bioreactor infrastructure.
Strategic Opportunities
- India CDMO Expansion:The country's pharmaceutical production incentives under PLI scheme are drawing biologics investment, creating virgin territory for single-use system deployment.
- Continuous Bioprocessing Convergence:Perfusion cell culture technologies paired with disposable chromatography skids enable integrated manufacturing trains without fixed equipment.
- Closed-System Mandates:EU MDR containment requirements for advanced therapy medicinal products are forcing legacy facility upgrades toward fully disposable fluid paths.
Industry Challenges
- Gamma Irradiation Capacity Scarcity:Sterilization service providers face bottlenecks as bioprocessing bag volumes outpace cobalt-60 source availability.
- Automation Integration Complexity:Legacy distributed control systems require custom middleware to communicate with modern single-use sensor networks.
- Single-Use Technology Specialist Shortage:Facilities lack personnel trained in disposable system assembly validation and failure-mode analysis.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Single Use Bioprocessing Market |
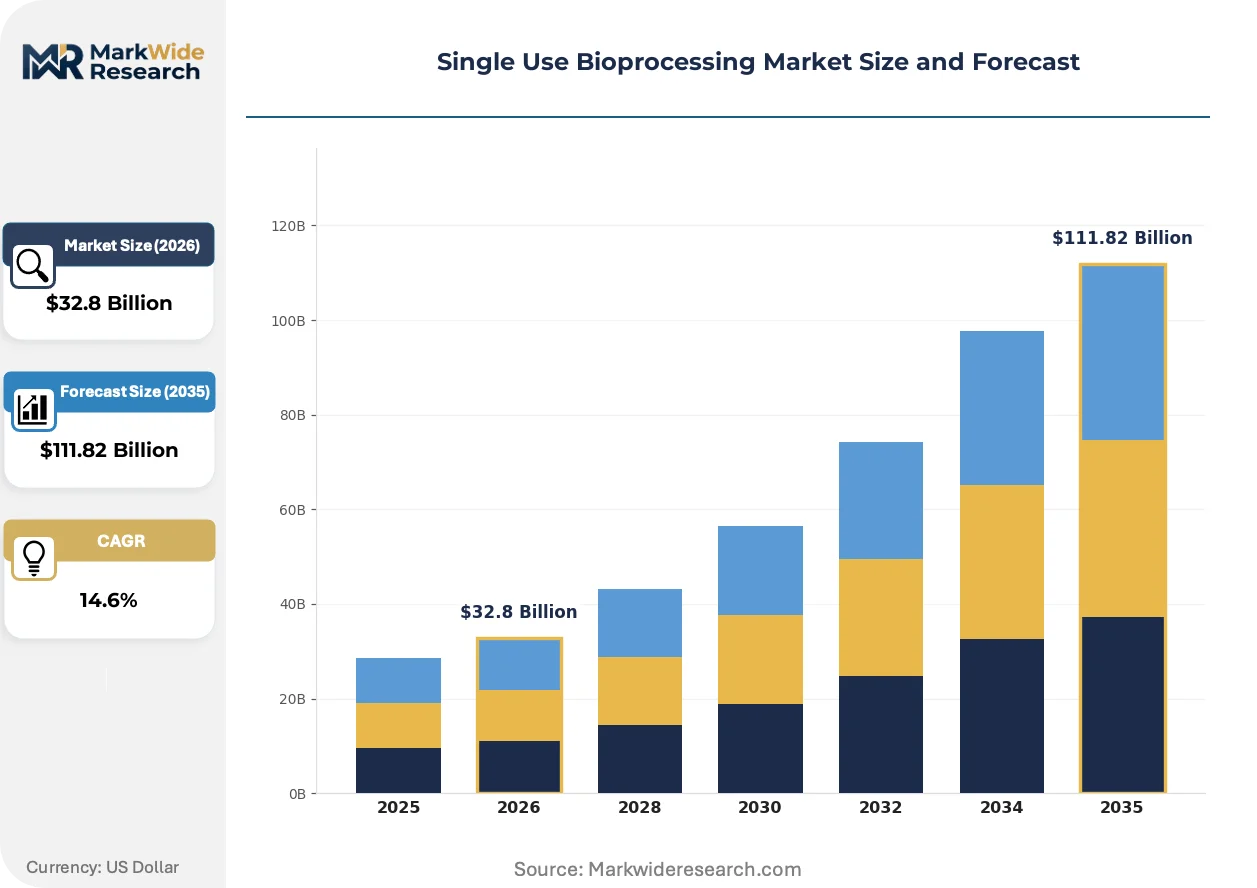
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $111.82 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bioreactors, Filtration Devices, Bags, Tubing End User: Pharmaceutical Companies, Biotechnology Firms, Contract Manufacturing Organizations, Research Laboratories Application: Vaccine Production, Monoclonal Antibodies, Gene Therapy, Cell Culture Technology: Filtration Technology, Mixing Technology, Liquid Handling, Automation |
| Companies Covered | Sartorius AG, Danaher Corporation, Thermo Fisher Scientific, Inc., Merck KGaA, Avantor, Inc., Eppendorf SE, Corning Incorporated, Lonza, Repligen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Single Use Bioprocessing Market Strategic Shifts & Innovations
Modular manufacturing architectures are compressing facility construction timelines while sensor-embedded disposables enable real-time process analytical technology deployment.
Pre-sterilized, pre-assembled process trains are decentralizing biologics production from centralized mega-sites to distributed regional facilities. CDMOs in Germany and Singapore are adopting plug-and-play skid configurations that reduce commissioning from months to weeks. This architecture is decentralizing supply chain risk by enabling multi-source manufacturing without capital-intensive site replication.
FDA process validation guidance and EMA GMP Annex 1 revisions are elevating extractables and leachables testing to mandatory status for all polymer contact materials. Suppliers must now maintain dual quality management systems bridging ISO 13485 medical device pathways and pharmaceutical GMP standards. Bioreactor film manufacturers face the steepest compliance burden as surface area-to-volume ratios maximize patient exposure risk.
Biopharma procurement functions are consolidating supplier relationships around integrated platform providers capable of delivering complete fluid management systems. Multi-year enterprise agreements are displacing spot purchasing for bags, tubing, and connectors. This concentration is most visible among US biotechnology firms scaling gene therapy manufacturing, where supply assurance outweighs unit price optimization.
Single Use Bioprocessing Market Segmentation
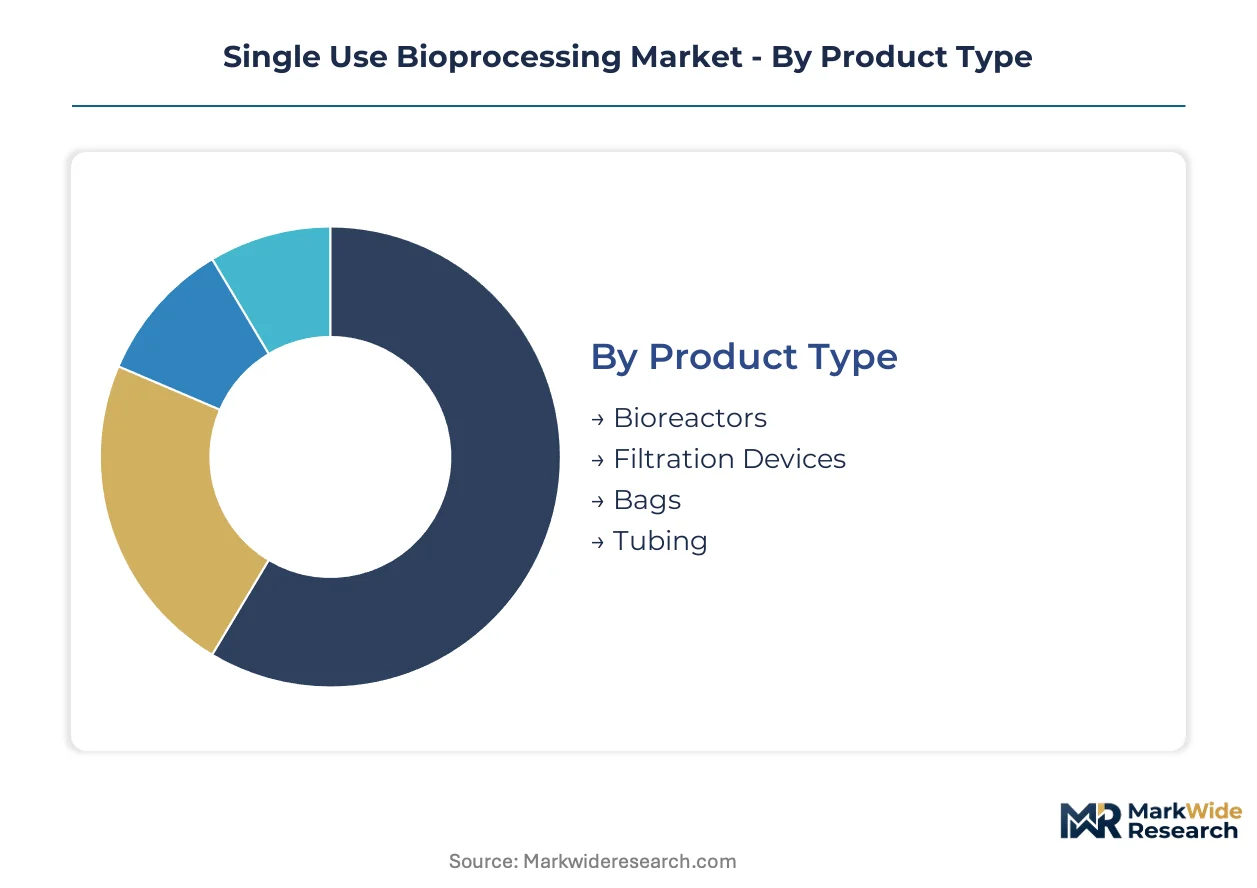
Segmentation in single-use bioprocessing reveals how regulatory complexity and manufacturing scale reshape procurement priorities across product categories. Each dimension carries distinct qualification burdens and margin structures that determine supplier positioning.
Product Type:
FDA process validation guidance and EMA GMP Annex 1 revisions impose tiered extractables testing requirements, with bioreactor films facing the steepest compliance burden due to maximum patient exposure risk.
- Bioreactors:Constructed from multilayer ethylene vinyl acetate and low-density polyethylene films, these vessels require gamma-irradiation sterilization and closed-system validation. Demand concentrates in Germany and China where CDMOs are retrofitting facilities for cell therapy manufacturing under EMA sterile processing mandates.
- Filtration Devices:Membrane assemblies compete on pore-size precision and surface area density, with gamma-irradiation compatibility serving as a gatekeeping specification. Biotechnology firms scaling gene therapy production in the United States drive premium positioning for high-capacity tangential flow configurations.
- Bags:Flexible containment systems for media storage and harvest collection generate recurring consumable revenue through per-batch replacement schedules.
- Tubing:Transfer lines connect process unit operations, with platinum-cured silicone and thermoplastic elastomer formulations dominating aseptic fluid handling applications.
Leading the category by volume: Bags. Growing fastest: Bioreactors.
End User:
Procurement sophistication varies sharply across customer types, with contract manufacturing organizations demanding integrated platform solutions while research laboratories prioritize flexibility over scale.
- Pharmaceutical Companies:Large-scale monoclonal antibody manufacturers above ten-thousand-liter scale retain stainless-steel preference for unit cost economics, constraining single-use penetration to downstream purification and fill-finish operations.
- Biotechnology Firms:Cell and gene therapy developers require rapid turnaround between patient batches, making clean-in-place cycles economically untenable and driving premium adoption of disposable containment architectures.
- Contract Manufacturing Organizations:Multi-product facilities prioritize batch flexibility over capital intensity, consolidating biologics production around modular single-use architectures that compress facility construction timelines.
- Research Laboratories:Early-stage process development relies on small-scale disposable systems for clone screening and media optimization without cleaning validation overhead.
Highest procurement concentration: Contract Manufacturing Organizations. Steepest expansion trajectory: Biotechnology Firms.
Application:
Manufacturing complexity and regulatory scrutiny intensity diverge across therapeutic modalities, with advanced therapy medicinal products commanding the most stringent closed-system requirements.
- Vaccine Production:Pandemic response infrastructure and seasonal manufacturing cycles favor disposable technologies that enable rapid capacity scaling without fixed asset commitment.
- Monoclonal Antibodies:Established high-volume workflows above five-thousand-liter scale retain stainless-steel economic advantage, though perfusion cell culture technologies are eroding this boundary.
- Gene Therapy:Viral vector manufacturing demands segregated production lines per product to prevent cross-contamination, making single-use systems the default architecture for multi-product facilities.
- Cell Culture:Anchorage-dependent and suspension cell workflows both leverage disposable bioreactors, with sensor-embedded films enabling real-time process analytical technology deployment.
Dominant volume segment: Monoclonal Antibodies. Climbing the fastest: Gene Therapy.
Technology:
Automation integration complexity and legacy distributed control system compatibility determine technology adoption timelines across manufacturing scales.
- Filtration Technology:Tangential flow and normal flow configurations compete on throughput and protein recovery rates, with disposable cassette formats displacing reusable hardware in clinical manufacturing.
- Mixing Technology:Magnetic levitation and overhead drive systems for media and buffer preparation eliminate mechanical seals and reduce contamination risk in closed-system processing.
- Liquid Handling:Precision dispensing and sampling systems integrate with single-use manifolds to enable automated aseptic transfer without open interventions.
- Automation:Custom middleware requirements for legacy distributed control system communication create implementation bottlenecks despite sensor-embedded disposable networks offering real-time data capture.
Widest deployment: Filtration Technology. Gaining share fastest: Automation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Suzhou Industrial Park and Shanghai Zhangjiang Hi-Tech Park anchor China's biologics manufacturing concentration, while German bioclusters and US innovation corridors compete for CDMO investment flows.
United States
Gene therapy manufacturing in Greater Boston and the San Francisco Bay Area drives disposable bioreactor demand. FDA process validation guidance mandates extractables testing for all polymer contact materials. The Research Triangle Park in North Carolina hosts expanding viral vector capacity.
Germany
EMA GMP Annex 1 revisions on sterile manufacturing accelerate facility retrofits toward closed-system processing. The country's pharmaceutical regulator enforces dual ISO 13485 and pharmaceutical GMP compliance. Heidelberg and Munich bioclusters concentrate perfusion cell culture technology deployment.
China
Suzhou and Shanghai development zones attract CDMO investment through tax incentives and streamlined NMPA approval pathways. The national medical products administration tightens polymer qualification standards for imported films. Wuxi Biologics anchors domestic single-use supply chain development.
India
Pharmaceutical production incentives under the PLI scheme draw biologics investment toward Hyderabad and Bengaluru. CDSCO alignment with ICH Q5A guidelines elevates viral safety validation requirements for disposable systems. The Genome Valley cluster expands contract manufacturing infrastructure.
Switzerland
Basel's pharmaceutical corridor sustains demand for high-purity filtration and fluid management systems. Swissmedic maintains stringent leachables profiling requirements exceeding baseline EU standards. The Lake Geneva region concentrates continuous bioprocessing technology development.
Single Use Bioprocessing Market Key Industry Players
Top-tier vendors anchor integrated platform provision, while mid-tier specialists compete on filtration precision and regional distribution density. The vendor base stratifies across three archetypes: diversified life science conglomerates, dedicated bioprocessing technology firms, and polymer film manufacturers with vertical capabilities. Competitive moves concentrate on multi-year enterprise agreements and automation-ready skid configurations.
Within the diversified conglomerate tier, Danaher Corporation and Thermo Fisher Scientific occupy positions spanning liquid handling through distribution control. Sartorius AG represents the dedicated specialist archetype with European supply chain anchoring. Merck KGaA exemplifies the integrated chemical-pharmaceutical pathway into polymer contact materials. These three patterns illustrate how competitive positioning diverges between breadth-driven and depth-driven strategies.
| Leading Market Players |
|---|
| Sartorius AG |
| Danaher Corporation |
| Thermo Fisher Scientific, Inc. |
| Merck KGaA |
| Avantor, Inc. |
| Eppendorf SE |
| Corning Incorporated |
| Lonza |
| Repligen |
| Others |
Cost & Logistics Intelligence
CDMO procurement consolidation around integrated platform providers is forcing film manufacturers to absorb extractables testing costs while maintaining gamma-irradiation sterilization capacity, compressing margins on standard-grade bags and tubing while preserving premium pricing for closed-system bioreactor configurations.
Pricing Analysis
Short lead-time premiums of fifteen to twenty percent apply to pre-validated bioreactor film assemblies held in regional distribution centers, while spot-market spot pricing for standard media bags reflects commodity polymer resin cost pass-through mechanics. Three-tier pricing structure across premium, standard, and economy levels segments on gamma-irradiation certification grade and extractables documentation depth. Price differentiation intensifies as Korean and Saudi petrochemical feedstock volatility transmits through ethylene vinyl acetate supply contracts. Biotechnology firms scaling gene therapy manufacturing show lowest price sensitivity due to batch failure costs, while research laboratories drive economy-tier volume.
Supply Chain Analysis
FDA and EMA polymer qualification requirements function as certification gates that exclude non-compliant film manufacturers from pharmaceutical-grade supply chains, concentrating approved supplier bases. Manufacturing concentrates in Germany, the United States, and China where CDMO clustering creates demand density for local gamma-irradiation services. Ethylene vinyl acetate, low-density polyethylene, and platinum-cured silicone elastomer feedstock draws from Korean and Saudi petrochemical complexes. Single-source vulnerability in cobalt-60 sterilization capacity creates bottlenecks during bioprocessing bag volume surges. Distribution runs through integrated life science distributors and direct enterprise agreements with CDMO platform providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EMA GMP Annex 1 extractables mandates and FDA process validation guidance have erected compliance moats that favor incumbent polymer film manufacturers with established dual ISO 13485 and pharmaceutical GMP quality systems.
For Market Incumbents: Anticipate margin compression in standard-grade consumables as Chinese domestic suppliers achieve NMPA polymer qualification, and respond by deepening captive supply of gamma-irradiation capacity in Germany and the United States. Prioritize automation-ready skid configurations that lock CDMOs into multi-year enterprise agreements through switching cost engineering. For New Entrants and Emerging Players: Capture virgin territory in India's PLI-driven biologics expansion where CDSCO alignment with ICH Q5A guidelines creates demand for qualified disposable systems without entrenched supplier relationships. Target Hyderabad and Bengaluru contract manufacturing clusters with pre-validated closed-system architectures. Lead with technical training services that address the specialist shortage in disposable system assembly validation. For Investors and Strategic Acquirers: The window for entry favors polymer film manufacturers with vertical capabilities into gamma-irradiation sterilization and extractables testing laboratories. Monitor cobalt-60 source availability constraints as the inflection signal for sterilization service provider acquisition premiums. Long-term viability hinges on regulatory divergence management between US and European polymer qualification standards.| Strategic Initiative | Industry Significance |
|---|---|
| Extractables Testing Laboratory Acquisition | Vertical integration into leachables profiling compresses qualification timelines for EMA GMP Annex 1 compliance. |
| Gamma Irradiation Capacity Expansion | Cobalt-60 sterilization bottlenecks in Germany and the United States threaten CDMO batch release schedules. |
| Automation-Ready Skid Configuration Launch | Plug-and-play process trains reduce CDMO commissioning from months to weeks under EMA closed-system mandates. |
| India CDMO Partnership Program | PLI scheme biologics investment in Hyderabad creates virgin demand for qualified single-use architectures. |
| Dual Quality System Certification Investment | Simultaneous ISO 13485 and pharmaceutical GMP compliance gates non-specialist competitors from EU MDR pathways. |
Research Approach
Independent corroboration across regulatory affairs directors at polymer film manufacturers, CDMO procurement executives, and gamma-irradiation service operators underwrites the qualitative findings on extractables testing burden and sterilization capacity scarcity. Secondary validation draws from FDA guidance documents, EMA GMP Annex 1 revision drafts, and NMPA polymer qualification standards. Bottom-up demand modeling triangulates against top-down pharmaceutical production capacity expansion announcements across the United States, Germany, and China.
Rate-of-change decomposition separates volume growth from mix-shift effects as cell and gene therapy manufacturing rebalances the end-use mix toward biotechnology firms and contract manufacturing organizations across the analysis window. Segmentation dimensions span product type, end user, application, and technology, with regulatory cluster and manufacturing scale tiered as cross-cutting variables. CAGRs derive from facility retrofit timelines under EMA sterile processing mandates and CDMO investment flows into Suzhou and Shanghai development zones.
The model holds under sustained EMA and FDA regulatory convergence on extractables testing; deviation toward divergent polymer qualification standards would shift supplier competitive positioning. Stakeholders should weight assumptions against their own operating context regarding gamma-irradiation capacity access and dual quality system maintenance costs.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
Laboratory Andrology Equipment Market
Biotechnology Equipment
Fetal Bovine Serum Market
Biotechnology Equipment
Botanical Extraction Equipment Market
Biotechnology Equipment
Lab Centrifuges Market
Biotechnology Equipment
PCR Master Mix Market
Biotechnology Equipment
Global Single-Use Bioreactor Market
Biotechnology Equipment
Small-Scale Bioreactors Market
Biotechnology Equipment
Global Automated Biochemical Analyzer Market
Biotechnology Equipment
Single-Use Bioreactor Bag Integrity and Leak Test Equipment Market
Biotechnology Equipment
RNA Isolation and Enrichment Reagent Market
Biotechnology Equipment
Cryogenic Vial Rack Market
Biotechnology Equipment
Global Cell Separation Technology Market
Biotechnology Equipment
Micro-Bioreactors Market
Biotechnology Equipment
Separation Systems for Commercial Biotechnology Market
Biotechnology Equipment
Balanced Salt Solution for Cell Culture Market
Biotechnology Equipment
Mammalian Cell Fermentation Technology Market