
 Bio-Engineered Stent Market | 2026-2036
Bio-Engineered Stent Market Size, Share, and Industry Trends Forecast 2026-2036
Bio-Engineered Stent Market Analytics
The gap between cobalt-chromium bare-metal platforms and next-generation bioresorbable magnesium alloys is narrowing as foundry-level metallurgy advances yield predictable degradation kinetics. Medtronic leverages its integrated structural heart franchise to sustain catheter-lab pull-through across integrated delivery networks. Boston Scientific Corporation anchors its competitive stance through polymer-science depth in controlled-release paclitaxel formulations. Abbott Laboratories differentiates via absorbable-polymer strategies that navigate European reimbursement complexity.
Bio-engineered stents are implantable endovascular scaffolds manufactured from biocompatible metals, synthetic polymers, or resorbable materials, typically ranging from 2.0 to 4.0 millimeters in deployed diameter and 8 to 38 millimeters in length, designed to restore luminal patency while modulating neointimal hyperplasia through pharmaceutical or biological surface engineering. Drug-eluting stents occupy the dominant revenue position due to established clinical efficacy in coronary artery disease, though biodegradable stents represent the fastest-expanding development pipeline as manufacturers resolve mechanical performance and degradation-control tradeoffs. Hospitals command the largest procurement volume among end-user segments, while outpatient surgical centers emerge as a concentrated margin pool where ambulatory payment classification shifts reward same-day intervention economics.
The FDA's premarket approval pathway and the EU Medical Device Regulation's clinical-evaluation requirements shape product development timelines and evidence-generation burdens for all active participants. Japan's PMDA enforces Japan-specific clinical trials that extend market-access horizons but reward compliant firms with durable reimbursement codes. Stakeholders must monitor how health technology assessment bodies in Germany, France, and England weight bioresorbable outcomes data against incremental cost thresholds when making formulary and procurement decisions.
Market Dynamics
The transition from permanent metallic implants to bioresorbable scaffolds is restructuring competitive advantage around materials science capabilities and degradation-control intellectual property rather than traditional manufacturing scale.
Growth Catalysts
- FDA breakthrough device designation:Expedited review pathways for novel magnesium-alloy platforms accelerate commercial timelines for first-generation bioresorbable entrants targeting complex coronary lesions.
- Japan's PMDA reimbursement incentives:Superior clinical data requirements under national health technology assessment programs reward manufacturers with durable procedure codes for drug-eluting platforms.
- Polymer-coating advances:Controlled-release paclitaxel formulations from synthetic absorbable polymers enable precise neointimal modulation without chronic inflammation risks.
Market Restraints
- Magnesium feedstock volatility:Specialized foundry-grade alloy supply concentrates among German and Chinese metallurgical suppliers, creating input cost exposure.
- EU MDR clinical evidence burdens:Post-market surveillance requirements and notified body capacity constraints extend recertification timelines for legacy polymer-coated devices.
- Bare-metal stent substitution:Cobalt-chromium platforms retain cost advantage in price-sensitive procurement environments where bioresorbable premiums face reimbursement resistance.
Strategic Opportunities
- Outpatient surgical center expansion:Ambulatory payment classification shifts in United States reimbursement create same-day intervention economics favoring rapid-deployment catheter systems.
- Peripheral artery disease applications:Below-the-knee lesion subsets represent underpenetrated anatomical targets where bioresorbable scaffolds address fracture risks of permanent implants.
- Digital twin integration:Computational modeling of degradation kinetics combined with patient-specific hemodynamics enables personalized stent selection protocols.
Industry Challenges
- Biomaterials engineering talent scarcity:Cross-disciplinary expertise spanning vascular biology, polymer chemistry, and computational modeling commands premium compensation and extends R&D team assembly timelines.
- ISO 10993 biocompatibility testing bottlenecks:Cytotoxicity and hemocompatibility validation for novel resorbable alloys requires 18-24 month preclinical programs before regulatory submission.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bio-Engineered Stent Market |
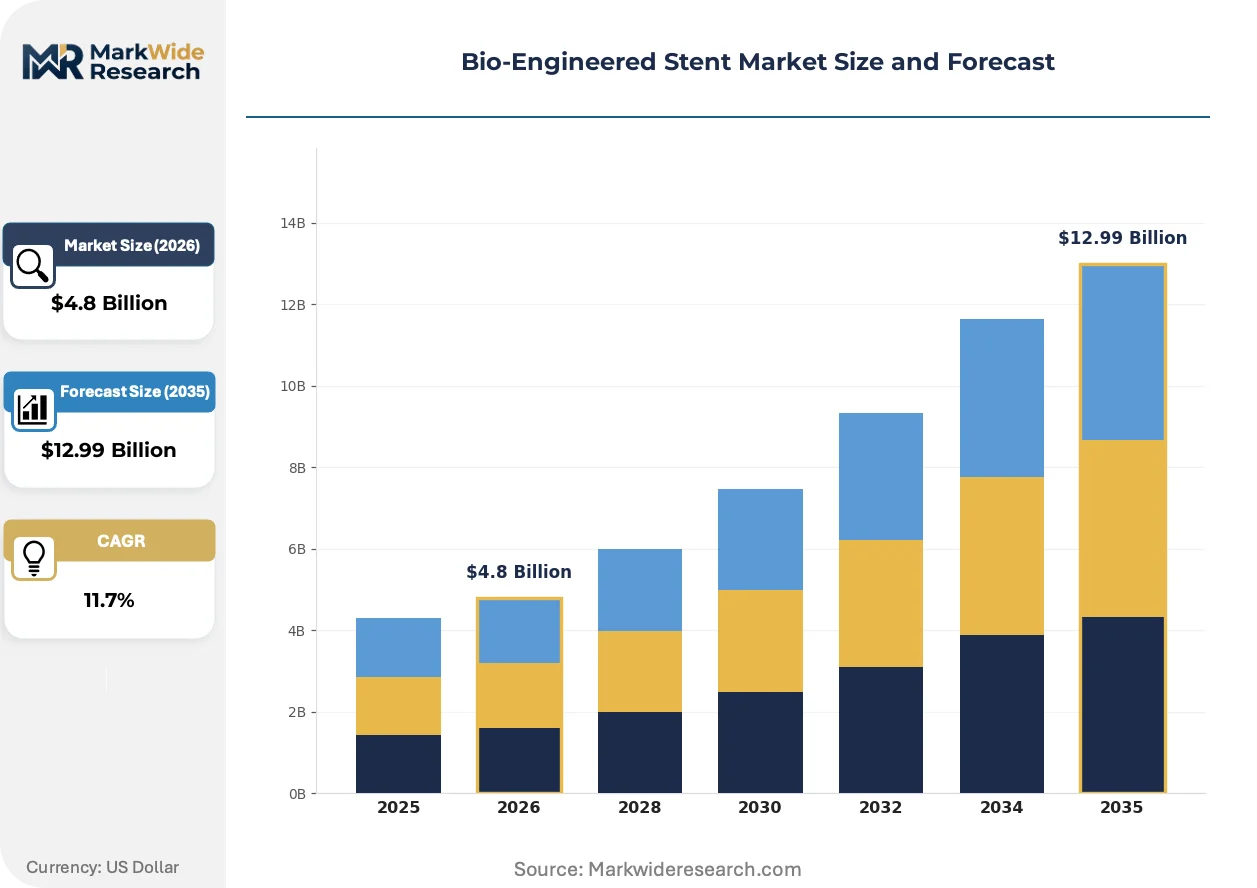
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drug-Eluting Stents, Bare-Metal Stents, Biodegradable Stents, Polymer-Coated Stents End User: Clinics, Hospitals, Outpatient Surgical Centers, Cardiology Practices Material: Polymer, Metal Alloys, Biodegradable Materials, Coatings Application: Coronary Artery Disease, Peripheral Artery Disease, Aneurysm Treatment, Renal Artery Stenting |
| Companies Covered | Medtronic, Boston Scientific Corporation, Abbott Laboratories, Biotronik SE & Co. KG, B. Braun Melsungen AG, Terumo Corporation, MicroPort Scientific Corporation, Meril Life Sciences Pvt. Ltd, W. L. Gore and Associates, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bio-Engineered Stent Market Evolving Landscape
Computational modeling and biomaterials convergence are compressing traditional development cycles while regulatory frameworks recalibrate evidence standards for transient implantable devices.
Magnesium-rare-earth alloy systems with tunable corrosion rates are virtualizing the traditional tradeoff between mechanical integrity and bioresorption speed. Interventional cardiologists in German university hospitals are piloting these platforms for bifurcation lesions where permanent metal complicates future bypass surgery. The technology is virtualizing historical segmentation between durable and biodegradable scaffold categories into a continuum of degradation-kinetic options.
EU Medical Device Regulation's clinical evaluation requirements are elevating post-market performance tracking from administrative checkbox to strategic differentiator. Manufacturers must maintain systematic literature reviews and PMCF studies that demonstrate sustained superiority against evolving standard-of-care benchmarks. German notified bodies are applying MDR Article 61 most stringently to first-generation bioresorbable submissions, forcing sponsors to augment premarket trial data with real-world evidence registries.
Hospital procurement committees are consolidating vendor relationships around integrated stent-catheter platforms that reduce inventory complexity. Cardiology departments in Japanese tertiary centers now specify single-source contracts covering delivery systems, dilation protocols, and staff training rather than discrete device purchases. This concentration pattern is most pronounced in metropolitan Tokyo and Osaka health systems where consolidated purchasing organizations negotiate multi-year supply agreements.
Bio-Engineered Stent Market Segmentation
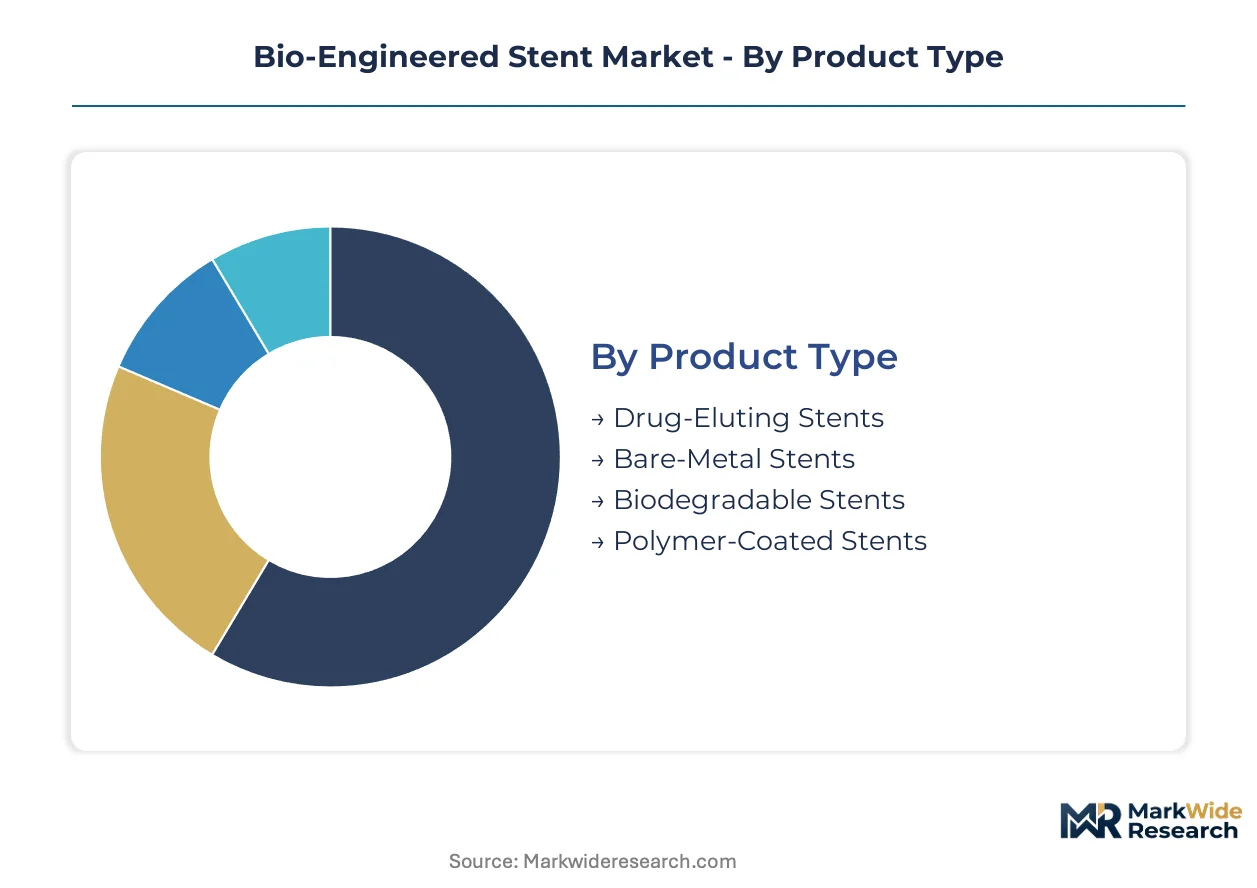
Segmentation in bio-engineered stents determines procurement patterns, regulatory pathways, and R&D resource allocation across fundamentally different clinical use cases and reimbursement environments. Manufacturers configure product portfolios around specific material platforms and end-user economics rather than pursuing horizontal coverage.
Product Type:
Replacement cycles vary dramatically across stent categories, with permanent metallic platforms requiring no follow-up intervention while biodegradable alternatives demand precise degradation timing matched to patient-specific healing trajectories.
- Drug-Eluting Stents:Polymer-matrix platforms release antiproliferative agents through controlled dissolution kinetics. Cardiology practices in Japan's metropolitan hospital systems concentrate procurement here due to PMDA reimbursement codes rewarding demonstrated superiority in complex lesions.
- Bare-Metal Stents:Cobalt-chromium scaffolds without pharmaceutical coating rely on mechanical properties alone. German university hospitals maintain selective use for patients with contraindications to prolonged dual antiplatelet therapy, though volume share is compressing against drug-eluting alternatives.
- Biodegradable Stents:Magnesium-alloy and poly-lactic acid platforms resorb completely after luminal remodeling. Below-the-knee peripheral applications in United States outpatient settings are climbing fastest as fracture risks of permanent metal drive substitution.
- Polymer-Coated Stents:Synthetic absorbable layers modulate drug release without permanent implant residue. EU MDR notified bodies in Germany are applying stringent Article 61 clinical evidence requirements to these submissions.
Drug-eluting platforms dominate installed base. Biodegradable stents are where expansion concentrates.
End User:
Procurement authority concentrates differently across settings, with integrated delivery networks controlling hospital purchasing while outpatient centers optimize around same-day intervention economics and ambulatory payment classification shifts.
- Hospitals:Tertiary cardiac centers with catheterization laboratories command the largest procurement volumes and negotiate multi-year supply agreements covering delivery systems and staff training protocols.
- Outpatient Surgical Centers:Standalone facilities optimized for rapid patient turnover. United States reimbursement shifts toward ambulatory payment classifications are concentrating margin expansion here.
- Cardiology Practices:Physician-owned intervention suites in metropolitan United States markets. Inventory complexity reduction is driving consolidation around single-source vendor relationships.
- Clinics:Diagnostic and referral-focused settings with limited intervention capability. Pre-procedure patient selection and post-implant surveillance generate downstream referral economics rather than device procurement.
Hospital procurement controls volume. Outpatient surgical centers capture expanding margin pools.
Material:
Supply chain configuration determines cost structure and regulatory validation burden, with specialized metallurgy commanding premium feedstock pricing while polymer platforms face shorter ISO 10993 biocompatibility pathways.
- Metal Alloys:Cobalt-chromium and platinum-iridium systems provide radial strength and radiopacity. German and Chinese foundry suppliers concentrate specialized alloy production, creating input cost exposure for manufacturers.
- Biodegradable Materials:Magnesium-rare-earth alloys and poly-lactic acid polymers with tunable corrosion kinetics. FDA breakthrough device designation pathways are accelerating commercial timelines for first-generation entrants.
- Polymer:Synthetic absorbable matrices for controlled drug release. Boston Scientific Corporation anchors competitive positioning through polymer-science depth in paclitaxel formulation.
- Coatings:Surface-engineered layers modifying hemocompatibility and drug elution. Cytotoxicity and hemocompatibility validation requirements extend preclinical programs.
Metal alloys anchor current revenue. Biodegradable materials represent the steepest expansion trajectory.
Application:
Clinical evidence requirements and reimbursement intensity diverge across anatomical targets, with coronary applications commanding premium pricing while peripheral segments offer volume expansion in underpenetrated lesion subsets.
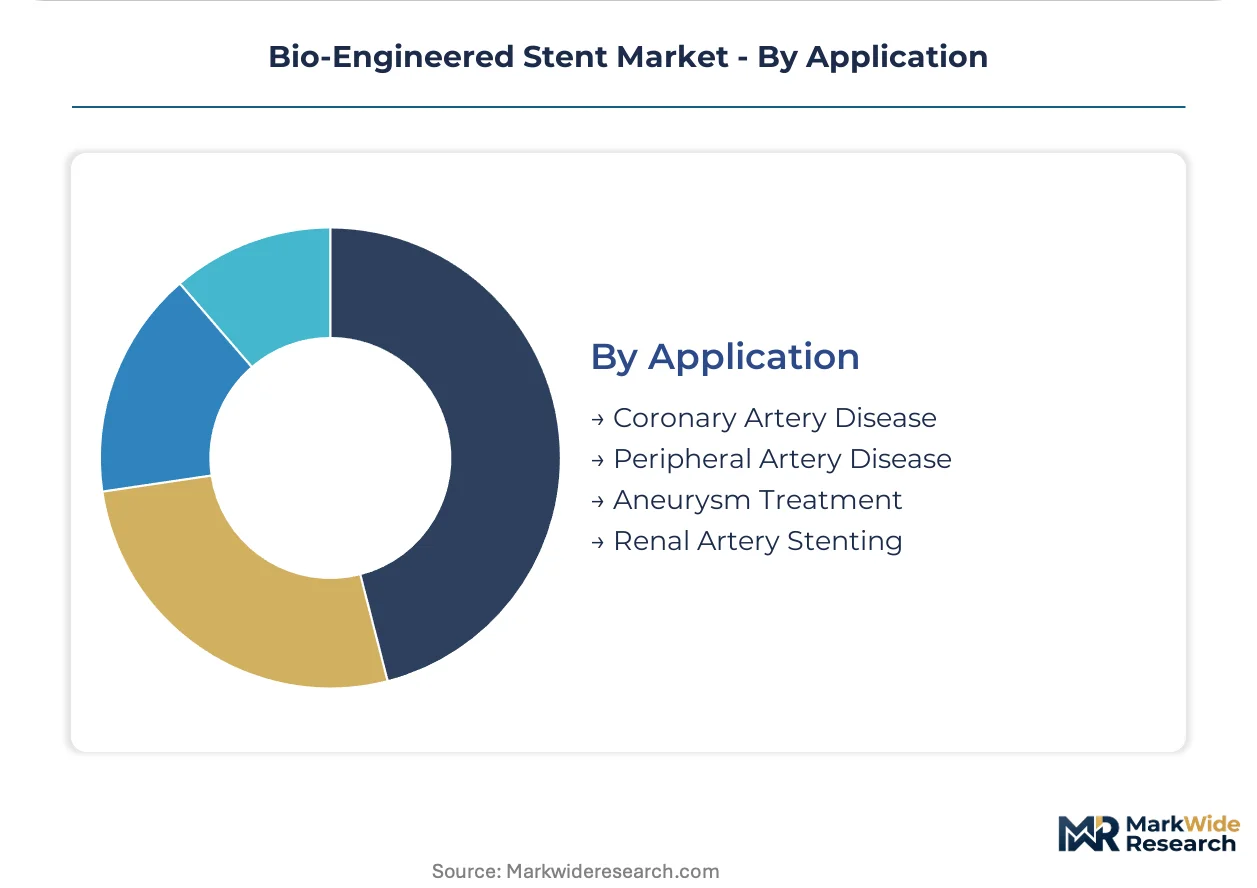
- Coronary Artery Disease:Narrowed epicardial vessels requiring revascularization. Drug-eluting platforms hold established efficacy data, though bioresorbable scaffolds are piloting in bifurcation lesions where permanent metal complicates future bypass surgery.
- Peripheral Artery Disease:Atherosclerotic narrowing of non-coronary vessels, particularly below-the-knee segments. Fracture risks of permanent cobalt-chromium implants in tibial arteries are driving biodegradable substitution.
- Aneurysm Treatment:Endovascular exclusion of dilated arterial segments. Flow-diverting stent platforms require distinct regulatory pathways from coronary scaffolds.
- Renal Artery Stenting:Revascularization of atherosclerotic renal artery stenosis. Clinical trial evidence for benefit over medical therapy alone has narrowed appropriate use criteria.
Coronary applications dominate procedure volume. Peripheral artery disease is gaining share fastest in expanding geographies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement committees in the United States, Germany, and Japan concentrate the highest-value purchasing decisions, with catheter-lab directors in tertiary cardiac centers wielding disproportionate influence over vendor selection and multi-year supply agreements.
United States
FDA breakthrough device designation pathways accelerate commercial timelines for magnesium-alloy bioresorbable entrants targeting complex coronary lesions. Ambulatory payment classification shifts reward same-day intervention economics, concentrating margin expansion in outpatient surgical centers across metropolitan markets. Greater Boston and the San Francisco Bay Area host the densest clusters of interventional cardiology training programs that pilot novel scaffold platforms.
Germany
BfArM maintains stringent CE marking requirements under EU Medical Device Regulation that favor polymer-coated platforms with robust clinical evidence packages. German university hospitals in Munich and Heidelberg pilot magnesium-rare-earth alloy systems for bifurcation lesions where permanent metal complicates future bypass surgery. Notified bodies apply MDR Article 61 most stringently to first-generation bioresorbable submissions.
Japan
METI-backed national health technology assessment programs prioritize drug-eluting stents with demonstrated superiority in complex lesion subsets. PMDA enforces Japan-specific clinical trials that extend market-access horizons but reward compliant firms with durable reimbursement codes. Tokyo and Osaka health systems negotiate single-source contracts covering delivery systems, dilation protocols, and staff training.
China
NMPA regulatory pathways for innovative medical devices compress review timelines for domestic manufacturers of bioresorbable scaffolds. National volume-based procurement reforms pressure pricing for drug-eluting platforms while creating entry opportunities for biodegradable alternatives. Shanghai and Beijing metropolitan hospitals concentrate the highest procedural volumes for coronary interventions.
Switzerland
Swissmedic maintains alignment with EU MDR standards while offering streamlined pathways for breakthrough device categories. Precision manufacturing clusters in the Lake Geneva region supply specialized cobalt-chromium alloy feedstock to European stent fabricators. Basel and Zurich university hospitals participate in multinational clinical trials for next-generation polymer-coated platforms.
Bio-Engineered Stent Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three discernible tiers. Vertically integrated structural heart franchises leverage catheter-lab pull-through across integrated delivery networks. Polymer-science specialists anchor positioning through controlled-release formulation depth. Materials-science entrants concentrate intellectual property around degradation-control metallurgy. Dominant competitive moves include strategic partnerships with German and Chinese foundry suppliers and portfolio diversification into peripheral artery disease applications.
Among diversified medical technology conglomerates, Medtronic, Boston Scientific Corporation, and Abbott Laboratories exemplify distinct strategic archetypes. Medtronic occupies a position emphasizing integrated structural heart ecosystems. Boston Scientific Corporation sits within the polymer-science specialist tier. Abbott Laboratories represents absorbable-polymer strategies calibrated for European reimbursement complexity. These three entities collectively illustrate how competitive advantage restructures around materials science capabilities rather than traditional manufacturing scale.
| Leading Market Players |
|---|
| Medtronic |
| Boston Scientific Corporation |
| Abbott Laboratories |
| Biotronik SE & Co. KG |
| B. Braun Melsungen AG |
| Terumo Corporation |
| MicroPort Scientific Corporation |
| Meril Life Sciences Pvt. Ltd |
| W. L. Gore and Associates |
| Others |
Value Network & Pricing Analysis
Magnesium feedstock volatility between German and Chinese foundry suppliers determines both pricing tier spreads across drug-eluting and biodegradable stent categories and supply chain shape through single-source metallurgical dependencies. Hospital procurement committees and outpatient surgical centers face divergent cost pass-through exposure depending on their contract indexation clauses.
Pricing Analysis
Cost-plus contracts with magnesium alloy indexation dominate long-term supply agreements between manufacturers and German foundry suppliers. Pricing stratifies across premium bioresorbable scaffolds, standard drug-eluting platforms, and economy bare-metal tiers based on clinical evidence depth and regulatory pathway complexity. Pricing pressure stems from China's volume-based procurement reforms compressing drug-eluting stent margins. Outpatient surgical centers exhibit highest price sensitivity due to ambulatory payment classification constraints, while Japanese tertiary centers show lowest sensitivity under durable PMDA reimbursement codes.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk planning for cobalt-chromium alloy feedstock. Manufacturing concentrates in Germany, China, and Switzerland for specialized metallurgy and precision polymer synthesis. Raw material dependencies center on magnesium-rare-earth alloys, synthetic absorbable polymers, and platinum-iridium radiopaque markers. Single-source vulnerability concentrates in German foundry-grade magnesium supply. Distribution runs through integrated delivery networks and group purchasing organizations controlling hospital procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. FDA breakthrough device designation and PMDA reimbursement code durability create switching costs that protect incumbent positions.
For Market Incumbents: Pre-empt biodegradable stent substitution by securing captive magnesium alloy supply through backward integration into German or Chinese foundry operations. Fortify polymer-coating intellectual property against emerging materials-science entrants. Prioritize outpatient surgical center channel control before ambulatory payment classification shifts consolidate purchasing authority. For New Entrants and Emerging Players: Build out peripheral artery disease applications in United States outpatient settings where fracture risks of permanent metal drive biodegradable substitution. Target below-the-knee lesion subsets with rapid-deployment catheter systems optimized for same-day intervention economics. Pursue hospital procurement committee access through integrated stent-catheter platform bundling. For Investors and Strategic Acquirers: FDA breakthrough device designation reshapes the acquisition landscape by accelerating commercial timelines for first-generation bioresorbable entrants. Five-to-ten year viability favors materials-science specialists with degradation-control metallurgy patents over polymer-formulation generalists. Monitor EU MDR notified body capacity constraints as inflection signal for recertification timeline risk.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Pathway | Expedited review accelerates magnesium-alloy bioresorbable market entry for complex coronary lesions. |
| CE Marking Under EU MDR | Article 61 compliance separates polymer-coated platforms with robust clinical evidence from commodity alternatives. |
| Hospital System Partnership | Single-source contracts covering delivery systems and staff training lock in catheter-lab pull-through. |
| Reimbursement Strategy | PMDA durable procedure codes reward manufacturers with demonstrated superiority in complex lesion subsets. |
| Software Companion Development | Computational modeling of degradation kinetics enables personalized stent selection protocols. |
Research Methodology
Cross-validation between primary interviews with interventional cardiologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers and secondary validation against FDA filings, PMDA submissions, ClinicalTrials.gov records, and hospital procurement databases anchors the qualitative findings. Bottom-up procedure volume estimates and top-down market size triangulation reconcile segmentation outputs.
Calibration against historical adoption curves for drug-eluting and bare-metal stent generations shapes the analytical framework across the projection horizon. Segmentation dimensions span product type, end user, material platform, and application with regional regulatory cluster overlays. CAGRs derive from fitted growth curves adjusted for reimbursement policy inflections and materials-science breakthrough timing. Forecast inputs incorporate magnesium alloy supply constraints and EU MDR notified body capacity.
Practitioners should monitor FDA breakthrough device designation awards, EU MDR recertification delays, and China volume-based procurement auction results for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Engineering
Global Biomedical Tester Market
Biomedical Engineering
Global Continuous Bioprocessing Market
Biomedical Engineering
Tissue Engineered Skin Substitute Market
Biomedical Engineering
Medical Biomimetics Market
Biomedical Engineering
North America Lab-On-A-Chip and Microarrays (Biochip) Market
Biomedical Engineering
Biomems Market
Biomedical Engineering
Bioprosthetics Market
Biomedical Engineering
Bioimplants Market
Biomedical Engineering
Protein Engineering Market
Biomedical Engineering
Europe Bioresorbable Vascular Scaffold Market
Biomedical Engineering
Tissue Extraction System Market
Biomedical Engineering
North America Biosurgery Market
Biomedical Engineering
Tissue Engineering Market
Biomedical Engineering
Self-Inflating Tissue Expander Market
Biomedical Engineering
Global Robotic Prosthetic Market
Biomedical Engineering
Global Bionics Market