
 3D Bioprinted Human Tissue Market | 2026-2036
3D Bioprinted Human Tissue Market Size, Share, and Industry Trends Forecast 2026-2036
3D Bioprinted Human Tissue Market Outlook
North America is narrowing its lead in translational bioprinting capacity as academic medical centers expand GMP-compliant production facilities. Organovo Holdings Inc. leverages its proprietary NovoGen bioprinting platform to anchor liver tissue models for pharmaceutical toxicology. CELLINK sustains its position through aggressive instrumentation sales coupled with open-source bioink formulations. Cyfuse Biomedical K.K. competes via its Kenzan needle-array technology, which eliminates scaffold dependence in spheroid assembly.
3D bioprinted human tissue comprises living cells, biomaterial scaffolds, and signaling molecules deposited through computer-guided additive manufacturing to replicate native tissue architecture, with resolution thresholds typically ranging from 100–500 micrometers depending on the modality. The primary commercial purpose centers on replacing animal models in pharmaceutical screening and enabling patient-specific regenerative grafts. Extrusion-based systems occupy the dominant equipment share due to lower capital thresholds and broader bioink compatibility, while laser-assisted modalities command premium positioning in microvascular applications where spatial precision determines functional perfusion. Drug testing applications currently absorb the majority of contract revenue as pharmaceutical companies seek clinically predictive tissue models ahead of IND filings.
The FDA's tissue-engineered medical products framework, alongside ISO 10993 biocompatibility standards and the EU Medical Device Regulation via notified body pathways, collectively shape market access timelines and clinical evidence requirements. These regulatory architectures force developers to front-load quality management systems and biomaterial traceability protocols before commercial dialogue with end users. Stakeholders must monitor how the FDA's emerging 3D printing guidance for medical devices extends to living tissue constructs, as this boundary definition will determine which entrants require PMA versus 510(k) pathways.
Market Dynamics
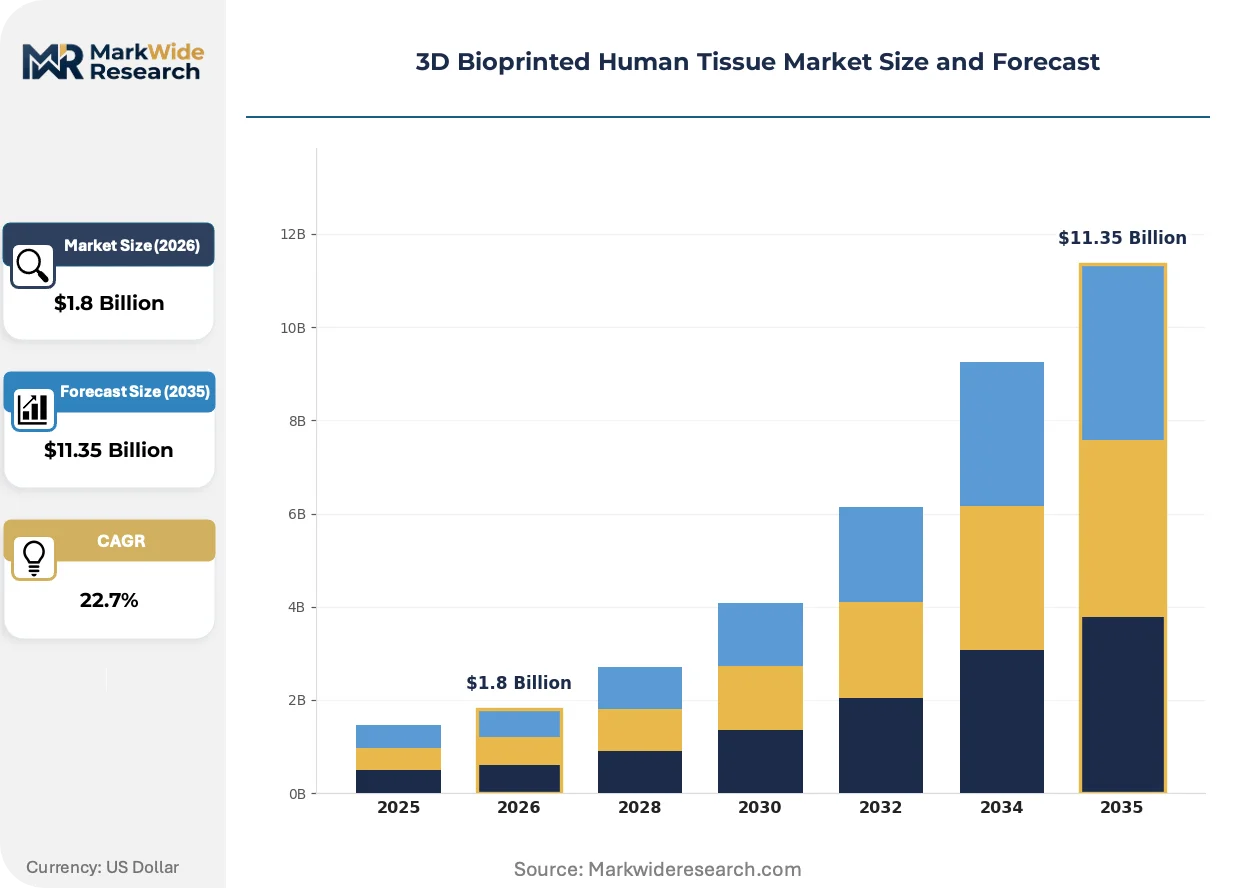
Extrusion-based bioprinting platforms are compressing capital barriers for pharmaceutical toxicology labs, while laser-assisted modalities capture microvascular applications where resolution thresholds determine functional perfusion outcomes.
Growth Catalysts
- FDA Tissue-Engineered Medical Products Framework:The evolving guidance accelerates clinical translation timelines for preclinical drug testing applications, reducing animal model dependency in pharmaceutical pipelines.
- Pharmaceutical Contract Research:Toxicology screening demand from IND-stage sponsors is pulling bioprinted liver and cardiac tissue models into standardized preclinical workflows.
- Boston-San Diego Biotech Clusters:Geographic concentration of academic medical centers and GMP-compliant production facilities is generating procurement volume and talent density.
Market Restraints
- Collagen and Gelatin Input Volatility:Bioink precursor costs fluctuate with agricultural supply chains, compressing margins for contract tissue manufacturers.
- Scaffold-Free Technical Limitations:Spheroid fusion rates in needle-array systems remain inconsistent for thick tissue constructs exceeding 5 millimeters.
- ISO 10993 Biocompatibility Burden:Extensive cytotoxicity and sensitization testing protocols extend development cycles before commercial dialogue with end users.
Strategic Opportunities
- Patient-Specific Regenerative Grafts:Autologous cell sourcing for burn reconstruction and cartilage repair represents underpenetrated clinical white space beyond pharmaceutical applications.
- EU Medical Device Regulation Pathways:Notified body certification for tissue-engineered products creates first-mover advantage for GMP-compliant European facilities.
- AI-Driven Print Path Optimization:Machine learning convergence with extrusion systems is reducing print failure rates and material waste in high-throughput screening workflows.
Industry Challenges
- Biofabrication Technician Shortage:Cross-disciplinary skill requirements spanning cell biology, materials science, and additive manufacturing limit production scale-up.
- Biomaterial Traceability Protocols:Quality management system implementation for cell line provenance and scaffold sourcing demands significant compliance infrastructure investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Bioprinted Human Tissue Market |
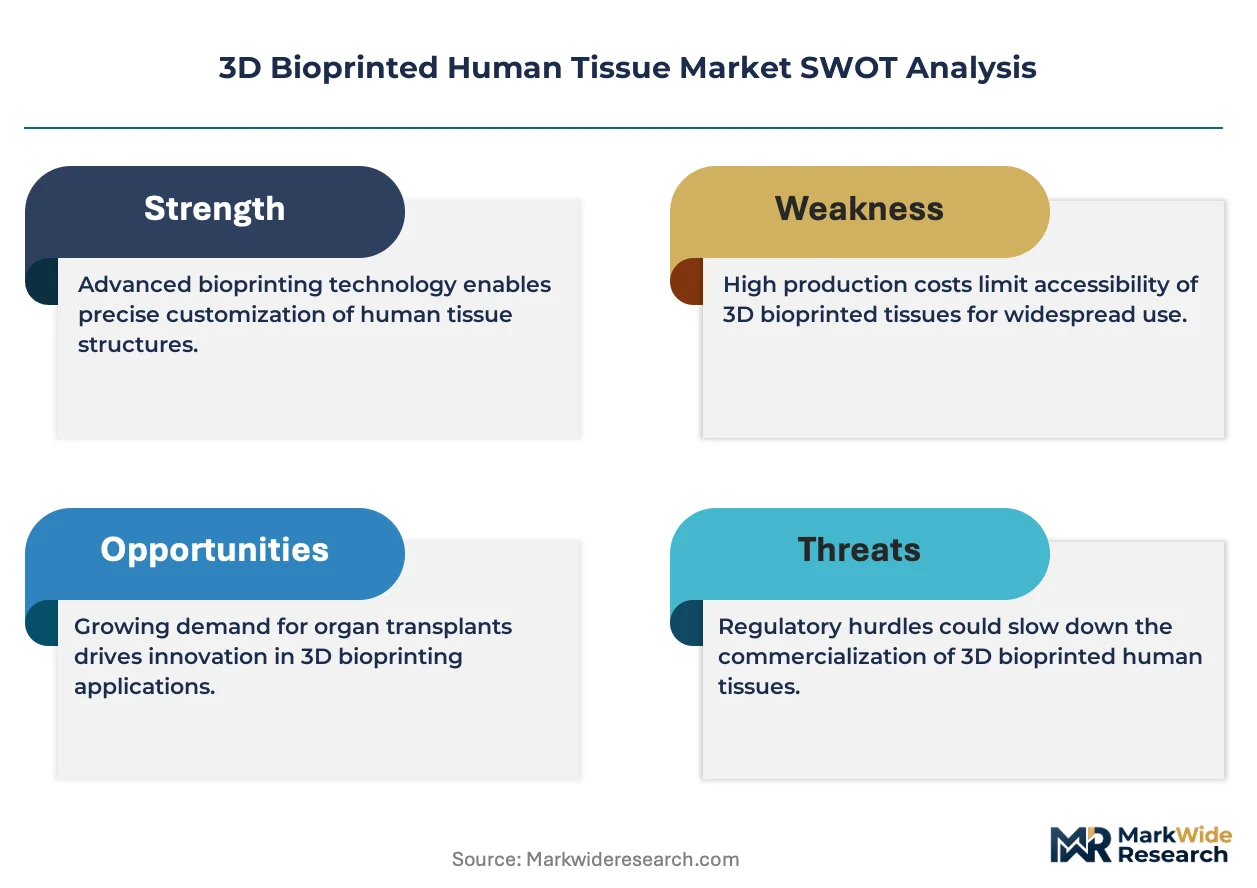
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $11.35 Billion |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organs, Tissues, Vascular Structures, Skin End User: Research Institutions, Pharmaceutical Companies, Biotech Firms, Hospitals Technology: Extrusion-Based, Inkjet Bioprinting, Laser-Assisted, Stereolithography Application: Drug Testing, Disease Modeling, Regenerative Medicine, Cosmetic Research |
| Companies Covered | Organovo Holdings Inc., CELLINK, Cyfuse Biomedical K.K., Aspect Biosystems Ltd, Prellis Biologics, Stratasys, 3D Systems, Inc., Allevi, Inc., EnvisionTEC, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Bioprinted Human Tissue Market Strategic Shifts
Resolution thresholds and vascular integration capabilities are becoming the primary axes of competitive differentiation, with modality selection increasingly dictated by end-use functional requirements rather than capital constraints alone.
Multi-material extrusion heads with integrated temperature control zones are rendering obsolete single-nozzle systems in pharmaceutical toxicology workflows. Contract research organizations running high-throughput screening programs are adopting these platforms at accelerated replacement cycles. The technology is compressing lead times for customized tissue geometries while reducing per-sample bioink waste.
REACH regulation amendments on nanomaterial classification are forcing European bioink formulators to requalify hydrogel compositions containing synthetic polymers. Industrial consequence includes reformulation costs and supply chain reconfiguration toward bio-derived alternatives. German and French notified bodies are experiencing backlog spikes as manufacturers front-load MDR technical documentation for tissue-engineered product categories.
Pharmaceutical procurement teams are unbundling tissue model supply from full-service toxicology contracts, creating direct purchasing relationships with bioprinting specialists. This disintermediation is compressing margins for legacy contract research organizations while rewarding GMP-certified tissue manufacturers with dedicated production capacity. The pattern is most visible in United States East Coast pharmaceutical clusters where sponsor companies maintain internal pharmacology groups.
3D Bioprinted Human Tissue Market Segmentation
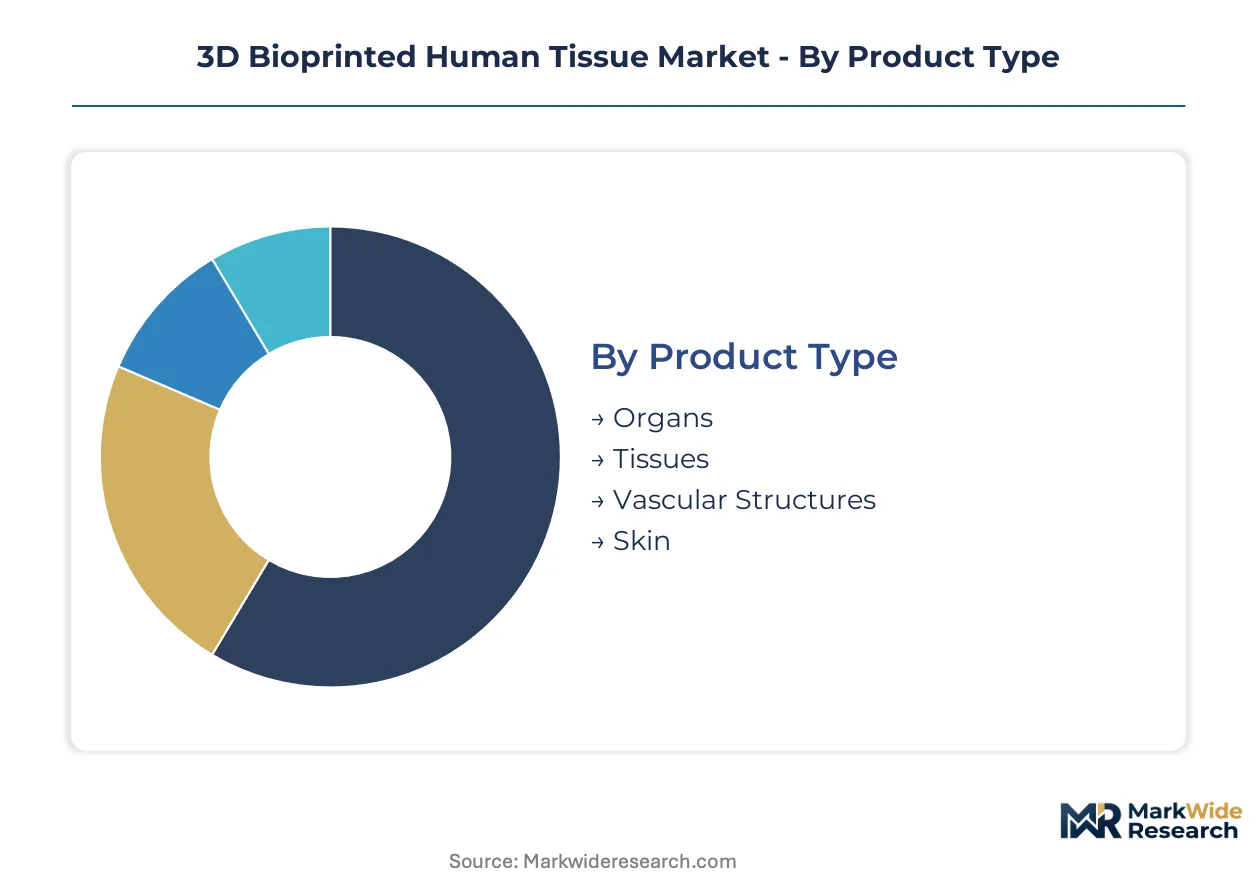
Segmentation in the 3D bioprinted human tissue market determines procurement patterns, capital allocation, and regulatory pathway selection. Each dimension—product type, end user, technology, and application—carries distinct margin profiles and compliance burdens that shape vendor strategy.
Product Type:
Cycle times vary dramatically across tissue categories, with skin constructs turning over in days while vascular structures require weeks of maturation.
- Tissues:Liver and cardiac tissue models dominate contract revenue from pharmaceutical toxicology programs. Boston and San Diego biotech clusters absorb the majority of output for IND-stage screening workflows.
- Organs:Kidney and liver constructs remain preclinical-stage products with extended development timelines. FDA tissue-engineered medical product guidance is compressing translation barriers for first-in-human trials.
- Skin:Epidermal and full-thickness dermal substitutes command premium pricing in burn reconstruction applications. Autologous sourcing protocols limit production scale despite clinical demand concentration.
- Vascular Structures:Microvascular networks require laser-assisted fabrication to achieve functional perfusion thresholds. Resolution constraints restrict commercial viability to specialized microfluidic integration contracts.
Tissues anchor the volume base while organs gain share at the steepest rate as clinical translation timelines compress.
End User:
Customer types stratify by procurement sophistication, with pharmaceutical companies demanding GMP certification while research institutions prioritize flexibility.
- Pharmaceutical Companies:Toxicology screening divisions now unbundle tissue procurement from full-service CRO contracts. Direct purchasing relationships with GMP-certified manufacturers are displacing legacy intermediaries.
- Research Institutions:Academic medical centers drive instrumentation demand through shared core facility models. Federal grant funding cycles create lumpy procurement patterns for extrusion-based platforms.
- Biotech Firms:Venture-backed developers concentrate in Boston and San Diego clusters with dedicated bioprinting capabilities. Burn rate constraints favor open-source bioink formulations over proprietary supply agreements.
- Hospitals:Burn centers and reconstructive surgery departments represent emerging clinical demand for patient-specific grafts. Reimbursement coding gaps currently limit procurement authorization.
Pharmaceutical companies anchor the volume base while hospitals expand most quickly as regenerative medicine reimbursement frameworks mature.
Technology:
Capital thresholds and resolution capabilities create distinct positioning tiers, with extrusion systems saturating pharmaceutical labs while laser platforms capture microvascular niches.
- Extrusion-Based:Pneumatic and mechanical extrusion systems dominate installed base through lower capital barriers and broader bioink compatibility. Multi-material print heads with temperature control zones are accelerating replacement cycles in high-throughput screening environments.
- Laser-Assisted:Photopolymerization modalities achieve sub-100 micrometer resolution for microvascular network fabrication. Functional perfusion requirements in organ-on-chip applications justify premium positioning despite limited throughput.
- Inkjet Bioprinting:Droplet deposition systems offer cell viability advantages for sensitive primary cell populations. Shear stress limitations restrict application to thin tissue constructs under 2 millimeters.
- Stereolithography:Mask-based projection systems enable rapid batch processing of standardized geometries. Scaffold dependence limits adoption for applications requiring cell-laden bioinks.
Extrusion-based platforms anchor the volume base while laser-assisted systems climb the fastest as microvascular applications mature.
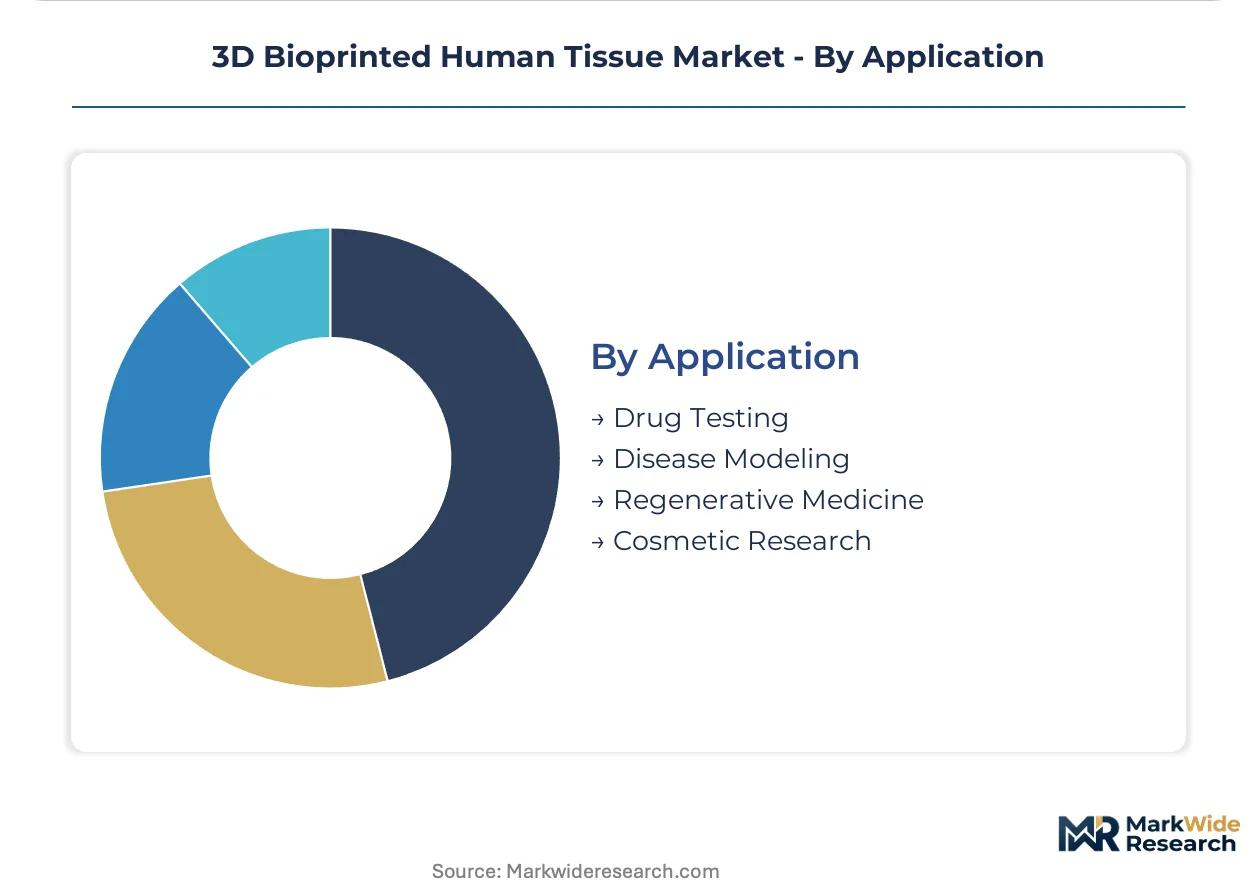
Application:
Revenue concentration and regulatory complexity diverge sharply across use cases, with drug testing absorbing the majority of contract revenue while regenerative medicine carries the highest compliance burden.
- Drug Testing:Liver and cardiac tissue models for ADMET screening represent the primary commercial revenue stream. Pharmaceutical sponsors seek clinically predictive alternatives to animal models ahead of IND filings.
- Regenerative Medicine:Patient-specific grafts for cartilage repair and burn reconstruction command premium pricing with autologous cell sourcing. ISO 10993 biocompatibility protocols extend development cycles before commercial dialogue.
- Disease Modeling:Patient-derived induced pluripotent stem cell platforms enable mechanistic studies in oncology and neurology. Academic consortia drive demand through multi-site grant-funded collaborations.
- Cosmetic Research:Dermal irritation and sensitization testing for personal care products represents a compliance-driven niche. REACH nanomaterial classification amendments are forcing reformulation of synthetic hydrogel compositions.
Drug testing anchors the volume base while regenerative medicine gains share fastest as GMP production capacity expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA tissue-engineered medical product guidance anchors United States market development, while EMA pathways and notified body frameworks in Europe compress translation timelines for preclinical applications.
United States
Pharmaceutical toxicology screening and IND-stage drug development drive procurement volume from Boston and San Diego biotech clusters. FDA guidance on 3D printing for medical devices is extending to living tissue constructs, determining PMA versus 510(k) pathway requirements. Academic medical centers in Massachusetts and California are expanding GMP-compliant production facilities to serve contract research demand.
Germany
REACH nanomaterial classification amendments are forcing bioink formulators to requalify hydrogel compositions containing synthetic polymers. German notified bodies are experiencing backlog spikes as manufacturers front-load MDR technical documentation for tissue-engineered product categories. The Eindhoven-to-Munich corridor concentrates instrumentation development and bioink supply chain reconfiguration.
Japan
PMDA regulatory frameworks for regenerative medicine are accelerating clinical translation for patient-specific graft applications. METI funding programs support academic-industrial partnerships in spheroid assembly and scaffold-free fabrication. Tokyo and Osaka metropolitan areas host concentrated bioprinting core facilities at university medical centers.
United Kingdom
Research council funding for organ-on-chip and disease modeling applications sustains instrumentation demand at shared academic facilities. MHRA post-Brexit regulatory autonomy is creating parallel consultation pathways for tissue-engineered product developers. London and Cambridge clusters concentrate venture-backed biotech firms with dedicated bioprinting capabilities.
South Korea
MFDS fast-track designation for regenerative medical products is compressing approval timelines for autologous graft applications. Government biotechnology initiatives fund multi-material extrusion platform development for high-throughput screening. Seoul Capital Area and Busan-Ulsan regions concentrate contract tissue manufacturing and pharmaceutical R&D partnerships.
3D Bioprinted Human Tissue Market Competitive Environment
Platform specialists and diversified instrumentation incumbents split the market between application-specific depth and capital equipment breadth. The vendor base concentrates around three strategic archetypes: bioprinting-native platform developers, diversified additive manufacturing incumbents, and contract tissue manufacturers with captive production technology. Competitive moves center on multi-material print head development and GMP certification capacity expansion to serve pharmaceutical procurement requirements.
Within the bioprinting-native tier, Organovo Holdings Inc. and CELLINK occupy positions representing liver tissue toxicology models and open-source bioink instrumentation strategies respectively. Cyfuse Biomedical K.K. exemplifies scaffold-free fabrication approaches through its needle-array technology specialization. These three companies anchor distinct technical vectors—extrusion-based tissue models, accessible research platforms, and spheroid assembly systems—that structure competitive positioning across pharmaceutical and academic end-user segments.
| Leading Market Players |
|---|
| Organovo Holdings Inc. |
| CELLINK |
| Cyfuse Biomedical K.K. |
| Aspect Biosystems Ltd |
| Prellis Biologics |
| Stratasys |
| 3D Systems, Inc. |
| Allevi, Inc. |
| EnvisionTEC, Inc. |
| Others |
Value Chain & Pricing Dynamics
The Rotterdam-to-Boston pharmaceutical freight corridor anchors cost dynamics for collagen and gelatin bioink precursors, compressing margins for European contract manufacturers while enabling premium pricing for GMP-certified tissue producers in Massachusetts and California. Supply concentration in agricultural processing regions intersects with FDA certification tiers to stratify pricing across pharmaceutical toxicology labs, academic medical centers, and emerging hospital burn centers.
Pricing Analysis
Geographic price spreads between United States East Coast pharmaceutical clusters and European research institutions reflect ISO 10993 certification burdens and GMP facility overhead differentials. Three-tier pricing structure across GMP-certified, research-grade, and preclinical tiers separates Organovo's liver toxicology models from open-source bioink platforms and unvalidated spheroid systems. Pricing pressure stems from collagen input volatility linked to agricultural supply chains. Pharmaceutical procurement teams exhibit lowest price sensitivity due to IND filing timelines, while venture-backed biotech firms in San Diego face acute burn-rate constraints.
Supply Chain Analysis
Extended payment terms from pharmaceutical sponsors now reach ninety days for contract tissue manufacturers, straining working capital for bioink formulators without captive collagen sourcing. Supply concentrates in United States, Germany, and Japan for extrusion platforms and laser-assisted systems. Raw material dependencies center on porcine-derived collagen, recombinant growth factors, and photopolymerizable hydrogels. Single-source vulnerability pervades recombinant protein supply. Distribution runs through direct procurement relationships with GMP-certified manufacturers, displacing legacy CRO intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The 3D bioprinted human tissue market represents high-growth disruption as FDA tissue-engineered medical product guidance compresses clinical translation timelines for preclinical drug testing and regenerative graft applications.
For Market Incumbents: Pre-empt margin compression in pharmaceutical toxicology by securing backward integration into collagen processing and expanding GMP capacity in Boston and San Diego clusters. CELLINK's open-source instrumentation strategy and Cyfuse's scaffold-free fabrication approaches threaten extrusion-based tissue model incumbents. Certification investment in ISO 10993 and FDA QMS compliance anchors pricing power against research-grade competitors. For New Entrants and Emerging Players: Establish a beachhead in patient-specific burn reconstruction grafts, where reimbursement coding gaps currently limit incumbent presence and autologous cell sourcing protocols favor nimble specialists. Hospital procurement authorization for regenerative medicine represents the most penetrable end-user segment beyond saturated pharmaceutical screening workflows. Go-to-market execution through burn center clinical champion programs accelerates adoption ahead of formal reimbursement frameworks. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors GMP-certified contract tissue manufacturers with dedicated pharmaceutical relationships over pure-play instrumentation vendors facing replacement-cycle saturation. Five-to-ten year viability hinges on clinical translation success for organ constructs and vascular networks. The signal to watch is FDA PMA versus 510(k) pathway determinations for living tissue constructs, which will reshape capital requirements and competitive moats.| Strategic Initiative | Industry Significance |
|---|---|
| GMP Certification Expansion | FDA tissue-engineered medical product guidance elevates certified facility scarcity for pharmaceutical contracts. |
| Multi-Material Print Head Development | Temperature-controlled extrusion systems reduce bioink waste in high-throughput IND-stage screening workflows. |
| Backward Integration into Collagen Processing | Agricultural supply chain volatility threatens margins for contract manufacturers without captive precursor sourcing. |
| AI-Driven Print Path Optimization | Machine learning convergence with extrusion platforms compresses failure rates in pharmaceutical toxicology programs. |
| EU MDR Technical Documentation Front-Loading | German and French notified body backlogs create first-mover advantage for European GMP facility investment. |
Study Parameters
Initial hypotheses were tested against primary input from pharmaceutical toxicology directors, GMP facility operations managers, bioink formulation scientists, and burn center reconstructive surgeons, then refined through secondary validation against FDA tissue-engineered medical product guidance documents, ISO 10993 biocompatibility standards, EMA scientific committee opinions, ClinicalTrials.gov entries for bioprinted tissue interventions, and SEC filings from publicly traded platform developers. Bottom-up instrumentation demand modeling and top-down pharmaceutical R&D spending allocation were triangulated to converge volume estimates.
Demand-supply balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning tissue type, end-user procurement sophistication, extrusion versus laser-assisted modality, and drug testing versus regenerative medicine application. CAGRs were derived from pharmaceutical toxicology contract growth rates and clinical translation pipeline maturation. Industry-specific forecast inputs incorporated FDA guidance evolution timelines and notified body certification capacity constraints.
Stress conditions across collagen price volatility, FDA pathway determinations, and reimbursement framework development were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory acceleration and clinical adoption curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Engineering
Bioabsorbable Implant Market
Biomedical Engineering
Global Robotic Prosthetic Market
Biomedical Engineering
Bioartificial Renal Assist Devices Market
Biomedical Engineering
North America Biosurgery Market
Biomedical Engineering
Bioactive Bone Grafts Market
Biomedical Engineering
Large and Small-Scale Bioprocessing Market
Biomedical Engineering
Bioink Market
Biomedical Engineering
Biological Implants Market
Biomedical Engineering
Non-Surgical Bio-Implants Market
Biomedical Engineering
Self-Inflating Tissue Expander Market
Biomedical Engineering
Protein Engineering Market
Biomedical Engineering
Tissue Expansion Market
Biomedical Engineering
North America Lab-On-A-Chip and Microarrays (Biochip) Market
Biomedical Engineering
Artificial Organ Bank Market
Biomedical Engineering
Bioabsorbable Osteosynthesis Devices Market
Biomedical Engineering
Bio-Engineered Stent Market