
 Industrial Bioprocessing Market | 2026-2036
Industrial Bioprocessing Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Bioprocessing Market Outlook
The gap between stainless-steel systems and single-use disposable platforms is consolidating around total cost of ownership and batch flexibility. Thermo Fisher Scientific leverages its chromatography and analytical instrument portfolio to anchor integrated workflow offerings across upstream and downstream stages. Sartorius AG differentiates through membrane and filtration specialization that sustains premium positioning in cell-culture media supply.
Industrial bioprocessing encompasses the large-scale cultivation of microorganisms, mammalian cells, or enzymes in controlled bioreactor environments, typically operating at parameters between 0.5 and 20,000 liters working volume, to manufacture therapeutic proteins, biofuels, or specialty chemicals. Fermentation equipment retains the largest installed base but faces margin compression as continuous production technology captures growth in monoclonal antibody manufacturing. Downstream processing commands disproportionate capital allocation because purification and separation steps determine final yield economics in bio-manufacturing applications.
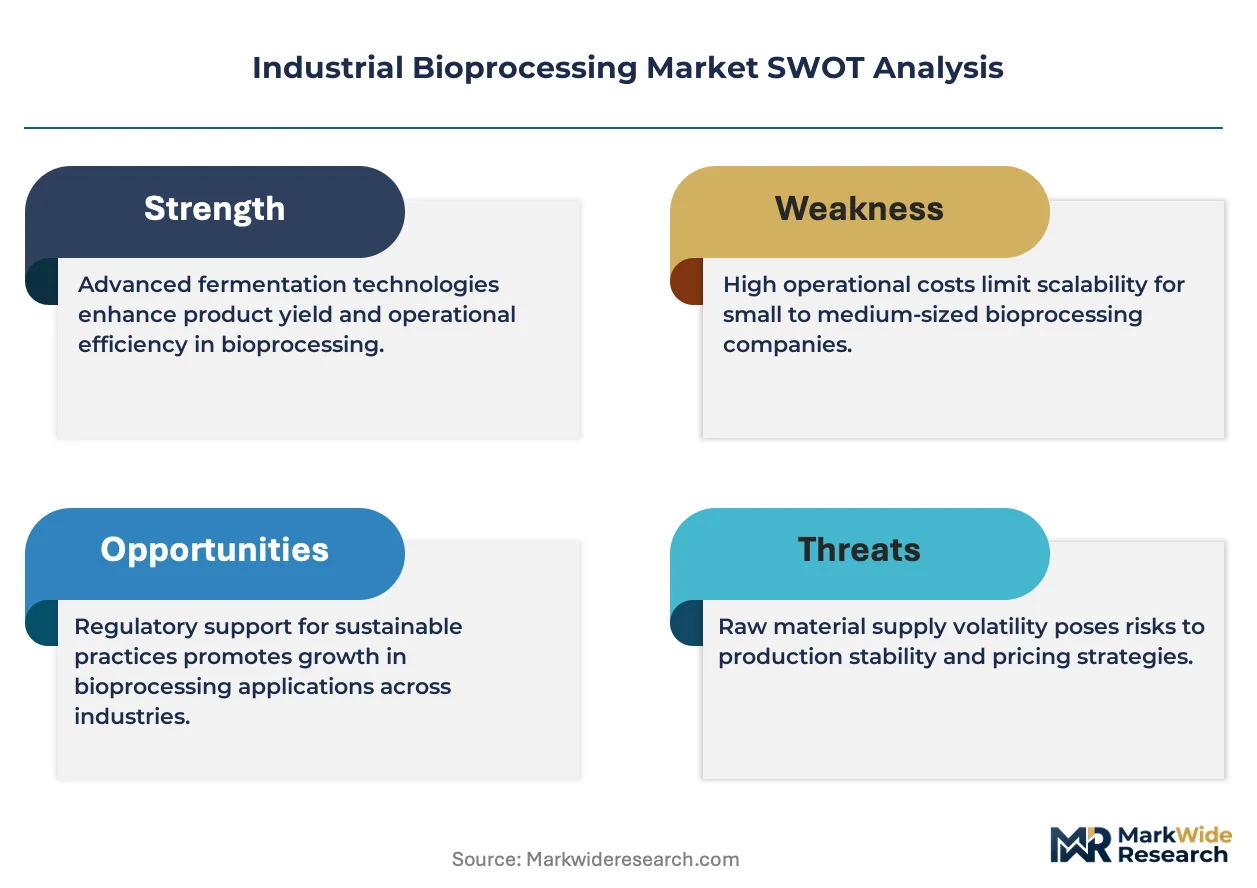
FDA, EMA, and ISO 13485 standards govern equipment qualification, process validation, and traceability requirements that shape procurement decisions across pharmaceutical and food-grade bioprocessing facilities. The EU Green Deal and REACH frameworks additionally constrain solvent selection and waste-stream management in European bioproduction sites. Stakeholders must weigh single-use platform conversion costs against regulatory compliance burdens when planning capacity expansions.
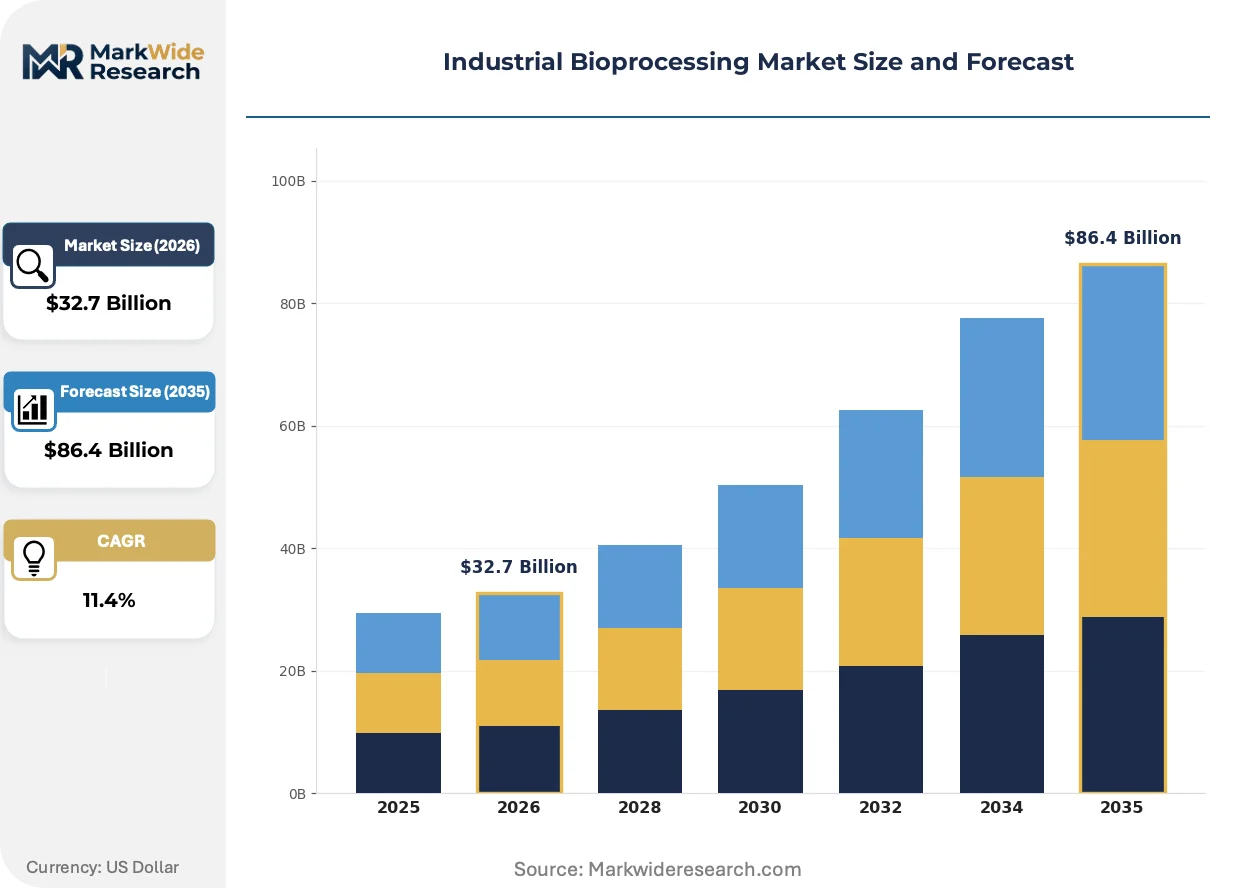
Market Dynamics
The transition from stainless-steel to single-use bioreactor platforms is compressing capital deployment timelines while EMA and FDA purity mandates force equipment qualification upgrades across pharmaceutical manufacturing networks.
Growth Catalysts
- EMA Annex 1 revisions:The 2022 update to EU GMP guidelines for sterile manufacturing elevates contamination control requirements, accelerating facility retrofit demand for closed-system bioreactor installations.
- Cell-culture media innovation:Chemically defined and animal-component-free formulations reduce batch-to-batch variability, enabling consistent monoclonal antibody titers that justify single-use platform investments.
- Germany's bioprocessing cluster:Concentrated equipment manufacturing in Göttingen and Hamburg creates supplier proximity advantages for European pharmaceutical producers seeking rapid technical support.
Market Restraints
- Filtration membrane supply concentration:PES and PVDF membrane production concentrates among a limited supplier base, creating input vulnerability for downstream purification operations.
- ISO 13485 validation timelines:Extended equipment qualification periods for quality management certification delay facility commissioning and revenue recognition.
- Stainless-steel installed base inertia:Sunk capital in existing fermentation infrastructure and trained operator pools slow platform conversion decisions despite TCO advantages.
Strategic Opportunities
- Continuous bioprocessing adoption:Perfusion cell-culture technology integration with single-use bioreactors enables higher volumetric productivity for contract manufacturing organizations.
- EU Green Deal solvent restrictions:REACH framework constraints on hazardous waste streams create demand for aqueous-based purification alternatives and closed-loop solvent recovery systems.
- India biologics manufacturing expansion:CDSCO regulatory pathway alignment with ICH standards positions Indian facilities for export-oriented biosimilar production capacity.
Industry Challenges
- Process analytical technology integration:PAT implementation requires cross-functional expertise spanning bioprocess engineering, data science, and regulatory affairs that remains scarce in hiring markets.
- Legacy SCADA system interoperability:Digital retrofit of existing stainless-steel facilities with modern distributed control systems demands customized validation protocols that extend project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Bioprocessing Market |
| Market Size in 2026 | $32.7 Billion |
| Market Size in 2035 | $86.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fermentation, Enzymes, Bioreactors, Cell Cultures Technology: Scale-Up Processes, Continuous Production, Downstream Processing, Biopreservation End User: Pharmaceuticals, Food & Beverages, Biofuels, Agriculture Application: Waste Treatment, Bio-manufacturing, Bio-remediation, Biopolymer Production |
| Companies Covered | Thermo Fisher Scientific, Sartorius AG, Merck KGaA, Danaher Corporation, Lonza Group, Corning Incorporated, Eppendorf, Getinge AB, Repligen Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Bioprocessing Market Strategic Shifts
Digital twin deployment and real-time release testing protocols are compressing quality assurance cycles while redefining competitive differentiation across upstream and downstream bioprocessing stages.
Single-use sensors for pH, dissolved oxygen, and biomass monitoring are converging with cloud-based data platforms to enable predictive process control. Contract development and manufacturing organizations are deploying these integrated systems fastest, attracted by reduced validation burden and faster batch turnaround. This convergence is compressing the competitive gap between established stainless-steel operators and agile single-use entrants.
REACH authorization requirements for chromatography solvents are forcing substitution of acetonitrile and methanol with biosourced alternatives in European purification operations. The industrial consequence is reformulation of downstream protocols and revalidation of established separation methods. Monoclonal antibody producers in Germany and Switzerland are responding fastest, driven by EMA inspection intensity and customer sustainability mandates.
Equipment-as-a-service contracting is displacing traditional capital purchase models among mid-scale biopharma manufacturers. Leasing arrangements with bundled maintenance and consumables supply are capturing share from distributor channels in North American and European markets. CDMOs with variable capacity needs represent the most visible adopters, prioritizing operational flexibility over asset ownership.
Industrial Bioprocessing Market Segmentation
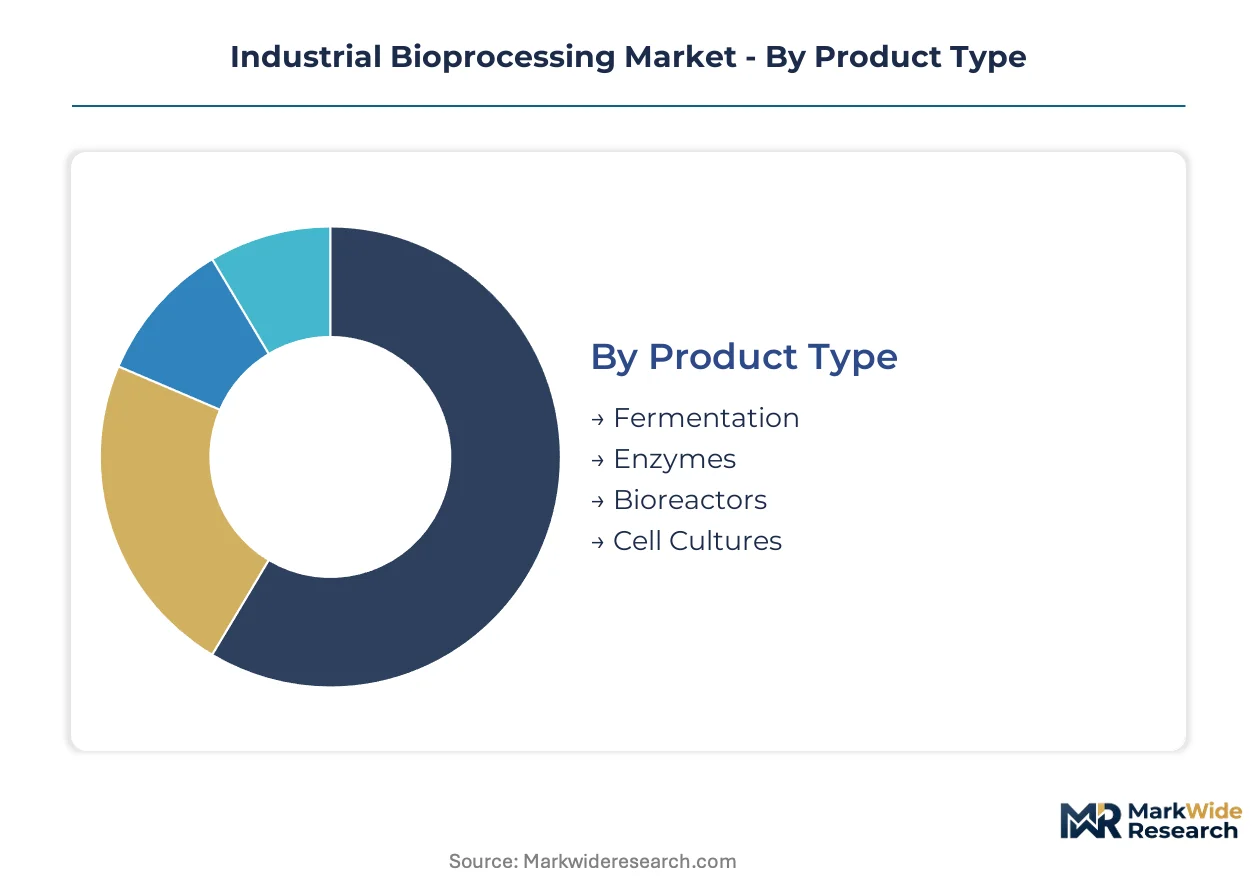
Industrial bioprocessing segmentation reveals divergent capital deployment patterns across equipment types and production modalities. Buyer priorities shift between batch flexibility, regulatory compliance burden, and total cost of ownership depending on end-use application and facility scale.
Product Type:
Procurement decisions center on working volume requirements and contamination risk tolerance across therapeutic protein, biofuel, and specialty chemical applications.
- Bioreactors:Stainless-steel systems dominate installed base above 2,000 liters working volume, while single-use platforms capture new capacity additions below 1,000 liters driven by EMA Annex 1 contamination control mandates. German pharmaceutical manufacturers anchor demand for advanced stirred-tank and wave-mixed configurations.
- Fermentation:Traditional microbial cultivation retains dominance in biofuel and commodity chemical production, operating at 10,000-20,000 liter scales with established operator expertise pools. Existing stainless-steel infrastructure and validated protocols create conversion inertia despite single-use alternatives.
- Enzymes:Cell-free and immobilized biocatalyst systems enable continuous processing with reduced bioreactor footprint requirements.
- Cell Cultures:Mammalian expression systems command premium positioning for monoclonal antibody production with chemically defined media formulations.
Bioreactors lead on scale; cell cultures lead on momentum.
Technology:
Technology selection determines facility throughput economics and regulatory qualification complexity across upstream and downstream operations.
- Downstream Processing:Chromatography and filtration operations absorb 60-70% of capital allocation in biologics facilities because purification yield directly determines manufacturing cost per gram. REACH solvent restrictions in Europe are accelerating aqueous-based separation method development.
- Continuous Production:Perfusion cell-culture technology integrated with single-use bioreactors enables volumetric productivity gains that justify platform conversion costs for contract manufacturing organizations with variable demand profiles.
- Scale-Up Processes:Process analytical technology integration and digital twin deployment compress timeline from pilot to commercial manufacturing.
- Biopreservation:Cryopreservation and hypothermic storage systems maintain cell viability across distribution networks for cell therapy applications.
Downstream processing dominates capital intensity; continuous production expands most quickly.
End User:
End-user concentration shapes equipment specification requirements and service contract structures across regulated and industrial applications.
- Pharmaceuticals:FDA and EMA sterile manufacturing guidelines enforce closed-system requirements and extensive process validation documentation. Single-use platform adoption concentrates among monoclonal antibody producers seeking reduced cross-contamination risk and faster batch turnaround.
- Biofuels:Fermentation-based ethanol and advanced biofuel production operates at commodity margin structures that favor stainless-steel durability and economies of scale over single-use flexibility.
- Food & Beverages:Enzyme-assisted processing and fermentation applications for ingredient production follow FSSAI and FDA food-grade standards with lower qualification burdens than pharmaceutical applications.
- Agriculture:Microbial inoculant and biopesticide manufacturing serves regional distribution networks with smaller batch requirements.
Pharmaceuticals lead on value concentration; biofuels lead on installed volume.
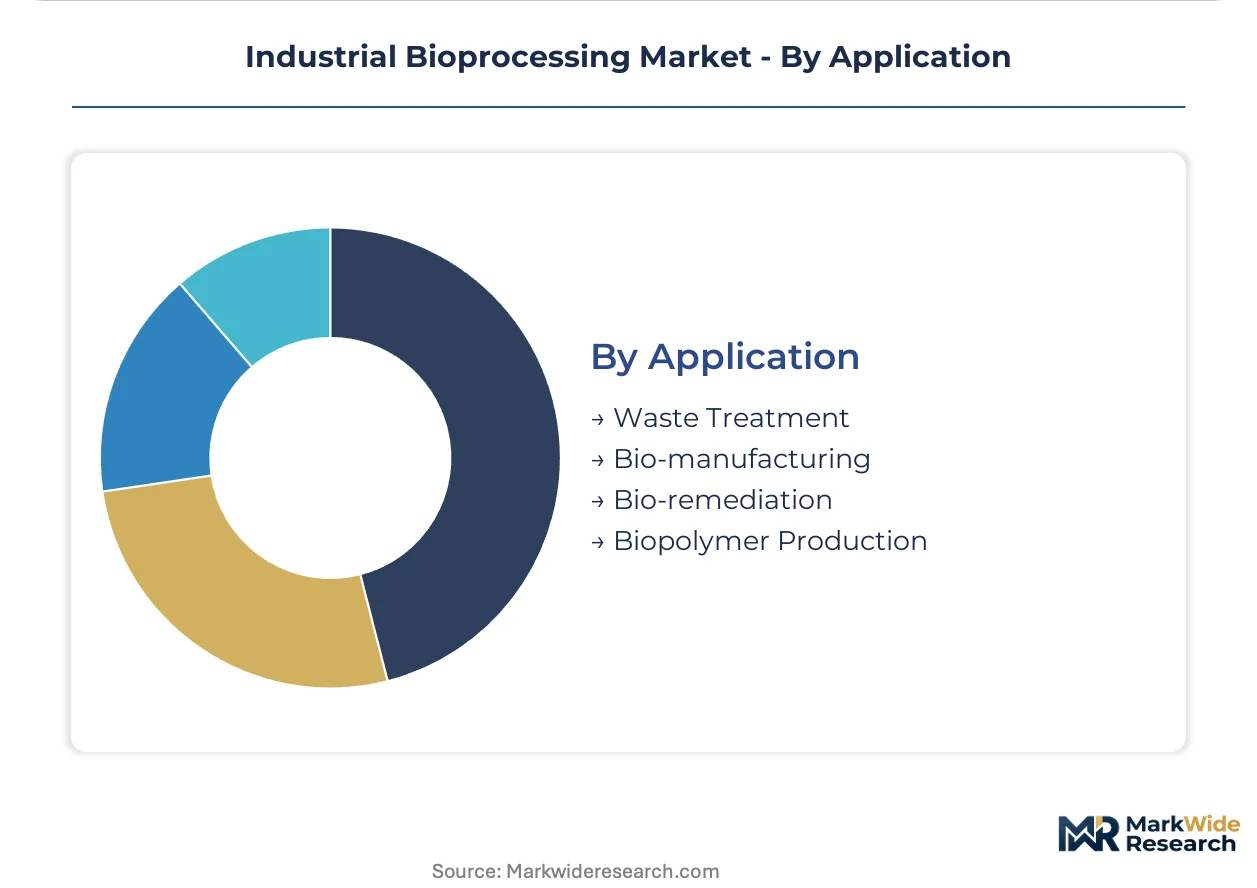
Application:
Application-specific yield requirements and regulatory scrutiny levels drive divergent technology platform preferences across industrial bioprocessing deployments.
- Bio-manufacturing:Therapeutic protein and biosimilar production commands highest purity standards with multi-stage purification trains and extensive batch release testing. CDSCO alignment with ICH standards positions Indian facilities for export-oriented capacity expansion.
- Biopolymer Production:Polyhydroxyalkanoates and other bio-based materials face cost-competitiveness pressures against petroleum-derived alternatives that favor continuous fermentation and integrated downstream recovery.
- Waste Treatment:Anaerobic digestion and aerobic bioremediation systems process agricultural and industrial effluents with lower capital intensity than pharmaceutical applications.
- Bio-remediation:Microbial degradation of soil and groundwater contaminants operates at environmental consulting margins with project-based equipment deployment.
Bio-manufacturing leads on revenue intensity; biopolymer production gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands the highest bioprocessing equipment density per capita, while the United States generates larger absolute facility investment volumes. India and China are expanding contract manufacturing capacity fastest. Switzerland maintains premium positioning through specialized precision engineering.
United States
FDA sterile manufacturing guidelines and IRA biomanufacturing incentives drive single-use platform conversions among Boston and San Francisco biotech clusters. The agency's 2023 quality management system updates accelerate facility qualification timelines. Greater Boston anchors monoclonal antibody production with concentrated CDMO capacity expansion.
Germany
EMA Annex 1 contamination control mandates and EU Green Deal solvent restrictions reshape purification protocol investments across pharmaceutical networks. REACH authorization requirements for chromatography inputs force aqueous-based separation method adoption. Göttingen and Hamburg equipment manufacturing clusters supply rapid technical support to European producers.
Switzerland
Swissmedic inspection intensity and customer sustainability mandates accelerate biosourced solvent substitution in downstream operations. The country's precision engineering heritage supports premium positioning in membrane and filtration specialization. Basel and Zurich regions concentrate biologics production with integrated continuous processing pilot deployments.
India
CDSCO regulatory pathway alignment with ICH standards positions export-oriented biosimilar capacity expansion. Government PLI scheme incentives for domestic API and biologics manufacturing reduce import dependency. Maharashtra and Telangana biotech parks attract multinational facility investments with trained operator pools.
China
NMPA biologics approval pathway reforms and dual carbon goals constrain energy-intensive fermentation operations. MIIT advanced manufacturing initiatives support domestic bioreactor equipment substitution. Yangtze River Delta biopharma clusters integrate perfusion technology with local supply chain development.
Industrial Bioprocessing Market Competitive Environment
Top-tier vendors anchor integrated workflow offerings, while mid-scale specialists concentrate on membrane and filtration subsystems. The vendor base stratifies across full-platform providers, consumables-dominant players, and precision component fabricators. Two strategic archetypes dominate: chromatography-anchored integrators and single-use technology pure-plays. Consolidation pressure favors M&A-driven portfolio expansion and geographic footprint extension into Asian contract manufacturing hubs.
Among Germany-based precision engineering groups, Sartorius AG and Merck KGaA exemplify membrane specialization and integrated workflow anchoring respectively. Thermo Fisher Scientific represents the chromatography-anchored integrator archetype with analytical instrument portfolio leverage. These three entities occupy positions across the premium-to-standard tier boundary, reflecting divergent bets on platform integration depth versus component specialization.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Sartorius AG |
| Merck KGaA |
| Danaher Corporation |
| Lonza Group |
| Corning Incorporated |
| Eppendorf |
| Getinge AB |
| Repligen Corporation |
| Others |
Value Chain & Pricing Dynamics
EMA Annex 1 contamination control mandates are forcing pharmaceutical manufacturers toward closed-system single-use bioreactor platforms, compelling equipment suppliers to absorb qualification documentation costs and compress delivery timelines to defend contract positions.
Pricing Analysis
Capacity additions in India and China are reshaping price floors for standard-grade fermentation equipment while premium bioreactor systems retain pricing power through integrated PAT bundles and validation support. Three-tier pricing structure across premium, standard, and economy levels separates GMP-validated pharmaceutical configurations from food-grade and research-scale alternatives. Cost compression in stainless-steel retrofit services is intensifying because CDMOs demand faster commissioning timelines. Contract manufacturing organizations exhibit highest price sensitivity due to variable utilization rates, while Big Pharma biologics divisions prioritize total cost of ownership over unit pricing.
Supply Chain Analysis
PES and PVDF membrane supply rests on German and Japanese specialty polymer producers with limited qualified secondary sources for pharmaceutical-grade filtration media. Chromatography resin production draws from agarose and synthetic polymer feedstocks concentrated in North American and European chemical processing hubs. Single-source vulnerability pervades gamma-irradiation sterilization services for single-use consumables, creating bottleneck exposure for just-in-time bioproduction networks. Distribution runs through authorized distributor channels with technical service bundling, though equipment-as-a-service contracting is displacing traditional capital purchase models among mid-scale manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where EMA and FDA purity standard convergence is elevating specification premiums for validated closed-system platforms over commodity fermentation alternatives.
For Market Incumbents: Lock in membrane and filtration specialization advantages through captive supply agreements with PES resin producers, insulating margin positions against raw material volatility. Deepen integration with CDMO technical service teams to embed consumables replenishment into long-term facility operating contracts, creating switching costs that emerging single-use pure-plays cannot match. For New Entrants and Emerging Players: CDMO technical partnerships offer the most penetrable channel for aqueous-based purification alternatives that address REACH solvent restrictions without incumbent chromatography portfolio cannibalization. Target Indian biosimilar manufacturers seeking ICH-aligned equipment qualification support with bundled validation documentation and local operator training programs as the primary go-to-market angle. For Investors and Strategic Acquirers: Asymmetric upside sits with precision component fabricators holding ISO 13485 certification and membrane casting capabilities that strategic buyers cannot replicate through greenfield investment. Long-term viability centers on continuous bioprocessing technology integration expertise that bridges upstream perfusion cell-culture with downstream real-time release testing protocols. Watch FDA quality management system enforcement intensity as the signal indicating inflection toward premium-tier equipment specification premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Bioprocessing Technology Integration | Perfusion cell-culture adoption enables volumetric productivity gains that justify single-use platform conversion costs for CDMOs. |
| Backward Integration into Membrane Resin Supply | Captive PES and PVDF polymer sourcing insulates filtration specialists against raw material concentration risks. |
| Equipment-as-a-Service Contracting Expansion | Leasing arrangements with bundled consumables capture share from distributor channels among variable-capacity manufacturers. |
| Aqueous-Based Purification Protocol Development | REACH-compliant solvent substitution creates differentiation for downstream processing vendors in European pharmaceutical networks. |
| Process Analytical Technology Platform Integration | Real-time release testing capability compresses quality assurance cycles and anchors premium positioning for integrated workflow providers. |
Study Parameters
Bottom-up biologics manufacturing capacity modeling reconciled against top-down bioreactor equipment shipment tracking forms the analytical core of this study. Primary interviews with bioprocess engineering directors, regulatory affairs leads at pharmaceutical manufacturers, CDMO procurement officers, and filtration membrane R&D heads combined with secondary validation against FDA 483 observation databases, EMA inspection reports, and SEC 10-K equipment supplier filings. Top-down trade data and customs records triangulate against bottom-up facility capacity announcements.
Historical trendline analysis of stainless-steel versus single-use platform adoption rates, coupled with EMA Annex 1 implementation timeline phasing, informs the projection framework across the analysis window. Segmentation dimensions include product type, technology modality, end-use application, and regional regulatory cluster. CAGRs derive from equipment replacement cycle analysis and capacity expansion announcement tracking. Forecast inputs incorporate CDSCO regulatory pathway alignment progress and EU Green Deal solvent restriction enforcement intensity.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to continuous bioprocessing technology maturation and perfusion cell-culture titers achieving commercial scale. Forecasts reflect documented assumptions regarding regulatory inspection intensity and single-use platform validation burden reduction. Supply chain disruption from filtration membrane raw material constraints or gamma-irradiation sterilization capacity bottlenecks could revise equipment delivery timelines and revenue recognition patterns. A small set of triggers—FDA quality management system updates, REACH authorization list expansions, and CDSCO ICH guideline adoption pace—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Microbiology
Mineral Yeast Market
Industrial Microbiology
Microbial Culture Market
Industrial Microbiology
Real Time Continuous Microbiological Monitoring Systems Market
Industrial Microbiology
Global Microbial Fermentation Technology Market
Industrial Microbiology
Microbial Therapeutic Products Market
Industrial Microbiology
Freeze-Dried Microbial Food Culture Market
Industrial Microbiology
Probiotic Yeast Market
Industrial Microbiology
Global Arabinogalactan Market
Industrial Microbiology
Microbial Cell Banking Market
Industrial Microbiology
Bacterial Amylase Market
Industrial Microbiology
Microbial-Derived Fiber Market
Industrial Microbiology
Global Escherichia Coli Testing Market
Industrial Microbiology
Benzoate-Free Enzymes Market
Industrial Microbiology
B-Glucuronidase Enzymes Market
Industrial Microbiology
North America Microbial Protein Market
Industrial Microbiology
Lactic Acid Bacteria Market