
 Global Clinical Oncology Next Generation Sequencing Market | 2026-2036
Global Clinical Oncology Next Generation Sequencing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Clinical Oncology Next Generation Sequencing Market Intelligence
China's significant investment in genomic sequencing infrastructure is tilting the competitive landscape toward localized data generation. Illumina, Inc. sustains market leadership through its extensive installed base of high-throughput instruments. Thermo Fisher Scientific competes on the breadth of its portfolio, integrating instruments with reagents. F. Hoffmann-La Roche Ltd. leverages its dual strength in diagnostics and pharmaceuticals for integrated oncology solutions.
Clinical oncology next-generation sequencing refers to the use of massively parallel sequencing technologies to analyze DNA and RNA from tumor samples. This process identifies genomic alterations, such as mutations and fusions, to inform personalized cancer treatment strategies. Within product types, reagents and consumables constitute the largest recurring revenue stream for suppliers. The application segment of companion diagnostics represents the fastest-growing area, directly linked to new drug approvals.
Regulatory oversight from the US FDA and the European Medicines Agency (EMA) governs the approval of NGS-based in-vitro diagnostics. China's NMPA has established its own stringent review pathways for genetic testing products. These frameworks dictate market access requirements and the need for extensive clinical validation data. Future development hinges on harmonizing standards and securing broader reimbursement coverage from payers.
Market Dynamics
The convergence of targeted pharmaceutical development and diagnostic testing is the central force shaping the market. This symbiosis links the approval of new oncology drugs directly to the validation and adoption of specific next-generation sequencing assays, creating a self-reinforcing growth cycle.
Growth Catalysts
- Companion Diagnostics Expansion:Proliferating targeted therapies require corresponding diagnostic tests to identify eligible patients, tying NGS assay demand directly to pharmaceutical pipelines.
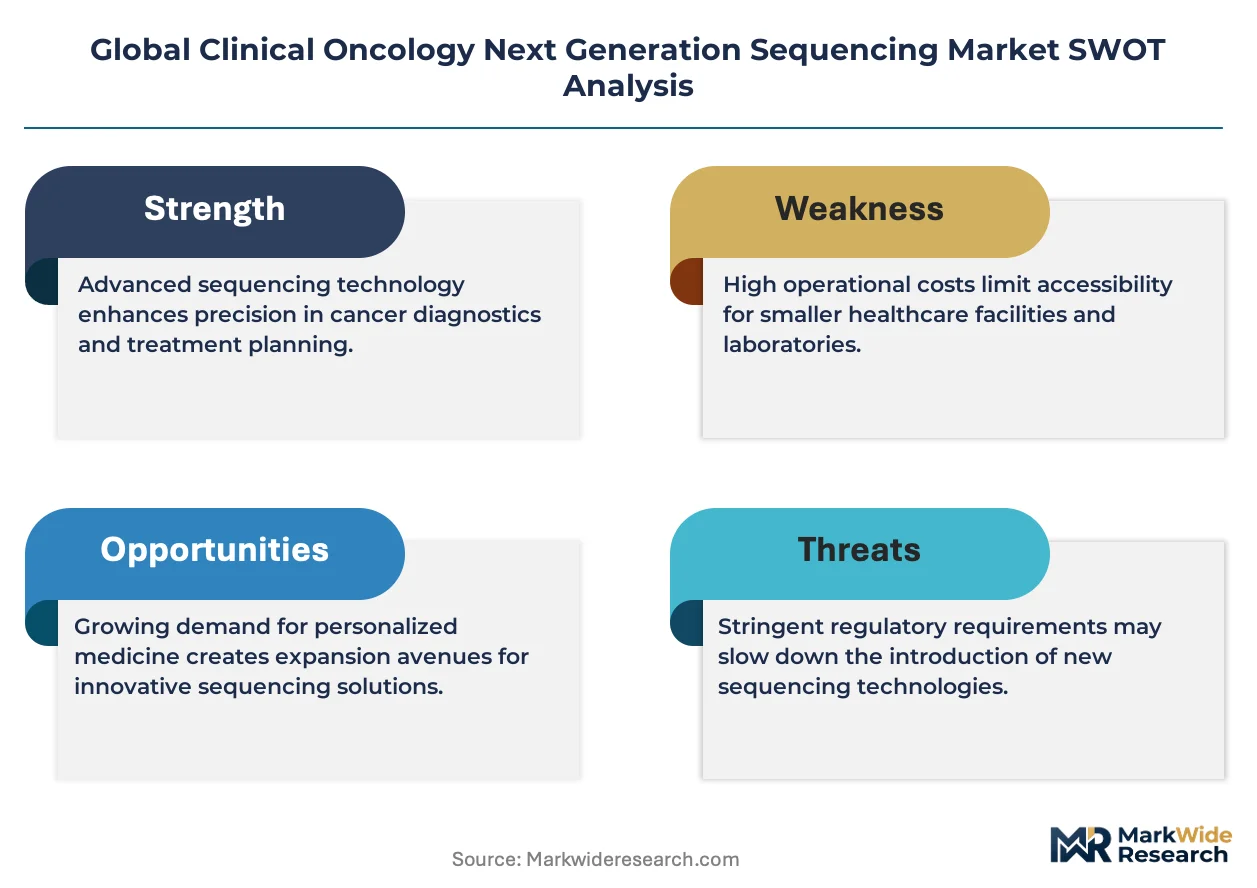
- Supportive Regulatory Frameworks:The FDA's parallel review process for drugs and diagnostics accelerates market access, creating a clear commercialization path for new NGS-based tests.
- Genomic Infrastructure Investment:National investment in sequencing capacity, particularly in China, is creating localized hubs for large-scale genomic data generation and analysis.
Market Restraints
- High Consumable Costs:Proprietary reagents and flow cells from instrument suppliers create high, recurring operational expenditures for clinical labs, limiting margin potential.
- Inconsistent Reimbursement Policies:Payer coverage for comprehensive genomic profiling remains fragmented, creating economic uncertainty and restricting patient access in key markets.
- Bioinformatics Bottleneck:A shortage of bioinformaticians to interpret complex sequencing data slows test turnaround times and limits wider clinical adoption.
Strategic Opportunities
- Liquid Biopsy Development:Advancing NGS for analyzing circulating tumor DNA (ctDNA) from blood samples opens a major opportunity for non-invasive cancer screening and monitoring.
- AI-Powered Variant Interpretation:Integrating artificial intelligence into analytical software can automate the classification of genomic alterations, reducing manual effort and improving diagnostic consistency.
- Penetration in Underserved Markets:Establishing diagnostic infrastructure in regions like Latin America and Southeast Asia represents a significant long-term growth avenue.
Industry Challenges
- Data Standardization:A lack of universal standards for data formatting and analysis pipelines complicates cross-study comparisons and the creation of federated genomic databases.
- Regulatory Compliance Complexity:Navigating distinct requirements from the FDA, EMA, and NMPA for diagnostics demands substantial investment in clinical validation.
- System Integration:Integrating NGS data workflows with existing Laboratory Information Systems (LIS) and Electronic Health Records (EHR) presents significant technical hurdles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Clinical Oncology Next Generation Sequencing Market |
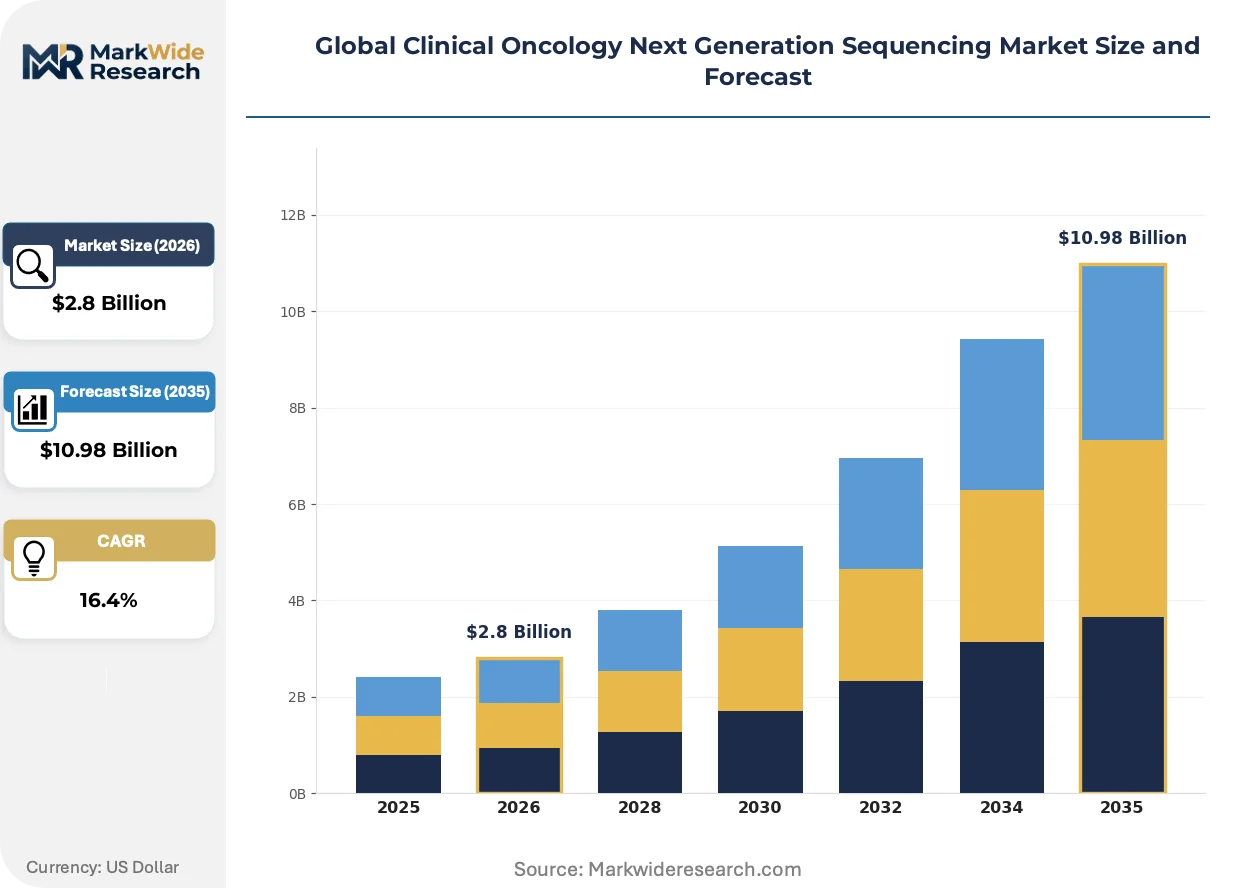
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $10.98 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Instruments, Software, Services Application: Companion Diagnostics, Biomarker Discovery, Genetic Profiling, Treatment Monitoring End User: Hospitals, Research Laboratories, Diagnostic Centers, Academic Institutions Technology: Sanger Sequencing, Ion Torrent, Pyrosequencing, Oligonucleotide Array |
| Companies Covered | Illumina, Inc., Thermo Fisher Scientific, F. Hoffmann-La Roche Ltd., Agilent Technologies, Qiagen N.V., Pacific Biosciences, Oxford Nanopore Technologies Ltd., PerkinElmer, Inc., BGI Genomics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Clinical Oncology Next Generation Sequencing Market Strategic Shifts & Innovations
A fundamental shift toward integrated, sample-to-answer workflows is defining the market's evolution. This pursuit of automation and speed aims to move next-generation sequencing from specialized research settings into routine clinical diagnostic practice, increasing accessibility and reducing turnaround times.
Long-read sequencing technology provides contiguous genomic data over many kilobases, enabling superior detection of complex structural variants. Major research hospitals and specialized clinical laboratories are adopting these systems for difficult-to-resolve cancer cases. This advanced capability is rendering obsolete the reliance on multiple, fragmented short-read assays to achieve a comprehensive tumor profile.
The European Union's In Vitro Diagnostic Regulation (IVDR) imposes stricter requirements for clinical evidence and post-market surveillance on all diagnostic tests. This elevates the burden of proof for manufacturers, demanding more rigorous validation data. Assay developers targeting the EU market are now investing heavily in performance studies to meet these stringent CE marking criteria.
A clear shift toward decentralized testing models is altering how oncology diagnostics are performed. This trend moves NGS capabilities from centralized reference laboratories into hospital-based labs closer to the patient. This change is most visible in the United States, driven by the need for faster turnaround times to guide immediate treatment decisions.
Global Clinical Oncology Next Generation Sequencing Market Segmentation
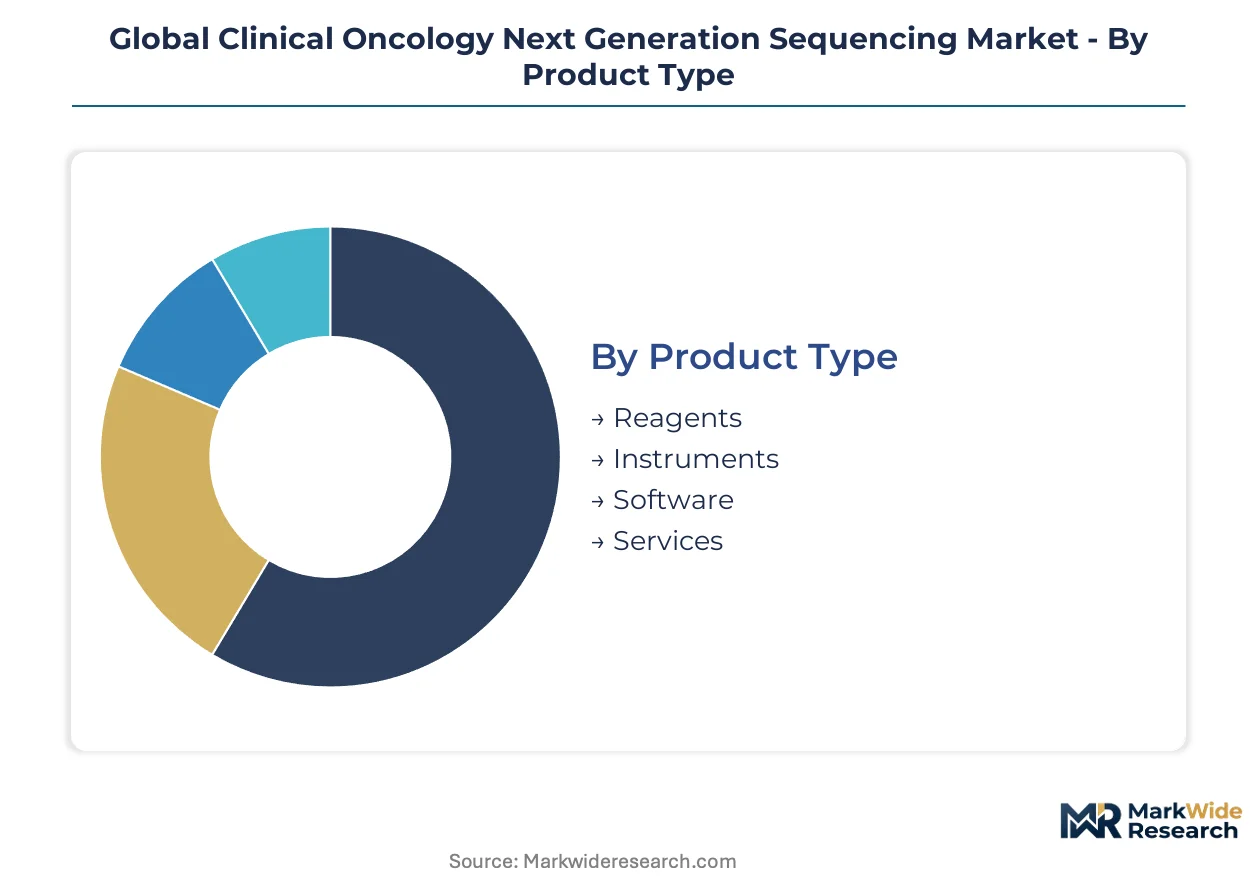
The segmentation of the global clinical oncology next generation sequencing market provides granular insights into its operational components and strategic growth vectors. Understanding these distinct categories helps identify specific demand patterns and technological adoption across diverse clinical settings and research environments.
Product Type:
The product type segmentation reveals a mature core alongside rapidly evolving components for genomic analysis.
- Reagents:These are proprietary chemical compounds and kits essential for preparing DNA/RNA samples and performing sequencing reactions. Recurring demand for reagents drives revenue stability in the United States and Germany, directly correlating with increased test volumes.
- Instruments:Sequencing instruments are complex hardware systems that automate the process of reading DNA/RNA sequences. Illumina and Thermo Fisher Scientific maintain significant installed bases in China and Japan, facilitating large-scale genomic data generation.
- Software:Bioinformatics software processes raw sequencing data, aligning reads, calling variants, and interpreting genomic alterations. Demand for advanced analytical software is growing in Canada, driven by the need to manage complex data sets.
- Services:These encompass outsourced sequencing, data analysis, and technical support provided by specialized laboratories or vendors. Clinical labs in Australia frequently utilize external services for niche or high-volume sequencing projects.
Reagents retains volume leadership; Instruments holds the steepest expansion curve.
Application:
Application segmentation highlights strategic priorities within clinical oncology, directly influencing patient management.
- Companion Diagnostics:These assays identify specific genomic alterations that determine patient eligibility for targeted cancer therapies. Expansion of companion diagnostics in the United States and the United Kingdom directly links to new drug approvals, creating substantial demand.
- Genetic Profiling:This application involves comprehensive analysis of a tumor's genetic makeup to guide personalized treatment strategies. Demand for detailed genetic profiling is rising in South Korea and Spain, driven by advancements in precision medicine.
- Biomarker Discovery:This involves identifying novel genetic markers that can be used for early cancer detection, prognosis, or therapeutic response prediction. Research institutions in France are actively pursuing biomarker discovery to improve clinical outcomes.
- Treatment Monitoring:NGS is used to track changes in tumor genomics over time, assessing treatment efficacy and detecting resistance mechanisms. Clinical adoption for treatment monitoring is increasing in Italy, particularly for liquid biopsy applications.
Demand for Companion Diagnostics is consolidating, while Genetic Profiling demonstrates significant potential.
End User:
End user categories reflect diverse operational models for NGS deployment and service delivery within the healthcare ecosystem.
- Hospitals:Hospital-based laboratories are increasingly adopting NGS platforms to integrate genomic testing directly into patient care pathways. Decentralized testing in hospitals across the United States and Germany improves turnaround times for critical treatment decisions.
- Diagnostic Centers:Specialized diagnostic centers offer high-throughput NGS testing services, often serving a broad network of clinicians. These centers in China and India handle large volumes of samples, leveraging economies of scale.
- Research Laboratories:Academic and commercial research laboratories utilize NGS for fundamental cancer research, drug discovery, and assay development. Major research hubs in the United Kingdom and Sweden rely on NGS for advanced genomic studies.
- Academic Institutions:Universities and teaching hospitals use NGS for both research and educational purposes, training future generations of genomic scientists. Institutions in Canada integrate NGS into oncology programs for both discovery and clinical translation.
Hospitals drives current adoption, and Diagnostic Centers shows accelerated expansion.
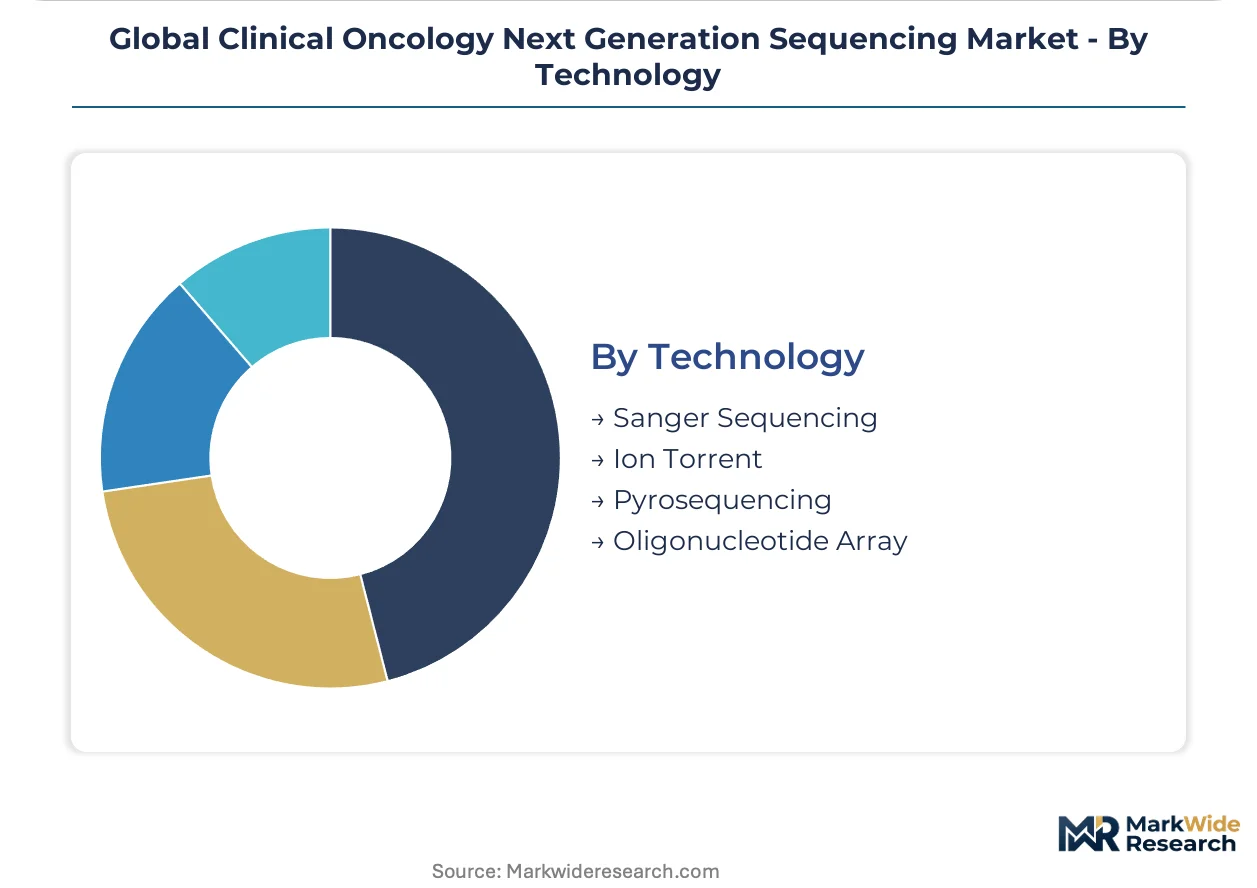
Technology:
Technology segmentation delineates the analytical capabilities available for genomic analysis, spanning traditional and advanced methods.
- Sanger Sequencing:This traditional method provides highly accurate sequence data for single genes or short DNA fragments. Sanger sequencing remains a foundational technology for validating NGS results and targeted mutation detection in laboratories across Japan.
- Ion Torrent:Ion Torrent platforms are based on semiconductor sequencing, detecting pH changes from released hydrogen ions during DNA synthesis. These systems offer integrated workflows and rapid turnaround times, popular in clinical labs in the United States.
- Pyrosequencing:This method detects DNA synthesis by measuring light emitted from pyrophosphate release. Pyrosequencing is used for specific applications like methylation analysis and SNP genotyping in specialized European labs.
- Oligonucleotide Array:These arrays use probes to detect specific DNA sequences or copy number variations. Oligonucleotide arrays find application in initial screening and cytogenetic analysis in clinical settings in Brazil.
Sanger Sequencing maintains broad market penetration, with Ion Torrent increasingly capturing advanced use cases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US FDA's stringent yet clear regulatory pathways anchor significant market development for clinical oncology next generation sequencing. These frameworks accelerate market entry for innovative diagnostic tests, fostering a robust environment for technological advancement. Demand for personalized treatment strategies drives adoption across diverse clinical settings in key global economies.
United States
The expansion of companion diagnostics directly drives demand for NGS assays in the United States. The FDA's parallel review process for drugs and diagnostics provides a clear commercialization path. Biotechnology hubs in Boston and San Francisco continue to drive innovation and clinical adoption of advanced genomic technologies.
China
China's significant investment in genomic sequencing infrastructure is creating localized demand for NGS platforms. The NMPA has established stringent review pathways for genetic testing products, influencing market access. Beijing and Shanghai are emerging as central hubs for large-scale genomic data generation and analysis.
Germany
Recurring demand for reagents and consumables supports the clinical oncology NGS market in Germany. The European Medicines Agency (EMA) and the IVDR impose strict requirements for clinical evidence. Munich and Heidelberg host prominent research institutions and diagnostic centers that integrate NGS into patient care.
Japan
Japan's mature healthcare infrastructure facilitates the adoption of NGS for targeted mutation detection and comprehensive tumor profiling. The PMDA governs medical device approvals, ensuring quality and efficacy for diagnostic tests. Tokyo and Osaka maintain significant installed bases of sequencing instruments, supporting advanced genomic studies.
United Kingdom
Companion diagnostics expansion and academic research initiatives propel NGS market growth in the United Kingdom. Regulatory oversight from the EMA (historically) and now the MHRA influences market entry for new diagnostic assays. London and Cambridge are major hubs for genomic studies and specialized research laboratories.
Global Clinical Oncology Next Generation Sequencing Market Key Industry Players
Instrument providers and integrated diagnostic-pharmaceutical companies split the market for clinical oncology next generation sequencing. This competitive structure features both specialized technology developers and diversified healthcare giants. Companies pursue portfolio diversification and strategic partnerships to expand their market reach and solution offerings.
Within the instrument and integrated solutions tiers, Illumina, Inc. and Thermo Fisher Scientific occupy significant positions, maintaining extensive installed bases of high-throughput instruments globally. F. Hoffmann-La Roche Ltd. exemplifies a dual strength in diagnostics and pharmaceuticals, offering integrated oncology solutions. These entities anchor distinct segments of the market, representing different strategic approaches to genomic testing.
| Leading Market Players |
|---|
| Illumina, Inc. |
| Thermo Fisher Scientific |
| F. Hoffmann-La Roche Ltd. |
| Agilent Technologies |
| Qiagen N.V. |
| Pacific Biosciences |
| Oxford Nanopore Technologies Ltd. |
| PerkinElmer, Inc. |
| BGI Genomics |
| Others |
Cost & Logistics Intelligence
The global cold chain logistics network's intricate cost dynamics directly influence the supply concentration of specialized reagents and instruments, thereby shaping downstream price differentiation for clinical oncology next-generation sequencing solutions.
Pricing Analysis
Geographic price spreads for clinical oncology NGS assays vary significantly, with higher costs observed in nascent markets compared to established regions like the United States and Germany. The dominant pricing model for reagents is per-unit transactional, while software often follows a subscription-based approach. Price differentiation stems from factors like instrument brand premium and the level of after-sales technical support. Pricing pressure stems from increasing competition among reagent suppliers, particularly for generic assay components. Research laboratories typically exhibit higher price sensitivity compared to large diagnostic centers or hospitals, which prioritize integrated solutions and reliability.
Supply Chain Analysis
Major instrument and reagent contract manufacturers in the United States, China, and Germany hold significant capacity for producing clinical oncology NGS components. The supply chain draws heavily from specialized enzymes and proprietary flow cell consumables. A structural risk involves single-source vulnerability for highly specialized reagents, which can lead to supply disruptions. Distribution runs through a hybrid model, combining direct sales channels for large instrument platforms with specialized distributors handling reagents and consumables for broader market reach.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The clinical oncology next-generation sequencing market is undergoing a platform-economics inflection, driven by the increasing interoperability between diagnostic assays and targeted therapeutic pipelines.
For Market Incumbents: Pre-empt emerging competition from AI-driven bioinformatics startups by investing heavily in proprietary data interpretation algorithms. Consolidate market share through strategic acquisitions of smaller, innovative software developers, mitigating the threat of fragmented data analysis solutions. Enhance vertical integration into reagent manufacturing to control costs and secure supply against potential geopolitical disruptions. Prioritize R&D in long-read sequencing applications to address complex genomic alterations, maintaining technological leadership.
For New Entrants and Emerging Players: Pursue niche application segments like liquid biopsy for early cancer detection in underserved markets such as Southeast Asia. Focus on developing cost-effective, automated sample-to-answer workflows to reduce operational expenditures for clinical labs. A specific go-to-market angle involves partnering with regional diagnostic centers to offer specialized, rapid-turnaround NGS services tailored to local clinical needs. Target the genetic profiling segment within mid-sized hospitals seeking to expand their in-house testing capabilities.
For Investors and Strategic Acquirers: Specialized bioinformatics firms offering AI-powered variant interpretation solutions represent an attractive acquisition target archetype for long-term viability. Companies with robust intellectual property in novel sequencing chemistries or advanced liquid biopsy technologies also present compelling investment opportunities over a five-to-ten-year window. The signal to watch is the broader reimbursement coverage for comprehensive genomic profiling, indicating market maturation and increased revenue predictability.
| Strategic Initiative | Industry Significance |
|---|---|
| Enhance AI-driven Bioinformatics | Integrating artificial intelligence improves the speed and accuracy of genomic variant interpretation for complex cancer cases. |
| Expand Liquid Biopsy Capabilities | Developing non-invasive liquid biopsy tests broadens access to cancer screening and treatment monitoring for patients. |
| Secure Proprietary Reagent Supply | Controlling the supply of specialized reagents stabilizes operational costs and ensures test availability for clinical labs. |
| Regional Market Penetration | Establishing diagnostic infrastructure in emerging economies expands patient access to advanced oncology testing. |
| Develop Automated Workflows | Automated sample-to-answer systems reduce manual errors and decrease turnaround times for critical diagnostic results. |
Research Approach
Two parallel data streams informed the analysis: extensive primary interviews and robust secondary research. Primary research involved discussions with clinical oncologists, laboratory directors, bioinformaticians, and pharmaceutical R&D leads. Secondary data sources included FDA filings, EMA guidelines, NMPA regulations, academic journals, and company investor reports, ensuring comprehensive market understanding. This approach facilitated bottom-up and top-down triangulation of market size and growth projections.
Forecast inputs considered the evolving regulatory landscape, technological advancements, and shifts in healthcare spending across the analysis window. The analytical framework modeled segmentation dimensions including product type, application, end-user, technology, and regional regulatory frameworks. Compound annual growth rates were derived from historical data trends and projected market dynamics. Key industry-specific forecast inputs included new drug approvals for targeted therapies and changes in reimbursement policies for genomic testing.
Sensitivities concentrate around unforeseen regulatory changes and rapid technological breakthroughs that could alter market trajectories. Forecasts reflect assumptions documented regarding clinical adoption rates and payer coverage. Quarterly review of new drug approvals and major reimbursement policy updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
Spatial OMICS Market
Genomics
Europe DNA Sequencing Products Market
Genomics
Global Single Nucleotide Polymorphism (SNP) Genotyping Market
Genomics
APO E Gene Test Kit Market
Genomics
Europe Epigenetics Market
Genomics
Cancer-Focused Genetic Testing Services Market
Genomics
North America Microarray Market
Genomics
Transcriptomics Technologies Market
Genomics
Global Artificial Intelligence in Genomics Market
Genomics
Plant Genomics Market
Genomics
Global Optical Genome Mapping Market
Genomics
Targeted DNA RNA Sequencing Market
Genomics
Glycan Sequencing Market
Genomics
Next-Generation Sequencing (NGS) Workflow Quality Control Test Kits and Instruments Market
Genomics
Global Pharmacogenetics Testing in Psychiatry/Depression Market
Genomics
Single-Cell Omics Market