
 Tissue Engineering Market | 2026-2036
Tissue Engineering Market Size, Share, and Industry Trends Forecast 2026-2036
Tissue Engineering Market Intelligence
A shift from traditional hospital procurement to specialized regenerative medicine centers is rebalancing the customer landscape for tissue engineering products. This trend favors companies with targeted clinical data and specialized sales forces. Medtronic leverages its extensive distribution network to supply orthopedic and spinal applications. Organogenesis Holdings Inc. specializes in bio-active wound healing and surgical biologics, while Integra LifeSciences Corporation competes with a broad portfolio in neurosurgery.
Tissue engineering is an interdisciplinary field that applies engineering and life sciences principles toward developing biological substitutes. These substitutes restore or improve tissue function, often using biocompatible scaffolds seeded with cells to guide new tissue formation. Scaffolds, particularly biopolymers and decellularized matrices, represent a foundational product segment due to their structural support. In applications, bone regeneration and skin repair are mature clinical areas, while cartilage restoration and nerve reconstruction represent fast-growing segments.
Market access is governed by stringent regulatory frameworks, including the FDA's RMAT designation in the United States and the EMA's ATMP pathway in Europe. In Japan, the PMDA provides a specific, accelerated framework for regenerative medicine products, influencing development timelines. These regulations shape requirements for clinical evidence and post-market surveillance. Navigating these distinct regional approval processes remains a critical challenge for developers.
Market Dynamics
The rebalancing of the customer landscape away from traditional hospitals toward specialized regenerative medicine centers is the central force shaping the market. This shift prioritizes companies with targeted clinical data and specialized sales channels over those with broad, generalist distribution networks.
Growth Catalysts
- 3D Bioprinting:Advances in bioprinting and electrospinning enable creation of complex, patient-specific scaffolds, improving outcomes in orthopedic applications.
- Favorable Regulations:The FDA's Regenerative Medicine Advanced Therapy (RMAT) designation provides an expedited pathway, encouraging investment and accelerating development in the United States.
- Growing Clinical Need:Rising prevalence of chronic diseases and trauma drives demand for solutions in fast-growing segments like cartilage and nerve reconstruction.
Market Restraints
- High Manufacturing Costs:The expense of GMP-grade cell culture media, growth factors, and sterile bioreactors creates a high cost of goods for cell-based therapies.
- Vascularization Hurdles:A persistent technical limit is the inability to effectively vascularize large tissue constructs, restricting applications to smaller or thinner tissues.
- Regulatory Fragmentation:Divergent requirements between the FDA, EMA, and PMDA for clinical evidence increase the cost and complexity of global product launches.
Strategic Opportunities
- Japanese Market Entry:The PMDA's framework for regenerative medicine offers a faster path to commercialization, creating an opportunity for early revenue generation in Japan.
- Neurological Applications:There is significant white space in developing scaffolds and cell therapies for nerve reconstruction and spinal cord injury beyond mature skin applications.
- AI-Integrated Bioreactors:Combining artificial intelligence with bioreactor systems presents an opportunity to automate and optimize tissue maturation, improving consistency and reducing manual oversight.
Industry Challenges
- Talent Scarcity:A shortage of professionals with dual expertise in cell biology and process engineering hampers scaling manufacturing from lab to commercial production.
- Standardization Deficit:Lack of industry-wide standards for raw material characterization and product testing complicates regulatory review and clinical adoption.
- Cold-Chain Logistics:Establishing a reliable, temperature-controlled supply chain for distributing living cell therapies to clinical sites remains a significant operational hurdle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tissue Engineering Market |
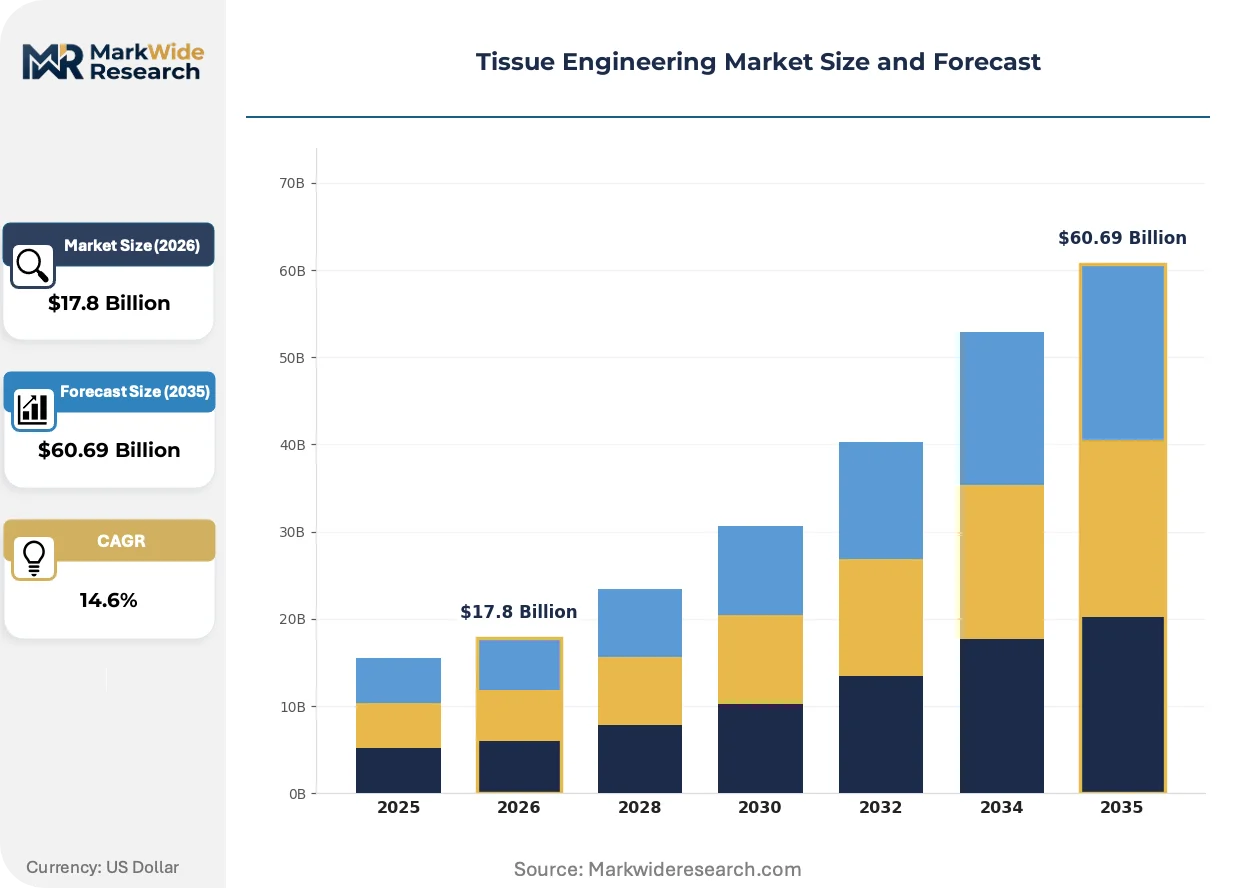
| Market Size in 2026 | $17.8 Billion |
| Market Size in 2035 | $60.69 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Scaffolds, Bioreactors, Bioinks, Growth Factors, Biopolymers Application: Bone Regeneration, Skin Repair, Cartilage Restoration, Nerve Reconstruction, Cardiac Tissue Formation End User: Research Laboratories, Regenerative Medicine Centers, Academic Institutions, Contract Research Organizations Technology: 3D Bioprinting, Electrospinning, Decellularization, Cell Seeding, Microfabrication |
| Companies Covered | Zimmer Biomet Holdings, Inc., Integra LifeSciences Corporation, Medtronic, Stryker Corporation, Organogenesis Holdings Inc., Baxter International, Inc., AbbVie (Allergan), Becton Dickinson and Company, Tissue Regenix Group plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tissue Engineering Market Strategic Shifts & Innovations
The convergence of advanced manufacturing technologies with personalized medicine is redefining market boundaries. This evolution is spurred by regulatory frameworks designed to accelerate the approval of novel therapies, pushing innovation from the lab into clinical practice.
4D bioprinting creates smart scaffolds that can change shape or function post-implantation. Advanced therapeutic developers are adopting it for complex organoid modeling. This capability is absorbing the limitations of static 3D constructs, enabling development of dynamic systems that better mimic native tissue regeneration.
Japan's accelerated approval pathway, via the PMDA, allows conditional marketing authorization for regenerative products with probable benefit. This framework shortens time-to-market compared to traditional trials. Consequently, developers targeting cartilage repair are prioritizing Japan for initial commercialization to generate early real-world evidence.
A preference for patient-specific autologous therapies is altering development pipelines away from allogeneic products. This favors decentralized manufacturing models where products are made near the point of care, disrupting centralized production. This trend is most visible in the United States and Germany, where specialized centers are equipped for patient-derived cell processing.
Tissue Engineering Market Segmentation
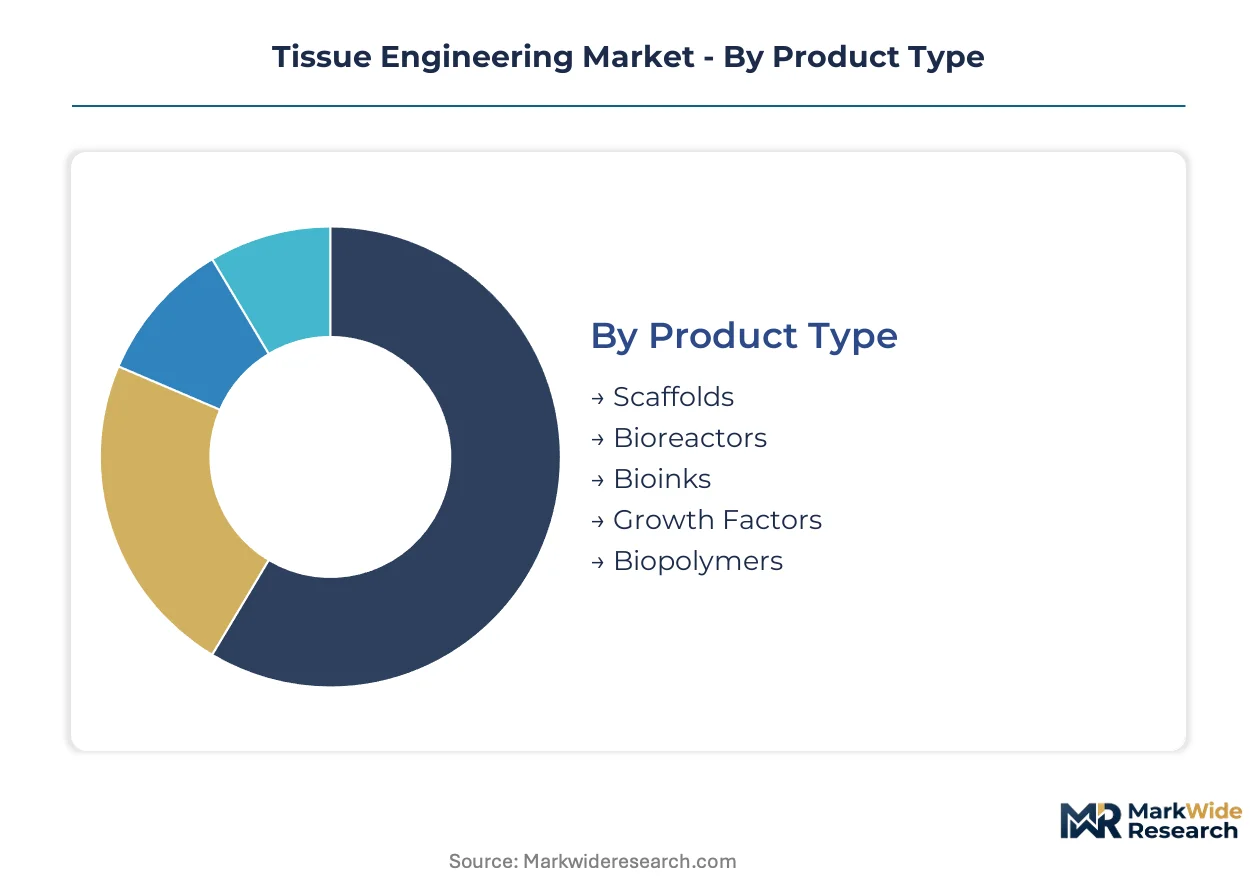
The Tissue Engineering Market's segmentation reflects the diverse technological approaches and clinical applications driving its evolution. Understanding these distinct segments provides clarity on where innovation and investment are concentrating to address unmet medical needs across various tissue types.
Product Type:
The market for tissue engineering products is defined by the core components and tools utilized in regenerative processes.
- Scaffolds:These biocompatible structures provide a temporary matrix for cell attachment, proliferation, and differentiation, guiding new tissue formation. Demand is concentrating in orthopedic applications, where scaffolds support bone and cartilage repair due to their structural integrity and porosity.
- Bioreactors:Controlled environments for cell culture and tissue maturation, bioreactors optimize conditions like nutrient supply, oxygen levels, and mechanical stimulation. Regenerative medicine centers increasingly procure advanced bioreactors to scale up production of complex tissue constructs for clinical trials.
- Bioinks:Specialized biomaterial formulations compatible with 3D bioprinting technologies, bioinks enable precise deposition of cells and extracellular matrix components. These are critical for creating intricate, multi-layered tissue models and organoids.
- Growth Factors:Signaling proteins that stimulate cell growth, proliferation, and differentiation, growth factors are essential for enhancing tissue regeneration. Their application spans wound healing and bone fusion procedures.
- Biopolymers:Natural or synthetic polymers, such as collagen or PLGA, form the basis for many scaffolds and drug delivery systems in tissue engineering. These materials offer tunable mechanical properties and biodegradability.
Scaffolds leads on scale; Bioinks leads on momentum.
Application:
Clinical needs dictate the application segments, showcasing where tissue engineering solutions are making the most significant impact.
- Bone Regeneration:This segment focuses on repairing or replacing damaged bone tissue, often employing scaffolds and growth factors to stimulate osteogenesis. Demand is strong in the United States, driven by trauma cases and an aging population requiring orthopedic interventions.
- Nerve Reconstruction:Targeting peripheral nerve injuries and spinal cord damage, this application involves engineered conduits and cell therapies to guide axonal regrowth. This represents a fast-growing segment, propelled by significant unmet needs and neurological research.
- Skin Repair:Covering chronic wounds, burns, and other dermatological conditions, skin repair utilizes bio-engineered skin substitutes and grafts. Organogenesis Holdings Inc. specializes in bio-active wound healing products for this area.
- Cartilage Restoration:Solutions for damaged articular cartilage, often involving cell-seeded scaffolds, aim to restore joint function and reduce pain. Japan's accelerated PMDA pathway is influencing early commercialization efforts in this application.
- Cardiac Tissue Formation:Developing engineered heart muscle or patches to treat cardiac diseases, this application remains in earlier research and development stages. It holds promise for patients with heart failure.
Bone Regeneration sees the highest clinical volume, while Nerve Reconstruction is expanding most quickly.
End User:
The customer landscape for tissue engineering products is shifting towards specialized facilities equipped for advanced therapies.
- Regenerative Medicine Centers:These specialized facilities focus on developing and delivering advanced cell and tissue-based therapies to patients. They represent a significant and expanding customer base for complex tissue engineering products.
- Research Laboratories:Academic and industry research laboratories conduct fundamental and translational research into new tissue engineering approaches and materials. They are primary consumers of bioreactors and novel bioinks for experimental models.
- Academic Institutions:Universities and teaching hospitals integrate tissue engineering into their research, education, and clinical trial programs. They contribute to foundational discoveries and early-stage product development.
- Contract Research Organizations:CROs provide specialized research services, including preclinical testing and clinical trial management, for tissue engineering product developers. They facilitate regulatory submissions and market entry.
Regenerative Medicine Centers drive the largest procurement value, with Research Laboratories exhibiting consistent demand for innovation.
Technology:
Technological advancements underpin the capabilities and complexity of engineered tissues, influencing product development pipelines.
- 3D Bioprinting:This additive manufacturing technique precisely deposits cells and biomaterials layer-by-layer to create complex 3D tissue structures. Advances in bioprinting enable patient-specific constructs for orthopedic applications and organoid modeling.
- Decellularization:The process of removing cellular components from tissues to create an extracellular matrix scaffold, preserving the native tissue architecture. Decellularized matrices are foundational in regenerative medicine for their inherent biocompatibility and structural support.
- Electrospinning:A fiber fabrication technique that uses an electric field to draw out polymer solutions into fine fibers, creating highly porous scaffolds mimicking native extracellular matrices. This technology is crucial for nerve reconstruction and vascular grafts.
- Cell Seeding:The process of introducing specific cell types onto a scaffold to guide tissue formation and maturation. Proper cell seeding protocols are vital for the functional success of engineered tissues.
- Microfabrication:Techniques used to create structures with features on the micron scale, enabling precise control over scaffold architecture and cellular microenvironments. This technology is applied in creating intricate tissue-on-a-chip models.
3D Bioprinting demonstrates the highest innovation velocity, while Decellularization underpins established product categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States and Germany exhibit distinct approaches to tissue engineering market development, reflecting differing regulatory priorities and healthcare systems. The US prioritizes expedited regulatory pathways for advanced therapies, while Germany focuses on robust research infrastructure and established medical technology sectors.
United States
United States demand for tissue engineered products stems from a high prevalence of chronic diseases and trauma cases requiring complex repair. The FDA's Regenerative Medicine Advanced Therapy (RMAT) designation provides an expedited pathway for novel regenerative therapies. Biotech hubs in Boston and California drive innovation in patient-specific constructs and cell-based therapies.
Germany
German market expansion for tissue engineering is supported by advanced orthopedic applications and a strong research base for biomaterials. The EMA's Advanced Therapy Medicinal Product (ATMP) pathway, which Germany influences, guides product approvals across Europe. Munich and Berlin host significant medical technology clusters focusing on biomaterials and bioreactor technologies.
Japan
Japan's aging population creates sustained demand for cartilage repair and bone regeneration solutions, alongside a focus on neurological applications. The PMDA's accelerated framework for regenerative medicine products shortens commercialization timelines for promising therapies. Tokyo's research institutions and Kyoto's biomedical centers lead advanced therapy development and clinical trials.
China
China's vast patient population and government initiatives drive demand for advanced tissue repair solutions, particularly in orthopedics and wound healing. The NMPA streamlines approval processes for innovative medical devices and biologics, encouraging domestic development. Shanghai's biotech parks and Beijing's research institutes are key centers for tissue engineering research and development.
India
India's growing healthcare sector and rising incidence of trauma cases fuel demand for tissue engineering products, especially in bone and skin repair. The CDSCO is developing specific guidelines for regenerative medicine, fostering domestic innovation and clinical adoption. Bengaluru's biotech cluster and Hyderabad's life sciences hub contribute to product development and manufacturing capabilities.
Tissue Engineering Market Key Industry Players
United States producers anchor one tier of the tissue engineering market; European specialists hold another. The market exhibits a tiered structure, combining large, diversified medical device conglomerates with smaller, niche regenerative medicine firms. Strategic archetypes include established players leveraging extensive distribution and agile biotechs focusing on novel platforms. Companies pursue strategic partnerships for technology access and portfolio diversification into new clinical applications.
Within the established medical device segment, Medtronic and Integra LifeSciences Corporation exemplify companies with broad portfolios spanning multiple surgical applications. These firms leverage their extensive distribution networks to reach various clinical settings and maintain market presence. Organogenesis Holdings Inc. sits within the specialized regenerative medicine archetype, focusing on bio-active wound healing and surgical biologics. These companies collectively demonstrate the market's reliance on both scale-driven market penetration and deep therapeutic expertise.
| Leading Market Players |
|---|
| Zimmer Biomet Holdings, Inc. |
| Integra LifeSciences Corporation |
| Medtronic |
| Stryker Corporation |
| Organogenesis Holdings Inc. |
| Baxter International, Inc. |
| AbbVie (Allergan) |
| Becton Dickinson and Company |
| Tissue Regenix Group plc |
| Others |
Cost & Logistics Intelligence
Niche regenerative medicine firms face intense pressure to justify premium pricing for advanced therapies, directly influencing their investment in specialized manufacturing and cold-chain logistics.
Pricing Analysis
Capacity additions in United States bioreactor manufacturing are reshaping price floors for cell culture equipment. The dominant pricing model for advanced tissue engineering products is value-based, reflecting clinical outcomes and patient-specific customization. Price differentiation stems from the level of clinical evidence and specific regulatory approvals like the FDA's RMAT designation. Pricing pressure stems from high manufacturing costs for GMP-grade inputs, impacting reimbursement discussions. Research laboratories exhibit lower price sensitivity for novel bioinks, while regenerative medicine centers are more sensitive for established scaffold products.
Supply Chain Analysis
Specialized biopolymer supply for tissue engineering rests on a concentrated base of manufacturers in Germany and the United States. Raw material dependencies include GMP-grade cell culture media, specific growth factors, and advanced biopolymers like PLGA. A significant supply chain risk is the complexity of cold-chain logistics required for distributing living cell therapies to clinical sites. Downstream, distribution runs through specialized sales forces targeting regenerative medicine centers and academic institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
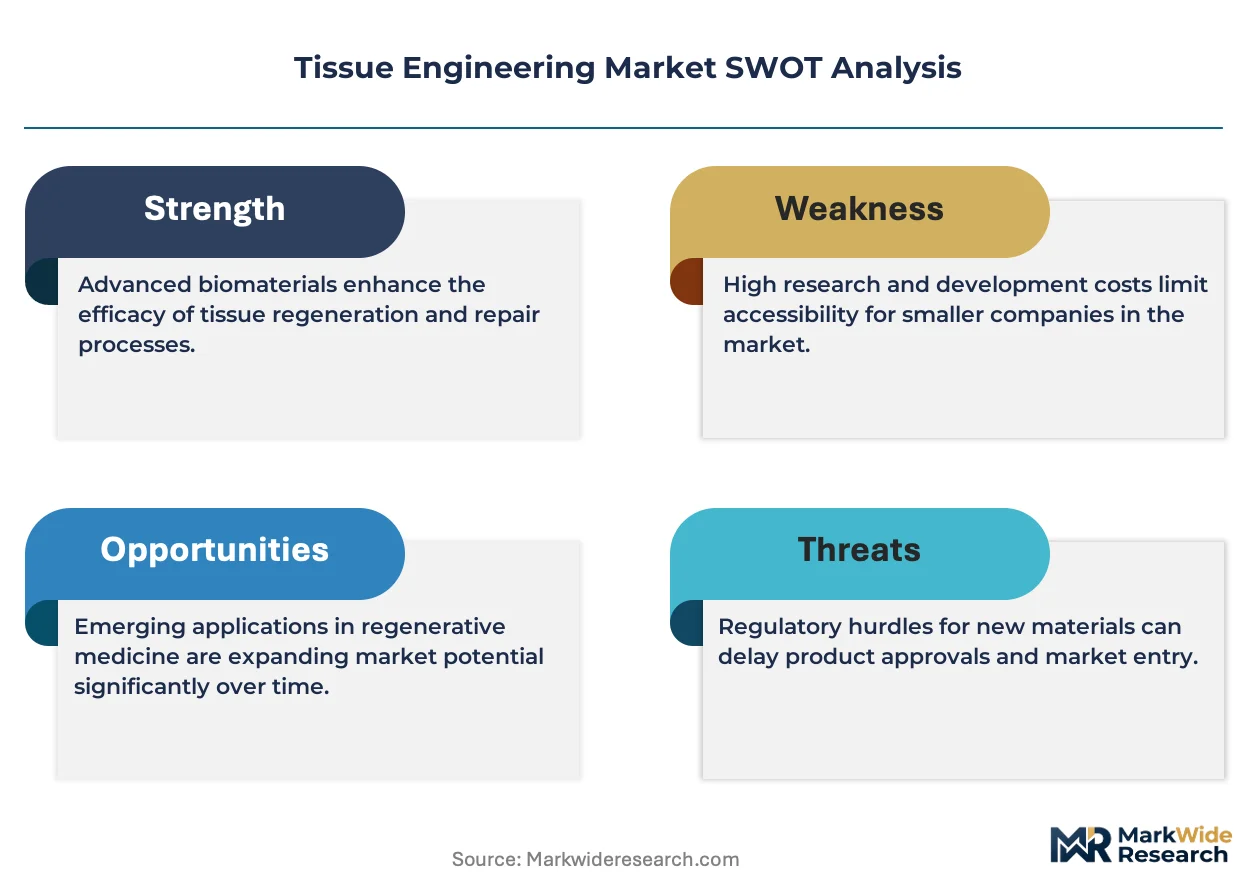
This market offers a geographic-arbitrage opportunity, particularly leveraging Japan's accelerated regulatory pathway for faster commercialization compared to the more stringent European EMA framework.
For Market Incumbents:Deepen strategic partnerships with specialized regenerative medicine centers to secure product adoption for complex tissue repair. Incumbents must also deepen their R&D into advanced manufacturing like 4D bioprinting to counter the threat from agile biotechs. This strategy enhances channel control and reinforces market presence against emerging competitors.
For New Entrants and Emerging Players:Capture underserved neurological applications, particularly nerve reconstruction and spinal cord injury, which represent significant white space beyond mature skin repair. New entrants should prioritize market entry in Japan for cartilage repair, leveraging the PMDA's accelerated framework for early revenue generation. A direct-to-specialized-center sales approach for patient-specific therapies offers a strong go-to-market angle.
For Investors and Strategic Acquirers:Valuations sit cheapest among early-stage biotechs developing novel bioprinting and electrospinning platforms. The long-term viability of this market is strong, driven by persistent unmet medical needs in complex tissue repair. Investors should target niche firms with strong intellectual property in neurological applications or AI-integrated bioreactors. Successful clinical trial readouts for these advanced therapies will serve as a critical inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Accelerates market access for novel engineered tissues. |
| Manufacturing Scale-Up | Reduces high manufacturing costs for cell-based therapies. |
| Strategic Partnership | Expands distribution networks to specialized centers globally. |
| Regulatory Approval Pathway | Navigates diverse regional frameworks like FDA RMAT. |
| Pipeline Diversification | Addresses unmet needs in fast-growing segments such as nerve reconstruction. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary insights with rigorous secondary validation. Interviews engaged regenerative medicine center directors, R&D scientists, regulatory affairs specialists, and orthopedic surgeons. Secondary data sources included FDA filings, EMA submissions, clinical trial registries, and peer-reviewed academic journals. This approach facilitated both bottom-up and top-down triangulation for comprehensive market understanding.
The forecast framework employed a segment-weighting approach, disaggregating the market across product type, application, end-user, technology, and regional regulatory pathways over the projection horizon. Compound annual growth rates were derived from historical trends and projected technological adoption curves. Key industry-specific inputs included the rising prevalence of chronic diseases and the pace of advancements in 3D bioprinting technology.
Regulatory changes, technological breakthroughs, and shifts in reimbursement policies are the dominant revision risks for future market estimates. Forecasts reflect assumptions documented at the time of analysis. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Engineering
Next-Generation Biomanufacturing Market
Biomedical Engineering
Tissue Extraction System Market
Biomedical Engineering
Argentina Artificial Organs and Bionic Implants Market
Biomedical Engineering
Bioprosthetics Market
Biomedical Engineering
Global Continuous Bioprocessing Market
Biomedical Engineering
Bioartificial Renal Assist Devices Market
Biomedical Engineering
Global Biomedical Tester Market
Biomedical Engineering
Topical Bioadhesives Market
Biomedical Engineering
Tissue Expansion Market
Biomedical Engineering
Self-Inflating Tissue Expander Market
Biomedical Engineering
Bioabsorbable Implant Market
Biomedical Engineering
Large and Small-Scale Bioprocessing Market
Biomedical Engineering
Biocompatible 3D Printing Market
Biomedical Engineering
Bioactive Bone Grafts Market
Biomedical Engineering
Bio-Engineered Stent Market
Biomedical Engineering
Tissue Engineered Skin Substitute Market