
 Tissue Extraction System Market | 2026-2036
Tissue Extraction System Market Size, Share, and Industry Trends Forecast 2026-2036
Tissue Extraction System Market Analytics
Aftermarket service revenue for capital extraction platforms is fragmenting across third-party refurbishers and original equipment channels. Johnson & Johnson Services Inc sustains a dense hospital service network in North America. Thermo Fisher Scientific anchors the research-grade instrument segment with cryogenic extraction workflows. Olympus Corporation competes through integrated endoscopic extraction suites that bundle visualization with tissue retrieval.
A tissue extraction system comprises electromechanical or pneumatic instruments designed to harvest, section, or aspirate biological specimens with controlled vacuum pressures ranging from 50 to 760 mmHg and cutting speeds calibrated to tissue density. These systems serve pathology diagnosis, graft preparation, and molecular analysis by preserving cellular architecture during retrieval. Vacuum-assisted technology commands the largest installed base among technology categories due to its standardization in breast biopsy protocols, while laser-based modalities represent the fastest-advancing segment as femtosecond pulse systems reduce thermal necrosis margins in ophthalmic and neural extraction. Surgical extractors retain dominant revenue share among product types, though microdissection tools are gaining traction in precision oncology workflows where spatial transcriptomics demands intact tissue microenvironments.
FDA 510(k) pathways and EMA MDR conformity assessments shape product development timelines for manufacturers seeking dual-territory approval, with biocompatibility testing under ISO 10993 now mandatory for all patient-contact extraction components. The EU AI Act introduces documentation burdens for systems embedding computer-vision guidance in automated biopsy targeting. Stakeholders must monitor evolving sterility standards for single-use extraction consumables as regulators in multiple jurisdictions tighten post-market surveillance requirements.
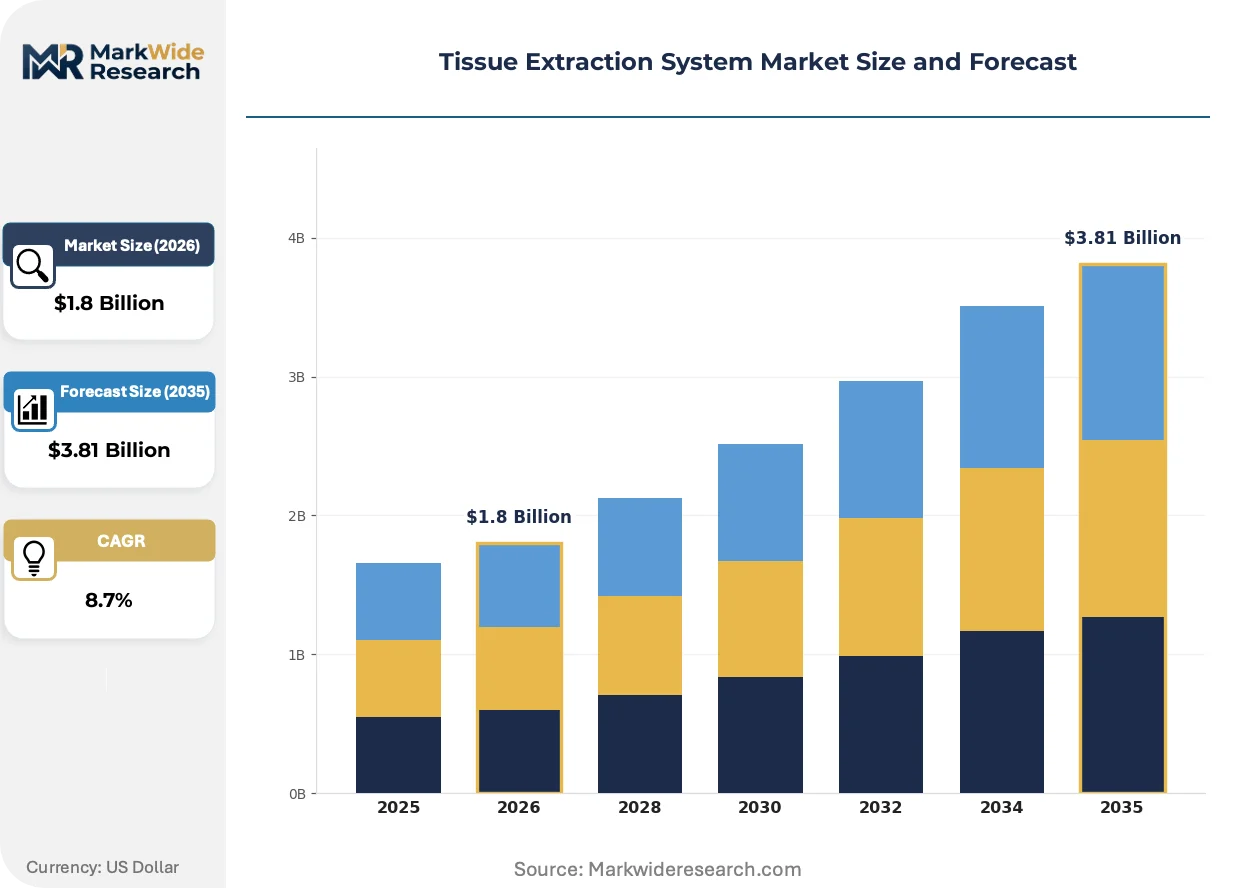
Market Dynamics
Minimally invasive extraction protocols are compressing hospital capital cycles as procurement committees prioritize platform consolidation over single-device purchases. Tertiary care centers in Germany, Japan, and the United States now demand integrated visualization-retrieval suites that reduce operative time and sterilization overhead.
Growth Catalysts
- FDA sterility validation tightening:The FDA's enhanced 510(k) requirements for single-use biopsy consumables are accelerating hospital replacement cycles of legacy reusable instruments.
- Oncology pathology volume:North American and European tertiary care centers are expanding molecular diagnostic pipelines that require intact tissue microenvironments for spatial transcriptomics workflows.
- Laser femtosecond pulse advancement:Ophthalmic and neural extraction applications are adopting thermal-damage-reduction protocols that expand addressable procedure categories.
Market Restraints
- Capital intensity of cryogenic workflows:Research-grade cryogenic extraction platforms require liquid nitrogen infrastructure that limits deployment to well-funded academic medical centers.
- EMA MDR conformity timeline extension:The European Union's Medical Device Regulation has lengthened approval cycles for patient-contact extraction components, delaying dual-territory launches.
- Reusable instrument refurbishment economics:Third-party refurbishers in Asia-Pacific are compressing service margins for original equipment manufacturers' aftermarket revenue streams.
Strategic Opportunities
- EU AI Act documentation frameworks:Computer-vision-guided automated biopsy systems face new compliance requirements that favor established manufacturers with regulatory infrastructure.
- Microdissection precision oncology:Spatial biology workflows are creating demand for intact tissue microenvironment preservation that exceeds standard vacuum-assisted capabilities.
- India CDSCO pathway alignment:The Central Drugs Standard Control Organization's harmonization with ISO 13485 is streamlining entry for manufacturers with existing FDA clearances.
Industry Challenges
- ISO 10993 biocompatibility testing capacity:Contract laboratories face backlogs for patient-contact extraction component validation that compress product development timelines.
- Endoscopic suite integration complexity:Hospitals demand seamless data interoperability between extraction platforms and electronic pathology systems, requiring substantial software engineering investment.
- Single-use consumable sterility assurance:Post-market surveillance requirements for extraction needles and catheters are intensifying quality system documentation burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tissue Extraction System Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Extractors, Biopsy Devices, Microdissection Tools, Endoscopic Systems Technology: Ultrasound-Assisted, Vacuum-Assisted, Radiofrequency, Laser-Based Application: Oncology, Transplantation, Research, Regenerative Medicine End User: Hospitals, Research Institutions, Diagnostic Laboratories, Specialty Clinics |
| Companies Covered | Medtronic plc, Johnson & Johnson Services Inc, CONMED Corporation, Stryker Corporation, Olympus Corporation, B. Braun Melsungen AG, Thermo Fisher Scientific, Danaher Corporation, Becton Dickinson Biosciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tissue Extraction System Market Evolving Landscape
Digital pathology integration and automated specimen handling are restructuring how tissue extraction systems interface with downstream diagnostic workflows. Manufacturers are embedding computer-vision guidance and closed-loop vacuum control to reduce operator-dependent variability.
Femtosecond laser extraction technology is virtualizing thermal damage margins in ophthalmic and neural tissue retrieval. Academic medical centers in Germany and Japan are piloting these systems for retinal and brain biopsy procedures. The technology is virtualizing the trade-off between extraction precision and cellular viability that has constrained laser modalities to superficial applications.
The EU AI Act's risk classification framework is redefining documentation obligations for automated biopsy targeting systems. Computer-vision guidance modules now face conformity assessment procedures previously reserved for therapeutic devices. European manufacturers are restructuring quality management systems to address algorithmic transparency requirements for extraction path planning.
Hospital procurement committees are consolidating vendor relationships around platform ecosystems that bundle extraction, visualization, and informatics. Independent service organizations are losing ground to manufacturer-captive service contracts that lock in consumable revenue. This concentration is most visible in United States health systems pursuing standardization across multiple hospital sites.
Tissue Extraction System Market Segmentation
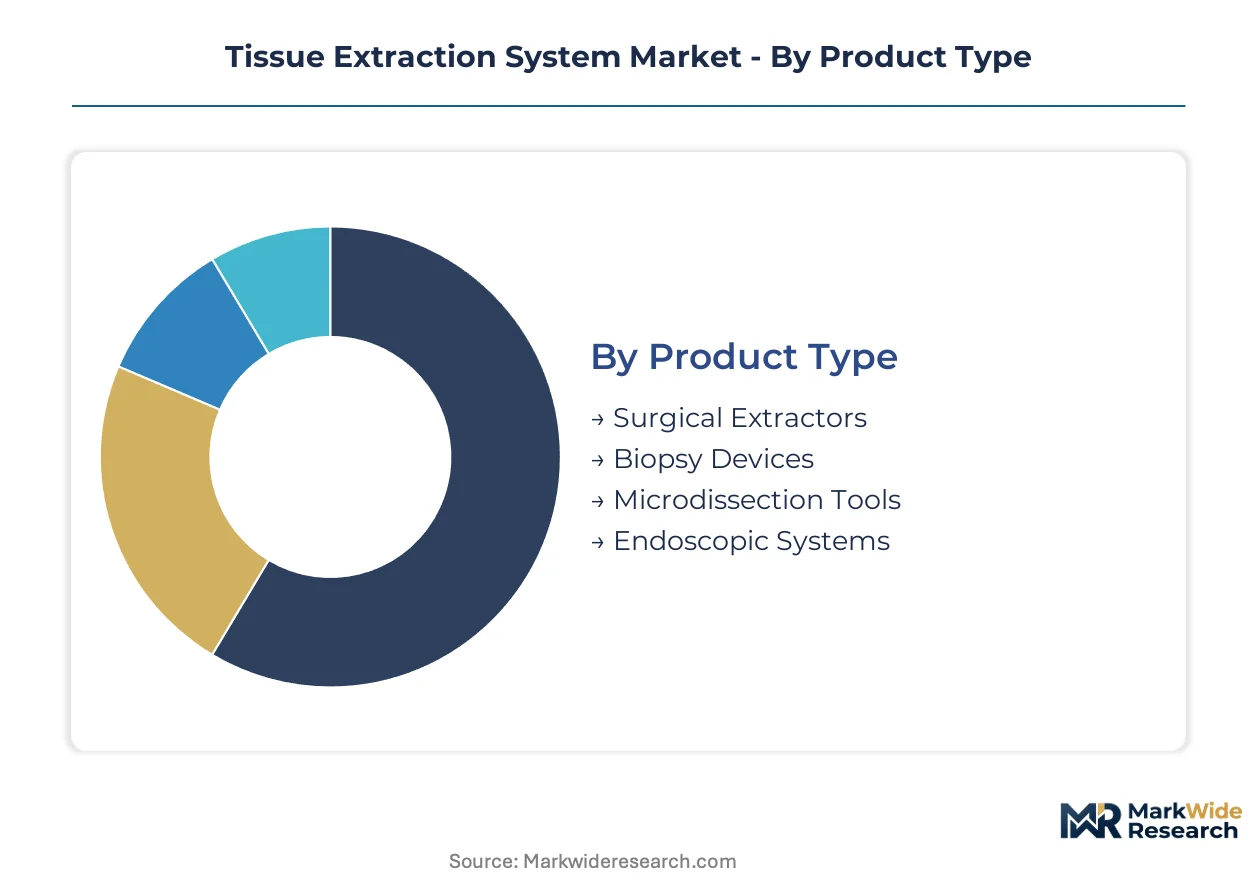
Tissue extraction system procurement varies sharply by clinical setting, with hospitals prioritizing platform consolidation while research institutions demand specimen integrity. Each segment carries distinct service attachment rates and regulatory pathways that shape vendor economics.
Product Type:
After-sales service intensity diverges dramatically across product categories, with capital-intensive platforms generating multi-year maintenance contracts versus disposable-heavy segments relying on consumable replenishment.
- Surgical Extractors:These electromechanical instruments integrate vacuum pumps, cutting assemblies, and tissue collection chambers rated for 50-760 mmHg pressure ranges. Tertiary care centers in Germany and the United States are standardizing on modular platforms that reduce sterilization turnaround. By volume, Surgical Extractors leads. By growth pace, Microdissection Tools is ahead.
- Biopsy Devices:Single-use needles and core sampling instruments dominate breast and prostate screening protocols. FDA sterility validation tightening is accelerating hospital migration from reusable alternatives, compressing replacement cycles.
- Microdissection Tools:Precision instruments preserving tissue microenvironments for spatial transcriptomics workflows. Academic medical centers in Japan are piloting these for oncology research requiring intact cellular architecture.
- Endoscopic Systems:Integrated visualization-retrieval suites bundling extraction with imaging. Olympus Corporation anchors this segment through bundled service contracts that lock in hospital procurement committees.
Service revenue concentrates in Surgical Extractors and Endoscopic Systems, where multi-year contracts exceed hardware margins.
Technology:
Capital deployment thresholds stratify adoption, with infrastructure-light modalities penetrating community hospitals while cryogenic and laser systems remain confined to well-funded academic centers.
- Vacuum-Assisted:Standardized negative-pressure protocols dominate breast biopsy workflows, offering reproducible specimen quality with minimal operator training. This technology commands the largest installed base across North American tertiary centers.
- Laser-Based:Femtosecond pulse systems reduce thermal necrosis margins to sub-cellular scales. Retinal and neural applications in German and Japanese academic hospitals are validating these for previously inaccessible anatomical sites.
- Ultrasound-Assisted:Real-time imaging guidance for percutaneous extraction procedures. Community hospitals favor this modality for its lower capital footprint versus integrated laser platforms.
- Radiofrequency:Thermal ablation combined with tissue retrieval for lesion targeting. Adoption concentrates in hepatocellular carcinoma protocols where simultaneous treatment and diagnosis is prioritized.
By installed base, Vacuum-Assisted dominates. By expansion trajectory, Laser-Based is climbing the fastest.
Application:
Specimen quality requirements intensify downstream, with diagnostic applications demanding cellular preservation that research workflows can sacrifice for throughput.
- Oncology:Molecular diagnostic pipelines require intact tissue microenvironments for genomic and transcriptomic analysis. North American and European tertiary centers are expanding procurement of precision extraction platforms to support personalized therapy selection.
- Research:Cryogenic workflows for biobanking and longitudinal specimen storage. Thermo Fisher Scientific anchors this segment through liquid nitrogen infrastructure partnerships with academic medical centers.
- Transplantation:Graft harvesting protocols prioritize vascular integrity during extraction. Specialized procurement committees evaluate these systems separately from general pathology instrumentation.
- Regenerative Medicine:Stem cell and tissue engineering applications requiring aseptic retrieval conditions. CDSCO pathway alignment in India is streamlining entry for manufacturers with existing FDA clearances.
Revenue concentrates in Oncology. Steepest expansion trajectory belongs to Regenerative Medicine.
End User:
Procurement authority and budget cycles fragment the customer base, with hospitals consolidating vendors while research institutions maintain fragmented best-of-breed purchasing.
- Hospitals:Integrated delivery networks in the United States are standardizing extraction platforms across multiple sites, favoring manufacturers with dense service networks. Johnson & Johnson Services Inc sustains advantage through captive maintenance contracts.
- Research Institutions:Cryogenic and laser platforms for spatial biology workflows. German and Japanese academic centers lead adoption of femtosecond systems for neural and ophthalmic applications.
- Diagnostic Laboratories:High-throughput biopsy processing for regional pathology networks. These customers prioritize consumable cost predictability over capital platform features.
- Specialty Clinics:Ambulatory extraction for dermatology and gastroenterology procedures. Lower sterilization overhead requirements favor single-use disposable configurations.
By procurement volume, Hospitals leads. By platform sophistication requirements, Research Institutions is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity for tissue extraction systems varies sharply by geography. Procurement committees in Germany and Japan prioritize platform consolidation over unit economics, while Indian hospitals remain acutely sensitive to capital expenditure thresholds.
United States
Integrated delivery networks are standardizing extraction platforms across multi-site health systems, favoring vendors with dense service networks. FDA sterility validation tightening for single-use biopsy consumables is accelerating hospital replacement cycles of legacy reusable instruments. The Greater Boston corridor anchors precision oncology research requiring intact tissue microenvironments.
Germany
Tertiary care centers in Bavaria and North Rhine-Westphalia are expanding procurement of minimally invasive extraction suites that reduce operative time. EMA MDR conformity assessments have lengthened approval cycles for patient-contact components, delaying dual-territory launches. Heidelberg and Munich academic medical centers pilot femtosecond laser systems for neural and retinal biopsy procedures.
Japan
Metropolitan Tokyo and Osaka hospital procurement committees demand integrated visualization-retrieval platforms with embedded computer-vision guidance. PMDA alignment with ISO 13485 streamlines entry for manufacturers with existing FDA clearances. Kansai region academic centers lead adoption of cryogenic workflows for spatial transcriptomics research.
India
CDSCO pathway harmonization with ISO 13485 is reducing regulatory friction for manufacturers holding FDA clearances. Maharashtra and Karnataka tertiary hospitals are expanding molecular diagnostic pipelines requiring precision extraction capabilities. Mumbai and Bangalore medical device clusters concentrate third-party refurbishment activity compressing OEM service margins.
United Kingdom
NHS procurement frameworks prioritize consumable cost predictability over capital platform features for regional pathology networks. MHRA post-market surveillance requirements for extraction needles intensify quality system documentation burdens. London and Cambridge research institutions drive demand for microdissection tools preserving cellular architecture.
Tissue Extraction System Market Competitive Landscape
Capability concentration sits with integrated platform specialists; scale advantage sits with diversified medical technology conglomerates. The vendor base stratifies across three tiers: full-suite integrators bundling visualization with retrieval, component specialists dominating single-use consumables, and research-grade instrument providers serving academic workflows. Consolidation pressures favor manufacturers with captive service networks and regulatory infrastructure spanning FDA and EMA pathways. M&A activity targets computer-vision guidance capabilities and cryogenic workflow expertise.
Among diversified medical technology conglomerates, Johnson & Johnson Services Inc and Stryker Corporation exemplify the scale-driven tier with extensive hospital service networks. Thermo Fisher Scientific occupies a distinct position anchoring the research-grade segment through liquid nitrogen infrastructure partnerships. Olympus Corporation represents the integrated-suite archetype, competing through bundled visualization-retrieval platforms that lock in procurement committees with multi-year service contracts.
| Leading Market Players |
|---|
| Medtronic plc |
| Johnson & Johnson Services Inc |
| CONMED Corporation |
| Stryker Corporation |
| Olympus Corporation |
| B. Braun Melsungen AG |
| Thermo Fisher Scientific |
| Danaher Corporation |
| Becton Dickinson Biosciences |
| Others |
Value Network & Pricing Analysis
The Trans-Pacific freight corridor from Shanghai to Long Beach anchors cost dynamics for German and Japanese manufacturers importing precision electromechanical assemblies, concentrating supply-side pricing power among integrated platform vendors while compressing margins for consumable-only suppliers facing hospital procurement committees.
Pricing Analysis
After-sales service contracts spanning multi-year maintenance agreements and consumable replenishment programs drive lifetime value capture for capital-intensive extraction platforms. Three-tier pricing structure across premium, standard, and economy levels segments buyers by sterilization validation tier and computer-vision integration depth. Pricing pressure stems from third-party refurbishers in India compressing OEM service margins. Diagnostic laboratories exhibit acute price sensitivity versus integrated delivery networks prioritizing platform consolidation.
Supply Chain Analysis
Precision electromechanical components and biocompatible polymers for patient-contact surfaces draw from specialized feedstock suppliers in Germany, Japan, and the United States. Stainless steel alloys for cutting assemblies, medical-grade silicones for vacuum seals, and optical fibers for laser delivery systems anchor raw material dependencies. Single-source vulnerability concentrates in femtosecond laser resonator manufacturing. Distribution runs through manufacturer-direct hospital contracts and group purchasing organization frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The tissue extraction system market is accelerating through femtosecond laser virtualization of thermal damage margins, a technological inflection expanding previously inaccessible neural and ophthalmic procedure categories.
For Market Incumbents: Insulate installed base positions through captive refurbishment networks that intercept third-party service encroachment in Asia-Pacific. Deepen backward integration into biocompatible polymer molding to secure ISO 10993 validation capacity against contract laboratory backlogs. Prioritize EMA MDR conformity infrastructure to maintain dual-territory launch velocity versus delayed competitors.
For New Entrants and Emerging Players: Establish a beachhead in microdissection tools for spatial transcriptomics workflows where intact tissue microenvironment requirements exceed incumbent vacuum-assisted capabilities. Target research institutions in Germany and Japan piloting femtosecond systems before hospital procurement committees standardize. Deploy liquid nitrogen infrastructure partnerships modeled on academic medical center cryogenic workflows.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified medical technology conglomerates seeking to divest non-core extraction assets amid platform consolidation pressures. Long-term viability hinges on regulatory infrastructure spanning FDA and EMA pathways rather than single-territory clearance. Monitor CDSCO harmonization progress with ISO 13485 as signal for Indian market entry feasibility.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Streamlined sterility validation documentation compresses hospital replacement cycles for single-use consumables. |
| CE Marking Pathway Investment | EMA MDR conformity infrastructure enables dual-territory launches before competitors face timeline extensions. |
| Hospital System Partnership | Integrated delivery network standardization locks in multi-site procurement across United States health systems. |
| Software Companion Development | Computer-vision guidance modules address EU AI Act documentation burdens favoring established manufacturers. |
| Reimbursement Strategy Formulation | Molecular diagnostic pipeline expansion in North American tertiary centers supports precision extraction platform adoption. |
Research Methodology
A spread of perspectives from hospital procurement committee chairs, biomedical engineering directors, GPO contracts managers, and pathology laboratory supervisors converged on the working assumptions. Primary interview insights combined with secondary validation from FDA 510(k) filings, EMA MDR submission databases, hospital procurement records, and CMS Medicare reimbursement data. Bottom-up segment sizing and top-down macro constraint triangulation anchored volume estimates.
Demand-supply balance dynamics across the projection horizon modeled technology adoption curves against sterilization infrastructure capacity constraints. Segmentation dimensions spanned product type, extraction modality, clinical application, end-user setting, and regional regulatory cluster. CAGRs derived from procedure volume elasticity to platform consolidation trends and consumable replacement cycle compression. Forecast inputs incorporated PMDA alignment timelines and CDSCO harmonization progress.
Sensitivities concentrate around EMA MDR approval timeline extensions, ISO 10993 testing capacity bottlenecks, and femtosecond laser component supply concentration. Forecasts reflect documented assumptions regarding hospital capital cycle compression and spatial biology workflow expansion. Quarterly review of FDA sterility validation guidance updates and EU AI Act implementing acts is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Engineering
Tissue Expansion Market
Biomedical Engineering
Bioresorbable Scaffolds Market
Biomedical Engineering
Global Robotic Prosthetic Market
Biomedical Engineering
Protein Engineering Market
Biomedical Engineering
Global Bovine-Based Collagen for Biomedical Applications Market
Biomedical Engineering
Large and Small-Scale Bioprocessing Market
Biomedical Engineering
Global Bionics Market
Biomedical Engineering
Biological Derived Devices Market
Biomedical Engineering
Global Bionic Ear Market
Biomedical Engineering
Tissue Engineering Market
Biomedical Engineering
Global Continuous Bioprocessing Market
Biomedical Engineering
North America Biosurgery Market
Biomedical Engineering
Medical Biomimetics Market
Biomedical Engineering
Artificial Organ Bank Market
Biomedical Engineering
Bio-Engineered Stent Market
Biomedical Engineering
3D Bioprinting Market