
 3D Bioprinted Organ Transplants Market | 2026-2036
3D Bioprinted Organ Transplants Market Size, Share, and Industry Trends Forecast 2026-2036
3D Bioprinted Organ Transplants Market Outlook
Decellularized extracellular matrix bioinks are recalibrating cost structures across the 3D bioprinted organ transplants landscape. Organovo Holding, Inc. leverages proprietary NovoGen bioprinting platforms to anchor its position in liver tissue models. CELLINK sustains broad installed-base dominance through open-system architecture and consumables lock-in. Aspect Biosystems Ltd. differentiates via microfluidic printhead technology that controls cell deposition at sub-millimeter resolution.
3D bioprinted organ transplants encompass additive manufacturing processes that layer living cells, biomaterials, and growth factors to fabricate functional tissue architectures with vascular channel diameters below 200 microns, serving preclinical drug screening and eventual human transplantation. Tissue constructs command premium positioning due to their complexity and regulatory validation burden compared with simpler organ models. Extrusion bioprinting occupies the largest installed base while laser-assisted modalities capture fastest-growing interest for microscale precision in cardiac patch applications. Medical institutions represent the most concentrated end-user segment, though pharmaceutical companies are expanding contract research budgets for organ-on-chip alternatives.
FDA breakthrough device and regenerative medicine advanced therapy designations shape clinical trial economics and investor access for developers targeting human transplantation. EMA's ATMP framework and Japan's PMDA regenerative medicine safety provisions create parallel compliance architectures that influence multicenter study design. ISO 10993 biocompatibility standards and WHO Good Manufacturing Practice for cell therapies govern material qualification and production scale-up. Stakeholders must monitor CMS national coverage determination proceedings for biofabricated tissues, as reimbursement precedent will determine whether hospital procurement committees treat these products as capital equipment or billable therapeutic procedures.
Market Dynamics
Decellularized extracellular matrix bioinks are recalibrating cost structures across the 3D bioprinted organ transplants landscape, forcing developers to reconfigure supply chains around biological sourcing partnerships rather than synthetic polymer procurement.
Growth Catalysts
- FDA Breakthrough Device Designation:The pathway compresses clinical trial timelines for developers targeting human transplantation, creating institutional pull at academic medical centers.
- NIH Funding Concentration:United States federal research allocations are scaling adoption of tissue constructs for surgical training applications.
- Microfluidic Printhead Technology:Sub-millimeter resolution control over cell deposition is enabling vascular channel fabrication below 200 microns.
Market Restraints
- Biological Input Volatility:Decellularized matrix sourcing depends on porcine and bovine tissue availability, exposing production to agricultural supply shocks.
- Regulatory Friction:EMA's ATMP framework imposes parallel compliance architectures that lengthen multicenter study design timelines.
- Technical Limitation:Vascularization beyond capillary-scale networks remains unresolved, constraining functional organ thickness.
Strategic Opportunities
- Underpenetrated Geography:Japan's PMDA regenerative medicine safety provisions create favorable entry conditions for developers with existing ISO 10993 qualification.
- Technology Convergence:Integration of laser-assisted bioprinting with extrusion platforms enables hybrid precision-speed workflows for cardiac patch applications.
- Channel Innovation:Direct-to-hospital tissue engineering service contracts are displacing traditional capital equipment sales models.
Industry Challenges
- Talent Scarcity:Cross-functional expertise spanning biomaterials science, vascular biology, and GMP manufacturing remains concentrated at fewer than twelve academic centers worldwide.
- Certification Timeline Compression:WHO Good Manufacturing Practice for cell therapies requires 18-24 month facility qualification cycles that outpace product development schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Bioprinted Organ Transplants Market |
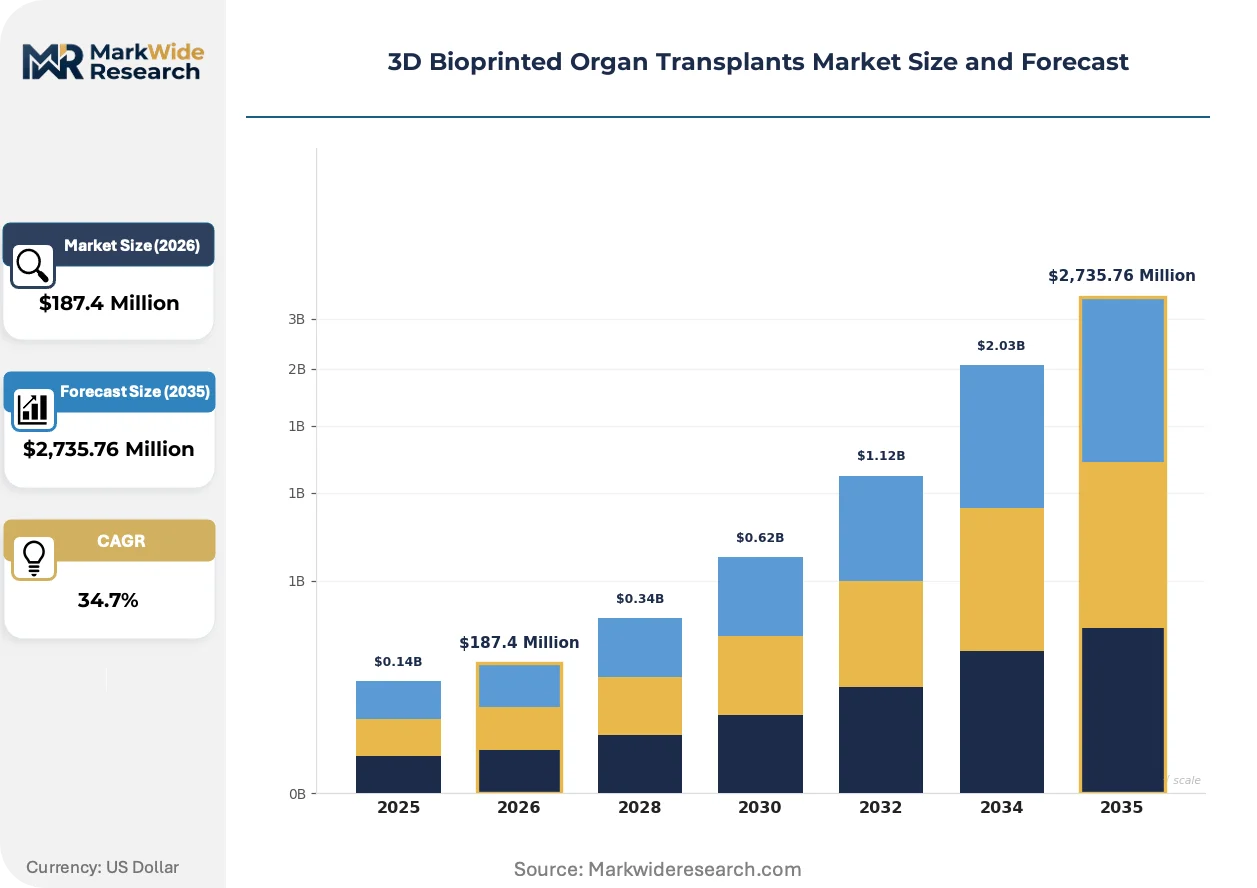
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $2,735.76 Million |
| CAGR (2026 – 2036) | 34.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organ Models, Tissue Constructs, Biomaterials, Perfusion Systems Technology: Extrusion Bioprinting, Laser-Assisted Bioprinting, Stereolithography, Inkjet Bioprinting End User: Research Laboratories, Medical Institutions, Pharmaceutical Companies, Academic Organizations Application: Regenerative Medicine, Drug Testing, Surgical Training, Personalized Medicine |
| Companies Covered | Organovo Holding, Inc., CELLINK, Aspect Biosystems Ltd., Cyfuse Biomedical K.K., Stratasys Ltd., Materialise N.V., EnvisionTEC, REGEMAT 3D, Rokit Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Bioprinted Organ Transplants Market Strategic Shifts
Bioprinting hardware architectures are fragmenting into application-specific configurations, with developers abandoning universal platforms in favor of dedicated systems optimized for single organ categories.
Multi-material extrusion systems with integrated temperature-controlled deposition chambers are modularizing production workflows for heterogeneous tissue constructs. Transplant centers at academic medical centers are adopting these platforms for surgical training applications at twice the pace of pharmaceutical contract research. The technology is modularizing what were previously integrated tissue engineering service offerings into separable hardware, consumables, and protocol licensing revenue streams.
EMA's ATMP framework revisions are tightening traceability requirements for starting materials in biofabricated tissues. Developers must now document chain-of-custody for all biological inputs across decellularization, sterilization, and bioink formulation stages. Cardiac patch manufacturers with existing CE-marked products face the steepest compliance reconfiguration costs.
Hospital procurement committees are unbundling capital equipment purchases from consumables contracts, forcing bioprinter manufacturers to compete on per-print pricing rather than installed-base lock-in. Pharmaceutical companies expanding organ-on-chip alternatives are driving this shift through volume-based sourcing negotiations. The United States exhibits the most pronounced procurement transformation, with CMS reimbursement discussions treating biofabricated tissues as billable therapeutic procedures rather than research tools.
3D Bioprinted Organ Transplants Market Segmentation
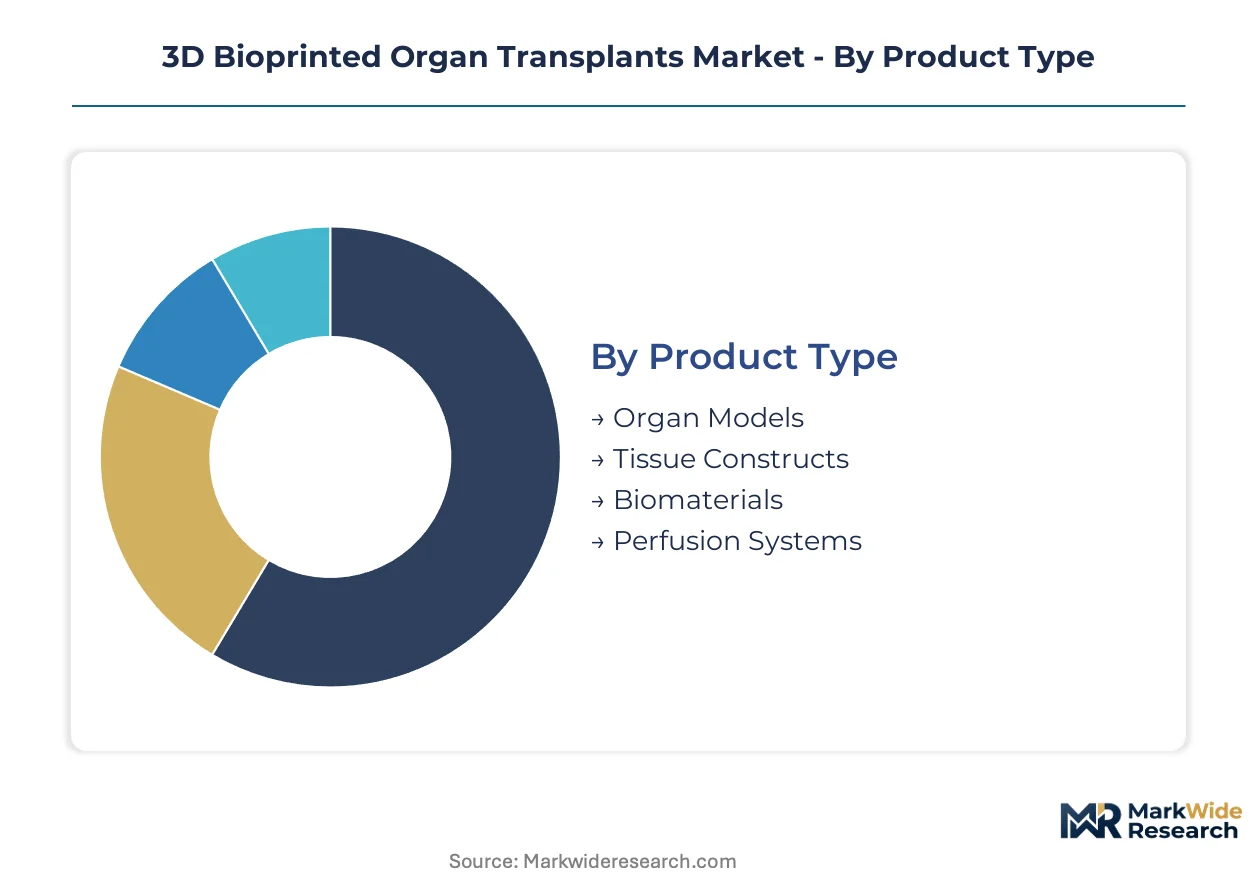
Segmentation in 3D bioprinted organ transplants reveals how technology maturity, regulatory validation burden, and end-user purchasing power fragment commercial opportunity. Product complexity and clinical proximity determine margin architecture across each dimension.
Product Type:
Volume concentrates in consumables and research tools while premium accrues to clinically validated tissue architectures.
- Tissue Constructs:Layered cellular architectures with vascular channel diameters below 200 microns command the highest validation burden and pricing power. Academic medical centers in the United States drive procurement for surgical training applications, with NIH funding creating institutional pull for complex liver and cardiac models.
- Organ Models:Simplified anatomical replicas lacking full vascularization serve pharmaceutical screening and medical education. Research laboratories in Germany and Japan represent concentrated demand as EMA ATMP framework revisions tighten traceability requirements for starting materials.
- Biomaterials:Decellularized extracellular matrix bioinks and synthetic polymer scaffolds constitute the recurring revenue base.
- Perfusion Systems:Bioreactor hardware enabling nutrient delivery to printed tissues during maturation.
Today's leader: Tissue Constructs. Tomorrow's challenger: Organ Models.
Technology:
Application specificity is fragmenting hardware architectures as developers abandon universal platforms.
- Extrusion Bioprinting:Dominates installed base through multi-material deposition of cell-laden bioinks with integrated temperature-controlled chambers. Medical institutions adopt these platforms at twice the pace of pharmaceutical contract research, modularizing previously integrated service offerings into separable hardware and consumables revenue streams.
- Laser-Assisted Bioprinting:Microscale precision enables cardiac patch applications with sub-millimeter cell deposition control. Japanese developers with METI funding access are gaining fastest share expansion in vascular network fabrication.
- Stereolithography:Photopolymerization-based layer curing suits acellular scaffold production.
- Inkjet Bioprinting:Drop-on-demand cell patterning for high-throughput screening applications.
Extrusion Bioprinting anchors current procurement volumes. Laser-Assisted Bioprinting represents the steepest expansion trajectory as cardiac applications mature.
End User:
Customer type determines whether purchases route through capital equipment committees or therapeutic reimbursement pathways.
- Medical Institutions:Academic medical centers concentrate demand for surgical training and preclinical validation. CMS reimbursement discussions in the United States are shifting procurement toward billable therapeutic procedure classification rather than research tool budgeting.
- Pharmaceutical Companies:Organ-on-chip alternatives and toxicity screening drive contract research expansion. These buyers unbundle capital equipment from consumables contracts, forcing per-print pricing competition.
- Research Laboratories:Early-stage tissue engineering and biomaterials characterization.
- Academic Organizations:Basic science and training curriculum development.
Medical Institutions dominate current spending. Pharmaceutical Companies are restructuring vendor economics through volume-based sourcing negotiations.
Application:
Clinical proximity separates premium-priced therapeutic targets from research-tool commoditization.
- Regenerative Medicine:Functional tissue implantation for human transplantation carries the highest regulatory validation burden and reimbursement potential. FDA breakthrough device designation pathways compress trial timelines for developers targeting this segment.
- Drug Testing:Pharmaceutical toxicology and efficacy screening using patient-derived organ models. EMA ATMP framework traceability requirements are reconfiguring compliance costs for CE-marked product manufacturers.
- Surgical Training:Resident education and procedure rehearsal using patient-specific anatomical models.
- Personalized Medicine:Patient-derived tissue fabrication for precision therapy selection.
Regenerative Medicine captures premium positioning. Drug Testing is expanding fastest as pharmaceutical R&D budgets shift toward organ-on-chip alternatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Boston-Cambridge biotech corridor anchors commercial traction for 3D bioprinted organ transplants, with academic medical centers driving procurement of tissue constructs for surgical training and preclinical validation.
United States
NIH funding concentration and CMS reimbursement discussions create institutional pull for complex liver and cardiac models. FDA breakthrough device designation pathways compress clinical trial timelines for developers targeting human transplantation. The San Francisco Bay Area and Research Triangle Park host the densest clusters of extrusion bioprinting installations for pharmaceutical contract research.
Germany
EMA's ATMP framework revisions tighten traceability requirements for starting materials in biofabricated tissues. Research laboratories in Berlin and Heidelberg drive demand for organ models as CE-marked product manufacturers face compliance reconfiguration costs. The country's national pharmaceutical regulator enforces chain-of-custody documentation across decellularization and sterilization stages.
Japan
METI funding access accelerates laser-assisted bioprinting adoption for vascular network fabrication. PMDA regenerative medicine safety provisions create favorable entry conditions for developers with existing ISO 10993 qualification. The Kansai region around Osaka concentrates microfluidic printhead development for sub-millimeter cell deposition control.
United Kingdom
Academic medical centers in London and Cambridge scale tissue construct procurement for resident education and procedure rehearsal. The country's national pharmaceutical regulator aligns with EMA ATMP frameworks while maintaining parallel compliance architectures for multicenter study design. Oxford and Manchester emerge as secondary hubs for biomaterials characterization.
South Korea
MFDS accelerates regulatory pathways for biofabricated tissues targeting cardiac patch applications. Government research allocations support hybrid precision-speed workflows integrating laser-assisted modalities with extrusion platforms. The Seoul Capital Area concentrates pharmaceutical company demand for organ-on-chip alternatives and toxicity screening.
3D Bioprinted Organ Transplants Market Competitive Environment
Global majors compete with regional champions across technology platforms and end-user segments, producing a tiered structure where installed-base dominance and open-system architecture define competitive positioning. The vendor base separates into three strategic archetypes: platform developers with proprietary bioprinting hardware, consumables specialists with biological sourcing partnerships, and hybrid service providers offering integrated tissue engineering contracts. Dominant competitive moves include strategic partnerships with academic medical centers for clinical validation and technology licensing agreements that modularize hardware from consumables revenue streams.
Within the platform developer tier, Organovo Holding, Inc. and CELLINK occupy positions representing contrasting architectural philosophies, while Aspect Biosystems Ltd. exemplifies specialization in microfluidic precision. These three companies anchor the competitive landscape through their representation of distinct technology vectors—proprietary NovoGen platforms, open-system installed-base dominance, and microfluidic sub-millimeter resolution control respectively.
| Leading Market Players |
|---|
| Organovo Holding, Inc. |
| CELLINK |
| Aspect Biosystems Ltd. |
| Cyfuse Biomedical K.K. |
| Stratasys Ltd. |
| Materialise N.V. |
| EnvisionTEC |
| REGEMAT 3D |
| Rokit Healthcare |
| Others |
Value Chain & Pricing Dynamics
Hospital procurement committees unbundling capital equipment from consumables contracts force bioprinter manufacturers to reconfigure pricing architectures around per-print economics rather than installed-base lock-in, compressing margins for vendors lacking biological sourcing partnerships.
Pricing Analysis
Decellularized extracellular matrix bioinks drive input-cost pass-through volatility as porcine and bovine tissue availability fluctuates with agricultural supply conditions. Three-tier pricing structure across premium, standard, and economy levels separates FDA breakthrough-designated tissue constructs from research-grade organ models and basic biomaterial scaffolds. Pricing pressure stems from pharmaceutical companies driving volume-based sourcing negotiations for organ-on-chip alternatives. Academic medical centers exhibit lowest price sensitivity due to NIH funding concentration, while contract research organizations face acute cost compression.
Supply Chain Analysis
Direct-to-hospital tissue engineering service contracts displace traditional capital equipment distribution, with biological inputs drawing from United States, Germany, and Japan decellularization facilities. Raw material dependencies center on porcine-derived matrix, synthetic polymer scaffolds, and recombinant growth factors. Single-source vulnerability concentrates in decellularized matrix suppliers lacking redundant agricultural partnerships. Distribution runs through academic medical center procurement committees and pharmaceutical R&D sourcing teams rather than conventional device distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
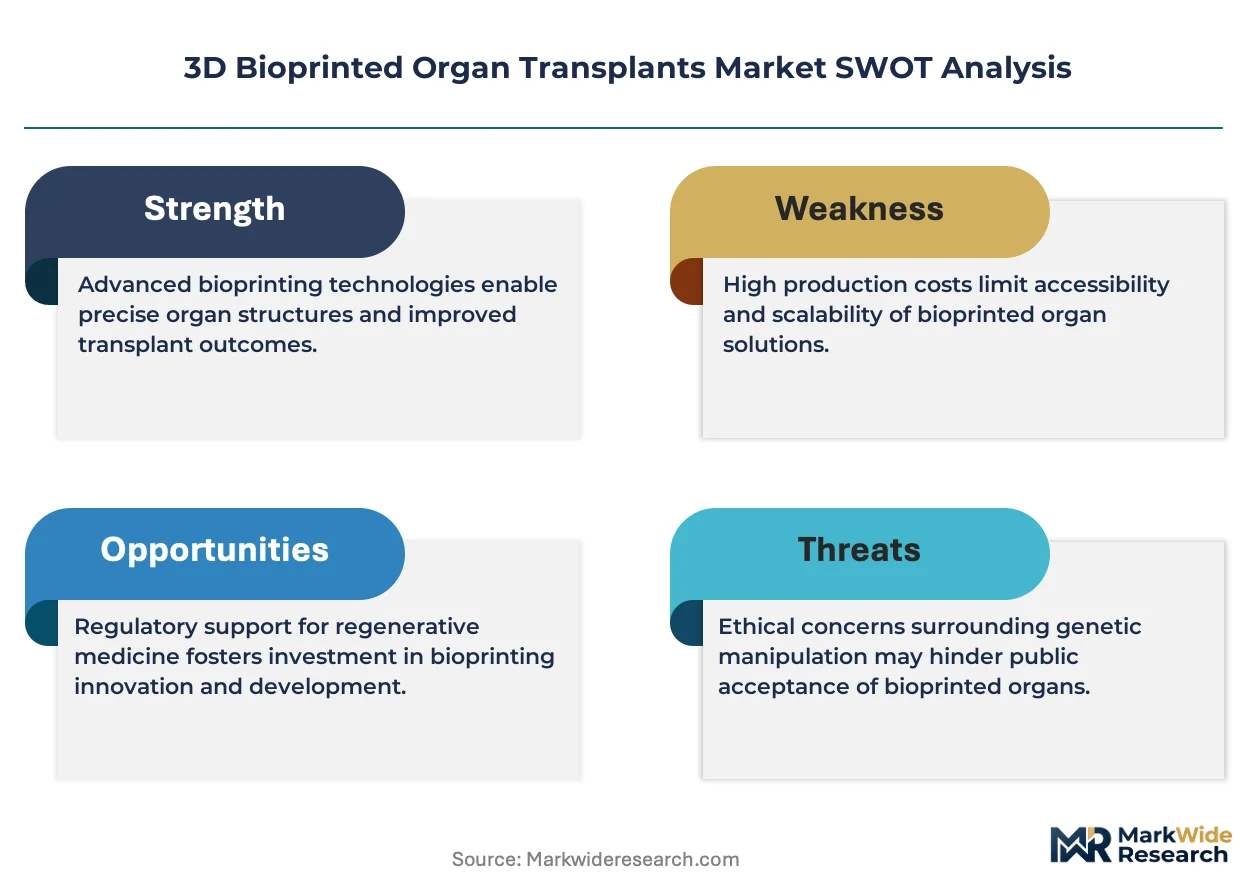
The 3D bioprinted organ transplants market functions as a regulatory compounder where FDA breakthrough device designation pathways accelerate clinical translation timelines and create institutional pull at academic medical centers.
For Market Incumbents: Extend installed-base dominance through open-system architecture that prevents consumables lock-in displacement by modular competitors. Anchor position in liver and cardiac tissue constructs by deepening biological sourcing partnerships with decellularization facilities. Counter laser-assisted bioprinting entrants by integrating microfluidic precision modules into existing extrusion platforms. For New Entrants and Emerging Players: The premium-to-economy price-point gap in vascularized tissue constructs creates entry space for developers with ISO 10993 qualification targeting Japan's PMDA regenerative medicine provisions. Penetrate pharmaceutical contract research segments through per-print pricing models that unbundle hardware from consumables. Lead with organ-on-chip alternatives for toxicity screening applications where traceability requirements remain less stringent than therapeutic implants. For Investors and Strategic Acquirers: Asymmetric upside sits with hybrid service providers offering integrated tissue engineering contracts rather than pure-play hardware manufacturers. Five-to-ten year viability favors developers with existing FDA breakthrough designations and CMS reimbursement pathway engagement. Monitor CMS national coverage determination proceedings as the inflection signal separating research-tool commoditization from therapeutic procedure premiumization.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Compresses clinical trial timelines for human transplantation targets. |
| Biological Sourcing Partnership | Secures decellularized matrix supply chains against agricultural volatility. |
| Microfluidic Printhead Integration | Enables sub-millimeter vascular channel fabrication for cardiac applications. |
| Direct-to-Hospital Service Contract | Displaces capital equipment sales with recurring tissue engineering revenue. |
| CMS Reimbursement Strategy | Positions biofabricated tissues as billable therapeutic procedures. |
Study Parameters
Coverage spans the United States, Germany, Japan, and South Korea, with primary inputs from each market combined with secondary validation. Interviews with tissue engineering executives, regulatory affairs leads at ATMP framework developers, hospital procurement managers, and GMP manufacturing directors anchored qualitative assessment. Secondary sources included FDA breakthrough device filings, EMA ATMP submission databases, NIH funding disclosures, and CMS reimbursement proceeding records. Bottom-up demand modeling triangulated against top-down market sizing across technology platforms.
Granularity-level modeling captured product type, technology modality, end-user segment, and application across the analysis window. CAGRs derived from weighted average of technology adoption curves, regulatory pathway probability assessments, and reimbursement timeline scenarios. Forecast inputs incorporated NIH appropriation trajectories, METI funding allocations, and EMA ATMP framework revision schedules without year-specific assumptions.
Caveats apply where FDA designation delays, agricultural supply disruptions, or CMS negative coverage determinations could materially shift the outlook. Forecasts reflect assumptions about vascularization technical progress and biological input standardization that carry execution risk. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Engineering
Bioactive Bone Grafts Market
Biomedical Engineering
Medical Biomimetics Market
Biomedical Engineering
Biocompatible 3D Printing Market
Biomedical Engineering
Biological Implants Market
Biomedical Engineering
Non-Surgical Bio-Implants Market
Biomedical Engineering
3D Bioprinted Human Tissue Market
Biomedical Engineering
Global Biomedical Tester Market
Biomedical Engineering
3D Bioprinting Market
Biomedical Engineering
Argentina Artificial Organs and Bionic Implants Market
Biomedical Engineering
Tissue Extraction System Market
Biomedical Engineering
Self-Inflating Tissue Expander Market
Biomedical Engineering
Large and Small-Scale Bioprocessing Market
Biomedical Engineering
Biomems Market
Biomedical Engineering
Global Continuous Bioprocessing Market
Biomedical Engineering
Global Robotic Prosthetic Market
Biomedical Engineering
Europe Bioresorbable Vascular Scaffold Market