
 Bioresorbable Scaffolds Market | 2026-2036
Bioresorbable Scaffolds Market Size, Share, and Industry Trends Forecast 2026-2036
Bioresorbable Scaffolds Market Intelligence
Customer demand for bioresorbable scaffolds is consolidating within large, multi-site hospital networks and integrated delivery systems. These large-scale buyers prioritize vendors with extensive clinical data and established supply chains. Abbott leverages its significant R&D investment in cardiovascular devices to maintain a strong market position. Medtronic competes through its broad portfolio and deep relationships with cardiology departments in major hospitals.
Bioresorbable scaffolds are temporary implants designed to support tissue regeneration before being safely absorbed by the body. These devices are often fabricated from polymers like poly-L-lactic acid (PLLA) with specific degradation rates tailored to the healing process. The cardiovascular application segment currently leads the market, driven by interventions for coronary artery disease. Polymer-based products represent the dominant material choice, while research into composite and hydrogel scaffolds is accelerating.
Market access is governed by stringent regulatory approvals from bodies such as the US FDA, Europe's EMA, and China's NMPA. These agencies mandate extensive pre-clinical and clinical trials to verify both safety and efficacy, influencing development timelines. Future material selection and device design will hinge on balancing clinical performance requirements with the evolving standards for long-term patient outcomes.
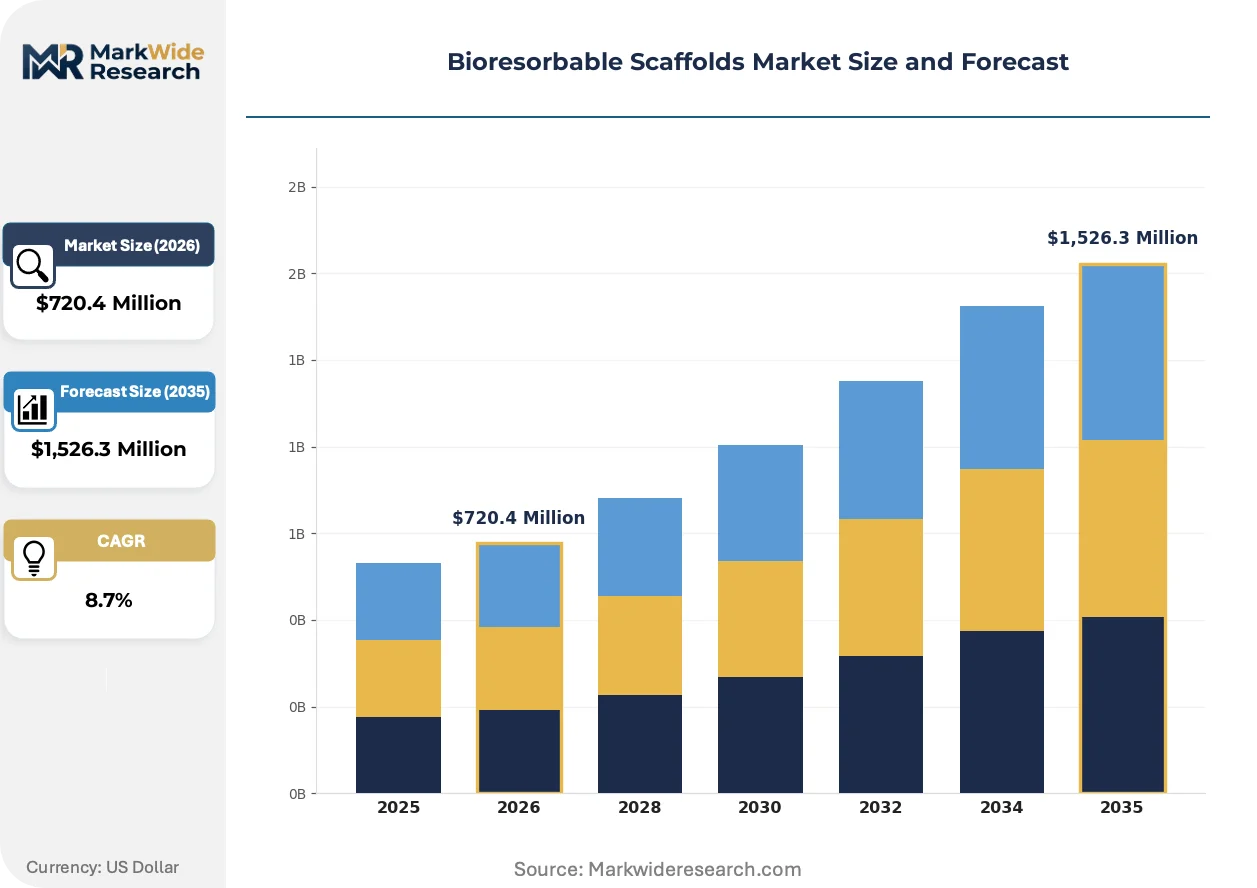
Market Dynamics
The central dynamic shaping the bioresorbable scaffolds market is the clinical imperative to improve long-term outcomes in cardiovascular disease treatment. This drives intense material science research to overcome the limitations of first-generation devices and perfect degradation profiles.
Growth Catalysts
- Material Science Advancement:Innovations in poly-L-lactic acid (PLLA) and other biocompatible polymers are creating scaffolds with more predictable absorption rates and improved mechanical strength, enhancing patient safety and efficacy in cardiovascular applications.
- Expanding Clinical Use:The rising incidence of coronary artery disease, particularly within aging populations in developed nations like Japan and Germany, is expanding the addressable patient pool for minimally invasive cardiovascular interventions.
- Regulatory Pathways:Clearer guidance from agencies like the US FDA on pre-clinical and clinical trial requirements for novel biomaterials is providing a more predictable, albeit lengthy, pathway for new device approvals.
Market Restraints
- Stringent Regulatory Hurdles:Extensive and costly clinical trials mandated by regulatory bodies such as the EMA and China's NMPA significantly increase development timelines and create high barriers to entry for new manufacturers.
- Technical Performance Challenges:Achieving a scaffold degradation rate that perfectly matches the variable healing process of each patient remains a significant technical challenge, with risks of premature collapse or late-term adverse events.
- High Manufacturing Costs:The complex fabrication processes and high cost of medical-grade polymers like PLLA result in a premium price point for bioresorbable scaffolds, limiting their adoption in cost-sensitive healthcare systems.
Strategic Opportunities
- New Therapeutic Areas:There is significant potential for applying bioresorbable scaffold technology beyond cardiology into new areas like orthopedics for bone grafting and soft tissue engineering for wound healing and reconstruction.
- Combination Devices:Integrating scaffolds with drug-eluting technologies offers a pathway to create advanced devices that provide mechanical support while delivering therapeutic agents to promote healing and prevent complications like restenosis.
- Geographic Expansion:Underpenetrated markets in Asia-Pacific, particularly China and India, represent a substantial opportunity as healthcare spending increases and access to advanced medical technologies improves for a large patient population.
Industry Challenges
- Specialized Talent Scarcity:The development and manufacturing of these devices require a highly specialized workforce with expertise in biomaterials science, polymer chemistry, and precision engineering, creating a competitive hiring environment. *Lack of Standardization: The absence of globally harmonized standards for testing the long-term biocompatibility and degradation byproducts of novel scaffold materials creates uncertainty for both developers and clinicians.
- Complex Supply Chain Logistics:Maintaining the sterility and structural integrity of polymer-based scaffolds requires sophisticated, temperature-controlled logistics and handling protocols, adding complexity and cost to distribution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bioresorbable Scaffolds Market |
| Market Size in 2026 | $720.4 Million |
| Market Size in 2035 | $1,526.3 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymer-based, Ceramics, Composite, Hydrogels Application: Tissue Engineering, Orthopedics, Cardiovascular, Dental End User: Hospitals, Clinics, Research Institutes, Biotech Companies Delivery Mode: Surgical Procedures, Endovascular Procedures, Implantation, Injection |
| Companies Covered | Abbott, Boston Scientific Corporation, Medtronic, BIOTRONIK, Elixir Medical, REVA Medical, Kyoto Medical Planning, Amaranth Medical, Meril Life Sciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bioresorbable Scaffolds Market Strategic Shifts & Innovations
Material science is defining the next generation of bioresorbable scaffolds, enabling designs that are more closely tailored to specific clinical needs. This evolution focuses on enhancing biocompatibility, controlling degradation kinetics, and improving long-term patient outcomes.
Composite scaffolds combining polymers with bioactive materials like hydroxyapatite are gaining traction. These materials are engineered to provide initial mechanical stability while actively encouraging new tissue formation. Orthopedic and maxillofacial surgery segments are early adopters, using these composites for complex reconstructions where promoting natural bone growth is critical. This technology is absorbing the clinical risk associated with permanent metallic implants in non-load-bearing applications.
The European Union's Medical Device Regulation (MDR) is setting a higher bar for clinical evidence. It requires manufacturers to conduct more rigorous post-market surveillance and long-term clinical follow-up for high-risk devices, including bioresorbable scaffolds. This directly impacts all companies seeking access to the European market, forcing greater investment in generating robust data to maintain CE marking and prove long-term safety and performance.
A shift from single-product purchasing to procurement of comprehensive procedural solutions is underway. Large, integrated hospital networks are bypassing simple device transactions in favor of strategic partnerships with vendors who can bundle scaffolds with associated imaging systems and clinical support. This trend is most visible in the consolidated healthcare systems of the United States and Germany, altering the competitive landscape for suppliers.
Bioresorbable Scaffolds Market Segmentation
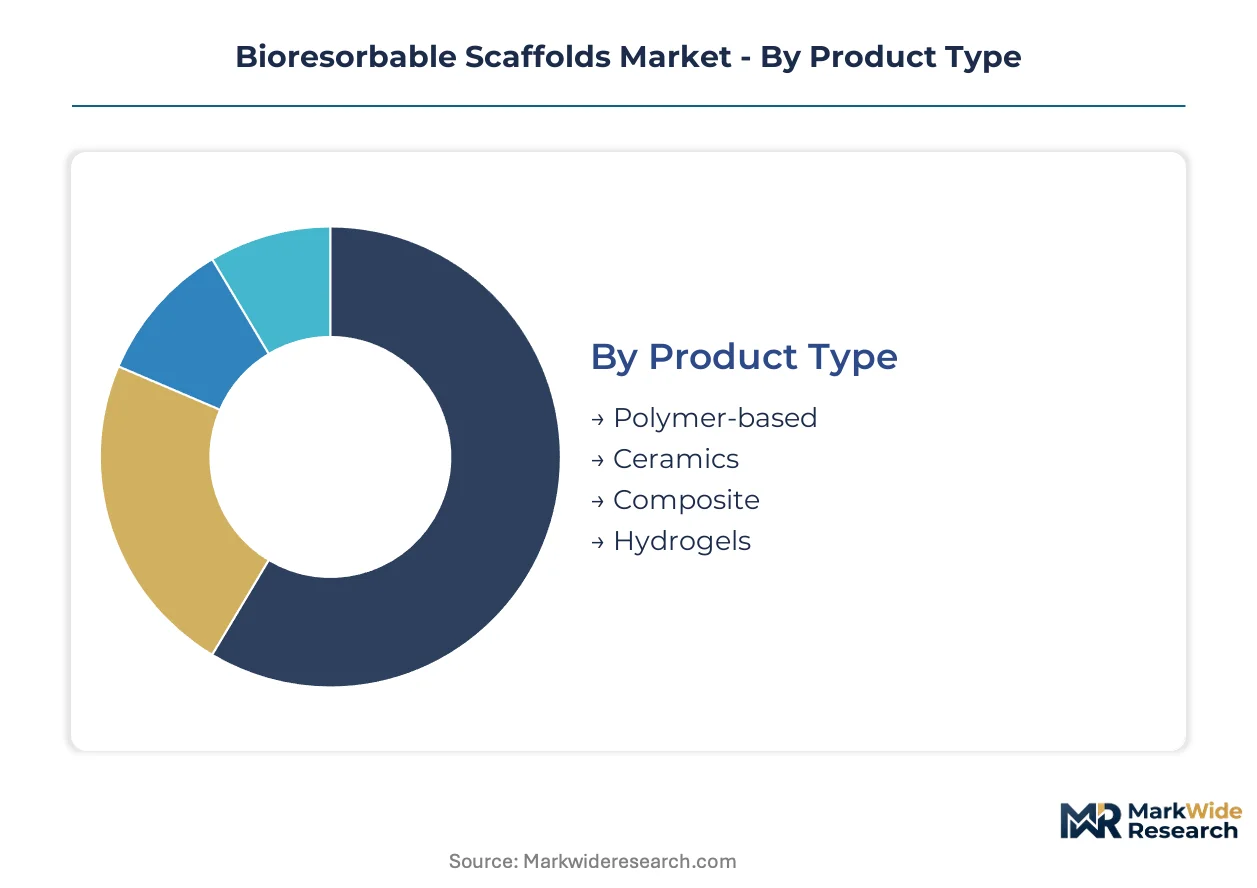
Understanding the segmentation of the bioresorbable scaffolds market is crucial for identifying areas of concentrated demand and emerging growth trajectories. This granular analysis reveals how different product types, applications, end users, and delivery modes shape the competitive landscape and influence investment decisions.
Product Type:
Supply concentration for bioresorbable scaffolds largely revolves around the material science capabilities and manufacturing infrastructure required for specific product types.
- Polymer-based:These scaffolds, often derived from poly-L-lactic acid (PLLA), offer tunable degradation rates and mechanical properties for temporary tissue support. Demand concentrates within cardiovascular applications, especially for coronary artery disease treatment, due to their established biocompatibility.
- Composite:Combining polymers with bioactive elements like hydroxyapatite, these scaffolds provide initial structural integrity and actively promote tissue regeneration. Orthopedic and maxillofacial surgery segments are early adopters, leveraging these materials for complex reconstructions requiring natural bone growth.
- Ceramics:Fabricated from materials such as calcium phosphate, ceramic scaffolds offer high compressive strength for bone repair applications.
- Hydrogels:These highly porous, water-rich scaffolds are suitable for soft tissue engineering and drug delivery due to their excellent biocompatibility.
Polymer-based products absorb the bulk of installed capacity; Composite scaffolds are expanding most quickly.
Application:
Volume output for bioresorbable scaffolds directly correlates with the prevalence and treatment pathways of various medical conditions.
- Cardiovascular:Bioresorbable scaffolds are critical for coronary artery disease interventions, providing temporary support to vessels before complete absorption. The rising incidence of heart conditions in aging populations, particularly in the United States and Germany, drives significant demand.
- Orthopedics:These scaffolds facilitate bone repair and regeneration, particularly in non-load-bearing applications and complex fracture management. Innovations in composite materials are expanding their utility in spinal fusion and joint reconstruction procedures.
- Tissue Engineering:Scaffolds provide a structural matrix for cell growth and differentiation in regenerative medicine, supporting the development of new tissues.
- Dental:Used in guided bone regeneration and periodontal tissue repair, dental applications leverage scaffolds for their biocompatibility and osteoconductive properties.
Demand for Cardiovascular applications drives significant investment, while Tissue Engineering presents emergent opportunities.
End User:
Customer type segmentation highlights the diverse procurement and utilization patterns for bioresorbable scaffolds across the healthcare ecosystem.
- Hospitals:Large, multi-site hospital networks and integrated delivery systems represent major purchasers, prioritizing vendors with extensive clinical data and robust supply chains. These institutions focus on comprehensive procedural solutions that bundle devices with clinical support.
- Research Institutes:These entities are critical for the development and testing of novel scaffold materials and designs, contributing to preclinical and early-stage clinical validation. Their focus is on advancing material science and expanding therapeutic applications.
- Clinics:Specialized clinics, particularly in orthopedics and dentistry, utilize bioresorbable scaffolds for specific outpatient procedures.
- Biotech Companies:These firms often develop and commercialize new scaffold technologies, collaborating with academic institutions and contract manufacturers.
Procurement patterns among Hospitals influence device design, and Research Institutes contribute to foundational research.
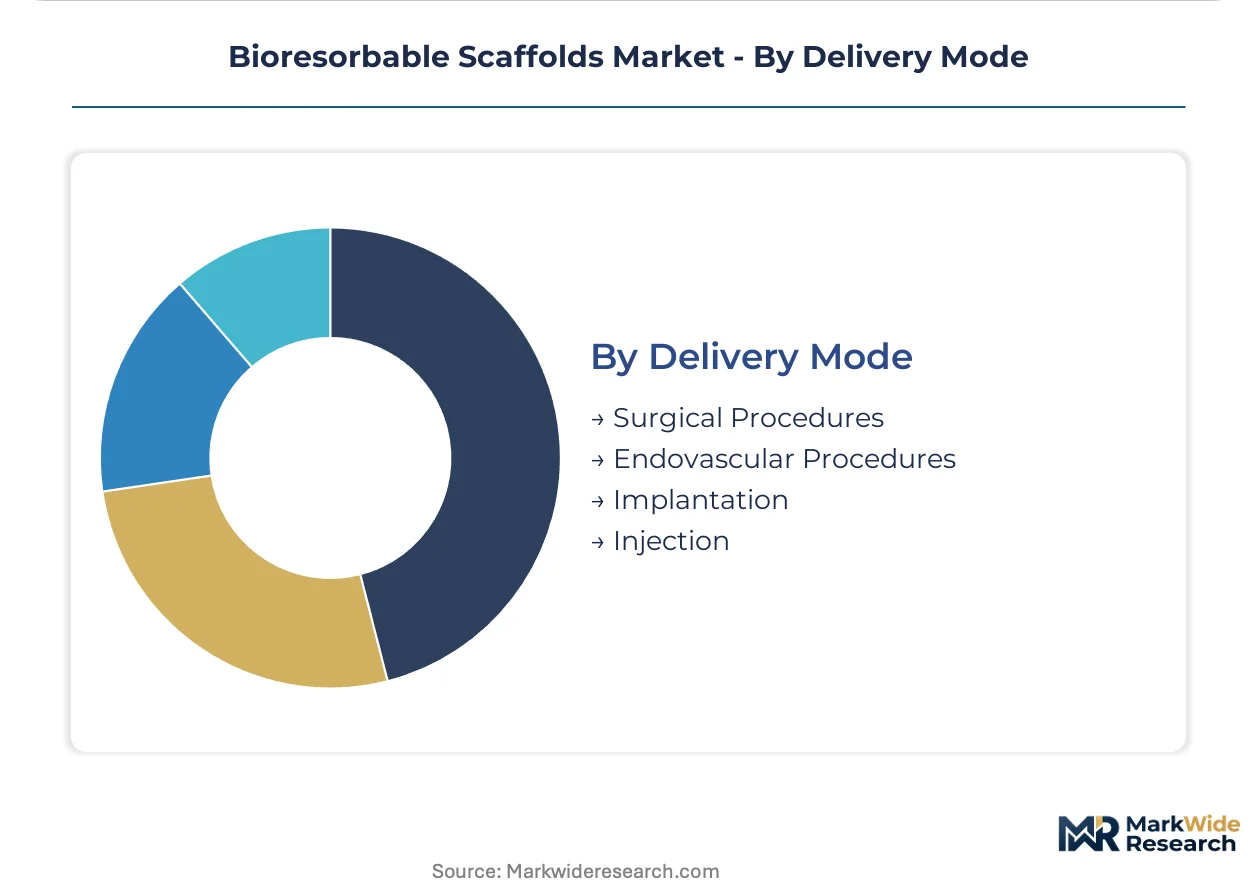
Delivery Mode:
Technological sophistication in delivery modes reflects the evolution towards less invasive and more precise application of bioresorbable scaffolds.
- Endovascular Procedures:These minimally invasive techniques, primarily used in cardiovascular interventions, involve delivering scaffolds through catheters to target sites. They offer reduced patient recovery times and lower procedural risks compared to open surgery.
- Implantation:This broad category encompasses direct surgical placement of scaffolds into the body, common in orthopedic and soft tissue repair. Precision in surgical technique is paramount for optimal device integration and healing.
- Surgical Procedures:Traditional open surgical methods are employed for larger or more complex scaffold placements, particularly in reconstructive surgeries.
- Injection:Emerging delivery methods involve injectable hydrogels or microspheres, offering non-invasive application for tissue regeneration in specific areas.
The evolution of Endovascular Procedures reduces patient recovery times, and Injection expands non-invasive treatment options.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Customer demand for bioresorbable scaffolds is concentrating within large, multi-site hospital networks and integrated delivery systems. These major purchasers prioritize vendors with extensive clinical data and established supply chains. This demand pattern shapes regional market development and investment priorities across key geographies.
United States
Cardiovascular applications for coronary artery disease drive significant demand in the United States. The US FDA mandates extensive pre-clinical and clinical trials for new device approvals, influencing development timelines. Major medical device hubs in Boston and Minneapolis foster innovation in material science and device design.
Germany
The aging population and high incidence of coronary artery disease fuel demand for bioresorbable scaffolds in Germany. European Medical Device Regulation (MDR) sets stringent requirements for post-market surveillance and long-term clinical follow-up. Specialized hospital systems in regions like Bavaria and North Rhine-Westphalia are key adoption centers.
Japan
An expanding elderly population in Japan creates a growing patient pool for minimally invasive cardiovascular interventions. The Pharmaceuticals and Medical Devices Agency (PMDA) oversees strict approval processes for novel biomaterials and devices. Research institutions in Tokyo and Osaka are actively exploring advancements in polymer-based scaffold technologies.
China
Increasing healthcare spending and access to advanced medical technologies generate substantial opportunities in China. The National Medical Products Administration (NMPA) enforces rigorous pre-clinical and clinical trial requirements for market entry. Major urban centers like Shanghai and Beijing are becoming crucial for clinical adoption and local manufacturing initiatives.
India
Rising incidence of cardiovascular diseases and improving healthcare infrastructure contribute to demand in India. The Central Drugs Standard Control Organization (CDSCO) regulates medical device approvals, impacting market access for international manufacturers. Emerging medical device clusters around cities like Chennai and Hyderabad are developing local production capabilities.
Bioresorbable Scaffolds Market Key Industry Players
United States producers anchor one tier of the bioresorbable scaffolds market; European specialists hold a strong position in advanced material development and regulatory compliance. The market exhibits a tiered structure, with established medical device giants competing alongside specialized biomaterials innovators. Key strategic archetypes include large diversified healthcare conglomerates focusing on cardiovascular applications and smaller firms specializing in novel material science. Companies often pursue strategic partnerships and portfolio diversification to enhance their market presence and address new therapeutic areas.
Among the established medical technology companies, Medtronic and Abbott exemplify market leaders with extensive R&D investments and broad product portfolios in cardiovascular devices. These companies leverage their deep relationships with cardiology departments in major hospitals to maintain strong market positions. Boston Scientific Corporation also represents a significant player, contributing to the development of advanced cardiovascular devices and expanding clinical applications. Their market presence is built on a foundation of robust clinical data and established supply chains, influencing procurement patterns in large hospital networks. These firms continuously adapt to evolving regulatory standards from bodies like the US FDA and EMA.
| Leading Market Players |
|---|
| Abbott |
| Boston Scientific Corporation |
| Medtronic |
| BIOTRONIK |
| Elixir Medical |
| REVA Medical |
| Kyoto Medical Planning |
| Amaranth Medical |
| Meril Life Sciences |
| Others |
Cost & Logistics Intelligence
Advancements in polymer science and precision manufacturing techniques simultaneously reshape cost economics and supply concentration for bioresorbable scaffolds. These innovations, while enhancing product performance, introduce specialized input requirements and complex fabrication steps, influencing the market's pricing and supply chain dynamics.
Pricing Analysis
Volume output for bioresorbable scaffolds commands lower margins than specialized product lines, reflecting the market's value-based pricing model. Price differentiation stems from the specific polymer grade used, such as poly-L-lactic acid (PLLA), and the level of US FDA or EMA certification achieved. Pricing pressure stems from the intensive R&D and manufacturing costs associated with novel biomaterials. Hospitals, particularly large integrated networks, exhibit lower price sensitivity due to the clinical benefits and comprehensive procedural solutions offered, while research institutes are more cost-conscious.
Supply Chain Analysis
Supply for critical polymer-based materials like poly-L-lactic acid (PLLA) rests on a limited number of specialty chemical producers, primarily located in the United States and Europe. Raw material dependencies include medical-grade polymers and bioactive elements such as hydroxyapatite. Single-source vulnerability for specialized raw materials presents a significant supply chain risk. Distribution runs through a network of direct sales forces and specialized medical device distributors, ensuring careful handling and temperature-controlled logistics to hospitals and clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a supply-constrained story, with specialized manufacturing capacity and stringent regulatory approval processes creating bottlenecks that prop up pricing.
For Market Incumbents:Deepen R&D investment in next-generation composite and hydrogel scaffolds to maintain a technological edge against emerging biomaterials innovators. Expand clinical data generation for long-term patient outcomes, particularly under the European MDR requirements, to reinforce market access. Further integrate supply chains for critical polymer inputs to mitigate single-source vulnerabilities and ensure consistent material quality. Leverage existing relationships with cardiology departments in major hospitals to drive adoption of new product iterations.
For New Entrants and Emerging Players:Begin with niche applications in orthopedic and maxillofacial surgery, where composite scaffolds are gaining traction and competition is less entrenched than in cardiovascular. Target underpenetrated markets in Asia-Pacific, such as China and India, where increasing healthcare spending creates new demand. A focused go-to-market angle concentrating on specific material innovations or unique degradation profiles can differentiate offerings. Partner with research institutes to accelerate preclinical validation and secure early clinical data.
For Investors and Strategic Acquirers:Exit pathways concentrate in specialized biomaterials innovators with strong intellectual property in polymer chemistry or advanced scaffold designs. The long-term viability of this market remains strong, driven by aging populations and the imperative for improved regenerative medicine outcomes over the next decade. Acquisition targets should possess robust clinical trial pipelines and established regulatory pathways in key geographies. A signal to watch is the successful completion of Phase III clinical trials for non-cardiovascular indications, indicating broader market applicability.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Robust clinical data validates long-term safety and efficacy for new device approvals with regulatory bodies. |
| Manufacturing Scale-Up | Expanding specialized production capacity addresses supply constraints for high-demand polymer-based scaffolds. |
| Hospital System Partnership | Collaborating with large hospital networks ensures market access and integrates devices into comprehensive procedural solutions. |
| Portfolio Diversification | Developing scaffolds for orthopedics and tissue engineering reduces reliance on the competitive cardiovascular segment. |
| Regulatory Approval Pathway | Navigating stringent requirements from the US FDA and EMA secures market entry and competitive advantage. |
Research Approach
Multi-period observation of market growth rates and technological innovation anchored the trend analysis, supplemented by interviews with cardiovascular surgeons, biomaterials scientists, hospital procurement managers, and regulatory affairs specialists. Secondary validation involved extensive review of US FDA filings, EMA submissions, clinical trial registries, and medical device databases. This approach enabled comprehensive bottom-up and top-down triangulation of market data.
The analytical framework utilized an input-output matrix to model market dynamics across the analysis window. Segmentation dimensions included product type, application, end user, delivery mode, and regional regulatory environment. Compound annual growth rates were derived from historical trends and projected market drivers, incorporating inputs such as the rising incidence rates of coronary artery disease and evolving polymer material costs.
Underlying measurement precision varies by segment; cardiovascular applications and polymer-based products carry tighter precision than others. Forecasts reflect assumptions regarding regulatory stability and technological progression. Unforeseen regulatory changes, breakthroughs in alternative treatments, or significant supply chain disruptions represent risk factors that could revise projections. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Engineering
Tissue Extraction System Market
Biomedical Engineering
3D Bioprinting Market
Biomedical Engineering
Artificial Organ Bank Market
Biomedical Engineering
Biological Implants Market
Biomedical Engineering
Bioabsorbable Implant Market
Biomedical Engineering
Protein Engineering Market
Biomedical Engineering
Biological Derived Devices Market
Biomedical Engineering
Bioactive Coating Devices Market
Biomedical Engineering
North America Lab-On-A-Chip and Microarrays (Biochip) Market
Biomedical Engineering
Non-Surgical Bio-Implants Market
Biomedical Engineering
Bionic Eye Market
Biomedical Engineering
Bioimplants Market
Biomedical Engineering
Argentina Artificial Organs and Bionic Implants Market
Biomedical Engineering
Global Single Use Bioprocessing Probes and Sensors Market
Biomedical Engineering
Global Biomedical Tester Market
Biomedical Engineering
Global Bovine-Based Collagen for Biomedical Applications Market