
 Self-Inflating Tissue Expander Market | 2026-2036
Self-Inflating Tissue Expander Market Size, Share, and Industry Trends Forecast 2026-2036
Self-Inflating Tissue Expander Market Analytics
Aftermarket service revenue is fragmenting across the self-inflating tissue expander value chain as manufacturers diversify beyond device sales. AbbVie Inc. leverages its Allergan Aesthetics heritage to sustain deep surgeon relationships and high-touch clinical support programs. Mentor Worldwide LLC anchors its position through integrated training ecosystems that lock in hospital procurement committees. PMT Corporation specializes in niche neurosurgical and reconstructive applications where technical specifications command premium positioning.
A self-inflating tissue expander comprises a silicone elastomer shell with an integrated osmotic or gas-generating mechanism that enables gradual tissue distension without external inflation ports or percutaneous needles; typical devices achieve expansion volumes of 100-1000 mL over 2-8 week protocols to generate vascularized soft tissue flaps for subsequent reconstructive transfer. Silicone expanders dominate current procurement volumes due to decades of biocompatibility data and established reimbursement codes, while smart expanders incorporating wireless pressure sensors represent the fastest-growing technology segment as remote patient monitoring protocols gain surgical adoption. Active tissue expansion systems capture the majority of margin pools through disposable valve and reservoir components, whereas biodegradable material platforms remain nascent with limited commercial scale.
The FDA's Class II 510(k) pathway governs device clearance for US market entry, while the EU Medical Device Regulation (MDR) imposes stricter clinical evidence requirements that extend certification timelines for European commercialization. Japan's PMDA maintains distinct biocompatibility testing protocols that create incremental regulatory burden for multinational manufacturers seeking Asian market access. Stakeholders must monitor evolving reimbursement decisions by CMS and parallel bodies in Germany and Japan, as coverage determinations for remote monitoring-enabled expanders will reshape competitive positioning between integrated device platforms and conventional passive systems.
Market Dynamics
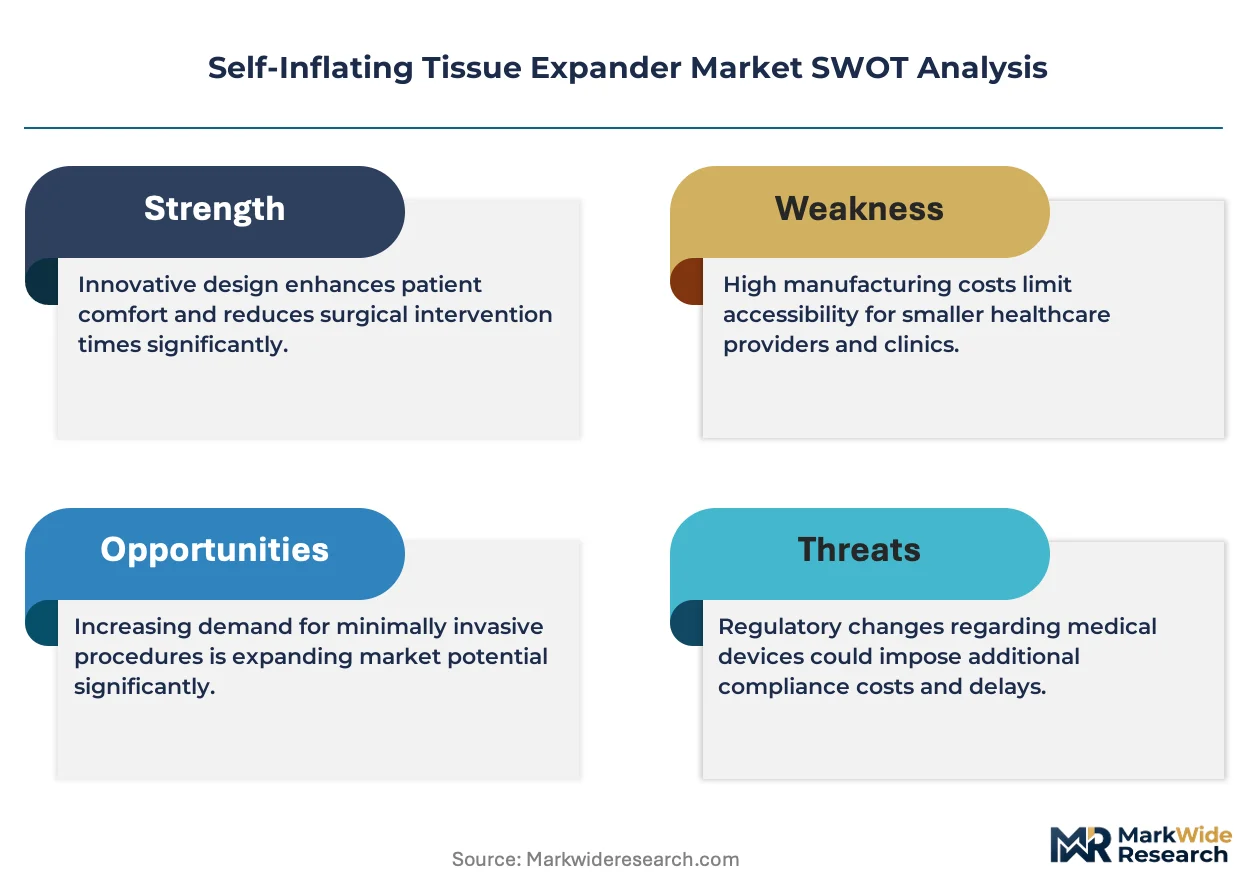
The self-inflating tissue expander market is experiencing structural pressure from the convergence of remote patient monitoring mandates and reimbursement code evolution, which is compressing development cycles for integrated sensor-enabled devices while elevating clinical evidence requirements for conventional passive systems.
Growth Catalysts
- FDA Class II 510(k) pathway:The streamlined clearance mechanism accelerates time-to-market for incremental device innovations, enabling manufacturers to iterate shell geometries and osmotic engine formulations without full premarket approval burdens.
- Post-mastectomy breast reconstruction protocols:Major hospital systems in the United States have institutionalized tissue expansion as standard-of-care, creating embedded demand for devices that reduce percutaneous infection risk.
- Silicone elastomer biocompatibility data:Decades of implant safety surveillance has generated regulatory precedent that lowers barriers for new market entrants utilizing established shell materials.
Market Restraints
- Medical-grade silicone supply concentration:Specialty elastomer production clusters in Germany and Japan, exposing device manufacturers to input cost volatility and geopolitical supply disruptions.
- EU MDR clinical evidence requirements:The expanded certification timelines for European commercialization delay revenue recognition and strain smaller manufacturers' liquidity positions.
- Biodegradable polymer performance limitations:Degradation rate variability and mechanical strength trade-offs constrain adoption in high-volume expansion protocols.
Strategic Opportunities
- Japan's aging demographic:The country's reconstructive surgery volume growth and PMDA biocompatibility protocol alignment with ISO standards create accessible expansion potential for compliant manufacturers.
- Wireless pressure sensor integration:Convergence of implantable telemetry with cloud-based monitoring platforms enables remote patient management and differentiated reimbursement positioning.
- Neurosurgical tissue expansion applications:Cranial reconstruction and scalp defect protocols represent underpenetrated indications with premium pricing tolerance.
Industry Challenges
- ISO 10993 biocompatibility testing capacity:Contract laboratory bottlenecks extend pre-submission timelines and compress development runway for competitive product launches.
- Surgeon training ecosystem integration:Device manufacturers must embed within hospital credentialing programs and residency curricula to secure procurement committee preference.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Self-Inflating Tissue Expander Market |
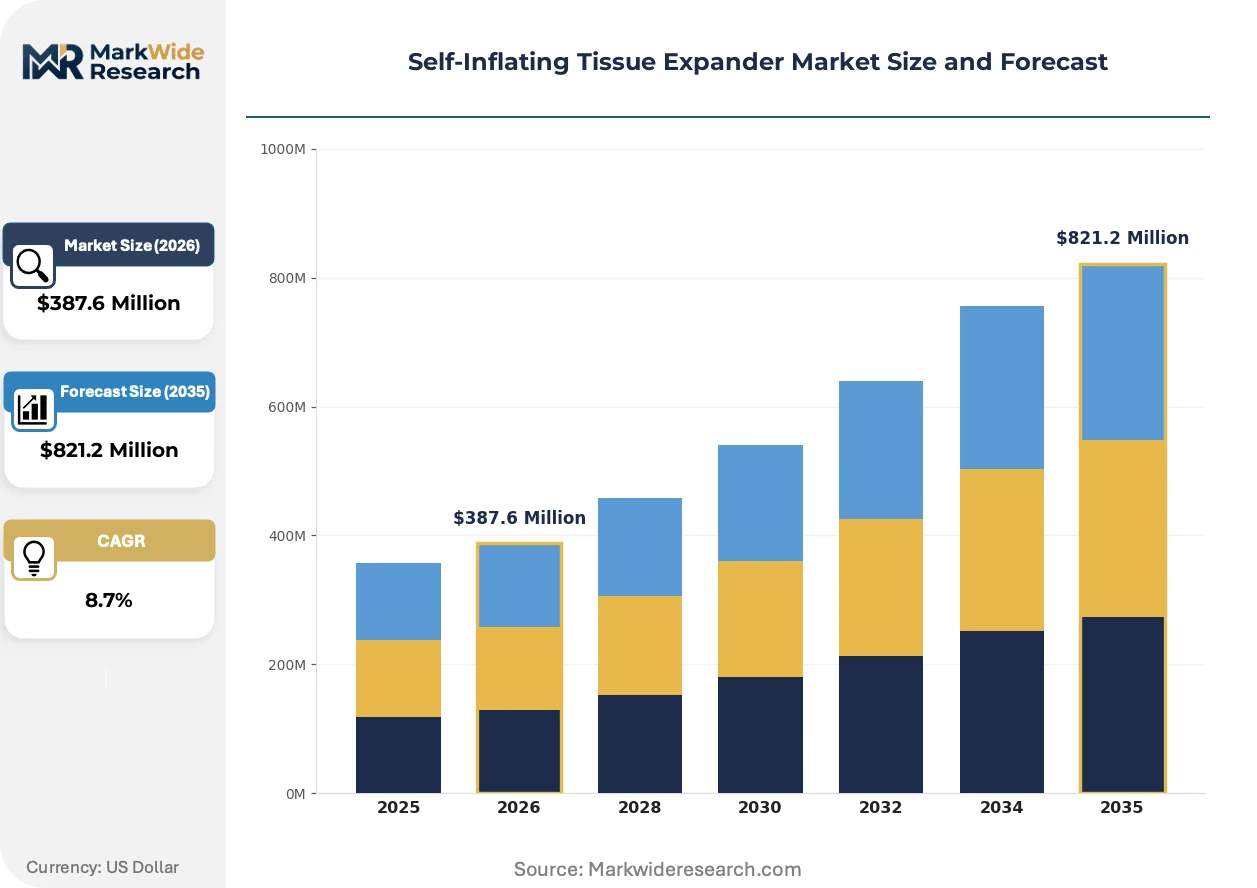
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone Expanders, Saline Expanders, Hybrid Expanders, Temporary Expanders End User: Hospitals, Ambulatory Surgical Centers, Clinics, Home Healthcare Application: Reconstructive Surgery, Aesthetic Enhancement, Trauma Repair, Tissue Regeneration Technology: Active Tissue Expansion, Passive Tissue Expansion, Biodegradable Materials, Smart Expanders |
| Companies Covered | AbbVie Inc., Mentor Worldwide LLC, PMT Corporation, Sientra, Inc., AirXpanders, Inc., Osmed GmbH, Sebbin, Guangzhou Wanhe Plastic Material Co.,Ltd, KOKEN CO., LTD., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Self-Inflating Tissue Expander Market Evolving Landscape
Wireless sensor integration and remote monitoring protocols are fundamentally restructuring competitive advantage in tissue expansion, shifting value capture from device fabrication to data-enabled care coordination and post-operative management services.
Smart expanders incorporating implantable pressure transducers and Bluetooth Low Energy transmission modules are collapsing the distinction between passive mechanical devices and active therapeutic platforms. Academic medical centers in the United States are piloting these systems for outpatient expansion monitoring, reducing clinic visit frequency and enabling earlier complication detection. The technology is compressing margin pools for conventional osmotic expanders while opening recurring revenue streams through disposable sensor arrays and cloud analytics subscriptions.
The EU Medical Device Regulation's strengthened clinical evidence requirements for Class IIb implantables are extending certification timelines and elevating post-market surveillance obligations. Manufacturers must now generate prospective clinical data for equivalence claims, increasing regulatory affairs headcount and documentation burden. European commercialization strategies are adapting through earlier notified body engagement and parallel US-EU study designs to amortize evidence generation costs across jurisdictions.
Hospital procurement committees are consolidating vendor relationships around integrated training and clinical support ecosystems rather than discrete device transactions. High-touch surgeon education programs and procedural simulation platforms are displacing traditional distributor-mediated sales models. This behavioral shift is most pronounced in United States health systems where value-based care contracts reward outcomes and reduce episode-of-care variation.
Self-Inflating Tissue Expander Market Segmentation
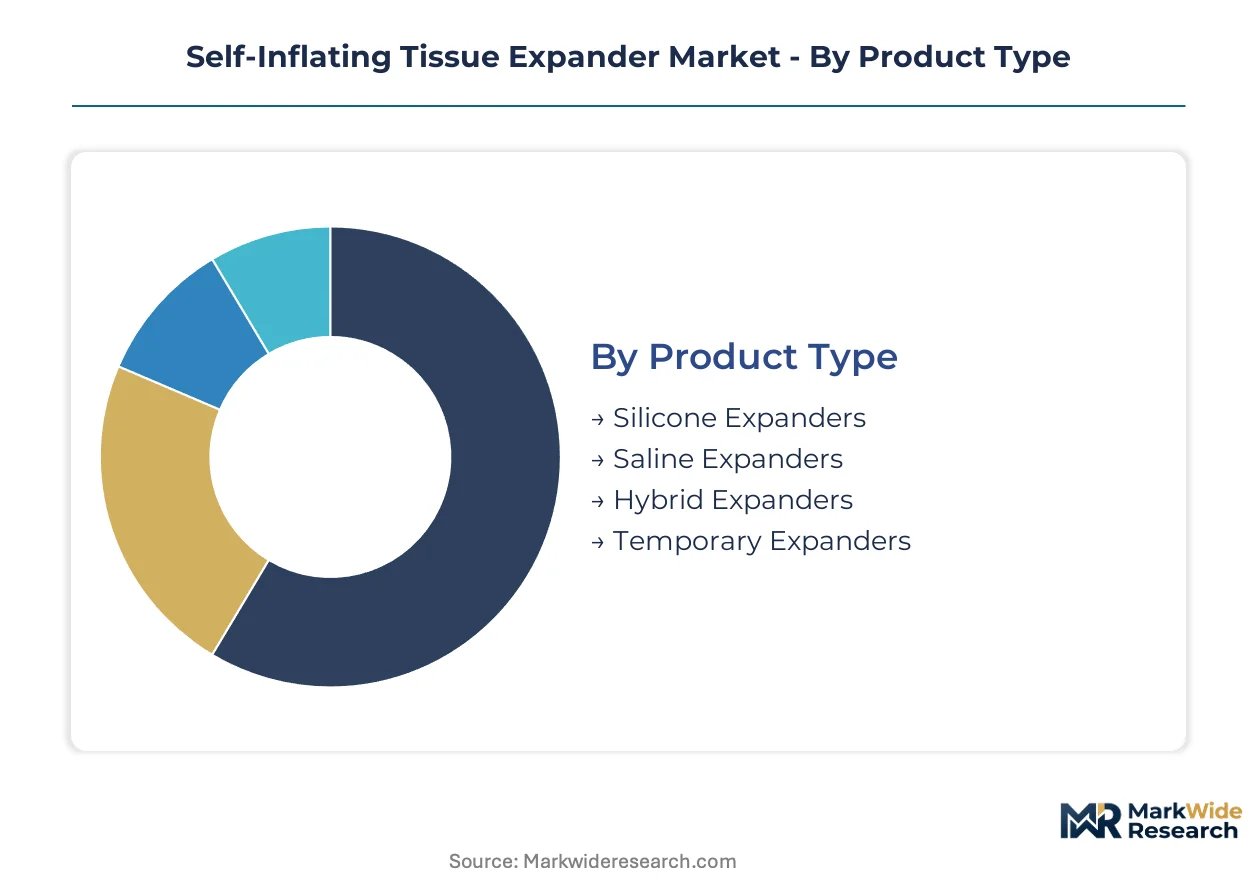
Segmentation reveals how device manufacturers must configure service intensity and technical support around distinct clinical workflows. Each category carries unique margin profiles and regulatory evidence requirements that reshape go-to-market economics.
Product Type:
After-sales service intensity varies sharply across shell materials, with silicone-based platforms demanding specialized repair protocols and saline systems requiring fluid management training programs.
- Silicone Expanders:These devices utilize medical-grade silicone elastomer shells with integrated osmotic engines for controlled tissue distension. Demand concentrates in United States hospital systems where decades of biocompatibility data support favorable reimbursement positioning and surgeon familiarity reduces training burden.
- Saline Expanders:These systems employ external or internal reservoirs with biocompatible saline solutions for gradual inflation. United States ambulatory surgical centers favor these devices for cost-sensitive protocols where simpler mechanics reduce per-procedure overhead and inventory complexity.
- Hybrid Expanders:Combines silicone structural elements with alternative fill mechanisms for specialized anatomical applications.
- Temporary Expanders:Short-duration devices designed for pre-flap conditioning in trauma and acute reconstructive settings.
Silicone expanders hold the largest share; momentum sits with hybrid configurations that bridge performance and cost optimization.
End User:
Procurement authority and technical support requirements diverge across care settings, with hospital committees prioritizing integrated training ecosystems while outpatient facilities emphasize device simplicity and rapid turnover.
- Hospitals:Major United States health systems anchor procurement volumes through value-based care contracts that reward standardized outcomes and reduced episode variation.
- Ambulatory Surgical Centers:These facilities capture expanding share through streamlined expansion protocols that minimize post-operative monitoring infrastructure and enable same-day discharge.
- Clinics:Private practice settings in United States metropolitan corridors drive demand for compact device formats with simplified insertion techniques.
- Home Healthcare:Emerging segment supported by remote monitoring-enabled expanders that permit patient-managed expansion with telemetry oversight.
Hospitals dominate current procurement; home healthcare is expanding most quickly as remote patient monitoring protocols mature.
Application:
Clinical evidence requirements and pricing tolerance fluctuate across indication types, with oncologic reconstruction commanding premium positioning and trauma applications demanding rapid availability.
- Reconstructive Surgery:Post-mastectomy breast reconstruction in United States academic medical centers anchors this segment through institutionalized care pathways and embedded surgeon training.
- Aesthetic Enhancement:Elective tissue expansion for body contouring concentrates in United States coastal markets where discretionary spending supports premium device uptake and concierge service models.
- Trauma Repair:Acute defect management protocols in Level I trauma centers require rapid-deployment expanders with minimal preparation time.
- Tissue Regeneration:Experimental applications in wound healing and congenital defect management remain investigational with limited commercial scale.
Reconstructive surgery generates the highest absolute revenue; aesthetic enhancement shows the steepest expansion trajectory as procedural volume diversifies beyond oncologic indications.
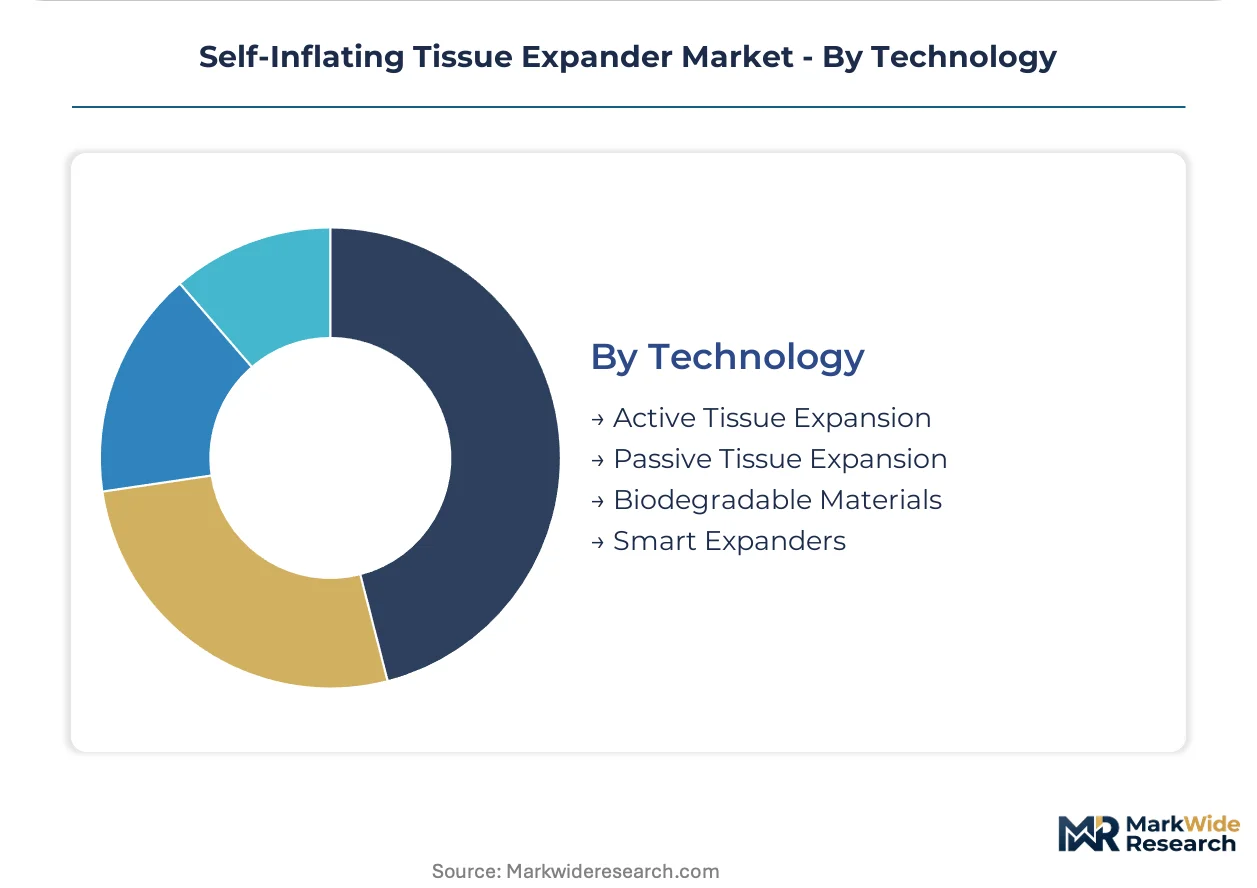
Technology:
Intellectual property concentration and development runway vary across mechanism types, with sensor-enabled systems demanding software validation while passive platforms compete on manufacturing scale.
- Smart Expanders:Implantable pressure transducers with Bluetooth Low Energy transmission enable cloud-based monitoring and earlier complication detection. United States academic centers pilot these systems for outpatient expansion management.
- Active Tissue Expansion:Integrated valve and reservoir systems with disposable components capture recurring revenue through replacement part cycles.
- Passive Tissue Expansion:Osmotic and gas-generating mechanisms without electronic components dominate current procurement through lower unit cost and established reimbursement codes.
- Biodegradable Materials:Degradable polymer platforms remain nascent due to degradation rate variability and mechanical strength constraints in high-volume protocols.
Passive systems retain the largest installed base; smart expanders are gaining share fastest as remote monitoring mandates reshape post-operative care economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and Japan demonstrate the lowest price elasticity, absorbing premium device costs through favorable reimbursement frameworks. United States procurement committees negotiate aggressively on unit pricing while demanding high-touch clinical support. Emerging markets in Asia-Pacific exhibit acute cost sensitivity, driving preference for simplified passive expander configurations.
United States
Post-mastectomy breast reconstruction protocols at academic medical centers in Boston and Houston generate concentrated device procurement volumes. FDA's Class II 510(k) pathway accelerates clearance timelines for incremental shell geometry innovations. The Mayo Clinic and MD Anderson Cancer Center anchor surgeon training ecosystems that lock in institutional procurement preferences.
Germany
Specialty elastomer production clusters around Leverkusen and Wiesbaden supply medical-grade silicone to device manufacturers worldwide. EMA's MDR implementation extends certification timelines for implantable Class IIb devices. Heidelberg University Hospital and Charité Berlin pilot remote monitoring-enabled expanders within EU-funded digital health initiatives.
Japan
Aging demographics and reconstructive surgery volume growth in Tokyo and Osaka metropolitan corridors expand addressable demand. PMDA maintains distinct biocompatibility testing protocols aligned with ISO 10993 standards that create manageable regulatory burden for compliant multinationals. Kobe and Nagoya host precision polymer processing facilities serving domestic device fabrication.
China
Domestic manufacturers in Guangzhou and Shenzhen capture share in cost-sensitive trauma and acute reconstructive applications. NMPA's medical device registration requirements for imported implantables create compliance complexity for foreign entrants. Shanghai's Fudan University Cancer Hospital develops institutional protocols for tissue expansion in oncologic reconstruction.
United Kingdom
NHS England's specialized commissioning frameworks for complex reconstructive procedures concentrate procurement authority at designated supra-regional centers. MHRA operates under retained EU MDR alignment post-Brexit, maintaining extended clinical evidence requirements for implantable devices. The Royal Marsden and Guy's Hospital anchor London's tissue expansion service delivery.
Self-Inflating Tissue Expander Market Competitive Landscape
Capability concentration sits with integrated aesthetics conglomerates; scale advantage sits with diversified medical device manufacturers. The market structures around three tiers: multinational conglomerates with surgeon training ecosystems, mid-cap specialists with niche indication focus, and regional fabricators serving cost-sensitive procurement. Strategic moves center on portfolio diversification beyond breast reconstruction and backward integration into medical-grade silicone supply.
Among diversified healthcare conglomerates, AbbVie Inc. and Mentor Worldwide LLC exemplify the integrated platform archetype, embedding device offerings within broader aesthetic surgery portfolios. PMT Corporation occupies a specialist position, anchoring neurosurgical and reconstructive applications where technical specifications command premium positioning. Guangzhou Wanhe Plastic Material Co.,Ltd represents the regional fabrication tier, serving Asia-Pacific markets with cost-optimized device configurations.
| Leading Market Players |
|---|
| AbbVie Inc. |
| Mentor Worldwide LLC |
| PMT Corporation |
| Sientra, Inc. |
| AirXpanders, Inc. |
| Osmed GmbH |
| Sebbin |
| Guangzhou Wanhe Plastic Material Co.,Ltd |
| KOKEN CO., LTD. |
| Others |
Value Network & Pricing Analysis
Leverkusen's medical-grade silicone production clusters anchor global elastomer supply for self-inflating tissue expander shells, concentrating upstream pricing power among German specialty chemical manufacturers while downstream device assemblers absorb input cost volatility through long-term offtake agreements.
Pricing Analysis
After-sales service revenue from disposable valve components and extended clinical support contracts drives lifetime value capture across the installed base. Three-tier pricing structure across premium sensor-enabled, standard silicone osmotic, and economy saline configurations stratifies by certification grade and wireless telemetry capability. Pricing pressure stems from ambulatory surgical center procurement committees demanding simplified passive devices with reduced per-procedure overhead. Hospital systems show lowest price sensitivity due to embedded surgeon training ecosystems and value-based care contract structures.
Supply Chain Analysis
Extended payment terms from German elastomer suppliers and supply-chain finance facilities at Japanese polymer processors ease working capital constraints for device manufacturers. Raw material flows draw from Germany, Japan, and the United States for medical-grade silicone, osmotic engine substrates, and sensor module components. Single-source vulnerability concentrates in specialty silicone formulation capacity around Leverkusen and Wiesbaden. Distribution runs through hospital procurement committees and group purchasing organizations in the United States, with direct manufacturer-to-facility relationships displacing traditional distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent manufacturers face substitution pressure from biodegradable polymer platforms that could displace silicone elastomer dominance in select reconstructive applications if degradation rate variability resolves.
For Market Incumbents: Entrench position through backward integration into medical-grade silicone supply and captive sensor module fabrication capacity. Lock hospital procurement committees via embedded surgeon training ecosystems and residency curriculum partnerships. Defend against biodegradable polymer substitutes by accelerating smart expander telemetry roadmaps that create data-enabled switching costs. For New Entrants and Emerging Players: Asia-Pacific trauma repair applications in Guangzhou and Shenzhen manufacturing corridors offer the most penetrable white space. Target cost-optimized passive expander configurations for acute reconstructive settings where rapid deployment outweighs premium feature requirements. Secure market access through NMPA registration partnerships with domestic distributors possessing established hospital relationships. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors sensor-enabled platform developers with FDA 510(k) clearance momentum and remote monitoring reimbursement pathway progress. Long-term viability hinges on convergence of implantable telemetry with cloud-based care coordination platforms. Watch CMS coverage determinations for wireless pressure monitoring as the inflection signal for platform economics transition.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Pathway Optimization | Accelerated clearance timelines compress competitive response windows for shell geometry innovations. |
| CE Marking Pathway Under MDR | Extended clinical evidence requirements strain smaller manufacturers' liquidity and documentation capacity. |
| Hospital System Partnership | Embedded training ecosystems at Mayo Clinic and MD Anderson lock procurement committee preferences. |
| Software Companion Development | Cloud analytics subscriptions transform device transactions into recurring revenue streams. |
| Reimbursement Strategy | CMS coverage determinations for remote monitoring-enabled expanders reshape competitive positioning. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with reconstructive surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers; and secondary validation against FDA 510(k) filings, CMS reimbursement databases, hospital procurement records, and ISO 10993 biocompatibility test registries. Bottom-up unit volume estimates across product type, end user, application, and technology segments triangulated with top-down market sizing from manufacturer revenue disclosures.
Forecast inputs incorporated procedural volume trajectories at academic medical centers, ambulatory surgical center expansion rates, and remote monitoring protocol adoption curves across the analysis window. Segmentation dimensions modeled include shell material grade, care setting tier, clinical indication type, and mechanism sophistication. CAGRs derived from regression analysis of historical procurement data against demographic and reimbursement variable projections.
Practitioners should monitor regulatory approval delays, silicone supply disruptions, and biodegradable polymer performance breakthroughs for early signals of forecast deviation. The analysis reflects assumptions about sustained FDA Class II pathway stability and continued reimbursement support for post-mastectomy reconstruction. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Engineering
Argentina Artificial Organs and Bionic Implants Market
Biomedical Engineering
Bioactive Bone Grafts Market
Biomedical Engineering
Bioabsorbable Osteosynthesis Devices Market
Biomedical Engineering
Global Bovine-Based Collagen for Biomedical Applications Market
Biomedical Engineering
Global Single Use Bioprocessing Probes and Sensors Market
Biomedical Engineering
Bionic Eye Market
Biomedical Engineering
Biological Implants Market
Biomedical Engineering
Global Bionics Market
Biomedical Engineering
Biological Derived Devices Market
Biomedical Engineering
Topical Bioadhesives Market
Biomedical Engineering
Global Continuous Bioprocessing Market
Biomedical Engineering
Global Robotic Prosthetic Market
Biomedical Engineering
Biomems Market
Biomedical Engineering
North America Lab-On-A-Chip and Microarrays (Biochip) Market
Biomedical Engineering
Bio-Engineered Stent Market
Biomedical Engineering
Medical Biomimetics Market