
 Global Bionics Market | 2026-2036
Global Bionics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Bionics Market Foresight
The EU Medical Device Regulation is consolidating clinical evidence requirements for implantable bionics across European markets. Medtronic plc leverages its deep neuromodulation pipeline to sustain leadership in neural implant development. Boston Scientific Corporation anchors its competitive position through advanced bioelectric sensor platforms for cardiac and neural applications.
Bionics encompasses electromechanical systems that interface with biological structures to restore or augment physiological functions, typically incorporating biocompatible alloys, conductive polymers, and signal processing architectures with sub-millisecond response latency. These systems serve industrial and commercial purposes ranging from limb replacement to neural signal restoration. Prosthetic limbs represent the most mature product category with established reimbursement pathways, while brain-computer interface technology commands the fastest development trajectory as FDA breakthrough device designations accumulate. Exoskeletons occupy a specialized niche where defense and industrial buyer budgets sustain premium pricing.
FDA breakthrough device pathways and EU MDR conformity assessments shape product development timelines and market access conditions for implantable bionics manufacturers. Japan's PMDA has streamlined approval frameworks for neuromodulation devices, accelerating East Asian market entry. China's NMPA now requires domestic clinical trials for Class III active implantables, raising compliance costs. Stakeholders must monitor evolving reimbursement decisions by Germany's Federal Joint Committee and Japan's Central Social Insurance Medical Council, as these determinations will signal which technology categories achieve sustainable commercial scale.
Market Dynamics
Defense procurement acceleration in the United States and Germany is compressing exoskeleton development cycles while EU MDR conformity assessments extend implantable neural device timelines, creating divergent velocity patterns across product categories.
Growth Catalysts
- Defense Exoskeleton Programs:Pentagon and Bundeswehr procurement budgets are underwriting industrial-grade load-bearing systems for logistics and combat applications, validating performance specifications that transfer to civilian rehabilitation markets.
- EU MDR Consolidation:The Medical Device Regulation's unified premarket clinical evidence requirements are streamlining multi-country market access for implantable manufacturers, reducing redundant national submissions.
- Neuromodulation Pipeline Maturation:Deep brain stimulation and spinal cord interface technologies are achieving therapeutic endpoints in movement disorders, expanding addressable patient populations beyond traditional prosthetic candidates.
Market Restraints
- Titanium Alloy Supply Concentration:Biocompatible metal feedstock for implantable housings concentrates among a limited supplier base, exposing manufacturers to price volatility and qualification delays.
- PMDA-NMPA Divergence:Japan's streamlined neuromodulation pathways contrast with China's domestic clinical trial mandates for Class III active implantables, fragmenting Asia-Pacific go-to-market economics.
- Reimbursement Uncertainty:Germany's Federal Joint Committee and Japan's Central Social Insurance Medical Council maintain non-binding exploratory statuses for brain-computer interfaces, delaying sustainable revenue models.
Strategic Opportunities
- Industrial Rehabilitation Clusters:Berlin and Munich are consolidating clinical trial infrastructure, manufacturing competence, and payer relationships, offering integrated launch platforms for European market entry.
- FDA Breakthrough Designation Accumulation:The accelerated review pathway for neural signal restoration devices is compressing time-to-revenue for qualifying brain-computer interface developers.
- Conductive Polymer Convergence:Integration of flexible electrode materials with sub-millisecond signal processing architectures is enabling next-generation peripheral nerve interfaces with reduced fibrotic encapsulation.
Industry Challenges
- Neural Signal Processing Talent Scarcity:The intersection of electrophysiology, real-time embedded systems, and biocompatibility engineering commands premium compensation and extended recruitment cycles.
- Legacy Prosthetic Certification Inertia:Established reimbursement codes for conventional limb replacement create friction against higher-cost bionic alternatives despite superior functional outcomes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Bionics Market |
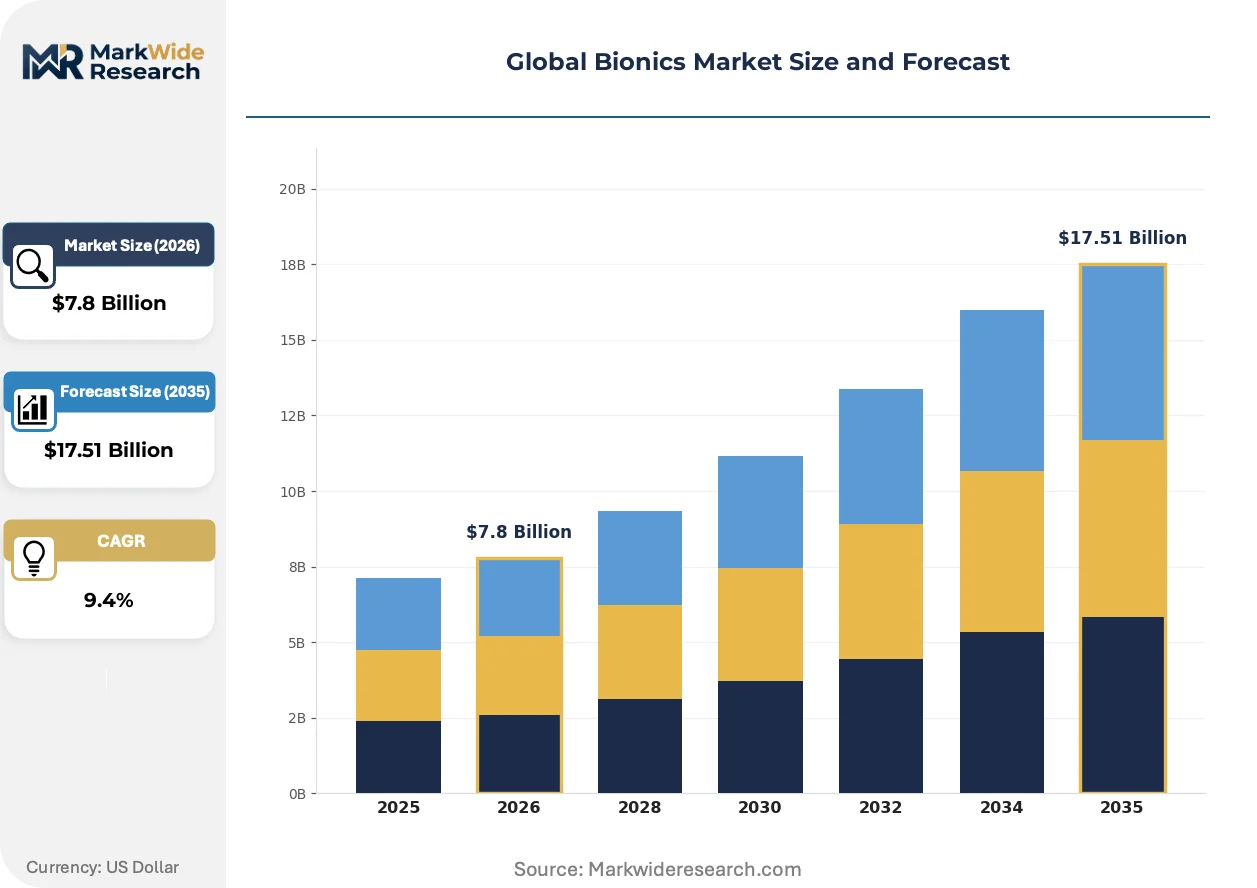
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $17.51 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prosthetic Limbs, Neural Implants, Exoskeletons, Sensory Devices, Orthotic Devices Technology: Electromyography, Brain-Computer Interface, Microelectromechanical Systems, Bioelectric Sensors, Haptic Feedback Application: Mobility Assistance, Neurorehabilitation, Occupational Therapy, Sports Enhancement, Communication Aid End User: Research Institutions, Rehabilitation Centers, Defense Sector, Sports Medicine Clinics, Consumer Healthcare |
| Companies Covered | Medtronic plc, Boston Scientific Corporation, Abbott Laboratories, Cochlear Limited, Össur, Ekso Bionics, Edwards Lifesciences Corporation, Zimmer Biomet Holdings Inc., ReWalk Robotics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Bionics Market Shifts & Advancements
Signal processing architectures with sub-millisecond response latency are compressing the functional gap between biological and electromechanical systems, while regulatory pathway divergence between jurisdictions is forcing parallel development tracks.
Peripheral nerve interfaces employing conductive polymer electrodes are electrifying motor control restoration for upper-limb amputees. Veterans Affairs healthcare systems and German statutory insurers are piloting coverage for these systems ahead of full market authorization. The technology is electrifying competitive positioning for developers capable of demonstrating sustained signal fidelity beyond twelve-month implantation horizons.
EU MDR's tightened premarket clinical evidence requirements for active implantables are extending development timelines by eighteen to thirty-six months for neural device categories. Manufacturers are responding with adaptive trial designs that satisfy both European notified bodies and FDA breakthrough pathway criteria. Brain-computer interface developers face the most pronounced timeline compression as they balance European conformity assessment rigor against American accelerated access incentives.
After-sales service unbundling is displacing bundled maintenance contracts in exoskeleton procurement. German industrial rehabilitation centers and US Veterans Affairs facilities are negotiating discrete pricing for hardware, software updates, and clinical training. This pattern is most visible in defense-to-civilian technology transfer programs where original equipment manufacturers lack established service infrastructure.
Global Bionics Market Segmentation
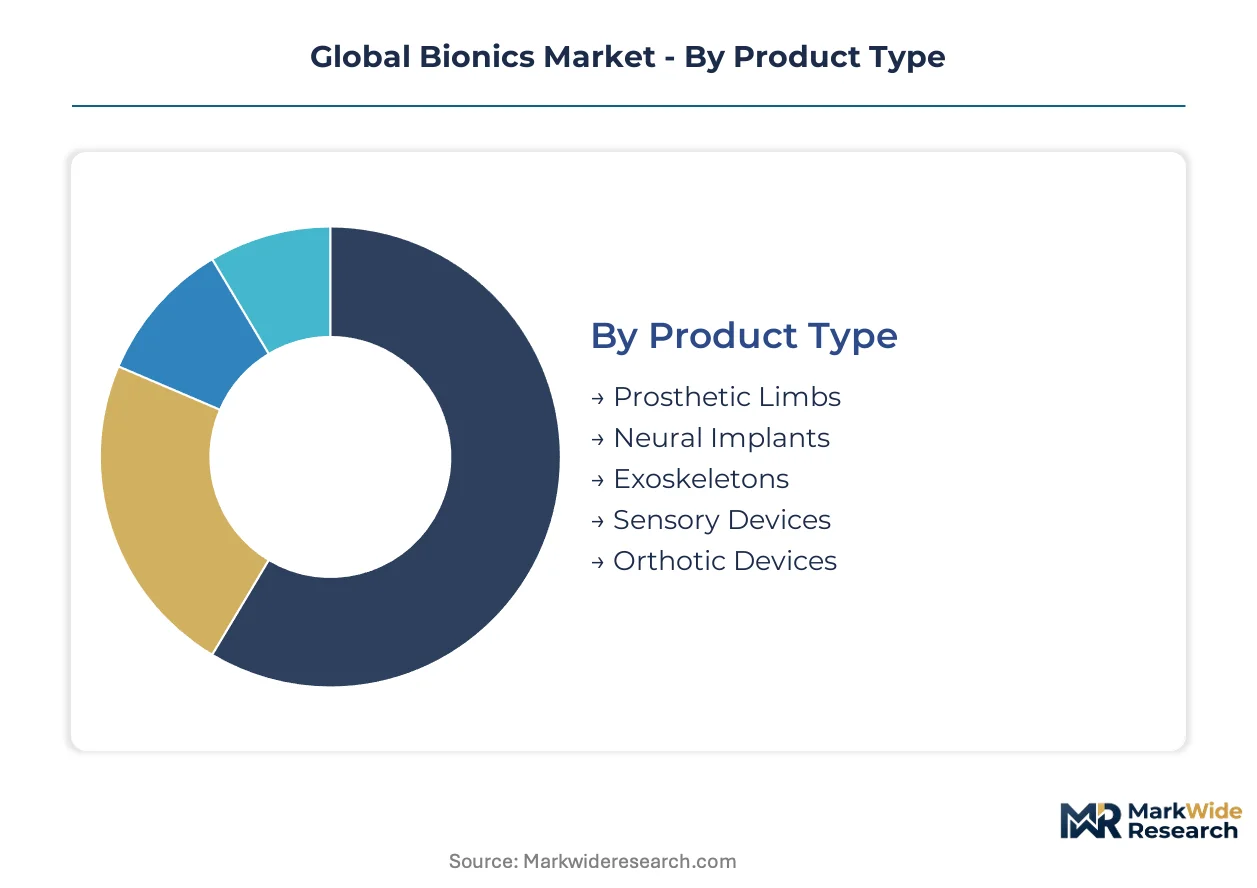
Bionic systems span electromechanical, neural, and sensory modalities with divergent regulatory pathways. Each segment demands distinct clinical evidence packages and reimbursement strategies. Manufacturers align R&D portfolios against specific approval timelines and end-user procurement cycles.
Product Type:
Certification burden concentrates in implantable categories requiring FDA breakthrough designation or EU MDR Class III conformity, while external systems navigate lighter Class IIa pathways.
- Prosthetic Limbs:Titanium and carbon-fiber composite structures with myoelectric control interfaces dominate commercial volume. German statutory insurers and US Veterans Affairs sustain procurement through established reimbursement codes, though legacy certification inertia constrains premium bionic adoption against conventional alternatives.
- Neural Implants:Deep brain stimulation and spinal cord interfaces incorporating platinum-iridium electrodes with sub-millisecond signal processing. FDA breakthrough device accumulation compresses timelines for qualifying developers, while EU MDR extends assessment cycles eighteen to thirty-six months.
- Exoskeletons:Load-bearing electromechanical frames for industrial and defense logistics. Pentagon and Bundeswehr procurement validates specifications transferable to civilian rehabilitation.
- Sensory Devices:Cochlear and retinal implants restoring auditory and visual signal pathways. Japan's PMDA streamlined frameworks accelerate East Asian market entry against China's NMPA domestic trial mandates.
- Orthotic Devices:External structural supports for musculoskeletal alignment. Lower regulatory classification enables faster commercialization but limits premium pricing capture.
Leading the category by volume: Prosthetic Limbs. Growing fastest: Neural Implants.
Technology:
Cost tiers separate established signal acquisition methods from emerging interface architectures commanding R&D premiums and extended development cycles.
- Brain-Computer Interface:Direct neural signal translation enabling motor control restoration for paralyzed patients. Non-binding exploratory status at Germany's Federal Joint Committee and Japan's Central Social Insurance Medical Council delays sustainable revenue models despite clinical efficacy.
- Electromyography:Surface and intramuscular electrode systems detecting motor unit activation patterns. Established component supply chains and mature reimbursement pathways sustain cost-competitive manufacturing for prosthetic control applications.
- Bioelectric Sensors:Implantable and wearable platforms for cardiac and neural signal monitoring. Boston Scientific anchors competitive positioning through advanced sensor architectures.
- Microelectromechanical Systems:Miniaturized mechanical structures integrated with signal processing electronics. Scale economies from consumer electronics crossover reduce unit costs.
- Haptic Feedback:Tactile sensation restoration through mechanoreceptor stimulation. Peripheral nerve interface integration with conductive polymers enables next-generation upper-limb prosthetic control.
Highest margin capture: Brain-Computer Interface. Steepest volume expansion: Electromyography.
Application:
Customer procurement authority separates institutional reimbursement-dependent segments from direct-pay or defense-funded categories.
- Mobility Assistance:Gait restoration and load-bearing support for lower-limb impairment. Berlin and Munich industrial rehabilitation clusters consolidate clinical trial infrastructure and payer relationships for integrated European launch platforms.
- Neurorehabilitation:Neural signal restoration for stroke and spinal cord injury patients. Veterans Affairs healthcare systems pilot coverage for peripheral nerve interfaces ahead of full market authorization.
- Occupational Therapy:Task-specific functional training with bionic augmentation. Discrete pricing for hardware, software updates, and clinical training displaces bundled maintenance contracts in procurement negotiations.
- Sports Enhancement:Performance augmentation beyond restorative medical necessity. Limited reimbursement coverage constrains commercial scale to direct-pay and elite athletic segments.
- Communication Aid:Speech synthesis and environmental control interfaces for locked-in patients. Brain-computer interface developers face timeline compression balancing European conformity rigor against American accelerated access incentives.
Institutional procurement concentration: Mobility Assistance. Fastest regulatory pathway accumulation: Neurorehabilitation.
End User:
Supply concentration in titanium alloy feedstock for implantable housings exposes manufacturers to qualification delays across buyer categories with stringent biocompatibility requirements.
- Defense Sector:Pentagon and Bundeswehr budgets underwrite industrial-grade exoskeleton development. Performance specifications validate civilian rehabilitation market entry.
- Rehabilitation Centers:German statutory insurers and US Veterans Affairs facilities negotiate unbundled service pricing. After-sales infrastructure gaps in defense-to-civilian transfers create procurement friction.
- Research Institutions:Early-stage clinical validation and adaptive trial design sponsorship. EU MDR and FDA breakthrough dual-track requirements concentrate investment in multi-site academic consortia.
- Sports Medicine Clinics:Elective performance and recovery applications. Direct-pay revenue models insulate against reimbursement uncertainty.
- Consumer Healthcare:Over-the-counter sensory and mobility devices. Lower regulatory barriers enable rapid commercialization but constrain clinical claims and premium positioning.
Procurement budget scale: Defense Sector. Coverage expansion trajectory: Rehabilitation Centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Berlin and Munich anchor Europe's industrial rehabilitation cluster, consolidating clinical trial infrastructure and payer relationships for integrated bionic launch platforms.
United States
Pentagon procurement budgets underwrite exoskeleton development for logistics and combat applications, validating specifications that transfer to civilian rehabilitation markets. FDA breakthrough device pathways compress neural implant timelines while extending market access for qualifying developers. Veterans Affairs healthcare systems pilot peripheral nerve interface coverage ahead of full authorization.
Germany
Bundeswehr defense programs accelerate industrial-grade load-bearing system adoption, with performance specifications driving civilian rehabilitation market entry. EU MDR conformity assessments extend implantable neural device timelines eighteen to thirty-six months, forcing adaptive trial designs. Berlin and Munich clusters concentrate manufacturing competence and payer negotiations for European market entry.
Japan
PMDA streamlined approval frameworks for neuromodulation devices accelerate East Asian market entry against regional regulatory fragmentation. Central Social Insurance Medical Council maintains non-binding exploratory status for brain-computer interfaces, delaying sustainable reimbursement models. Tokyo and Osaka metropolitan areas concentrate clinical validation infrastructure and statutory insurer relationships.
China
NMPA domestic clinical trial mandates for Class III active implantables raise compliance costs and extend market entry timelines. Shanghai and Beijing clusters concentrate manufacturing scale and hospital procurement relationships for local market penetration. National reimbursement catalog updates signal which technology categories achieve sustainable commercial scale.
Switzerland
Swissmedic regulatory frameworks support precision manufacturing clusters for biocompatible alloy processing and implantable housing fabrication. Geneva and Basel regions concentrate neuromodulation R&D infrastructure and clinical trial sponsorship. Watchmaking-derived microelectromechanical systems expertise transfers to peripheral nerve interface development.
Global Bionics Market Competitive Landscape
Premium-margin players sit above commodity-margin players across regulatory pathway sophistication and clinical evidence depth. The vendor base stratifies between consolidated implantable neuromodulation specialists and fragmented exoskeleton developers. Three archetypes dominate: diversified medical technology conglomerates with deep neuromodulation pipelines, pure-play neural interface developers accumulating FDA breakthrough designations, and defense-to-civilian exoskeleton transfer specialists. Competitive moves concentrate on adaptive trial design capabilities satisfying both FDA and EU MDR requirements, plus unbundled after-sales service pricing displacing bundled maintenance contracts.
Within the diversified conglomerate tier, Medtronic plc and Boston Scientific Corporation exemplify players leveraging deep therapeutic pipelines to sustain implantable market positions. Abbott Laboratories occupies a position bridging cardiac and neural signal restoration applications. Among pure-play mobility specialists, Össur and Ekso Bionics represent archetypes navigating divergent reimbursement pathways for external versus implantable systems. ReWalk Robotics sits within the defense-civilian transfer specialist category, capitalizing on Pentagon-validated specifications for rehabilitation market entry.
| Leading Market Players |
|---|
| Medtronic plc |
| Boston Scientific Corporation |
| Abbott Laboratories |
| Cochlear Limited |
| Össur |
| Ekso Bionics |
| Edwards Lifesciences Corporation |
| Zimmer Biomet Holdings Inc. |
| ReWalk Robotics |
| Others |
Supply & Pricing Matrix
Titanium alloy spot price indices cascade through bionic implant manufacturing into tiered pricing structures, with biocompatible metal feedstock concentration among limited suppliers amplifying cost volatility across premium neural implant and standard prosthetic categories.
Pricing Analysis
Functional outcome metrics anchor value-based pricing for neural implants, with therapeutic efficacy benchmarks commanding premium positioning against mobility-assistance alternatives. Three-tier pricing structure across premium, standard, and economy levels separates FDA breakthrough-designated brain-computer interfaces from conventional myoelectric prosthetics and basic mechanical limb replacements. Pricing pressure stems from Bundeswehr and Pentagon procurement leverage in exoskeleton categories, compressing margins for defense-to-civilian transfer specialists. Rehabilitation centers and Veterans Affairs facilities exhibit highest price sensitivity due to unbundled service negotiations, while defense sector buyers absorb premium positioning through validated performance specifications.
Supply Chain Analysis
Electrophysiology and embedded systems engineering talent scarcity in Switzerland, Germany, and the United States constrains manufacturing scale-up for sub-millisecond signal processing architectures. Titanium alloy feedstock for implantable housings draws from concentrated metallurgical suppliers, while conductive polymers and platinum-iridium electrodes rest on specialized chemical processing capabilities. Single-source vulnerability in biocompatible alloy qualification exposes manufacturers to eighteen-month recertification delays. Distribution runs through hospital procurement committees and defense logistics channels, with GPO contracts and statutory insurer frameworks governing downstream access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
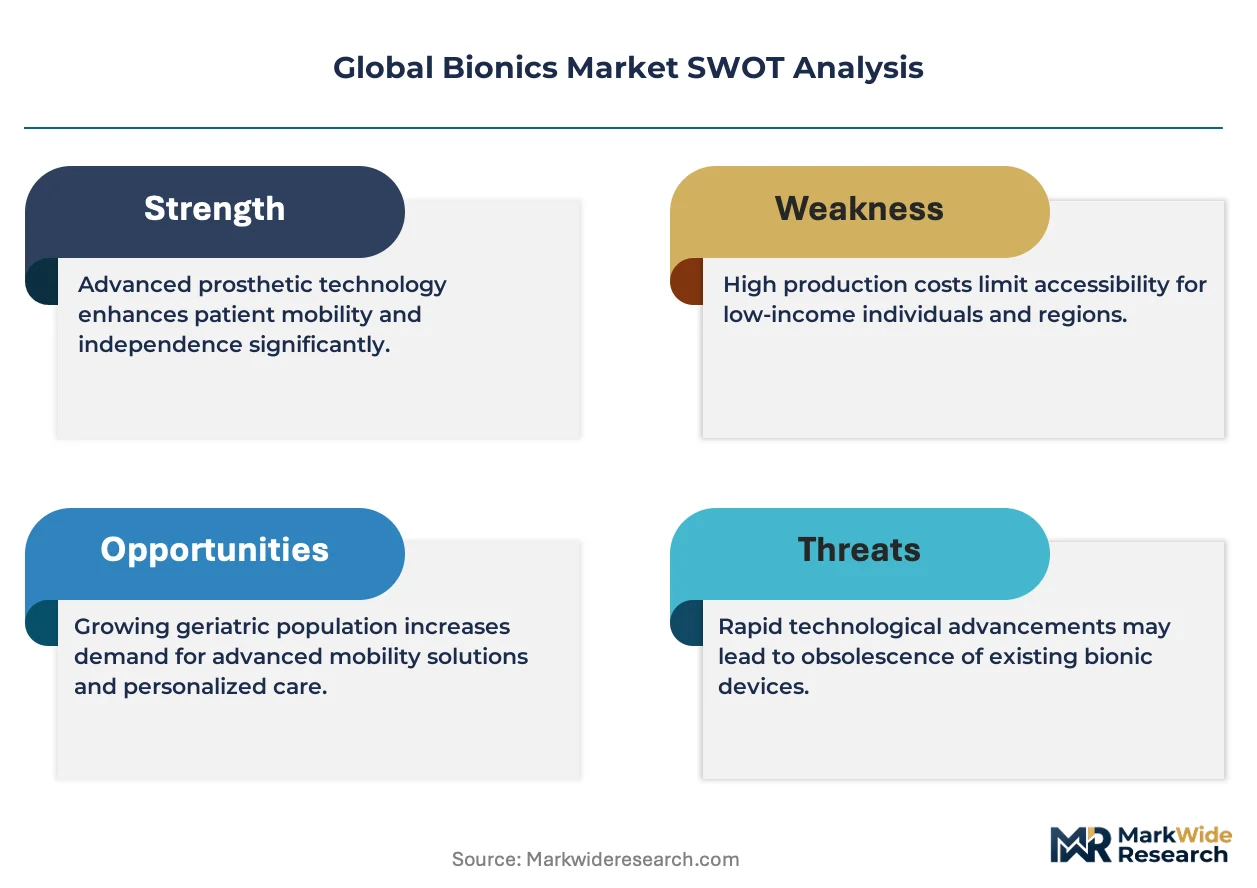
The Global Bionics Market functions as a vertical-integration race, with players pursuing backward integration into biocompatible alloy processing to secure feedstock qualification and compress implantable device cost structures.
For Market Incumbents: Anchor defensive positioning through captive supply of titanium alloy feedstock and in-house conductive polymer electrode fabrication, neutralizing emerging pure-play neural interface developers accumulating FDA breakthrough designations. Deepen neuromodulation pipeline investment to extend therapeutic endpoint coverage against spinal cord interface specialists. For New Entrants and Emerging Players: FDA breakthrough designation pathways in the United States open a window for brain-computer interface developers to compress time-to-revenue against EU MDR-extended incumbent timelines. Target peripheral nerve interface categories where Veterans Affairs pilot coverage precedes full reimbursement authorization, leveraging conductive polymer convergence for fibrotic encapsulation reduction. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap exoskeleton specialists with Pentagon-validated specifications and incomplete civilian service infrastructure in German industrial rehabilitation clusters. Watch Germany's Federal Joint Committee binding determination on brain-computer interface reimbursement as inflection signal for neural implant category viability.| Strategic Initiative | Industry Significance |
|---|---|
| Adaptive Trial Design Investment | Dual FDA-EU MDR pathway compliance compresses neural implant development timelines for qualifying developers. |
| Biocompatible Alloy Backward Integration | Captive titanium feedstock supply insulates implantable manufacturers from qualification delay risks. |
| Defense-to-Civilian Technology Transfer | Pentagon-validated exoskeleton specifications accelerate rehabilitation market entry with proven performance benchmarks. |
| Peripheral Nerve Interface Development | Conductive polymer integration enables sustained signal fidelity beyond twelve-month implantation horizons. |
| Unbundled Service Pricing Negotiation | Discrete hardware, software, and training contracts displace bundled maintenance in German statutory insurer procurement. |
Research Methodology
Document review covered FDA breakthrough designation filings, EU MDR notified body assessment reports, and Pentagon procurement disclosures, complemented by interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and defense acquisition officers. Secondary validation drew from CMS Medicare reimbursement databases, German Federal Joint Committee determinations, and statutory insurer coverage catalogs. Bottom-up demand modeling across prosthetic limb, neural implant, exoskeleton, and sensory device categories triangulated against top-down therapeutic pipeline assessments.
Cross-referencing historical approval timeline patterns with expert panel input on regulatory pathway evolution shaped the analytical framework across the analysis window. Segmentation dimensions modeled encompass product type, signal processing technology, application indication, and end-user procurement authority. CAGRs were derived from therapeutic endpoint achievement rates, reimbursement decision trajectories, and defense budget allocation shifts. Forecast inputs incorporated PMDA streamlined pathway utilization rates and NMPA domestic clinical trial mandate compliance costs.
The model assumes a particular technology adoption path; alternative pathways for brain-computer interface reimbursement determination would alter the outlook for neural implant category scaling. Forecasts reflect embedded assumptions regarding EU MDR assessment duration stability and titanium alloy supply concentration persistence. A small set of named triggers—Germany's Federal Joint Committee binding determinations, Japan's Central Social Insurance Medical Council coverage expansions, and Pentagon exoskeleton procurement acceleration—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Engineering
Non-Surgical Bio-Implants Market
Biomedical Engineering
Global Single Use Bioprocessing Probes and Sensors Market
Biomedical Engineering
3D Bioprinted Human Tissue Market
Biomedical Engineering
Global Biomedical Tester Market
Biomedical Engineering
Bioink Market
Biomedical Engineering
Bio-Engineered Stent Market
Biomedical Engineering
Artificial Organ Bank Market
Biomedical Engineering
Bioactive Bone Grafts Market
Biomedical Engineering
Bioactive Coating Devices Market
Biomedical Engineering
3D Bioprinted Organ Transplants Market
Biomedical Engineering
Global Bionic Ear Market
Biomedical Engineering
Next-Generation Biomanufacturing Market
Biomedical Engineering
Biomems Market
Biomedical Engineering
Tissue Extraction System Market
Biomedical Engineering
Self-Inflating Tissue Expander Market
Biomedical Engineering
Global Continuous Bioprocessing Market