
 Global Bionic Ear Market | 2026-2036
Global Bionic Ear Market Size, Share, and Industry Trends Forecast 2026-2036
Global Bionic Ear Market Foresight
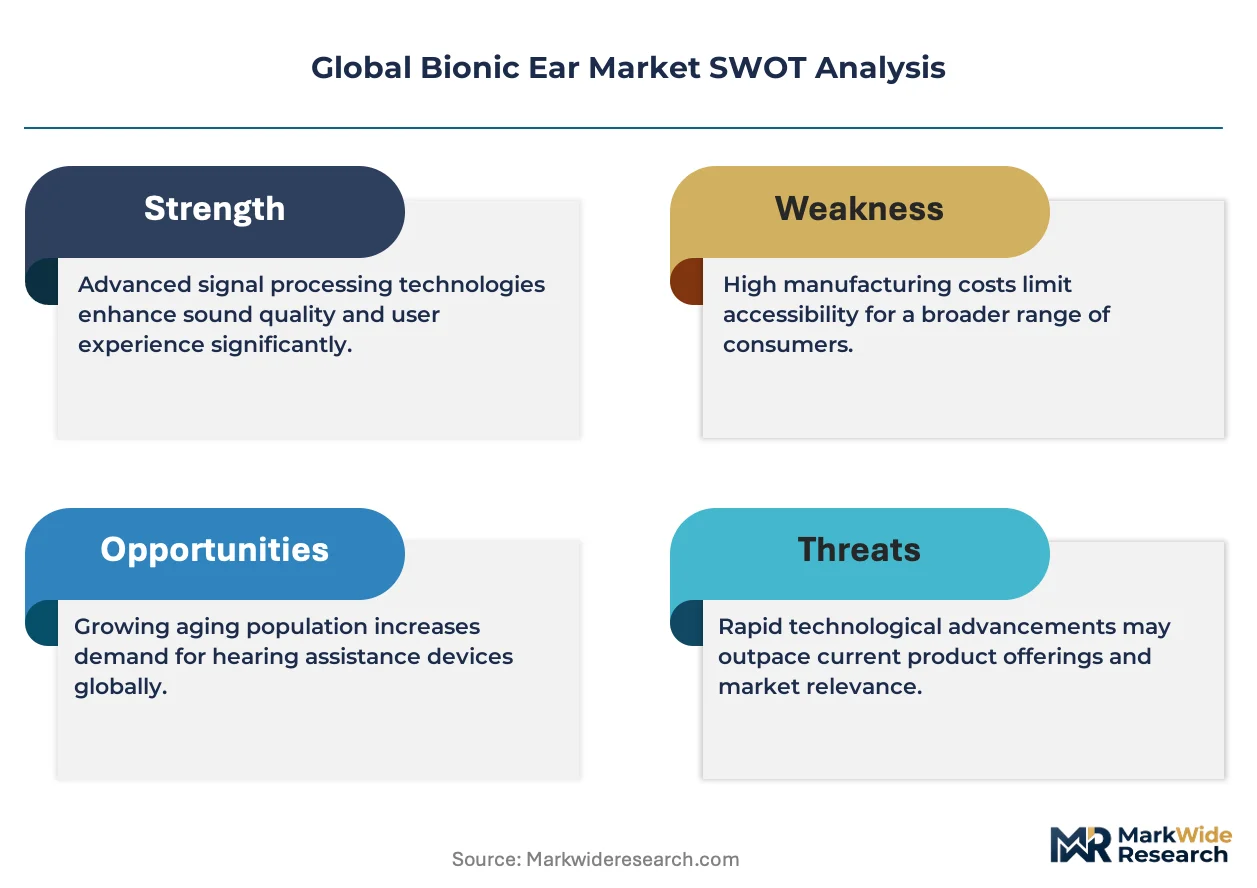
A capital-intensity divergence between fully integrated manufacturers and component-assemblers is bifurcating competitive dynamics in the bionic ear landscape. Cochlear Ltd leverages in-house electrode array fabrication and surgical tool ecosystems to sustain premium positioning across developed markets. MED-EL Medical Electronics anchors its European manufacturing base while competing aggressively on processor miniaturization and MRI-compatible designs.
A bionic ear comprises an externally worn sound processor and an internal implant with electrode array that directly stimulates the auditory nerve, typically operating across 12 to 24 active channels with sampling rates exceeding 16 kHz for speech encoding fidelity. Cochlear implants dominate product-type revenue due to established reimbursement and surgical training infrastructure, while bone conduction devices represent the fastest-growing segment driven by single-sided deafness indications and transcutaneous magnetic coupling advances. Multichannel technology leads the technology dimension with digital signal processing architectures displacing legacy single-channel systems in new installations.
FDA premarket approval requirements and CE marking under the EU Medical Device Regulation shape product development timelines and clinical evidence burdens for manufacturers seeking market access. Japan's PMDA and Australia's TGA impose additional country-specific auditory performance benchmarks that delay launches but elevate long-term product credibility. Stakeholders must monitor evolving sound-processing algorithm patent landscapes and reimbursement policy shifts in public health systems to anticipate which technology configurations will secure sustainable commercial traction.
Market Dynamics
Reimbursement policy fragmentation across public health systems is creating divergent commercialization timelines for multichannel cochlear implant manufacturers, forcing parallel regulatory track strategies and localized clinical evidence generation.
Growth Catalysts
- Japan's PMDA pediatric expansion:Revised auditory performance benchmarks for early implantation are accelerating program enrollment in Tokyo and Osaka medical centers.
- Transcutaneous magnetic coupling:Advances in bone conduction signal transmission are eliminating percutaneous abutment complications and expanding single-sided deafness candidacy.
- Australian hearing rehabilitation infrastructure:Government-funded ENT clinic networks in Sydney and Melbourne are standardizing bilateral implant protocols for pediatric patients.
Market Restraints
- Electrode array material concentration:Platinum-iridium alloy supply chains concentrate with three specialized foundries, creating input cost volatility for array fabricators.
- FDA premarket approval timelines:Multichannel system clinical requirements now demand 24-month longitudinal speech perception data, extending development cycles.
- Acoustic hearing aid substitution:Advanced digital signal processing in high-power behind-the-ear devices retains moderate-to-severe hearing loss patients who would otherwise progress to implantation.
Strategic Opportunities
- German ambulatory surgical center channel:Outpatient cochlear implantation protocols are opening direct procurement relationships outside traditional hospital purchasing committees.
- MRI-compatible processor convergence:Titanium-ceramic receiver-stimulator housings combined with diametric magnet designs are unlocking 3.0 Tesla diagnostic access for implanted patients.
- UK NHS bundled payment pilots:Five-year outcomes-based contracts covering device, surgery, and rehabilitation are restructuring provider risk allocation.
Industry Challenges
- Electrophysiology mapping specialization:Intraoperative neural response telemetry interpretation requires certified audiologists, creating surgical team bottlenecks in secondary markets.
- Sound-processing algorithm IP fragmentation:Patent thickets around spectral envelope extraction are complicating new entrant licensing negotiations.
- Legacy single-channel system migration:Firmware backward compatibility requirements constrain processor architecture redesigns for established implant populations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Bionic Ear Market |
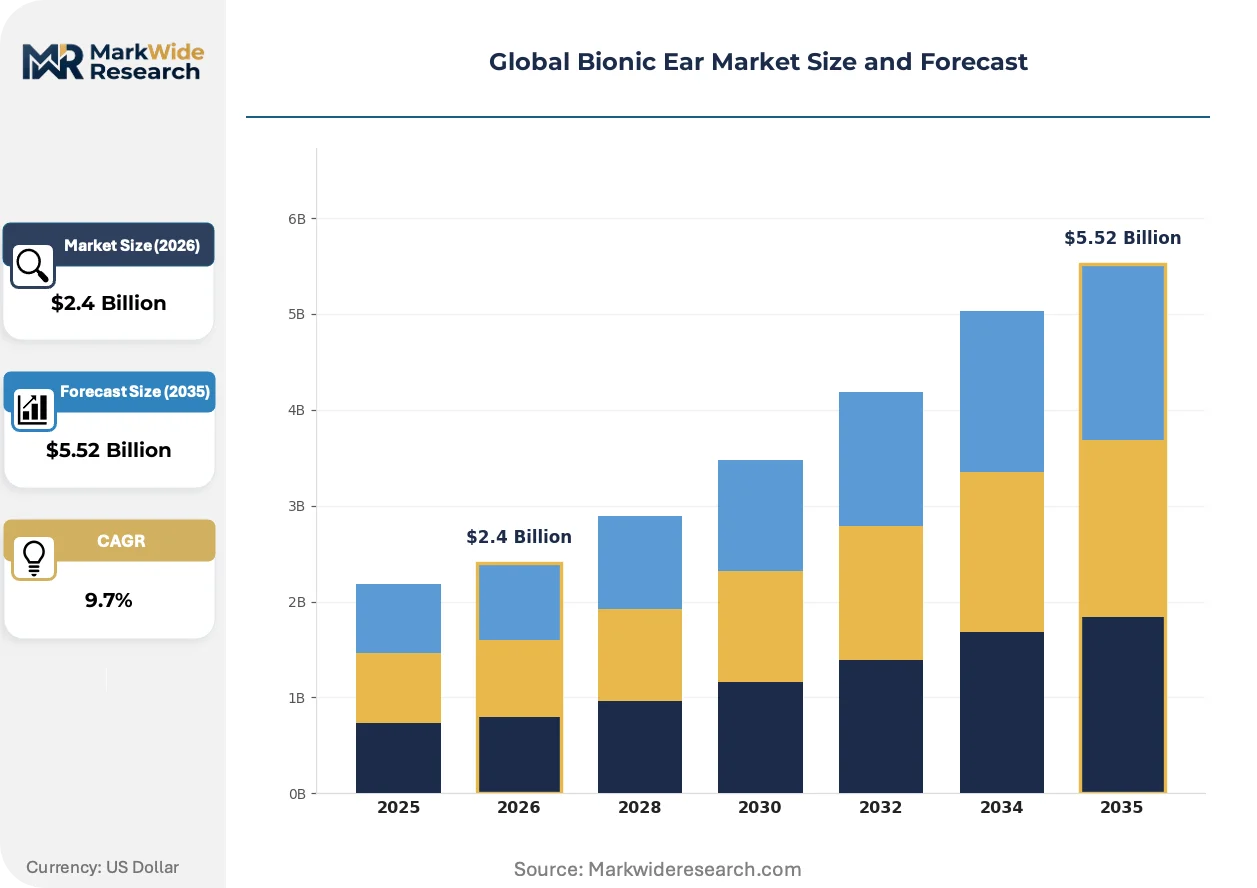
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.52 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cochlear Implants, Middle Ear Implants, Bone Conduction Devices, Auditory Brainstem Implants, Hybrid Implants Technology: Single Channel, Multichannel, Digital Signal Processing, Wireless Connectivity, Sound Processing Algorithms Application: Sensorineural Hearing Loss, Conductive Hearing Loss, Mixed Hearing Loss, Auditory Neuropathy, Single-Sided Deafness End User: ENT Clinics, Hearing Rehabilitation Centers, Audiology Labs, Hearing Aid Dispensers, Specialty Hospitals |
| Companies Covered | Cochlear Ltd, MED-EL Medical Electronics, Advanced Bionics, Sonova, Oticon Medical, Nurotron Biotechnology, WS Audiology, Starkey Hearing Technologies, GN Store Nord, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Bionic Ear Market Shifts & Advancements
Digital signal processing architectures are fragmenting the competitive landscape between premium multichannel systems and emerging low-channel alternatives, while regulatory convergence pressures are compressing development timelines across major jurisdictions.
Electrode array electrodeposition manufacturing is bifurcating competitive positioning in the implant segment. Laser-guided platinum pad placement onto silicone carriers enables 22-active-channel densities in pediatric arrays. Leading ENT departments in Germany and Australia are prioritizing these high-density configurations for pre-lingual deafness cases. The technology is bifurcating market tiers between integrated manufacturers with captive fabrication and assemblers dependent on third-party array suppliers.
EU Medical Device Regulation CE marking pathways are tightening clinical evidence requirements for cochlear implant systems. Notified bodies now mandate post-market surveillance registries tracking five-year speech discrimination outcomes. Manufacturers targeting European market access are restructuring quality management systems to accommodate periodic safety update reports. Pediatric indication extensions face particular scrutiny under the MDR's stricter benefit-risk frameworks for vulnerable populations.
After-sales service unbundling is disrupting traditional hearing rehabilitation center revenue models. Independent audiology practices in the United States are acquiring direct processor upgrade and mapping capabilities, bypassing manufacturer-owned clinic networks. This channel fragmentation concentrates in metropolitan markets with established cochlear implant volumes. Device suppliers are responding with tiered technical training certifications and proprietary fitting software licensing to retain program influence.
Global Bionic Ear Market Segmentation
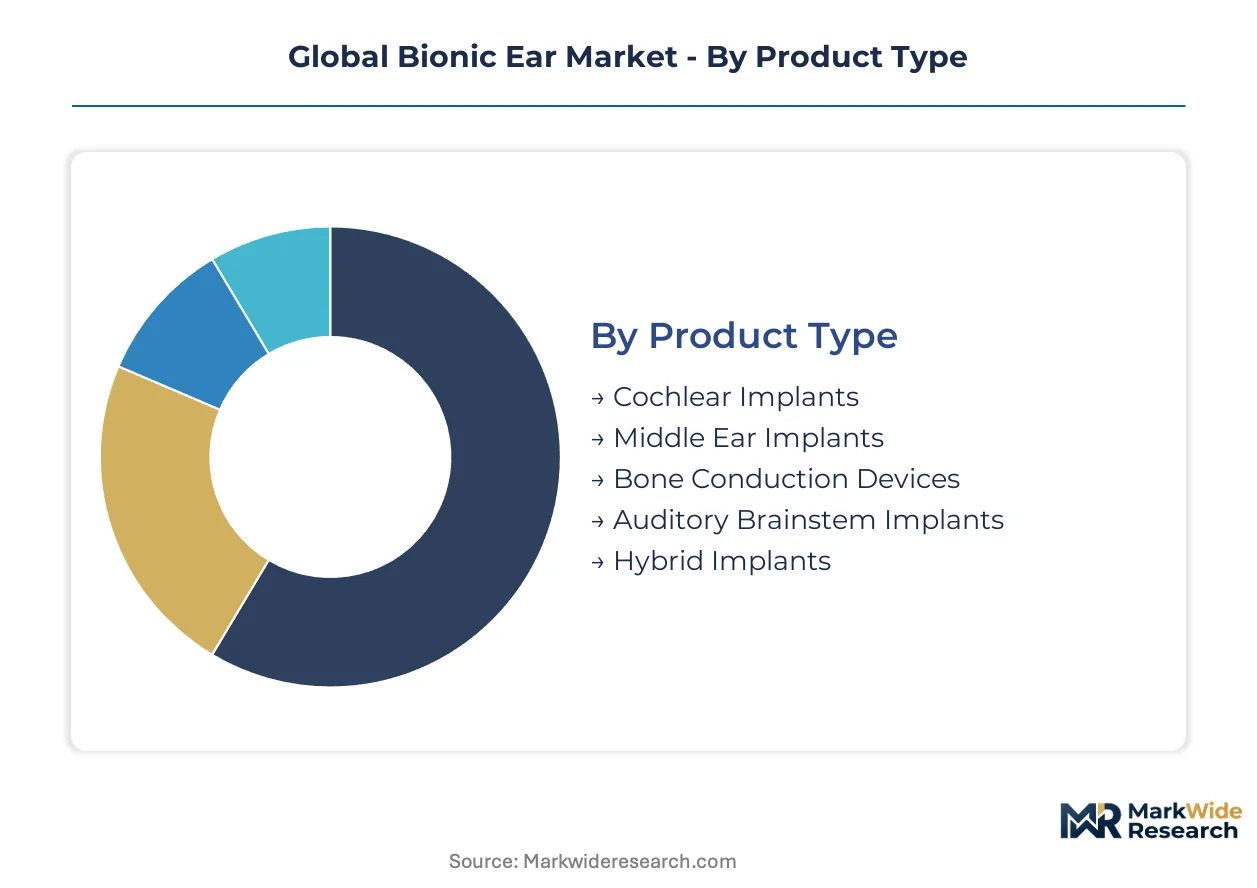
Segmentation in the bionic ear market reveals distinct procurement patterns across clinical settings and patient populations. Reimbursement pathways diverge sharply between pediatric cochlear implantation and adult bone conduction candidacy, forcing manufacturers to architect parallel commercial strategies.
Product Type:
Domestic production concentrates cochlear implant manufacturing in Australia and Germany, while bone conduction devices show stronger export-led growth from European specialists serving Asian markets.
- Cochlear Implants:These systems comprise an external speech processor and internal receiver-stimulator with electrode arrays delivering 12 to 24 active channels. Demand concentrates in ENT clinics across the United States, Germany, and Australia where bilateral pediatric protocols are standardizing. FDA premarket approval timelines now demand 24-month longitudinal speech perception data, extending development cycles for new entrants.
- Bone Conduction Devices:Transcutaneous magnetic coupling advances are eliminating percutaneous abutment complications and expanding single-sided deafness candidacy. Japanese PMDA pediatric expansion and Australian government-funded rehabilitation networks are accelerating adoption in metropolitan Sydney and Melbourne centers.
- Middle Ear Implants:These devices mechanically couple to ossicular structures for conductive and mixed hearing loss cases.
- Auditory Brainstem Implants:Neurofibromatosis type II patients and cochlear nerve aplasia cases drive specialized demand in tertiary referral centers.
- Hybrid Implants:Combined electric-acoustic stimulation preserves residual hearing in high-frequency sensorineural loss.
Cochlear implants hold the largest share; momentum sits with bone conduction devices.
Technology:
Cost tier differentiation separates premium multichannel systems from emerging low-channel alternatives, with digital signal processing commanding price premiums in developed markets.
- Multichannel:Digital signal processing architectures with 16 kHz-plus sampling rates dominate new installations. EU Medical Device Regulation CE marking pathways now mandate five-year post-market surveillance registries, restructuring quality management systems for European market access.
- Digital Signal Processing:Spectral envelope extraction algorithms are concentrating patent thickets, complicating licensing negotiations for new entrants.
- Single Channel:Legacy firmware backward compatibility requirements constrain processor architecture redesigns for established implant populations.
- Wireless Connectivity:Bluetooth Low Energy streaming integration is standardizing across external processor generations.
- Sound Processing Algorithms:Directional microphone beamforming and noise reduction IP fragments across competing research institutions.
Multichannel systems capture premium positioning; digital signal processing is gaining share fastest.
Application:
Volume concentration varies by severity threshold, with sensorineural cases representing established surgical flow and single-sided deafness expanding addressable populations.
- Sensorineural Hearing Loss:Pre-lingual pediatric cases drive bilateral implantation protocols in German and Australian ENT departments.
- Single-Sided Deafness:Bone conduction candidacy expansion is reshaping patient selection criteria in Tokyo and Osaka medical centers following revised PMDA auditory performance benchmarks.
- Conductive Hearing Loss:Chronic otitis media and atresia cases concentrate demand in specialty hospitals.
- Mixed Hearing Loss:Stapedectomy failure and otosclerosis progression create hybrid implant candidacy.
- Auditory Neuropathy:Neural synchrony disorders require specialized electrophysiology mapping capabilities.
Sensorineural hearing loss maintains dominant volume; single-sided deafness shows steepest expansion trajectory.
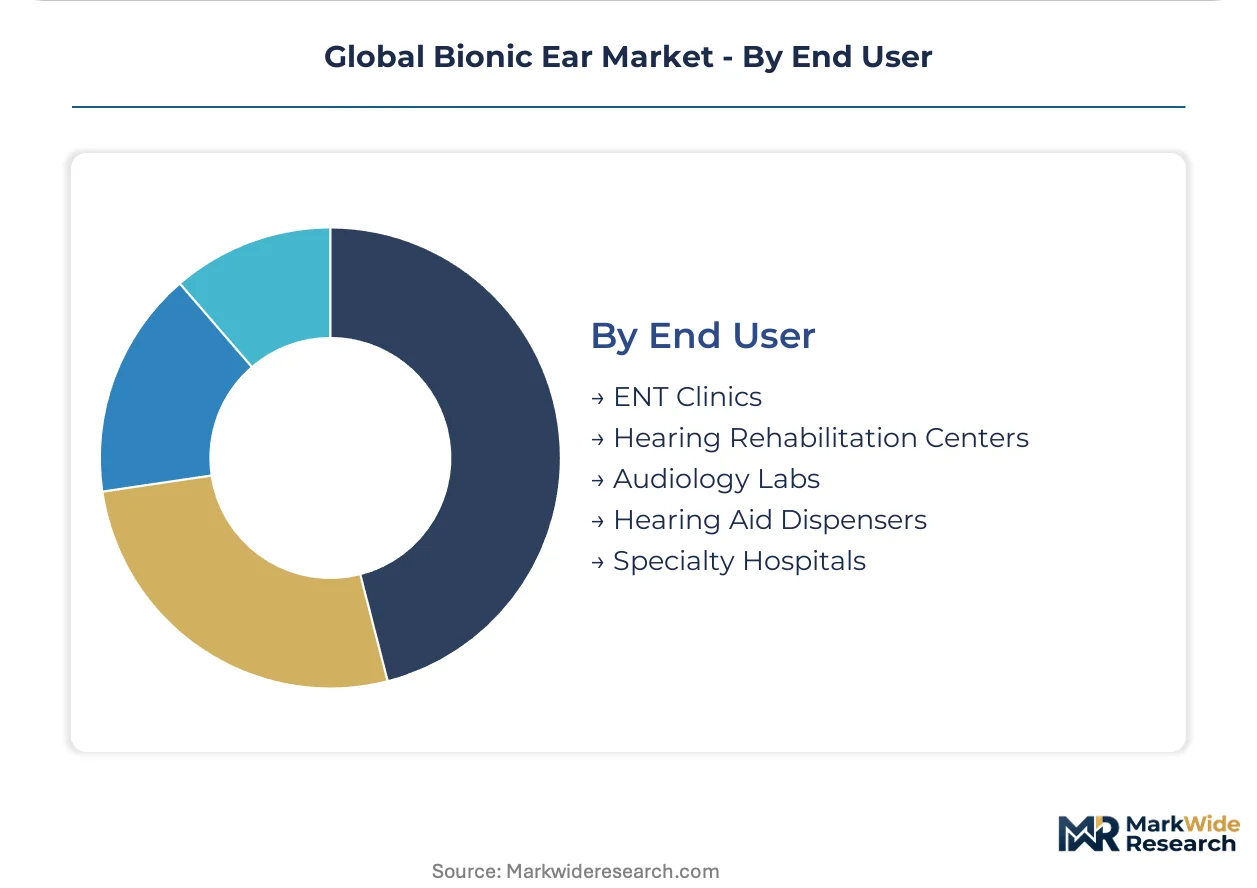
End User:
Customer type fragmentation is disrupting traditional procurement, with independent audiology practices acquiring direct mapping capabilities outside manufacturer-owned networks.
- ENT Clinics:German ambulatory surgical centers are opening direct procurement relationships outside hospital purchasing committees through outpatient cochlear implantation protocols.
- Hearing Rehabilitation Centers:Government-funded networks in Sydney and Melbourne standardize bilateral pediatric protocols.
- Audiology Labs:Intraoperative neural response telemetry interpretation requires certified specialists, creating surgical team bottlenecks.
- Hearing Aid Dispensers:After-sales service unbundling concentrates in metropolitan United States markets with established implant volumes.
- Specialty Hospitals:Tertiary referral centers manage auditory brainstem implant and complex revision cases.
ENT clinics command the largest procurement volume; hearing rehabilitation centers are expanding fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. Japanese and German buyers absorb premium pricing for MRI-compatible systems, while Indian and Brazilian markets prioritize cost-optimized configurations despite lower reimbursement coverage.
United States
FDA premarket approval timelines now demand 24-month longitudinal speech perception data for multichannel systems, extending development cycles. The agency's tightened clinical requirements concentrate procurement in established ENT clinic networks across metropolitan markets. Boston and New York medical centers drive bilateral pediatric protocol standardization.
Germany
EU Medical Device Regulation CE marking pathways mandate five-year post-market surveillance registries, restructuring quality management systems for European access. Ambulatory surgical center outpatient cochlear implantation protocols are opening direct procurement relationships outside hospital purchasing committees. Munich and Berlin ENT departments prioritize high-density electrode arrays for pre-lingual cases.
Japan
PMDA revised auditory performance benchmarks for early implantation, accelerating program enrollment in Tokyo and Osaka medical centers. Government-funded rehabilitation infrastructure supports bilateral pediatric protocols. Domestic demand concentrates on processor miniaturization and transcutaneous magnetic coupling advances.
Australia
TGA imposes country-specific auditory performance benchmarks that delay launches but elevate long-term product credibility. Government-funded ENT clinic networks in Sydney and Melbourne standardize bilateral implant protocols for pediatric patients. Local manufacturing anchors supply for Asia-Pacific distribution.
United Kingdom
NHS bundled payment pilots covering five-year outcomes-based contracts for device, surgery, and rehabilitation are restructuring provider risk allocation. Reimbursement policy shifts favor multichannel system procurement in established hearing rehabilitation centers. London and Manchester tertiary referral centers manage complex revision cases.
Global Bionic Ear Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Fully integrated manufacturers with captive electrode array fabrication command premium positioning, while component-assemblers compete on price and regional customization. Three archetypes dominate: integrated system developers, specialized implant fabricators, and hearing aid conglomerates diversifying into implantables. Competitive moves concentrate on MRI-compatible processor development and ambulatory surgical center channel expansion.
Within the integrated system tier, Cochlear Ltd and MED-EL Medical Electronics occupy positions defined by manufacturing depth and regional regulatory mastery. Advanced Bionics represents the hearing-aid-conglomerate archetype, leveraging audiology distribution infrastructure. These three companies exemplify how competitive positioning derives from supply chain configuration rather than product specification alone.
| Leading Market Players |
|---|
| Cochlear Ltd |
| MED-EL Medical Electronics |
| Advanced Bionics |
| Sonova |
| Oticon Medical |
| Nurotron Biotechnology |
| WS Audiology |
| Starkey Hearing Technologies |
| GN Store Nord |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements for platinum-iridium electrode arrays lock in supply access for integrated manufacturers while anchoring price visibility against foundry volatility. These contracts concentrate procurement power among three specialized alloy foundries serving Germany, Australia, and Japan, creating tiered cost structures that ripple through finished implant pricing.
Pricing Analysis
After-sales service revenue from processor upgrades and mapping recalibrations drives lifetime value for manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates MRI-compatible titanium-ceramic systems from conventional designs and entry-level bone conduction alternatives. Cost compression in the standard tier intensifies because independent audiology practices are acquiring direct fitting capabilities outside manufacturer-owned networks. Pediatric bilateral protocols in German ENT clinics show least price sensitivity, while single-sided deafness candidacy expansion in emerging markets absorbs economy-tier configurations.
Supply Chain Analysis
Container availability constraints on Asia-Pacific trade lanes are elevating inbound logistics costs for silicone carrier substrates and precision-machined surgical tools. Manufacturing concentrates in Australia, Germany, and Switzerland, with electrode array fabrication drawing from platinum-iridium alloy feedstock sourced from South African and Russian metallurgical processors. Single-source vulnerability sits with the three specialized foundries controlling platinum-iridium electrodeposition capacity. Distribution runs through hospital purchasing committees in the United States and ambulatory surgical center direct procurement channels in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics inflect as sound-processing algorithm ecosystems fragment across competing IP holders, forcing interoperability investments that reshape competitive moats from hardware toward software companion architectures.
For Market Incumbents: Secure captive electrode array fabrication capacity through backward integration into platinum-iridium alloy sourcing, insulating against foundry concentration risk. Deepen channel control by acquiring independent audiology practices in metropolitan United States markets before competitors establish tiered technical training certifications. For New Entrants and Emerging Players: Differentiate on transcutaneous magnetic coupling miniaturization for single-sided deafness applications, where bone conduction candidacy expansion outpaces established reimbursement infrastructure. Target German ambulatory surgical centers with outpatient cochlear implantation protocols that bypass entrenched hospital purchasing committees. For Investors and Strategic Acquirers: Specialized electrophysiology mapping software developers with certified audiologist training platforms represent the most defensible acquisition archetype. Long-term viability hinges on five-year post-market surveillance registry capabilities under EU MDR requirements. Watch for PMDA auditory performance benchmark revisions as the signal indicating Japan pediatric program acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Premarket Approval Pathway | 24-month longitudinal speech perception data requirements extend development cycles for multichannel entrants. |
| CE Marking Pathway | EU MDR five-year post-market surveillance registries restructure quality management systems for European access. |
| Hospital System Partnership | Bilateral pediatric protocol standardization in Sydney and Melbourne government-funded ENT networks anchors volume. |
| Software Companion Development | Proprietary fitting software licensing retains program influence against independent audiology practice channel fragmentation. |
| Reimbursement Strategy | NHS bundled payment pilots covering device, surgery, and rehabilitation restructure provider risk allocation in the United Kingdom. |
Research Methodology
The analysis maps cochlear implant, bone conduction, and auditory brainstem implant sub-sectors, each validated through ENT surgeons, biomedical engineers, hospital purchasing committee managers, and GPO contracts specialists. Primary interviews combined with secondary validation from FDA 510(k) and PMA filings, CE marking databases under EU MDR, PMDA approval summaries, and TGA registration records. Bottom-up installation volume modeling triangulated against top-down reimbursement expenditure analysis.
Consistency checks validated volume and value outputs against hospital procurement database benchmarks and government-funded rehabilitation network expenditure reports. Segmentation dimensions modeled across product type, technology tier, application severity, and end-user channel throughout the forecast period. CAGRs derived from logistic diffusion curves fitted to pediatric implantation rate trajectories and adult bone conduction candidacy expansion patterns.
The analysis sits within stated boundaries; outcomes outside sustained platinum-iridium alloy supply continuity, stable FDA premarket approval timelines, and unchanged public health system reimbursement policies would require recalibration. Forecasts reflect documented assumptions regarding bilateral protocol adoption rates and MRI-compatible processor penetration. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Engineering
Bioresorbable Scaffolds Market
Biomedical Engineering
Global Single Use Bioprocessing Probes and Sensors Market
Biomedical Engineering
North America Biosurgery Market
Biomedical Engineering
Global Biomedical Tester Market
Biomedical Engineering
Biological Derived Devices Market
Biomedical Engineering
Protein Engineering Market
Biomedical Engineering
Bioabsorbable Implant Market
Biomedical Engineering
Biomems Market
Biomedical Engineering
Tissue Engineering Market
Biomedical Engineering
Next-Generation Biomanufacturing Market
Biomedical Engineering
Medical Biomimetics Market
Biomedical Engineering
3D Bioprinted Organ Transplants Market
Biomedical Engineering
North America Lab-On-A-Chip and Microarrays (Biochip) Market
Biomedical Engineering
Bioink Market
Biomedical Engineering
Non-Surgical Bio-Implants Market
Biomedical Engineering
Global Bionics Market