
 Biocompatible 3D Printing Market | 2026-2036
Biocompatible 3D Printing Market Size, Share, and Industry Trends Forecast 2026-2036
Biocompatible 3D Printing Market Insights
Single-source polymer supply for medical-grade filaments is decoupling as hospitals and contract manufacturers diversify vendor relationships to reduce qualification risk. 3D Systems Inc. leverages its vertically integrated resin platform to control quality from monomer synthesis through finished filament. Evonik Industries AG anchors European supply with high-performance PEEK and PA12 powders certified for implantable applications. Stratasys Ltd. competes through hospital-centric service models that bundle hardware with regulatory documentation packages.
Biocompatible 3D printing encompasses additive manufacturing processes that process filaments, powders, resins, or pastes meeting ISO 10993 cytotoxicity and sensitization thresholds to produce patient-contact devices, scaffolds, or surgical guides with defined pore architectures and mechanical properties matched to native tissue. Its primary purpose is to enable geometrically complex, lot-size-one production of implants and instrumentation without conventional tooling constraints. Resins and powders capture the dominant share of current revenue, with resins leading dental applications and powders commanding premium pricing in cranio-maxillofacial implants. Fused Deposition Modeling dominates installed base volume in research settings, while Selective Laser Sintering claims higher average selling prices in production-grade orthopedic applications.
FDA 510(k) and De Novo pathways govern U.S. market access for biocompatible printed devices, with the agency issuing targeted guidance on patient-matched guides to clarify validation expectations. EMA's Medical Device Regulation in Europe imposes stricter clinical evidence requirements on custom-made implants, lengthening approval timelines but raising barriers to low-quality entrants. ISO 10993-1 biological evaluation frameworks and ASTM F3335 additive manufacturing standards shape material qualification protocols across both jurisdictions. Stakeholders must monitor evolving FDA guidance on point-of-care manufacturing, as decentralized hospital printing threatens to fragment traditional OEM supply relationships and recast liability frameworks.
Market Dynamics
Decentralized hospital manufacturing is fragmenting traditional OEM supply relationships as point-of-care printing capabilities expand across tertiary care networks, forcing material suppliers to recast distribution and liability frameworks.
Growth Catalysts
- FDA Point-of-Care Guidance:Clarified validation expectations for patient-matched surgical guides accelerate hospital adoption of in-house printing workflows.
- ISO 10993-18 Material Characterization:Standardized chemical assessment protocols reduce requalification burden when switching resin or powder suppliers.
- Cranio-maxillofacial Reconstruction Demand:Patient-specific titanium and PEEK implants command premium pricing in Germany's university hospital clusters.
Market Restraints
- PEEK Powder Supply Concentration:Evonik Industries AG controls the majority of implantable-grade polyetheretherketone supply, creating single-source vulnerability for SLS implant manufacturers.
- EMA MDR Clinical Evidence Requirements:Stricter documentation burdens for custom-made implants extend European approval timelines versus FDA 510(k) pathways.
- Bioceramic Substitution Pressure:Hydroxyapatite and tricalcium phosphate scaffolds compete for load-bearing bone applications where metallic implants previously dominated.
Strategic Opportunities
- Veterinary Orthopedics:Unregulated animal health applications allow rapid iteration of titanium lattice structures before human clinical translation.
- India's PLI Scheme for Medical Devices:Domestic manufacturing incentives attract filament extrusion investments to serve South Asian contract research organizations.
- AI-Generative Design Convergence:Topology optimization software integrated with DICOM imaging automates patient-specific implant geometry generation.
Industry Challenges
- Biomedical Engineer Talent Scarcity:Hospitals struggle to recruit personnel fluent in both additive process parameters and sterile field protocols.
- Cleanroom Capital Requirements:ISO Class 7 environments for powder handling demand seven-figure facility investments beyond printer hardware costs.
- Post-Processing Bottlenecks:Residual monomer removal and surface finishing steps constrain throughput in high-volume dental aligner production.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biocompatible 3D Printing Market |
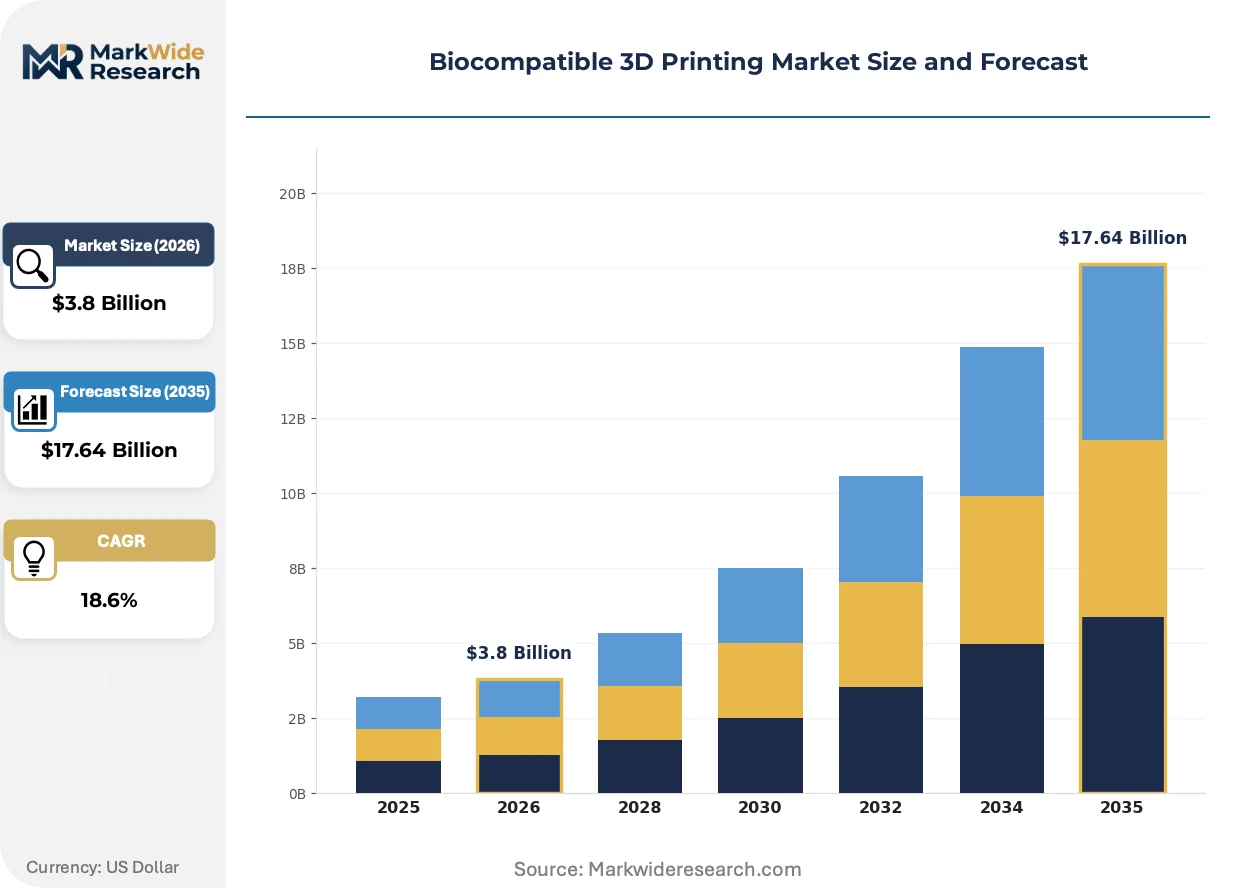
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Filaments, Powders, Resins, Pastes Application: Healthcare Devices, Tissue Engineering, Prosthetics, Dental Implants Technology: Fused Deposition Modeling, Stereolithography, Selective Laser Sintering, Binder Jetting End User: Hospitals, Research Laboratories, Academic Institutions, Biotech Companies |
| Companies Covered | 3D Systems Inc., Stratasys Ltd., Formlabs Inc., Evonik Industries AG, EOS GmbH, Renishaw plc, EnvisionTEC Inc., Concept Laser GmbH, Aspect Biosystems Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biocompatible 3D Printing Market Trends and Innovations
Multi-material extrusion systems and resin formulation advances are compressing the gap between prototyping and production-grade biocompatibility, while regulatory frameworks adapt to decentralized manufacturing models.
Photopolymer resin platforms incorporating ceramic fillers are unifying aesthetic and mechanical performance in dental prosthetics. Large dental laboratory networks in the United States are transitioning from milled zirconia to printed hybrid resins at scale. This convergence is unifying previously separate equipment investments into single-platform workflows.
EMA's Medical Device Regulation imposes unique device identification and post-market surveillance obligations on custom implant manufacturers. European orthopedic OEMs now maintain device history records for lot-size-one production. Cranial plate producers in Germany and Switzerland have reorganized quality management systems to accommodate patient-specific traceability.
Hospital procurement committees now require bundled regulatory documentation packages alongside hardware quotations. Traditional capital equipment vendors face displacement by service-oriented suppliers offering compliance support. This preference shift is most pronounced in North American academic medical centers building centralized printing facilities.
Biocompatible 3D Printing Market Segmentation
Biocompatible 3D printing segments diverge sharply by material qualification burden and regulatory pathway complexity. Each category reflects distinct buyer priorities: polymer purity thresholds for material suppliers, anatomical precision demands for clinicians, throughput requirements for production managers, and compliance documentation needs for procurement officers.
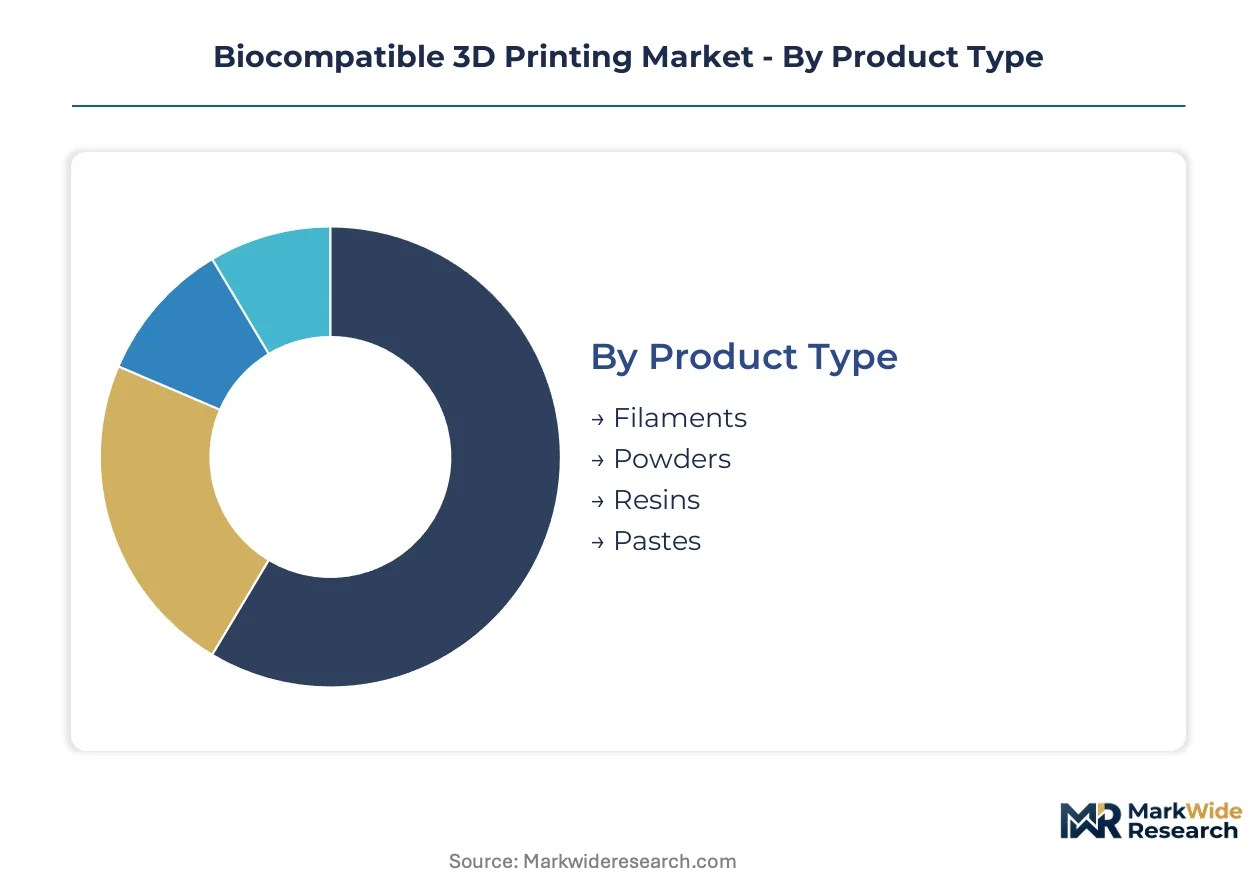
Product Type:
Buyers in this category prioritize supply security and requalification speed when switching vendors, with implantable-grade certifications commanding substantial price premiums over research-grade alternatives.
- Filaments:Thermoplastic extrusions of PLA, ABS, and PEEK for FDM systems require tight diameter tolerances and moisture-controlled packaging. Hospital point-of-care facilities in Germany and the United States concentrate demand for sterilizable PEEK filaments used in cranial plate prototypes.
- Powders:Polyamide 12 and titanium powders for SLS and binder jetting processes dominate production-scale orthopedic implant manufacturing. Evonik Industries AG's implantable-grade PA12 supply anchors European cranio-maxillofacial reconstruction workflows, though single-source concentration creates procurement vulnerability for contract manufacturers.
- Resins:Photopolymer formulations with ceramic fillers serve dental prosthetics and surgical guide applications. Large dental laboratory networks in the United States favor hybrid resin platforms over milled zirconia for aesthetic restorations.
- Pastes:Shear-thinning bioinks and collagen hydrogels enable extrusion-based bioprinting of cell-laden constructs. Academic tissue engineering programs in Switzerland and the Netherlands drive specialized paste formulation demand.
Powders lead volumes today; resins are gaining share fastest.
Application:
Application selection correlates directly with reimbursement pathway maturity and patient-contact duration, with permanent implants facing steeper clinical evidence requirements than temporary surgical instrumentation.
- Healthcare Devices:Patient-matched surgical guides, instrumentation, and external fixators constitute the highest-volume application segment. FDA 510(k) clearance pathways for guides accelerate hospital adoption across tertiary care networks in the United States.
- Tissue Engineering:Scaffold architectures with defined pore sizes and degradation rates support cell infiltration and vascularization. Research laboratories in Germany and the Netherlands concentrate demand for collagen and hydroxyapatite composite scaffolds targeting bone regeneration.
- Prosthetics:Custom socket interfaces and cosmetic covers leverage geometric complexity unavailable through conventional manufacturing. Veterans Affairs hospitals in the United States deploy in-house printing for lower-limb prosthetic fittings.
- Dental Implants:Titanium and zirconia crowns, bridges, and abutments command premium pricing in aesthetic dentistry. Dental laboratory consolidation in the United States and Germany drives centralized production investments.
Healthcare devices dominate current revenue; tissue engineering is expanding most quickly.
Technology:
Technology selection hinges on surface finish requirements, material compatibility, and throughput economics, with production environments favoring powder bed fusion while research settings prioritize material flexibility.
- Fused Deposition Modeling:Thermoplastic extrusion dominates installed base volume in academic and hospital research settings due to low capital cost and material accessibility. FDM systems serve prototyping workflows for surgical guides at institutions lacking cleanroom infrastructure.
- Stereolithography:Vat photopolymerization delivers superior surface finish for dental prosthetics and microfluidic device channels. Dental laboratories in the United States transition to SLA platforms for hybrid resin crown production.
- Selective Laser Sintering:Powder bed fusion with CO2 lasers commands premium pricing in production-grade orthopedic applications. SLS systems process implantable-grade PA12 and PEEK powders for cranial and spinal implants in Germany's university hospital clusters.
- Binder Jetting:Powder-based printing with liquid binding agents enables high-throughput metal part production. Emerging applications in porous titanium bone scaffolds attract orthopedic OEM evaluation.
Fused Deposition Modeling retains the largest installed base; Selective Laser Sintering captures the steepest expansion trajectory.
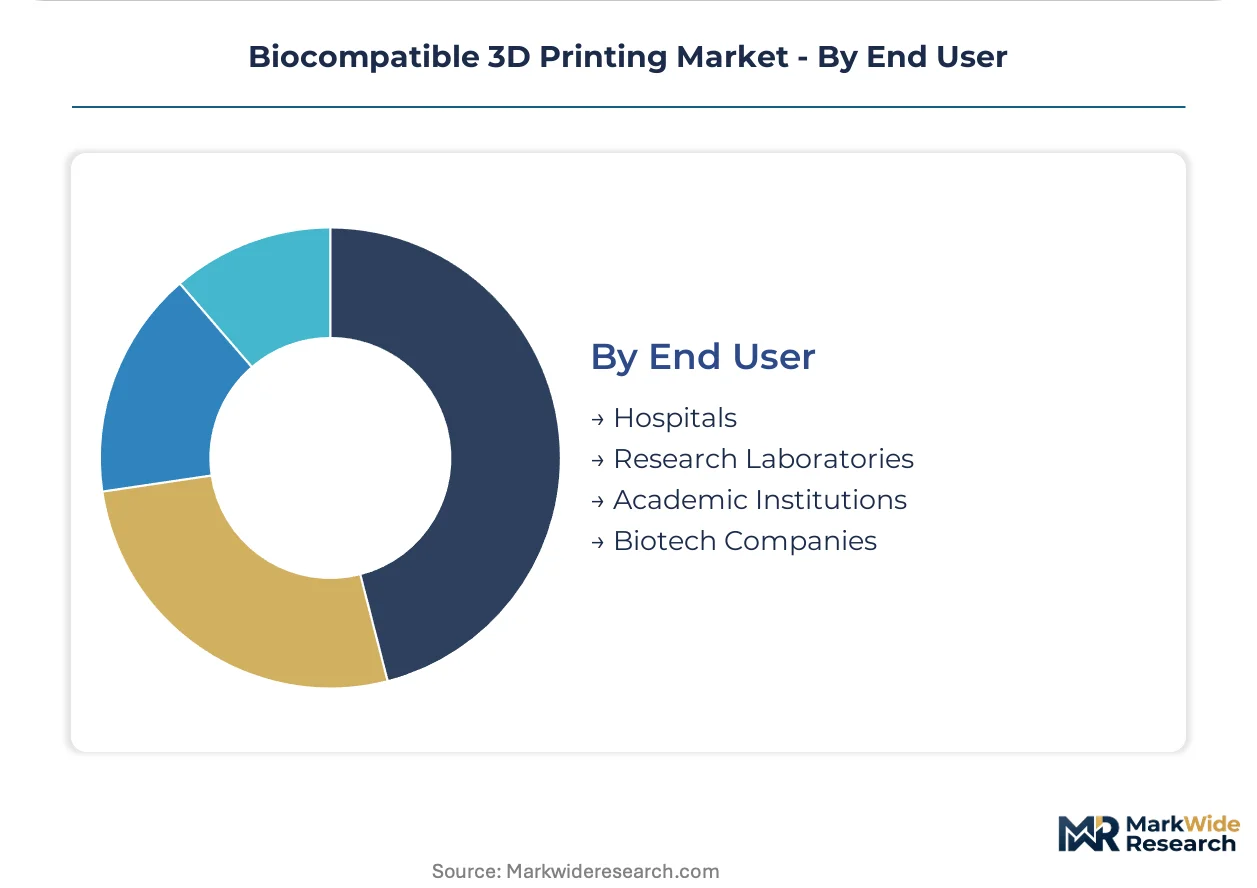
End User:
End user categories separate by regulatory sophistication, capital availability, and sterile field integration requirements, with hospitals demanding bundled compliance support unavailable to research purchasers.
- Hospitals:Tertiary care networks building centralized printing facilities require ISO 10993 documentation packages and point-of-care manufacturing protocols. North American academic medical centers lead in-house implant production investments.
- Research Laboratories:Contract research organizations and government institutes prioritize material flexibility and iterative design speed over production throughput. India's PLI scheme for medical devices attracts filament extrusion investments serving South Asian CROs.
- Academic Institutions:University engineering and medical schools train biomedical engineers in additive process parameters and sterile field protocols. Swiss and German technical universities anchor European polymer research hubs.
- Biotech Companies:Tissue engineering startups and regenerative medicine firms concentrate demand for bioink formulations and bioreactor-compatible printing systems. Netherlands-based cell therapy companies drive specialized paste development.
Hospitals generate the largest revenue concentration today; biotech companies are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redistributing biocompatible 3D printing investments toward jurisdictions with streamlined device approval pathways and concentrated polymer research infrastructure. Manufacturers are relocating production to exploit gaps between FDA 510(k) efficiency and EMA MDR documentation burdens.
United States
Academic medical centers in Boston and Houston are scaling centralized printing facilities for patient-matched surgical guides. FDA's 2022 point-of-care manufacturing guidance clarified validation protocols for hospital-based production. The Minneapolis-St. Paul corridor anchors dental laboratory consolidation toward hybrid resin platforms.
Germany
University hospital clusters in Munich and Heidelberg command premium pricing for cranio-maxillofacial PEEK implants. EMA's Medical Device Regulation imposes unique device identification requirements that reorganize quality management systems for lot-size-one production. The Rhine-Main region concentrates SLS powder supply relationships.
China
Domestic medical device clusters in Suzhou and Shenzhen are absorbing technology transfer from Western polymer formulation specialists. NMPA's streamlined Class II device pathways accelerate market entry for dental prosthetics manufacturers. Yangtze River Delta hospitals are piloting in-house titanium lattice production.
Switzerland
Swissmedic's alignment with EU MDR standards enables parallel market access strategies for custom implant producers. Zurich and Basel anchor European bioprinting research with specialized bioink development programs. The country's technical universities train biomedical engineers in sterile field additive protocols.
India
Contract research organizations in Hyderabad and Bangalore are attracting filament extrusion investments under the PLI scheme for medical devices. CDSCO's evolving framework for custom-made devices creates regulatory clarity for point-of-care manufacturing pilots. Domestic polymer research hubs are qualifying implantable-grade PA12 alternatives.
Biocompatible 3D Printing Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue bioprinting specialization and decentralized service models. The market structures around three tiers: vertically integrated material-platform vendors, hardware-centric system suppliers, and application-focused service providers. Consolidation pressure concentrates in powder supply chains where implantable-grade certifications create bottlenecks. Dominant competitive moves include backward integration into monomer synthesis and strategic partnerships with hospital procurement committees.
Among Germany-based chemical and systems specialists, EOS GmbH and Evonik Industries AG exemplify the material-platform archetype through captive supply of implantable-grade powders. 3D Systems Inc. occupies a position representing the vertically integrated resin-to-filament control model that hospital procurement committees increasingly favor for bundled compliance documentation. These three anchors illustrate how competitive positioning stratifies between upstream material qualification and downstream regulatory service bundling.
| Leading Market Players |
|---|
| 3D Systems Inc. |
| Stratasys Ltd. |
| Formlabs Inc. |
| Evonik Industries AG |
| EOS GmbH |
| Renishaw plc |
| EnvisionTEC Inc. |
| Concept Laser GmbH |
| Aspect Biosystems Ltd. |
| Others |
Pricing and Supply Chain Analysis
Family-owned German chemical specialists anchor implantable-grade PEEK powder supply, translating captive production into pricing discipline that resists commoditization even as hospital procurement committees demand bundled regulatory documentation packages. Their concentrated ownership structures prioritize long-term certification investments over short-term volume share, reinforcing premium positioning across European cranio-maxillofacial implant workflows.
Pricing Analysis
Distributor margins for medical-grade filaments and powders typically range from 15-25 percent, with direct-to-hospital contracts commanding steeper discounts in exchange for multi-year supply commitments. Pricing stratifies across implantable-grade certifications, ISO 10993-18 compliant materials, and research-grade alternatives, with FDA-cleared resins capturing substantial premiums over CE-marked equivalents. Cost compression in dental hybrid resins is intensifying because large laboratory networks are consolidating purchasing power and transitioning from milled zirconia. Contract manufacturers exhibit the highest price sensitivity due to single-source qualification risks, while academic medical centers prioritize bundled compliance support over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with Evonik Industries AG's dominance of implantable-grade PEEK powder production, creating procurement concentration risk for SLS implant manufacturers dependent on German supply. Raw material dependencies draw from Saudi Arabia for high-purity titanium sponge, Belgium for specialized photopolymer monomers, and China for ceramic filler precursors. Tariff exposure on Chinese-sourced titanium powder feeds into cost structures for binder jetting bone scaffold producers. Distribution runs through authorized medical device distributors with cold-chain and cleanroom handling capabilities, bypassing general industrial channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where FDA 510(k) pathway efficiency versus EMA MDR documentation burdens creates 12-18 month approval timeline differentials, rewarding production relocation toward U.S. hospital procurement networks.
For Market Incumbents: Hedge PEEK powder supply concentration by qualifying secondary PA12 sources from India's emerging polymer research hubs, while accelerating backward integration into photopolymer monomer synthesis to defend margin position against resin formulation specialists. Hospital procurement committee consolidation threatens traditional distributor relationships, making captive regulatory documentation capabilities the critical defensive lever. For New Entrants and Emerging Players: Direct-to-biomedical-engineer digital channels bypass capital equipment vendor gatekeepers, enabling rapid penetration of veterinary orthopedics applications where regulatory barriers remain minimal. India's PLI scheme for medical devices offers the most penetrable geography for filament extrusion investments serving South Asian contract research organizations. A software companion strategy pairing topology optimization tools with material qualification support accelerates clinical translation timelines. For Investors and Strategic Acquirers: Valuations sit cheapest among bioprinting paste specialists with academic hospital pilot contracts but limited production scale, offering asymmetric upside if cell-therapy regulatory frameworks mature. Long-term viability across the analysis window hinges on successful navigation of FDA point-of-care manufacturing guidance evolution. Watch for NMPA Class II device pathway acceleration as the inflection signal for Chinese market entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 10993-18 Certification Investment | Reduces requalification burden for hospitals switching resin suppliers under FDA guidance. |
| Hospital System Partnership | Bundles hardware with regulatory documentation packages preferred by North American academic medical centers. |
| Backward Integration into Monomer Synthesis | Enables 3D Systems Inc. to control quality from raw material through finished filament. |
| Veterinary Orthopedics Pilot Program | Allows rapid titanium lattice iteration before human clinical translation under FDA pathways. |
| AI-Generative Design Integration | Automates patient-specific implant geometry generation from DICOM imaging for cranio-maxillofacial applications. |
Research Methodology
Bottom-up hospital procurement modeling reconciled against top-down powder and resin supply tracking forms the analytical core of this study. Primary interviews with biomedical engineers, hospital purchasing committee chairs, GPO contracts managers, and regulatory affairs leads at dental laboratory networks combined with secondary validation from FDA 510(k) filings, EMA MDR submission databases, ISO 10993 certification registries, and customs trade data for medical-grade polymer imports. Triangulation between demand-side adoption curves and supply-side capacity announcements ensures coherence across volume and value estimates.
Historical trendline analysis of cranio-maxillofacial implant production volumes and dental prosthetic unit economics established baseline growth patterns across the projection horizon. The analytical framework segments by material type, application, technology platform, and end-user category, with additional modeling of regulatory pathway cluster effects. CAGRs were derived from fitted growth curves adjusted for EMA MDR implementation lag effects and FDA point-of-care guidance adoption rates. Forecast inputs incorporate hospital capital expenditure cycles for cleanroom infrastructure and polymer research hub expansion timelines.
The model assumes a particular technology adoption path; alternative pathways for binder jetting metal production would alter the outlook if throughput economics improve faster than projected. Forecasts reflect assumptions about ISO 10993-18 standardization timelines, FDA guidance finalization, and hospital sterile field integration capabilities. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Engineering
North America Biosurgery Market
Biomedical Engineering
Bioabsorbable Osteosynthesis Devices Market
Biomedical Engineering
3D Bioprinted Organ Transplants Market
Biomedical Engineering
3D Bioprinting Market
Biomedical Engineering
Non-Surgical Bio-Implants Market
Biomedical Engineering
Bioimplants Market
Biomedical Engineering
Europe Bioresorbable Vascular Scaffold Market
Biomedical Engineering
Next-Generation Biomanufacturing Market
Biomedical Engineering
Bionic Eye Market
Biomedical Engineering
Bioabsorbable Implant Market
Biomedical Engineering
Self-Inflating Tissue Expander Market
Biomedical Engineering
North America Lab-On-A-Chip and Microarrays (Biochip) Market
Biomedical Engineering
Biological Derived Devices Market
Biomedical Engineering
Tissue Extraction System Market
Biomedical Engineering
Global Biomedical Tester Market
Biomedical Engineering
Protein Engineering Market