
 Next-Generation Biomanufacturing Market | 2026-2036
Next-Generation Biomanufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Next-Generation Biomanufacturing Market Outlook
Single-use bioreactor materials are restructuring capital deployment across biologics facilities, replacing multi-million dollar stainless steel installations with flexible polymer-based systems. Thermo Fisher Scientific leverages its consumables portfolio to anchor downstream purification workflows. Danaher Corporation sustains competitive pressure through integrated process analytics. Merck KGaA differentiates via high-performance cell culture media formulations.
Next-generation biomanufacturing encompasses integrated production platforms that combine cell culture, fermentation, and continuous processing with gene editing capabilities to yield recombinant proteins, viral vectors, and cell therapies at commercial scale. These systems operate under tightly controlled parameters including temperature, pH, dissolved oxygen, and metabolite concentration to ensure batch consistency and regulatory compliance. The technology dimension shows continuous processing gaining traction as manufacturers pursue real-time release testing and reduced facility footprints. The application dimension reveals therapeutics commanding the largest value share, though industrial enzymes represent an emerging margin pool as bio-based chemistry expands.
FDA's process validation guidance and EMA's good manufacturing practice framework for advanced therapy medicinal products shape equipment qualification requirements and facility design standards. China's NMPA alignment with ICH Q5A through Q5D guidelines accelerates international technology transfer into domestic biologics plants. Stakeholders must monitor evolving biosimilar pathway requirements across major jurisdictions to anticipate capacity allocation decisions.
Market Dynamics
Single-use bioreactor systems are compressing facility construction timelines from five years to eighteen months while simultaneously lowering contamination risk profiles across viral vector manufacturing.
Growth Catalysts
- Continuous Processing Technology:Real-time release testing capabilities eliminate batch hold times and reduce quality control labor intensity. FDA's process validation guidance explicitly accommodates these continuous manufacturing paradigms.
- EMA's ATMP Framework:The advanced therapy medicinal products manufacturing standards create regulatory clarity for cell therapy commercialization. European facilities are expanding capacity to meet these qualification requirements.
- China's Biologics Manufacturing:NMPA alignment with ICH Q5A through Q5D guidelines accelerates technology transfer into domestic plants. Suzhou and Shanghai clusters host the fastest capacity expansion.
Market Restraints
- Polymer Supply Concentration:Specialized fluoropolymer films for single-use bags originate from a limited supplier base concentrated in Germany and the United States. Any disruption cascades through biologics production schedules.
- Process Analytical Technology Costs:Raman spectroscopy and capacitance probe installations require substantial capital outlay. Mid-tier CDMOs defer these investments despite regulatory pressure.
- Stainless Steel Asset Stranding:Existing multi-million dollar fixed-tank installations face accelerated depreciation as flexible systems capture new build decisions. Facility retrofit economics rarely justify hybrid configurations.
Strategic Opportunities
- India's Emerging CDMO Base:Hyderabad and Bengaluru clusters attract technology transfer partnerships from Western sponsors. CDSCO's streamlined biosimilar pathways reduce approval timelines versus historical norms.
- Continuous Chromatography Convergence:Multi-column countercurrent systems combined with single-use flow paths enable fully continuous downstream processing. This integration compresses facility footprints by sixty percent versus batch alternatives.
- Japan's Regenerative Medicine:PMDA's conditional approval framework for cell therapies creates early revenue windows. Manufacturing partnerships with domestic pharma accelerate market access.
Industry Challenges
- Skilled Technician Scarcity:Aseptic processing and cell culture optimization require specialized training pipelines. Singapore's biologics training institutes report enrollment capacity constraints.
- Legacy MES Integration:Manufacturing execution systems from prior facility generations resist interoperability with modern distributed control architectures. Data integrity remediation consumes validation resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Next-Generation Biomanufacturing Market |
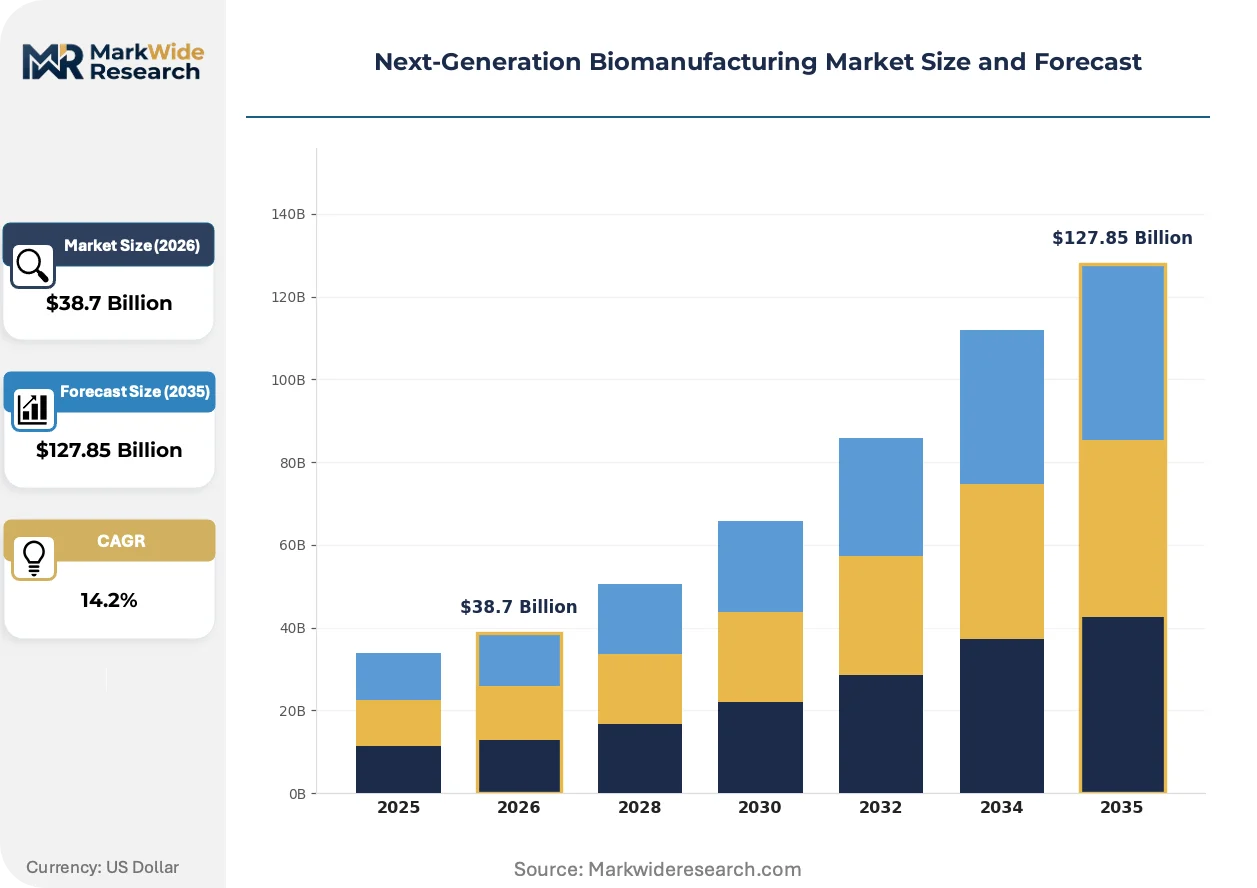
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $127.85 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibodies, Enzymes, Vaccines, Hormones Technology: Cell Culture, Fermentation, Continuous Processing, Gene Editing Application: Therapeutics, Diagnostics, Research, Industrial End User: Pharmaceutical Companies, Biotech Firms, Research Institutions, Contract Manufacturers |
| Companies Covered | Thermo Fisher Scientific Inc., Danaher Corporation, Merck KGaA, Sartorius AG, Applikon Biotechnology BV, bbi-biotech GmbH, PBS Biotech, Inc., Eppendorf AG, Meissner Filtration Products, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Next-Generation Biomanufacturing Market Strategic Shifts
Digital twin architectures and artificial intelligence-driven process control are converging with physical bioreactor infrastructure to enable predictive manufacturing across therapeutic modalities.
Perfusion bioreactor platforms are integrating cell retention devices with automated nutrient feed systems to achieve densities exceeding one hundred million cells per milliliter. Gene therapy manufacturers in Massachusetts and North Carolina are deploying these systems for AAV production. The technology is integrating upstream and downstream unit operations into unified continuous trains that collapse overall production duration.
EMA's revised Annex 1 guidelines on sterile product manufacturing impose enhanced environmental monitoring requirements on fill-finish operations. The industrial consequence mandates isolator technology adoption and restricted access barrier systems across European facilities. Cell therapy producers are responding with closed-system automation that minimizes human intervention during critical processing steps.
CDMO selection criteria now emphasize integrated service capabilities spanning cell line development through commercial release. Biopharma sponsors are consolidating vendor relationships and awarding multi-product, multi-year agreements to single partners. This concentration is most visible among mid-cap biotech companies in the San Francisco Bay Area and Boston corridors seeking to preserve capital for clinical development.
Next-Generation Biomanufacturing Market Segmentation
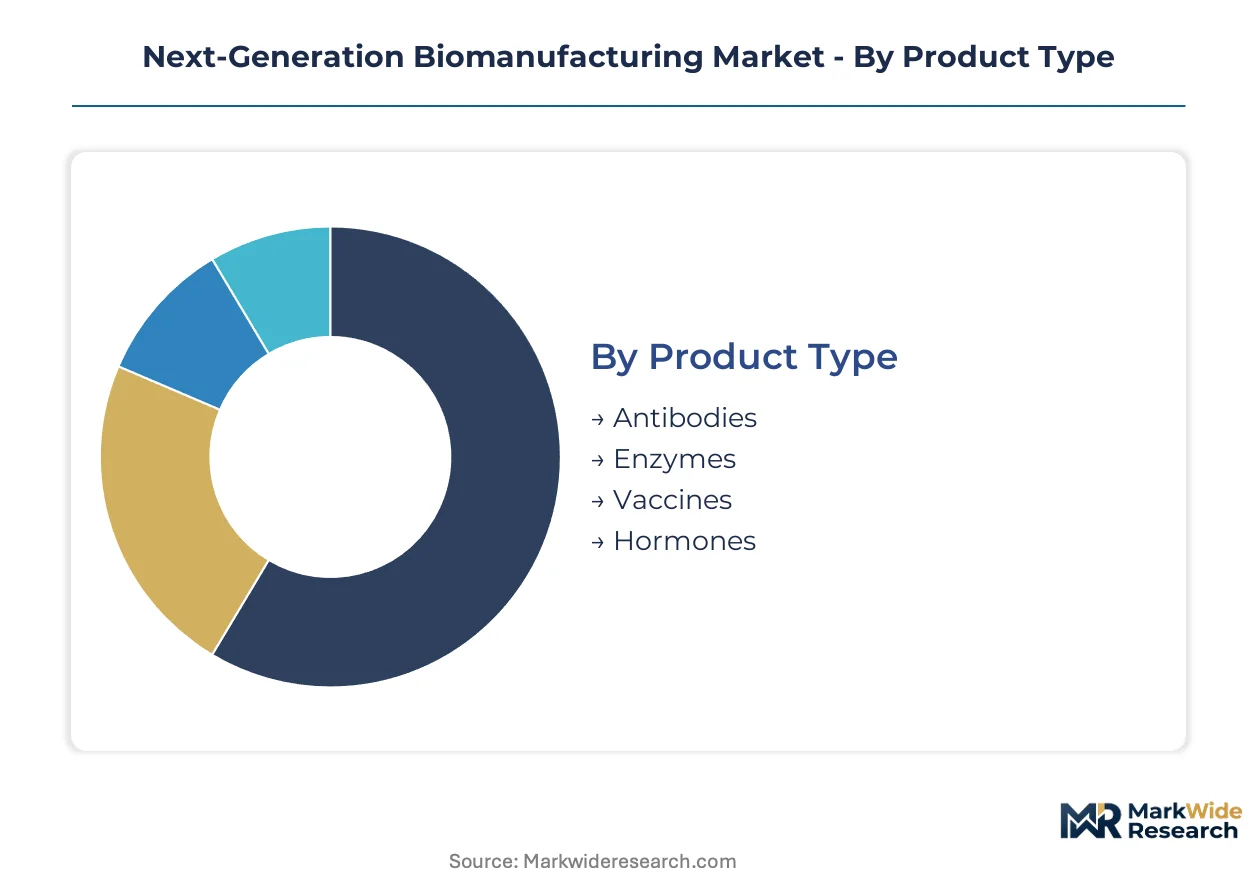
Segmentation in next-generation biomanufacturing reveals how technology choices and application priorities redistribute capital across facility types. Product modality dictates equipment configuration, while end-user scale determines whether single-use or stainless steel platforms dominate procurement decisions.
Product Type:
Supply concentration in specialized polymer films and cell culture media creates divergent margin structures across product categories, with high-value modalities capturing premium capacity allocation.
- Antibodies:Monoclonal and bispecific antibody production commands the largest installed base of single-use bioreactors. Massachusetts and North Carolina facilities prioritize perfusion platforms for these high-titer molecules. FDA process validation guidance accommodates continuous manufacturing paradigms that compress batch release timelines.
- Enzymes:Industrial enzyme manufacturing favors stainless steel fermentation infrastructure at scale. Novozymes and DuPont legacy facilities in Denmark and Iowa maintain competitive cost positions through established fixed-tank assets. Bio-based chemistry expansion in Germany and China is redirecting some capacity toward pharmaceutical-grade enzyme production.
- Vaccines:Viral vector and recombinant protein vaccines deploy hybrid cell culture-fermentation trains. EMA Annex 1 sterile manufacturing requirements drive isolator technology adoption across European fill-finish operations.
- Hormones:Recombinant hormone production leverages established microbial expression systems. Insulin and growth factor manufacturing concentrates in established biologics clusters with mature regulatory track records.
Today's leader: Antibodies. Tomorrow's challenger: Enzymes.
Technology:
Cost tier differentiation separates capital-intensive continuous installations from modular batch alternatives, with mid-tier CDMOs deferring analytics investments despite regulatory pressure.
- Cell Culture:Mammalian and insect cell platforms produce complex glycoproteins requiring post-translational modification. Perfusion bioreactors with automated cell retention achieve densities exceeding one hundred million cells per milliliter in AAV production facilities.
- Fermentation:Microbial systems yield high-titer proteins and enzymes at lower cost per gram. Stainless steel tanks retain economic advantage for commodity-scale outputs where flexibility matters less than unit economics.
- Continuous Processing:Integrated upstream-downstream trains enable real-time release testing. Multi-column countercurrent chromatography combined with single-use flow paths compresses facility footprints by sixty percent versus batch alternatives.
- Gene Editing:CRISPR-enabled cell line engineering accelerates clone selection and productivity optimization. Chinese hamster ovary cell engineering platforms in Boston and San Francisco corridors reduce timeline to commercial cell banks.
Volume concentration favors cell culture today. Margin expansion is climbing the fastest in continuous processing.
Application:
Application priority determines regulatory pathway complexity, with therapeutics commanding the most stringent qualification requirements and quality control intensity.
- Therapeutics:Commercial biologics production absorbs the majority of next-generation manufacturing capacity. FDA and EMA quality guidelines tighten process analytical technology requirements across monoclonal antibody and cell therapy modalities.
- Diagnostics:Recombinant protein and enzyme production for diagnostic assays operates under less intensive GMP oversight. Supply security concerns post-COVID have diversified manufacturing geography for critical diagnostic reagents.
- Research:Preclinical and clinical-grade material production serves pipeline development needs. Contract manufacturers in Hyderabad and Bengaluru attract technology transfer partnerships for research-scale outputs.
- Industrial:Bio-based chemicals and specialty enzymes represent an emerging margin pool. China's dual carbon goals accelerate fermentation capacity expansion for renewable material precursors.
Today's anchor: Therapeutics. Tomorrow's expansion vector: Industrial.
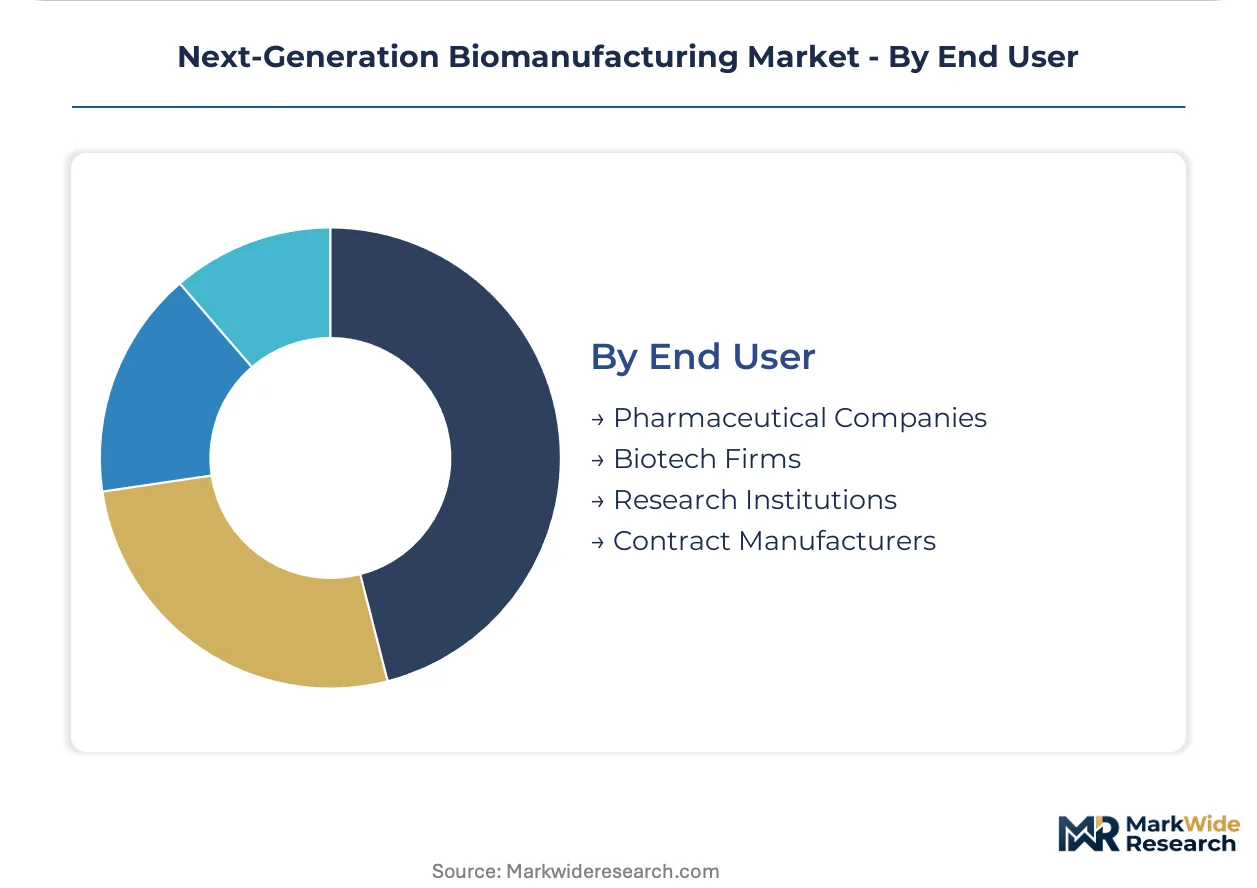
End User:
Customer type stratification separates integrated pharmaceutical sponsors from capital-constrained biotech firms, with procurement patterns diverging on single-use versus stainless steel preferences.
- Pharmaceutical Companies:Large sponsors consolidate vendor relationships and award multi-product, multi-year agreements to single CDMO partners. Thermo Fisher Scientific and Danaher Corporation compete for integrated service contracts spanning cell line development through commercial release.
- Biotech Firms:Mid-cap companies in San Francisco and Boston corridors prioritize capital preservation for clinical development. These sponsors favor flexible single-use platforms that defer fixed asset commitments until commercial proof.
- Research Institutions:Academic and government laboratories operate at smaller scale with less stringent regulatory requirements. Merck KGaA differentiates via high-performance cell culture media formulations targeting this price-sensitive segment.
- Contract Manufacturers:CDMOs invest in platform technologies that accommodate diverse client molecules. Singapore's biologics training institutes report enrollment capacity constraints as CDMOs compete for skilled aseptic processing technicians.
Current volume leader: Pharmaceutical Companies. Emerging share gainer: Contract Manufacturers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Massachusetts anchors the most concentrated biologics manufacturing footprint worldwide, with North Carolina and the San Francisco Bay Area forming secondary poles of cell therapy and viral vector production.
United States
FDA process validation guidance accommodates continuous manufacturing paradigms that compress batch release timelines. The 21st Century Cures Act provisions accelerate cell therapy commercialization pathways. Massachusetts facilities prioritize perfusion platforms for high-titer monoclonal antibody production.
Germany
Specialized fluoropolymer films for single-use bags originate from concentrated supplier bases in Germany. EMA Annex 1 sterile manufacturing guidelines impose enhanced environmental monitoring on fill-finish operations. Bavaria hosts legacy stainless steel fermentation assets that maintain competitive positions in industrial enzyme production.
China
NMPA alignment with ICH Q5A through Q5D guidelines accelerates technology transfer into domestic biologics plants. Dual carbon goals redirect fermentation capacity expansion toward renewable material precursors. Suzhou and Shanghai clusters host the fastest capacity expansion for mammalian cell culture platforms.
India
Hyderabad and Bengaluru clusters attract technology transfer partnerships from Western sponsors seeking cost-efficient research-scale outputs. CDSCO streamlined biosimilar pathways reduce approval timelines versus historical norms. Singapore's biologics training institutes report enrollment capacity constraints as regional CDMOs compete for skilled technicians.
Japan
PMDA's conditional approval framework for cell therapies creates early revenue windows for domestic manufacturers. METI industrial policy supports manufacturing partnerships between domestic pharma and international technology providers. Kanto region facilities concentrate on closed-system automation that minimizes human intervention during critical processing steps.
Next-Generation Biomanufacturing Market Competitive Environment
Capacity expansion dominates the current landscape as CDMOs race to capture multi-product, multi-year agreements from capital-constrained biotech sponsors. The vendor base stratifies across three tiers: integrated life science conglomerates with consumables-to-instrument portfolios, specialized equipment fabricators with deep bioreactor expertise, and regional automation specialists serving price-sensitive academic segments. Strategic archetypes include platform-technology aggregators, single-use materials specialists, and process analytics integrators. Geographic expansion and technology licensing represent the dominant competitive moves, with players establishing training institutes and qualification centers in Singapore and India to secure technician pipelines.
Within the integrated conglomerate tier, Thermo Fisher Scientific Inc. and Danaher Corporation exemplify platform-technology aggregators that span cell line development through commercial release. Merck KGaA occupies a distinct position as a consumables-focused specialist with deep formulation expertise. Sartorius AG and Eppendorf AG represent German-engineered precision equipment fabricators. Applikon Biotechnology BV and bbi-biotech GmbH sit within the specialized bioreactor segment, while PBS Biotech, Inc. and Meissner Filtration Products, Inc. anchor the single-use materials and filtration technology vectors respectively.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Danaher Corporation |
| Merck KGaA |
| Sartorius AG |
| Applikon Biotechnology BV |
| bbi-biotech GmbH |
| PBS Biotech, Inc. |
| Eppendorf AG |
| Meissner Filtration Products, Inc. |
| Others |
Value Chain & Pricing Dynamics
Fluoropolymer film indices for single-use bioreactor bags cascade through three-tier pricing structures across premium, standard, and economy levels, with German and US resin concentration amplifying cost pass-through volatility for biologics manufacturers navigating stainless steel displacement timelines.
Pricing Analysis
Input-cost pass-through from specialized polymer films dominates pricing dynamics across single-use system tiers. Pricing stratifies across premium, standard, and economy tiers based on certification grade against FDA process validation guidance and volume scale commitments from multi-year CDMO agreements. Cost compression in standard-tier consumables is intensifying because mid-tier contract manufacturers defer Raman spectroscopy investments despite EMA Annex 1 pressure. Research institutions exhibit highest price sensitivity, while integrated pharmaceutical sponsors prioritize total cost of ownership over unit pricing.
Supply Chain Analysis
Workforce availability constraints in Singapore's biologics training institutes and Massachusetts cell therapy corridors are forcing capacity allocation decisions across facility expansion timelines. Supply concentration rests on Germany and the United States for fluoropolymer films, China for stainless steel fermentation infrastructure, and India for research-scale outputs. Critical dependencies include cell culture media formulations, automated cell retention devices, and multi-column chromatography skids. Single-source vulnerability in polymer resin supply creates cascading production schedule risks. Distribution runs through integrated life science conglomerates with consumables-to-instrument portfolios serving CDMO consolidation trends.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with EMA's ATMP framework and FDA process validation guidance accelerating facility qualification investments that lock in multi-year demand cycles.
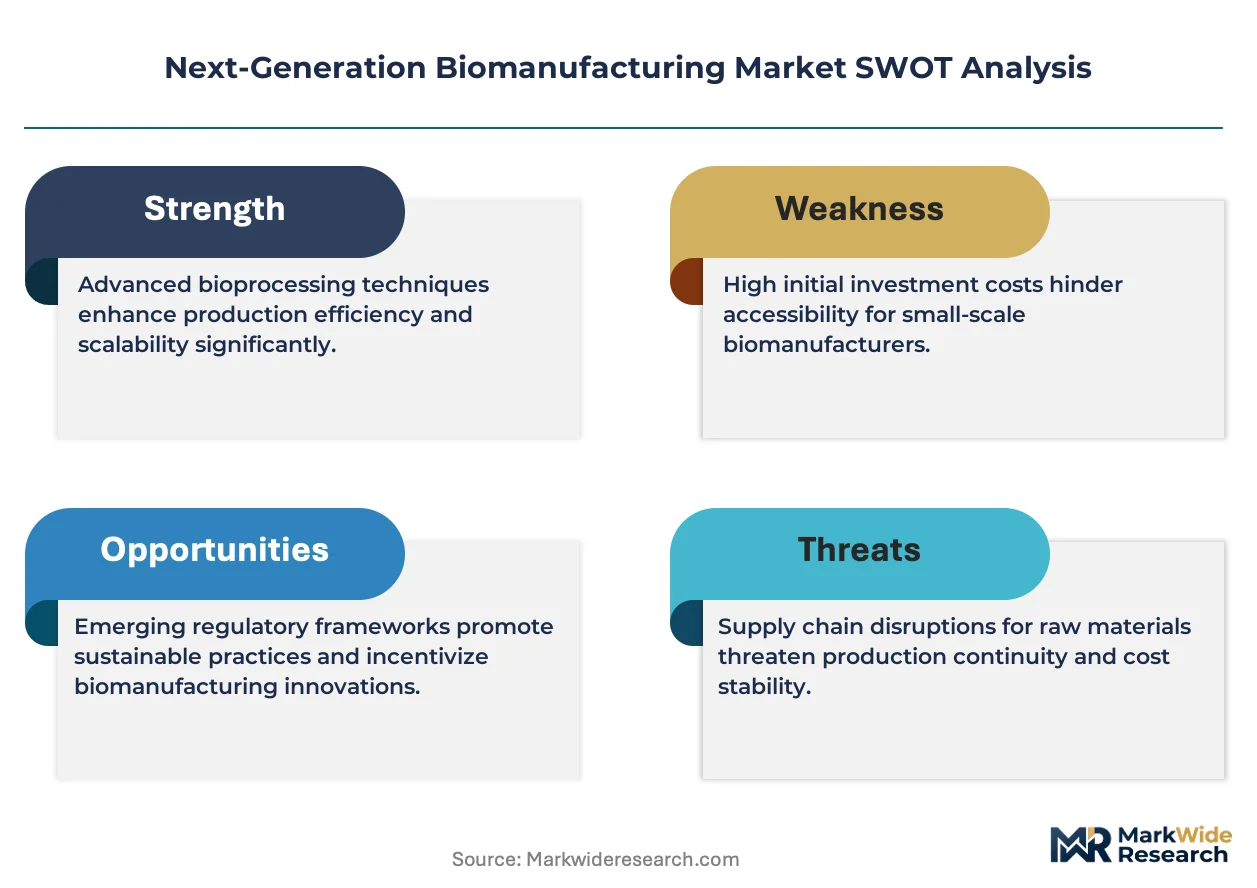
For Market Incumbents: Extend platform-technology aggregation into continuous processing integration to defend against emerging automation specialists capturing mid-tier CDMO relationships. Anchor consumables portfolios with backward integration into cell culture media formulation capacity. Prioritize certification investment against evolving EMA Annex 1 sterile manufacturing requirements to maintain pricing power in European fill-finish operations. For New Entrants and Emerging Players: Mid-cap biotech firms in Boston and San Francisco corridors represent the most penetrable buyer archetype, with capital preservation priorities favoring flexible single-use procurement over fixed asset commitments. White-space targets include isolator technology for cell therapy closed-system automation and perfusion platform servicing for viral vector manufacturers in North Carolina. Go-to-market positioning should emphasize eighteen-month facility construction timelines versus five-year stainless steel alternatives. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized bioreactor fabricators possessing deep perfusion expertise and established training institute partnerships in Singapore and India. Long-term viability hinges on regulatory alignment velocity rather than manufacturing scale alone. Acquisition target archetypes include single-use materials specialists with captive fluoropolymer film relationships. Monitor NMPA-ICH harmonization milestones as inflection indicators for China technology transfer acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Processing Integration | Multi-column countercurrent chromatography combined with single-use flow paths compresses facility footprints by sixty percent versus batch alternatives. |
| CDMO Consolidation Partnerships | Multi-product, multi-year agreements with capital-constrained biotech sponsors in San Francisco and Boston corridors secure predictable revenue streams. |
| Regulatory Certification Investment | EMA Annex 1 compliance and FDA process validation guidance alignment differentiate vendors for European fill-finish and US therapeutic production. |
| Workforce Pipeline Development | Singapore biologics training institutes and Indian technician certification programs address skilled aseptic processing scarcity constraining capacity expansion. |
| Regional Technology Transfer | NMPA-ICH Q5A through Q5D alignment accelerates international equipment qualification into Suzhou and Shanghai manufacturing clusters. |
Study Parameters
Multiple input streams — primary interviews with bioprocess engineers, regulatory affairs leads at CDMOs, and facility design architects, alongside secondary validation against FDA guidance documents, EMA submission databases, and SEC filings from integrated life science conglomerates — were reconciled through bottom-up and top-down triangulation to establish market boundaries and growth trajectories.
Data-stream reconciliation across product modality segmentation, technology platform tiers, and end-user scale categories enabled CAGR derivation through installed base replacement modeling and capacity expansion pipeline tracking over the projection horizon. Forecast inputs incorporated stainless steel asset stranding velocity, single-use bioreactor adoption curves, and continuous processing regulatory acceptance thresholds.
Underlying measurement precision varies by segment; antibody and cell therapy manufacturing carry tighter precision than industrial enzyme production given more transparent capacity announcements and regulatory filing visibility. Forecasts reflect assumptions regarding polymer supply stability, technician training pipeline expansion, and harmonized guidance implementation timelines. Material deviation in NMPA inspection readiness timelines or fluoropolymer supplier concentration triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Engineering
Bioactive Coating Devices Market
Biomedical Engineering
Bioprosthetics Market
Biomedical Engineering
Tissue Extraction System Market
Biomedical Engineering
Tissue Engineering Market
Biomedical Engineering
Bioabsorbable Implant Market
Biomedical Engineering
Bionic Eye Market
Biomedical Engineering
Tissue Engineered Skin Substitute Market
Biomedical Engineering
Bioink Market
Biomedical Engineering
Global Bionics Market
Biomedical Engineering
Non-Surgical Bio-Implants Market
Biomedical Engineering
Artificial Organ Bank Market
Biomedical Engineering
Bioimplants Market
Biomedical Engineering
3D Bioprinted Human Tissue Market
Biomedical Engineering
Bio-Engineered Stent Market
Biomedical Engineering
Biomems Market
Biomedical Engineering
North America Biosurgery Market