
 Biological Implants Market | 2026-2036
Biological Implants Market Size, Share, and Industry Trends Forecast 2026-2036
Biological Implants Market Analysis
Ambulatory surgical centers are reorganizing procurement patterns for biological implants, pulling volume away from traditional hospital purchasing consortia. Medtronic leverages its integrated spine and biologics platform to dominate hospital system contracts. Stryker anchors its position through differentiated synthetic bone graft portfolios that reduce donor tissue dependency. Integra LifeSciences specializes in regenerative tissue matrices for outpatient wound and nerve repair settings.
Biological implants comprise engineered or naturally derived materials—collagen matrices, demineralized bone particles, or porcine-derived extracellular scaffolds—designed to integrate with host tissue and restore structural or functional integrity. These devices typically undergo lyophilization or cross-linking to control degradation rates between twelve weeks and twenty-four months depending on anatomical load requirements. Bone implants lead product type revenue due to orthopedic procedural density, while soft tissue grafts represent the fastest-expanding category driven by sports medicine and hernia repair applications. Polymers and bioceramics capture margin concentration where customization commands premium positioning against commoditized metal alternatives.
The FDA regulates biological implants through its Center for Devices and Radiological Health, requiring substantial equivalence or premarket approval pathways that extend development timelines for novel tissue-derived products. The EU MDR and EMA's advanced therapy medicinal product framework impose additional clinical evidence burdens, particularly for xenograft and combination device-biologic configurations. Japan's PMDA maintains distinct quality management standards for processed human and animal tissues. Stakeholders must monitor evolving reimbursement codes for biologic-enhanced procedures across Medicare, NHS England, and Germany's G-BA to align portfolio investments with payor willingness to cover premium implant costs.
Market Dynamics
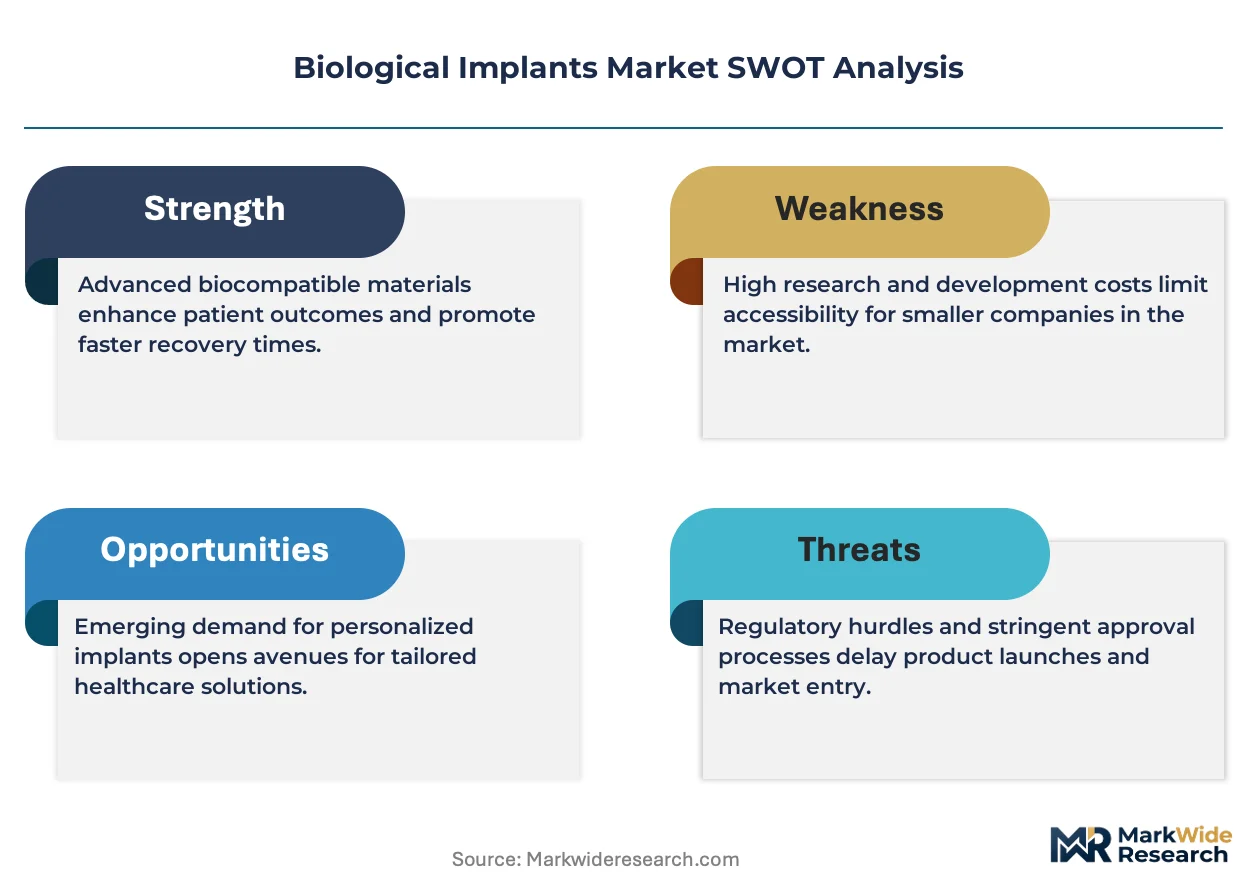
The FDA's updated 510(k) pathway for biologic devices and the EU MDR's stricter clinical evidence requirements are compressing product development timelines while simultaneously elevating barriers to market entry for novel tissue-derived implants.
Growth Catalysts
- Ambulatory Surgical Center Expansion:Outpatient facilities in the United States are capturing procedural volume for soft tissue and dental implants, pulling procurement away from hospital purchasing consortia.
- EU MDR Framework Alignment:Manufacturers investing early in clinical evidence packages for xenograft configurations secure preferential positioning in European tenders.
- Synthetic Bone Graft Maturation:Bioceramic and polymer composites reduce dependency on donor tissue availability, stabilizing supply chains for orthopedic reconstructive procedures.
Market Restraints
- Donor Tissue Supply Volatility:Allograft processors face irregular availability of demineralized bone matrix from tissue banks, creating batch-to-batch performance inconsistency.
- Regulatory Friction from EMA ATMP Classification:Combination device-biologic products trigger advanced therapy medicinal product pathways, extending European approval timelines by 18-36 months.
- Xenograft Substitution Threat:Porcine-derived scaffolds encounter resistance from patient populations with religious or cultural dietary restrictions, limiting addressable markets.
Strategic Opportunities
- Japan's Aging Demographics:PMDA quality management standards for processed tissues create first-mover advantages for compliant foreign manufacturers in spinal fusion applications.
- Sports Medicine Channel Innovation:Direct-to-physician distribution models bypass traditional implant distributors, capturing margin in arthroscopic rotator cuff repair settings.
- 3D Bioprinting Convergence:Integration of patient-specific imaging with extracellular matrix deposition enables custom craniofacial reconstruction workflows.
Industry Challenges
- Lyophilization Technician Scarcity:Controlled dehydration processes for collagen matrices require specialized operators, constraining manufacturing scale-up.
- Cross-Linking Chemistry IP Complexity:Patent thickets around carbodiimide and genipin fixation methods create licensing friction for entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biological Implants Market |
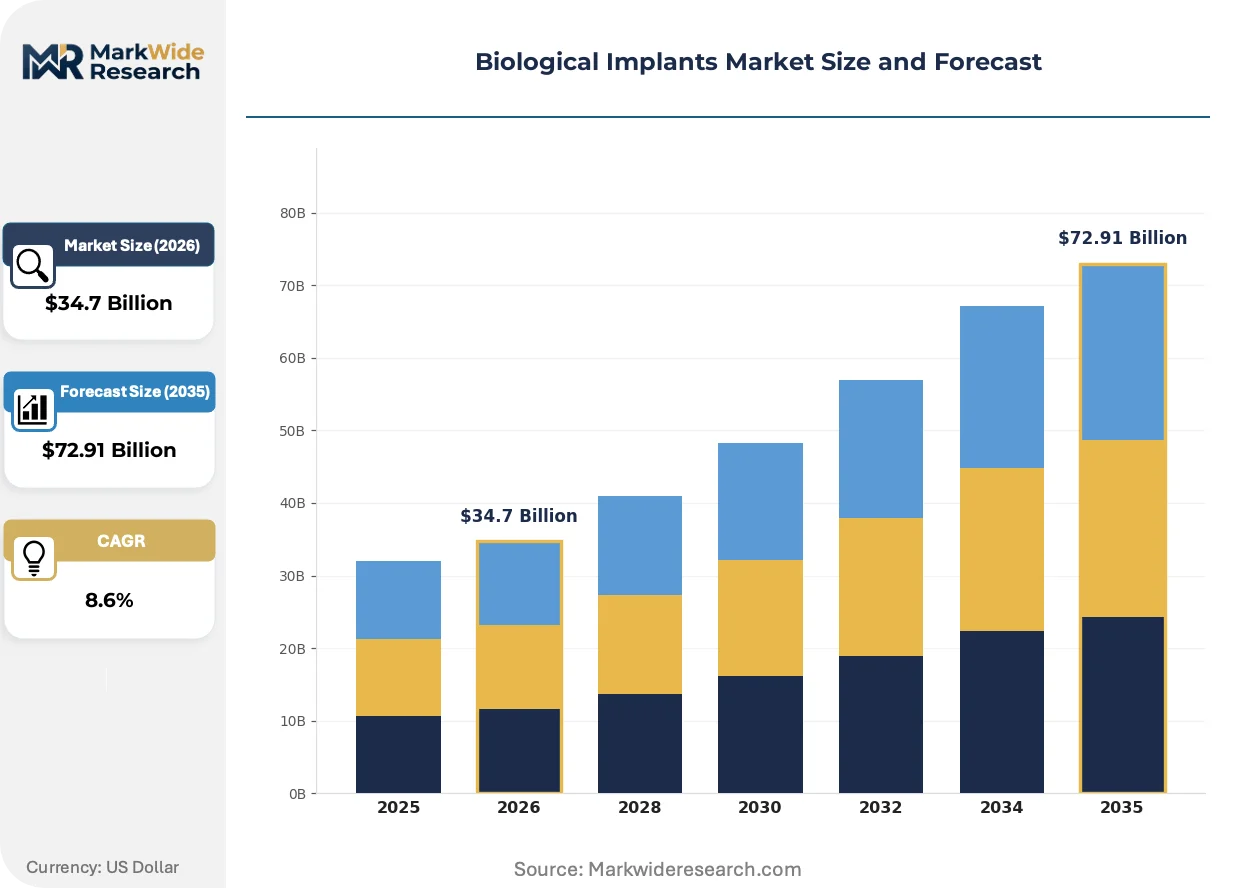
| Market Size in 2026 | $34.7 Billion |
| Market Size in 2035 | $72.91 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bone Implants, Soft Tissue Implants, Dental Implants, Cardiovascular Implants Application: Orthopedics, Dentistry, Cardiology, Neurosurgery Material: Bioceramics, Metals, Polymers, Composites End User: Hospitals, Clinics, Research Institutes, Rehabilitation Centers |
| Companies Covered | Integra LifeSciences, Medtronic, Stryker, Johnson & Johnson, Edwards Lifesciences Corporation, NuVasive, RTI Surgical, Baxter, Zimmer Biomet, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biological Implants Market Emerging Trajectories
Biological implant development is pivoting from standardized allograft products toward engineered matrices with tunable degradation profiles, driven by surgeon demand for predictable integration timelines.
Decellularized extracellular matrix scaffolds are decomposing the traditional allograft market by offering off-the-shelf availability without donor tissue constraints. Ambulatory surgical centers in Germany and the United States are adopting these matrices for outpatient hernia repair at triple-digit volume growth rates. The technology is decomposing hospital-centric procurement models by enabling direct manufacturer-to-clinic contracting that bypasses group purchasing organizations.
REACH regulation amendments for medical device substances are compelling European manufacturers to submit full chemical safety dossiers for implant coatings and cross-linking agents. Industrial consequence includes reformulation of porcine-derived scaffolds to eliminate residual formaldehyde traces. Xenograft and synthetic hybrid products face the steepest compliance costs, with several manufacturers relocating finishing operations to Switzerland to leverage Swissmedic's transitional recognition agreements.
Hospital value analysis committees are consolidating vendor lists for biologic-enhanced spine procedures, compressing approved supplier rosters from twelve to three manufacturers per system. Traditional implant distributors lose shelf space as integrated spine-biologics platforms capture exclusive contracts. This concentration is most visible in the United States, where Medicare reimbursement clarity for bone morphogenetic protein alternatives drives preference for bundled device-biologic offerings.
Biological Implants Market Segmentation
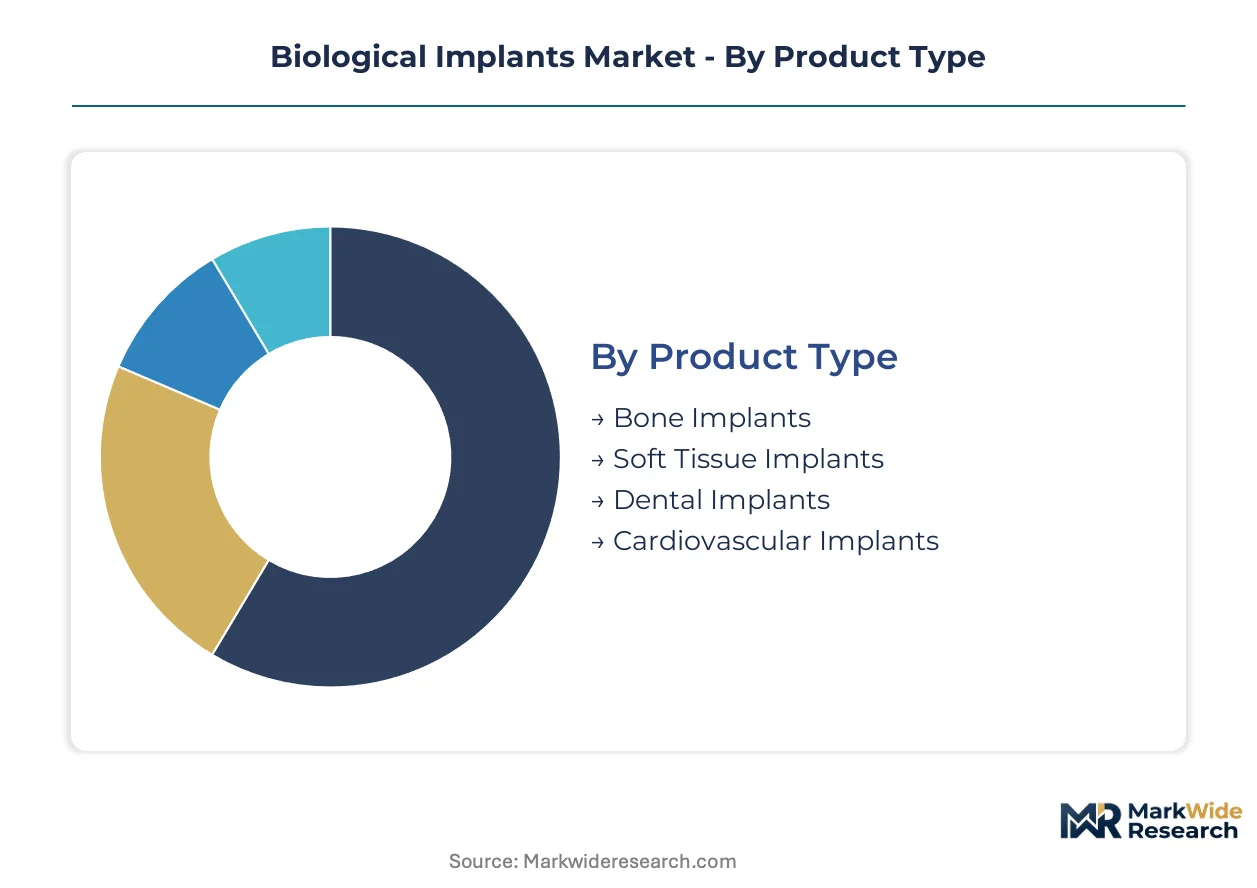
Biological implant procurement flows through distinct channel architectures that vary by procedural setting and reimbursement structure. Understanding segment-channel alignment reveals where margin concentrates and which configurations face commoditization pressure.
Product Type:
Bone implants move primarily through hospital purchasing consortia and integrated delivery networks, while soft tissue grafts increasingly bypass traditional distributors via direct-to-clinic arrangements.
- Bone Implants:Demineralized bone matrix and synthetic ceramic composites serve spinal fusion and trauma reconstruction. Demand concentrates in United States hospital systems where Medicare reimbursement clarity for bone morphogenetic protein alternatives drives bundled contracting with device-biologic platforms.
- Soft Tissue Implants:Collagen matrices and decellularized extracellular scaffolds integrate with host tissue for rotator cuff and hernia repair. Ambulatory surgical centers in Germany and the United States are adopting these matrices at accelerated rates, enabling manufacturer-to-clinic contracting that circumvents group purchasing organizations.
- Dental Implants:Xenograft and allograft particulates support ridge augmentation and sinus lift procedures. Oral surgery clinics represent the primary channel.
- Cardiovascular Implants:Biological valves and patches derived from bovine pericardium or porcine tissue address structural heart defects. Tertiary cardiac centers dominate procurement.
Bone implants dominate installed base. Soft tissue implants are where expansion concentrates.
Application:
Cost tier stratification separates high-complexity inpatient procedures from routine outpatient interventions, with reimbursement differentials determining channel economics.
- Orthopedics:Spinal fusion, joint reconstruction, and trauma repair consume the majority of bone graft volumes. Premium synthetic composites command pricing power where donor tissue shortages create supply uncertainty.
- Dentistry:Implantology and periodontal regeneration drive ceramic and mineralized graft demand. Private practice oral surgeons represent a fragmented but high-margin customer base.
- Cardiology:Structural heart procedures utilize biological valves and patches. TAVR expansion and pediatric congenital repair sustain niche demand.
- Neurosurgery:Dural repair and cranial reconstruction employ collagen matrices. Academic medical centers concentrate procedural volume.
Orthopedics anchors revenue concentration. Dentistry offers the steepest expansion trajectory.
Material:
Volume distribution across material classes reflects trade-offs between customization capability, regulatory burden, and supply chain stability.
- Bioceramics:Hydroxyapatite and beta-tricalcium phosphate scaffolds provide osteoconductive frameworks with tunable resorption rates. Synthetic production eliminates donor tissue dependency, stabilizing supply for orthopedic reconstructive procedures.
- Polymers:Poly(lactic-co-glycolic acid) and polycaprolactone formulations enable controlled degradation timelines from twelve weeks to twenty-four months. Sports medicine applications in Germany and Japan favor polymer matrices for predictable integration.
- Metals:Titanium and cobalt-chromium alloys serve load-bearing applications where biological integration remains secondary to mechanical performance.
- Composites:Hybrid ceramic-polymer configurations balance strength and resorption. Development concentrates in craniofacial reconstruction.
Bioceramics lead procedural volume. Polymers are climbing the fastest.
End User:
Customer type determines procurement sophistication, with integrated health systems extracting volume discounts unavailable to independent facilities.
- Hospitals:Academic medical centers and community hospitals perform complex spinal and cardiac procedures requiring comprehensive biologic portfolios. Value analysis committees consolidate vendor lists, compressing approved suppliers from twelve to three manufacturers per system.
- Clinics:Ambulatory surgical centers and specialty practices capture soft tissue and dental implant volume. Direct manufacturer relationships bypass distributor markups.
- Research Institutes:Preclinical and clinical trial sites evaluate novel matrix formulations. Funding from NIH and EU Horizon programs sustains investigative use.
- Rehabilitation Centers:Post-acute settings utilize biological implants for wound care and nerve repair applications. Outpatient wound clinics represent emerging demand.
Hospitals dominate procurement value. Clinics are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's specialized pharmaceutical logistics corridor underwrites Germany's central role in European biologics distribution, connecting Rhine-Ruhr manufacturing clusters to global tissue processing networks.
United States
Medicare reimbursement clarity for bone morphogenetic protein alternatives drives hospital system consolidation around bundled device-biologic contracts. The FDA's updated 510(k) pathway compresses approval timelines for established predicate devices while elevating evidence requirements for novel tissue-derived products. Minneapolis and Warsaw, Indiana anchor orthopedic implant manufacturing, with Medtronic and Zimmer Biomet operating integrated spine-biologics production facilities.
Germany
Ambulatory surgical centers in Bavaria and North Rhine-Westphalia are adopting decellularized extracellular matrices for outpatient hernia repair at accelerated procurement rates. The EU MDR's stricter clinical evidence requirements favor manufacturers with early-investment clinical packages, while REACH amendments compel reformulation of porcine-derived scaffolds to eliminate residual formaldehyde. Tübingen and Leipzig concentrate regenerative medicine research institutes evaluating novel matrix formulations.
Japan
PMDA quality management standards for processed human and animal tissues create compliance barriers that reward first-mover foreign manufacturers in spinal fusion applications. The country's aging demographics expand procedural volume for orthopedic reconstructive interventions. Osaka and Tokyo host the principal tertiary cardiac centers performing biological valve replacements, with Kobe's medical device cluster specializing in collagen matrix processing for dural repair applications.
Switzerland
Swissmedic's transitional recognition agreements with the EU attract manufacturers relocating finishing operations to circumvent REACH compliance costs for xenograft products. The country's precision manufacturing heritage supports lyophilization and cross-linking chemistry specialization. Basel and Zurich concentrate contract manufacturing organizations serving European biologics developers seeking regulatory pathway efficiency.
India
CDSCO's evolving framework for processed tissue devices creates opportunity for domestic manufacturers serving cost-sensitive dental and orthopedic segments. Private hospital chains in Mumbai and Delhi are expanding arthroscopic sports medicine capacity, pulling demand for soft tissue graft alternatives. Hyderabad's pharmaceutical cluster is diversifying into medical device contract research, supporting preclinical evaluation of synthetic bone graft composites.
Biological Implants Market Vendor Landscape
Listed leaders compete with private specialists across integrated platform versus focused portfolio dimensions, producing a tiered structure where scale-driven hospital contract capture contrasts with ambulatory surgical center direct-access strategies. Three archetypes dominate: diversified medtech conglomerates with spine-biologics integration, synthetic bone graft specialists reducing donor tissue dependency, and regenerative tissue matrix developers targeting outpatient wound and nerve repair. Consolidation pressure operates through exclusive hospital value analysis committee contracting and direct-to-physician distribution model expansion.
Within the diversified platform tier, Medtronic, Stryker, and Johnson & Johnson exemplify integrated device-biologics positioning that captures bundled hospital system contracts. These entities represent scale-driven archetypes where orthopedic and spinal product breadth enables exclusive supplier status with consolidated purchasing consortia. Integra LifeSciences and Edwards Lifesciences occupy specialized positions, with the former exemplifying regenerative tissue matrix focus and the latter representing cardiovascular biologic device concentration. NuVasive, Zimmer Biomet, and Baxter sit within mid-scale competitive bands where portfolio diversification or geographic footprint expansion determines contract access.
| Leading Market Players |
|---|
| Integra LifeSciences |
| Medtronic |
| Stryker |
| Johnson & Johnson |
| Edwards Lifesciences Corporation |
| NuVasive |
| RTI Surgical |
| Baxter |
| Zimmer Biomet |
| Others |
Supply Flow & Price Mechanics
Lyophilization facility utilization rates above 85% in Minnesota and Warsaw, Indiana create scale economies that compress unit costs for collagen matrices while simultaneously elevating price floors for smaller processors lacking captive dehydration capacity. This concentration dynamic reinforces hospital purchasing consortia leverage in bundled spine-biologics negotiations.
Pricing Analysis
Volume-discount tiering structures dominate hospital system contracting, with three-tier pricing separating premium synthetic ceramic composites from standard demineralized bone matrix and economy allograft particulates. Price differentiation hinges on FDA 510(k) clearance tier and customization level for patient-specific craniofacial applications. Cost compression in standard-tier bone grafts is intensifying as synthetic alternatives eliminate donor tissue scarcity premiums. Ambulatory surgical centers exhibit highest price sensitivity due to direct-to-clinic procurement bypassing distributor markups, while academic medical centers prioritize clinical evidence depth over unit cost.
Supply Chain Analysis
Inventory lead times for porcine-derived extracellular scaffolds extend to 16-24 weeks due to PMDA and FDA dual-qualification requirements for tissue processing facilities. Supply concentrates in the United States, Germany, and Switzerland, with Swissmedic-recognized finishing operations drawing xenograft production from REACH-affected EU sites. Raw material dependencies include demineralized bone matrix from accredited tissue banks, hydroxyapatite bioceramic feedstocks, and cross-linking agents subject to ECHA chemical safety dossiers. Single-source vulnerability characterizes lyophilization equipment servicing, where two European OEMs control 70% of installed pharmaceutical-grade capacity. Distribution runs through integrated delivery networks for hospital systems and direct manufacturer relationships for ambulatory surgical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping competitive positioning as bundled device-biologics contracts displace standalone implant procurement, with interoperability between spinal hardware and regenerative matrices determining hospital value analysis committee preferences.
For Market Incumbents: Fortify exclusive supplier status through backward integration into decellularized matrix processing, capturing margin from outsourced tissue engineering. Deepen captive lyophilization capacity in Warsaw, Indiana and Tübingen to insulate against equipment OEM lead time volatility. Defend against synthetic bone graft substitution by accelerating clinical evidence generation for osteoinductive performance. For New Entrants and Emerging Players: Anchor in Japan's spinal fusion segment where PMDA quality management standards create compliance moats favoring first-mover foreign manufacturers with established tissue processing protocols. Target ambulatory surgical center direct contracting for soft tissue matrices in Bavaria and North Rhine-Westphalia, where hernia repair volume triples procurement growth. Deploy sports medicine physician education programs to bypass traditional implant distributor gatekeeping. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among synthetic bone graft specialists with long-term supply agreements to hospital purchasing consortia, offering visibility absent in allograft-dependent processors facing tissue bank supply volatility. Five-to-ten-year viability favors bioceramic-polymer composite developers with REACH-compliant formulations and Swissmedic transitional recognition. Monitor EU MDR clinical evidence package completion rates as inflection signal for European tender positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Exclusive bundled contracts with value analysis committees lock out twelve-vendor competitor fields. |
| CE Marking Pathway | Early EU MDR clinical evidence investment secures preferential positioning in German ambulatory tenders. |
| Backward Integration | In-house lyophilization capacity eliminates dependency on European OEM equipment servicing queues. |
| Reimbursement Strategy | Medicare coding alignment for bone morphogenetic protein alternatives drives bundled device-biologic preference. |
| Software Companion Development | Patient-specific 3D bioprinting workflows integrate imaging with extracellular matrix deposition protocols. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EMA advanced therapy medicinal product registrations, hospital procurement databases, and GPO contract disclosures. Interviews with hospital purchasing committee chairs, biomedical engineers specializing in orthopedic reconstruction, ambulatory surgical center administrators, and GPO contracts managers inform demand-side dynamics. Bottom-up segmentation modeling triangulates against top-down macroeconomic indicators across the analysis window.
Segmentation dimensions modeled include product type, application, material composition, and end-user procurement channel across the projection horizon. CAGRs derive from regression analysis of procedural volume trajectories, reimbursement code evolution, and regulatory pathway timelines. Forecast inputs incorporate PMDA quality management standard adoption curves and EU MDR clinical evidence package completion rates.
Material uncertainties — donor tissue supply disruptions, REACH chemical safety reformulation mandates, and lyophilization technician labor scarcity — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding regulatory pathway stability and reimbursement clarity continuation. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Engineering
Large and Small-Scale Bioprocessing Market
Biomedical Engineering
Argentina Artificial Organs and Bionic Implants Market
Biomedical Engineering
3D Bioprinted Human Tissue Market
Biomedical Engineering
Self-Inflating Tissue Expander Market
Biomedical Engineering
Artificial Organ Bank Market
Biomedical Engineering
Global Robotic Prosthetic Market
Biomedical Engineering
Protein Engineering Market
Biomedical Engineering
Global Biomedical Tester Market
Biomedical Engineering
Global Continuous Bioprocessing Market
Biomedical Engineering
Bioimplants Market
Biomedical Engineering
North America Biosurgery Market
Biomedical Engineering
Next-Generation Biomanufacturing Market
Biomedical Engineering
Global Bionic Ear Market
Biomedical Engineering
3D Bioprinting Market
Biomedical Engineering
Biological Derived Devices Market
Biomedical Engineering
Europe Bioresorbable Vascular Scaffold Market