
 Large and Small-Scale Bioprocessing Market | 2026-2036
Large and Small-Scale Bioprocessing Market Size, Share, and Industry Trends Forecast 2026-2036
Large and Small-Scale Bioprocessing Market Analytics
Contract manufacturing networks for cell and gene therapies is rewriting how bioprocessing equipment reaches end users. Thermo Fisher Scientific leverages its integrated service model to anchor large-scale stainless steel and single-use bioreactor deployments across North American pharma hubs. Lonza sustains dominance in mammalian cell culture through its specialized manufacturing platforms for monoclonal antibody production. Sartorius AG differentiates via deep specialization in filtration and fluid management technologies that support both clinical and commercial bioprocessing stages.
Large and small-scale bioprocessing encompasses the cultivation, separation, and purification of biological materials using bioreactors operating from milliliter bench-top scales to multi-thousand-liter production vessels, with critical parameters including temperature, pH, dissolved oxygen, and agitation speed controlled through automated process analytical technology systems. The primary purpose centers on producing therapeutic proteins, viral vectors, and cellular products under current good manufacturing practice conditions for clinical and commercial supply. Single-use technology leads equipment investment due to reduced cross-contamination risk and faster batch turnaround in multi-product facilities, while continuous processing represents the fastest-growing technology segment as manufacturers pursue higher productivity and real-time quality assurance. Bioreactors capture the largest product type category by installed base value, though chromatography systems command premium margins driven by resin costs and purification complexity in downstream operations.
The FDA enforces process analytical technology and quality by design frameworks that compel bioprocessors to validate real-time monitoring systems, while the EMA's good manufacturing practice guidelines for advanced therapy medicinal products impose stringent cell traceability requirements across European manufacturing sites. ISO 13485 and ISO 14698 standards further govern cleanroom operations and biocontamination control, shaping equipment specifications and facility design decisions. Stakeholders must weigh capital allocation between stainless steel durability and single-use flexibility as product portfolios shift between monoclonal antibodies and personalized cell therapies.
Market Dynamics
The FDA's process analytical technology mandate is compressing batch timelines and forcing bioprocessors to choose between continuous processing retrofits and greenfield single-use facilities, redistributing capital across the value chain.
Growth Catalysts
- Cell therapy manufacturing surge:Autologous and allogeneic cell therapies require flexible, small-scale bioreactor deployments that single-use technology uniquely supports, expanding the addressable equipment base beyond traditional monoclonal antibody production.
- EMA's ATMP GMP framework:The European Medicines Agency's good manufacturing practice guidelines for advanced therapy medicinal products mandate end-to-end cell traceability, driving investment in automated process analytical technology systems across European manufacturing sites.
- Boston-San Francisco corridor concentration:Venture-funded cell therapy developers cluster around these US biotech hubs, creating localized demand spikes for contract manufacturing organization capacity and associated bioprocessing equipment.
Market Restraints
- Resin cost volatility:Protein A and specialty chromatography resins face supply concentration among Japanese and European chemical suppliers, compressing downstream margins when raw material prices spike.
- Stainless steel asset stranding:Large-scale stainless steel bioreactor installations face utilization risk as product portfolios shift toward personalized cell therapies requiring smaller, flexible batches.
- Cross-contamination liability:Multi-product facilities face heightened regulatory scrutiny under FDA current good manufacturing practice enforcement, extending validation timelines and insurance costs.
Strategic Opportunities
- India biopharma manufacturing expansion:The country's production-linked incentive scheme for pharmaceuticals attracts greenfield bioprocessing investments, creating demand for mid-scale single-use systems serving export markets.
- Continuous processing convergence:Integration of perfusion cell culture with continuous chromatography enables real-time quality assurance, compressing facility footprints and operational expenditure for new entrants.
- Modular facility construction:Pre-fabricated cleanroom modules reduce facility build-out time from years to months, enabling faster market entry for contract manufacturing organizations serving emerging biotechs.
Industry Challenges
- Process analytical technology skill scarcity:Bioprocessors struggle to hire engineers capable of integrating spectroscopic sensors with statistical process control software, slowing continuous processing adoption.
- Legacy system integration friction:Brownfield sites face data architecture incompatibility when connecting new single-use sensors to existing distributed control systems, requiring costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Large and Small-Scale Bioprocessing Market |
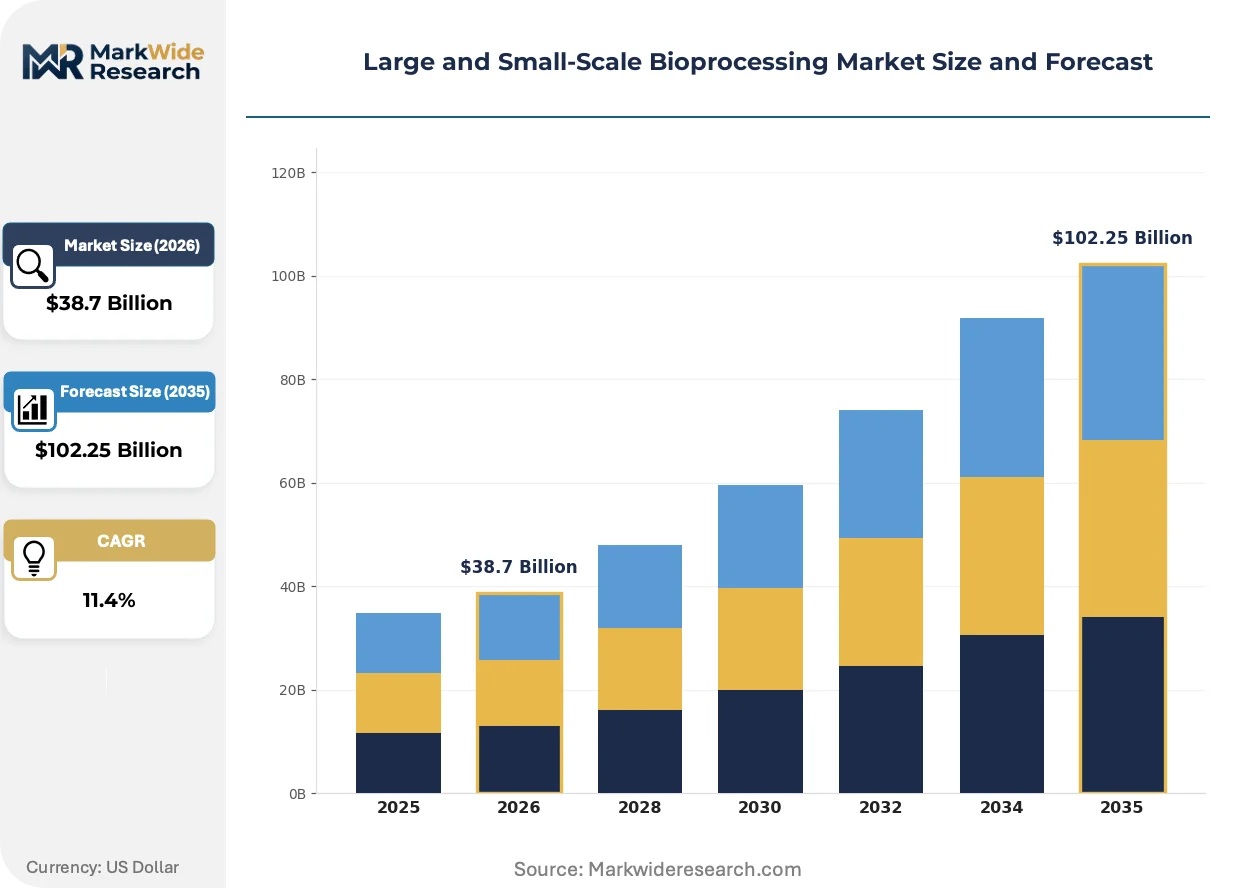
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $102.25 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bioreactors, Chromatography Systems, Filtration Units, Fermentation Systems End User: Pharmaceutical Companies, Biotechnology Firms, Research Institutions, Contract Manufacturers Technology: Single-Use Technology, Continuous Processing, Parallel Processing, Media Preparation Application: Monoclonal Antibodies, Vaccines, Cell Therapy, Enzyme Production |
| Companies Covered | Thermo Fisher Scientific, Lonza, Sartorius AG, Merck KGaA, Danaher (Cytiva), Avantor, Corning, Eppendorf AG, Getinge AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Large and Small-Scale Bioprocessing Market Evolving Landscape
Bioprocessing technology is pivoting from batch efficiency toward real-time quality assurance, compressing the gap between upstream production and downstream release. Equipment vendors and facility operators are reconfiguring around continuous flow architectures.
Single-use perfusion bioreactors equipped with integrated cell retention devices enable weeks-long culture durations without contamination risk. Cell therapy developers and viral vector manufacturers are adopting these systems at pilot scale before committing to commercial capacity. The technology is rendering obsolete the traditional fed-batch paradigm that required larger vessel volumes and longer facility occupancy for equivalent output.
The FDA's quality by design framework now requires predefined design spaces and control strategies for commercial biologics licensure. This regulatory architecture forces manufacturers to invest in multivariate data analysis platforms and automated feedback control loops. Mammalian cell culture operations face the steepest compliance burden, with monoclonal antibody producers leading the adoption of real-time release testing methodologies.
Biopharma procurement departments are unbundling equipment purchases from service contracts, negotiating separate agreements for installation qualification, operational qualification, and ongoing maintenance. This purchasing pattern disrupts the traditional bundled pricing model that sustained original equipment manufacturer margins. The shift is most pronounced among mid-cap biotechs in the United States, where capital constraints favor operational expenditure structures over upfront capital deployment.
Large and Small-Scale Bioprocessing Market Segmentation
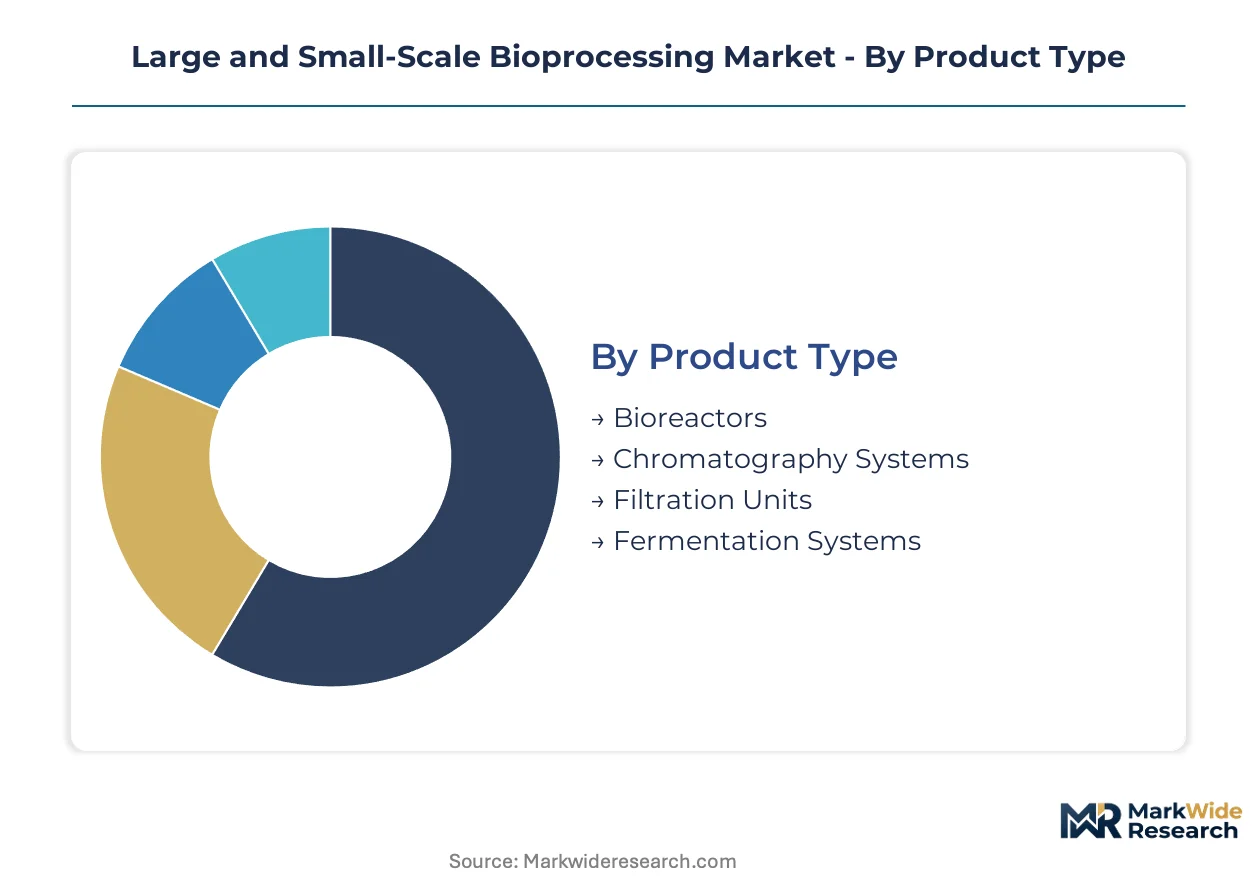
Bioprocessing equipment segments exhibit divergent replacement cycles, with single-use consumables turning over in months while stainless steel infrastructure depreciates over decades. Understanding these velocity differences shapes capital allocation and supplier relationship strategies across the value chain.
Product Type:
Bioreactors command the longest procurement cycles measured in years, while filtration consumables rotate fastest based on batch throughput.
- Bioreactors:Stainless steel and single-use vessels ranging from bench-top to production scale, with automated process analytical technology integration now standard for commercial licensure. Pharmaceutical companies in the United States concentrate demand around 2,000-liter single-use systems for flexible multi-product manufacturing, driven by FDA quality by design mandates requiring validated control strategies.
- Chromatography Systems:Purification platforms utilizing protein A and specialty resins for downstream separation, with resin costs representing the dominant operational expenditure component. Biotechnology firms face margin compression when Japanese and European chemical suppliers constrain resin availability, forcing inventory buffer strategies.
- Filtration Units:Tangential flow and depth filtration systems for cell retention and sterile processing, with membrane cartridges replaced per batch in single-use configurations.
- Fermentation Systems:Microbial culture vessels for enzyme and vaccine production, with longer validation timelines than mammalian cell culture equipment.
Bioreactors anchor the volume base while filtration units gain share at the steepest rate.
End User:
Capital deployment intensity varies sharply, with contract manufacturers spreading equipment utilization across client portfolios while research institutions prioritize flexibility over throughput.
- Pharmaceutical Companies:Large-scale manufacturers operating integrated facilities with dedicated stainless steel trains for blockbuster monoclonal antibodies, now retrofitting with continuous processing to compress batch timelines. These firms concentrate investment in the Boston-San Francisco corridor, where FDA process analytical technology enforcement is most stringent.
- Biotechnology Firms:Venture-funded developers requiring pilot-scale single-use flexibility for pipeline candidates, with equipment decisions driven by platform standardization across clinical phases. Cell therapy specialists in these firms demand small-scale bioreactor deployments that single-use technology uniquely supports.
- Research Institutions:Academic and government laboratories utilizing bench-top systems for early-stage process development, with procurement constrained by grant funding cycles.
- Contract Manufacturers:CDMOs and CMOs deploying multi-product facilities with rapid changeover capabilities, with utilization rates determining equipment ROI.
Pharmaceutical companies dominate capital deployment while contract manufacturers expand capacity most aggressively.
Technology:
Adoption maturity separates established batch paradigms from emerging continuous architectures, with implementation risk concentrated in integration complexity.
- Single-Use Technology:Disposable bioreactors, bags, and connectors eliminating cleaning validation requirements, with cross-contamination risk reduction driving multi-product facility adoption. The EMA's ATMP GMP framework accelerates European deployment for cell therapy manufacturing requiring closed system processing.
- Continuous Processing:Perfusion cell culture integrated with continuous chromatography enabling real-time quality assurance and compressed facility footprints. Bioprocessors face skill scarcity in integrating spectroscopic sensors with statistical process control software, slowing adoption despite FDA encouragement.
- Parallel Processing:Multiple small-scale units operating simultaneously for high-throughput screening and process optimization.
- Media Preparation:Automated buffer and cell culture media formulation systems reducing manual intervention and batch variability.
Single-use technology sustains the installed base while continuous processing climbs the fastest despite integration friction.
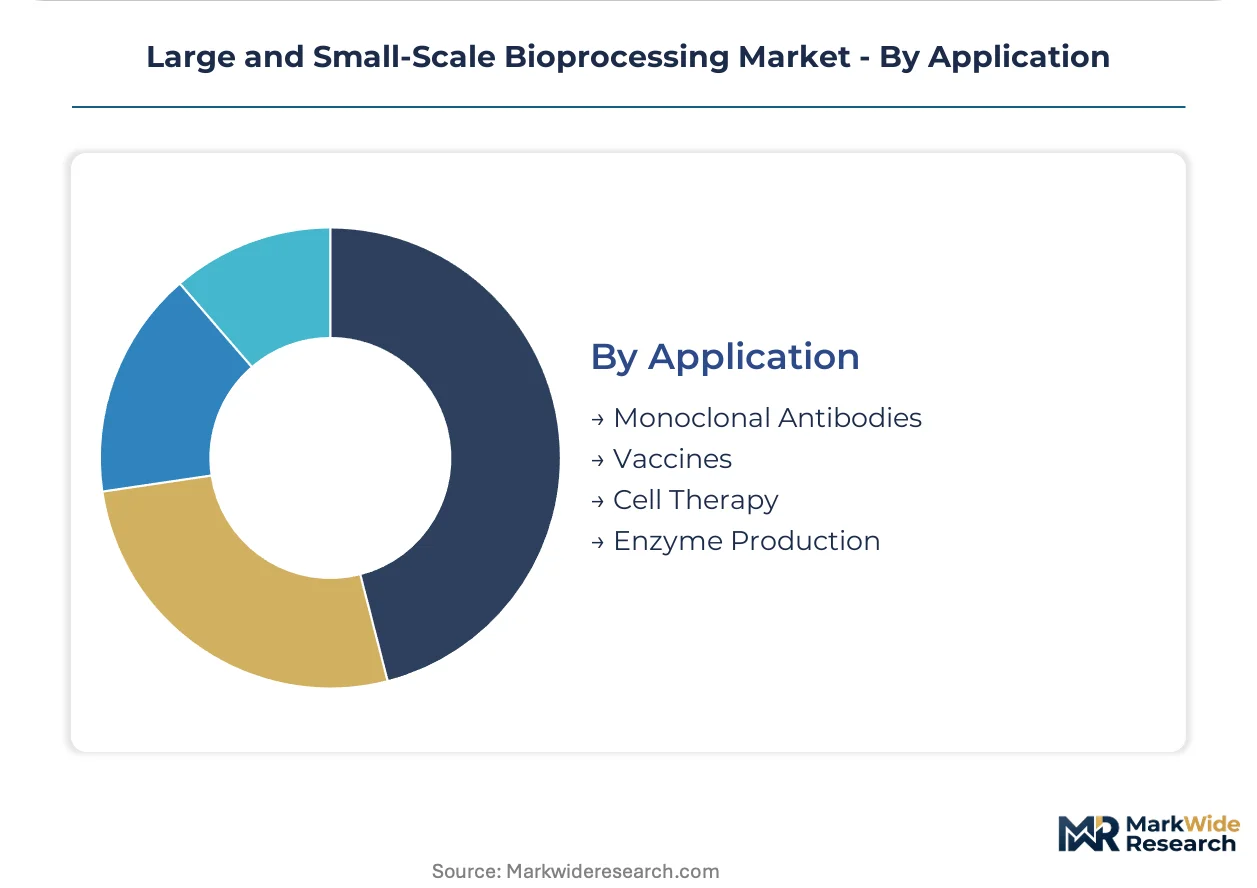
Application:
Regulatory pathway complexity and batch size requirements create divergent equipment specifications across therapeutic categories.
- Monoclonal Antibodies:Large-scale mammalian cell culture in fed-batch or perfusion mode, with protein A chromatography dominating downstream purification. FDA quality by design frameworks impose the steepest compliance burden here, with real-time release testing methodologies now required for commercial licensure.
- Cell Therapy:Autologous and allogeneic products requiring small-scale, closed-system bioprocessing with end-to-end cell traceability mandated by EMA guidelines. Manufacturing networks for these therapies are rewriting how equipment reaches end users through distributed production models.
- Vaccines:Viral vector and recombinant protein production with pandemic preparedness driving surge capacity requirements.
- Enzyme Production:Microbial fermentation systems for industrial and therapeutic enzymes, with longer production campaigns than mammalian cell culture.
Monoclonal antibodies retain the largest equipment footprint while cell therapy applications expand most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold chain infrastructure anchors European biologics distribution, while the I-95 corridor's refrigerated trucking network underwrites North American just-in-time cell therapy logistics.
United States
FDA process analytical technology enforcement compresses batch timelines for monoclonal antibody producers. The production-linked incentive framework for domestic biopharma manufacturing accelerates greenfield facility construction. Boston and San Francisco biotech corridors concentrate venture-funded cell therapy developers demanding flexible single-use capacity.
Germany
Specialized filtration and fluid management technologies anchor the industrial base for downstream purification systems. EMA good manufacturing practice guidelines for advanced therapy medicinal products mandate end-to-end cell traceability across manufacturing sites. Bavaria's pharmaceutical manufacturing cluster sustains demand for automated process analytical technology integration.
Switzerland
Contract manufacturing networks for cell and gene therapies rewrite equipment procurement patterns through integrated service models. Swissmedic's alignment with EMA frameworks ensures regulatory coherence for export-oriented production. Basel's biopharma hub concentrates monoclonal antibody manufacturing requiring large-scale stainless steel and single-use bioreactor deployments.
India
The production-linked incentive scheme for pharmaceuticals attracts greenfield bioprocessing investments serving export markets. CDSCO's harmonization with ICH guidelines streamlines commercial licensure pathways for biosimilars. Maharashtra and Gujarat's pharmaceutical manufacturing corridors expand mid-scale single-use system adoption for contract manufacturing organizations.
Japan
PMDA's quality by design frameworks impose predefined design spaces for commercial biologics licensure. Protein A and specialty chromatography resin supply concentration among domestic chemical suppliers shapes inventory strategies. Kanto region's pharmaceutical cluster leads real-time release testing methodology adoption for mammalian cell culture operations.
Large and Small-Scale Bioprocessing Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in filtration and fluid management. The vendor base stratifies between diversified life science conglomerates and focused equipment fabricators. Three archetypes dominate: integrated service providers bundling equipment with validation services, pure-play bioreactor specialists, and downstream purification technology houses. Competitive moves center on capacity expansion for cell therapy manufacturing and technology licensing for continuous processing architectures.
Among diversified platform providers, Thermo Fisher Scientific and Danaher (Cytiva) occupy positions spanning upstream through downstream workflows. Lonza exemplifies the contract manufacturing organization archetype that influences equipment specifications through aggregated procurement leverage. Sartorius AG represents component specialists whose deep specialization in filtration technologies anchors relationships across both clinical and commercial bioprocessing stages.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Lonza |
| Sartorius AG |
| Merck KGaA |
| Danaher (Cytiva) |
| Avantor |
| Corning |
| Eppendorf AG |
| Getinge AB |
| Others |
Value Network & Pricing Analysis
Basel's pharmaceutical manufacturing cluster concentrates protein A chromatography resin production among a handful of Japanese and European chemical suppliers, translating upstream supply constraints into downstream pricing volatility for bioprocessors. This geographic concentration of critical purification inputs compresses margins for contract manufacturing organizations when raw material availability tightens.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated process analytical technology systems from basic bench-top configurations and refurbished legacy equipment. Price differentiation rests on certification grade and after-sales service bundling, with validated commercial-scale systems commanding substantial premiums over pilot-scale alternatives. Cost compression in the standard tier is intensifying because biopharma procurement departments now unbundle equipment purchases from service contracts. Mid-cap biotechs exhibit the highest price sensitivity due to capital constraints favoring operational expenditure structures, while large pharmaceutical companies prioritize compliance assurance over unit cost.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from equipment vendors help biotechnology firms manage the capital intensity of single-use bioreactor deployments. Manufacturing concentrates in Germany, Switzerland, and the United States for precision filtration and fluid management components, while Japan anchors specialty chromatography resin production. Raw material dependencies include cell culture media formulations, polymer films for single-use bags, and protein A resins. Single-source vulnerability in resin supply creates inventory risk when Japanese chemical suppliers face capacity constraints. Distribution runs through direct OEM sales teams for large pharmaceutical accounts and specialized distributors serving mid-scale contract manufacturing organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bioprocessing equipment markets increasingly monetize through recurring revenue layers, with validation services and consumable resupply contracts expanding faster than hardware sales. This service-attach dynamic rewards vendors that integrate ongoing process support with initial equipment deployment.
For Market Incumbents: Entrench platform dominance by deepening captive supply of chromatography resins and filtration membranes to offset raw material volatility. Incumbents should expand continuous processing technology licensing to defend against emerging pure-play automation specialists. Vertical integration into resin manufacturing reduces exposure to Japanese and European chemical supplier concentration.
For New Entrants and Emerging Players: Build out modular facility construction capabilities targeting contract manufacturing organizations in India's production-linked incentive corridors. The most penetrable segment comprises mid-scale single-use systems for export-oriented biosimilar production. A software-first go-to-market angle emphasizing integrated process analytical technology platforms differentiates against legacy hardware vendors.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors component specialists with deep filtration expertise over diversified platform providers facing margin compression. Long-term viability hinges on recurring revenue intensity from consumables and service contracts rather than transactional equipment sales. The signal to watch is FDA enforcement trajectory on real-time release testing mandates, which would accelerate continuous processing adoption and reshape equipment replacement cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Processing Technology Licensing | Enables real-time quality assurance under FDA process analytical technology mandates. |
| Modular Facility Construction Partnerships | Compresses build-out timelines for contract manufacturing organizations serving emerging biotechs. |
| Chromatography Resin Backward Integration | Reduces exposure to Japanese and European chemical supplier concentration and price volatility. |
| Cell Therapy Manufacturing Capacity Expansion | Captures localized demand spikes around Boston and San Francisco biotech corridors. |
| Process Analytical Technology Platform Integration | Addresses skill scarcity in spectroscopic sensor deployment for continuous bioprocessing. |
Research Methodology
Cross-validation between primary interviews with bioprocessing engineers and secondary validation through FDA filings and EMA submissions anchors the qualitative findings. Stakeholder consultations included bioreactor operations managers, downstream purification specialists, regulatory affairs leads at contract manufacturing organizations, and procurement directors at venture-funded cell therapy developers. Secondary sources encompassed ISO 13485 certification databases, SEC 10-K equipment revenue disclosures, and trade data on chromatography resin imports. Bottom-up and top-down triangulation reconciled facility capacity announcements with end-user equipment procurement patterns.
Calibration against historical replacement cycles for stainless steel versus single-use infrastructure shaped the analytical framework. Segmentation dimensions modeled include product type, technology adoption maturity, end-user capital deployment intensity, and regional regulatory cluster. CAGRs were derived from capacity expansion announcements and vendor order backlog analysis. Industry-specific forecast inputs incorporated EMA ATMP GMP framework implementation timelines and FDA quality by design enforcement patterns across the projection horizon.
The forecast holds incumbent behavior within observed patterns; aggressive moves by pure-play continuous processing automation specialists would shift outcomes. Forecasts reflect assumptions about regulatory enforcement continuity and resin supply stability. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Engineering
3D Bioprinted Human Tissue Market
Biomedical Engineering
Argentina Artificial Organs and Bionic Implants Market
Biomedical Engineering
Global Bionic Ear Market
Biomedical Engineering
Europe Bioresorbable Vascular Scaffold Market
Biomedical Engineering
North America Biosurgery Market
Biomedical Engineering
Bionic Eye Market
Biomedical Engineering
Tissue Engineering Market
Biomedical Engineering
Bioimplants Market
Biomedical Engineering
Artificial Organ Bank Market
Biomedical Engineering
Global Single Use Bioprocessing Probes and Sensors Market
Biomedical Engineering
Bioprosthetics Market
Biomedical Engineering
Non-Surgical Bio-Implants Market
Biomedical Engineering
Global Bovine-Based Collagen for Biomedical Applications Market
Biomedical Engineering
Biological Implants Market
Biomedical Engineering
Self-Inflating Tissue Expander Market
Biomedical Engineering
Tissue Engineered Skin Substitute Market