
 Bioink Market | 2026-2036
Bioink Market Size, Share, and Industry Trends Forecast 2026-2036
Bioink Market Analytics
Multi-source procurement for specialized biomaterials is consolidating as bioprinting platforms mature and quality specifications tighten. Cellink anchors the European supply landscape through integrated hardware-ink workflows. Poietis differentiates with laser-assisted bioprinting expertise and precision tissue manufacturing. Advanced BioMatrix leverages its deep catalog of ECM-derived formulations to sustain pricing power in research-grade segments.
Bioink denotes a formulation of living cells, biomaterials, and signaling molecules engineered for deposition through additive manufacturing platforms, typically exhibiting shear-thinning viscosity between 10 and 1000 Pa·s to preserve cell viability during extrusion. Its primary commercial purpose centers on fabricating tissue constructs for regenerative therapy, disease modeling, and pharmaceutical toxicity screening. Natural bioinks derived from collagen, alginate, and decellularized matrix dominate current volume due to established biocompatibility profiles, while synthetic bioinks command margin premiums for tunable mechanical properties and batch-to-batch consistency. Microextrusion bioprinting occupies the largest technology share by installed base, though inkjet modalities are gaining traction in high-throughput drug discovery applications where droplet precision outweighs construct scale.
The FDA maintains active guidance development for 3D-printed medical products, while the EPA monitors solvent residuals in synthetic hydrogel manufacturing, and ISO 10993 biocompatibility standards govern preclinical validation pathways. These frameworks elevate barriers for unvalidated formulations while creating preferred supplier status for manufacturers with documented quality systems. Stakeholders must monitor regulatory convergence between device and biologic classification frameworks, as jurisdictional ambiguity around living-tissue products threatens to fragment market access requirements across oversight bodies.
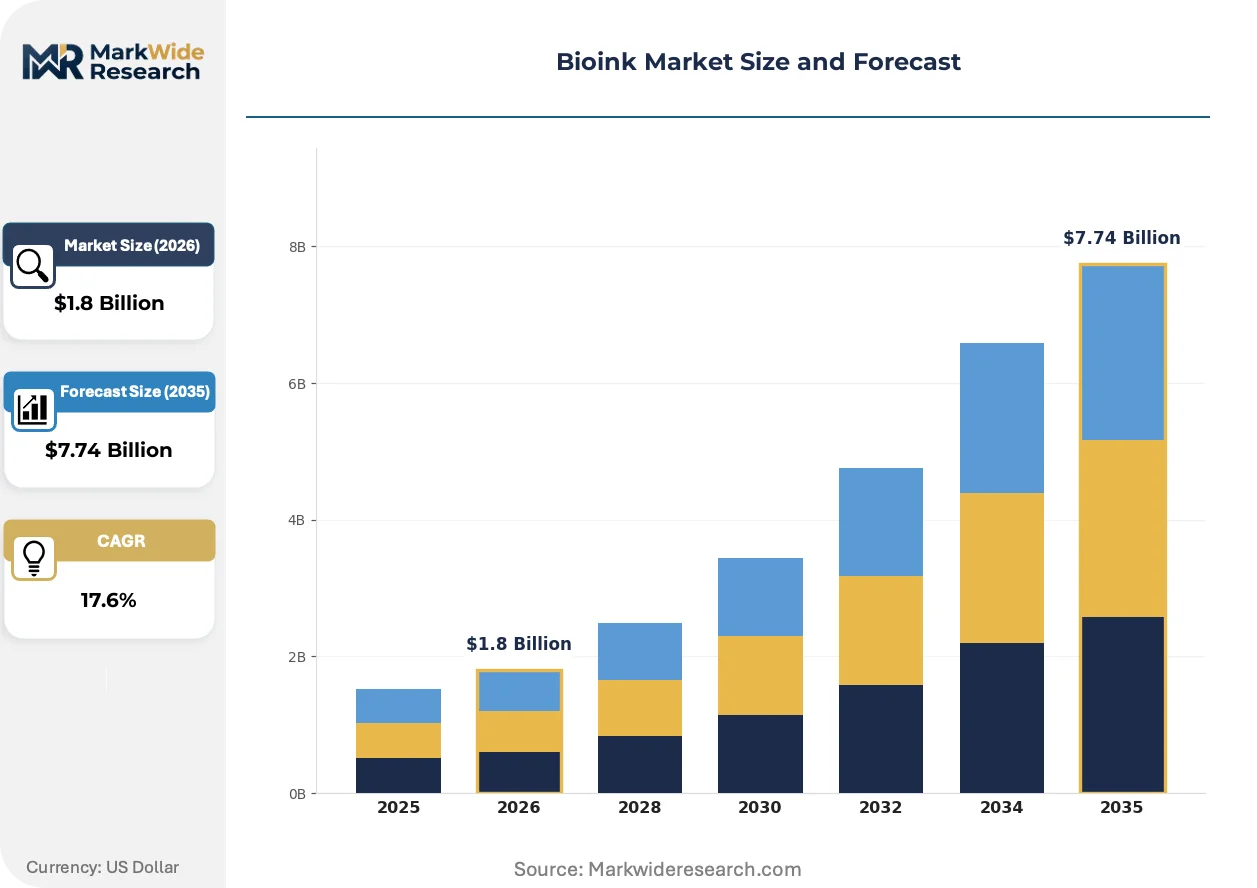
Market Dynamics
Pharmaceutical toxicity screening is displacing academic research as the primary demand driver, with contract research organizations now specifying bioink mechanical properties in procurement tenders rather than accepting catalog formulations.
Growth Catalysts
- NIH regenerative medicine funding:The National Institutes of Health maintains multi-year grant programs for vascularized tissue constructs, channeling resources toward Boston and San Diego academic-industry clusters.
- ISO 10993 biocompatibility standards:Preclinical validation pathways now require documented quality systems, creating preferred supplier status for manufacturers with certified formulations.
- Shear-thinning hydrogel advances:Alginate-collagen composite bioinks with tunable viscosity profiles enable microextrusion platforms to deposit thicker tissue layers without compromising cell viability.
Market Restraints
- Decellularized matrix supply concentration:Porcine and bovine tissue sourcing clusters in Midwestern US processing facilities, exposing buyers to livestock disease outbreak disruptions.
- FDA jurisdictional ambiguity:Classification friction between device and biologic frameworks for living-tissue products fragments market access requirements across oversight bodies.
- Synthetic polymer cost volatility:Polyethylene glycol and Pluronic raw material prices fluctuate with petrochemical feedstock cycles, compressing margins for formulation specialists.
Strategic Opportunities
- India contract manufacturing:CDSCO regulatory harmonization efforts and lower-cost GMP infrastructure attract bioprinting platform developers seeking secondary production sites.
- Laser-assisted bioprinting convergence:Integration of photonic positioning systems with microfluidic cell handling enables precision deposition for corneal and neural tissue applications.
- Direct-to-clinic distribution:Hospital-based bioprinting centers in Germany and Switzerland bypass traditional distributor markups for patient-specific bone graft constructs.
Industry Challenges
- Biofabrication technician scarcity:Cross-disciplinary training combining cell biology, materials science, and additive manufacturing remains underdeveloped in vocational programs.
- Batch-to-batch certification timelines:Each new bioink lot requires ISO 10993 cytotoxicity and sensitization testing, extending release cycles for research-grade formulations.
- IP fragmentation across ECM derivatives:Patent thickets surrounding decellularization protocols and crosslinking chemistries complicate freedom-to-operate analyses for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bioink Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $7.74 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Bioinks, Synthetic Bioinks, Hybrid Bioinks, Hydrogel Bioinks Application: Tissue Engineering, Drug Delivery, Regenerative Medicine, 3D Bioprinting End User: Research Institutions, Pharmaceutical Companies, Hospitals, Academic Labs Technology: Inkjet Bioprinting, Laser Bioprinting, Microextrusion Bioprinting, Stereolithography |
| Companies Covered | EnvisionTEC, Poietis, Allevi, Voltz Biotechnology, RegenHU, Bioink Solutions, 3D Bioprinting Solutions, Advanced BioMatrix, Cellink, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bioink Market Evolving Landscape
Bioprinting workflows are converging with automated cell culture systems, eliminating manual handling steps that previously introduced contamination risk and batch variability. This integration is compressing development timelines for tissue constructs intended for regulatory submission.
Organ-on-a-chip platforms are expanding into high-throughput pharmaceutical screening workflows. Contract research organizations at Merck KGaA and Roche now specify microfluidic-compatible bioink viscosities in vendor qualification documents. The technology is expanding into disease modeling applications previously dominated by animal studies, enabling human-relevant mechanistic insights for oncology and fibrosis pathways.
EMA's evolving guidance on 3D-printed medical products is mandating design history files for living-tissue constructs. Manufacturers must document cell sourcing, expansion protocols, and final formulation stability across shelf-life studies. German and Swiss notified bodies are developing specialized review pathways for bioprinted cartilage implants, accelerating time-to-certification for compliant submissions.
Research consortia are consolidating bioink procurement through shared biorepositories. The Advanced Regenerative Manufacturing Institute in New Hampshire pools academic and industrial buyers to negotiate volume pricing for collagen and alginate base materials. This collective purchasing is displacing individual laboratory catalog orders and forcing suppliers to offer tiered pricing structures based on consortium membership tiers rather than institutional prestige.
Bioink Market Segmentation
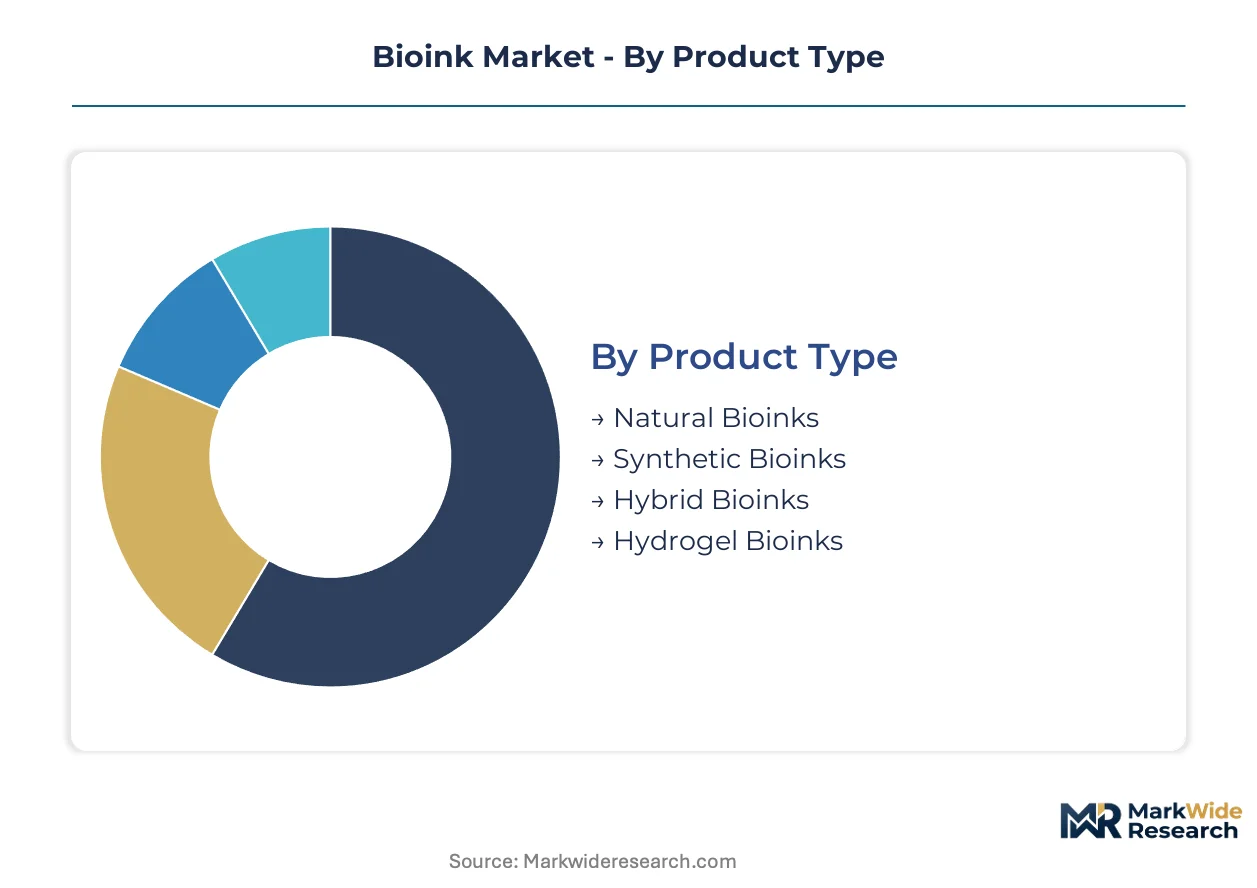
Segmentation in the bioink market tracks how formulation chemistry, deposition physics, and end-use requirements create distinct procurement specifications. Buyers now demand mechanical property documentation rather than accepting generic catalog formulations, fragmenting what once operated as a monolithic research supply category.
Product Type:
Formulation chemistry determines shear-thinning viscosity profiles, crosslinking kinetics, and batch-to-batch consistency specifications.
- Natural Bioinks:Derived from collagen, alginate, and decellularized extracellular matrix, these formulations dominate current procurement volumes through established ISO 10993 biocompatibility documentation. Demand concentrates in NIH-funded academic-industry clusters in Boston and San Diego, where vascularized tissue construct grants require proven cell viability profiles.
- Synthetic Bioinks:Polyethylene glycol and Pluronic-based hydrogels command margin premiums for tunable mechanical properties and precise molecular weight distribution. Pharmaceutical companies at Merck KGaA and Roche now specify synthetic formulations in high-throughput toxicity screening tenders where batch consistency outweighs biomimetic complexity.
- Hybrid Bioinks:Composite systems combining natural ECM components with synthetic polymer backbones balance biocompatibility with mechanical tunability for load-bearing tissue applications.
- Hydrogel Bioinks:Water-swollen polymer networks with tunable porosity support nutrient diffusion in thick tissue constructs for regenerative therapy pipelines.
Mature deployment sits with Natural Bioinks. Newer deployment is concentrated in Synthetic Bioinks.
Application:
End-use purpose dictates regulatory pathway complexity and validation timeline requirements.
- Tissue Engineering:Scaffold fabrication for organ replacement and repair drives demand for vascularization-compatible formulations with interconnected pore architectures. German and Swiss notified bodies are developing specialized review pathways for bioprinted cartilage implants, accelerating certification timelines for compliant submissions.
- Drug Delivery:Encapsulation systems for controlled release require tunable degradation kinetics matched to therapeutic windows. Contract research organizations now specify bioink mechanical properties in procurement tenders rather than accepting catalog formulations.
- Regenerative Medicine:Cell-laden constructs for direct therapeutic implantation face FDA jurisdictional ambiguity between device and biologic classification frameworks.
- 3D Bioprinting:Platform-specific optimization for deposition hardware creates formulation-service bundling opportunities.
Volume leadership belongs to Tissue Engineering. Steepest expansion trajectory is visible in Drug Delivery.
End User:
Procurement scale and specification authority vary dramatically across buyer categories.
- Research Institutions:Grant-dependent purchasing through shared biorepositories like the Advanced Regenerative Manufacturing Institute pools demand for volume pricing on collagen and alginate base materials. Collective purchasing is displacing individual laboratory catalog orders.
- Pharmaceutical Companies:Preclinical drug screening workflows at Roche and Merck KGaA now displace academic research as the primary demand driver, with CROs specifying microfluidic-compatible bioink viscosities in vendor qualification documents.
- Hospitals:German and Swiss hospital-based bioprinting centers bypass traditional distributor markups for patient-specific bone graft constructs.
- Academic Labs:Individual principal investigator purchasing faces consolidation pressure from consortium procurement structures.
Specification authority is shifting from Academic Labs to Pharmaceutical Companies.
Technology:
Deposition physics determines viable viscosity ranges, cell survival rates, and construct resolution limits.
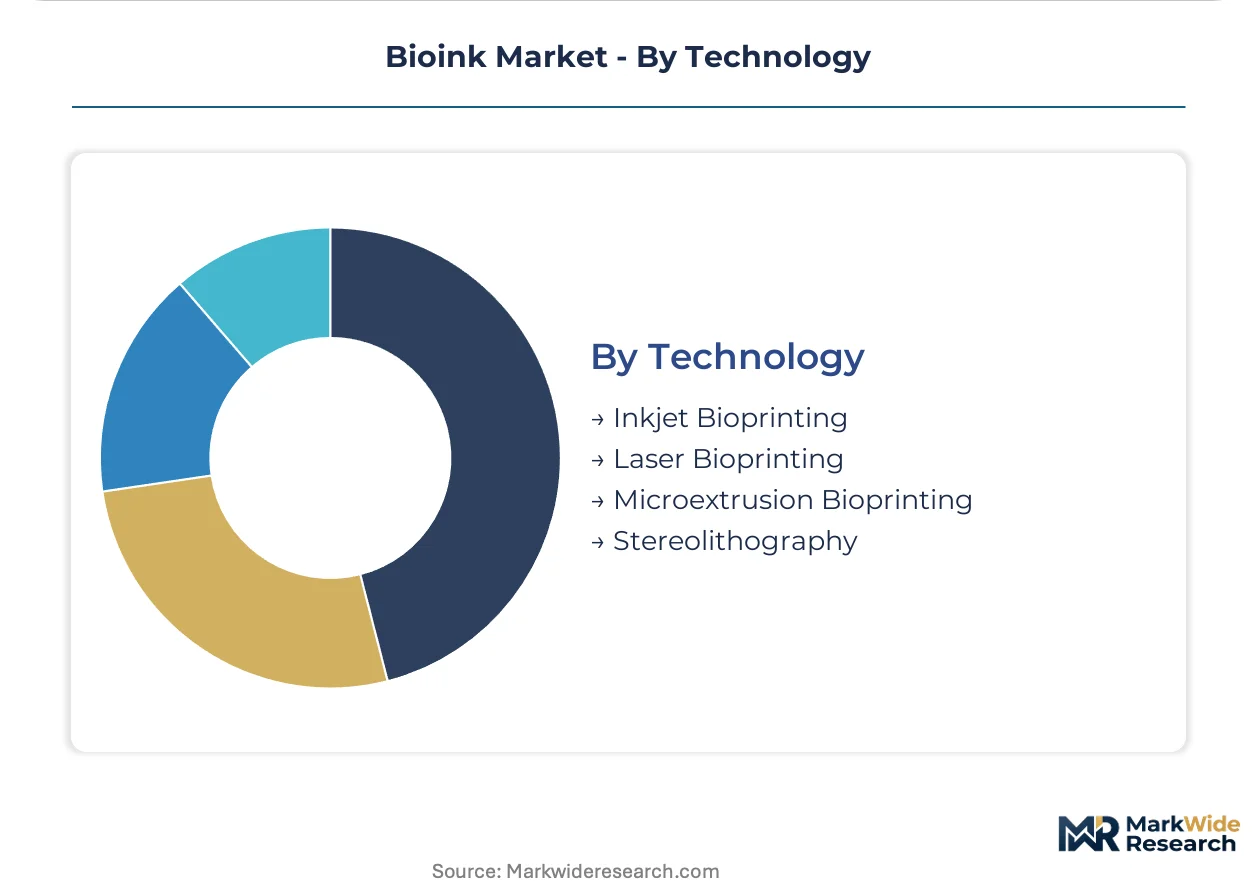
- Microextrusion Bioprinting:Pneumatic or mechanical screw-driven deposition occupies the largest installed base, with alginate-collagen composite bioinks enabling thicker tissue layers through tunable shear-thinning profiles between 10 and 1000 Pa·s.
- Laser Bioprinting:Cell-impregnated ribbon transfer via focused laser pulses enables precision deposition for corneal and neural tissue applications where droplet positioning accuracy outweighs construct scale. Poietis anchors European supply through laser-assisted expertise.
- Inkjet Bioprinting:Thermal or piezoelectric droplet ejection gains traction in high-throughput pharmaceutical screening where speed dominates volumetric throughput.
- Stereolithography:Photocrosslinking through patterned light exposure enables complex vascular channel architectures with sub-100-micron resolution.
Installed base dominance belongs to Microextrusion Bioprinting. Capability differentiation is concentrating in Laser Bioprinting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Porcine and bovine tissue sourcing clusters in Midwestern US processing facilities anchor raw-material availability for decellularized matrix formulations. NIH grant programs channel resources toward academic-industry partnerships in Boston and San Diego. German and Swiss notified bodies pioneer specialized review pathways for bioprinted implants.
United States
NIH regenerative medicine funding drives procurement for vascularized tissue constructs. FDA guidance development for 3D-printed medical products accelerates compliance investments among formulation specialists. Boston and San Diego academic-industry clusters concentrate grant-funded research and contract manufacturing capacity.
Germany
Hospital-based bioprinting centers bypass traditional distributor markups for patient-specific bone graft constructs. EMA evolving guidance on 3D-printed medical products mandates design history files for living-tissue constructs. Notified bodies in Baden-Württemberg and Bavaria develop specialized review pathways for bioprinted cartilage implants.
Switzerland
Direct-to-clinic distribution models concentrate in German-speaking cantons for orthopedic applications. Swissmedic oversight aligns with EMA frameworks while maintaining national sovereignty on biologic-device classification. Zurich and Basel clusters host precision manufacturing for laser-assisted bioprinting platforms.
India
CDSCO regulatory harmonization efforts attract bioprinting platform developers seeking secondary production sites. Lower-cost GMP infrastructure supports contract manufacturing expansion for research-grade formulations. Hyderabad and Bangalore biotech corridors consolidate cell culture and biomaterial processing capabilities.
United Kingdom
Research consortia pool bioink procurement through shared biorepositories modeled on ARMI structures. MHRA post-Brexit regulatory autonomy creates parallel compliance pathways for synthetic hydrogel formulations. London-Oxford-Cambridge triangle concentrates academic spinouts and venture-funded bioprinting ventures.
Bioink Market Competitive Landscape
Strategic partnerships dominate the current landscape as hardware-ink workflow integration becomes the primary differentiation vector. The vendor base organizes around three tiers: integrated platform providers, specialized formulation houses, and regional contract manufacturers. Two strategic archetypes predominate: companies bundling bioprinters with proprietary bioink subscriptions, and pure-play suppliers monetizing catalog depth through tiered certification pricing. M&A activity concentrates on decellularized matrix sourcing capabilities, while capacity expansion targets GMP-grade synthetic polymer production.
Within the integrated platform tier, Cellink anchors European supply through hardware-ink bundling, while Poietis exemplifies laser-assisted specialization for precision tissue manufacturing. Advanced BioMatrix occupies the formulation-depth archetype, leveraging ECM-derived catalog breadth to sustain pricing power in research-grade segments. These three represent distinct competitive vectors: workflow integration, photonic positioning capability, and biomaterial portfolio scale.
| Leading Market Players |
|---|
| EnvisionTEC |
| Poietis |
| Allevi |
| Voltz Biotechnology |
| RegenHU |
| Bioink Solutions |
| 3D Bioprinting Solutions |
| Advanced BioMatrix |
| Cellink |
| Others |
Value Network & Pricing Analysis
Automated cell culture integration is compressing batch variability and reshaping cost economics while concentrating procurement power among consortium buyers who negotiate volume terms. This technological shift simultaneously elevates quality specifications and fragments supplier pricing power across research-grade and GMP-tier formulations.
Pricing Analysis
Hardware-ink bundling dominates the commercial structure, with integrated platform providers wrapping bioink subscriptions into multi-year equipment contracts while pure-play suppliers monetize unbundled formulations through tiered certification pricing. Price differentiation hinges on ISO 10993 documentation depth and GMP compliance grade, with pharmaceutical procurement teams at Merck KGaA and Roche commanding steeper discounts through specification authority than grant-dependent academic labs. Cost compression in synthetic polymer tiers is intensifying because petrochemical feedstock volatility feeds directly into polyethylene glycol and Pluronic raw material costs. Academic labs exhibit highest price sensitivity due to fixed grant allocations, while hospital-based bioprinting centers in Germany and Switzerland absorb premium pricing for patient-specific constructs.
Supply Chain Analysis
Single-source vulnerability sits with Midwestern US processing facilities that anchor porcine and bovine tissue sourcing for decellularized matrix formulations. Raw material procurement draws from collagen extraction clusters in the United States, alginate harvesting operations in Norway and Chile, and synthetic polymer production concentrated in Germany and China. Supply chain risk centers on livestock disease outbreak disruptions that would cascade through ECM-dependent formulation pipelines. Distribution runs through specialized life-science distributors for research-grade tiers, while GMP-compliant formulations bypass intermediaries via direct-to-clinic channels in German-speaking European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bioink market is a vertical-integration race where control over decellularized matrix sourcing and GMP-grade synthetic polymer production determines margin sustainability. Players are pursuing backward integration into raw material processing to escape feedstock volatility and secure batch-to-batch consistency documentation.
For Market Incumbents: Acquire decellularized matrix processing capabilities in the Midwestern United States to secure porcine and bovine tissue supply chains against livestock disease disruptions. Expand captive GMP-grade synthetic polymer production in Germany or Switzerland to capture margin premiums from pharmaceutical toxicity screening demand while insulating formulations from petrochemical price cycles. For New Entrants and Emerging Players: Capture contract manufacturing opportunities in India's Hyderabad and Bangalore biotech corridors where CDSCO regulatory harmonization and lower-cost GMP infrastructure attract platform developers seeking secondary production sites. Target laser-assisted bioprinting precision applications for corneal and neural tissue where Poietis holds limited European anchorage and technical differentiation barriers remain surmountable through photonic positioning expertise. For Investors and Strategic Acquirers: Exit pathways concentrate in platform-ink bundling acquisitions by diversified life-science instrumentation conglomerates seeking bioprinting workflow integration. Long-term viability favors targets with documented ISO 10993 quality systems and established pharmaceutical CRO procurement relationships over pure hardware plays. Watch FDA-EMA regulatory convergence on living-tissue product classification as the critical inflection signal determining market access fragmentation versus harmonization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Raw Material Processing | Captive decellularized matrix supply secures batch consistency for NIH-funded vascularized tissue construct programs. |
| GMP Certification Investment | EMA-mandated design history files for living-tissue constructs create preferred supplier status with German notified bodies. |
| Consortium Procurement Participation | ARMI membership unlocks volume pricing on collagen and alginate base materials displacing individual catalog orders. |
| Laser-Assisted Platform Development | Photonic positioning convergence with microfluidic cell handling enables precision deposition for corneal applications. |
| Direct-to-Clinic Distribution Launch | Hospital-based bioprinting centers in Switzerland bypass distributor markups for patient-specific bone graft constructs. |
Research Methodology
Independent corroboration across bioink formulation specialists, bioprinting platform engineers, and pharmaceutical CRO procurement directors underwrites the qualitative findings. Primary interviews with regulatory affairs leads at German notified bodies, NIH grant program administrators, and hospital-based bioprinting center operators supplied forward-looking demand signals. Secondary validation drew from FDA guidance documents on 3D-printed medical products, EMA design history file requirements, ISO 10993 biocompatibility standards, and CDSCO regulatory harmonization circulars. Bottom-up segmentation modeling triangulated against top-down market sizing from trade flow analysis and equipment installation databases.
Historical reference periods anchored the projection horizon through documented NIH funding trajectories, pharmaceutical preclinical screening workflow adoption curves, and bioprinting platform installed base expansion patterns. Segmentation dimensions modeled include formulation chemistry, deposition technology, end-use application, and buyer procurement authority tier. CAGRs were derived from regression analysis against NIH appropriation cycles, pharmaceutical R&D outsourcing trends, and GMP infrastructure capacity buildout rates. Forecast inputs incorporated shear-thinning hydrogel viscosity optimization timelines and laser-assisted bioprinting precision capability maturation curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA jurisdictional classification decisions, livestock disease outbreak frequencies, and petrochemical feedstock price cycles. Forecasts reflect assumptions regarding continued NIH regenerative medicine funding, EMA-EMA regulatory pathway stability, and synthetic polymer manufacturing scale-up feasibility. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Engineering
North America Biosurgery Market
Biomedical Engineering
Biological Implants Market
Biomedical Engineering
Bioactive Bone Grafts Market
Biomedical Engineering
Global Bionics Market
Biomedical Engineering
3D Bioprinting Market
Biomedical Engineering
3D Bioprinted Organ Transplants Market
Biomedical Engineering
Topical Bioadhesives Market
Biomedical Engineering
Tissue Engineered Skin Substitute Market
Biomedical Engineering
Artificial Organ Bank Market
Biomedical Engineering
Bioresorbable Scaffolds Market
Biomedical Engineering
Non-Surgical Bio-Implants Market
Biomedical Engineering
Global Biomedical Tester Market
Biomedical Engineering
Argentina Artificial Organs and Bionic Implants Market
Biomedical Engineering
Global Bionic Ear Market
Biomedical Engineering
Medical Biomimetics Market
Biomedical Engineering
Bioactive Coating Devices Market