
 Non-Surgical Bio-Implants Market | 2026-2036
Non-Surgical Bio-Implants Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Surgical Bio-Implants Market Analytics
Aftermarket service revenue is fragmenting across training, certification, and patient-monitoring platforms as manufacturers seek recurring income beyond implant sales. Johnson & Johnson leverages its Ethicon infrastructure to bundle bio-implant products with surgeon education programs. Anika Therapeutics anchors its position in hyaluronic acid orthobiologics through dedicated R&D spending on single-injection viscosupplementation. Fidia Farmaceutici competes by extending its hyaluronan manufacturing expertise from ophthalmology into aesthetic and orthopedic indications.
Non-surgical bio-implants comprise biocompatible materials—collagen, hyaluronic acid, polylactic acid, and calcium hydroxylapatite—formulated as injectable or implantable constructs that integrate with host tissue without incisional procedures, typically degrading over 6–24 months while stimulating endogenous matrix production. Their primary purpose spans facial volume restoration, joint lubrication, dermal wound bed preparation, and targeted drug depot formation. Hydrogels and scaffolds lead product-type revenue due to established reimbursement in osteoarthritis and chronic wound protocols, while drug delivery systems represent the fastest-expanding category as manufacturers load bio-implants with antibiotics, growth factors, and corticosteroids for localized release kinetics. Tissue engineering applications dominate clinical volume, though soft tissue repair is gaining share as microfabrication enables precise cell-seeded constructs for tendon and ligament augmentation.
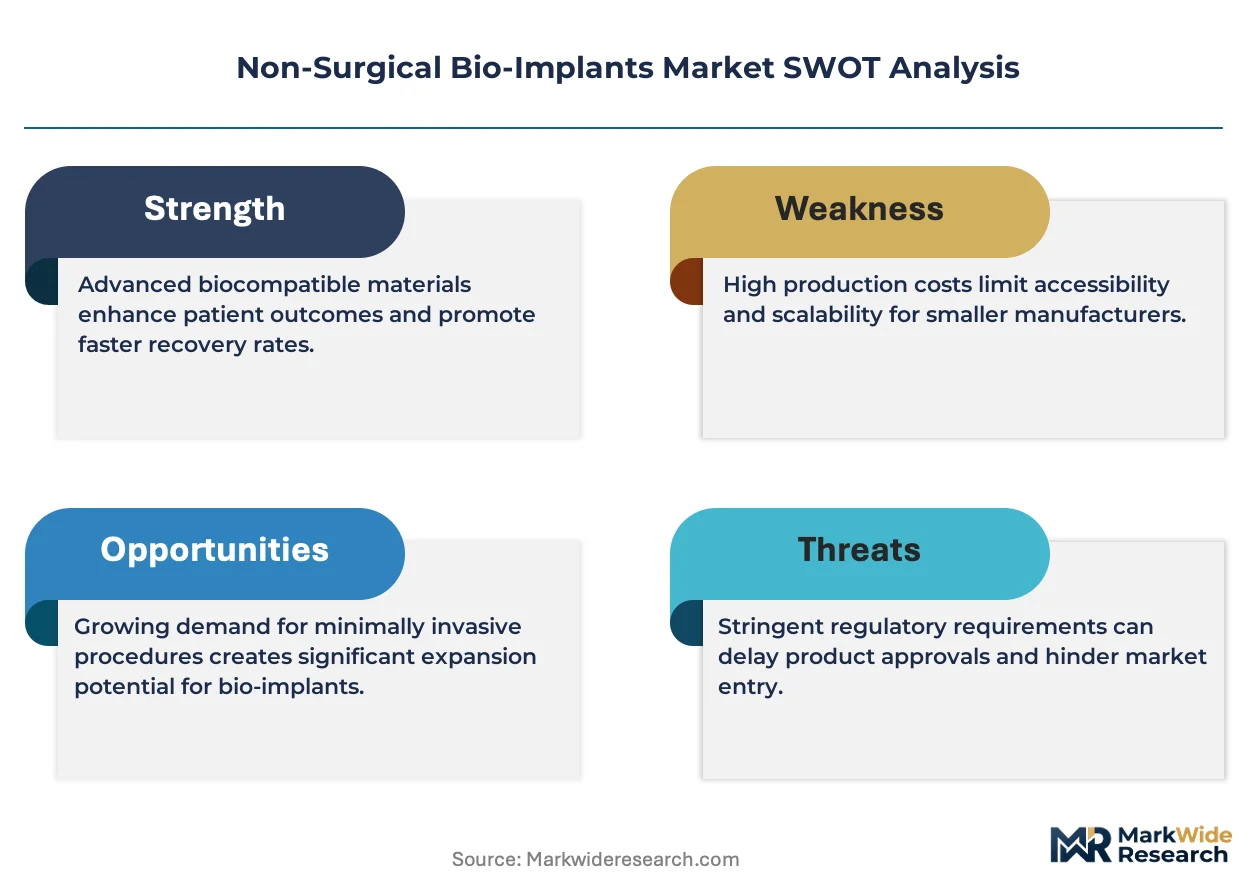
The FDA's dermal filler safety guidance and the EU Medical Device Regulation (MDR) impose biocompatibility testing, post-market clinical follow-up, and unique device identification requirements that elevate barriers for new entrants while consolidating incumbent positions. China's NMPA implements domestic clinical trial mandates for imported bio-implants, slowing foreign market access but accelerating local manufacturing partnerships. Stakeholders must monitor evolving biodegradability standards and regenerative medicine classification debates that could resegment product pathways across jurisdictions.
Market Dynamics
The FDA's updated dermal filler safety guidance is compressing approval timelines and forcing manufacturers to restructure post-market surveillance systems around real-world evidence collection.
Growth Catalysts
- Outpatient procedural migration:Hospital outpatient departments in the United States and Brazil are absorbing volume once reserved for surgical suites as hyaluronic acid fillers demonstrate equivalent aesthetic outcomes to rhinoplasty.
- MDR compliance consolidation:The EU Medical Device Regulation's biocompatibility testing requirements are accelerating incumbent market share capture by firms with established quality management systems.
- Orthobiologic protocol expansion:Single-injection viscosupplementation is displacing multi-injection regimens in osteoarthritis management across German and Italian reimbursement frameworks.
Market Restraints
- Input concentration risk:Pharmaceutical-grade hyaluronic acid supply clusters with a limited set of fermentation-based manufacturers in China and Japan, exposing formulators to batch variability and import licensing delays.
- Domestic trial mandates:China's NMPA requires local clinical data for imported bio-implants, extending time-to-market by 18-36 months for foreign entrants lacking Chinese manufacturing partnerships.
- Substitute procedure revival:Minimally invasive thread lifting and energy-based skin tightening are recapturing facial rejuvenation patients seeking longer-lasting results than 6-12 month filler degradation cycles.
Strategic Opportunities
- Drug-device convergence:Antibiotic-loaded hydrogels for chronic wound beds represent an underdeveloped category where localized release kinetics can command premium reimbursement.
- Tissue engineering pivot:Microfabricated cell-seeded scaffolds for tendon augmentation are migrating from academic research into commercial orthobiologics through partnerships with sports medicine networks.
- Training platform monetization:Surgeon certification programs and patient-monitoring apps offer recurring revenue streams that decouple manufacturer economics from unit sales volatility.
Industry Challenges
- Biodegradability standard fragmentation:ISO working groups, FDA guidance documents, and EU harmonized standards currently specify incompatible in-vitro degradation testing protocols, forcing redundant qualification studies.
- Regenerative medicine classification uncertainty:Jurisdictional debates over whether cell-laden constructs qualify as medical devices, biologics, or combination products are delaying market authorization timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Surgical Bio-Implants Market |
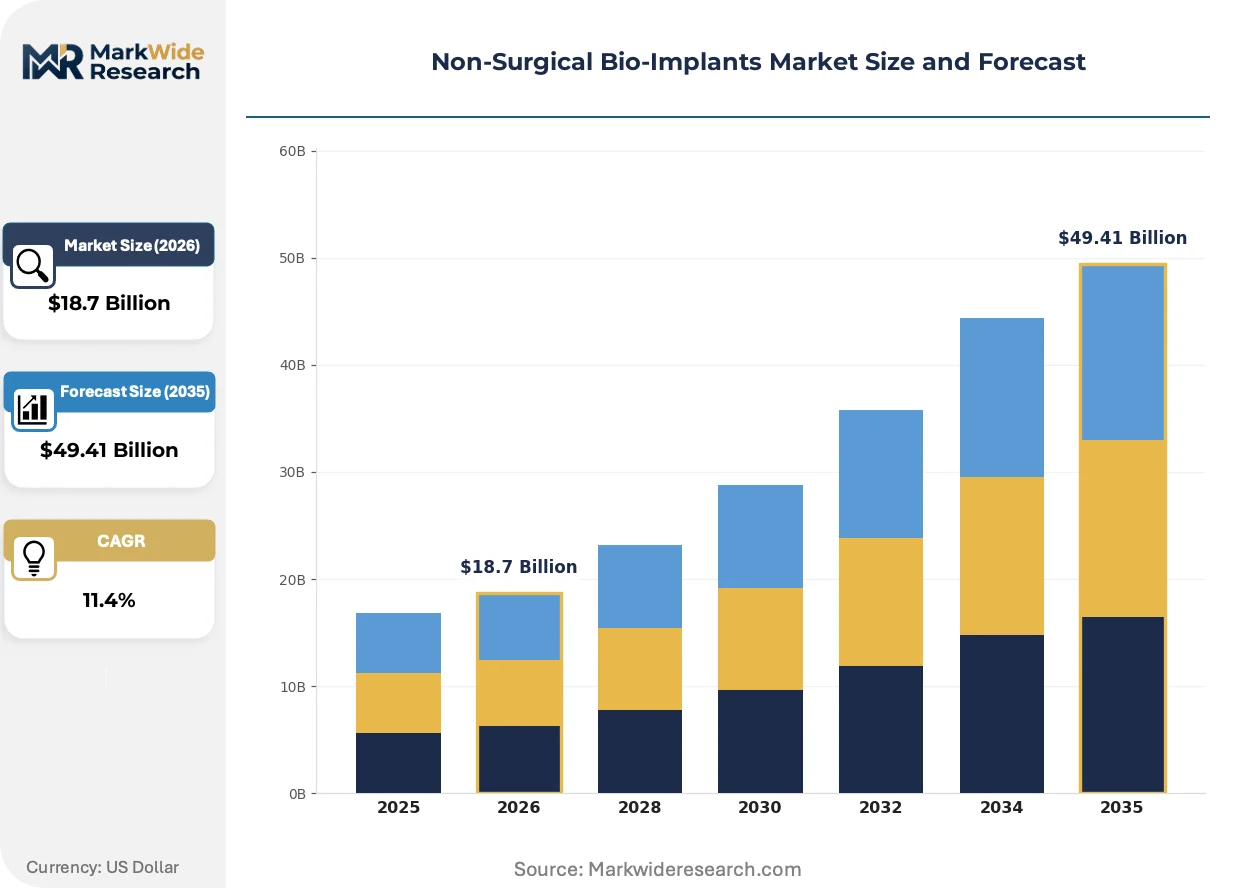
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Scaffolds, Hydrogels, Coatings, Drug Delivery Systems Application: Tissue Engineering, Drug Release, Wound Healing, Soft Tissue Repair Technology: 3D Bioprinting, Electrodeposition, Microfabrication, Additive Manufacturing End User: Hospital, Research Institutes, Surgical Centers, Home Care |
| Companies Covered | Albiorex International, FibroGen, Kythera Pharmaceuticals, Moma Therapeutics, Novatex Bioengineering SA, Anika Therapeutics, Johnson & Johnson, Fidia Farmaceutici, LCA Pharma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Surgical Bio-Implants Market Evolving Landscape
Computational modeling and digital patient profiling are compressing the gap between injectable formulation design and individualized treatment outcomes.
Cross-linked hyaluronic acid gels with tunable rheological properties are virtualizing the functional role of surgical implants in facial volumization. Aesthetic practitioners in South Korea and Brazil are adopting these formulations for non-surgical nose and chin reshaping at rates exceeding traditional procedural growth. This virtualization is collapsing the addressable market for invasive augmentation surgeries while expanding the treatable patient population to risk-averse demographics.
The EU Medical Device Regulation's post-market clinical follow-up requirements are mandating systematic long-term safety surveillance for all resorbable implant classes. Manufacturers must now maintain active registries tracking adverse events for 10-15 years post-implantation. Dermal filler portfolios with established safety databases are capturing preferential formulary placement in German and French hospital purchasing consortia.
Service unbundling is fragmenting the traditional device-sale model across training, certification, and remote patient monitoring. Aesthetic clinic chains in the United States are negotiating direct-to-manufacturer subscription arrangements that separate product procurement from educational content access. This restructuring is most pronounced in metropolitan markets where practice consolidation has concentrated purchasing leverage.
Non-Surgical Bio-Implants Market Segmentation
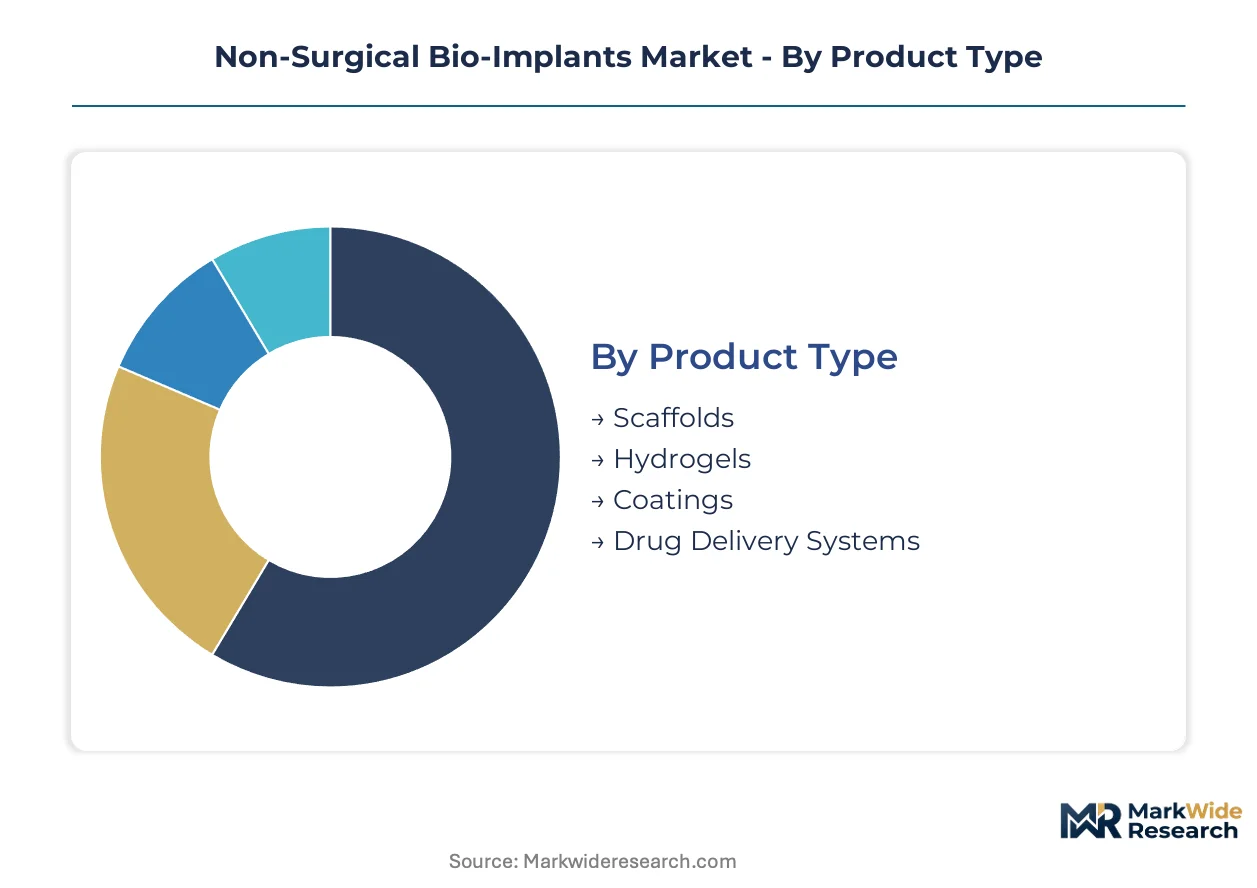
Segmentation in the non-surgical bio-implants market reveals how material science, clinical setting, and manufacturing technique intersect to determine commercial viability. Product type and application dimensions expose where reimbursement coverage concentrates, while technology and end-user splits illuminate capital intensity and regulatory pathway differences.
Product Type:
Material composition and structural architecture differentiate revenue potential across the four product categories, with hydrogels and scaffolds commanding established reimbursement positions.
- Scaffolds:Porous three-dimensional matrices—collagen, polylactic acid, or calcium hydroxylapatite—provide temporary mechanical support while host tissue infiltrates and remodels. Demand clusters in orthopedic and maxillofacial applications across German and Italian hospital purchasing consortia where post-market clinical follow-up databases demonstrate long-term safety profiles. The EU MDR's biocompatibility testing requirements favor incumbent scaffold manufacturers with established quality management systems.
- Hydrogels:Cross-linked hydrophilic polymer networks—predominantly hyaluronic acid formulations—deliver tunable rheological properties for injectable delivery. Brazilian and South Korean aesthetic clinics absorb volume for non-surgical facial volumization as these gels demonstrate equivalent outcomes to invasive rhinoplasty. Supply concentration in Chinese and Japanese fermentation-based manufacturers exposes formulators to batch variability risk.
- Coatings:Surface-modifying layers enhance biocompatibility or controlled release kinetics on underlying implants.
- Drug Delivery Systems:Bio-implant platforms loaded with antibiotics, growth factors, or corticosteroids for localized therapeutic release.
Hydrogels hold installed capacity. Drug Delivery Systems is rotating up the share rankings.
Application:
Clinical use case determines regulatory classification, reimbursement coding, and competitive intensity across the four application areas.
- Tissue Engineering:Cell-seeded constructs for regenerative repair of bone, cartilage, or dermal defects. Academic medical centers in the United States and hospital networks in Germany drive protocol adoption where microfabrication enables precise scaffold-cell integration. Jurisdictional debates over whether cell-laden constructs qualify as medical devices, biologics, or combination products delay market authorization timelines.
- Soft Tissue Repair:Injectable or implantable constructs for tendon, ligament, and dermal augmentation. Sports medicine networks in Brazil and aesthetic clinic chains in South Korea absorb volume as microfabricated cell-seeded scaffolds migrate from research into commercial orthobiologics. Thread lifting and energy-based skin tightening procedures compete for facial rejuvenation patients seeking longer-lasting results.
- Drug Release:Depot formulations for sustained pharmaceutical delivery.
- Wound Healing:Bio-active matrices for chronic wound bed preparation.
Tissue Engineering holds installed capacity. Soft Tissue Repair is expanding most quickly through sports medicine network partnerships.
Technology:
Fabrication method dictates capital requirements, scale economics, and geometric precision achievable in final construct architecture.
- 3D Bioprinting:Layer-by-layer deposition of bio-inks containing living cells and extracellular matrix components. Research institutes in the United States and Germany concentrate early adoption where computational modeling compresses formulation design cycles. Equipment costs and regulatory uncertainty around living cell constructs constrain commercial scale-up.
- Microfabrication:Photolithographic and soft-lithographic techniques enabling sub-micron feature resolution in scaffold architecture. Tendon augmentation applications in sports medicine networks leverage these capabilities for anisotropic mechanical properties mimicking native tissue. Partnerships between academic research groups and commercial orthobiologics firms accelerate technology transfer.
- Electrodeposition:Electrochemical synthesis of thin-film coatings and surface modifications.
- Additive Manufacturing:Powder-bed fusion and material extrusion for patient-specific implant geometries.
Microfabrication holds installed capacity. 3D Bioprinting is climbing the fastest as research collaborations mature into commercial partnerships.
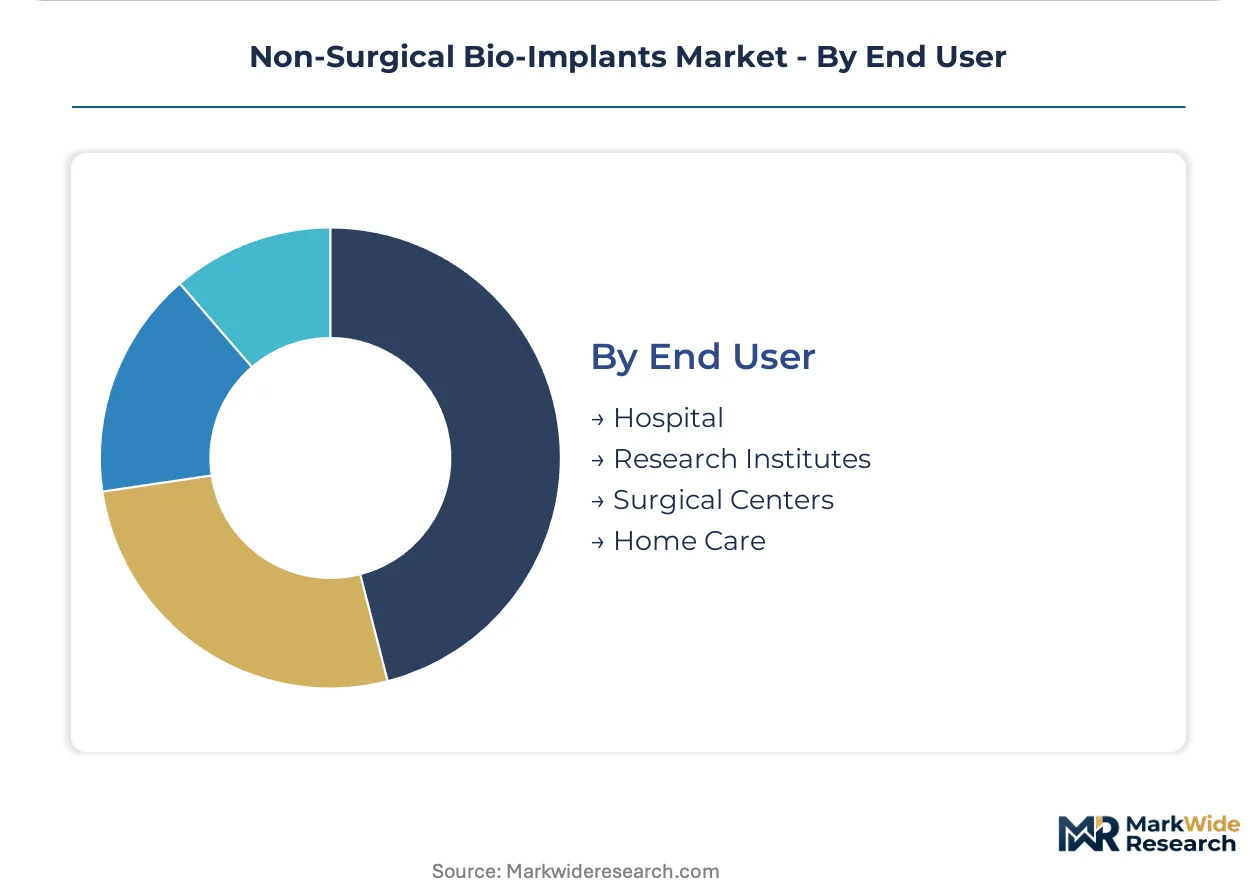
End User:
Site of care determines purchasing authority, reimbursement pathway, and service bundling requirements across the four end-user categories.
- Hospital:Inpatient and outpatient departments with centralized procurement and formulary committees. United States hospital outpatient departments absorb volume once reserved for surgical suites as hyaluronic acid fillers displace invasive procedures. German and French hospital purchasing consortia prefer dermal filler portfolios with established safety databases.
- Surgical Centers:Ambulatory facilities specializing in same-day procedures. Aesthetic clinic chains in metropolitan United States markets negotiate direct-to-manufacturer subscription arrangements separating product procurement from educational content access. Practice consolidation concentrates purchasing leverage in these settings.
- Research Institutes:Academic and government laboratories conducting preclinical and clinical investigation.
- Home Care:Patient-administered or remote-supervised therapeutic delivery settings.
Hospital holds installed capacity. Surgical Centers is gaining share fastest through subscription-based procurement restructuring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity diverges sharply across geographies: Brazilian and South Korean aesthetic patients absorb premium hyaluronic acid formulations with minimal resistance, while German and Italian hospital purchasing consortia enforce rigorous tender processes that compress margins on orthobiologic scaffolds.
United States
Hospital outpatient departments drive volume migration as hyaluronic acid fillers displace invasive rhinoplasty and chin augmentation procedures. The FDA's updated dermal filler safety guidance compresses approval timelines while mandating real-world evidence collection systems. Metropolitan aesthetic clinic chains in Los Angeles and New York negotiate subscription-based procurement separating product from educational content access.
Germany
Hospital purchasing consortia prioritize dermal filler portfolios with established post-market clinical follow-up databases spanning 10-15 years. The EU Medical Device Regulation's biocompatibility testing requirements favor incumbent manufacturers with quality management systems already certified. The Rhine-Ruhr and Bavarian medical technology clusters concentrate orthobiologic scaffold production for osteoarthritis protocols.
China
Domestic clinical trial mandates for imported bio-implants extend foreign time-to-market by 18-36 months, accelerating local manufacturing partnerships. The NMPA implements stricter domestic clinical data requirements that slow foreign access while protecting indigenous fermentation-based hyaluronic acid producers. Shanghai and Suzhou biotech parks host expanding contract manufacturing organizations serving both domestic and export markets.
Brazil
Aesthetic clinics absorb disproportionate volume for non-surgical facial volumization as hyaluronic acid gels demonstrate equivalent outcomes to invasive augmentation surgeries. ANVISA maintains alignment with international standards while requiring local adverse event reporting infrastructure. São Paulo and Rio de Janeiro concentrate private aesthetic practice chains with concentrated purchasing leverage over manufacturers.
South Korea
Aesthetic practitioners adopt cross-linked hyaluronic acid formulations for non-surgical nose and chin reshaping at rates exceeding traditional procedural growth. The MFDS regulates bio-implants under medical device pathways with streamlined approval for materials with established international safety profiles. Seoul's Gangnam district anchors global aesthetic tourism demand with clinic density unmatched elsewhere.
Non-Surgical Bio-Implants Market Competitive Landscape
Capability concentration sits with specialized orthobiologic and aesthetic formulation developers; scale advantage sits with diversified healthcare conglomerates leveraging existing surgical infrastructure. The market structure tiers across three segments: fermentation-based raw material suppliers, formulation specialists with proprietary cross-linking technologies, and integrated healthcare systems bundling products with training platforms. Dominant competitive moves include strategic partnerships between raw material suppliers and finished formulators, plus geographic expansion through local manufacturing joint ventures to satisfy domestic trial mandates.
Among diversified healthcare conglomerates, Johnson & Johnson occupies a position exemplifying the bundling archetype through surgeon education program integration. Anika Therapeutics and Fidia Farmaceutici sit within the formulation specialist tier, representing contrasting strategic anchors: one emphasizing dedicated R&D spending on single-injection viscosupplementation, the other extending hyaluronan manufacturing expertise across ophthalmology, aesthetic, and orthopedic indications. These three entities collectively illustrate how competitive positioning fragments across capability depth versus portfolio breadth trade-offs.
| Leading Market Players |
|---|
| Albiorex International |
| FibroGen |
| Kythera Pharmaceuticals |
| Moma Therapeutics |
| Novatex Bioengineering SA |
| Anika Therapeutics |
| Johnson & Johnson |
| Fidia Farmaceutici |
| LCA Pharma |
| Others |
Value Network & Pricing Analysis
Undercapacity in pharmaceutical-grade hyaluronic acid fermentation facilities across Shandong and Zhejiang provinces is elevating raw material premiums and compressing formulation margins for finished bio-implant producers.
Pricing Analysis
Surgeon certification and patient-monitoring subscriptions now generate recurring revenue streams that exceed unit-sale lifetime value for leading manufacturers. Three-tier pricing structure across premium, standard, and economy levels segments by rheological complexity and cross-linking density. Cost compression in economy-tier viscosupplementation is intensifying because Brazilian and South Korean clinic chains negotiate volume-based procurement agreements. Hospital purchasing consortia in Germany exhibit highest price sensitivity; aesthetic clinic networks in Seoul and São Paulo absorb premium formulations with minimal resistance.
Supply Chain Analysis
Upstream feedstock of pharmaceutical-grade sodium hyaluronate concentrates in Chinese and Japanese fermentation facilities with limited alternative sourcing. Finished formulation draws from collagen extraction operations in Italy, polylactic acid polymerization in Germany, and calcium hydroxylapatite synthesis in the United States. Single-source vulnerability in hyaluronic acid supply exposes formulators to batch variability and import licensing delays. Distribution runs through direct manufacturer-to-clinic arrangements in metropolitan aesthetic markets and GPO-negotiated contracts in hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The FDA's updated dermal filler safety guidance and EU MDR post-market surveillance mandates are compressing approval timelines while elevating compliance barriers, creating asymmetric growth conditions favoring prepared incumbents.
For Market Incumbents: Harden quality management systems against EU MDR biocompatibility testing requirements and FDA real-world evidence collection mandates. Consolidate supply security through captive fermentation partnerships or long-term offtake agreements with Shandong-based raw material suppliers. Thread lifting and energy-based device substitutes threaten facial rejuvenation volume; defend through extended-duration filler formulations and bundled training platform lock-in.
For New Entrants and Emerging Players: Antibiotic-loaded hydrogels for chronic wound beds in German and Italian hospital purchasing consortia represent the most penetrable entry point where localized release kinetics command premium reimbursement. Microfabricated cell-seeded scaffolds for tendon augmentation through sports medicine networks in Brazil offer second-mover advantage as academic partnerships mature. Prioritize direct-to-clinic subscription models that separate product procurement from educational content access.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among formulation specialists with proprietary cross-linking technologies and established surgeon certification platforms. Long-term viability over the projection horizon rests on navigating regenerative medicine classification debates across FDA, EMA, and NMPA jurisdictions. Acquisition targets should demonstrate active post-market clinical follow-up databases spanning the full EU MDR compliance window. Monitor NMPA domestic trial mandate enforcement as the signal indicating acceleration or deceleration of Chinese market access timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR biocompatibility testing requirements favor incumbents with certified quality management systems in German clusters. |
| Hospital System Partnership | Direct procurement relationships with United States outpatient departments displace traditional surgical suite volume. |
| Reimbursement Strategy | German and Italian viscosupplementation protocol expansion enables single-injection premium capture over multi-injection regimens. |
| Software Companion Development | Patient-monitoring apps and remote surveillance platforms generate recurring revenue decoupled from unit sales volatility. |
| Backward Integration | Captive supply of pharmaceutical-grade hyaluronic acid mitigates batch variability risk from concentrated fermentation sources. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with regulatory affairs leads, biomedical engineers, hospital purchasing committee members, and GPO contracts managers; and secondary validation through FDA 510(k) filings, EUDAMED device registrations, NMPA approval databases, and hospital procurement records. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators to establish volume and value estimates.
Forecast inputs include material type, cross-linking technology, clinical application, end-user setting, and geographic regulatory cluster across the modeling period. CAGRs were derived from segment-level growth trajectories weighted by installed base dynamics and reimbursement pathway maturity. Industry-specific inputs incorporated orthobiologic protocol adoption curves, aesthetic procedural migration rates, and domestic trial mandate compliance timelines.
Macroeconomic conditions sit as an overlay; deviation in healthcare expenditure growth, currency volatility affecting import-dependent supply chains, or regulatory harmonization failures would shift the trajectory. Cross-checking against CMS Medicare reimbursement data and EUDAMED adverse event reporting trends is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Engineering
Global Bionics Market
Biomedical Engineering
Global Robotic Prosthetic Market
Biomedical Engineering
Tissue Expansion Market
Biomedical Engineering
Bioabsorbable Implant Market
Biomedical Engineering
Biological Implants Market
Biomedical Engineering
Europe Bioresorbable Vascular Scaffold Market
Biomedical Engineering
Global Biomedical Tester Market
Biomedical Engineering
Bio-Engineered Stent Market
Biomedical Engineering
Topical Bioadhesives Market
Biomedical Engineering
Bioimplants Market
Biomedical Engineering
Self-Inflating Tissue Expander Market
Biomedical Engineering
Global Bionic Ear Market
Biomedical Engineering
North America Lab-On-A-Chip and Microarrays (Biochip) Market
Biomedical Engineering
Bioactive Coating Devices Market
Biomedical Engineering
Biomems Market
Biomedical Engineering
Bioactive Bone Grafts Market