
 Disodium Guanylate Market | 2026-2036
Disodium Guanylate Market Size, Share, and Industry Trends Forecast 2026-2036
Disodium Guanylate Market Outlook
The gap between food-grade and pharmaceutical-grade specifications is shifting procurement criteria across the supply base. Ajinomoto Co., Inc. leverages its integrated fermentation technology to command premium positioning in high-purity grades. Fufeng Group anchors volume production through backward integration into corn starch feedstocks. Angel Yeast Co., Ltd. differentiates via specialized yeast-derived nucleotide extraction capabilities.
Disodium guanylate is a nucleotide salt produced through microbial fermentation of carbohydrates, typically yielding a sodium salt of guanosine 5-monophosphate with purity thresholds exceeding 97 percent for food applications. It functions synergistically with monosodium glutamate to amplify umami perception at reduced sodium levels in processed foods. The food additive application segment dominates current volume flows, while flavor enhancer positioning in clean-label formulations represents the fastest-expanding margin pool. Powder form leads industrial handling efficiency, though granule demand accelerates among restaurant chains seeking controlled dissolution rates.
China's SAMR enforces GB 1886.325 food additive standards that dictate microbial limits and heavy metal thresholds for domestic disodium guanylate production. The U.S. FDA classifies the compound as GRAS for intended use levels, while EFSA in Europe reviews nucleotide additive combinations under re-evaluation protocols. Stakeholders must monitor regulatory divergence on combined nucleotide usage caps, as these thresholds will determine formulation flexibility and regional market access.
Market Dynamics
Fermentation technology improvements are compressing production cycles for nucleotide salts while China's SAMR tightens purity thresholds, forcing producers to recalibrate capital deployment between volume scale and grade specialization.
Growth Catalysts
- Clean-label formulation mandates:Processed food manufacturers in East Asia are reformulating to reduce sodium content while preserving umami intensity, creating specification pull for high-purity nucleotide salts.
- GB 1886.325 enforcement:China's updated food additive safety standards are accelerating facility upgrades among domestic producers, filtering out subscale operators and consolidating compliant supply.
- Ready-to-eal meal expansion:Urban consumption patterns in Chinese metropolitan clusters are driving volume demand for flavor-enhanced convenience foods with extended shelf stability.
Market Restraints
- Corn starch feedstock volatility:Input cost swings for carbohydrate feedstocks constrain margin predictability for fermentation-based producers without backward integration into agricultural supply.
- Shandong-Jiangsu supply concentration:Nucleotide production clusters in two Chinese provinces create geographic risk exposure to regional energy policy shifts or environmental enforcement actions.
- Combined nucleotide caps:EFSA re-evaluation protocols for additive combinations impose formulation constraints that limit regional market access for certain product grades.
Strategic Opportunities
- Pharmaceutical-grade verticals:Purification technology investments can unlock higher-margin nucleotide applications in cell culture media and therapeutic formulations.
- Granule format adoption:Restaurant chain procurement is pivoting toward controlled-dissolution formats, creating specification differentiation for producers with spray-drying capabilities.
- Fermentation technology licensing:Proprietary microbial strain development and process IP can generate revenue streams independent of commodity nucleotide sales.
Industry Challenges
- Bioprocess engineering talent scarcity:Specialized expertise in industrial-scale fermentation optimization and downstream purification remains concentrated among a limited pool of practitioners.
- Dual-grade facility certification:Simultaneous compliance with food-grade and pharmaceutical-grade standards requires capital-intensive cleanroom infrastructure and extended validation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Disodium Guanylate Market |
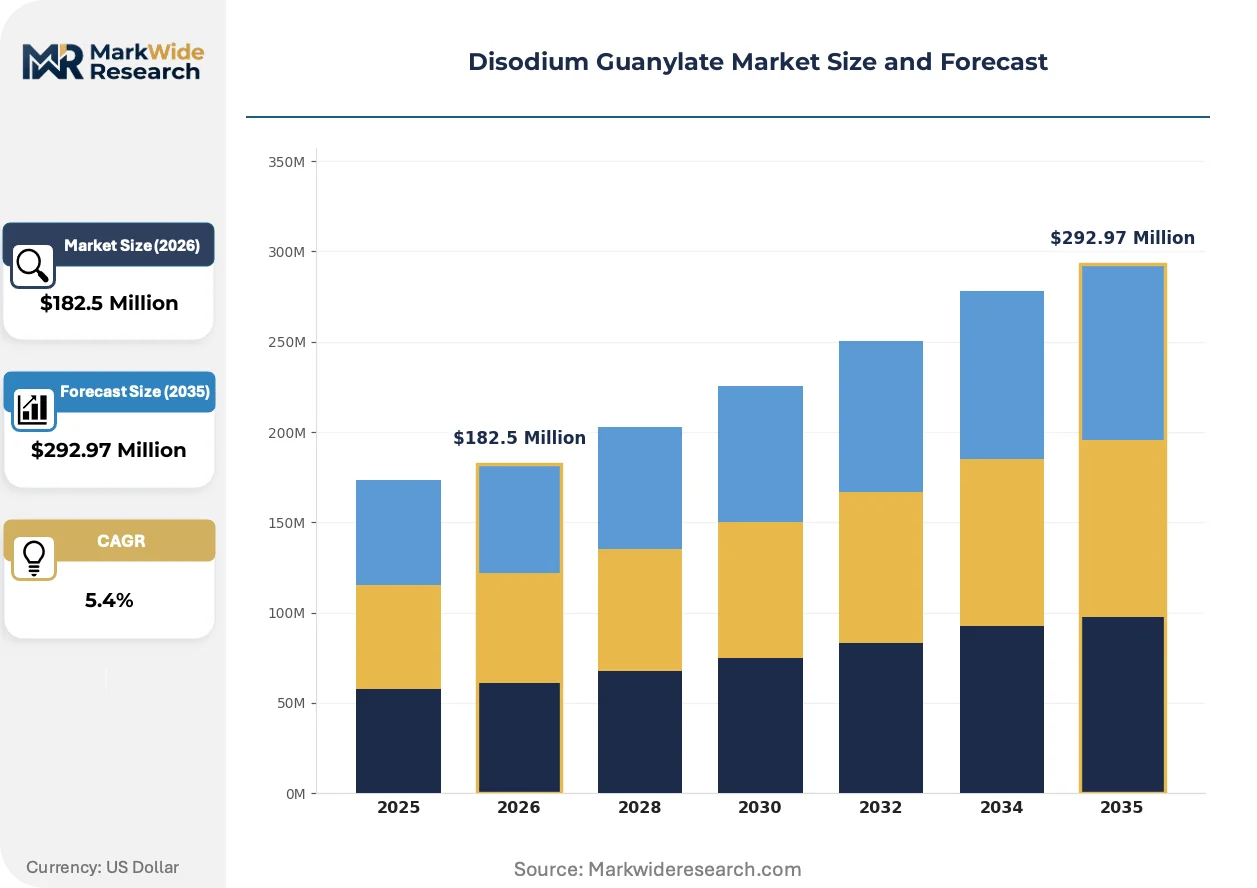
| Market Size in 2026 | $182.5 Million |
| Market Size in 2035 | $292.97 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Food Additive, Flavor Enhancer, Seasoning, Meat Products Form: Powder, Granules, Tablets, Liquid End User: Food Industry, Beverage Sector, Restaurant Chains, Snack Manufacturers Grade: Food Grade, Pharmaceutical Grade, Industrial Grade, Technical Grade |
| Companies Covered | Ajinomoto Co., Inc., Fufeng Group, Angel Yeast Co., Ltd., Meihua Holdings Group, Vedan International Holdings Ltd., Ningxia EPPEN Bioengineering, Lianyungang Shuren Kechuang Food Additive Co., Ltd., AIPU Food Industry Co., Ltd., Biorigin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Disodium Guanylate Market Strategic Shifts
Continuous fermentation systems are displacing batch processes in nucleotide manufacturing, while regulatory divergence between major markets is fragmenting formulation standards and procurement specifications.
Continuous bioprocessing equipment is modularizing nucleotide production infrastructure, enabling mid-scale producers to deploy capacity in phased increments rather than committing to monolithic facility investments. Yeast-derived extraction specialists are adopting these systems to flex output between food-grade and pharmaceutical-grade specifications based on spot margin differentials. This modularization is compressing the minimum efficient scale for viable entry, eroding the volume advantage historically held by integrated starch-to-nucleotide producers.
EFSA's ongoing re-evaluation of nucleotide additive combinations under EU food safety protocols is tightening usage caps in infant formula and specialized nutrition applications. Manufacturers targeting European market access are reformulating to stay beneath combined IMP/GMP thresholds, redirecting R&D resources toward single-nucleotide positioning or alternative umami technologies. The regulatory friction is most acute for exporters from East Asian production clusters who built capacity around higher combined-nucleotide formulations acceptable under FDA GRAS determinations.
Restaurant chain procurement teams are consolidating supplier relationships and demanding format customization with documented dissolution performance metrics. Powder specifications dominate industrial handling, but granule contracts carry premium pricing for chains operating standardized kitchen equipment with fixed hydration protocols. This buyer-driven specification bifurcation is most visible in China's quick-service restaurant expansion, where national chains are qualifying dual-source suppliers capable of matching dissolution curves across format types.
Disodium Guanylate Market Segmentation
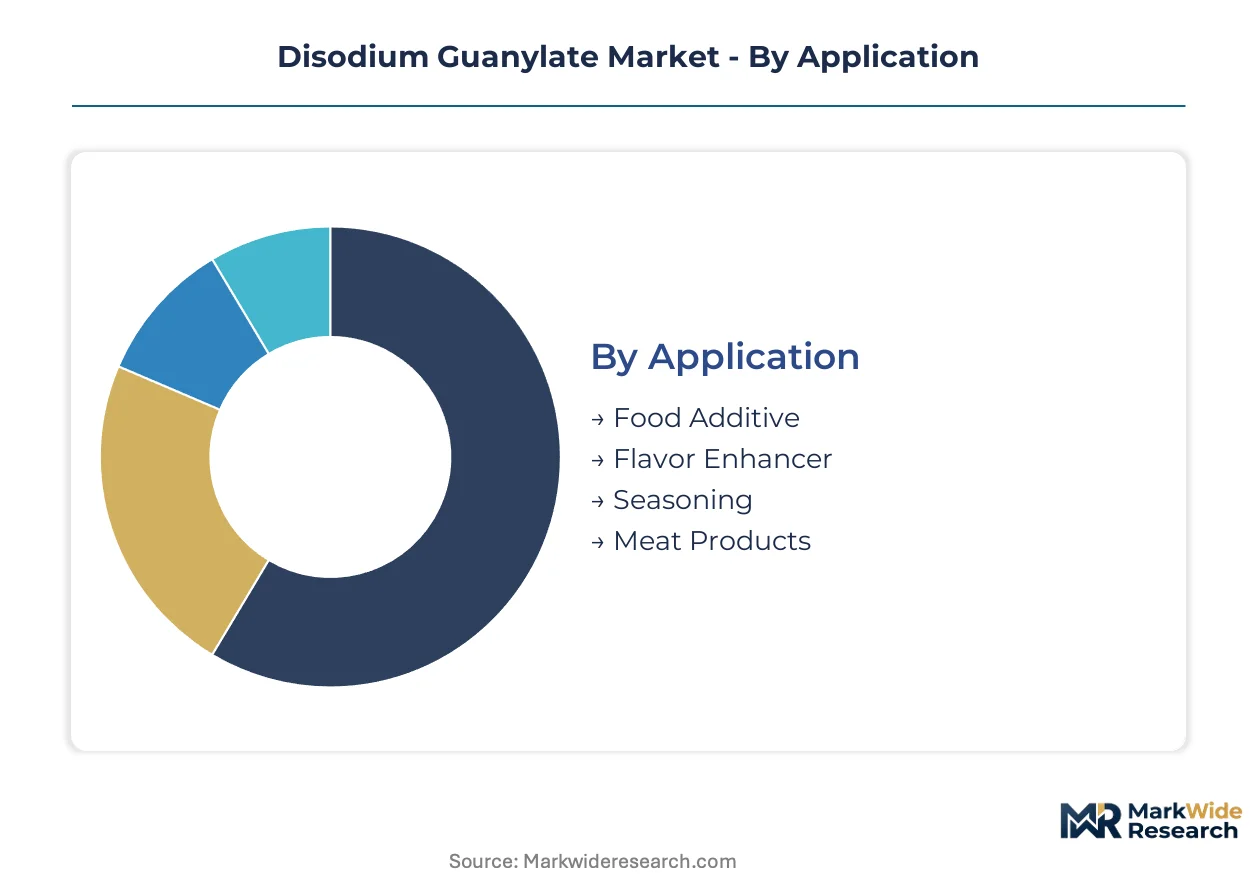
Segmentation in the disodium guanylate market reflects divergent purity requirements, handling preferences, and regulatory exposure across buyer types. Manufacturers configure production lines around specific grade and form combinations to capture margin pools in pharmaceutical verticals versus commodity food applications.
Application:
Buyers differentiate by sodium reduction mandates versus clean-label positioning, with formulation flexibility determining contract value and renewal rates.
- Food Additive:The sodium salt of guanosine 5-monophosphate integrates into processed foods at sub-1% concentrations to amplify umami perception without standalone flavor contribution. China's Shandong province processors dominate volume procurement for instant noodle seasoning packets.
- Flavor Enhancer:Synergistic pairing with monosodium glutamate enables sodium reduction of 30-40% in ready-to-eat meals while preserving taste intensity. Restaurant chains in Chinese metropolitan clusters specify dissolution-calibrated grades for standardized kitchen protocols.
- Seasoning:Pre-blended nucleotide salts enter retail spice mixes and bouillon formulations through third-party compounders. Demand concentrates among Southeast Asian export-oriented seasoning houses.
- Meat Products:Cured and processed meat applications require low-microbial-load specifications under China's GB 1886.325 standards. Jiangsu province meat processors account for disproportionate share of pharmaceutical-grade crossover demand.
Volume sits with Food Additive; growth tilts toward Flavor Enhancer.
Form:
Handling economics and dissolution control separate industrial buyers from foodservice operators, with format choice directly impacting logistics costs and kitchen workflow integration.
- Powder:Fine particulate morphology maximizes surface area for rapid hydration in high-throughput manufacturing environments. Bulk pneumatic handling systems at Fufeng Group's Shandong facilities optimize for powder specifications.
- Granules:Controlled particle size distribution enables metered dispensing in quick-service restaurant environments with fixed hydration protocols. National Chinese chains are qualifying dual-source suppliers for dissolution curve matching.
- Tablets:Compressed unit-dose formats serve institutional catering and remote food preparation settings where precise portion control outweighs unit cost premiums.
- Liquid:Pre-dissolved nucleotide solutions eliminate hydration variables in automated sauce production lines. Japanese beverage sector buyers specify liquid formats for umami water applications.
Industrial procurement favors Powder; foodservice expansion drives Granule adoption.
End User:
Scale requirements and specification complexity create distinct supplier relationship models, from transactional commodity purchasing to co-development partnerships.
- Food Industry:Processed food manufacturers in East Asia integrate disodium guanylate into seasoning bases for instant noodles, soups, and savory snacks. China's SAMR enforcement of GB 1886.325 is filtering subscale suppliers from approved vendor lists.
- Beverage Sector:Nucleotide-enhanced umami waters and functional drinks represent emerging application territory with specialized solubility requirements. Japanese METI guidelines influence formulation standards for regional exporters.
- Restaurant Chains:Central kitchen procurement teams demand documented dissolution performance metrics and format flexibility. China's quick-service expansion is consolidating supplier relationships around dual-format capability.
- Snack Manufacturers:Seasoning application on extruded and fried products requires heat-stable nucleotide grades with minimal degradation during high-temperature processing.
Procurement scale concentrates in Food Industry; specification complexity climbs fastest in Restaurant Chains.
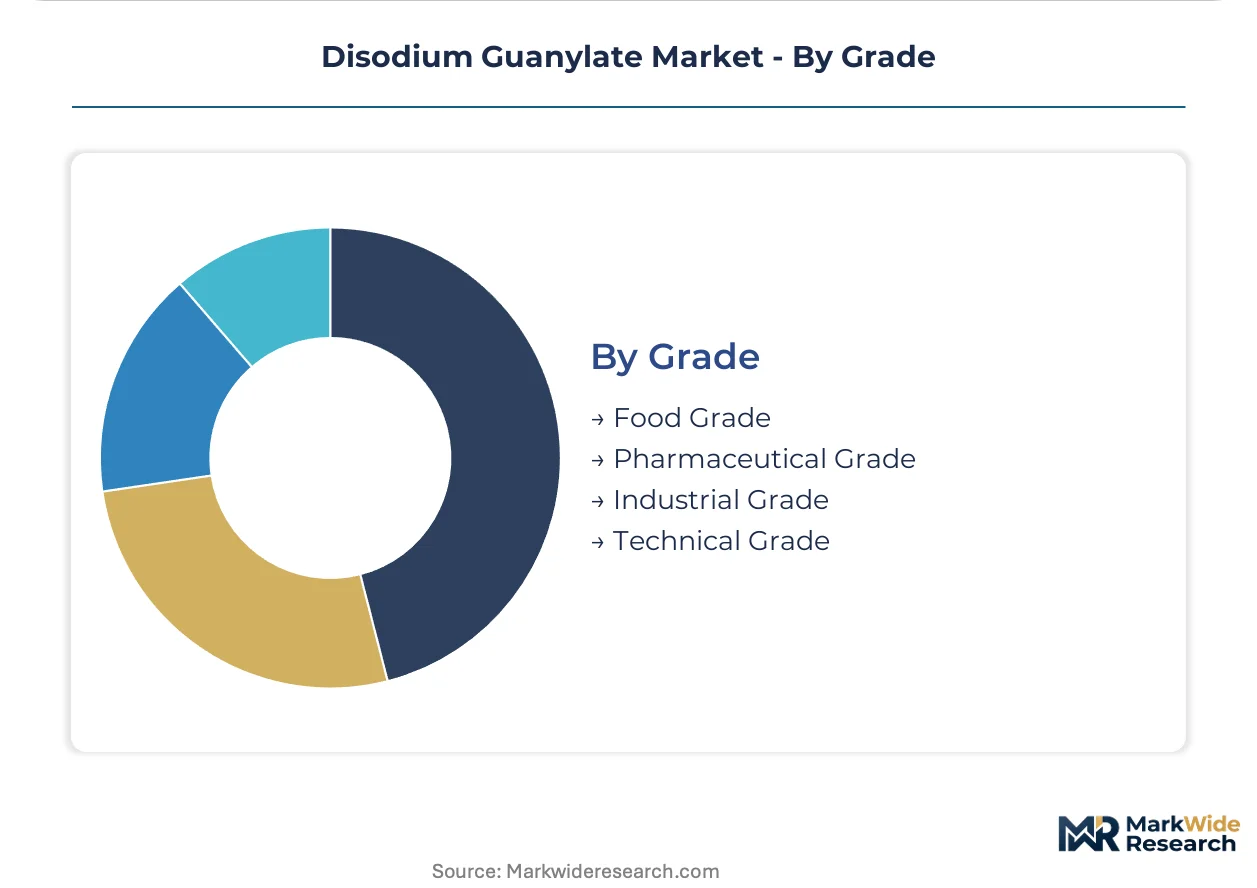
Grade:
Regulatory jurisdiction and end-use liability determine purity thresholds, with pharmaceutical-grade commanding 3-5x price multiples over commodity food grades.
- Food Grade:Minimum 97% purity with controlled microbial limits satisfies China's GB 1886.325 and FDA GRAS determinations for general food applications. Shandong-Jiangsu production clusters optimize for this specification band.
- Pharmaceutical Grade:Ultra-high purity with endotoxin control and heavy metal thresholds below 10 ppm unlocks cell culture media and therapeutic formulation applications. Ajinomoto's integrated fermentation technology anchors premium positioning.
- Industrial Grade:Relaxed purity specifications serve non-food applications including biochemical reagents and research use, with minimal regulatory compliance burden.
- Technical Grade:Intermediate purity band for veterinary nutrition and animal feed flavoring, subject to less stringent residue monitoring than human food applications.
Revenue concentrates in Food Grade; margin expansion tilts toward Pharmaceutical Grade.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Shandong-Jiangsu corridor anchors nucleotide salt production, with fermentation facilities clustering around Qingdao and Xuzhou to exploit corn starch supply chains and port logistics for Asian export markets.
China
Instant noodle manufacturers in Henan and snack producers in Fujian drive bulk procurement of food-grade nucleotide salts. SAMR's GB 1886.325 enforcement is de-listing subscale fermenters in Shandong province. Qingdao-based producers are upgrading to pharmaceutical-grade capability to capture margin expansion in cell culture applications.
Japan
Umami water innovators and functional beverage formulators in Tokyo-Osaka corridor seek solubility-optimized nucleotide grades. METI guidelines on food additive labeling influence formulation standards for regional exporters. Ajinomoto's integrated fermentation complex in Kawasaki anchors premium-grade supply for therapeutic and cell culture verticals.
United States
Clean-label sauce manufacturers and sodium-reduction focused CPG brands in Chicago and California metro areas specify high-purity nucleotide combinations. FDA GRAS determinations permit broader formulation flexibility than EFSA protocols allow. New Jersey-based flavor houses are qualifying East Asian suppliers for dual-nucleotide seasoning bases.
Germany
EFSA's re-evaluation of combined IMP/GMP thresholds is forcing reformulation among infant nutrition compounders in Bavaria. REACH compliance requirements add regulatory burden for nucleotide importers at Rotterdam-Antwerp gateway. Frankfurt-area distributors are pivoting toward single-nucleotide positioning to preempt usage cap restrictions.
Brazil
Processed meat seasoning houses in São Paulo state and snack flavoring specialists in Minas Gerais represent emerging volume demand. ANVISA's evolving food additive registry creates compliance uncertainty for imported nucleotide salts. Santos port logistics are improving customs clearance velocity for East Asian fermentation-derived ingredients.
Disodium Guanylate Market Competitive Environment
Capital-heavy producers compete with asset-light designers as integrated fermentation operators with captive starch supply confront specialized yeast-extraction specialists with modular bioprocessing capability. The vendor base separates into three tiers: global integrated players with pharmaceutical-grade certification, regional volume producers with backward integration into agricultural feedstocks, and niche extraction specialists with flexible grade-switching capacity. Dominant competitive moves include fermentation technology licensing to capture IP revenue independent of commodity sales, and spray-drying capacity investments to serve restaurant chain granule specifications.
Within the integrated fermentation tier, Ajinomoto Co., Inc. exemplifies premium positioning through proprietary strain development and downstream purification depth. Fufeng Group occupies a position as a volume anchor with upstream control over corn starch supply chains in China's northern plains. Angel Yeast Co., Ltd. represents the specialized extraction archetype, leveraging yeast-derived nucleotide capabilities to serve dual-grade demand across food and pharmaceutical specifications.
| Leading Market Players |
|---|
| Ajinomoto Co., Inc. |
| Fufeng Group |
| Angel Yeast Co., Ltd. |
| Meihua Holdings Group |
| Vedan International Holdings Ltd. |
| Ningxia EPPEN Bioengineering |
| Lianyungang Shuren Kechuang Food Additive Co., Ltd. |
| AIPU Food Industry Co., Ltd. |
| Biorigin |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap specialists in Shandong and Jiangsu provinces anchor nucleotide salt production, translating agricultural feedstock control into pricing discipline that resists spot-market volatility. Their captive corn starch supply insulates margin structures from commodity swings while SAMR enforcement tightens the compliant supplier pool.
Pricing Analysis
Yield-anchored pricing tied to dissolution performance metrics dominates restaurant chain procurement contracts. Three-tier pricing structure across pharmaceutical, food, and technical grades separates Ajinomoto's premium fermentation technology from Fufeng's volume-scale commodity positioning. Cost compression in food-grade powder specifications is intensifying because continuous fermentation systems are modularizing entry barriers. Snack manufacturers in Fujian exhibit highest price sensitivity due to thin seasoning margins, while pharmaceutical-grade buyers accept 3-5x multiples for endotoxin-controlled cell culture applications.
Supply Chain Analysis
Dual-sourcing mandates from national Chinese quick-service restaurant chains are fragmenting procurement across Shandong yeast-extraction specialists and Jiangsu starch-fermentation operators. Production gravity centers on China, Japan, and South Korea for fermentation-derived nucleotides, with corn starch, microbial strains, and downstream purification resins as critical input dependencies. Single-source vulnerability concentrates in the Qingdao-Xuzhou corridor where environmental enforcement actions could disrupt regional output. Distribution runs through bonded port logistics at Qingdao and Shanghai for Asian export markets, with Rotterdam-Antwerp serving European gateway clearance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply constraints in pharmaceutical-grade certification capacity prop pricing power for compliant producers, as dual-grade facility investments face 18-24 month validation timelines that throttle near-term expansion.
For Market Incumbents: Extend pharmaceutical-grade purification capabilities to capture cell culture media demand before modular bioprocessing erodes scale advantages. Defend against yeast-extraction specialists by locking multi-year contracts with restaurant chains seeking dissolution-curve standardization. Prioritize spray-drying capacity additions in Jiangsu to serve granule format procurement consolidation. For New Entrants and Emerging Players: GB 1886.325 in China opens a window for compliant mid-scale fermenters to capture de-listed subscale operator volume. Target beverage sector umami water applications in Japan where solubility specifications favor specialized liquid format production. Enter through fermentation technology licensing to generate IP revenue without commodity nucleotide margin exposure. For Investors and Strategic Acquirers: Distressed-cycle entries favor yeast-extraction specialists with flexible grade-switching capability in China's interior provinces. Long-term viability hinges on pharmaceutical-grade certification depth rather than commodity food additive scale. Watch EFSA combined nucleotide cap decisions as the inflection signal for European market access restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Pharmaceutical-Grade Certification Investment | Unlocks 3-5x pricing multiples in cell culture media applications for compliant producers. |
| Spray-Drying Capacity Expansion | Captures granule format premiums from restaurant chains with fixed hydration protocols. |
| Fermentation Technology Licensing | Generates recurring IP revenue independent of commodity nucleotide price cycles. |
| Continuous Bioprocessing Adoption | Compresses minimum efficient scale and enables flexible output between grade specifications. |
| Dual-Grade Facility Certification | Extends addressable market across food additive and therapeutic formulation verticals. |
Study Parameters
Multi-period observation of GB 1886.325 enforcement patterns and fermentation technology deployment anchored the trend analysis, supplemented by interviews with plant managers at Shandong-Jiangsu production clusters, procurement leads at instant noodle manufacturers, regulatory affairs specialists at SAMR, and technical R&D directors at yeast extraction facilities. Secondary validation drew from customs trade data, SEC 10-K filings of listed nucleotide producers, Chinese food additive registry updates, and EFSA re-evaluation protocols. Bottom-up capacity modeling and top-down demand segmentation triangulated volume estimates.
Input-output matrices mapped fermentation yield coefficients against corn starch feedstock availability across the projection horizon. Segmentation dimensions modeled include application type, form factor, grade tier, and end-user industry. CAGRs derived from capacity expansion timelines, regulatory compliance trajectories, and substitution elasticity estimates for MSG-nucleotide combinations. Forecast inputs incorporated SAMR enforcement velocity and EFSA combined nucleotide threshold decisions.
The model assumes a particular technology adoption path; alternative pathways for continuous fermentation modularization would alter the outlook for minimum efficient scale and incumbent volume advantages. Deviation in corn starch price volatility or Shandong-Jiangsu environmental enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Oilfield Drilling Fluid Additive Market
Additives
Crystal Growth Modifier Market
Additives
China Sodium Reduction Ingredient Market
Additives
Middle East Lubricant Additives Market
Additives
Global Asphalt Additives Market
Additives
Driveline Additives Market
Additives
Anti-Creasing Agent Market
Additives
Weighing Agents Market
Additives
Citric Acid Anhydrous Market
Additives
Texture Modifier Market
Additives
Stabilizers Market
Additives
Sorbitan Laurate Market
Additives
1,4 Butanediol Derivatives Market
Additives
Global Feed Acidifiers Market
Additives
Global Slip Additives Market
Additives
India Feed Additives Market