
 Anti Crystallizing Agents Market | 2026-2036
Anti Crystallizing Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Anti Crystallizing Agents Market Outlook
China is tilting its chemical intermediate capacity toward food-grade polyol derivatives that serve anti-crystallizing applications. BASF leverages its Ludwigshafen integrated site to sustain captive supply of high-purity sorbitol for European confectionery clients. Cargill anchors North American demand through its corn-derived polyol portfolio and direct relationships with bakery manufacturers. Evonik competes on specialty propylene glycol grades designed for pharmaceutical stability applications.
Anti-crystallizing agents are hygroscopic additives, typically polyols or modified carbohydrates, that disrupt molecular lattice formation in supersaturated solutions by interfering with hydrogen bonding patterns at concentrations between 0.5% and 5% by weight. These compounds maintain textural uniformity in processed foods, extend the viable shelf life of liquid pharmaceuticals, and prevent phase separation in cosmetic emulsions. Sorbitol dominates volume demand across confectionery applications where it suppresses sucrose recrystallization in hard candies and chewing gums. Glycerol occupies the fastest-expanding position in pharmaceutical end uses where its dual functionality as humectant and crystallization inhibitor commands premium pricing. Propylene glycol sustains stable margins in beverage applications where regulatory clearance for direct consumption narrows the supplier base.
FDA food additive regulations under 21 CFR govern the permissible daily intake thresholds for sorbitol and glycerol in U.S. processed foods, while EFSA evaluates novel polyol submissions under updated Novel Food guidance. REACH registration requirements for propylene glycol imports into the European Union shape supplier qualification timelines and testing burdens. Manufacturers must monitor evolving pharmaceutical-grade monographs from USP and EP pharmacopeias, as tightening purity specifications for injectable formulations will determine which suppliers retain access to high-margin segments.
Market Dynamics
Pharmaceutical-grade purity specifications are compressing supplier margins while concentrating procurement among integrated polyol manufacturers capable of certifying to USP and EP injectable monographs. This regulatory ratchet is forcing mid-scale humectant producers toward food-grade applications or exit.
Growth Catalysts
- Biologic formulation stability mandates:Injectable protein therapies require anti-crystallizing excipients that prevent aggregation during freeze-thaw cycles. Parenteral drug manufacturers are qualifying sorbitol and trehalose grades at volumes that reshape polyol capacity planning.
- EU REACH purity tiering:Registration dossiers for food-contact polyols now demand contaminant thresholds below 10 ppm for certain process residuals. This is accelerating replacement of technical-grade inventories with refined alternatives in German and French confectionery supply chains.
- Clean-label confectionery reformulation:Hard candy manufacturers are replacing traditional glucose syrups with non-crystallizing polyol blends to achieve shelf-stable transparency without artificial stabilizers.
Market Restraints
- Propylene glycol supply concentration:European pharmaceutical-grade supply routes through Ludwigshafen and Rotterdam create single-point vulnerability for injectable formulation clients dependent on just-in-time delivery.
- Technical substitution ceiling:Glycerol's hygroscopic performance in low-water-activity applications hits functional limits below 15% equilibrium relative humidity, blocking expansion into certain dehydrated food matrices.
- REACH testing cost escalation:Extended one-generation reproductive toxicity studies for novel polyol submissions now exceed €800,000 per substance, freezing innovation pipelines for mid-size specialty chemical houses.
Strategic Opportunities
- Indian pharmaceutical excipient qualification:CDSCO's alignment with ICH Q3D guidelines for elemental impurities creates opening for USP-certified sorbitol producers to displace informal supply channels in Mumbai and Hyderabad formulation clusters.
- Cell culture media anti-crystallizing additives:Cryopreservation solutions for CAR-T manufacturing require non-permeating cryoprotectants that suppress ice nucleation without osmotic toxicity.
- Japan's Food with Function Claims system:FOSHU regulatory pathway rewards documented digestive tolerance for sugar alcohols, incentivizing confectionery brands to feature polyol content in functional positioning.
Industry Challenges
- Pharmacopeial certification timeline compression:USP and EP monograph updates now arrive on 18-month cycles, forcing quality teams to revalidate analytical methods faster than legacy document control systems permit.
- Bioprocess integration complexity:Single-use bioreactor systems require excipient grades with extractables profiles that differ from traditional stainless-steel validated standards, creating dual inventory requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti Crystallizing Agents Market |
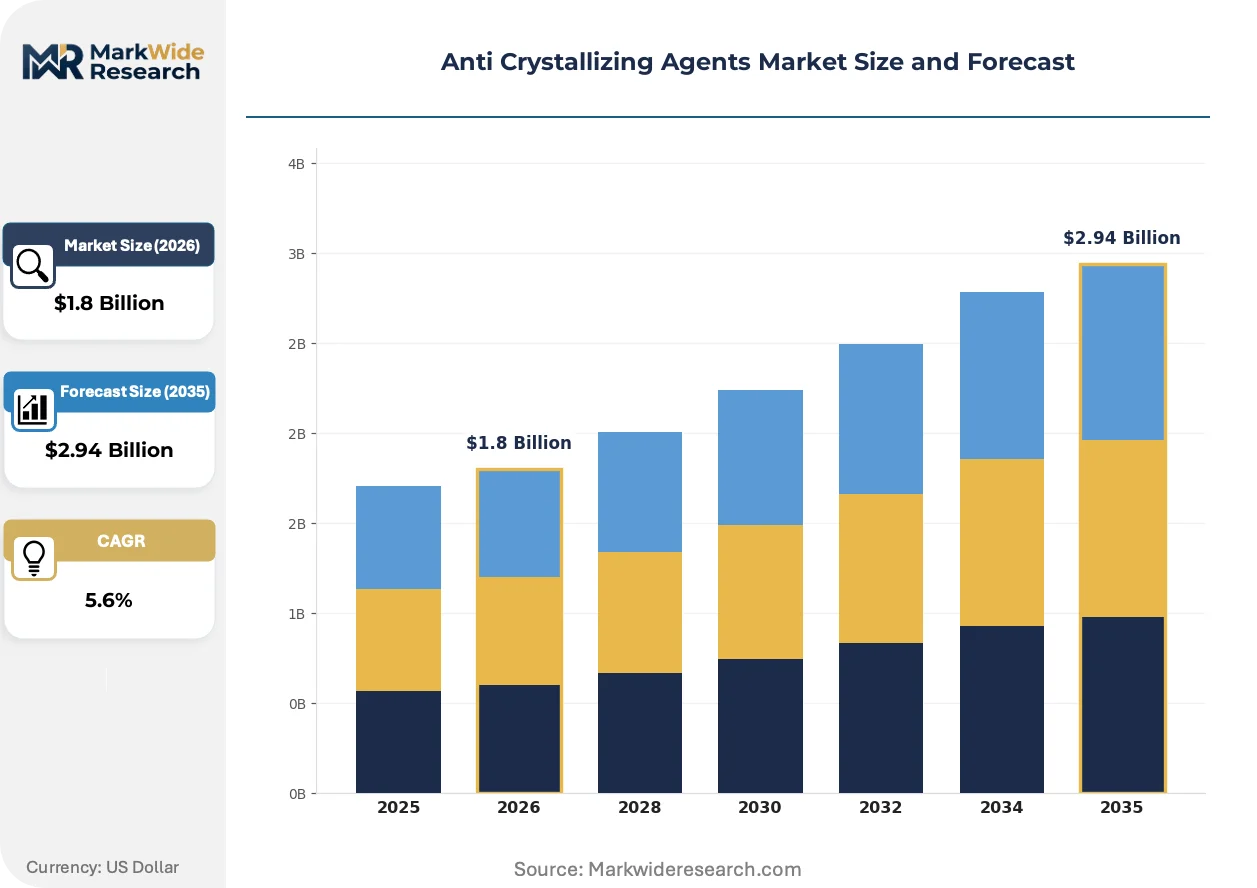
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.94 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sorbitol, Glycerol, Propylene Glycol, Maltodextrin Application: Confectionery, Dairy, Bakery, Beverages End User: Food Manufacturers, Pharmaceutical Companies, Cosmetic Producers, Nutraceutical Firms Form: Liquid, Powder, Granular, Solid |
| Companies Covered | BASF, Cargill, Roquette, Fine Organics, Nikko Chemicals, Shandong Futaste, Evonik, Croda International, Lubrizol Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti Crystallizing Agents Market Strategic Shifts
Computational molecular modeling is shortening development cycles for next-generation crystallization inhibitors, while regulatory data sharing initiatives are collapsing redundant safety testing across jurisdictions.
Amorphous solid dispersion technology is virtualizing traditional formulation approaches by embedding active pharmaceutical ingredients in polyol matrices that maintain kinetic stability indefinitely. Generic drug manufacturers in India and Eastern Europe are adopting spray-drying equipment at twice the previous rate to access this platform. The technology is virtualizing the competitive barrier that patent-protected crystal forms previously provided originator firms.
REACH's 2023 update to restriction entries for residual solvents in food-contact materials is forcing polyol producers to retire legacy hydrogenation catalysts containing nickel above 0.1 ppm thresholds. Manufacturers serving Dutch and Belgian chocolate coating applications are accelerating transition to supported palladium systems. The confectionery segment bears the steepest reformulation cost, with smaller compounders lacking in-house hydrogenation capacity facing supplier consolidation.
Direct manufacturer-to-formulator relationships are displacing traditional distribution intermediaries for pharmaceutical-grade humectants. Large parenteral drug producers in Germany and Switzerland now require batch-specific certificates of analysis with elemental impurity data rather than accepting standard COA templates. This behavioral shift is most visible in Basel and Munich, where procurement teams have eliminated regional distributors from qualified supplier lists for critical excipients.
Anti Crystallizing Agents Market Segmentation
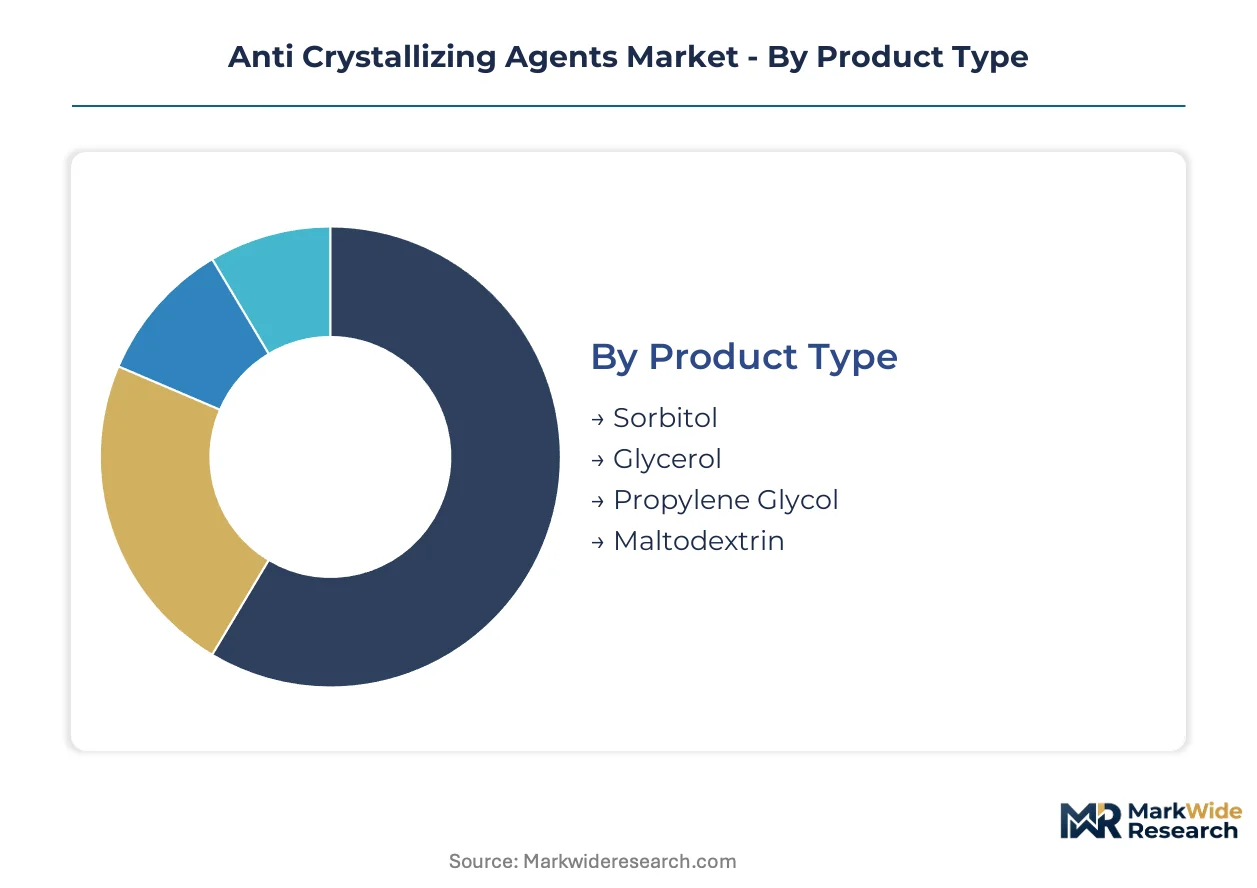
Anti-crystallizing agents serve distinct functional requirements across formulation chemistries and processing conditions. Segmentation reveals how purity grades, physical forms, and end-use specifications reshape procurement patterns and supplier qualification thresholds.
Product Type:
Mature polyol chemistries dominate volume positions while novel carbohydrate derivatives carve emerging niches in specialized applications.
- Sorbitol:A hexitol sugar alcohol produced through catalytic hydrogenation of glucose. German confectionery clusters in Cologne and Solingen sustain concentrated demand for crystalline grades that suppress sucrose recrystallization in hard candy manufacturing.
- Glycerol:A trihydric alcohol derived from triglyceride hydrolysis or petrochemical synthesis. Injectable pharmaceutical formulations in Basel and Munich drive premium-grade procurement with USP monograph certification requirements.
- Propylene Glycol:A synthetic diol meeting stringent residual solvent thresholds under REACH food-contact regulations. Beverage applications in Rotterdam and Antwerp favor this grade for its regulatory clearance in direct-consumption products.
- Maltodextrin:A partially hydrolyzed starch polymer with DE values between 5 and 20. Spray-dried encapsulation systems for volatile flavor compounds represent its fastest-climbing application vector.
Sorbitol retains volume leadership; maltodextrin holds the steepest expansion curve.
Application:
Application segmentation traces divergent formulation constraints from high-water-activity beverages to low-moisture confectionery matrices.
- Confectionery:Hard candies, chewing gums, and sugar-free lozenges require polyol blends that maintain glassy amorphous states. EFSA purity tiering for food-contact materials is accelerating technical-grade inventory replacement in French and Belgian production facilities.
- Dairy:Ice cream and frozen dessert formulations leverage cryoprotectant properties to control ice crystal growth during thermal cycling. Scandinavian dairy cooperatives specify low-ash sorbitol grades for premium frozen yogurt lines.
- Bakery:Moisture retention in soft breads and extended shelf-life cakes depends on humectant selection balanced against Maillard reaction interference. North American industrial bakeries favor corn-derived polyol portfolios with direct supplier relationships.
- Beverages:Clear liquid formulations and concentrated syrups demand complete solubility without haze formation. Japanese functional drink manufacturers exploit FOSHU regulatory pathways to feature sugar alcohol content in digestive tolerance claims.
Confectionery commands the largest share of polyol consumption; beverages are climbing fastest on pharmaceutical-grade glycerol uptake.
End User:
End-user categories separate commodity-scale food operations from certification-intensive pharmaceutical and cosmetic formulations.
- Food Manufacturers:Industrial bakeries, confectionery compounders, and dairy processors procuring technical and food-grade polyols at volume scale. German chocolate coating applications bear the steepest reformulation costs from REACH residual solvent updates.
- Pharmaceutical Companies:Parenteral drug and biologic manufacturers requiring USP and EP injectable monograph certification with batch-specific elemental impurity documentation. CDSCO alignment with ICH Q3D guidelines is opening qualification pathways in Mumbai and Hyderabad clusters.
- Cosmetic Producers:Emulsion formulators preventing phase separation in creams and lotions through humectant stabilization. Korean skincare manufacturers specify low-irritant propylene glycol grades for sensitive-skin product lines.
- Nutraceutical Firms:Dietary supplement and functional food developers incorporating anti-crystallizing agents into gummy matrices and powder blends. Direct-to-consumer brands are compressing supplier margins through consolidated procurement platforms.
Food manufacturers absorb the greatest tonnage; pharmaceutical companies extract the highest margin premiums.
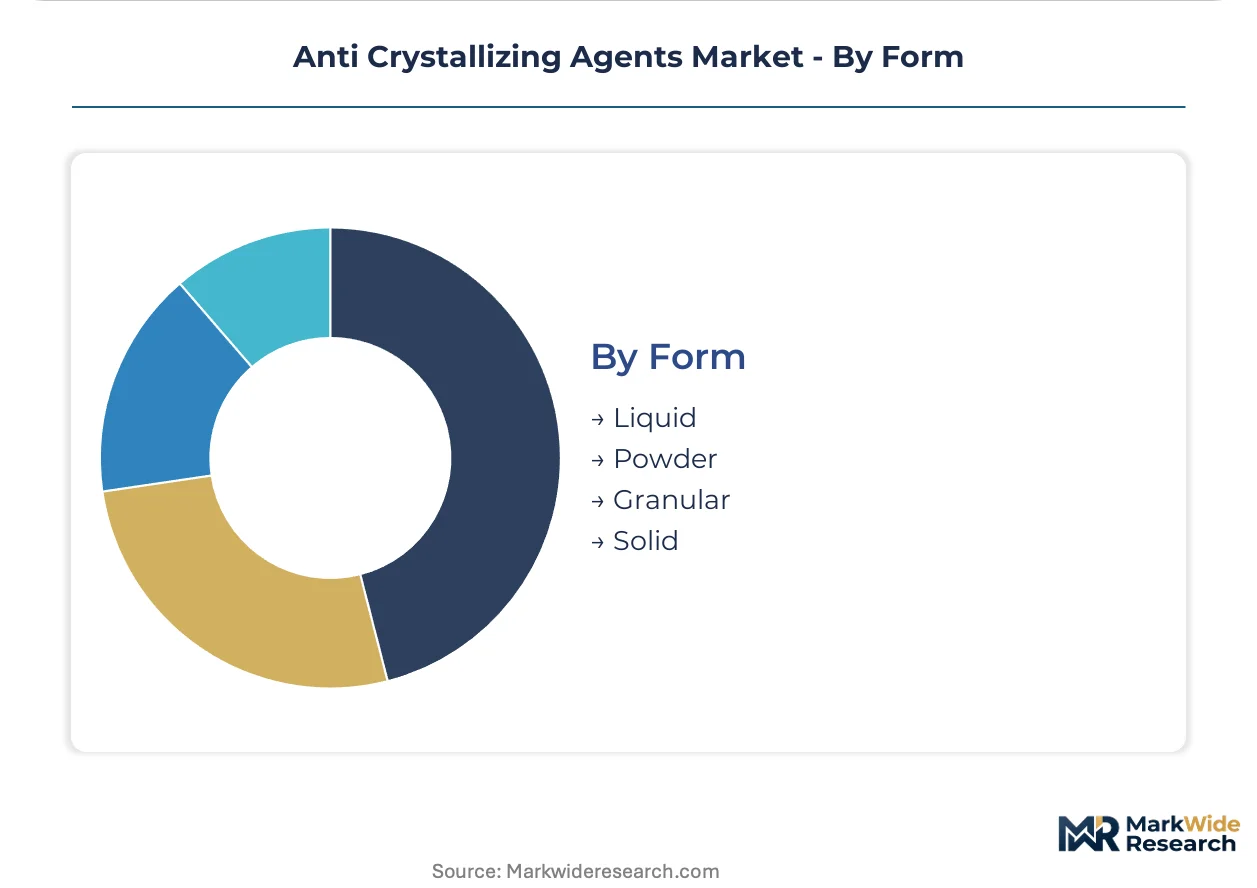
Form:
Physical form selection hinges on processing equipment compatibility, dissolution kinetics, and storage stability requirements.
- Liquid:Pumpable polyol solutions preferred in continuous manufacturing lines and automated dosing systems. Beverage concentrate producers in the Netherlands favor liquid glycerol for blending efficiency.
- Powder:Spray-dried or milled particulates enabling precise dry-blending in bakery premixes and powdered drink formulations. Indian excipient suppliers are expanding spray-drying capacity for amorphous solid dispersion applications.
- Granular:Free-flowing agglomerates with reduced dusting and improved handling characteristics. Confectionery compounders in Switzerland specify granular sorbitol for hard candy cooking operations.
- Solid:Crystalline or compressed blocks for specialized pharmaceutical tableting and direct compression processes. Japanese tablet manufacturers require specific particle size distributions for uniform disintegration.
Liquid forms dominate beverage and pharmaceutical processing; powder forms are gaining fastest on spray-drying technology diffusion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH purity tiering for food-contact polyols anchors European procurement patterns, while FDA food additive regulations under 21 CFR govern permissible intake thresholds in the United States. CDSCO alignment with ICH Q3D guidelines is reshaping excipient qualification pathways in India.
Germany
Confectionery manufacturing clusters in Cologne and Solingen sustain concentrated demand for crystalline sorbitol grades that suppress sucrose recrystallization in hard candy production. EFSA evaluates novel polyol submissions under updated Novel Food guidance, tightening contaminant thresholds below 10 ppm for certain process residuals. BASF leverages its Ludwigshafen integrated site to sustain captive supply of high-purity sorbitol for European confectionery clients.
United States
North American industrial bakeries favor corn-derived polyol portfolios with direct supplier relationships for moisture retention in soft breads and extended shelf-life cakes. FDA regulations under 21 CFR govern permissible daily intake thresholds for sorbitol and glycerol in processed foods. Cargill anchors regional demand through its corn-derived polyol portfolio and direct relationships with bakery manufacturers.
India
Pharmaceutical formulation clusters in Mumbai and Hyderabad are displacing informal supply channels as CDSCO aligns with ICH Q3D guidelines for elemental impurities. The national pharmaceutical regulator now mandates batch-specific certificates of analysis with elemental impurity data rather than accepting standard COA templates. Generic drug manufacturers are adopting spray-drying equipment at twice the previous rate to access amorphous solid dispersion technology.
China
Chemical intermediate capacity is tilting toward food-grade polyol derivatives that serve anti-crystallizing applications in processed food exports. SAMR oversight of food-contact materials shapes supplier qualification timelines for domestic and export markets. Shandong-based producers are expanding spray-drying capacity to serve Indian pharmaceutical excipient qualification openings.
Japan
Functional drink manufacturers exploit FOSHU regulatory pathways to feature sugar alcohol content in digestive tolerance claims. PMDA pharmaceutical-grade monographs govern injectable formulation purity specifications for biologic stability applications. Tablet manufacturers in Kanto require specific particle size distributions for uniform disintegration in direct compression processes.
Anti Crystallizing Agents Market Competitive Environment
Integrated polyol manufacturers and specialty chemical houses split the market along certification-grade boundaries. Pharmaceutical-grade purity specifications are compressing supplier margins while concentrating procurement among players capable of certifying to USP and EP injectable monographs. This regulatory ratchet forces mid-scale humectant producers toward food-grade applications or exit. Dominant competitive moves include backward integration into captive hydrogenation capacity and geographic expansion to serve CDSCO-aligned qualification pathways in Mumbai and Hyderabad.
Within the integrated-manufacturer tier, BASF and Cargill exemplify divergent feedstock strategies. BASF represents petrochemical-sourced propylene glycol and synthetic polyol production anchored at Ludwigshafen. Cargill occupies a position defined by agricultural feedstock integration, with corn-derived sorbitol and polyol portfolios reflecting North American grain belt proximity. Evonik sits within the specialty-grade segment, competing on propylene glycol grades designed for pharmaceutical stability applications where residual solvent thresholds command premium positioning.
| Leading Market Players |
|---|
| BASF |
| Cargill |
| Roquette |
| Fine Organics |
| Nikko Chemicals |
| Shandong Futaste |
| Evonik |
| Croda International |
| Lubrizol Corporation |
| Others |
Value Chain & Pricing Dynamics
Rotterdam-Antwerp barge freight corridors transmit cost volatility from petrochemical feedstock hubs directly into polyol pricing spreads, compressing margins for non-integrated compounders while amplifying differentiation between pharmaceutical-grade and technical-grade tiers.
Pricing Analysis
Geographic price spreads between Ludwigshafen-sourced pharmaceutical-grade sorbitol and technical-grade alternatives from Shandong producers exceed threefold multiples, reflecting certification burden disparities. Pricing stratifies across USP/EP-certified premium tiers, food-grade standard tiers, and technical-grade economy levels. Cost compression in technical-grade segments is intensifying because REACH residual solvent thresholds are forcing catalyst system upgrades. Pharmaceutical companies exhibit lowest price sensitivity due to biologic stability mandates; confectionery compounders face highest sensitivity as clean-label reformulation absorbs reformulation costs.
Supply Chain Analysis
Upstream corn glucose and propylene oxide feedstock availability anchors supply concentration in the United States, Germany, and China. Hydrogenation catalysts, vegetable oil triglycerides, and steam cracker derivatives constitute critical input dependencies. Single-source vulnerability persists for pharmaceutical-grade propylene glycol routed through Ludwigshafen and Rotterdam. Distribution runs through direct manufacturer-to-formulator relationships for certified grades, with regional distributors retained only for technical-tier volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities in this market center on batch-specific analytical certification and elemental impurity documentation, recurring-revenue layers expanding faster than base polyol volumes as pharmaceutical procurement teams eliminate standard COA acceptance.
For Market Incumbents: Harden defensibility through captive hydrogenation capacity investments in Rhine corridor production sites and accelerated USP monograph revalidation cycles that mid-scale competitors cannot match. Regulatory ratchet effects from 18-month pharmacopeial update cycles threaten laggards with disqualification from injectable formulation supply chains. Backward integration into corn glucose refining secures margin control against agricultural commodity swings. For New Entrants and Emerging Players: Build out spray-drying capabilities targeting Indian pharmaceutical excipient qualification openings as CDSCO ICH Q3D alignment displaces informal Mumbai and Hyderabad supply channels. White-space concentration appears in cell culture media cryoprotectants for CAR-T manufacturing and FOSHU-positioned functional confectionery in Japan. A certification-first go-to-market approach bypasses volume competition with integrated agricultural processors. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with orphaned humectant divisions lacking pharmaceutical-grade certification infrastructure. Long-term viability favors assets with demonstrated USP/EP injectable monograph compliance and established relationships with parenteral drug manufacturers in Basel and Munich clusters. Watch for CDSCO enforcement actions against uncertified Indian excipient suppliers as inflection signal for qualification-driven consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hydrogenation Capacity | Captive catalyst systems at Ludwigshafen and Rotterdam sites eliminate nickel contamination risk from tolling arrangements. |
| Pharmaceutical-Grade Certification Investment | USP and EP injectable monograph compliance opens access to biologic formulation stability mandates in Basel and Munich. |
| Geographic Expansion to Indian Excipient Qualification | CDSCO ICH Q3D alignment creates displacement opportunity for certified producers in Mumbai and Hyderabad clusters. |
| Long-Term Supply Agreement with Confectionery Manufacturers | Direct relationships with Cologne and Solingen hard candy producers lock in crystalline sorbitol offtake against technical-grade competition. |
| Green Manufacturing Transition to Palladium Catalyst Systems | Supported palladium hydrogenation meets REACH residual solvent thresholds for Dutch and Belgian chocolate coating applications. |
Study Parameters
Initial hypotheses were tested against primary input from pharmaceutical formulation scientists, confectionery compounder procurement leads, hydrogenation plant managers, and regulatory affairs specialists at polyol manufacturers, then refined against customs trade data, ECHA registration dossiers, FDA food additive petitions, USP monograph update notices, and SEC filings from integrated agricultural processors. Bottom-up volume builds across grade tiers and end-use segments were triangulated against top-down capacity assessments from major production hubs.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation modeled by product chemistry, purity grade tier, end-use industry, physical form, and regional regulatory cluster. CAGRs were derived from slope analysis of segment-specific volume trajectories, incorporating biologic formulation pipeline data, confectionery clean-label reformulation announcements, and REACH restriction entry timelines as industry-specific inputs.
Stress conditions across feedstock cost volatility, pharmacopeial certification timeline compression, and regulatory enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about CDSCO alignment completion, EFSA Novel Food evaluation pacing, and USP/EP monograph update adoption rates. Cross-checking against ECHA registration statistics and Indian pharmaceutical import data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Americas Coating Additives Market
Additives
LAMEA Driveline Additives Market
Additives
Global Scale Inhibitors Market
Additives
Global Anti-Fog Additives Market
Additives
Calcium Acetate Market
Additives
Feedstuff Additives Market
Additives
Butyrate Additives Market
Additives
Europe Choline Chloride Market
Additives
Competitive Inhibitors Market
Additives
Foundry Additives Market
Additives
Low Melt Inclusions Market
Additives
Battery Additives Market
Additives
Global Butylated Hydroxytoluene Market
Additives
Nucleating and Clarifying Agents Market
Additives
Trioctyldodecyl Citrate Market
Additives
Sodium Benzoate Market