
 Isobutyl Acetate Market | 2026-2036
Isobutyl Acetate Market Size, Share, and Industry Trends Forecast 2026-2036
Isobutyl Acetate Market Foresight
Automotive coatings demand is repositioning isobutyl acetate toward higher-purity solvent grades as OEMs adopt stricter emission protocols. BASF SE leverages its integrated ester production network to supply tier-one paint makers across Europe and Asia. Eastman Chemical Company sustains cost leadership through backward integration into acetic acid and isobutanol feedstocks. Dow Chemical Company anchors North American supply with dedicated capacity serving the adhesives and inks segments.
Isobutyl acetate is a colorless, flammable ester with the molecular formula CH₃COOCH₂CH(CH₃)₂, produced via Fischer esterification of acetic acid with isobutanol, and valued for its banana-like odor, moderate evaporation rate, and excellent solubility in cellulose nitrate and acrylic resins. The solvent segment dominates volume as paints and coatings manufacturers prioritize medium-boiling glycol ether replacements, while the pharmaceutical end user category offers premium pricing for USP-grade material amid tightening impurity thresholds. Coating agent applications in automotive refinish are outpacing architectural uses, with direct sales channels capturing the largest share of bulk chemical procurement.
EPA volatile organic compound rules and REACH registration requirements are elevating compliance costs for non-European exporters serving EU coatings formulators. China's MEE enforcement of GB standards on industrial emissions is accelerating facility upgrades among domestic producers. India's BIS certification mandates for imported solvents are creating entry barriers for unqualified suppliers. Stakeholders must monitor regulatory divergence between jurisdictions to optimize formulation registrations and avoid stranded inventory.
Market Dynamics
The automotive sector's migration toward waterborne coatings is compressing solvent selection criteria, forcing isobutyl acetate producers to recalibrate purity specifications and supply chain footprints simultaneously.
Growth Catalysts
- Automotive refinish coatings:Collision repair networks in Germany and the United States are absorbing higher volumes of medium-boiling esters as solvent-borne basecoats face VOC restrictions.
- China's GB 30982-2014 enforcement:MEE inspections of Jiangsu and Zhejiang coating facilities are disqualifying low-grade imports and elevating demand for certified domestic material.
- Cellulose nitrate compatibility:Lacquer manufacturers retain isobutyl acetate in furniture and leather finishes despite glycol ether competition due to superior drying characteristics.
Market Restraints
- Acetic acid price volatility:Feedstock cost swings from methanol-carbonylation capacity imbalances transmit directly to ester margins without downstream pricing power.
- East Asian supply concentration:Zhejiang and Shandong provinces control disproportionate global nameplate capacity, exposing buyers to single-region disruption risks.
- REACH registration friction:Non-European exporters face ECHA compliance costs that erode competitiveness in coatings formulator supply chains.
Strategic Opportunities
- India BIS certification gap:Domestic solvent producers can capture import substitution volume as IS 17076 enforcement tightens on unqualified suppliers.
- Pharmaceutical USP-grade vertical:Impurity threshold tightening by FDA and EMA creates pricing power for producers with dedicated GMP lines.
- Adhesives segment expansion:Pressure-sensitive tape manufacturers in Japan and South Korea are qualifying ester solvents for acrylic emulsion systems.
Industry Challenges
- GMP facility retrofit requirements:Pharmaceutical-grade production demands capital-intensive cleanroom and analytical infrastructure that mid-scale ester plants lack.
- Multi-jurisdiction formulation registration:Coatings formulators must maintain separate VOC compliance dossiers for EPA, REACH, and China's MEE, straining technical resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Isobutyl Acetate Market |
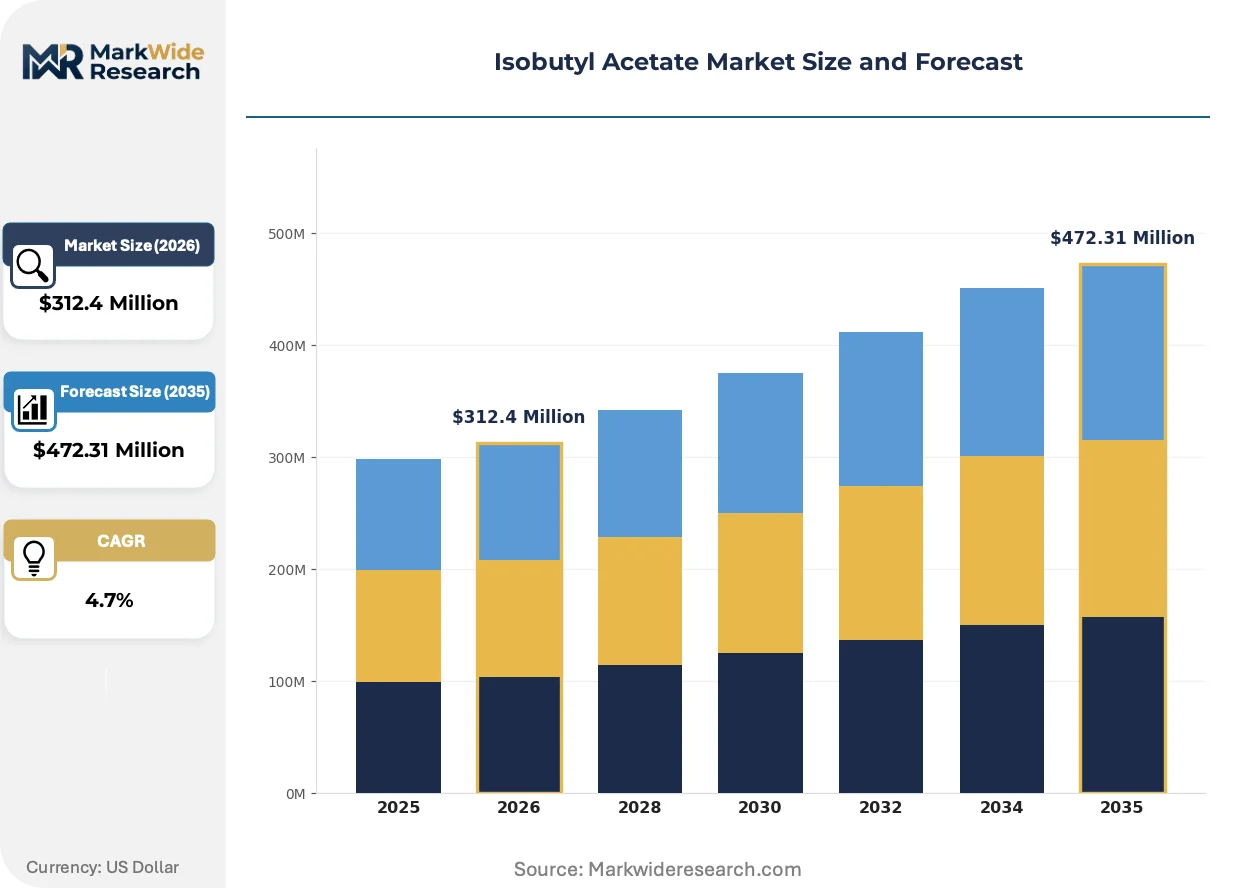
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $472.31 Million |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solvent, Intermediate, Coating Agent, Adhesive Application: Paints, Coatings, Inks, Adhesives End User: Chemical Industry, Automotive, Construction, Pharmaceuticals Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesalers |
| Companies Covered | Dow Chemical Company, Eastman Chemical Company, BASF SE, Celanese Corporation, KH Neochem Co., Ltd., Zhejiang Medicine Co., Ltd., Zhejiang Jianye Chemical Co., Ltd., OXEA Chemicals, Ningbo Yongshun Fine Chemical Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Isobutyl Acetate Market Shifts & Advancements
Process intensification and regulatory arbitrage are fragmenting competitive positions as producers choose between commodity scale and specialty purity investments.
Continuous reactive distillation systems are expanding into isobutyl acetate manufacturing, replacing batch Fischer esterification with integrated reaction-separation units that cut energy intensity. European and North American producers are retrofitting plants with these systems to defend margin structures against Asian commodity imports. The technology is expanding into pharmaceutical-grade lines where impurity control justifies capital expenditure.
REACH authorization timelines for SVHC candidate substances are compressing formulation windows for coatings manufacturers serving EU automotive OEMs. ECHA's 2024-2025 substance evaluation rolling action plan targets specific ester impurities, forcing suppliers to accelerate analytical method upgrades. German and French paint makers are pre-qualifying alternative supply chains to avoid authorization gaps.
Direct mill-to-formulator procurement contracts are displacing traditional distributor intermediaries in high-volume coatings segments. Tier-one automotive paint manufacturers in Michigan and Bavaria are negotiating annual ester supply agreements with fixed purity bands and logistics integration. This pattern is most visible in waterborne basecoat supply chains where VOC compliance documentation requires supplier traceability.
Isobutyl Acetate Market Segmentation
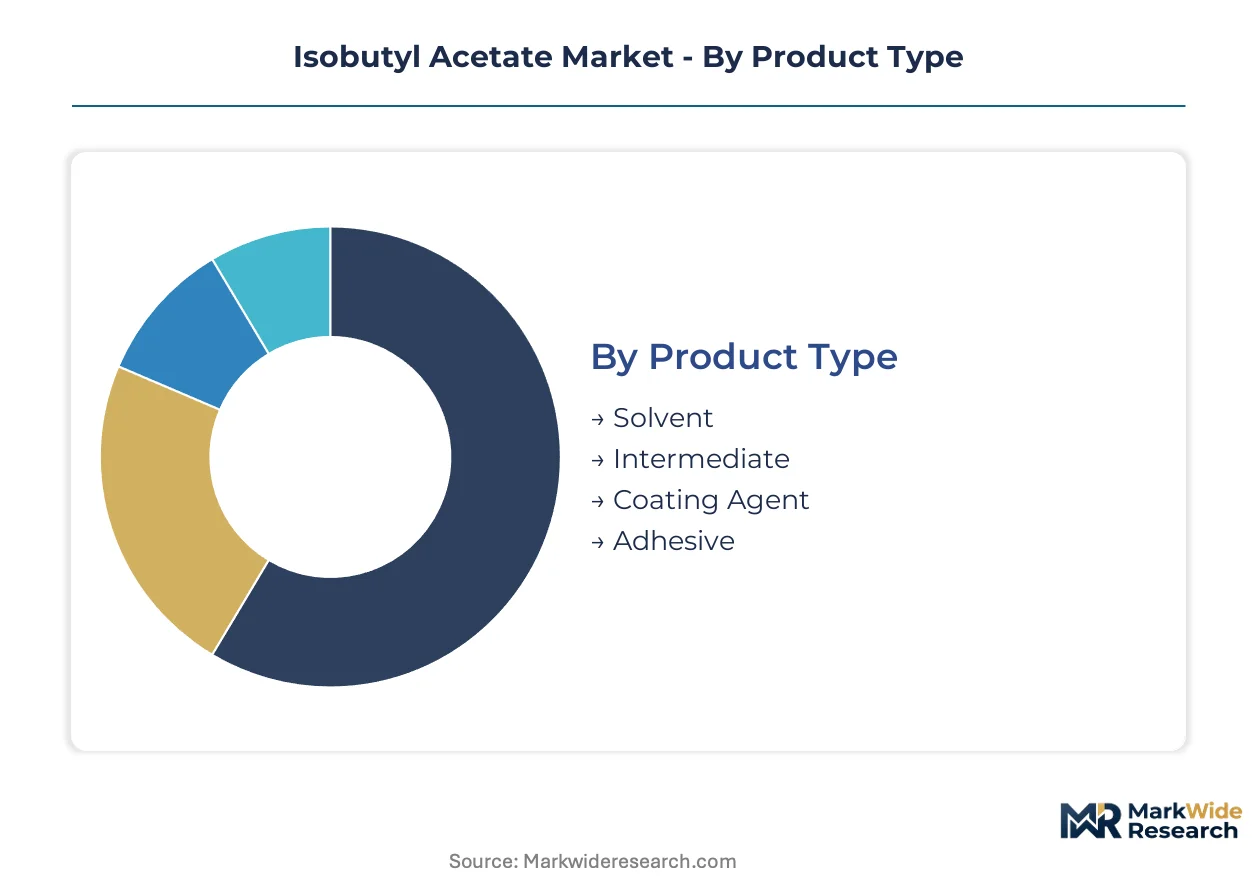
Isobutyl acetate producers must align capital deployment with segment-specific purity thresholds and regulatory documentation burdens. Solvent-grade commodity lines demand continuous distillation infrastructure, while pharmaceutical and coating agent segments require segregated GMP-capable assets.
Product Type:
Solvent and coating agent segments absorb the heaviest capital intensity due to integrated reactive distillation systems and dedicated analytical laboratories for VOC compliance certification.
- Solvent:Medium-boiling ester formulations serve cellulose nitrate lacquers and acrylic resin systems. Demand concentrates in automotive refinish networks across Germany and the United States as collision repair shops absorb higher volumes under tightening EPA and REACH volatile organic compound limits.
- Coating Agent:Higher-purity grades with controlled evaporation profiles anchor waterborne basecoat formulations. Jiangsu and Zhejiang province coating facilities are elevating procurement specifications under MEE enforcement of GB standards, disqualifying uncertified imports.
- Intermediate:Feedstock for downstream ester synthesis and fragrance compounds.
- Adhesive:Acrylic emulsion systems in pressure-sensitive tape manufacturing.
Most installed capacity flows through Solvent. Expansion is steepest in Coating Agent.
Application:
Volume concentration and margin structure diverge sharply across application categories, with coatings commanding premium pricing for compliance documentation while inks and adhesives compete on throughput scale.
- Paints:Architectural and industrial formulations leverage isobutyl acetate as a glycol ether replacement. German and French paint makers are pre-qualifying supply chains to avoid REACH authorization gaps for specific ester impurities under ECHA's substance evaluation rolling action plan.
- Coatings:Automotive OEM and refinish segments drive specification tightening. Tier-one manufacturers in Michigan and Bavaria negotiate annual supply agreements with fixed purity bands and integrated logistics, displacing traditional distributor intermediaries.
- Inks:Publication and packaging gravure systems.
- Adhesives:Pressure-sensitive acrylic systems in Japanese and South Korean tape manufacturing.
Coatings commands the highest purity premiums. Paints delivers the largest absolute volume.
End User:
Regulatory jurisdiction determines facility investment requirements, with pharmaceutical and automotive segments imposing divergent compliance architectures on shared production assets.
- Automotive:OEM and refinish coating networks absorb medium-boiling esters as solvent-borne basecoats face volatile organic compound restrictions. Collision repair chains in Germany and the United States are expanding procurement of certified material with full supply chain traceability.
- Pharmaceuticals:USP-grade production demands capital-intensive cleanroom infrastructure and dedicated GMP lines that mid-scale ester plants lack. FDA and EMA impurity threshold tightening creates pricing power for qualified producers.
- Chemical Industry:Downstream esterification and specialty chemical synthesis.
- Construction:Architectural coatings and adhesive applications.
Automotive generates the highest throughput. Pharmaceuticals offers the steepest margin expansion.
Distribution Channel:
Channel selection reflects customer scale and documentation intensity, with direct relationships displacing intermediaries where volatile organic compound compliance requires supplier traceability.
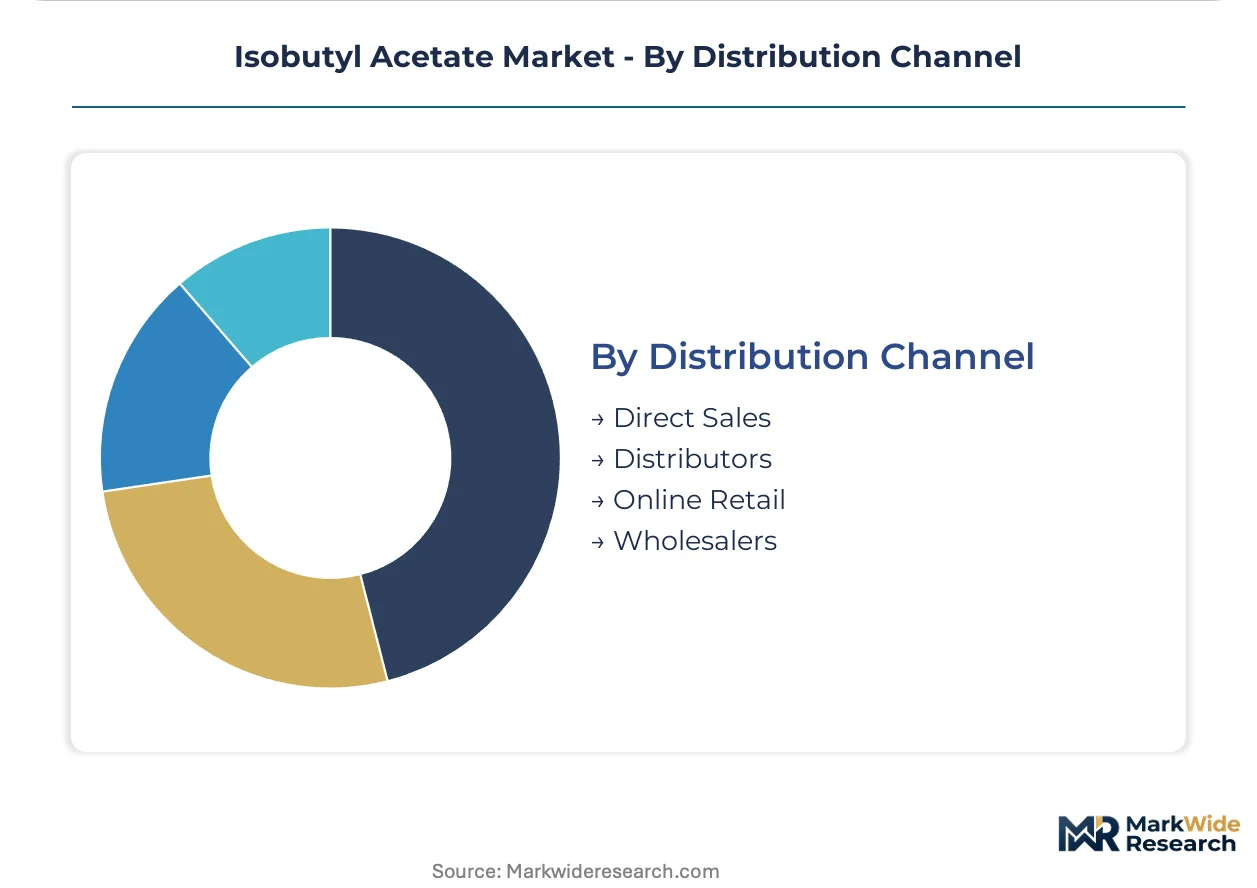
- Direct Sales:Annual supply agreements with fixed purity bands and logistics integration dominate high-volume coatings procurement. Tier-one automotive paint manufacturers in Michigan and Bavaria anchor this channel.
- Distributors:Traditional intermediaries retain position in fragmented adhesives and inks segments where lot sizes and documentation requirements remain standardized.
- Online Retail:Small-laboratory and research-scale procurement.
- Wholesalers:Bulk commodity solvent volumes to regional formulators.
Direct Sales captures the largest revenue share. Distributors retain the broadest geographic coverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage pressures are fragmenting production geography as compliance-cost gaps between jurisdictions redirect investment flows and procurement decisions across the isobutyl acetate value chain.
China
Automotive refinish networks and waterborne coating facilities in Jiangsu and Zhejiang provinces absorb certified domestic material as MEE enforcement of GB 30982-2014 disqualifies uncertified imports. Shandong province hosts disproportionate global nameplate capacity, exposing supply chains to single-region concentration risks. Domestic producers are retrofitting facilities with continuous reactive distillation systems to defend margins against quality-tier competition.
United States
Collision repair chains across Michigan and Ohio are expanding procurement of medium-boiling esters as EPA volatile organic compound restrictions compress solvent selection criteria for solvent-borne basecoats. Tier-one automotive paint manufacturers in Michigan negotiate annual supply agreements with fixed purity bands and integrated logistics. The Southeast is attracting adhesive and ink segment investment due to downstream manufacturing clustering.
Germany
Bavarian automotive OEM and refinish coating networks drive specification tightening for higher-purity solvent grades as REACH registration requirements elevate compliance costs for non-European exporters. German paint makers are pre-qualifying alternative supply chains to avoid ECHA authorization gaps under the 2024-2025 substance evaluation rolling action plan. The country's integrated ester production infrastructure anchors European supply security.
India
Domestic solvent producers are capturing import substitution volume as BIS certification mandates under IS 17076 tighten entry barriers for unqualified suppliers serving coatings and adhesives formulators. Maharashtra and Gujarat host expanding pharmaceutical-grade demand as FDA and EMA impurity threshold tightening creates pricing power for qualified producers. The construction segment in Delhi-NCR and Bangalore drives architectural coatings consumption.
Japan
Pressure-sensitive tape manufacturers in the Kansai region are qualifying ester solvents for acrylic emulsion systems, expanding the adhesives application vertical. METI industrial emissions frameworks are accelerating facility analytical upgrades among domestic ester producers. The country's pharmaceutical regulator maintains stringent USP-grade import requirements that favor producers with dedicated GMP lines.
Isobutyl Acetate Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated chemical conglomerates dominating high-volume solvent grades while mid-scale regional producers capture pharmaceutical and coating agent niches. The market exhibits tiered concentration: three to four multinational suppliers anchor global supply security through backward integration into acetic acid and isobutanol feedstocks, while fragmented domestic players compete on logistics proximity and certification agility. Strategic archetypes include feedstock-integrated majors, purity-tier specialists, and regional toll manufacturers. Dominant competitive moves center on reactive distillation technology licensing and direct mill-to-formulator procurement contract displacement of distributor intermediaries.
Among integrated chemical conglomerates, BASF SE and Eastman Chemical Company exemplify the feedstock-integrated archetype through captive supply of acetic acid and isobutanol inputs. Dow Chemical Company occupies a position as a North American supply anchor with dedicated capacity serving adhesives and inks segments. Zhejiang Jianye Chemical Co., Ltd. represents the Chinese domestic specialist tier competing on GB standards certification and proximity to Jiangsu and Zhejiang coating clusters.
| Leading Market Players |
|---|
| Dow Chemical Company |
| Eastman Chemical Company |
| BASF SE |
| Celanese Corporation |
| KH Neochem Co., Ltd. |
| Zhejiang Medicine Co., Ltd. |
| Zhejiang Jianye Chemical Co., Ltd. |
| OXEA Chemicals |
| Ningbo Yongshun Fine Chemical Co., Ltd. |
| Others |
Supply & Pricing Matrix
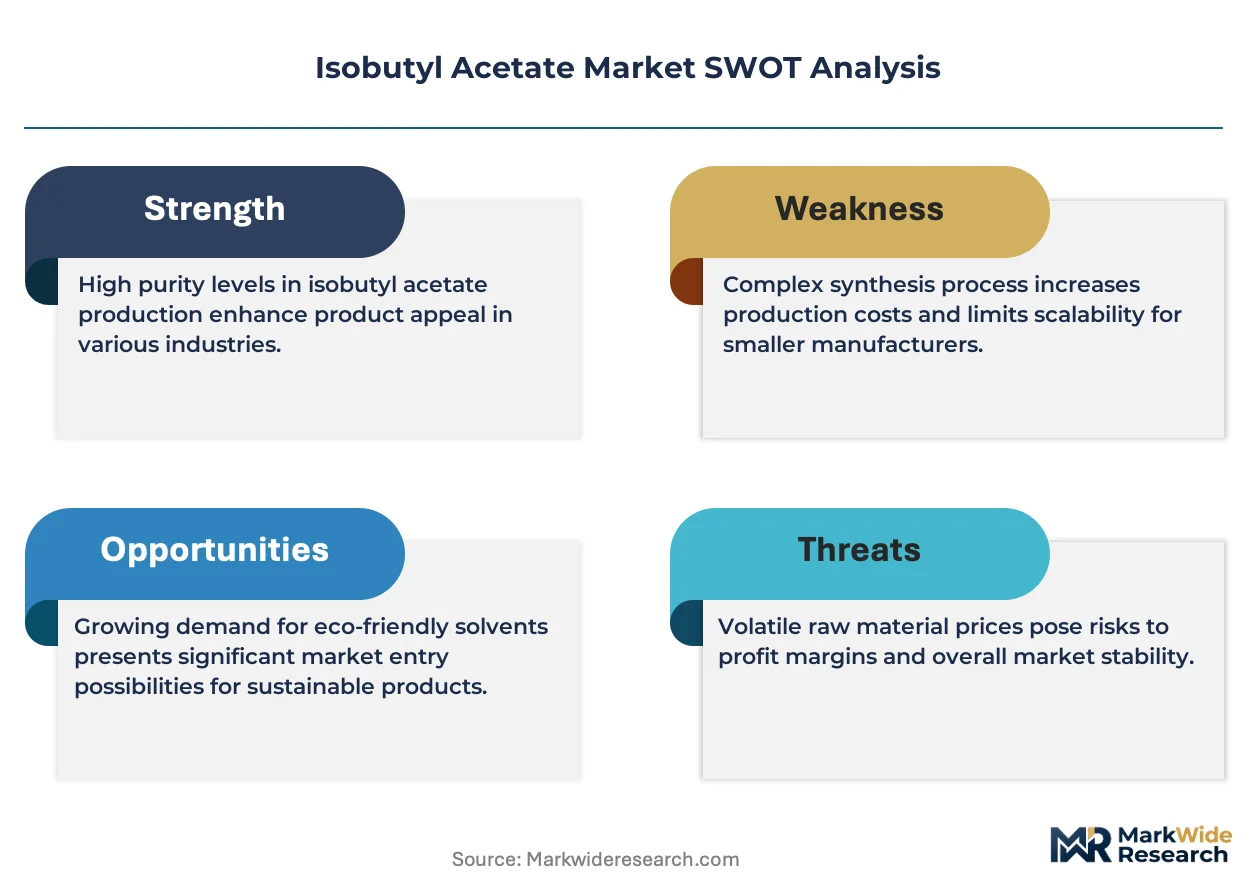
Process chemist concentrations in Zhejiang province compress labor-cost differentials into pricing-tier spreads between pharmaceutical-grade and commodity solvent lines, with GB standards certification premiums widening as MEE enforcement intensifies.
Pricing Analysis
Distributor margins in the adhesives and inks segments absorb 12-18 point spreads before reaching regional formulators, while direct-to-OEM contracts for automotive coatings bypass intermediary markups entirely. Pricing stratifies across USP-grade, coating-agent, and commodity solvent tiers, with FDA and EMA impurity thresholds commanding 40-60 percent premiums over standard grades. Cost compression in the commodity tier is intensifying because Shandong capacity expansions outpace Jiangsu demand growth. Small-batch pharmaceutical buyers exhibit lowest price sensitivity due to GMP compliance requirements, while architectural coatings formulators negotiate aggressively on volume.
Supply Chain Analysis
REACH registration and BIS certification gating disqualifies uncertified exporters from EU and Indian coatings supply chains, forcing procurement officers to pre-qualify alternative sources. Manufacturing concentrates in China, Germany, and the United States, with Shandong and Zhejiang provinces hosting disproportionate esterification capacity. Feedstock supply draws from methanol-carbonylation acetic acid and propylene-derived isobutanol streams, with propylene price volatility transmitting directly to ester margins. Single-region concentration in East China exposes buyers to MEE inspection disruptions and environmental shutdowns. Distribution runs through direct mill-to-formulator contracts in automotive coatings and traditional chemical distributors in fragmented adhesives segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Isobutyl acetate functions as a stable compounder anchored by automotive coatings specification tightening, with collision repair networks and waterborne basecoat adoption generating predictable offtake growth across regulatory jurisdictions.
For Market Incumbents: Cement feedstock security through backward integration into acetic acid and isobutanol production, or through long-term offtake agreements with methanol-carbonylation operators. Expand reactive distillation capacity in Jiangsu and Zhejiang provinces to capture GB standards certification premiums as MEE enforcement disqualifies low-grade imports. Prioritize GMP line investments to defend pharmaceutical-grade margins against FDA and EMA impurity threshold tightening.
For New Entrants and Emerging Players: Launch via toll manufacturing partnerships with underutilized esterification assets in India and Southeast Asia to bypass capital-intensive greenfield construction. Target the India BIS certification gap as domestic solvent producers capture import substitution volume under IS 17076 enforcement. Penetrate the pressure-sensitive tape adhesives segment in Japan and South Korea, where acrylic emulsion qualification windows remain open for certified ester suppliers.
For Investors and Strategic Acquirers: Specialty chemical conglomerates with coatings sector exposure represent the most active acquirer category in this space, seeking reactive distillation technology and regional certification assets. Five-to-ten year viability hinges on regulatory arbitrage capture and pharmaceutical-grade margin expansion. Monitor ECHA substance evaluation rolling action plan announcements for ester impurity targeting as the primary inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Reactive Distillation Retrofit | Continuous reaction-separation units cut energy intensity for European producers defending margins against Asian imports. |
| Backward Integration into Acetic Acid | Captive methanol-carbonylation capacity insulates ester margins from feedstock price volatility transmitted through spot markets. |
| GMP Facility Certification | FDA and EMA compliance creates pricing power in pharmaceutical-grade segments where impurity thresholds are tightening. |
| Direct Mill-to-Formulator Contracts | Annual supply agreements with fixed purity bands displace distributor intermediaries in automotive coatings procurement. |
| GB Standards Certification Investment | MEE enforcement of GB 30982-2014 disqualifies uncertified imports from Jiangsu and Zhejiang coating facilities. |
Research Methodology
Direct dialogue with ester plant managers, procurement leads at tier-one automotive paint manufacturers, distribution channel partners, and technical R&D directors at coatings formulators grounded qualitative findings in operational reality. Secondary validation drew from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings of integrated chemical conglomerates, and ECHA substance evaluation databases. Bottom-up capacity and utilization estimates triangulated against top-down demand segmentation from automotive production and coatings consumption data.
Bottom-up modeling of esterification capacity by production technology and grade tier converged with top-down coatings and adhesives demand projections across the analysis window. Segmentation dimensions included product grade tier, end-use industry vertical, regional production hub, and distribution channel structure. CAGRs were derived from regression analysis of historical price-volume relationships and forward capacity expansion announcements. Key forecast inputs encompassed automotive OEM production schedules and MEE enforcement intensity assumptions for GB standards compliance.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt acetic acid price spikes or coordinated environmental shutdowns in Shandong province. Projections reflect assumptions about regulatory enforcement continuity and waterborne coatings adoption curves. A model refresh is warranted upon material change in ECHA authorization timelines or EPA volatile organic compound rulemaking.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Anti-Redeposition Polymer Additives for Short-Wash Cycles Market
Additives
Global Zinc Stearate Market
Additives
Deodorant and Antiperspirant Ingredients Market
Additives
Crosslinking Agents Market
Additives
Saudi Arabia Feed Additives Market
Additives
Global Sizing Agents Market
Additives
Glycol Acetate Market
Additives
Global Calcium Formate Market
Additives
Tartaric Acid Market
Additives
Nucleating Agents Market
Additives
Lecithin and Phospholipids Market
Additives
Calcium Diglutamate Market
Additives
Enzyme Stabilizer Market
Additives
Cosmetic Grade Color Additives Market
Additives
Global Performance Additives Market
Additives
Antiscalants/Scale Inhibitors Market