
 Flux Injection System Market | 2026-2036
Flux Injection System Market Size, Share, and Industry Trends Forecast 2026-2036
Flux Injection System Market Insights
ISO 9001 quality management certification is unwinding the competitive landscape for flux injection system suppliers, raising barriers for unqualified entrants. Inductotherm Group leverages its induction heating heritage to anchor furnace-integrated flux delivery platforms. Pyrotek sustains global reach through refractory and molten metal handling expertise that extends into injection system design. Otto Junker GmbH dominates European demand with specialized metallurgical equipment engineering.
A flux injection system is a precision-controlled apparatus that meters and delivers flux materials—typically chloride, fluoride, or borax-based compounds—into molten metal baths or semiconductor process chambers at temperatures exceeding 600°C to remove oxides and improve material purity. The system regulates injection velocity, particle size distribution, and thermal profile to optimize chemical reaction kinetics. Pneumatic flux injectors lead installed base volumes due to proven reliability in aluminum smelting and secondary steelmaking, though electromagnetic injection technology is displacing conventional methods in semiconductor cleanroom environments where particulate contamination must stay below Class 100 thresholds. Hybrid flux injectors are capturing margin pools at the premium tier by combining pressure modulation with thermal management for multi-stage process control.
China's SAMR enforces GB standards on industrial equipment safety that dictate flux injection system pressure vessel ratings and electrical isolation requirements. The EU's REACH regulation governs chemical composition disclosures for flux materials, while RoHS restricts heavy metal content in system electronics. Japan's METI promotes JIS-compliant energy efficiency benchmarks that shape procurement criteria for domestic foundries. Stakeholders must monitor how divergent chemical registration regimes between Asia-Pacific and European jurisdictions will reshape supplier certification burdens and equipment qualification timelines.
Market Dynamics
Semiconductor foundries in Taiwan and South Korea are driving capacity expansion for flux injection systems as advanced node production below 5nm demands ultra-high-purity flux chemistries. This demand concentration is compressing supplier qualification timelines and reshaping equipment specifications across the value chain.
Growth Catalysts
- EU RoHS hazardous substance restrictions:Manufacturers are retrofitting legacy aluminum smelting lines with closed-loop flux injection systems to eliminate heavy metal contamination from process effluents.
- Secondary steelmaking revival:Electric arc furnace operators in Turkey and India are installing pneumatic flux injectors to reduce tap-to-tap times and improve slag chemistry control.
- Hsinchu-Taoyuan semiconductor corridor:Taiwan's concentrated foundry ecosystem is generating bundled procurement contracts that favor multi-chamber flux delivery platforms with predictive maintenance capabilities.
Market Restraints
- High-purity fluoride supply concentration:Chinese state-owned enterprises control 70% of metallurgical-grade fluoride precursor production, exposing non-Chinese system builders to raw material access risk.
- REACH chemical registration costs:European flux chemistry suppliers face cumulative compliance expenditures exceeding €500,000 per substance, deterring mid-tier entrants from portfolio expansion.
- Physical vapor deposition substitution:Select semiconductor applications are bypassing liquid flux chemistries entirely through dry process alternatives that eliminate contamination vectors.
Strategic Opportunities
- Vietnam's emerging electronics manufacturing:Samsung and Intel packaging facilities near Ho Chi Minh City are commissioning first-generation flux injection capacity without legacy equipment constraints.
- China's dual carbon policy framework:Provincial MEE offices are incentivizing aluminum smelters to adopt electromagnetic flux injection for energy intensity reductions aligned with 2060 neutrality targets.
- Hybrid thermal-pressure modulation:Convergence of induction heating with precision pneumatic dosing is opening premium-tier positioning for multi-stage aluminum degassing applications.
Industry Challenges
- Cleanroom certification timelines:SEMI S2 and S8 safety evaluations for semiconductor-grade flux injectors require 14-18 month validation cycles that delay revenue recognition.
- Legacy PLC integration complexity:Foundry operators in Japan's Keihin industrial belt struggle to synchronize modern flux injection controllers with 1990s-era furnace automation architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flux Injection System Market |
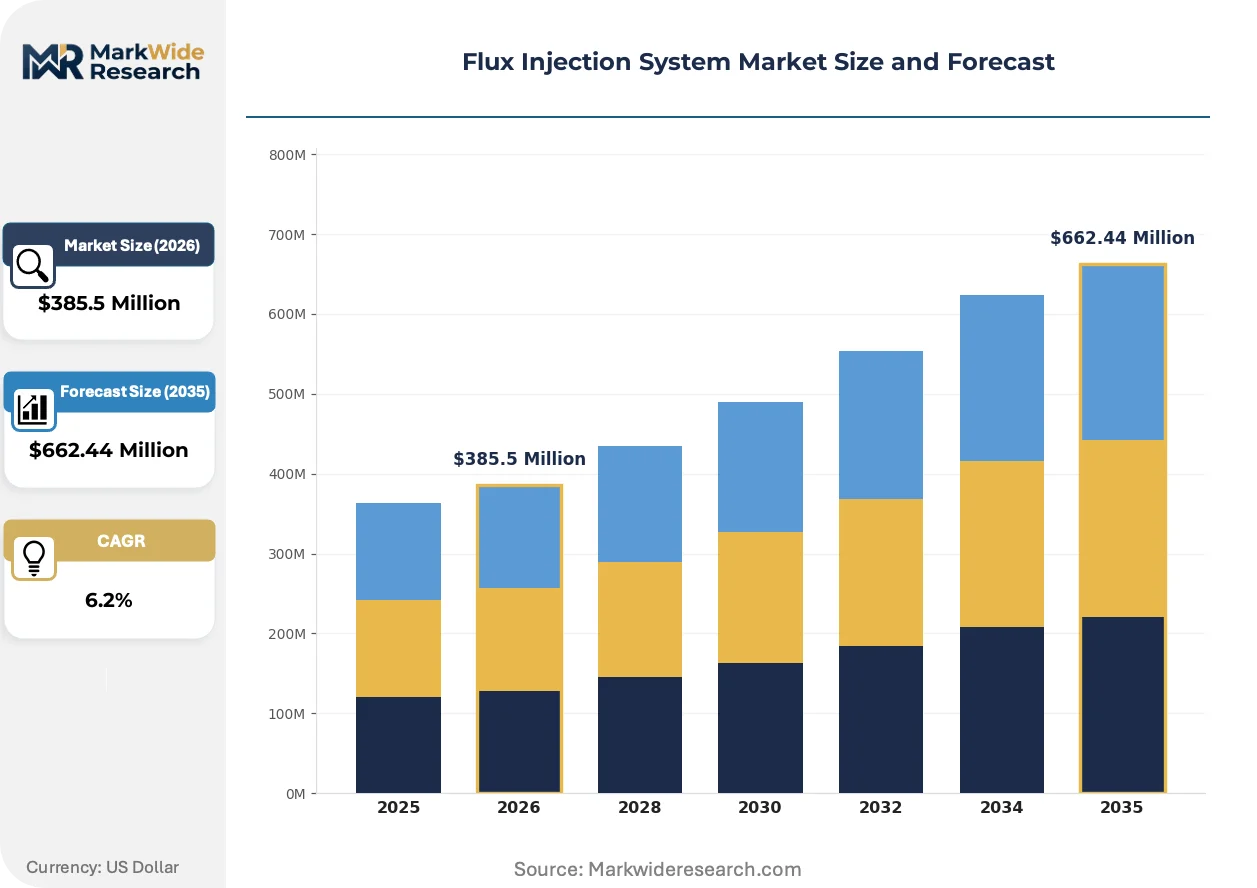
| Market Size in 2026 | $385.5 Million |
| Market Size in 2035 | $662.44 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Flux Injectors, Pneumatic Flux Injectors, Electric Flux Injectors, Hybrid Flux Injectors Technology: Electromagnetic Injection, Pressure Modulation, Thermal Management, Laser-Assisted Injection, Acoustic Wave Injection Application: Semiconductor Manufacturing, Automotive Assembly, Aerospace Fabrication, Energy Sector Equipment, Industrial Automation End User: Chip Producers, Vehicle Manufacturers, Aircraft Fabricators, Power Generation Firms, Factory Automation Providers |
| Companies Covered | Inductotherm Group, Pyrotek, Otto Junker GmbH, Sintokogio Ltd., StrikoWestofen GmbH, Foshan Hengyang Furnace Manufacturing Co., Ltd., Yizumi Holdings Co., Ltd., ABP Induction Systems GmbH, Scottish Chemical Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flux Injection System Market Trends and Innovations
Electromagnetic flux injection architectures are fragmenting established technology hierarchies as semiconductor cleanliness requirements exceed the capability boundaries of conventional pneumatic systems. Equipment specifications are diverging sharply between metallurgical and electronics-grade applications.
Electromagnetic particle acceleration technology eliminates carrier gas streams that generate particulate contamination in sub-100 nanometer process nodes. TSMC's Fab 18 in Tainan and Samsung's Pyeongtaek complex are deploying these systems for 3nm gate stack formation. This adoption pattern is fragmenting the supplier base into metallurgical-specialist and semiconductor-dedicated tiers with incompatible R&D roadmaps.
China's GB 150 pressure vessel standards are mandating revised safety interlock architectures for flux injection systems operating above 10 bar delivery pressure. SAMR enforcement inspections in Shandong and Henan provinces have accelerated replacement cycles for pre-2018 installed equipment. Aluminum smelters are responding by consolidating procurement around domestic system integrators with established GB certification track records.
After-sales service unbundling is disrupting traditional equipment-plus-maintenance bundling as foundry operators seek granular cost visibility. Korean secondary steelmakers are purchasing flux injection hardware from German suppliers while contracting predictive maintenance separately through local industrial automation specialists. This pattern is most pronounced in the Seoul metropolitan area where labor cost arbitrage favors hybrid support models.
Flux Injection System Market Segmentation
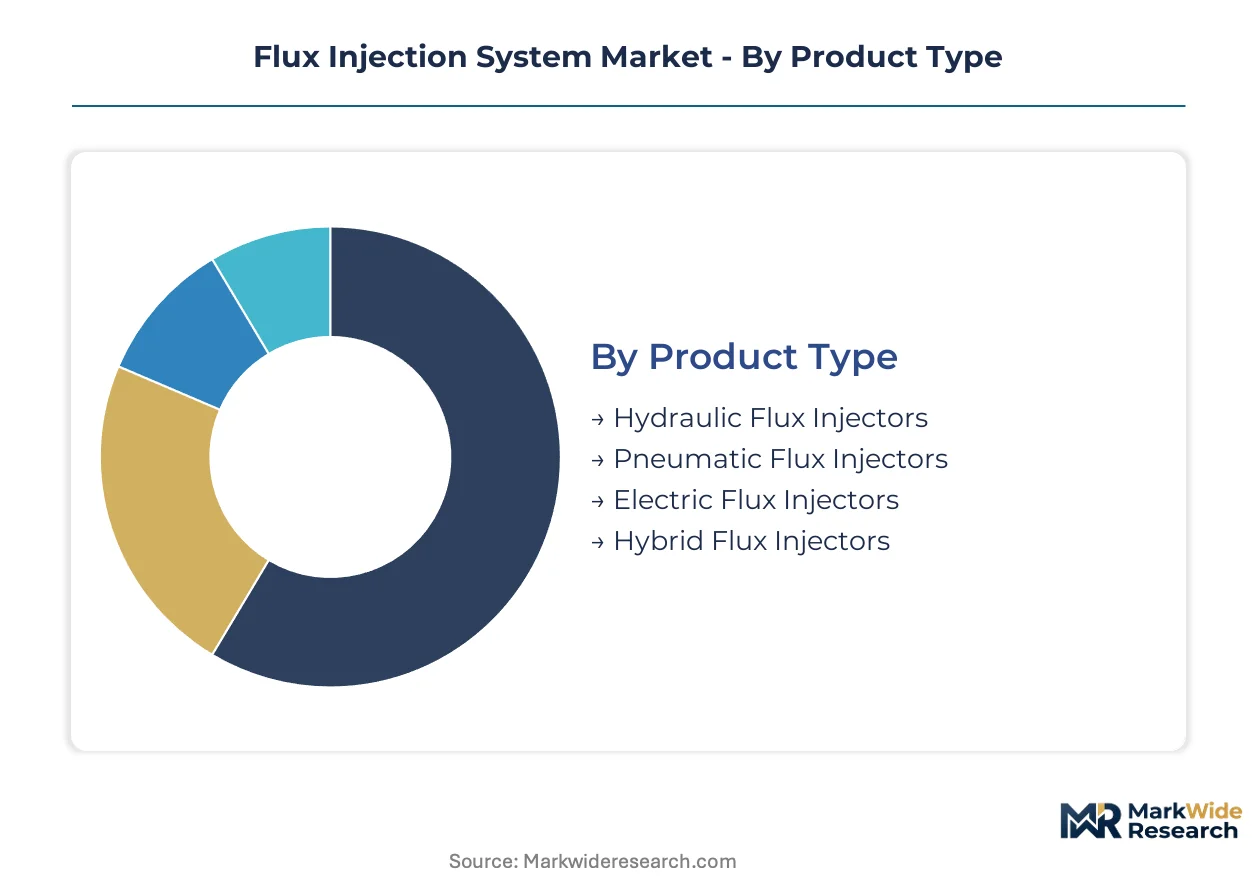
Flux injection system demand fragments sharply across metallurgical and electronics-grade specifications, with procurement patterns diverging between established industrial clusters and emerging semiconductor corridors. Understanding these segment boundaries reveals where equipment margins concentrate and which technology platforms command premium positioning.
Product Type:
Pneumatic systems anchor domestic-heavy demand in legacy aluminum and steel operations, while electric and hybrid architectures serve export-oriented semiconductor supply chains requiring cleanroom compliance.
- Pneumatic Flux Injectors:Compressed gas-driven delivery systems meter chloride and fluoride compounds into molten aluminum baths at 600-800°C with proven reliability metrics. Turkish and Indian electric arc furnace operators dominate procurement volumes as secondary steelmaking revives across Anatolia and the Deccan Plateau.
- Hybrid Flux Injectors:Converging pressure modulation with induction heating enables multi-stage thermal management for precision degassing sequences. Taiwan's Hsinchu-Taoyuan foundry corridor generates bundled procurement contracts favoring these platforms with integrated predictive maintenance modules.
- Hydraulic Flux Injectors:Fluid-powered actuation suits high-pressure aluminum smelting environments in China's Shandong province where SAMR enforces GB 150 pressure vessel compliance.
- Electric Flux Injectors:Servo-controlled precision dosing targets semiconductor wafer fabrication with particulate thresholds below Class 100.
Pneumatic flux injectors command the established base. The steepest expansion runs through hybrid thermal-pressure modulation systems.
Technology:
Cost tiers separate mature pressure-based methods from premium electromagnetic and laser-assisted platforms, with thermal management bridging mid-market positioning.
- Electromagnetic Injection:Particle acceleration via controlled magnetic fields eliminates carrier gas contamination vectors critical for sub-5nm node production. TSMC's Tainan complex and Samsung's Pyeongtaek facilities anchor demand concentration as 3nm gate stack formation requires ultra-high-purity flux delivery.
- Thermal Management:Multi-zone temperature profiling optimizes reaction kinetics for borax-based flux chemistries in secondary aluminum refining. China's provincial MEE offices under the dual carbon policy framework incentivize adoption for energy intensity reductions in Henan smelting operations.
- Pressure Modulation:Precision pneumatic dosing remains the workhorse technology for standard-grade metallurgical applications with mature installed bases.
- Laser-Assisted Injection:Directed energy beam activation enables localized flux deposition for aerospace superalloy welding sequences requiring minimal heat-affected zones.
- Acoustic Wave Injection:Ultrasonic agitation enhances particle dispersion uniformity in specialized semiconductor packaging applications.
Pressure modulation retains volume leadership across mature metallurgical segments. Electromagnetic architectures gain share fastest in cleanroom-constrained wafer fabrication.
Application:
Customer maturity levels diverge sharply: semiconductor and aerospace buyers specify predictive maintenance integration, while automotive and energy sector procurement prioritizes capital efficiency.
- Semiconductor Manufacturing:Wafer-level flux injection for die attach and underfill processes demands SEMI S2/S8 safety certification with 14-18 month validation cycles. Korea's Seoul metropolitan area and Taiwan's Tainan Science Park concentrate foundry demand for multi-chamber delivery platforms.
- Automotive Assembly:Aluminum body-in-white welding and battery tray fabrication drive flux injection for oxide removal in electric vehicle production lines. Germany's KBA vehicle type approval framework shapes equipment specifications for European OEM integration.
- Aerospace Fabrication:Titanium and nickel superalloy joining for airframe structures requires specialized thermal profiles with NADCAP accreditation.
- Energy Sector Equipment:Power turbine blade repair and nuclear component fabrication employ flux injection for crack remediation in high-temperature alloys.
- Industrial Automation:General-purpose robotic welding cells integrate flux delivery for standardized steel fabrication workflows.
Automotive assembly commands the established base. The steepest expansion runs through semiconductor manufacturing.
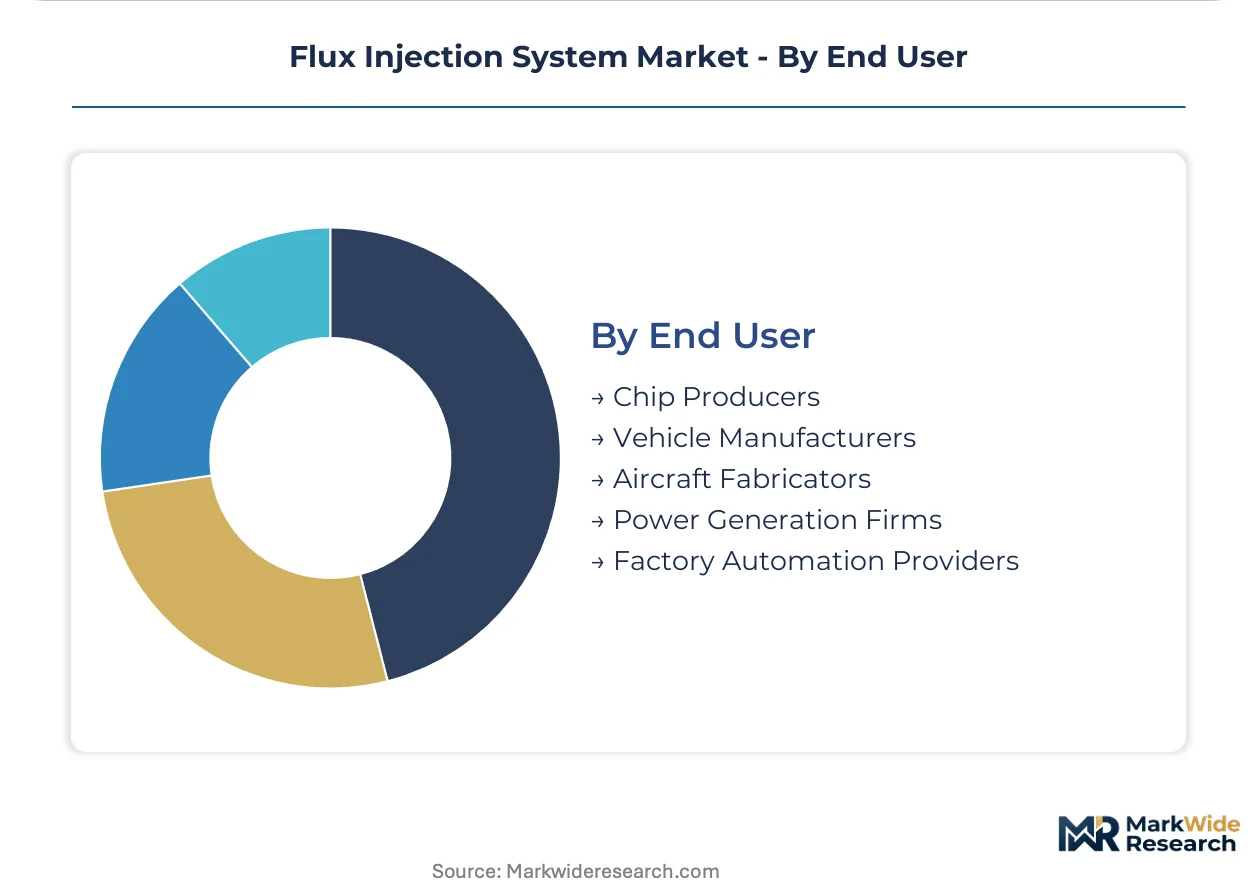
End User:
Volume concentration sits with integrated chip producers and vehicle manufacturers, while aircraft fabricators and power generation firms drive premium-tier specification development.
- Chip Producers:Foundry operators and IDMs procure Class 100-compliant systems with unbundled predictive maintenance contracts. Samsung and Intel packaging facilities near Vietnam's Ho Chi Minh City commission first-generation capacity without legacy PLC integration constraints.
- Vehicle Manufacturers:OEM aluminum casting operations and tier-1 suppliers specify pneumatic and hybrid injectors for powertrain and structural component production. Japan's Keihin industrial belt struggles with synchronization between modern controllers and 1990s-era furnace automation architectures.
- Aircraft Fabricators:Airframers and engine manufacturers demand NADCAP-accredited systems for superalloy joining with full process traceability.
- Power Generation Firms:Turbine maintenance contractors deploy portable flux injection for field repair of high-temperature components.
- Factory Automation Providers:System integrators bundle flux injection modules into turnkey robotic welding solutions for general manufacturing.
Vehicle manufacturers command the established base. The steepest expansion runs through chip producers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's dual carbon policy framework is accelerating electromagnetic flux injection adoption in provincial aluminum smelting operations. Taiwan's foundry ecosystem and South Korea's semiconductor corridor are compressing supplier qualification timelines for ultra-high-purity systems. Germany's KBA vehicle approval standards and Turkey's secondary steelmaking revival are reshaping equipment specifications across metallurgical applications.
China
Provincial MEE offices under dual carbon targets incentivize electromagnetic flux injection for energy intensity reductions in Henan and Shandong aluminum smelting. SAMR enforces GB 150 pressure vessel standards that mandate revised safety interlock architectures above 10 bar delivery pressure. Shandong smelters are consolidating procurement around domestic system integrators with established GB certification track records.
Taiwan
TSMC's Fab 18 in Tainan and the Hsinchu-Taoyuan foundry corridor generate bundled procurement contracts for multi-chamber flux delivery platforms. SEMI S2 and S8 safety evaluations require 14-18 month validation cycles that delay revenue recognition for semiconductor-grade equipment. The concentrated foundry ecosystem favors predictive maintenance-integrated systems without legacy PLC constraints.
South Korea
Samsung's Pyeongtaek complex deploys electromagnetic particle acceleration systems for 3nm gate stack formation requiring Class 100 particulate thresholds. Korean secondary steelmakers near Seoul are unbundling after-sales service from hardware procurement to capture labor cost arbitrage. The metropolitan area favors hybrid support models combining German equipment with local automation specialists.
Germany
Otto Junker GmbH dominates European metallurgical equipment demand through specialized engineering capabilities anchored in North Rhine-Westphalia. The KBA vehicle type approval framework shapes flux injection specifications for aluminum body-in-white welding in electric vehicle production. Industrial clusters in Baden-Württemberg integrate precision dosing systems into automated powertrain casting lines.
Turkey
Electric arc furnace operators across Anatolia are installing pneumatic flux injectors to reduce tap-to-tap times and improve slag chemistry control in secondary steelmaking revival. The country's national industrial equipment regulator enforces pressure vessel safety ratings for molten metal handling systems. Istanbul-based foundry operators prioritize capital-efficient retrofit solutions for legacy smelting infrastructure.
Flux Injection System Market Competitive Landscape
Player mix skews toward induction heating heritage companies and refractory specialists with molten metal handling expertise. The supplier base fragments sharply between metallurgical-specialist and semiconductor-dedicated tiers with incompatible R&D roadmaps. Three archetypes dominate: furnace-integrated platform builders, precision dosing specialists, and regional system integrators with certification track records. Competitive moves concentrate on GB compliance acceleration and predictive maintenance capability unbundling.
Within the induction heating heritage tier, Inductotherm Group and ABP Induction Systems GmbH exemplify platform builders leveraging thermal management legacy into flux delivery architectures. Pyrotek occupies a position among refractory-rooted specialists whose molten metal handling expertise extends into injection system design. Otto Junker GmbH anchors European demand concentration through metallurgical equipment engineering specialization. Sintokogio Ltd. and StrikoWestofen GmbH represent precision furnace fabricators with regional certification depth. Foshan Hengyang Furnace Manufacturing Co., Ltd. and Yizumi Holdings Co., Ltd. sit within the China-based system integrator archetype consolidating procurement around established GB 150 compliance track records.
| Leading Market Players |
|---|
| Inductotherm Group |
| Pyrotek |
| Otto Junker GmbH |
| Sintokogio Ltd. |
| StrikoWestofen GmbH |
| Foshan Hengyang Furnace Manufacturing Co., Ltd. |
| Yizumi Holdings Co., Ltd. |
| ABP Induction Systems GmbH |
| Scottish Chemical Industries |
| Others |
Pricing and Supply Chain Analysis
GB 150 pressure vessel certification from China's SAMR gates both supplier qualification and price differentiation, forcing equipment builders to absorb compliance costs while semiconductor buyers extract premiums for Class 100 cleanroom ratings. Metallurgical-grade pneumatic systems face margin compression from commoditized fluoride sourcing, whereas electromagnetic architectures command 40-60% price multiples in Taiwan's foundry corridor.
Pricing Analysis
Cost-plus contracts with aluminum fluoride indexation dominate procurement for legacy smelting equipment, with Turkish and Indian electric arc furnace operators driving spot-market volatility. Three-tier pricing structure across premium, standard, and economy levels separates SEMI S2-certified semiconductor systems from GB 150-compliant metallurgical units and unlicensed regional alternatives. Price differentiation hinges on certification tier and predictive maintenance bundling, with Korean foundries unbundling service contracts to capture labor arbitrage. Cost compression in standard-grade pneumatic injectors is intensifying because Chinese state-owned enterprises control 70% of metallurgical-grade fluoride precursor production.
Supply Chain Analysis
Port congestion along the Shanghai-Rotterdam trade lane elevates inbound logistics costs for European flux chemistry suppliers dependent on Chinese fluoride precursors. Component sourcing draws from China for pressure vessel fabrication, Germany for precision dosing controllers, and Japan for servo-actuated cleanroom mechanisms. Raw material dependencies center on metallurgical-grade fluoride, borax compounds, and high-purity chloride salts. Single-source vulnerability concentrates in Chinese state-controlled fluoride production. Distribution runs through domestic system integrators in Shandong and Henan provinces, with direct OEM relationships dominating semiconductor-grade procurement in Taiwan and South Korea.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating around Taiwan's Hsinchu-Taoyuan foundry corridor and Samsung's Pyeongtaek complex, with bundled procurement contracts squeezing supplier margins while fragmenting the vendor base into incompatible metallurgical and semiconductor tiers.
For Market Incumbents: Secure GB 150 certification acceleration in China's provincial MEE offices before SAMR enforcement inspections tighten replacement cycles. Backward integration into fluoride precursor supply buffers raw material access risk from Chinese state-owned enterprise concentration. Prioritize predictive maintenance capability development to defend against unbundling trends in Korea's Seoul metropolitan area. For New Entrants and Emerging Players: SEMI S2 fast-track certification opens white-space positioning in Vietnam's Ho Chi Minh City electronics manufacturing zone, where Samsung and Intel packaging facilities commission first-generation capacity without legacy PLC constraints. Target electromagnetic injection architectures for 3nm node production as TSMC and Samsung fragment established technology hierarchies. Pursue channel partnerships with German precision dosing specialists to bypass 14-18 month validation timelines. For Investors and Strategic Acquirers: Carve-out targets emerge from induction heating heritage companies with dormant flux injection R&D programs, particularly North American furnace builders lacking semiconductor cleanroom expertise. Long-term viability favors platforms bridging metallurgical reliability with electronics-grade purity specifications. Watch for inflection when China's dual carbon policy framework provincial MEE offices mandate electromagnetic retrofit timelines in Henan aluminum smelting operations.| Strategic Initiative | Industry Significance |
|---|---|
| GB 150 Certification Acceleration | Domestic Chinese system integrators consolidate procurement around established compliance track records in Shandong province. |
| Predictive Maintenance Unbundling | Korean secondary steelmakers separate hardware procurement from service contracts to capture Seoul metropolitan labor arbitrage. |
| Electromagnetic Architecture Migration | TSMC's Tainan complex and Samsung's Pyeongtaek facilities displace pneumatic systems for sub-5nm node production. |
| Fluoride Precursor Backward Integration | Non-Chinese equipment builders reduce exposure to state-owned enterprise supply concentration in metallurgical-grade inputs. |
| SEMI S2 Fast-Track Certification | Vietnam's emerging electronics manufacturing zone bypasses legacy validation constraints for first-generation cleanroom deployment. |
Research Methodology
Desk research of customs trade databases, SAMR enforcement records, and SEMI safety documentation preceded structured interviews with foundry maintenance directors, flux injection system procurement leads at TSMC and Samsung, Chinese aluminum smelter plant managers, and German precision dosing controller engineers. Primary fieldwork validated equipment specification trends across Taiwan's Hsinchu-Taoyuan corridor and Korea's Seoul metropolitan area. Secondary sources included SEC filings from induction heating heritage companies, Chinese provincial MEE dual carbon policy implementation reports, and REACH chemical registration disclosures. Bottom-up unit economics triangulated against top-down market sizing from foundry capital expenditure tracking.
Variance decomposition across product type, technology platform, application grade, and end-user maturity shaped the analytical framework throughout the projection horizon. Modeled segmentation captured pneumatic, hybrid, and electromagnetic architectures; metallurgical versus electronics-grade specifications; and procurement patterns across integrated chip producers, vehicle manufacturers, and secondary steelmakers. CAGRs derived from equipment replacement cycles, foundry capacity expansion announcements, and regulatory compliance deadline clustering. Industry-specific inputs included SEMI S2/S8 validation timeline distributions and Chinese provincial MEE electromagnetic retrofit incentive trajectories.
Underlying assumptions cover sustained foundry capital expenditure concentration in Taiwan and South Korea, with deviation risk concentrated in Chinese fluoride precursor export restrictions and REACH chemical registration cost escalation. Forecasts reflect these conditions; semiconductor dry process substitution or GB 150 enforcement acceleration outside modeled timelines would require model recalibration. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Global Zinc Stearate Market
Additives
Lubricant Additives Market
Additives
Chelating Agents Market
Additives
Global Mold Release Agents Market
Additives
Global Butylated Hydroxytoluene Market
Additives
Green Chelates/Natural Chelating Agents Market
Additives
Metal Deactivators Market
Additives
Rheological Additives Market
Additives
Anti-Slip Additives Market
Additives
Engine Oil Additive Market
Additives
Epoxy Type Stabilizers Market
Additives
Metal Modifiers Market
Additives
Phthalate and Non-Phthalate Plasticizers Market
Additives
Butyrate Additives Market
Additives
Conditioning Agent Market
Additives
Low Melt Inclusions Market