
 North America Paints and Coatings Additives Market | 2026-2036
North America Paints and Coatings Additives Market Size, Share, and Industry Trends Forecast 2026-2036
North America Paints and Coatings Additives Market Analytics
Full-system additive bundling is consolidating buyer choice across the North American supply base as formulators seek pre-optimized packages over discrete chemical procurement. BASF SE leverages its integrated pigment-additive portfolio to anchor large architectural accounts. Dow Inc. competes through silicone-based defoamer specialization for industrial lines. Eastman Chemical Company sustains regional manufacturing scale from its Kingsport, Tennessee operations.
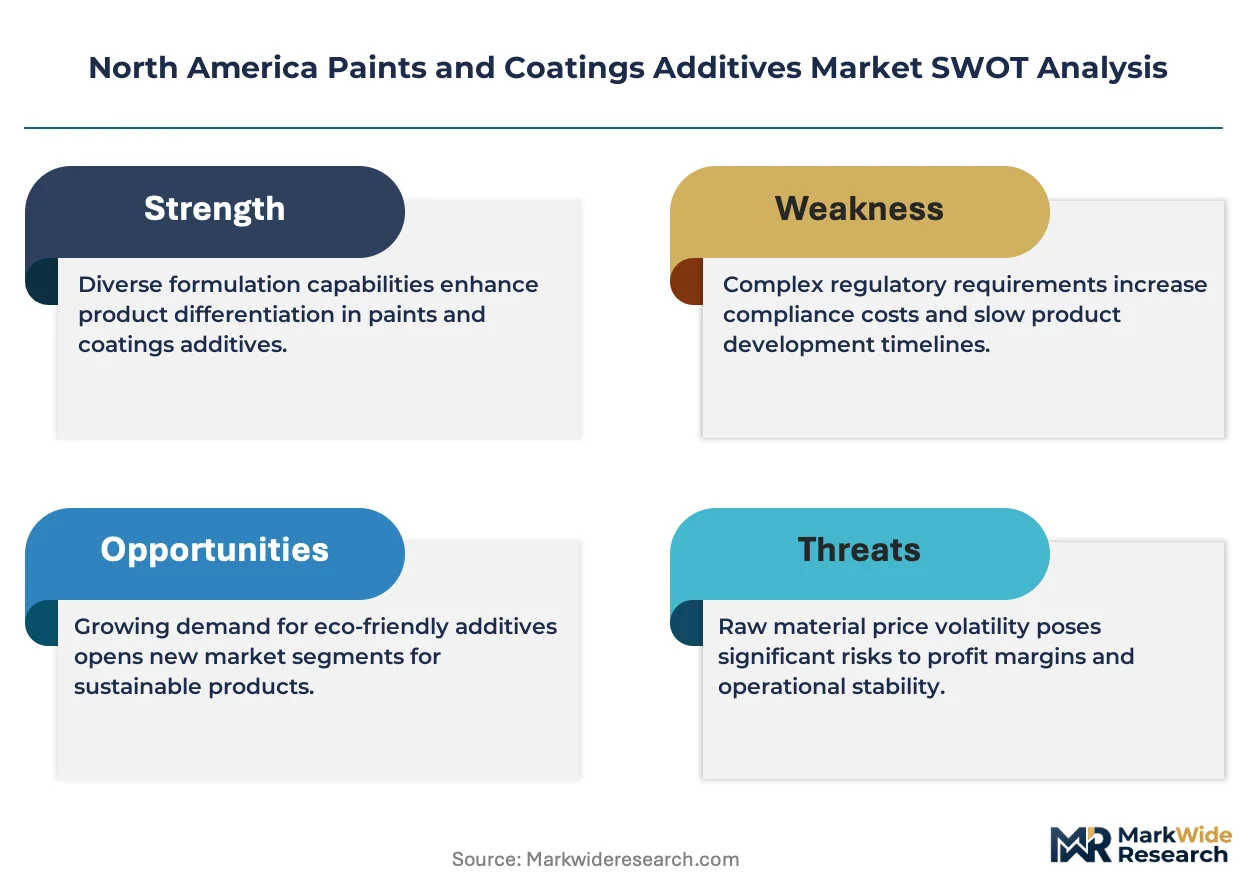
North America paints and coatings additives comprise functional chemicals—typically 0.1-5.0% by formulation weight—that modify rheology, stabilize dispersion, prevent microbial degradation, or control foam during manufacture and application. These additives serve primarily to meet performance specifications and regulatory compliance in liquid, powder, aerosol, and paste delivery modes. Dispersant demand leads volume within product type segments due to universal need across waterborne and solvent systems, while biocide formulations face margin pressure from EPA re-registration requirements. Architectural coatings application segments mature in volume terms but shift toward higher-value additive loading as zero-VOC specifications proliferate.
EPA toxicity evaluations under the Toxic Substances Control Act, California Air Resources Board VOC limits, and Health Canada PMRA biocide registrations collectively determine which chemistries gain market access across the continent. Formulators now face divergent compliance costs between US federal and Canadian federal timelines, reshaping cross-border product line strategies. Stakeholders must monitor pending EPA risk evaluations for 1,2-benzisothiazolin-3-one and related isothiazolinone biocides that could remove cornerstone preservatives from approved use lists.
Market Dynamics
Waterborne formulation conversion across automotive OEM coating lines is compressing additive specification windows while concentrating procurement authority among fewer formulator-buyers.
Growth Catalysts
- EPA VOC limits:Federal emissions caps are accelerating solvent-to-waterborne line conversions at Tier 1 automotive suppliers in Michigan and Ontario.
- Zero-VOC architectural specifications:California SCAQMD Rule 1113 amendments are mandating additive package upgrades across commercial building coatings.
- US Gulf Coast petrochemical clustering:Proximity between specialty additive production and resin supply reduces logistics costs for dispersant and rheology modifier procurement.
Market Restraints
- Propylene oxide feedstock volatility:Price swings in this key polyurethane dispersant input compress margin predictability for formulators.
- Biocide re-registration timelines:EPA TSCA Section 6 risk evaluations for isothiazolinone chemistries are extending product approval cycles.
- Silicone defoamer supply concentration:Three producers control over 70% of North American silicone intermediate supply, creating bottleneck risk.
Strategic Opportunities
- Canadian federal biocide harmonization:Health Canada PMRA alignment delays with EPA timelines create first-mover positioning for dual-registered chemistries.
- Powder coating additive bundling:Industrial maintenance segments in Texas and Louisiana are adopting pre-optimized additive packages for high-temperature applications.
- AI-driven formulation optimization:Machine learning platforms are converging with high-throughput screening to compress additive selection cycles for custom industrial coatings.
Industry Challenges
- Cross-border compliance divergence:Formulators face parallel EPA and Health Canada registration costs for identical biocide actives, fragmenting product line economics.
- Specialized rheology modifier formulation expertise:Shortage of chemists trained in associative thickener behavior across high-shear industrial application equipment limits new product rollout velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Paints and Coatings Additives Market |
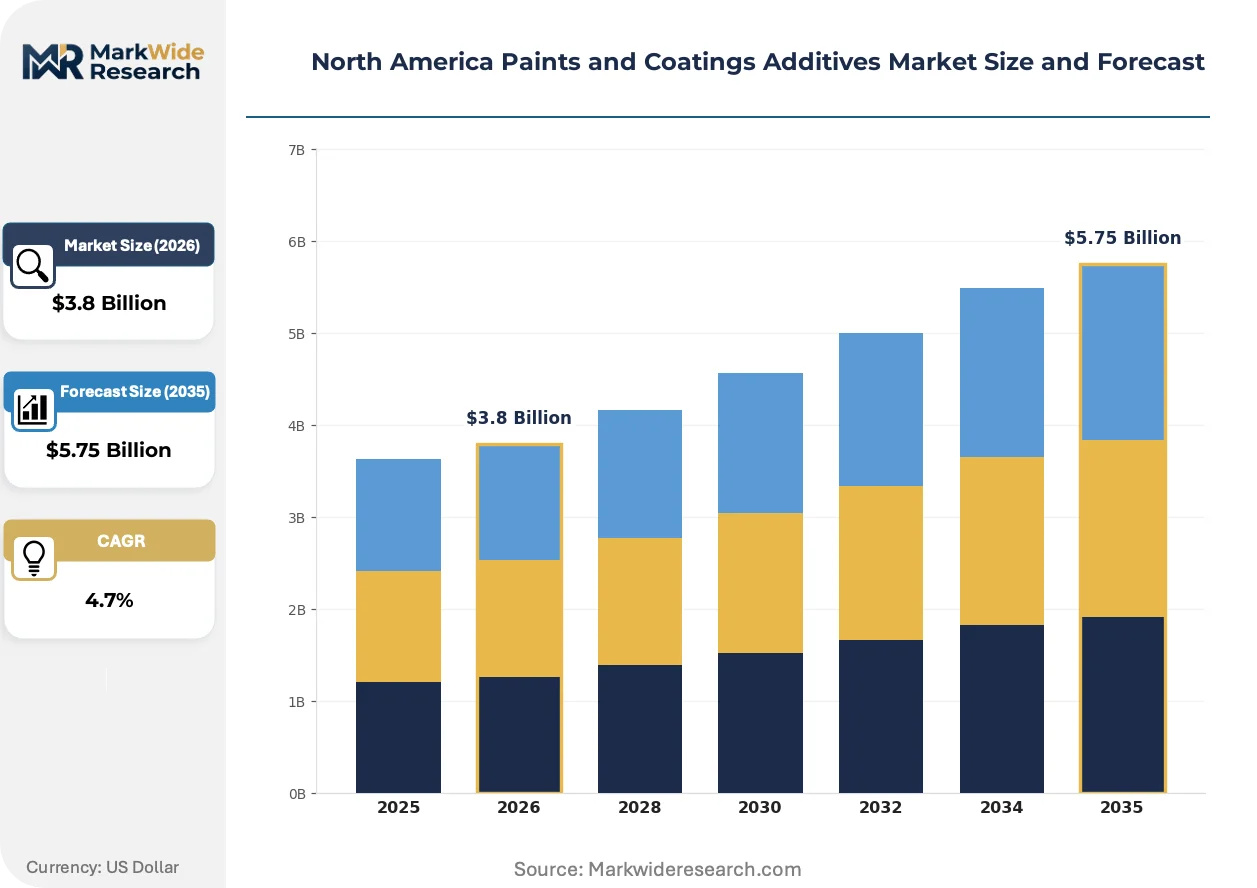
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thickeners, Dispersants, Biocides, Foam Control Agents Application: Architectural Coatings, Industrial Coatings, Automotive Coatings, Wood Coatings End User: Construction, Automotive, Furniture, Manufacturing Delivery Mode: Aerosol, Liquid, Powder, Paste |
| Companies Covered | BASF SE, Altana AG, Dow Inc., Ashland Inc., Evonik Industries AG, Arkema, Eastman Chemical Company, Clariant AG, Nouryon, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Paints and Coatings Additives Market Evolving Landscape
Additive suppliers are embedding predictive performance modeling into specification workflows, collapsing the traditional trial-and-error cycle that once governed formulator-producer relationships.
Hybrid dispersant-rheology modifier chemistries are unifying stabilization and flow control functions into single-molecule architectures. Automotive OEMs in Michigan are specifying these dual-function additives for waterborne basecoat lines to reduce formulation complexity. This convergence is compressing the number of discrete SKUs formulators must inventory and qualify.
California Air Resources Board is tightening VOC limits for industrial maintenance coatings below current federal EPA thresholds. The regulation forces formulators serving California to maintain separate additive inventories from their federal-compliant product lines. Industrial segments with cross-border distribution networks face the highest compliance cost multiplication.
Pre-optimized additive packages are displacing discrete chemical procurement among mid-sized architectural coating producers. Large formulators in the US Southeast are consolidating supplier relationships around bundled offerings that include technical service and regulatory documentation. This shift is most visible among regional paint manufacturers lacking in-house formulation laboratories.
North America Paints and Coatings Additives Market Segmentation
Additive specification varies sharply across end-use performance requirements in North America. Formulators select chemistries based on cure conditions, substrate compatibility, and regulatory load rather than commodity pricing.
Product Type:
Functional chemistry determines formulation stability, application behavior, and in-can preservation across waterborne and solvent systems.
- Dispersants:Polymeric and surfactant-based systems stabilize pigment distribution in both waterborne and solventborne matrices. Demand concentrates in automotive OEM basecoat lines in Michigan and Ontario where color consistency specifications are tightest. EPA VOC limits are accelerating waterborne dispersant adoption over traditional solvent-compatible alternatives.
- Thickeners:Associative and cellulosic rheology modifiers control sag resistance and brush drag in architectural applications. High-volume procurement clusters among Southeast US regional paint manufacturers upgrading to zero-VOC specifications under California SCAQMD Rule 1113 pressure.
- Biocides:Isothiazolinone and formaldehyde-releasing preservatives prevent in-can microbial degradation. EPA TSCA Section 6 re-registration timelines are compressing approved chemistry lists and extending product approval cycles.
- Foam Control Agents:Silicone and mineral oil defoamers manage air entrainment during high-speed manufacturing. Three producers control over 70% of North American silicone intermediate supply, creating procurement concentration risk.
Mature deployment sits with Dispersants. Newer deployment is concentrated in Thickeners as zero-VOC architectural specifications proliferate.
Application:
End-use performance specifications dictate additive loading rates and chemistry selection across the value chain.
- Architectural Coatings:Interior and exterior decorative paints drive volume demand for thickeners and biocides. California Air Resources Board limits are forcing separate additive inventories for California-compliant versus federal-compliant product lines.
- Industrial Coatings:Protective and maintenance coatings for infrastructure and equipment require specialized dispersant and foam control packages. Pre-optimized additive bundling is consolidating procurement among mid-sized formulators in Texas and Louisiana.
- Automotive Coatings:OEM clearcoats and basecoats demand precision dispersant systems for metallic and pearlescent effects. Waterborne line conversions at Tier 1 suppliers in Michigan and Ontario are compressing specification windows.
- Wood Coatings:Furniture and flooring finishes utilize rheology modifiers for spray and dip application compatibility. Demand clusters in Southeast US furniture manufacturing corridors.
Volume concentration remains in Architectural Coatings. Margin expansion is steepest in Automotive Coatings as waterborne complexity increases.
End User:
Customer scale and technical capability determine whether formulators procure discrete additives or bundled packages.
- Construction:Commercial and residential building activity drives architectural coating consumption. Zero-VOC mandates in California are cascading into specification requirements across the US Southwest.
- Automotive:OEM assembly plants and Tier 1 suppliers in Michigan and Ontario anchor precision additive demand. Waterborne coating line expansions are concentrating procurement authority among fewer formulator-buyers.
- Furniture:Wood finishing operations in North Carolina and Tennessee utilize specialized rheology modifiers for spray booth application. Smaller formulators in this segment increasingly rely on pre-optimized additive packages.
- Manufacturing:General industrial coating applications span metal fabrication, machinery, and appliance finishing. Powder coating adoption in high-temperature applications is creating additive specification divergence from liquid systems.
Procurement sophistication is highest in Automotive. Package bundling penetration is deepest in Furniture.
Delivery Mode:
Physical form factor determines additive incorporation methods and supply chain handling requirements.
- Liquid:Pumpable concentrates dominate waterborne architectural and industrial formulations. US Gulf Coast petrochemical clustering minimizes logistics costs for high-volume liquid dispersant procurement.
- Powder:Solid additives serve high-temperature powder coating applications in industrial maintenance segments. Texas and Louisiana manufacturing hubs are adopting pre-optimized packages for this delivery mode.
- Aerosol:Propellant-dispensed systems require specialized foam control and rheology packages. Niche demand concentrates in consumer DIY and touch-up applications.
- Paste:High-solids concentrates target thick-film industrial coatings and specialty wood finishes. Limited volume but premium positioning in custom formulation work.
Volume leadership sits with Liquid. Powder is expanding most quickly as industrial maintenance segments convert from solventborne systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Additive production concentrates along the US Gulf Coast resin corridor while consumption spreads across automotive clusters in Michigan and Ontario, architectural formulators in California, and industrial maintenance operations in Texas and Louisiana.
United States
EPA VOC limits under the Toxic Substances Control Act are accelerating solvent-to-waterborne conversions at Tier 1 automotive suppliers in Michigan. California Air Resources Board Rule 1113 amendments mandate separate additive inventories for California-compliant versus federal-compliant architectural product lines. The US Gulf Coast petrochemical corridor anchors specialty dispersant and rheology modifier production near upstream resin supply.
Canada
Health Canada PMRA biocide registration timelines lag EPA re-registration schedules, creating first-mover positioning for dual-registered chemistries. Ontario automotive OEM coating lines are expanding waterborne capacity in tandem with Michigan operations. Quebec architectural formulators face cross-border compliance divergence that fragments product line economics between federal and provincial specifications.
Mexico
Automotive assembly plant expansion in Nuevo León and the Bajío Region is pulling additive demand from US suppliers across the border. Mexico's federal environmental regulator SEMARNAT is tightening industrial emissions standards that affect coating formulation requirements. Querétaro and Guanajuato manufacturing corridors are adopting pre-optimized additive packages for industrial maintenance applications.
North America Paints and Coatings Additives Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across additive categories, creating a tiered structure where integrated chemical majors anchor large architectural accounts while regional specialists serve custom industrial formulations. Three strategic archetypes dominate: pigment-additive integrators, silicone-based defoamer specialists, and regional manufacturing-scale operators. Consolidation through additive bundling and backward integration into resin supply are the primary competitive moves reshaping procurement relationships.
Among diversified chemical majors, BASF SE and Dow Inc. exemplify the integrated archetype, leveraging broad portfolios to anchor specification decisions at large formulators. Eastman Chemical Company occupies a position as a regional manufacturing-scale specialist, sustaining production proximity to Southeast US demand clusters. These three entities represent the competitive tension between global bundling power and regional responsiveness that defines current market dynamics.
| Leading Market Players |
|---|
| BASF SE |
| Altana AG |
| Dow Inc. |
| Ashland Inc. |
| Evonik Industries AG |
| Arkema |
| Eastman Chemical Company |
| Clariant AG |
| Nouryon |
| Others |
Value Network & Pricing Analysis
Performance-grade divergence between zero-VOC architectural specifications and legacy solvent-compliant formulations splits both procurement costs and supplier qualification pathways across North American additive markets. EPA VOC limits and California SCAQMD Rule 1113 create parallel inventory requirements that amplify price spreads while concentrating supply relationships around pre-optimized bundled packages.
Pricing Analysis
Margin tightening in standard-grade biocide formulations reflects EPA TSCA Section 6 re-registration delays extending product approval cycles. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume scale, with large architectural formulators commanding lowest unit costs through consolidated procurement. Cost-down pressure on silicone-based foam control agents accelerates because three producers control over 70% of North American silicone intermediate supply. Mid-sized regional paint manufacturers show highest price sensitivity due to limited in-house formulation laboratories and technical service dependencies.
Supply Chain Analysis
Single-source vulnerability sits with propylene oxide feedstock for polyurethane dispersant production, exposing formulators to commodity price volatility. Geographic supply concentration centers on the US Gulf Coast petrochemical corridor, with secondary clustering in Kingsport, Tennessee and Ontario automotive corridors. Raw material dependencies draw from propylene oxide, silicone intermediates, and cellulosic polymers. Tariff exposure on Canadian cross-border biocide registrations fragments product line economics. Distribution runs through direct technical sales relationships with large formulators and distributor networks serving regional paint manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Waterborne formulation technology is displacing solvent-based coating lines across automotive OEM and architectural segments, compressing additive specification windows and consolidating procurement authority among fewer buyers with advanced technical capabilities.
For Market Incumbents: Extend bundled additive package offerings to anchor specification decisions at mid-sized architectural formulators lacking in-house laboratories. Backward integration into propylene oxide or silicone intermediate supply would defend margin position against feedstock volatility and supply concentration risk from the three dominant silicone producers. Prioritize dual-registration investment for biocide actives across EPA and Health Canada PMRA timelines to capture first-mover positioning as regulatory harmonization lags. For New Entrants and Emerging Players: Begin with AI-driven formulation optimization platforms serving custom industrial coating segments in Texas and Louisiana where procurement sophistication lags automotive OEM standards. Powder coating additive packages for high-temperature industrial maintenance applications represent the most penetrable white space, with pre-optimized bundling displacing discrete chemical procurement. A technical service-heavy go-to-market model can overcome incumbent relationships among regional manufacturers. For Investors and Strategic Acquirers: Re-rating potential sits with regional manufacturing-scale specialists possessing captive resin supply and Gulf Coast logistics positioning given waterborne conversion acceleration. Long-term viability over a multi-year horizon favors additive suppliers with integrated pigment portfolios and regulatory documentation capabilities. Watch EPA risk evaluation outcomes for isothiazolinone biocides as an inflection indicator for chemistry substitution cycles and portfolio restructuring requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Propylene Oxide Supply | Captive feedstock sourcing defends margin predictability against commodity volatility in polyurethane dispersant production. |
| Dual-Registration Investment for Biocide Actives | Parallel EPA and Health Canada PMRA approvals capture first-mover positioning as regulatory timelines diverge. |
| AI-Driven Formulation Platform Development | Machine learning convergence with high-throughput screening compresses additive selection cycles for custom industrial coatings. |
| Powder Coating Additive Package Expansion | Pre-optimized bundling addresses high-temperature industrial maintenance conversion from solventborne systems in Texas and Louisiana. |
| Zero-VOC Certification Investment | California SCAQMD Rule 1113 compliance enables specification capture in commercial building coatings segments. |
Research Methodology
Document review covered EPA TSCA filings, Health Canada PMRA registration databases, SEC 10-K disclosures from diversified chemical majors, and automotive OEM coating line expansion announcements, complemented by interviews with plant managers at specialty additive production facilities, procurement leads at Tier 1 automotive suppliers, technical R&D directors at architectural coating formulators, and distribution channel partners serving the US Gulf Coast petrochemical corridor. Bottom-up volume modeling triangulated against top-down value estimates derived from resin consumption correlations and additive loading rate assumptions.
Segment-level projections across dispersants, thickeners, biocides, and foam control agents were generated through regression analysis of formulation conversion rates, regulatory compliance timelines, and end-use demand patterns over the projection horizon. The analytical framework incorporated product type, application segment, end-user category, and delivery mode as core segmentation dimensions, with CAGRs derived from elasticity-adjusted growth rate synthesis. Key forecast inputs included EPA VOC limit phase-in schedules and waterborne coating line expansion announcements from Michigan and Ontario automotive clusters.
Underlying measurement precision varies by segment; automotive OEM specifications carry tighter precision than fragmented furniture finishing applications due to concentrated buyer visibility and public production data. Forecasts reflect assumptions around regulatory implementation timelines, feedstock price stability, and technology adoption curves that could shift with unanticipated EPA risk evaluation outcomes or propylene oxide supply disruptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Global Coalescing Agent Market
Additives
Cassia Gum Market
Additives
Rosin Ester Market
Additives
Phenolic Antioxidant Market
Additives
Phthalate and Non-Phthalate Plasticizers Market
Additives
Clouding Agents Market
Additives
LAMEA Driveline Additives Market
Additives
Middle East Lubricant Additives Market
Additives
Global Performance Additives Market
Additives
Plastic Antioxidants Market
Additives
Europe Anti-Caking Market
Additives
Flux Injection System Market
Additives
Pectin Market
Additives
Volatile Corrosion Inhibitors Market
Additives
Nucleating Agents Market
Additives
Dipotassium Guanylate Market