
 Macroporous Strong Acid Cation Exchange Resin Market | 2026-2036
Macroporous Strong Acid Cation Exchange Resin Market Size, Share, and Industry Trends Forecast 2026-2036
Macroporous Strong Acid Cation Exchange Resin Market Insights
Chinese specialty chemical producers is shifting macroporous strong acid cation exchange resin capacity toward higher-crosslink grades for power plant demineralization. Dow leverages backward integration into styrene-divinylbenzene monomer supply to protect margin structure. Purolite anchors European demand through its pharmaceutical-grade resin certification under EMA guidelines. Mitsubishi Chemical dominates Asian electronics water purification with ultra-low TOC resin formulations.
Macroporous strong acid cation exchange resin consists of a crosslinked polystyrene matrix with sulfonic acid functional groups, engineered with permanent pore structures exceeding 100 angstroms to facilitate large organic molecule exchange. The material removes calcium, magnesium, and heavy metal cations from process streams in high-temperature or oxidizing environments where gel-type resins degrade. Application-level demand in semiconductor manufacturing leads value creation due to sub-ppt purity requirements for chip fabrication rinse loops. Water softening occupies the largest volume share among end users, though pharmaceutical purification commands premium pricing through FDA-validated regeneration protocols. Product type segmentation shows macroporous variants displacing gel types in fossil fuel power generation where thermal oxidative stress degrades conventional matrices.
EPA effluent limitation guidelines and China's MEE water quality standards shape resin selection criteria for industrial boiler feedwater systems. REACH registration requirements in Europe constrain import of uncertified ion exchange materials, favoring established suppliers with ECHA-compliant supply chains. FDA 21 CFR validation for pharmaceutical applications creates barrier-to-entry dynamics for new market participants. Stakeholders must monitor tightening semiconductor-grade water specifications in East Asian fabrication clusters as next-node lithography demands ever-lower ionic contamination thresholds.
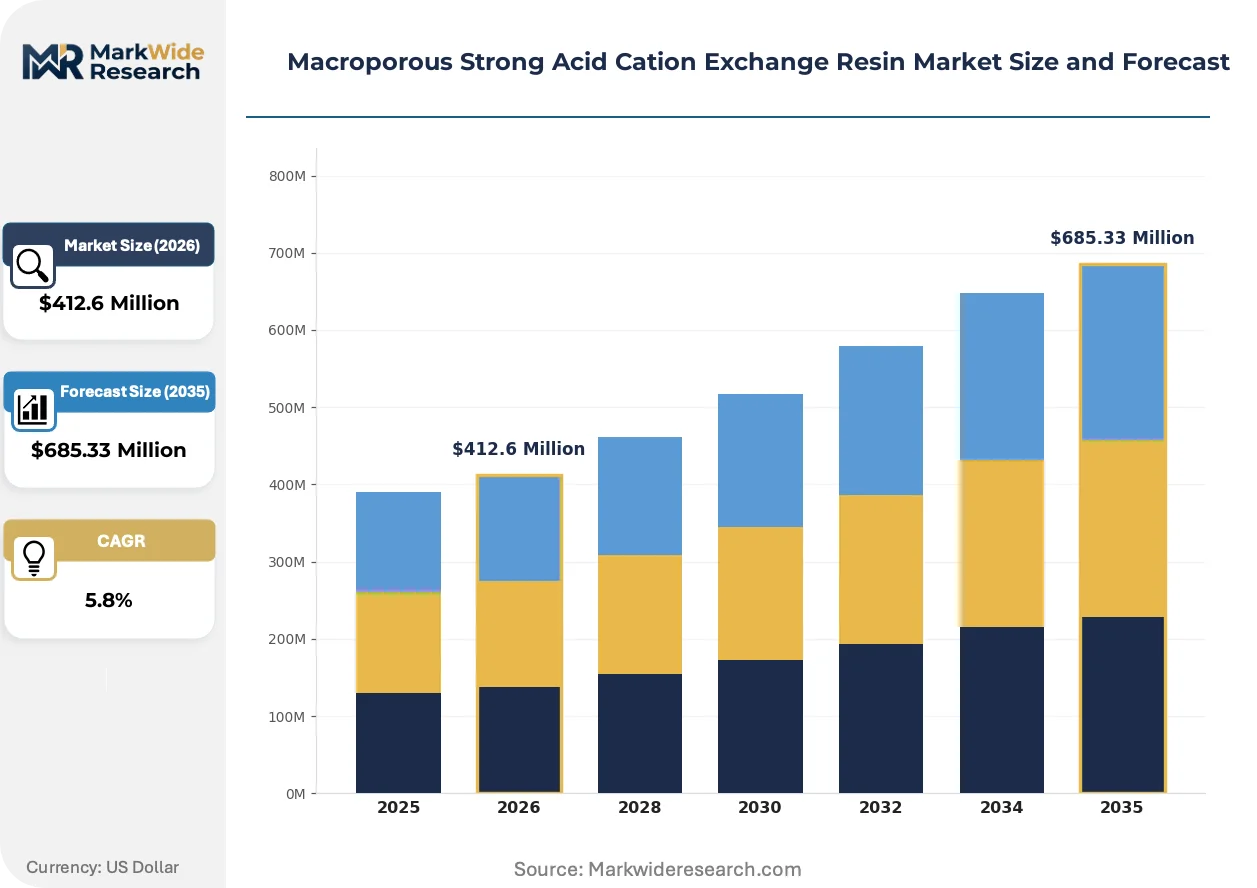
Market Dynamics
Tightening EPA effluent limitation guidelines and China's MEE water quality standards are forcing industrial water treatment operators to replace gel-type resins with macroporous variants that withstand thermal oxidative stress in high-temperature boiler feedwater systems.
Growth Catalysts
- Stricter Boiler Feedwater Standards:China's MIIT enforces elevated purity requirements for power generation, compelling utilities to upgrade demineralization systems with higher-crosslink macroporous resins.
- Semiconductor Fabrication Expansion:East Asian chip clusters demand ultra-low TOC resin formulations for sub-ppt rinse loops as lithography nodes advance.
- Pharmaceutical-Grade Certification:EMA-validated regeneration protocols under EU guidelines create premium pricing tiers for resin suppliers serving drug purification markets.
Market Restraints
- Styrene-Divinylbenzene Feedstock Volatility:Crude oil price fluctuations directly impact polystyrene matrix production costs, compressing supplier margins during energy market turbulence.
- REACH Registration Barriers:ECHA compliance requirements constrain uncertified ion exchange material imports into Europe, favoring established suppliers with documented supply chains.
- Regenerable Resin Substitution:Advanced reverse osmosis membrane systems compete for high-purity water applications in municipal and light industrial segments.
Strategic Opportunities
- Underpenetrated Indian Power Sector:CEA mandates for thermal plant water efficiency create procurement windows for macroporous resin suppliers as utilities modernize aging demineralization trains.
- Green Hydrogen Electrolyzer Water:Ultra-high purity water requirements for PEM electrolyzer feedstock represent an emerging demand vertical with specialized resin specifications.
- Digital Water Management Integration:IoT-enabled resin bed monitoring systems allow predictive regeneration scheduling, opening service-revenue models for chemical suppliers.
Industry Challenges
- Specialized Polymer Chemistry Talent Scarcity:Formulation expertise for high-crosslink macroporous matrices resides with a limited pool of aging technical specialists, constraining R&D velocity.
- FDA 21 CFR Validation Timelines:Pharmaceutical application approvals require multi-year stability documentation, delaying market entry for new resin grades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Macroporous Strong Acid Cation Exchange Resin Market |
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $685.33 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gel Type, Macroporous Type, Mixed Bed Type, Chelating Type Application: Water Softening, Food & Beverage Processing, Pharmaceutical Purification, Chemical Processing, Semiconductor Manufacturing End User: Chemical Manufacturers, Beverage Producers, Pharmaceutical Companies, Electronics Manufacturers Packaging Type: Bulk Bags, Drums, Fiber Drums, Intermediate Bulk Containers, Loose Packaging |
| Companies Covered | Dow, Purolite, Lanxess, DuPont, Ion Exchange (India), Mitsubishi Chemical, Samyang Corporation, Thermax, ResinTech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Macroporous Strong Acid Cation Exchange Resin Market Trends and Innovations
Macroporous strong acid cation exchange resin technology is evolving through three concurrent pathways: material science advances in matrix durability, regulatory tightening across major industrial jurisdictions, and fundamental shifts in how water treatment operators procure and deploy ion exchange systems.
Hybrid organic-inorganic composite matrices are integrating silica nanoparticles into polystyrene-divinylbenzene backbones to enhance thermal stability beyond 150°C. Fossil fuel power generators in China and India are adopting these grades aggressively as boiler operating temperatures rise. The technology is integrating oxidative resistance as a baseline specification, compressing demand for conventional gel-type alternatives in high-stress applications.
REACH registration requirements in Europe are mandating full substance identity disclosure for ion exchange resin imports, creating compliance moats around ECHA-registered suppliers. Industrial water treatment operators now prioritize documented supply chain transparency over unit cost in procurement decisions. Pharmaceutical and electronics-grade resin categories face the steepest compliance burden, accelerating supplier consolidation toward vertically integrated European producers.
Long-term service contracts with bundled resin supply and regeneration management are displacing spot procurement in large industrial accounts. Water treatment operators in Germany's chemical corridor and Japan's electronics clusters favor single-source accountability over multi-vendor fragmentation. This model concentrates purchasing power with resin suppliers offering predictive analytics and on-site technical support, compressing margins for commodity distributors lacking service capabilities.
Macroporous Strong Acid Cation Exchange Resin Market Segmentation
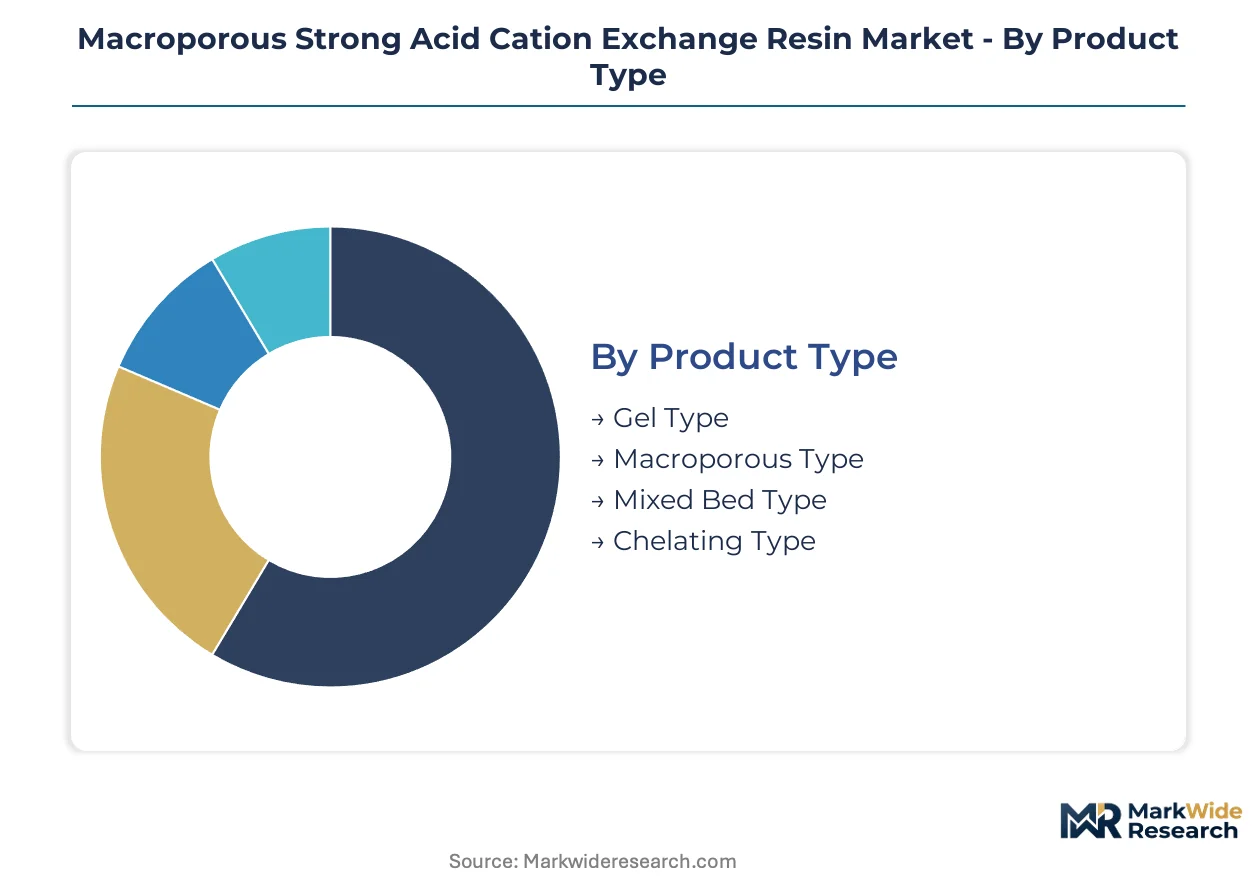
Macroporous strong acid cation exchange resin procurement patterns diverge sharply between standalone ion exchange systems and embedded multi-stage purification trains. Understanding these integration pathways clarifies why specification requirements vary dramatically across customer types and end-use environments.
Product Type:
Integration depth separates gel-type resins deployed in standalone softening units from macroporous grades engineered for high-stress embedded systems in power generation and electronics manufacturing.
- Gel Type:Dense polystyrene-divinylbenzene matrices without permanent pore structures suit low-temperature water softening where organic fouling remains minimal. Demand concentrates in North American municipal utilities with moderate feedwater complexity and limited oxidant exposure.
- Macroporous Type:Permanent pore structures exceeding 100 angstroms facilitate large organic molecule exchange and withstand thermal oxidative stress. China's power sector drives procurement as MIIT enforces stricter boiler feedwater purity standards for thermal generation fleets.
- Mixed Bed Type:Intimate mixtures of cation and anion resins in single vessels deliver polished water for high-purity applications. Electronics manufacturers in Japan and South Korea specify these for final rinse loops in semiconductor fabrication.
- Chelating Type:Functionalized with iminodiacetic acid groups for selective heavy metal capture. Mining and hydrometallurgical operations in Australia and Canada deploy these for process stream purification.
Volume placements concentrate in Gel Type for basic softening; the faster expansion belongs to Macroporous Type as industrial boiler specifications tighten globally.
Application:
Cost tier stratification separates commodity water softening from premium pharmaceutical and electronics-grade purification where validation protocols command substantial price premiums.
- Water Softening:Largest volume application removing calcium and magnesium hardness from municipal and industrial feedwater. North American and European utilities dominate procurement with established regeneration infrastructure and lower purity thresholds.
- Food & Beverage Processing:Decolorization and deashing of sugar syrups, fruit juices, and edible oils. Brazilian and Thai sugar processors represent significant demand centers for food-grade certified resins.
- Pharmaceutical Purification:Active pharmaceutical ingredient separation and final polishing of water for injection. FDA 21 CFR and EMA validation requirements create steep entry barriers and sustain premium pricing tiers for documented supply chains.
- Chemical Processing:Catalyst recovery and product purification across specialty chemical manufacturing. German and Belgian chemical corridor operators specify high-crosslink grades for aggressive organic solvent environments.
- Semiconductor Manufacturing:Sub-ppt purity requirements for chip fabrication rinse loops and chemical mechanical planarization. East Asian fabrication clusters in Taiwan, South Korea, and Japan drive specification evolution as lithography nodes advance.
Revenue concentration sits with Semiconductor Manufacturing; steepest expansion trajectory belongs to Pharmaceutical Purification as biologics manufacturing scales.
End User:
Customer type determines procurement sophistication, with electronics and pharmaceutical buyers demanding full supply chain documentation while chemical manufacturers prioritize unit economics.
- Chemical Manufacturers:Broad deployment across process water treatment and product purification. Integrated petrochemical complexes in the US Gulf Coast and Middle East represent high-volume accounts with standardized specifications.
- Beverage Producers:Water quality standardization for consistent product taste and shelf stability. Major bottling operations in Mexico, Indonesia, and Nigeria drive regional demand patterns.
- Pharmaceutical Companies:Stringent validation requirements for resin lot traceability and regeneration protocol documentation. European and North American drug manufacturers anchor premium-grade procurement.
- Electronics Manufacturers:Ultra-low TOC specifications for semiconductor and display panel fabrication. Taiwanese and South Korean chip foundries set the most demanding purity benchmarks globally.
Procurement volume concentrates in Chemical Manufacturers; margin expansion favors Electronics Manufacturers as node shrinkage intensifies purity requirements.
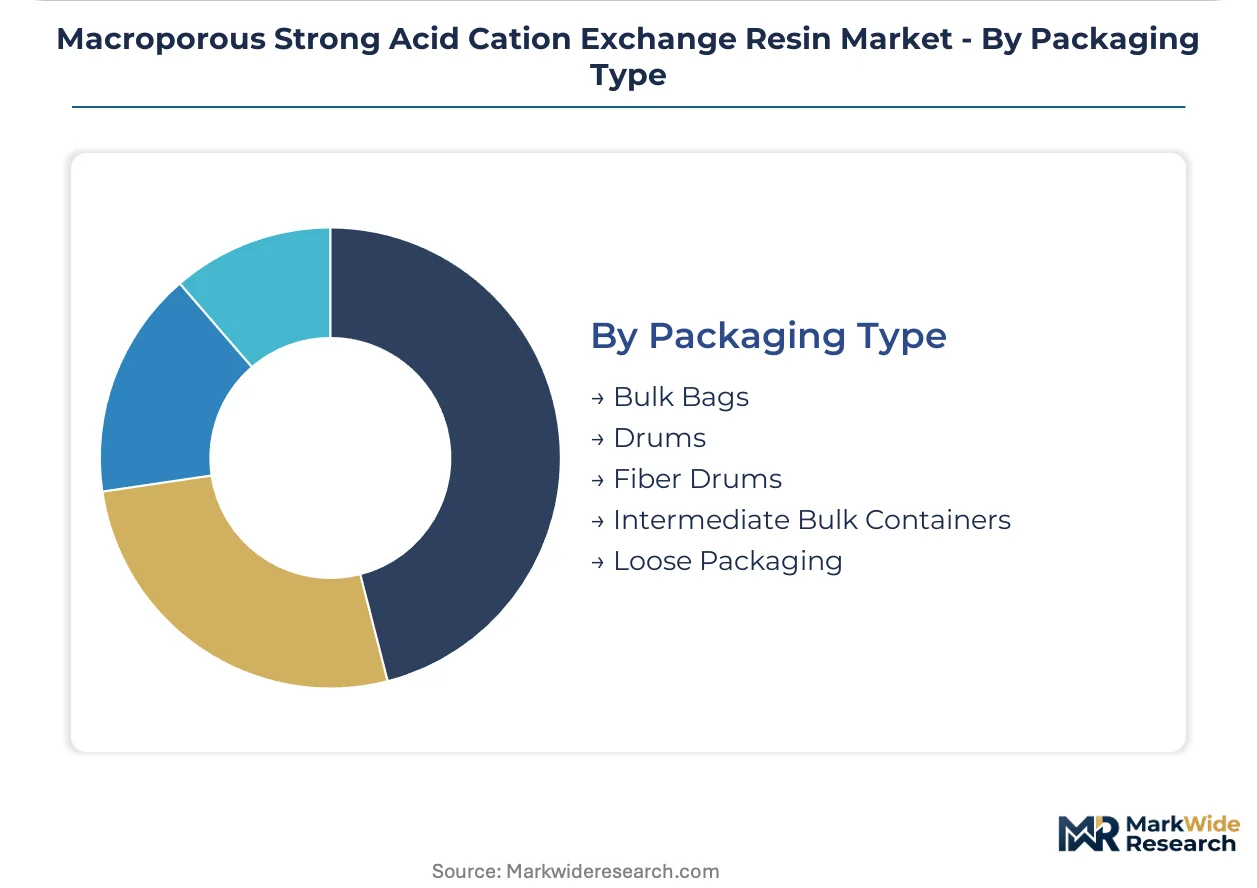
Packaging Type:
Supply chain configuration shapes packaging selection, with bulk logistics favoring intermediate bulk containers for large integrated sites while drum formats serve fragmented distributor networks.
- Bulk Bags:Flexible intermediate bulk containers for high-volume automated handling at integrated industrial sites. Power utilities and petrochemical complexes in China and India favor this format for demineralization train replenishment.
- Drums:Standardized steel or plastic containers for distributor-stocked inventory and smaller industrial accounts. European and North American maintenance-repair-operations channels depend on this format for responsive availability.
- Fiber Drums:Lightweight corrugated containers for food-grade and pharmaceutical applications requiring contamination-resistant packaging. Japanese and European pharmaceutical resin shipments specify fiber drum formats.
- Intermediate Bulk Containers:Rigid composite totes for medium-volume direct shipments to water treatment facilities. Australian mining and Indonesian palm oil processing operations utilize IBCs for remote site logistics.
- Loose Packaging:Bulk tanker or railcar delivery for very large integrated consumers with on-site storage silos. Major power generation and semiconductor fabrication campuses in Taiwan and South Korea receive resin via dedicated bulk logistics.
Shipment volumes concentrate in Bulk Bags; fastest adoption belongs to Intermediate Bulk Containers as mid-scale industrial water treatment modernizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Styrene-divinylbenzene feedstock availability clusters along the US Gulf Coast petrochemical corridor, China's Yangtze River Delta, and Germany's Rhine-Ruhr industrial zone, shaping resin manufacturing geography and trade flows.
China
Thermal power utilities in Jiangsu and Shandong provinces drive macroporous resin procurement as MIIT enforces stricter boiler feedwater purity standards. MEE water quality regulations mandate demineralization system upgrades across coal-fired generation fleets. Yangtze River Delta chemical complexes anchor domestic resin production capacity expansion.
United States
EPA effluent limitation guidelines compel industrial water treatment operators in Texas and Louisiana to replace gel-type resins with thermally stable macroporous variants. Gulf Coast petrochemical complexes integrate captive resin regeneration infrastructure. Semiconductor fabrication clusters in Arizona and Oregon specify ultra-low TOC formulations for advanced lithography nodes.
Germany
REACH registration requirements create compliance barriers for uncertified ion exchange material imports, favoring ECHA-registered suppliers with documented supply chains. Chemical corridor operators in North Rhine-Westphalia prioritize high-crosslink grades for aggressive solvent environments. Bavarian pharmaceutical manufacturers demand EMA-validated resin lots for drug purification protocols.
India
CEA mandates for thermal plant water efficiency create procurement windows as utilities in Gujarat and Maharashtra modernize aging demineralization trains. BIS certification requirements shape import substitution dynamics for domestic resin manufacturers. Tamil Nadu electronics manufacturing zones drive emerging demand for semiconductor-grade formulations.
Japan
METI industrial water recycling directives accelerate resin bed replacement cycles in Kansai region chemical processing. Tokyo-Osaka electronics clusters set global benchmarks for sub-ppt purity specifications in chip fabrication rinse loops. JIS standards compliance anchors procurement decisions for domestic water treatment operators.
Macroporous Strong Acid Cation Exchange Resin Market Competitive Landscape
Global majors compete with regional champions across regulatory compliance capabilities and specialized formulation expertise. The vendor base stratifies into three tiers: integrated petrochemical conglomerates with captive monomer supply, mid-scale specialists with pharmaceutical-grade certifications, and regional fabricators serving price-sensitive industrial accounts. Dominant competitive moves include backward integration into styrene-divinylbenzene feedstock and long-term service contracts bundling resin supply with predictive regeneration management.
Among North American integrated suppliers, Dow and DuPont exemplify the petrochemical-major archetype with upstream control over matrix raw materials. Purolite occupies a position within the certification-focused specialist tier, anchoring European demand through EMA-compliant supply chains. Mitsubishi Chemical represents the Asia-Pacific technology leader archetype, with ultra-low TOC formulations serving East Asian semiconductor fabrication clusters.
| Leading Market Players |
|---|
| Dow |
| Purolite |
| Lanxess |
| DuPont |
| Ion Exchange (India) |
| Mitsubishi Chemical |
| Samyang Corporation |
| Thermax |
| ResinTech |
| Others |
Pricing and Supply Chain Analysis
Styrene-divinylbenzene monomer costs cascade through three distinct pricing tiers as the polystyrene matrix feedstock moves from Gulf Coast petrochemical complexes through Chinese Yangtze Delta fabricators to European pharmaceutical compounders. Long-term offtake contracts with resin regeneration service bundling command premiums over spot procurement in fragmented industrial accounts.
Pricing Analysis
Service-bundling coverage separates premium-priced pharmaceutical-grade resin lots with EMA-validated regeneration protocols from unbundled commodity grades sold through distributor channels. Three-tier pricing structure across pharmaceutical-certified, industrial high-crosslink, and standard softening grades reflects FDA 21 CFR documentation burden and thermal stability specifications. Cost compression in standard softening tiers intensifies because reverse osmosis membrane systems capture municipal and light industrial volume. Chemical manufacturers in integrated petrochemical complexes exhibit highest price sensitivity; semiconductor fabricators in Taiwan and South Korea show least sensitivity due to sub-ppt purity requirements.
Supply Chain Analysis
Dual-sourcing qualification requirements from pharmaceutical and electronics buyers mandate ECHA-registered European suppliers alongside Asia-Pacific producers for supply continuity. Manufacturing concentrates in China, the United States, and Germany where styrene-divinylbenzene feedstock availability anchors production. Raw material dependencies encompass crude oil derivatives for polystyrene matrices, chlorosulfonic acid for sulfonation, and divinylbenzene crosslinking agents. Single-source vulnerability persists in ultra-low TOC formulations where Mitsubishi Chemical holds specialized oxidative resistance IP. Distribution runs through direct mill-to-plant bulk logistics for power utilities and chemical distributors for maintenance-repair-operations channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
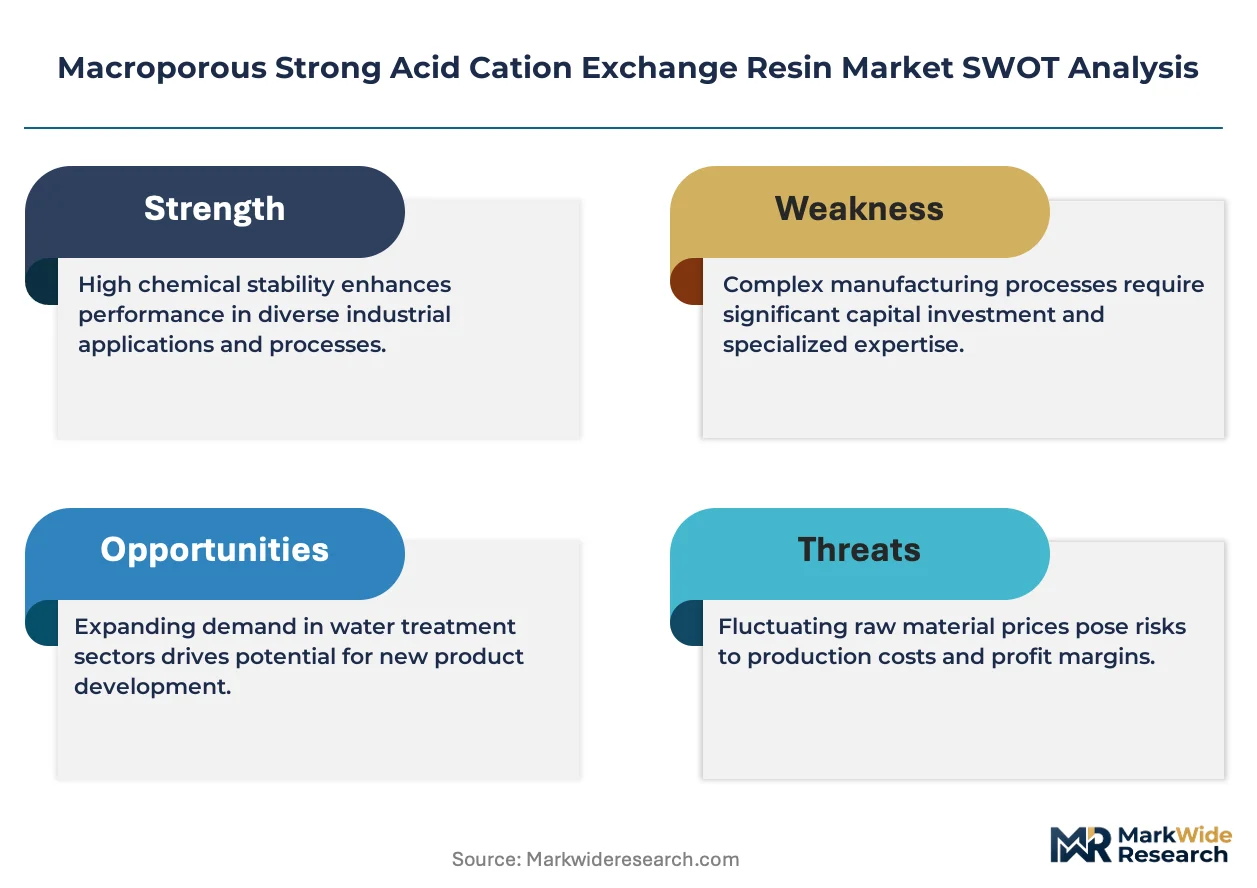
Specialized polymer chemistry talent scarcity constrains formulation capacity expansion, propping pricing power for incumbents with captive technical expertise pipelines.
For Market Incumbents: Anchor market position through backward integration into styrene-divinylbenzene monomer supply and EMA certification investments that raise compliance barriers against uncertified imports. Threat from advanced reverse osmosis membrane substitution in municipal segments demands defensive R&D in hybrid organic-inorganic composite matrices for high-temperature power generation applications. Capacity addition in Jiangsu province serves Chinese MIIT-mandated boiler feedwater upgrades. For New Entrants and Emerging Players: Silica nanoparticle composite formulation expertise offers entry wedge into fossil fuel power generation as thermal oxidative stress specifications tighten. White-space targets include Indian CEA-mandated thermal plant modernization in Gujarat and Maharashtra, plus green hydrogen electrolyzer water purification for PEM stack feedstock. Go-to-market through digital water management integration with IoT-enabled resin bed monitoring creates service-revenue differentiation against commodity distributors. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale specialists with pharmaceutical-grade certifications in European chemical corridors where REACH registration creates compliance moats. Long-term viability over a decade-plus horizon rests on consolidation of ECHA-registered supply chains as regulatory disclosure requirements intensify. Signal to watch is semiconductor node shrinkage pace in East Asian fabrication clusters driving sub-ppt purity specification evolution.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Monomer Supply | Dow's captive styrene-divinylbenzene production protects margin structure against crude oil volatility. |
| Pharmaceutical-Grade Certification Investment | Purolite's EMA-validated regeneration protocols create premium pricing tiers in European drug purification markets. |
| Ultra-Low TOC Formulation Development | Mitsubishi Chemical's semiconductor-grade resins serve sub-ppt rinse loops in Taiwan and South Korea. |
| Digital Water Management Integration | IoT-enabled resin bed monitoring opens predictive regeneration service contracts with German chemical corridor operators. |
| Hybrid Composite Matrix R&D | Silica nanoparticle integration extends thermal stability beyond 150°C for Chinese and Indian power utilities. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this macroporous strong acid cation exchange resin market assessment. Primary interviews with plant managers at power utilities, procurement leads at semiconductor fabricators, technical R&D directors at resin manufacturers, and pharmaceutical quality assurance officers validated demand patterns. Secondary sources encompassed EPA effluent limitation guidelines, China's MEE water quality standards, ECHA REACH registration databases, and SEC 10-K disclosures from integrated petrochemical suppliers. Bottom-up resin volume estimates by application and end-use triangulated against top-down market sizing from chemical industry federation reports.
Granularity-level modeling deployed crosslink density tiers, end-use industry classifications, packaging format logistics, and regional regulatory cluster distinctions across the projection horizon. CAGRs derived from regression analysis of historical procurement patterns against announced capacity expansions and regulatory implementation timelines. Forecast inputs incorporated MIIT boiler feedwater standard enforcement schedules, semiconductor lithography node roadmaps, and CEA thermal plant efficiency mandate compliance windows.
Several conditions sit outside the modeled scope, including unannounced styrene-divinylbenzene feedstock disruptions, abrupt shifts in EPA or MEE regulatory timelines, and breakthrough membrane technologies displacing ion exchange in high-purity applications. Deviation in crude oil price volatility or REACH registration enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Foamed Plastics Market
Polymers & Resins
Super Absorbent Polymer Market
Polymers & Resins
Europe Polyolefin Market
Polymers & Resins
Basic Methacrylate Copolymer Market
Polymers & Resins
Homopolymer Resins Market
Polymers & Resins
Acrylic Polymer Emulsion Market
Polymers & Resins
Optically Clear Resin Market
Polymers & Resins
Bio-Based Polypropylene in Medical Devices Market
Polymers & Resins
Global Styrene Acrylic Emulsion Polymer Market
Polymers & Resins
Semi-Rigid Spray Polyurethane Foam Market
Polymers & Resins
Dispersant Polymer Market
Polymers & Resins
Vinyl Acetate Homopolymer Emulsion Market
Polymers & Resins
Middle-East and Africa Thermoplastics Market
Polymers & Resins
Caprolactam (Nylon 6 Fiber and Nylon 6 Resin) Market
Polymers & Resins
Europe Epoxy Resins Market
Polymers & Resins
Global Polyamide 6 Market