
 Polyoxyethylene Sorbitan Monostearate Market | 2026-2036
Polyoxyethylene Sorbitan Monostearate Market Size, Share, and Industry Trends Forecast 2026-2036
Polyoxyethylene Sorbitan Monostearate Market Analytics
Plant-derived lecithin is repositioning conventional emulsifier economics in food systems, forcing polyoxyethylene sorbitan monostearate suppliers to emphasize performance differentiation. Croda International Plc leverages its lipid technology heritage to sustain premium positioning in pharmaceutical-grade surfactants. Kao Group anchors Asia-Pacific supply through integrated oleochemical operations. Evonik Industries AG differentiates via high-purity excipient standards for injectable formulations.
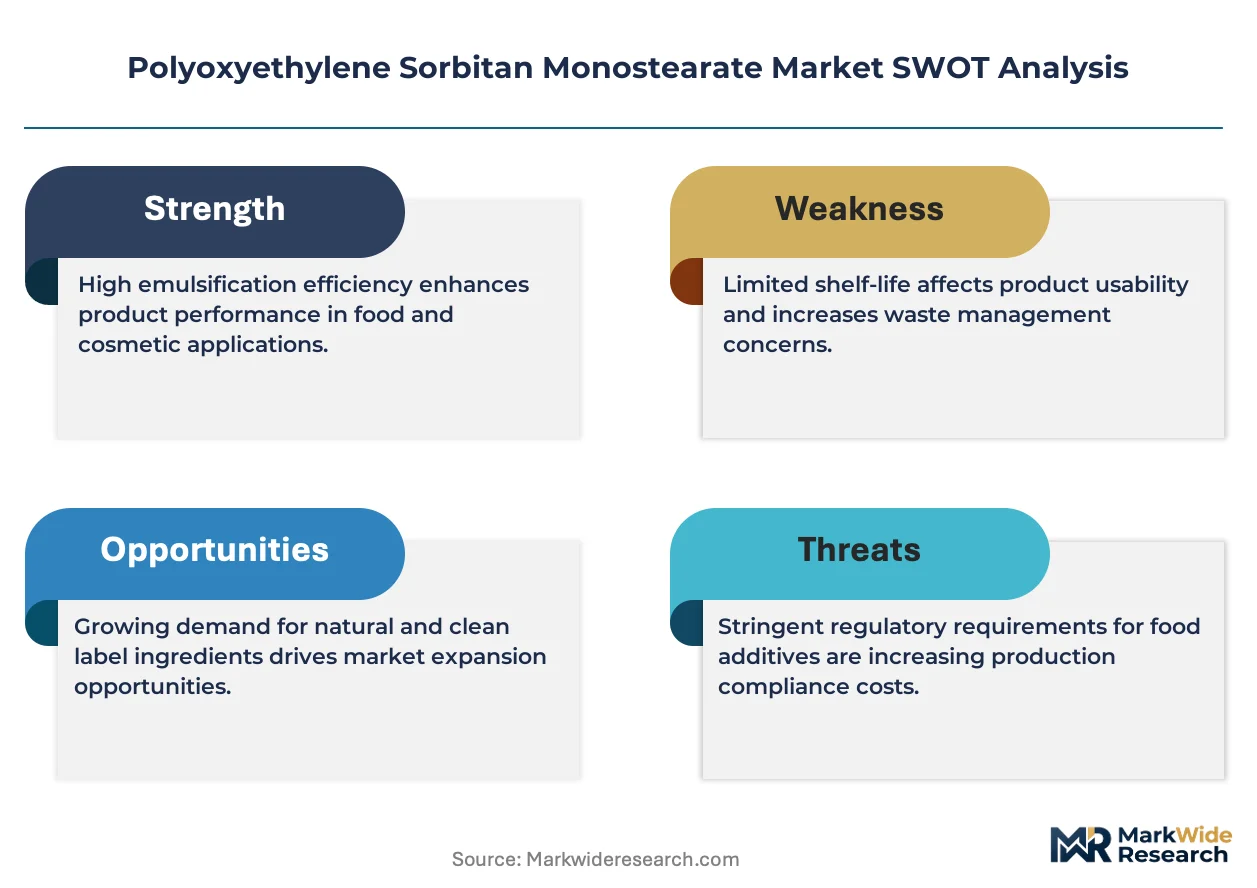
Polyoxyethylene sorbitan monostearate is a nonionic surfactant synthesized from sorbitan monostearate ethoxylated with approximately 20 moles of ethylene oxide, yielding an HLB value near 14.9 that enables oil-in-water emulsification across aqueous food and cosmetic matrices. The liquid product type dominates volume throughput due to ease of incorporation in continuous-process bakery and beverage lines, while powder grades command margin premiums in pharmaceutical tableting where flowability and shelf stability determine excipient selection. Cosmetics applications represent the fastest-expanding demand pool as formulators seek mild, PEG-derived emulsifiers for sensitive-skin positioning.
FDA food additive regulations under CFR 21 govern emulsifier purity and usage limits in standardized foods, while REACH registration requirements in Europe enforce comprehensive toxicological dossiers for ethoxylated surfactants. China's NMPA and GB standards for pharmaceutical excipients are raising import barriers and redirecting procurement toward domestic-certified manufacturers. Stakeholders must monitor evolving clean-label thresholds and regional purity divergences to calibrate product portfolios and certification investments.
Market Dynamics
Clean-label formulation mandates across food and personal care sectors are compressing demand for synthetic emulsifiers while simultaneously elevating purity requirements for retained polyoxyethylene sorbitan monostearate applications. This tension forces suppliers to bifurcate portfolios between cost-optimized industrial grades and certified pharmaceutical excipients.
Growth Catalysts
- Ethoxylated surfactant demand in parenteral drug delivery:Injectable formulation growth requires high-HLB excipients meeting USP-NF and EP compendial standards. NMPA's tightened pharmaceutical excipient guidelines in China redirect import substitution toward domestic-certified producers.
- Continuous-process bakery automation:Liquid emulsifier incorporation systems enable throughput scaling in industrial bread and cake manufacturing. Equipment manufacturers specify pumpable surfactant grades with defined viscosity profiles.
- Cosmetic mild-surfactant positioning:PEG-derived emulsifiers capture share in sensitive-skin and baby-care segments as formulators replace sulfate-based systems. Dermatological testing protocols favor established nonionic chemistries with extensive safety dossiers.
Market Restraints
- Ethylene oxide feedstock volatility:Crude oil derivative pricing and regional petrochemical capacity constraints transmit cost instability to ethoxylated surfactant producers. Spot ethylene oxide differentials between US Gulf Coast and Northeast Asia exceed historical ranges.
- Plant-derived lecithin substitution economics:Sunflower and rapeseed lecithin processors achieve cost parity in standard food emulsification applications. Clean-label preference curves accelerate displacement in retail-facing packaged goods.
- REACH registration cost amortization:ECHA's comprehensive toxicological dossier requirements for ethoxylates impose fixed compliance burdens disproportionately affecting smaller specialty chemical manufacturers.
Strategic Opportunities
- Biosimilar and complex generic expansion in India:CDSCO's accelerated approval pathways for follow-on biologics expand demand for compendial-grade excipients. Domestic formulation houses seek qualified regional surfactant suppliers.
- Carbon accounting integration in EU procurement:CSRD-mandated Scope 3 disclosure requirements favor emulsifier suppliers with verified lifecycle assessments and mass-balance certification. Premium positioning attaches to ISCC PLUS-claimed ethoxylates.
- Direct-to-manufacturer digital channels:Specialty chemical marketplaces reduce distributor markup capture in mid-volume pharmaceutical and cosmetic ingredient procurement. Platform verification protocols substitute for traditional supplier audits.
Industry Challenges
- Pharmaceutical excipient qualification timelines:Drug master file compilation and regulatory authority review cycles extend 18-36 months for new supplier entry. CMO validation requirements add parallel commercial friction.
- Analytical method transfer complexity:Ethylene oxide content and dioxane level testing protocols vary across USP, EP, and JP compendia. Multi-regional product registration demands redundant laboratory capability.
- Oleochemical feedstock traceability:RSPO and analogous sustainability certifications require chain-of-custody documentation from palm or coconut oil origin through ethoxylation. Supplier audit depth strains quality assurance bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyoxyethylene Sorbitan Monostearate Market |
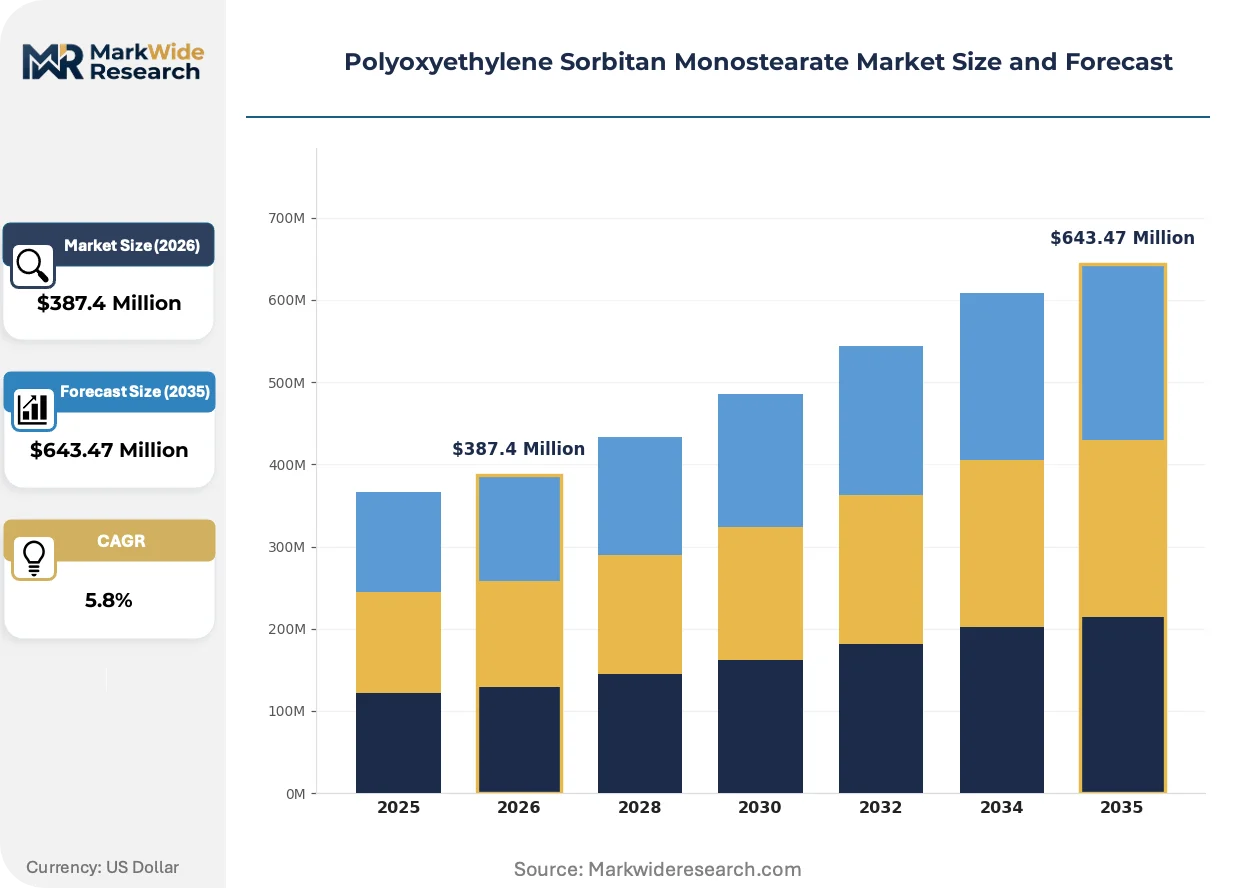
| Market Size in 2026 | $387.4 Million |
| Market Size in 2035 | $643.47 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Granules, Emulsion Application: Food Industry, Pharmaceuticals, Cosmetics, Paints End User: Manufacturers, Distributors, Retailers, Food Processors Distribution Channel: Online, Offline, Direct Sales, Wholesalers |
| Companies Covered | Merck KGaA, Croda International Plc, Kao Group, Sigma-Aldrich Co. LLC, Spectrum Chemical Manufacturing Corp., Evonik Industries AG, Amresco LLC, CISME ITALY S.R.L, Sisco Research Laboratories Pvt. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyoxyethylene Sorbitan Monostearate Market Evolving Landscape
Bio-based feedstock substitution and precision ethoxylation control technologies are reconfiguring competitive advantage in emulsifier manufacturing. Process intensification and analytical advancement separate commodity producers from premium-positioned specialists.
Continuous-flow ethoxylation reactor designs are absorbing capital investment from batch equipment replacements in integrated oleochemical complexes. Kao Group and Southeast Asian petrochemical operators deploy these systems for tighter polydispersity control and reduced dioxane formation. The technology is absorbing market share from conventional stirred-tank processes by enabling pharmaceutical-grade output without downstream purification bottlenecks.
REACH Annex XIV authorization proposals for ethylene oxide classify the monomer as a substance of very high concern, triggering downstream notification obligations for ethoxylated surfactant importers. ECHA's regulatory consequence cascades through cosmetic and pharmaceutical supply chains as formulators assess substitution timelines. European personal care manufacturers accelerate supplier qualification audits to secure existing authorization continuity.
Consolidated buyer concentration among multinational CPG conglomerates compresses emulsifier procurement into centralized category management functions. Unilever and Nestlé specification harmonization across regional manufacturing networks reduces qualified supplier lists to tier-one chemical producers with multi-continent manufacturing footprints. This behavioral shift concentrates contract value with integrated surfactant suppliers capable of global volume commitments and unified quality systems.
Polyoxyethylene Sorbitan Monostearate Market Segmentation
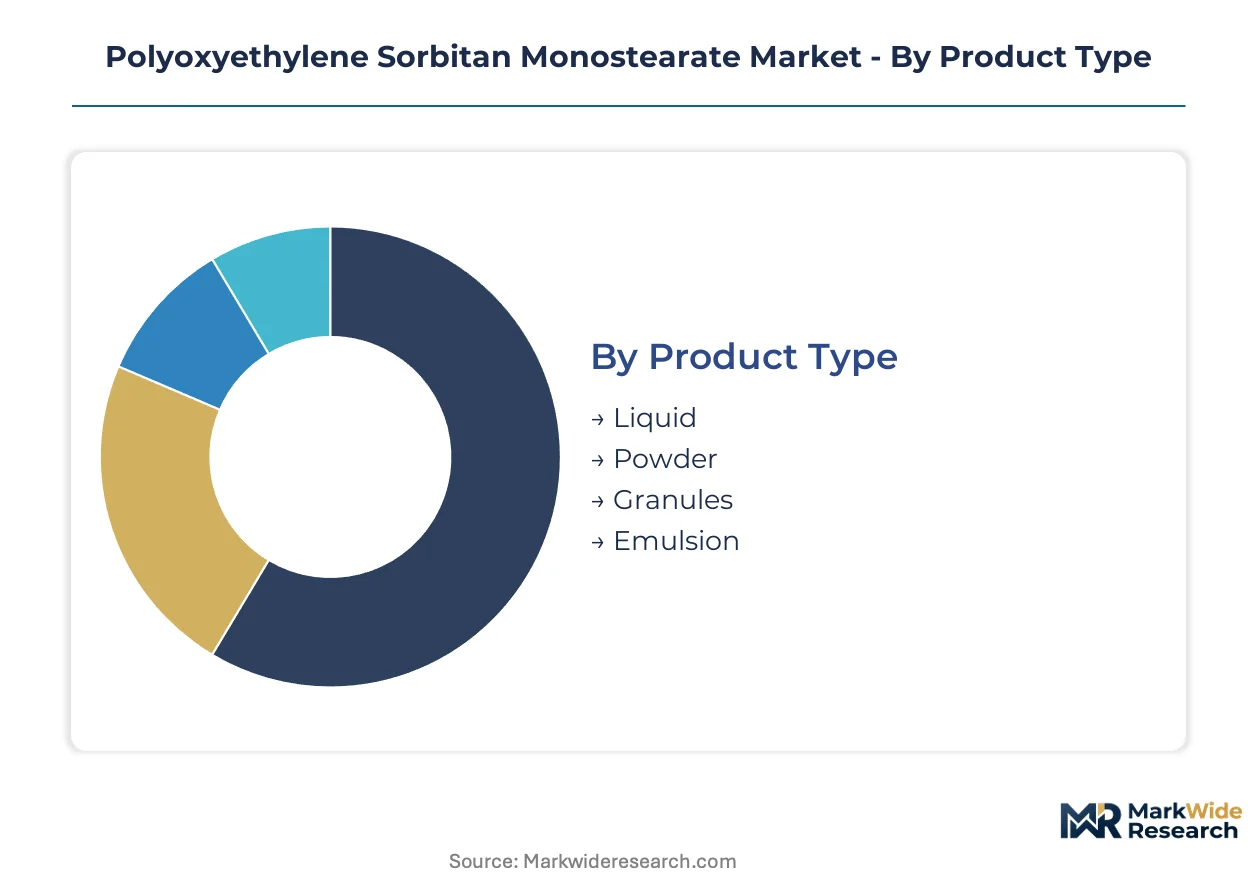
Polyoxyethylene sorbitan monostearate procurement decisions pivot on viscosity requirements, compendial certification, and incorporation method. Segment boundaries blur as pharmaceutical-grade liquid grades penetrate cosmetic formulations and food processors adopt pumpable systems for continuous lines.
Product Type:
Buyers select physical form based on equipment compatibility and downstream handling economics rather than unit cost alone.
- Liquid:Pumpable surfactant with defined rheological profiles integrates directly into continuous-process bakery and beverage manufacturing lines. Equipment manufacturers specify viscosity ranges that enable automated dosing without pre-dilution, concentrating procurement among industrial food processors in China and Southeast Asia.
- Powder:Free-flowing excipient grades meet USP-NF and EP compendial standards for pharmaceutical tableting where moisture sensitivity and shelf stability govern selection. Domestic manufacturers in India and China redirect import substitution toward certified regional suppliers as NMPA and CDSCO tighten excipient guidelines.
- Granules:Intermediate physical form bridges liquid handling convenience with powder storage stability for mid-scale cosmetic compounders.
- Emulsion:Pre-dispersed aqueous systems reduce formulation complexity for small-batch cosmetic and specialty food applications.
Liquid leads on scale; powder leads on momentum as pharmaceutical certification investments accelerate.
Application:
End-use specifications diverge sharply across compendial purity tiers, with regulatory jurisdiction determining supplier qualification pathways.
- Food Industry:Emulsifier applications span standardized bread, cake, and dairy formulations under FDA CFR 21 and EFSA food additive codes. Clean-label pressures compress synthetic emulsifier volumes even as purity thresholds rise for retained applications in industrial bakery automation.
- Pharmaceuticals:High-HLB excipient demand concentrates in parenteral and oral solid dosage forms requiring USP-NF, EP, and JP compliance. Injectable formulation growth drives qualification of suppliers with continuous-flow ethoxylation capabilities and sub-ppm dioxane control.
- Cosmetics:Mild-surfactant positioning in sensitive-skin and baby-care segments expands most quickly as formulators replace sulfate-based systems with established nonionic chemistries. PEG-derived emulsifiers leverage extensive dermatological safety dossiers for premium positioning.
- Paints:Industrial coating applications exploit wetting and dispersing properties for pigment stabilization in waterborne systems.
Food industry maintains volume dominance; cosmetics climbs fastest on premium formulation trends.
End User:
Procurement scale and technical specification authority separate direct manufacturers from intermediary channels.
- Manufacturers:Integrated formulators in pharmaceuticals and food command specification-setting authority, consolidating qualified supplier lists through centralized category management functions.
- Distributors:Regional chemical distributors capture mid-volume cosmetic and specialty food procurement, offering blended inventories and technical service.
- Retailers:Private-label food and personal care brands specify emulsifier grades through contract manufacturers, exerting indirect pressure on ingredient transparency.
- Food Processors:Industrial bakery and dairy operations specify pumpable liquid grades for continuous-line incorporation, prioritizing supply security over unit cost optimization.
Manufacturers concentrate contract value; food processors expand specification influence fastest.
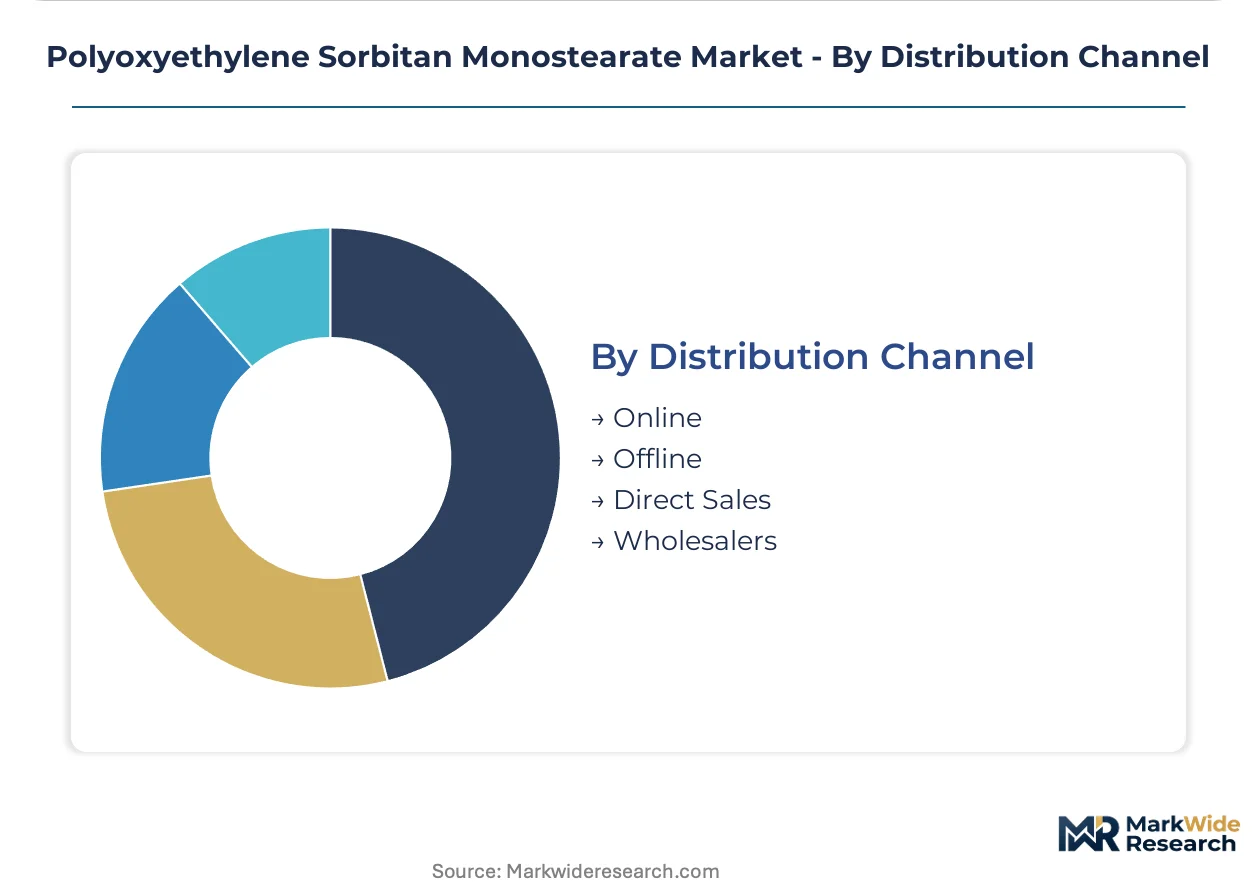
Distribution Channel:
Channel selection balances verification depth against procurement efficiency, with digital platforms eroding traditional distributor markups.
- Online:Specialty chemical marketplaces reduce friction in mid-volume pharmaceutical and cosmetic ingredient procurement, with platform verification protocols substituting for traditional supplier audits.
- Offline:Established distributor relationships persist where technical service and local inventory buffer supply continuity risks.
- Direct Sales:Global CPG conglomerates and multinational pharmaceutical houses negotiate direct supply agreements with tier-one integrated producers capable of unified quality systems across continents.
- Wholesalers:Commodity-grade food emulsifier volumes flow through regional chemical wholesalers serving smaller compounders without direct supplier qualification resources.
Direct sales anchors premium-grade volume; online channels expand most quickly in mid-market procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta industrial corridor concentrates the world's largest polyoxyethylene sorbitan monostearate manufacturing base. Domestic pharmaceutical excipient demand and food processing automation drive regional capacity expansion. Regulatory divergence across FDA, EMA, and NMPA jurisdictions shapes supplier qualification investments.
China
Pharmaceutical excipient import substitution and continuous-process bakery automation dominate demand growth. NMPA's tightened GB standards for pharmaceutical-grade surfactants redirect procurement toward domestic-certified manufacturers. The Yangtze River Delta cluster around Shanghai and Jiangsu province anchors ethoxylation capacity expansion for both food and pharmaceutical grades.
United States
Injectable formulation growth and industrial bakery automation sustain demand for high-HLB liquid grades. FDA CFR 21 food additive regulations govern emulsifier purity thresholds in standardized bread and dairy applications. The Gulf Coast petrochemical corridor supplies ethylene oxide feedstock to integrated surfactant producers serving pharmaceutical and food processing markets.
Germany
REACH compliance investments and carbon accounting integration drive supplier selection criteria. ECHA's authorization proposals for ethylene oxide classify the monomer as a substance of very high concern, triggering downstream notification obligations. The North Rhine-Westphalia chemical cluster maintains pharmaceutical-grade ethoxylation expertise for parenteral drug delivery applications.
India
Biosimilar expansion and complex generic formulation growth expand demand for compendial-grade excipients. CDSCO's accelerated approval pathways for follow-on biologics create procurement opportunities for qualified regional surfactant suppliers. The Mumbai-Pune pharmaceutical belt and Hyderabad formulation cluster drive excipient qualification investments.
Japan
Cosmetic mild-surfactant positioning and sensitive-skin formulation trends elevate PEG-derived emulsifier demand. PMDA pharmaceutical regulations enforce stringent dioxane limits in injectable-grade surfactants. The Kansai region around Osaka maintains oleochemical processing heritage serving both domestic cosmetic houses and pharmaceutical exporters.
Polyoxyethylene Sorbitan Monostearate Market Competitive Landscape
Portfolio diversification dominates the current landscape as suppliers bifurcate between cost-optimized industrial grades and certified pharmaceutical excipients. The vendor base concentrates around integrated oleochemical operators with continuous-flow ethoxylation capabilities and multi-regional quality systems. Three archetypes define competitive positioning: integrated petrochemical majors with captive ethylene oxide supply, specialty chemical houses with pharmaceutical compendial expertise, and regional oleochemical processors serving food-grade volume markets. Capacity expansion and strategic partnerships represent the dominant competitive moves, with continuous-flow reactor investments separating pharmaceutical-grade specialists from commodity producers.
Within the integrated specialty tier, Croda International Plc and Evonik Industries AG exemplify pharmaceutical-grade positioning through compendial certification depth. Kao Group anchors Asia-Pacific supply security through integrated oleochemical operations spanning feedstock to finished surfactant. Merck KGaA occupies a position bridging laboratory chemical distribution with pharmaceutical excipient qualification. These three entities represent distinct geographic and capability archetypes: European pharmaceutical-grade specialists, Asia-Pacific integrated operators, and German diversified chemical houses.
| Leading Market Players |
|---|
| Merck KGaA |
| Croda International Plc |
| Kao Group |
| Sigma-Aldrich Co. LLC |
| Spectrum Chemical Manufacturing Corp. |
| Evonik Industries AG |
| Amresco LLC |
| CISME ITALY S.R.L |
| Sisco Research Laboratories Pvt. Ltd. |
| Others |
Value Network & Pricing Analysis
Captive ethylene oxide supply through integrated petrochemical complexes anchors pricing power for polyoxyethylene sorbitan monostearate producers serving pharmaceutical and food-grade markets. Gulf Coast operators leverage upstream control over ethoxylation feedstock to buffer margin compression from volatile spot markets, while Asian integrated players exploit Yangtze River Delta manufacturing density to optimize logistics costs against certification-grade premiums.
Pricing Analysis
Ethylene oxide feedstock pass-through dominates pricing architecture for ethoxylated surfactants, with crude oil derivative volatility transmitting directly to contract renegotiation cycles. Pharmaceutical-grade excipients command substantial premiums over industrial food grades based on USP-NF and EP compendial certification, sub-ppm dioxane control, and continuous-flow reactor investments. Cost compression intensifies in standard food emulsification as sunflower lecithin achieves parity, squeezing synthetic emulsifier margins. Industrial bakery processors exhibit highest price sensitivity due to volume procurement and clean-label substitution options, while parenteral drug manufacturers prioritize supply security over unit cost.
Supply Chain Analysis
Skilled process engineering talent availability in Shanghai, Jiangsu province, and Osaka prefecture sustains continuous-flow ethoxylation operations requiring precision reactor control. Manufacturing concentrates in China, the United States, and Germany, with the Yangtze River Delta, Gulf Coast petrochemical corridor, and North Rhine-Westphalia anchoring respective regional supply. Raw material dependencies span ethylene oxide from naphtha cracking, sorbitan monostearate from palm or coconut oleochemicals, and catalytic ethoxylation agents. Single-source vulnerability runs through concentrated ethylene oxide capacity in integrated petrochemical complexes. Distribution runs through direct sales agreements for pharmaceutical-grade volumes and specialty chemical marketplaces for mid-tier cosmetic procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polyoxyethylene sorbitan monostearate procurement has shifted toward late-cycle quality prioritization as injectable formulation growth and REACH authorization pressures elevate compendial certification requirements over commodity volume plays.
For Market Incumbents: To counter plant-derived lecithin displacement in clean-label food applications, incumbents should deepen backward integration into RSPO-certified oleochemical feedstocks and accelerate continuous-flow reactor deployments for pharmaceutical-grade dioxane control. Certification investments in NMPA and CDSCO excipient standards capture import substitution demand across Asia-Pacific formulation houses. For New Entrants and Emerging Players: Specialty chemical marketplaces offer the most penetrable channel for mid-volume pharmaceutical and cosmetic ingredient procurement, enabling platform-verified supplier qualification without traditional audit burdens. White-space targets include CDSCO-registered excipient supply for Indian biosimilar expansion and ISCC PLUS-certified ethoxylates for EU carbon accounting procurement. For Investors and Strategic Acquirers: Roll-up economics work for regional oleochemical processors with captive ethoxylation capacity because pharmaceutical excipient qualification timelines create defensive moats against commodity entrants. Acquisition targets should demonstrate continuous-flow reactor assets and multi-regional compendial filings. The signal to watch is ECHA authorization timeline acceleration for ethylene oxide, which would trigger downstream substitution demand and reshape supplier valuation premia.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous-Flow Reactor Investment | Enables sub-ppm dioxane control for USP-NF and EP injectable-grade certification without downstream purification bottlenecks. |
| Backward Integration into Oleochemical Feedstock | Secures RSPO-certified palm and coconut oil supply for sustainability-committed CPG procurement under CSRD Scope 3 disclosure. |
| NMPA and CDSCO Excipient Registration | Captures pharmaceutical import substitution demand as China's GB standards and India's accelerated biosimilar pathways expand. |
| Specialty Chemical Marketplace Partnership | Reduces distributor markup capture in mid-volume cosmetic and pharmaceutical ingredient procurement through platform verification. |
| ISCC PLUS Mass-Balance Certification | Supports premium positioning for EU procurement under CSRD-mandated carbon accounting and supply chain transparency requirements. |
Research Methodology
Direct dialogue with plant managers at integrated oleochemical complexes, procurement leads at multinational food processors, pharmaceutical formulation scientists, and specialty chemical distribution channel partners grounded qualitative insights. Secondary validation drew from FDA CFR 21 filings, ECHA REACH registration dossiers, NMPA pharmaceutical excipient guidelines, customs trade data for ethoxylated surfactant flows, and SEC filings from listed chemical producers. Bottom-up capacity assessments across Yangtze River Delta and Gulf Coast manufacturing clusters were triangulated against top-down demand modeling from end-use industry consumption patterns.
Bottom-up modeling of ethoxylation capacity by reactor type and grade tier was cross-referenced against top-down pharmaceutical excipient demand projections and food industry emulsifier consumption trends across the analysis window. Segmentation dimensions included physical form, application industry, compendial certification level, and regional regulatory cluster. CAGRs were derived from production capacity expansion announcements, import substitution trajectories, and formulation technology shifts in parenteral drug delivery. Key inputs encompassed ethylene oxide feedstock pricing differentials, REACH authorization timeline assumptions, and clean-label substitution elasticity in retail packaged goods.
Revisions become necessary when ECHA ethylene oxide authorization proposals accelerate, NMPA excipient guidelines diverge from international compendia, or crude oil derivative volatility disrupts ethoxylation economics beyond historical ranges. Forecasts reflect documented assumptions regarding regulatory trajectory, feedstock cost pass-through elasticity, and substitution technology penetration. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Extrusion Aids Market
Additives
Inorganic Rheology Modifiers Market
Additives
Antimicrobial Additives Market
Additives
Chemical Silage Additives Market
Additives
Foundry Additives Market
Additives
Glycyrrhizic Acid Glycosides Market
Additives
Global Rheology Modification Coating Additives Market
Additives
Global Synthetic Tackifier Market
Additives
Combustion Clean-Up Additives for High-Mileage Fleets Market
Additives
Germany Sodium Reduction Ingredient Market
Additives
Plasticizer Concrete Admixtures Market
Additives
Americas Coating Additives Market
Additives
Liquid Silage Additive Market
Additives
Texture Modifier Market
Additives
Green Polymer Additive Market
Additives
Sodium Stearyl Fumarate Market