
 United States Betaine Market | 2026-2036
United States Betaine Market Size, Share, and Industry Trends Forecast 2026-2036
United States Betaine Market Analytics
Contract feed manufacturers is unwinding legacy reliance on commodity methionine as a methyl donor, redirecting procurement budgets toward betaine hydrochloride and anhydrous grades. Stepan Company leverages its surfactant-chemistry heritage to supply high-purity betaine variants for personal care and industrial applications. American Crystal Sugar Company anchors domestic natural betaine output through sugar-beet molasses extraction, capitalizing on proximity to Midwest agricultural processors. DuPont competes in the pharmaceutical-grade segment with fermentation-derived offerings that meet USP monograph standards.
Betaine denotes trimethylglycine, a zwitterionic quaternary ammonium compound with the molecular formula C5H11NO2, typically manufactured via sugar-beet molasses extraction or chemical synthesis from monochloroacetic acid and trimethylamine, functioning primarily as an osmolyte, methyl donor, and surfactant across nutrition and industrial matrices. Natural betaine dominates volume flows from beet processing co-products, while synthetic betaine hydrochloride captures margin pools in pharmaceutical and dietary supplement channels where USP certification commands price premiums. Feed additives represents the largest application slice, though personal care products demonstrates the fastest structural expansion as formulators substitute betaine for sulfated surfactants in rinse-off applications.
The FDA governs betaine's food and pharmaceutical pathways through GRAS self-affirmation and drug master file requirements, while the USDA shapes animal feed additive compliance through FSMA-mandated preventive controls for medicated and non-medicated ingredients. EPA oversight of chloroacetic acid precursors influences synthetic betaine manufacturing permits and effluent standards. Stakeholders must monitor pending FDA guidance on osmolyte health claims and state-level feed ingredient registration shifts that could alter channel economics.
Market Dynamics
Feed formulators across the Midwest corn belt are systematically substituting betaine for methionine as a methyl donor, compressing legacy amino acid procurement cycles and redirecting volume toward ethanol co-product and sugar-beet molasses extraction pathways.
Growth Catalysts
- FDA GRAS Pathway:The self-affirmation framework for food-grade betaine eliminates pre-market approval bottlenecks, accelerating formulation trials in functional beverages and sports nutrition.
- Integrated Livestock Operations:Iowa and Illinois pork and poultry producers are consolidating feed milling on-site, creating captive demand for bulk anhydrous betaine delivered via tanker.
- Ethanol Co-Product Recovery:Corn-to-ethanol processors in Minnesota and Nebraska are extracting natural betaine from stillage, shortening supply chains to regional feed compounders.
Market Restraints
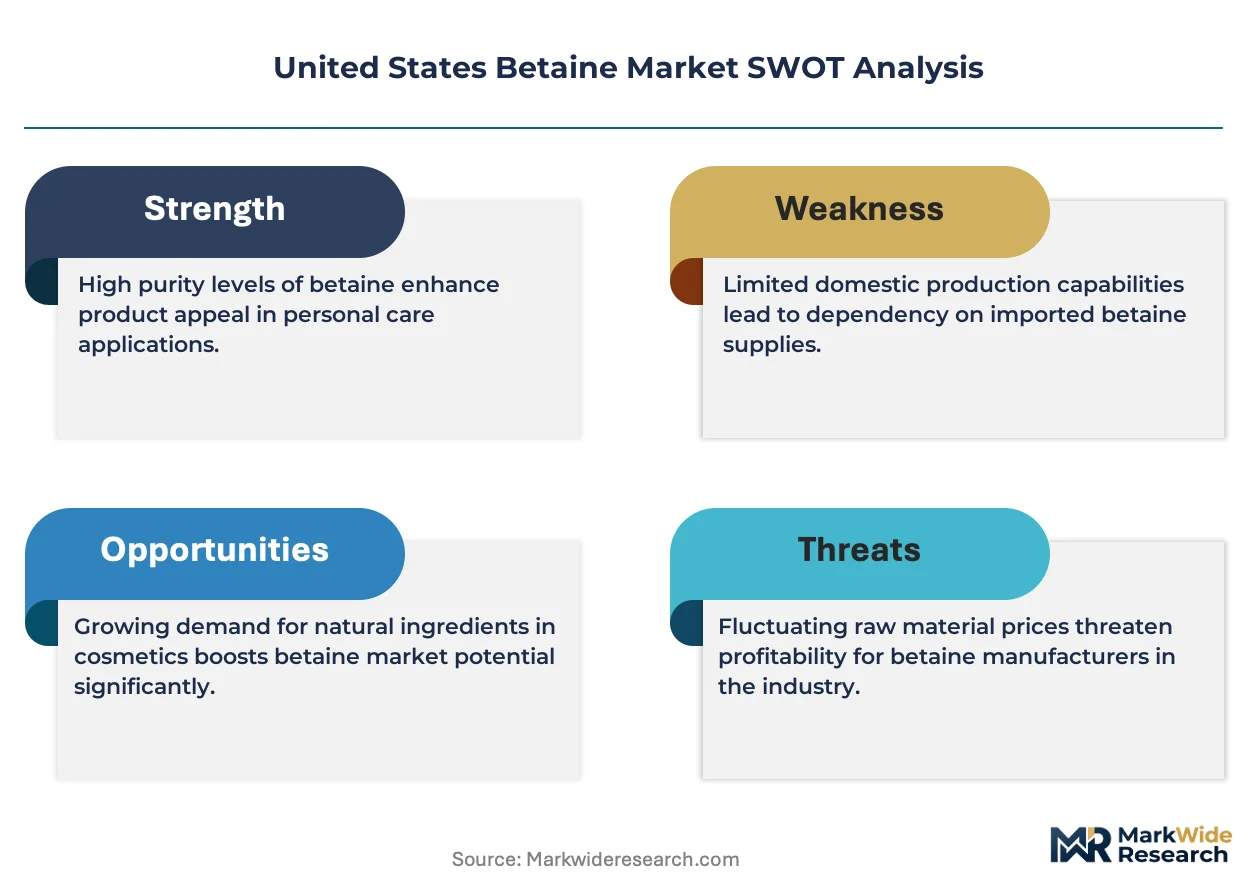
- Chloroacetic Acid Feedstock Volatility:Synthetic betaine hydrochloride production depends on petrochemical-derived precursors subject to refinery output fluctuations and EPA effluent permitting delays.
- Natural Betaine Supply Concentration:American Crystal Sugar Company's sugar-beet molasses extraction dominates domestic natural supply, creating single-source vulnerability for pharmaceutical-grade certification batches.
- Methionine Price Arbitrage:Commodity DL-methionine from Chinese fermentation capacity periodically undercuts betaine on a cost-per-methyl-donor basis, stalling substitution in price-sensitive swine finishing diets.
Strategic Opportunities
- Personal Care Formulation:Sulfate-free shampoo and body wash brands are adopting betaine as a mild surfactant, opening margin pools above feed-grade pricing in rinse-off cosmetics.
- Texas and California Feed Markets:Underpenetrated dairy and aquaculture operations in these states lack proximity to Midwest betaine extraction infrastructure, creating distribution white space for regional blending facilities.
- FSMA Preventive Controls Alignment:USDA-mandated hazard analysis requirements for animal feed ingredients favor betaine suppliers with documented supply chain traceability, disadvantaging spot-market methionine traders.
Industry Challenges
- USP Monograph Compliance Timeline:Pharmaceutical-grade betaine certification requires 18-24 month validation cycles for endotoxin and heavy metal testing, delaying entry into parenteral nutrition formulations.
- Cross-Contamination Controls:Multi-product feed mills must segregate betaine handling from coccidiostat and antibiotic premixes, necessitating dedicated pneumatic conveying infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Betaine Market |
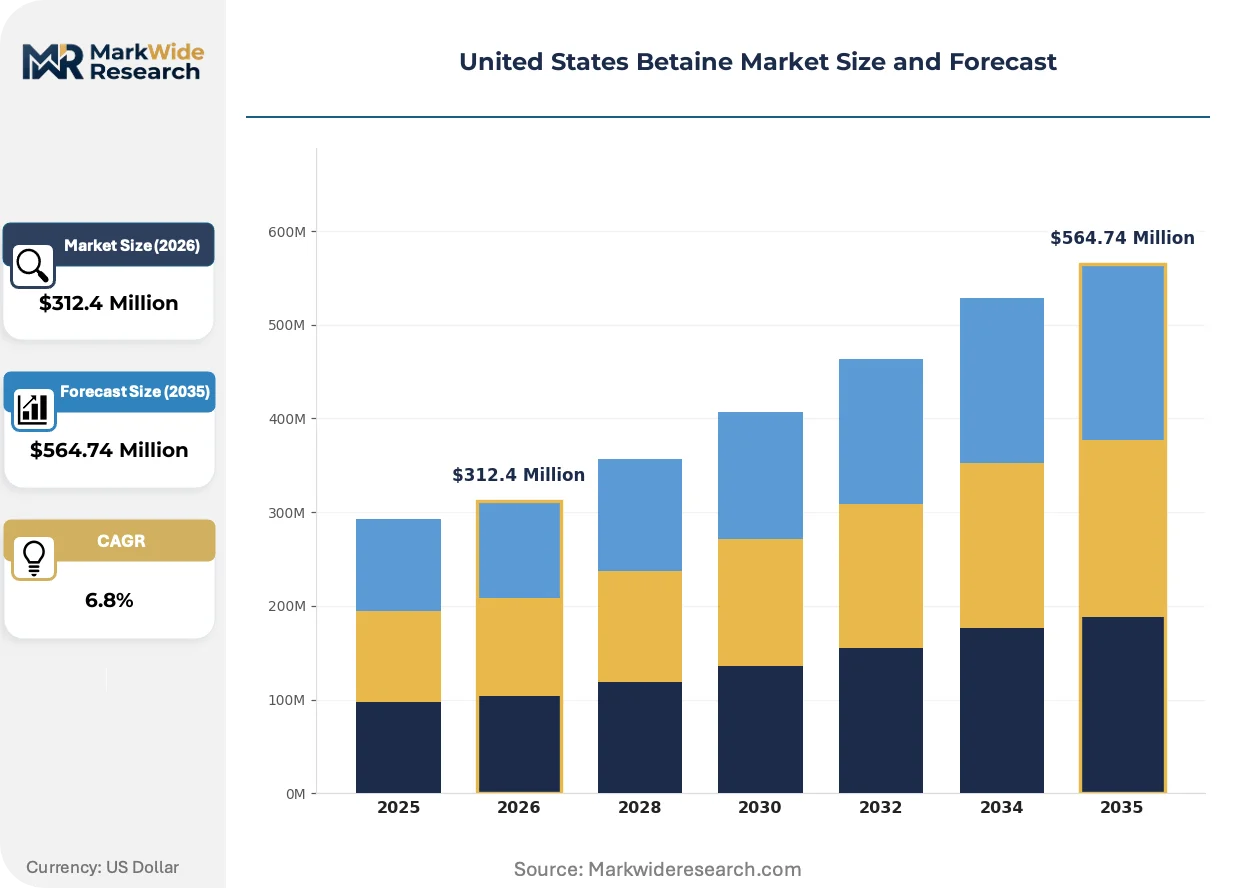
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Betaine, Synthetic Betaine, Betaine Anhydrous, Betaine Hydrochloride End User: Food & Beverage, Pharmaceutical, Cosmetics, Animal Feed Application: Dietary Supplements, Personal Care Products, Feed Additives, Industrial Applications Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Stepan Company, American Crystal Sugar Company, DuPont, Merck KGaA, AMINO GmbH, Evonik Industries AG, Kao Corporation, Esprix Technologies, Solvay, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Betaine Market Evolving Landscape
Formulation science and regulatory interpretation are diverging from historical feed-additive conventions, creating parallel innovation tracks in osmolyte health positioning, surfactant chemistry, and precision livestock nutrition delivery.
Fermentation-derived betaine is fragmenting the pharmaceutical-grade supply base. Bioprocess engineers at contract manufacturing organizations are deploying recombinant yeast strains to produce USP-compliant trimethylglycine without sugar-beet agricultural exposure. Specialty pharmaceutical compounders are adopting these batches for parenteral and enteral nutrition formulations. The technology is fragmenting procurement patterns away from agricultural co-product dependence toward controlled bioreactor output.
EPA effluent guidelines for chloroacetic acid derivatives are tightening discharge limits for synthetic betaine manufacturers. Facilities in Texas and Louisiana must retrofit wastewater treatment to meet revised maximum contaminant levels for organochlorine byproducts. Capital expenditure requirements are compressing synthetic capacity expansion plans, advantaging natural extraction pathways in beet-processing states.
Direct-to-farm feed additive distribution is bypassing traditional distributor networks. Large integrated pork and poultry operators in North Carolina and Arkansas are negotiating annual betaine supply contracts with extraction facilities, eliminating regional feed-dealer markups. This channel compression is most visible in sow farm and broiler breeder operations with captive milling capacity and certified on-site storage.
United States Betaine Market Segmentation
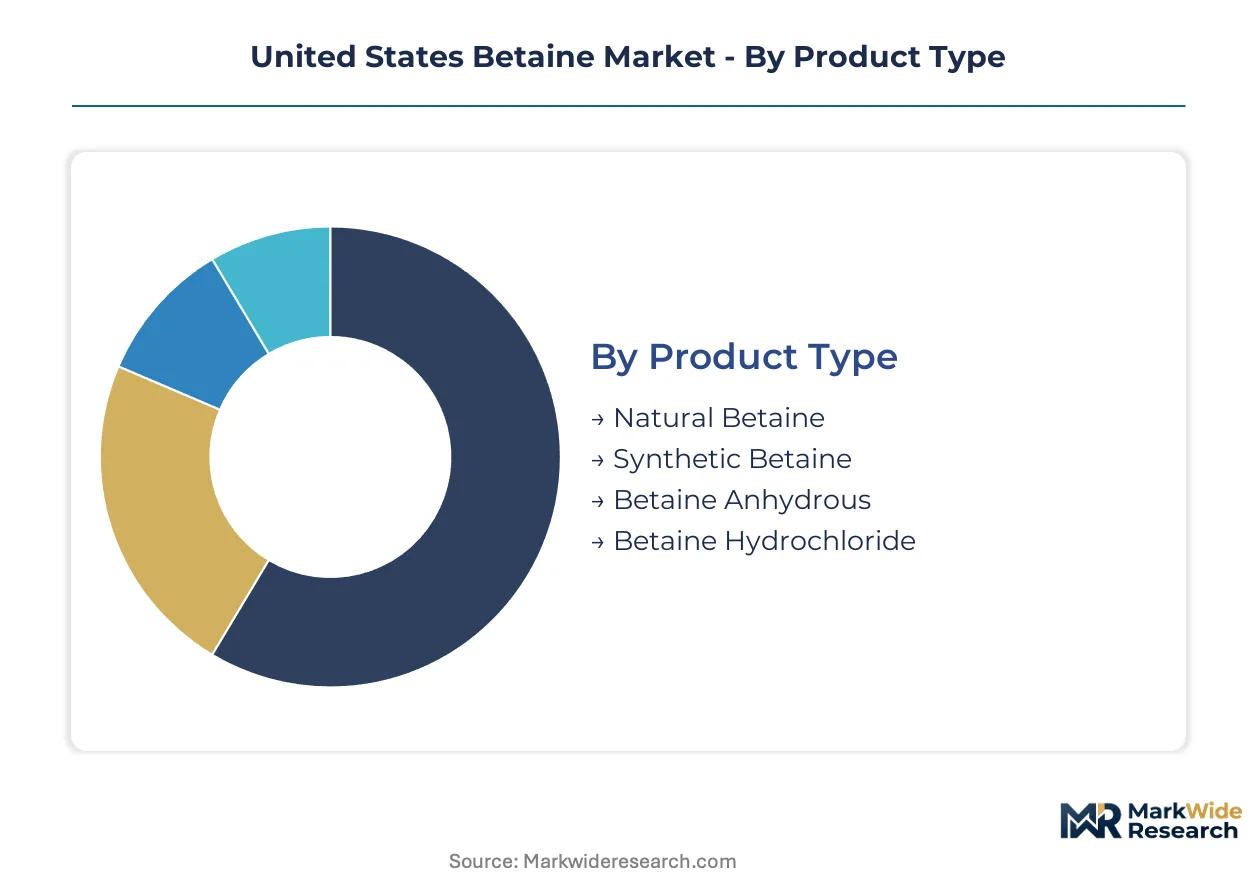
Segmentation in the United States betaine market determines pricing power, certification requirements, and channel access. Product origin and purity grade dictate whether volumes flow through commodity feed distributors or specialty chemical brokers.
Product Type:
Channel economics diverge sharply between agricultural co-product extraction and petrochemical synthesis, with purity thresholds determining whether betaine moves through feed-dealer networks or pharmaceutical ingredient brokers.
- Natural Betaine:Extracted from sugar-beet molasses via chromatographic separation, this grade carries agricultural-residue risk that restricts pharmaceutical use. Midwest ethanol processors and beet refiners in Minnesota and North Dakota dominate output, supplying regional feed compounders through bulk tanker delivery. Poultry integrators in Iowa prefer this grade for methionine substitution programs.
- Synthetic Betaine:Manufactured from monochloroacetic acid and trimethylamine through quaternization chemistry, this pathway achieves higher purity consistency required for USP-grade certification. Texas and Louisiana petrochemical corridors host production, though EPA effluent permits for organochlorine byproducts constrain capacity expansion. Personal care formulators source this grade for sulfate-free surfactant applications.
- Betaine Anhydrous:Crystalline form with minimal water content, favored by premix manufacturers for flowability in automated feed milling systems.
- Betaine Hydrochloride:Acid-stabilized variant common in dietary supplement tablets and capsules, distributed through nutraceutical ingredient distributors.
Natural betaine dominates installed base. Synthetic betaine is where expansion concentrates.
End User:
Customer sophistication and regulatory exposure create four distinct procurement patterns, from commodity spot purchasing to multi-year supply agreements with audit requirements.
- Animal Feed:Integrated pork and poultry operations in the Midwest corn belt negotiate annual contracts for bulk anhydrous delivery, bypassing traditional distributor markups through direct-to-farm supply chains. Methionine replacement economics drive adoption, though price volatility in Chinese DL-methionine imports periodically stalls conversion.
- Pharmaceutical:Parenteral and enteral nutrition compounders demand USP monograph compliance with endotoxin and heavy metal documentation, sourcing through validated contract manufacturers with 18-24 month qualification cycles. Fermentation-derived alternatives are fragmenting supply away from beet extraction dependence.
- Food & Beverage:Sports nutrition and functional beverage brands leverage FDA GRAS self-affirmation to accelerate formulation trials, purchasing through specialty ingredient distributors.
- Cosmetics:Rinse-off personal care brands adopt betaine as a mild amphoteric surfactant, with formulation houses sourcing through cosmetic chemical distributors.
Animal feed commands volume leadership. Pharmaceutical applications are climbing the fastest.
Application:
Performance requirements and regulatory pathways segment demand across nutrition, industrial, and consumer product matrices with incompatible certification standards.
- Feed Additives:Methyl donor functionality in poultry and swine diets represents the largest volume application, with USDA FSMA preventive controls favoring suppliers with documented supply chain traceability.
- Personal Care Products:Amphoteric surfactant properties enable sulfate-free shampoo and body wash formulations, with brands paying premiums above feed-grade pricing for cosmetic-grade certification.
- Dietary Supplements:Osmolyte health positioning in sports nutrition drives capsule and tablet demand, requiring USP or FCC grade verification.
- Industrial Applications:Cryoprotectant and viscosity modifier uses in specialty chemical manufacturing, sourced through industrial solvent distributors.
Feed additives anchor volume flows. Personal care products represent the steepest expansion trajectory.
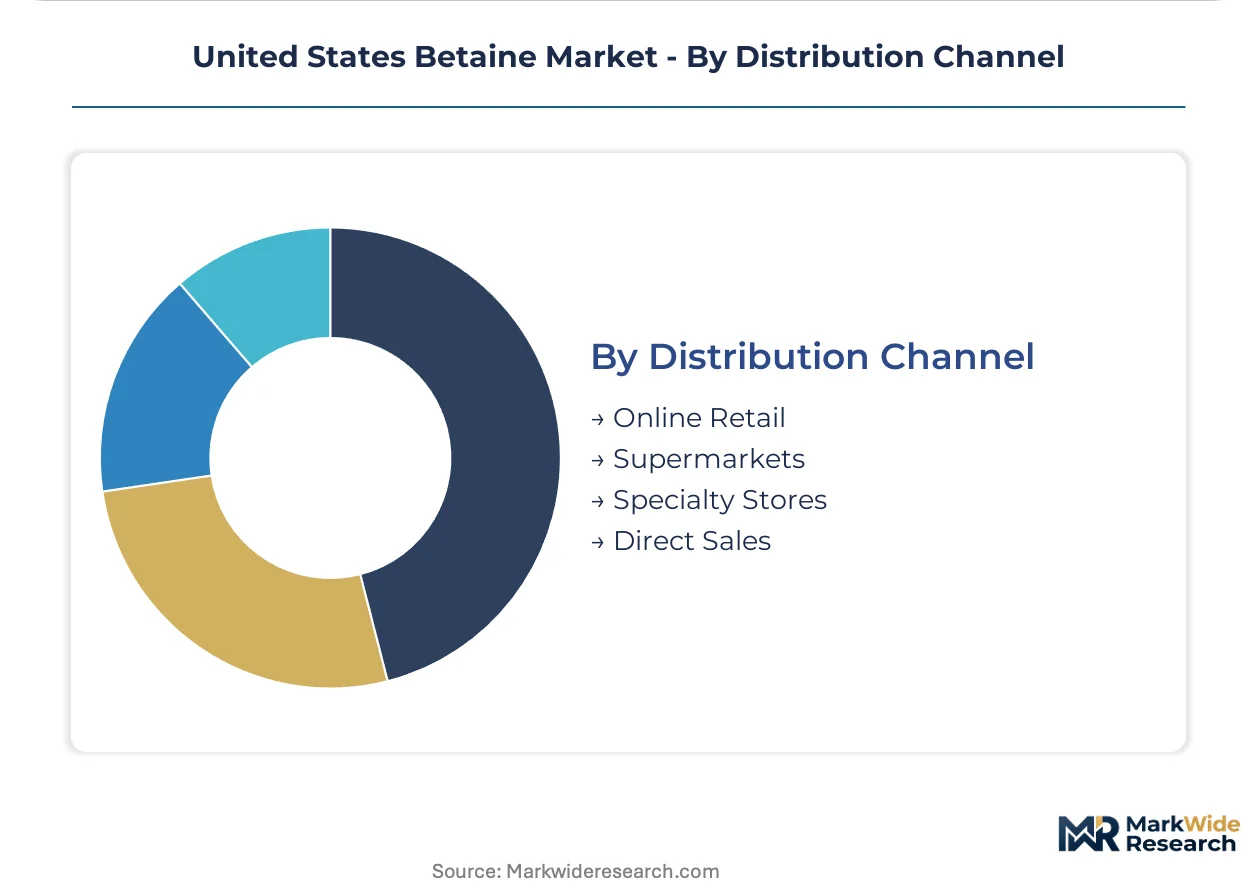
Distribution Channel:
Channel selection reflects customer scale, technical service requirements, and the need for regulatory documentation in audited supply chains.
- Direct Sales:Large integrated livestock operators with captive feed milling negotiate annual supply contracts with extraction facilities, eliminating regional dealer margins. This channel captures the majority of Midwest poultry and pork volume.
- Specialty Stores:Nutraceutical and cosmetic ingredient houses serve small-batch compounders requiring technical formulation support and certificate-of-analysis documentation.
- Online Retail:E-commerce platforms supply small-scale dietary supplement manufacturers and research institutions with packaged grades in sub-ton quantities.
- Supermarkets:Limited to consumer-facing betaine supplement products, not industrial or feed-grade volumes.
Direct sales dominate commercial volume. Specialty stores capture margin-rich pharmaceutical and cosmetic segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Mississippi River barge network and Union Pacific rail corridors enable bulk betaine distribution from Midwest extraction facilities to coastal feed compounders. Interstate highway density and refrigerated tanker access determine regional procurement economics for anhydrous and hydrochloride grades.
Midwest Corn Belt
Iowa and Illinois pork integrators are consolidating on-site feed milling, creating captive demand for bulk anhydrous betaine delivered via tanker. USDA FSMA preventive controls favor suppliers with documented traceability through this channel. Minnesota ethanol processors extract natural betaine from stillage, supplying regional poultry operations without transloading.
Southeast
North Carolina and Arkansas broiler breeders lack proximity to Midwest extraction infrastructure, importing betaine through Memphis and New Orleans port terminals. FDA GRAS self-affirmation accelerates formulation trials for regional sports nutrition brands in Atlanta. Georgia-based distributors serve small-batch compounders requiring certificate-of-analysis documentation.
Texas Gulf Coast
Petrochemical corridors host synthetic betaine production from chloroacetic acid precursors, though EPA effluent permits for organochlorine byproducts constrain capacity expansion. Houston-area surfactant manufacturers supply personal care formulators with cosmetic-grade certification. Underpenetrated dairy operations in the Panhandle create distribution white space for regional blending facilities.
California
Aquaculture operations in the Central Valley and dairy processors in the San Joaquin Valley source betaine through Los Angeles and Long Beach port terminals. State-level feed ingredient registration requirements differ from federal FSMA standards, altering channel economics for imported volumes. Bay Area fermentation startups are piloting recombinant yeast strains for pharmaceutical-grade output.
Pacific Northwest
Washington and Oregon represent nascent demand for betaine in salmon aquaculture and specialty poultry operations. Limited rail access from Midwest extraction facilities elevates landed costs relative to other regions. Portland-area distributors serve small-scale dietary supplement manufacturers with packaged hydrochloride grades in sub-ton quantities.
United States Betaine Market Competitive Landscape
Listed leaders compete with private specialists across certification tiers and geographic coverage. The market structures around three concentration nodes: agricultural co-product extraction in beet-processing states, petrochemical synthesis along the Gulf Coast, and fermentation-derived pharmaceutical grades. Strategic archetypes include integrated agribusinesses with captive molasses streams, diversified chemical conglomerates with surfactant heritage, and contract manufacturing organizations with USP validation capabilities. Competitive moves center on backward integration into ethanol stillage recovery and forward integration into direct-to-farm distribution.
Within the extraction-based tier, American Crystal Sugar Company anchors domestic natural supply through sugar-beet molasses processing in Minnesota and North Dakota. Stepan Company represents the surfactant-chemistry heritage archetype, supplying high-purity variants for personal care and industrial applications. DuPont occupies a position in the pharmaceutical-grade segment with fermentation-derived offerings that meet USP monograph standards.
| Leading Market Players |
|---|
| Stepan Company |
| American Crystal Sugar Company |
| DuPont |
| Merck KGaA |
| AMINO GmbH |
| Evonik Industries AG |
| Kao Corporation |
| Esprix Technologies |
| Solvay |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between Midwest ethanol processors and integrated livestock operators lock in both supply access and price visibility, insulating feed-grade volumes from spot-market methionine volatility while compressing margins for distributors excluded from direct negotiations.
Pricing Analysis
Volume-discount tiering separates USP-certified pharmaceutical batches from feed-grade anhydrous and cosmetic-grade surfactant variants. Price differentiation rests on certification burden and endotoxin documentation, with pharmaceutical compounders absorbing premiums for 18-24 month validation cycles. Cost compression in feed-grade tiers intensifies as Chinese DL-methionine imports periodically undercut betaine on a per-methyl-donor basis. Spot-market traders show acute price sensitivity; pharmaceutical formulators demonstrate inelastic demand for validated batches.
Supply Chain Analysis
Inventory cycles stretch 6-8 weeks for natural extraction facilities processing sugar-beet molasses, while synthetic manufacturers in Texas and Louisiana manage chloroacetic acid precursor lead times tied to refinery output schedules. Geographic supply concentration centers on Minnesota and North Dakota for natural betaine, with Texas and Louisiana hosting synthetic capacity. Raw material dependencies include sugar-beet agricultural streams, monochloroacetic acid petrochemical feedstocks, and trimethylamine reagents. Single-source vulnerability from American Crystal Sugar Company's dominance in domestic natural extraction creates structural risk. Distribution runs through direct-to-farm tanker delivery for integrated livestock operators and specialty chemical brokers for pharmaceutical and cosmetic channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping this market as direct-to-farm distribution bypasses traditional dealer networks, creating interoperability between ethanol co-product recovery and captive feed milling ecosystems that locks in volume flows outside conventional channel structures.
For Market Incumbents: Shield market position by securing backward integration into ethanol stillage recovery infrastructure and deepening FDA GRAS documentation for food-grade expansion. Methionine price arbitrage from Chinese fermentation capacity threatens feed-grade margins; vertical integration into Midwest extraction assets provides cost structure defense against commodity amino acid volatility.
For New Entrants and Emerging Players: Service-layer gaps in pharmaceutical-grade fermentation-derived supply create entry space for contract manufacturing organizations with USP validation capabilities. Underpenetrated dairy and aquaculture operations in California and Texas lack proximity to Midwest infrastructure, representing the most penetrable geography. A go-to-market angle anchored in FSMA-aligned traceability documentation addresses preventive control requirements that spot-market traders cannot satisfy.
For Investors and Strategic Acquirers: Fermentation-derived pharmaceutical-grade specialists with recombinant yeast platforms and validated contract manufacturing capabilities represent the priority acquisition archetype. Long-term viability over a multi-year window hinges on displacement of agricultural co-product dependence in parenteral nutrition channels. The signal to monitor is FDA guidance progression on osmolyte health claims, which would unlock formulation expansion in functional beverages and sports nutrition.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethanol Stillage Recovery | Captures natural betaine feedstock from Minnesota and Nebraska corn processors, shortening supply chains to Iowa poultry integrators. |
| USP Monograph Certification Investment | Enables parenteral nutrition entry through endotoxin and heavy metal validation cycles that pharmaceutical compounders require. |
| Direct-to-Farm Distribution Expansion | Bypasses regional feed-dealer markups by negotiating annual tanker contracts with North Carolina and Arkansas broiler breeders. |
| FSMA Preventive Controls Alignment | Documents supply chain traceability that USDA mandates for animal feed ingredients, disadvantaging spot-market methionine traders. |
| Fermentation-Derived Platform Development | Produces USP-compliant trimethylglycine without sugar-beet agricultural exposure, fragmenting procurement away from extraction dependence. |
Research Methodology
The analysis maps natural extraction, synthetic manufacturing, pharmaceutical-grade fermentation, and personal care surfactant sub-sectors, each validated through feed formulators, pharmaceutical compounders, cosmetic chemists, and ethanol processor operations managers. Primary interview intelligence triangulates against secondary sources including FDA GRAS notifications, EPA effluent permit databases, USDA FSMA guidance documents, and SEC filings from diversified chemical conglomerates. Bottom-up volume builds from facility-level capacity and utilization estimates reconcile with top-down demand segmentation across methyl donor, osmolyte, and surfactant applications.
Consistency checks validated outputs against external benchmarks including customs trade flows for betaine hydrochloride and anhydrous grades, American Crystal Sugar Company processing volume disclosures, and Stepan Company surfactant segment revenue allocations. The analytical framework models product origin, purity grade, end-use industry, and regional production hub dimensions across the projection horizon. CAGRs derive from segment-level volume trajectories weighted by price realization in pharmaceutical, feed, food, and cosmetic channels. Forecast inputs incorporate ethanol co-product recovery capacity expansion timelines and EPA effluent permit issuance patterns for synthetic manufacturers.
Underlying assumptions cover GRAS self-affirmation pathway stability, Midwest agricultural processor capacity utilization, and chloroacetic acid precursor supply continuity, with deviation risk concentrated in FDA guidance shifts on osmolyte health claims and state-level feed ingredient registration changes. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Global Formulation Additives Market
Additives
Global Corrosion Inhibitor Market
Additives
2-Ethylhexyl Nitrate (2EHN) Market
Additives
Global UV Absorbers Market
Additives
Low VOC Coating Additives Market
Additives
Global Coalescing Agent Market
Additives
Inorganic Filler Market
Additives
Global Sodium Acetate Market
Additives
South Africa Acidulants Market
Additives
Sodium Metabisulfite Market
Additives
Feedstuff Additives Market
Additives
Fuel Additives Market
Additives
North America Pectin Market
Additives
Dipotassium Guanylate Market
Additives
Tocopheryl Acetate Market
Additives
Global UV Stabilizers Market