
 Potting Mix Additives Market | 2026-2036
Potting Mix Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Potting Mix Additives Market Analytics
Buyer concentration among commercial nurseries is recalibrating procurement leverage across the potting mix additives supply chain. The Scotts Miracle-Gro Company leverages its retail distribution network to control shelf placement in North American garden centers. Sun Gro Horticulture anchors its position through peat-based substrate integration with regional perlite blending facilities. Klasmann-Deilmann dominates professional greenhouse supply in Western Europe with certified organic substrate lines.
Potting mix additives encompass mineral and organic materials blended into growing media to modify aeration, water retention, nutrient availability, or pH balance, with perlite typically expanded at 900°C to achieve 0.5-2.5mm granules for pore space optimization. These additives serve commercial propagation, container agriculture, and consumer gardening by replacing or supplementing native soil in controlled environments. Coconut coir represents the fastest-expanding product category as peat substitution pressures mount across European retail channels. Hydroponics application segments command premium pricing due to sterility requirements and customized electrical conductivity specifications. Organic palm-type formulations attract margin premiums from home gardeners and certified nursery operations despite higher raw material costs.
The EPA regulates heavy metal limits in soil amendments under the Toxic Substances Control Act, while the EU Fertilizing Products Regulation mandates CE conformity for organic and organo-mineral products entering member state markets. Oregon and California state agriculture departments enforce additional pathogen screening protocols for coconut coir imports, raising compliance costs for West Coast distributors. Stakeholders must monitor evolving peat restriction timelines and substrate certification harmonization between North American and European frameworks to anticipate raw material substitution curves.
Market Dynamics
Peat substitution mandates across European retail channels are compressing demand timelines for alternative substrates and forcing rapid raw material qualification cycles. Commercial greenhouse operators in the Netherlands and Germany now require additive suppliers to demonstrate carbon footprint documentation alongside traditional performance metrics.
Growth Catalysts
- EU Fertilizing Products Regulation:CE conformity requirements for organic and organo-mineral products create certification premiums for compliant additive blends entering member state markets.
- Hydroponics propagation:Controlled-environment agriculture facilities demand sterile, customized electrical conductivity specifications that command pricing premiums over standard nursery grades.
- Perlite expansion capacity:New high-temperature processing facilities in Greece and Turkey reduce freight exposure for Mediterranean greenhouse clusters.
Market Restraints
- Peat extraction moratoriums:Ireland and Baltic state harvesting restrictions constrain traditional substrate supply bases and accelerate cost pass-through to end-users.
- Coconut coir logistics:Container shipping volatility from Sri Lankan and Indian processing centers creates inventory planning friction for European distributors.
- Pathogen screening protocols:Oregon and California agriculture departments impose additional testing layers on coir imports, raising landed costs for West Coast nurseries.
Strategic Opportunities
- Urban vertical farming:Rooftop and warehouse cultivation in Singapore and the UAE creates demand for lightweight, engineered substrate formulations with precise drainage control.
- Biostimulant integration:Humic acid and seaweed extract infusion into perlite-coir matrices opens premium pricing tiers for organic certification holders.
- Direct-to-grower platforms:Digital procurement channels bypass traditional distribution markups for mid-scale greenhouse operations in Spain and Italy.
Industry Challenges
- Substrate chemist talent scarcity:Formulation expertise spanning mineralogy, plant physiology, and organic chemistry concentrates among aging specialists in Dutch research institutes.
- Batch-to-batch consistency:Natural variability in coconut coir fiber length and salt content requires real-time quality adjustment that strains blending facility throughput.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Potting Mix Additives Market |
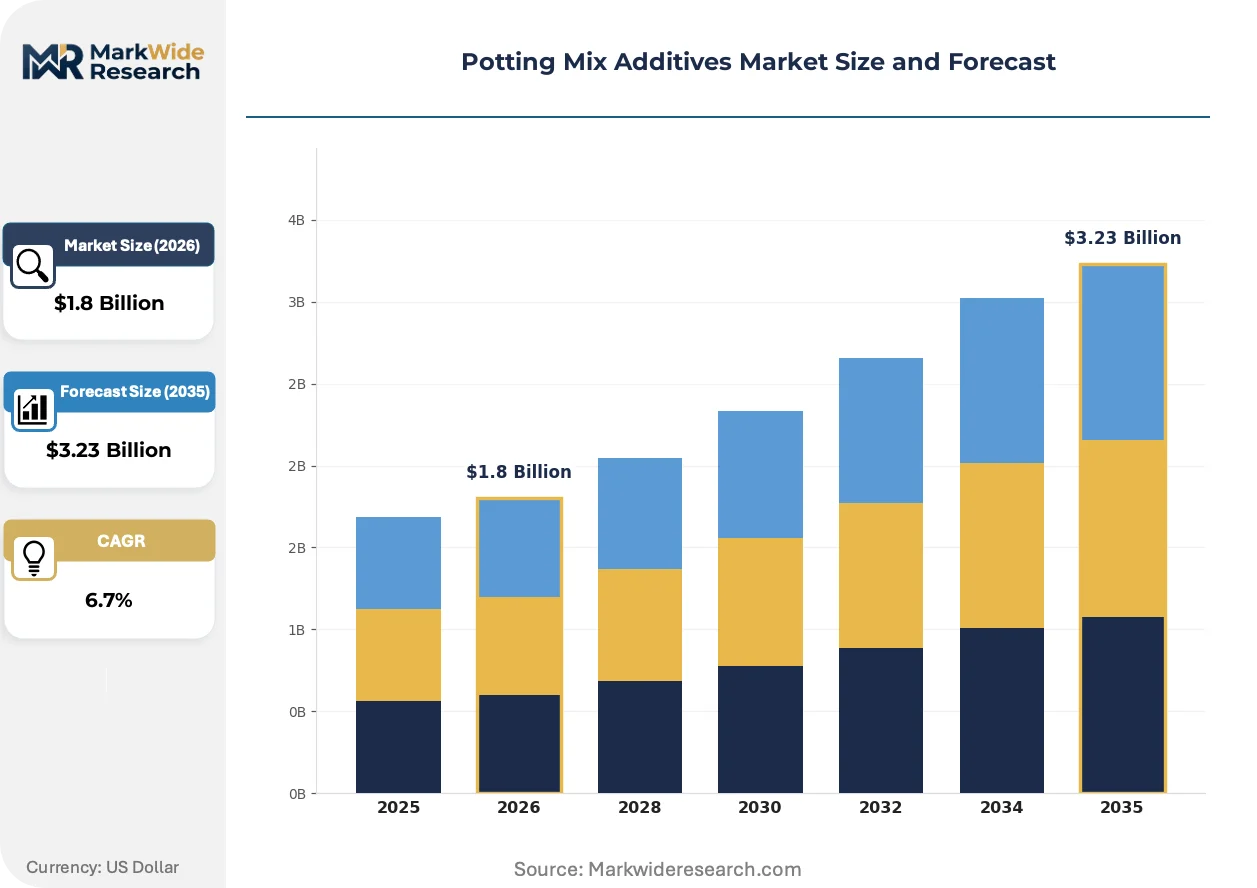
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pearlite, Vermiculite, Coconut Coir, Bark Application: Indoor Gardening, Outdoor Landscaping, Horticulture, Hydroponics End User: Commercial Nurseries, Home Gardeners, Agricultural Producers, Landscape Professionals Palm Type: Organic, Synthetic, Biodegradable, Mixed |
| Companies Covered | The Scotts Miracle-Gro Company, Sun Gro Horticulture, Premier Tech Horticulture, FoxFarm Soil & Fertilizer Company, Klasmann-Deilmann, ASB Greenworld, Espoma Company, Compo, Lambert, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Potting Mix Additives Market Evolving Landscape
Engineered biochar and composted bark fractions are displacing conventional mineral conditioners in premium growing media formulations. Additive suppliers now invest in pyrolysis and composting infrastructure to capture margin that previously flowed to raw material traders.
Biochar from agricultural residue pyrolysis is expanding into professional greenhouse substrates as a carbon-negative aeration agent with cation exchange capacity. Dutch tomato propagation facilities have adopted 15-20% biochar inclusion rates in coir-perlite blends. This technology is compressing demand for vermiculite in high-value vegetable transplant production.
The EU Fertilizing Products Regulation's 2026 implementation timeline for full CE marking enforcement is compressing supplier certification investments. Non-compliant organic amendments face market access barriers in Germany, France, and the Netherlands. Substrate blenders in Poland and Romania are accelerating laboratory testing partnerships to meet documentation requirements.
Certification-driven procurement now dominates commercial nursery purchasing decisions, with organic substrate labels displacing price-per-cubic-meter comparisons. German retail chains demand chain-of-custody documentation from propagation suppliers. This behavioral shift concentrates volume with additive producers holding EU organic and RHP quality certifications.
Potting Mix Additives Market Segmentation
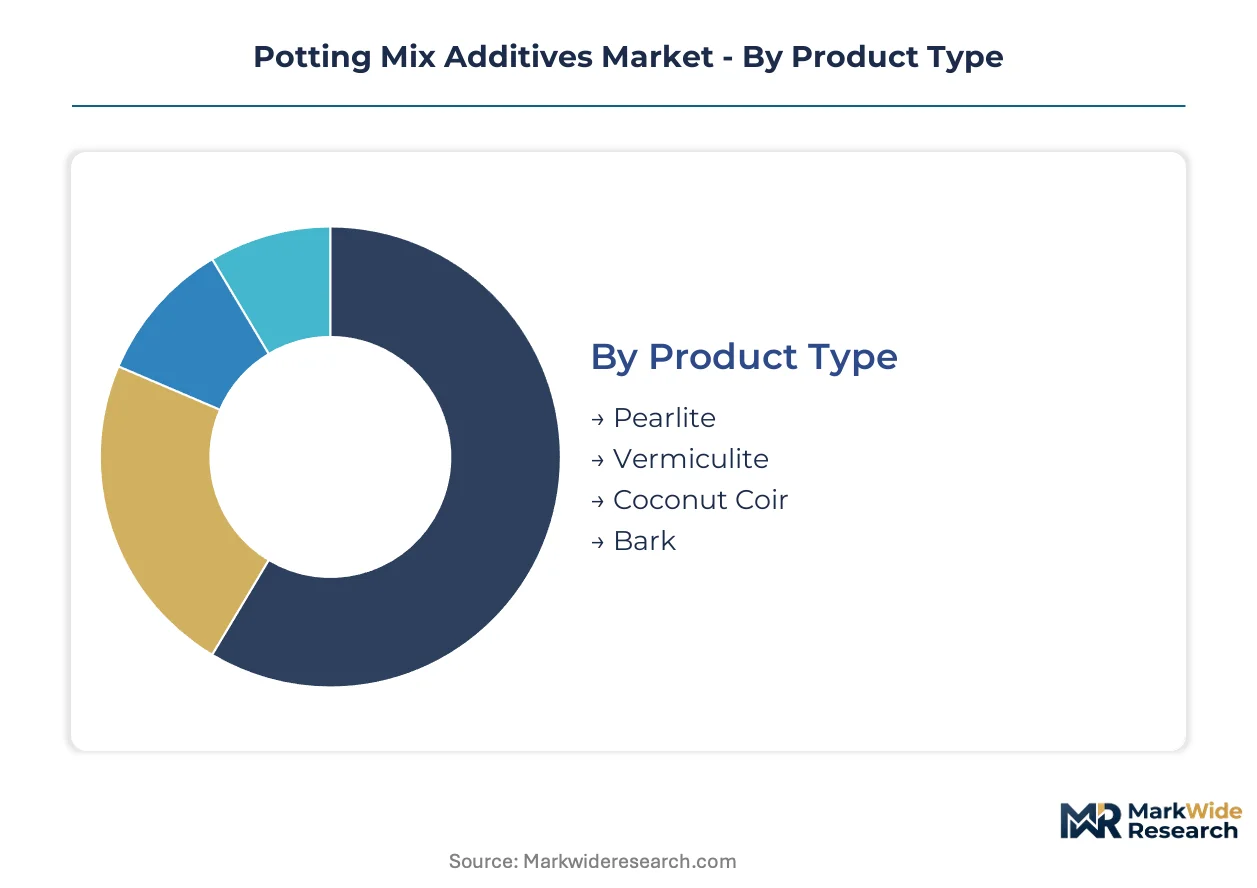
Potting mix additives fragment across mineral and organic chemistries, each commanding distinct procurement workflows and performance specifications. Buyers select substrates based on aeration requirements, water retention targets, and compliance obligations rather than commodity pricing alone.
Product Type:
Cost tier separates commodity mineral expanders from premium organic fibers in procurement negotiations.
- Perlite:Expanded volcanic glass processed at 900°C yields 0.5-2.5mm granules optimized for pore space. Dutch tomato propagation facilities specify perlite-coir blends for controlled drainage in hydroponic vegetable production.
- Coconut Coir:Pith and fiber fractions from Sri Lankan and Indian processing centers displace peat in European retail channels. German and French garden centers now mandate coir-based substrates to satisfy EU Green Deal sourcing requirements.
- Vermiculite:Hydrated laminar magnesium-aluminum-iron silicate serves high-temperature insulation and seed germination applications.
- Bark:Composted pine and fir fractions from Pacific Northwest forestry operations condition acidic-loving ornamentals.
Volume sits with perlite; growth tilts toward coconut coir.
Application:
Performance specifications intensify as cultivation environments shift from open-field to controlled systems.
- Hydroponics:Sterility mandates and customized electrical conductivity specifications command premium pricing tiers. Singapore and UAE vertical farming installations specify engineered substrate formulations with precise drainage control for rooftop and warehouse cultivation.
- Horticulture:Professional greenhouse operations in the Netherlands drive premium additive consumption for vegetable propagation.
- Indoor Gardening:Home cultivation of ornamentals and culinary herbs in urban apartments.
- Outdoor Landscaping:Container plantings and bed amendments for residential and commercial grounds.
Revenue concentrates in horticulture; margins expand fastest in hydroponics.
End User:
Procurement scale and certification requirements diverge sharply between professional and consumer channels.
- Commercial Nurseries:Volume purchasers in the United States expand orders for organic perlite and coconut coir blends. Oregon and California agriculture departments impose additional pathogen screening protocols on coir imports, raising compliance costs for West Coast distributors.
- Agricultural Producers:Large-scale vegetable and berry operations integrate substrates into mechanized transplanting systems.
- Home Gardeners:Retail consumers select pre-blended products based on organic certification labels.
- Landscape Professionals:Installation contractors specify bulk substrates for commercial and municipal projects.
Procurement volume aggregates with commercial nurseries; certification premiums attract agricultural producers.
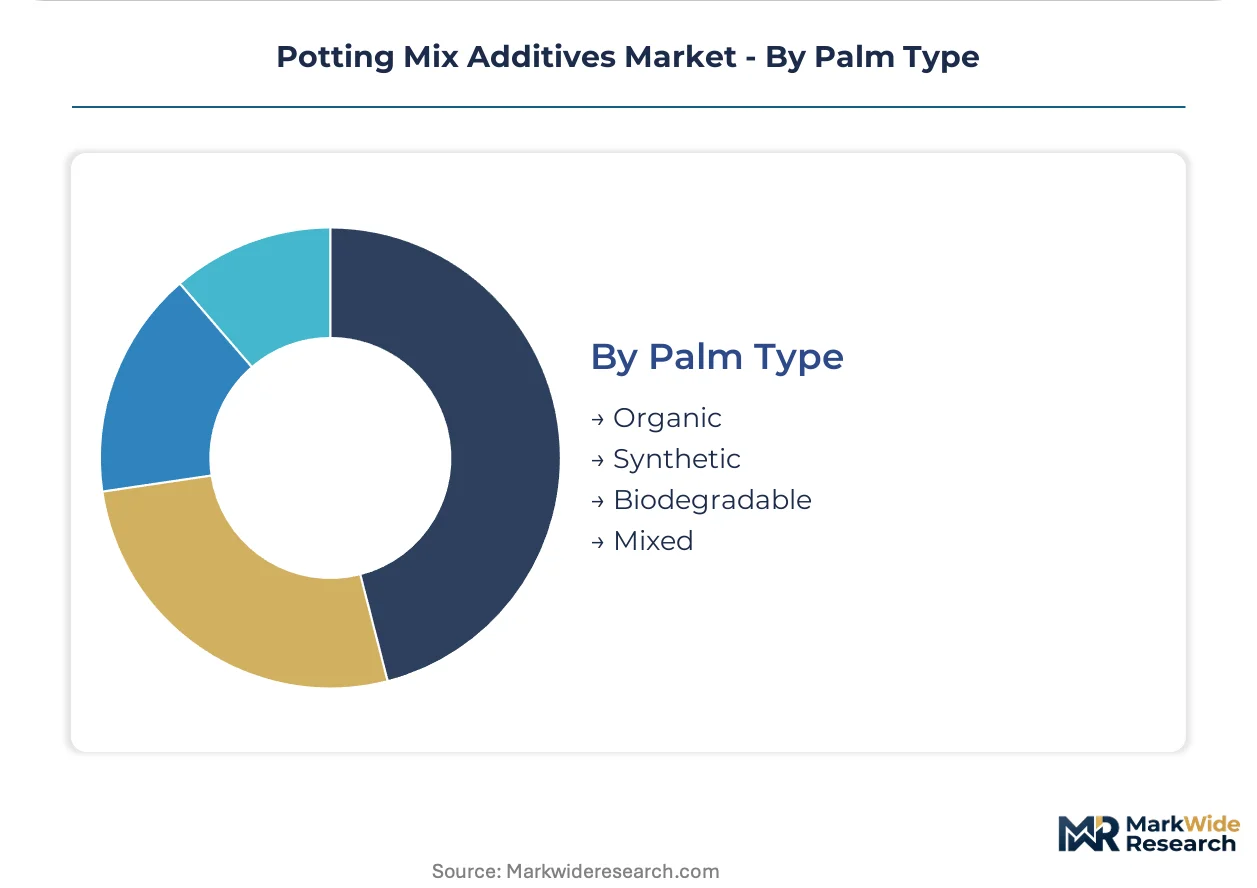
Palm Type:
Label claims and chain-of-custody documentation now outweigh price-per-cubic-meter in purchasing decisions.
- Organic:Certified substrate lines from Klasmann-Deilmann and EU-compliant blenders capture professional greenhouse supply in Western Europe. German retail chains demand complete chain-of-custody documentation from propagation suppliers.
- Biodegradable:Time-bound decomposition specifications for temporary container applications.
- Synthetic:Polymer-based conditioners for industrial-scale floriculture operations.
- Mixed:Hybrid formulations balancing cost and performance across variable growing conditions.
Certification share clusters with organic; biodegradable formulations gain traction in temporary propagation systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Perlite deposits in Greece and Turkey anchor Mediterranean supply chains for European greenhouse clusters. Coconut coir processing centers in Sri Lanka and India feed peat substitution demand across Northern European retail channels.
United States
Commercial nurseries in Oregon and California scale orders for organic perlite-coir blends. The EPA regulates heavy metal limits in soil amendments under the Toxic Substances Control Act. West Coast distributors face elevated compliance costs from state agriculture department pathogen screening protocols on coir imports.
Germany
German retail chains now mandate complete chain-of-custody documentation from propagation suppliers. The EU Fertilizing Products Regulation mandates CE conformity for organic amendments entering member state markets. Professional greenhouse operations in Lower Saxony drive premium substrate consumption for vegetable transplant production.
Netherlands
Dutch tomato propagation facilities specify engineered perlite-coir blends for hydroponic drainage control. The EU Green Deal sourcing requirements compress peat substitution timelines across retail channels. Greenhouse vegetable operations in Westland cluster consume premium additive volumes at 15-20% biochar inclusion rates.
China
Domestic perlite expansion capacity serves controlled-environment agriculture installations in Shandong and Jiangsu provinces. The Ministry of Ecology and Environment enforces dual carbon goals that reshape substrate processing energy profiles. Yangtze River Delta vertical farming pilots specify lightweight engineered formulations for rooftop cultivation.
United Arab Emirates
Singapore and UAE urban vertical farming installations create demand for precision drainage substrates. MOHAP oversees agricultural input safety standards for imported growing media. Dubai-based warehouse cultivation facilities source customized electrical conductivity specifications from Mediterranean suppliers.
Potting Mix Additives Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue biochar integration and direct-to-grower digital channels. The supplier base concentrates around peat-based substrate integrators, mineral expanders with captive processing infrastructure, and certified organic blenders serving professional greenhouse procurement. Three archetypes dominate: retail brand owners controlling shelf placement, regional substrate blenders with perlite expansion assets, and certified organic specialists holding EU quality accreditations. Capacity expansion in Mediterranean perlite processing and laboratory testing partnerships in Eastern Europe represent the dominant competitive vectors.
Among North American retail brand owners, The Scotts Miracle-Gro Company exemplifies distribution network leverage. Sun Gro Horticulture occupies a position among regional substrate blenders with integrated perlite facilities. Klasmann-Deilmann represents the certified organic specialist archetype serving Western European professional greenhouse supply.
| Leading Market Players |
|---|
| The Scotts Miracle-Gro Company |
| Sun Gro Horticulture |
| Premier Tech Horticulture |
| FoxFarm Soil & Fertilizer Company |
| Klasmann-Deilmann |
| ASB Greenworld |
| Espoma Company |
| Compo |
| Lambert |
| Others |
Value Network & Pricing Analysis
Perlite spot pricing from Greek and Turkish expansion facilities cascades through three distinct procurement tiers. Container freight indices from Sri Lankan coir processing centers feed directly into landed cost calculations for European distributors, compressing margins on standard-grade blends while organic-certified lines retain pricing power.
Pricing Analysis
Certification-bundling separates compliant substrate lines from uncertified commodity grades. Three-tier pricing structure across premium, standard, and economy levels tracks EU organic certification, RHP quality marks, and basic mineral expanders. Price differentiation hinges on chain-of-custody documentation and laboratory testing investment. Cost compression in standard perlite-coir blends is intensifying because Mediterranean capacity additions expand supply. Home gardeners exhibit highest price sensitivity; Dutch greenhouse operators prioritize performance specifications over per-cubic-meter rates.
Supply Chain Analysis
Direct-to-grower digital platforms and traditional distribution markups serve divergent buyer scale segments. Geographic supply concentration centers on Greece, Turkey, and the Mediterranean basin for perlite expansion, with Sri Lanka and India anchoring coconut coir fiber processing. Raw material dependencies draw from volcanic glass deposits, palm husk agricultural residue, and forestry bark fractions. Single-source vulnerability in Sri Lankan coir pith supply creates inventory planning friction during monsoon shipping disruptions. Distribution runs through regional blending facilities with captive perlite expansion assets, agricultural input distributors, and retail garden center networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
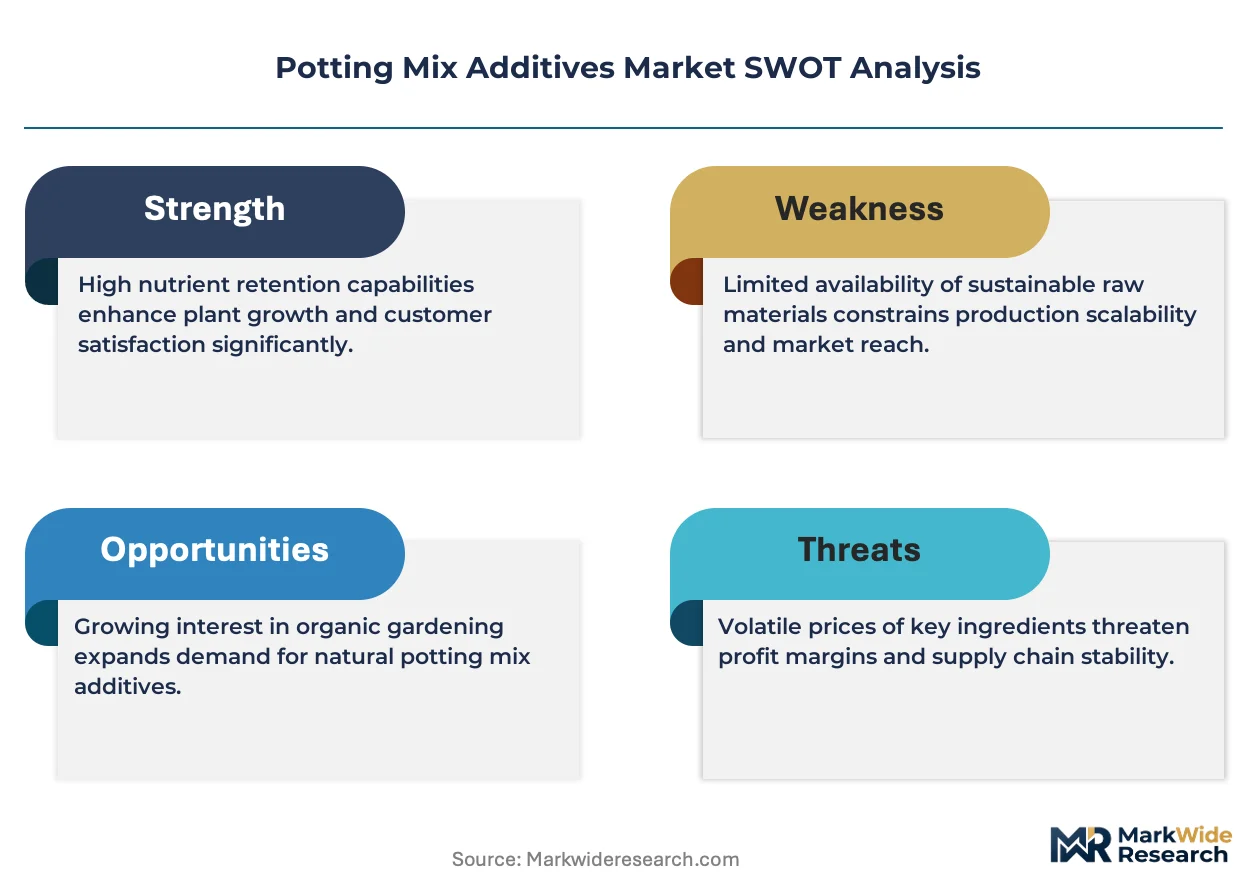
The EU Fertilizing Products Regulation erects a compliance moat that favors incumbent additive producers with laboratory testing infrastructure and CE marking capabilities. Non-compliant organic amendments face market access barriers that concentrate volume with certified specialists.
For Market Incumbents: Anticipate biochar displacement of vermiculite in high-value vegetable transplant production by securing pyrolysis partnerships or in-house production capabilities. Accelerate certification investments ahead of full CE marking enforcement to capture German and Dutch greenhouse procurement. Defend against direct-to-grower digital entrants by tightening channel control through volume commitment contracts with mid-scale Spanish and Italian operations. For New Entrants and Emerging Players: Premium-to-economy price spreads in organic substrate lines present white-space entry points for certified regional blenders. Target Polish and Romanian laboratory testing partnerships to meet documentation requirements for EU market access. Pursue urban vertical farming installations in Singapore and UAE with lightweight engineered formulations as the most penetrable application segment. Launch through direct-to-grower digital procurement channels to bypass established distribution markups. For Investors and Strategic Acquirers: Distressed-cycle entries favor certified organic substrate specialists with EU quality accreditations in Western Europe. Long-term viability over the projection horizon rests on peat substitution acceleration and carbon footprint documentation capabilities. Monitor biochar inclusion rate adoption curves in Dutch tomato propagation facilities as the inflection indicator for mineral conditioner displacement.| Strategic Initiative | Industry Significance |
|---|---|
| CE Certification Investment | EU Fertilizing Products Regulation compliance unlocks German, French, and Dutch greenhouse procurement channels. |
| Backward Integration into Coir Processing | Captive Sri Lankan or Indian pith drying capacity reduces container shipping volatility exposure. |
| Biochar Pyrolysis Infrastructure | Agricultural residue carbon-negative aeration agents capture margin from vermiculite displacement in vegetable substrates. |
| Direct-to-Grower Platform Launch | Digital procurement channels bypass traditional distribution markups for mid-scale Mediterranean greenhouse operations. |
| Regional Perlite Expansion Capacity | Greek and Turkish high-temperature processing facilities reduce freight exposure for Mediterranean greenhouse clusters. |
Research Methodology
Trade databases, agricultural input customs records, and EU regulatory filing repositories formed the secondary backbone for volume and trade flow calibration. Primary interviews with commercial nursery procurement directors, substrate formulation chemists, greenhouse operations managers, and agricultural input distributors combined with secondary validation. Bottom-up and top-down triangulation reconciled facility-level capacity assessments against end-use consumption patterns.
Bottom-up modeling tracked additive consumption by product type, application intensity, and end-user procurement scale across the analysis window. Segmentation dimensions included mineral versus organic chemistry, hydroponics versus horticulture versus indoor gardening applications, and commercial nursery versus home gardener channels. CAGRs derived from trend extrapolation of peat substitution rates, biochar adoption curves, and regulatory compliance timelines. Industry-specific forecast inputs incorporated EU Green Deal sourcing requirement implementation and vertical farming installation pipelines.
Inputs from greenhouse operator procurement databases and substrate blender production records were available through the study window; gaps in real-time coconut coir fiber quality variability introduce uncertainty bands around batch-to-batch consistency assumptions. Forecasts reflect documented assumptions regarding regulatory harmonization and raw material substitution elasticity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Tricalcium Citrate Market
Additives
Metal Deactivators Market
Additives
Asia-Pacific Fuel Additives Market
Additives
Inhibited Propylene Glycol Market
Additives
Inorganic Rheology Modifiers Market
Additives
Friction Modifier Additives Market
Additives
Nucleating and Clarifying Agents Market
Additives
Phenolic Antioxidant Market
Additives
Low-Carbon Concrete Shrinkage-Reduction Additives Market
Additives
Epoxy Type Stabilizers Market
Additives
Antimicrobial Additives Market
Additives
Lubricant Additives Market
Additives
Indonesia Feed Additives Market
Additives
Silage Additives Market
Additives
Global PVC Additives Market
Additives
Adjustive Agents Market