
 Polysaccharides and Oligosaccharides Market | 2026-2036
Polysaccharides and Oligosaccharides Market Size, Share, and Industry Trends Forecast 2026-2036
Polysaccharides and Oligosaccharides Market Outlook
Ingredient supply chains for functional carbohydrates is reconfiguring as manufacturers seek dual-source security for hydrocolloid and prebiotic feedstocks. Cargill leverages its North American corn wet milling infrastructure to anchor global starch derivative output. Tate & Lyle competes through specialty fiber and modified starch portfolios tailored to clean-label food reformulation.
Polysaccharides and oligosaccharides comprise long-chain and short-chain carbohydrate polymers with repeating monosaccharide units, typically featuring molecular weights from hundreds to millions of daltons and glycosidic linkages that determine solubility, viscosity, and fermentability; these properties make them indispensable as thickeners, stabilizers, prebiotics, and drug delivery matrices across food, pharma, and personal care systems. Starch derivatives occupy the largest value pool given their ubiquity in processed food texture modification, while chitosan from crustacean sources represents the fastest-expanding segment as antimicrobial and wound-healing applications multiply in medical device formulations. Plant-based sourcing still dominates volume, though microbial fermentation routes are gaining traction for precision-tailored oligosaccharide structures.
The FDA scrutinizes novel polysaccharide excipients through its Emerging Technology Program, while EMA's MDR framework imposes biocompatibility documentation burdens on chitosan-based medical devices. China's NMPA accelerates local registration timelines for microbial-sourced oligosaccharides, redirecting investment toward domestic fermentation capacity. Stakeholders must track how divergent purity standards across FDA, EMA, and NMPA pathways reshape qualification costs and geographic manufacturing commitments.
Market Dynamics
Pharmaceutical pipelines are absorbing oligosaccharide excipients at accelerating rates, while FDA's tightening novel excipient guidance forces manufacturers to front-load biocompatibility documentation before commercial scale-up.
Growth Catalysts
- Prebiotic formulation expansion:Functional food manufacturers in China are integrating microbial-sourced oligosaccharides into infant nutrition and senior dietary products, supported by NMPA's accelerated local registration pathways.
- Wound-healing device demand:Chitosan-based antimicrobial dressings are penetrating hospital procurement channels across Germany and France as EMA's MDR framework elevates biocompatibility standards that favor proven polysaccharide matrices.
- Fermentation infrastructure investment:Precision-tailored oligosaccharide structures from microbial routes are attracting capital as plant-based feedstock volatility pressures hydrocolloid cost structures.
Market Restraints
- Crustacean supply concentration:Chitosan raw material dependence on Southeast Asian shrimp processing clusters exposes processors to seasonal harvest fluctuations and aquaculture disease outbreaks.
- Novel excipient qualification costs:FDA's Emerging Technology Program demands extensive toxicology dossiers that extend time-to-market for innovative polysaccharide carriers by 18-36 months.
- Starch derivative substitution:Cellulose ethers and synthetic hydrocolloids are capturing clean-label reformulation contracts where modified starches face consumer perception headwinds.
Strategic Opportunities
- India's PLI scheme leverage:Contract fermentation capacity under India's production-linked incentive framework offers cost-competitive microbial oligosaccharide manufacturing for export-oriented pharmaceutical clients.
- Dual-source security mandates:North American and European food manufacturers are qualifying secondary polysaccharide suppliers to derisk concentrated Asian hydrocolloid sourcing.
- Personalized nutrition convergence:Gut microbiome testing integration with prebiotic supplementation protocols is creating direct-to-consumer oligosaccharide formulation channels.
Industry Challenges
- Glycosidic linkage analytical expertise:Advanced carbohydrate structural characterization requires scarce mass spectrometry specialists, creating recruitment bottlenecks for quality control expansion.
- Cross-regulatory dossier harmonization:Divergent purity specifications between FDA, EMA, and NMPA pathways force manufacturers to maintain multiple analytical method validations.
- Legacy starch processing retrofit:Wet milling facilities require substantial capital redeployment to handle microbial fermentation feedstocks alongside traditional corn and tapioca lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polysaccharides and Oligosaccharides Market |
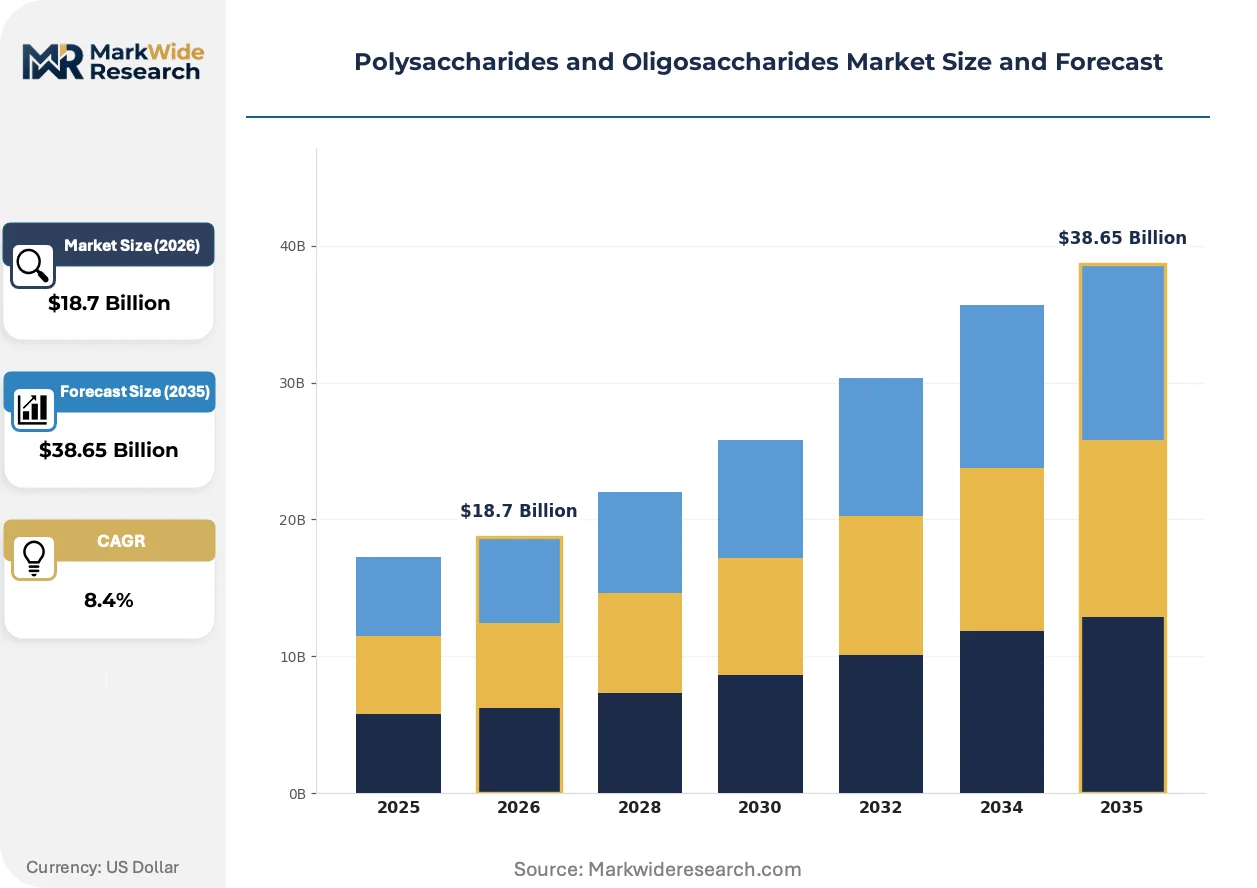
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Starch, Cellulose, Pectin, Chitosan Application: Food & Beverages, Pharmaceuticals, Cosmetics, Animal Feed Source: Plant-based, Microbial, Seaweed, Synthetic Form: Powder, Liquid, Granules, Capsules |
| Companies Covered | Tate & Lyle, BENEO, Cargill, IFF, CP Kelco, DuPont, FrieslandCampina, Ingredion, Archer Daniels Midland, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polysaccharides and Oligosaccharides Market Strategic Shifts
Enzymatic precision is displacing chemical modification as the dominant production paradigm, enabling molecular weight control that unlocks targeted pharmacokinetic profiles in drug delivery applications.
Precision enzymatic synthesis platforms are enabling site-specific glycosidic bond formation that chemical routes cannot replicate. Biopharma formulators are adopting these materials for controlled-release oral dosage matrices. The technology is migrating from specialty pharmaceutical applications toward broader nutraceutical encapsulation systems as unit economics improve.
EMA's Medical Device Regulation is tightening biocompatibility documentation requirements for implantable chitosan products. Manufacturers must now submit extended cytotoxicity and sensitization data packages. Wound-healing segment players are responding by consolidating testing partnerships with notified bodies in Germany and the Netherlands.
Hospital procurement coalitions are consolidating polysaccharide excipient purchasing through centralized tender platforms. Traditional distributor networks are losing share to direct manufacturer relationships with GPOs. This concentration is most visible in the United States, where three major purchasing alliances now control over half of institutional parenteral nutrition formulation supply.
Polysaccharides and Oligosaccharides Market Segmentation
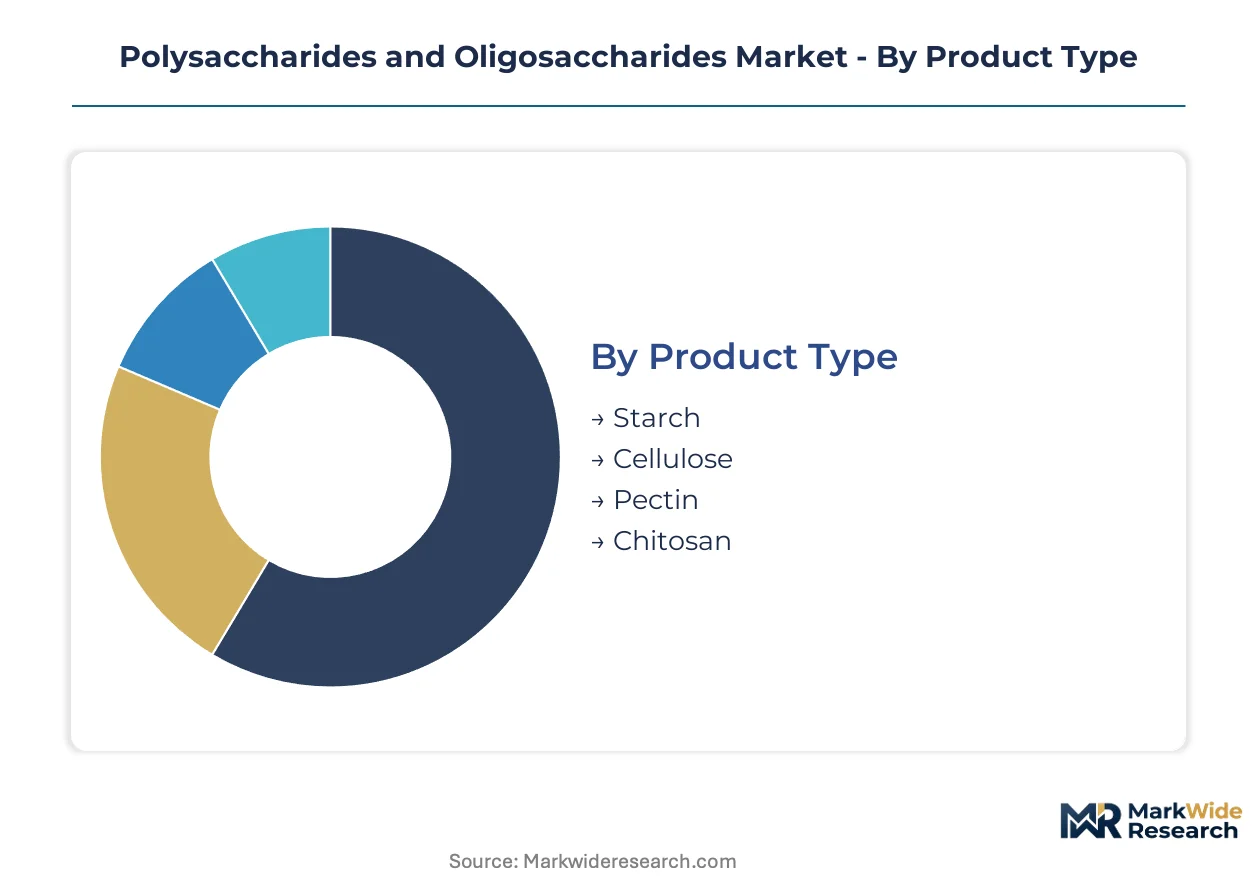
Structural heterogeneity across polysaccharide and oligosaccharide categories demands granular segmentation. Product chemistry, sourcing biology, and formulation requirements create distinct value pools with divergent margin profiles and regulatory pathways.
Product Type:
Cost tier differentiation separates commodity hydrocolloids from specialty biomedical grades.
- Starch:Derivatives dominate processed food texture modification through modified amylopectin structures. North American wet milling infrastructure anchors global output, though clean-label reformulation pressures erode modified starch contracts in premium retail channels.
- Chitosan:Crustacean-sourced deacetylated chitin delivers antimicrobial and hemostatic properties unmatched by plant alternatives. German and French hospital procurement channels are consolidating purchases of chitosan wound dressings as EMA MDR biocompatibility documentation requirements favor established suppliers.
- Cellulose:Microcrystalline grades serve pharmaceutical tablet binding and disintegration functions.
- Pectin:Citrus and apple extraction yields gelling agents for reduced-sugar confectionery systems.
Starch commands the established base. The steepest expansion runs through chitosan.
Application:
End-use concentration patterns reveal where formulation science creates pricing power.
- Food & Beverages:Hydrocolloid stabilizers and prebiotic fibers integrate across infant nutrition, plant-based dairy alternatives, and senior dietary products. Chinese functional food manufacturers are accelerating microbial-sourced oligosaccharide adoption supported by NMPA streamlined registration pathways.
- Pharmaceuticals:Excipient-grade polysaccharides enable controlled-release oral dosage matrices and parenteral nutrition emulsification. FDA's Emerging Technology Program demands front-loaded toxicology dossiers that extend qualification timelines for novel carriers.
- Cosmetics:Film-forming and moisture-retention properties drive chitosan and hyaluronic acid derivative demand.
- Animal Feed:Prebiotic oligosaccharides modulate gut microbiota in poultry and swine production systems.
Food and beverage applications anchor volume. Pharmaceutical qualification creates the steepest value expansion trajectory.
Source:
Supply biology determines purity specifications, batch consistency, and geographic manufacturing commitments.
- Plant-based:Corn, tapioca, and citrus extraction routes still dominate hydrocolloid volume. Cargill's North American wet milling network and Southeast Asian cassava processing clusters concentrate upstream supply.
- Microbial:Precision fermentation enables tailored oligosaccharide structures with defined glycosidic linkages. India's PLI scheme is attracting contract manufacturing investment for export-oriented pharmaceutical clients seeking dual-source security.
- Seaweed:Carrageenan and alginate extraction from red and brown algae serves food gelling and biomedical applications.
- Synthetic:Chemically polymerized saccharide analogs capture niche pharmaceutical applications requiring non-biological contamination profiles.
Plant-based sourcing retains volume leadership. Microbial routes are climbing the fastest as precision structures command formulation premiums.
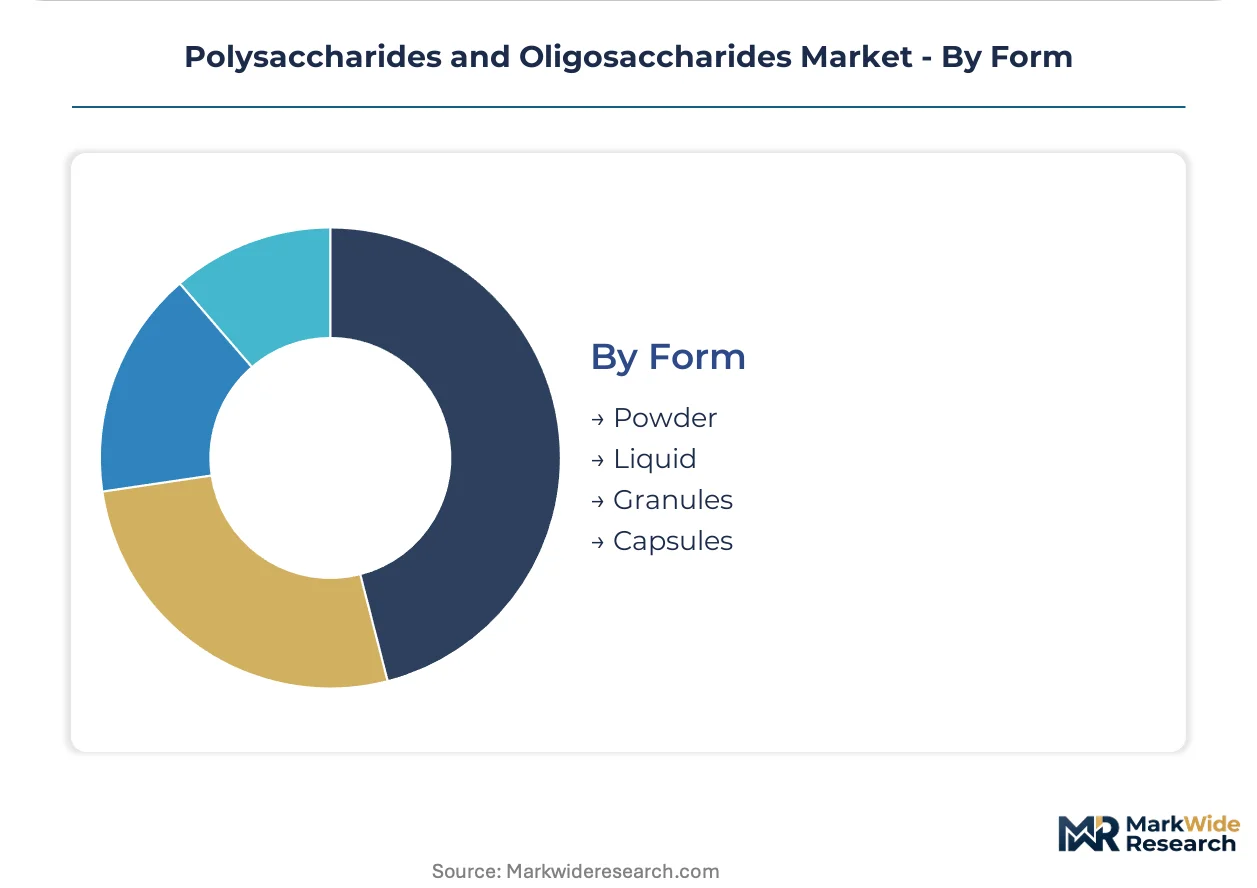
Form:
Physical state dictates handling infrastructure, shelf stability, and dosing precision in downstream systems.
- Powder:Spray-dried and milled grades dominate bulk ingredient logistics and dry-blend food manufacturing. Hygroscopicity management requirements differentiate pharmaceutical-grade specifications from industrial hydrocolloid grades.
- Liquid:Pre-hydrated solutions and concentrated suspensions eliminate dissolution steps in high-throughput beverage and personal care production lines.
- Granules:Agglomerated forms improve flow properties for direct-compression tablet manufacturing.
- Capsules:Pre-metered unit doses serve nutraceutical and clinical nutrition applications requiring precise oligosaccharide quantities.
Powder forms command the established base. Liquid concentrates are gaining share fastest in automated manufacturing environments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's specialized liquid bulk terminals anchor European hydrocolloid import flows, while China's Ningbo-Zhoushan port complex handles the largest volume of crustacean-derived chitosan feedstock globally. These maritime gateways determine regional manufacturing cost structures and supply security calculations.
United States
Pharmaceutical excipient demand from Boston and San Francisco biotech clusters drives high-purity polysaccharide consumption. FDA's Emerging Technology Program imposes extended toxicology documentation timelines on novel carriers. Corn wet milling infrastructure concentrated in Iowa and Illinois supplies modified starch derivatives for domestic food processing.
China
Domestic biopharma contract manufacturers in Suzhou and Shanghai are expanding microbial-sourced oligosaccharide fermentation capacity. NMPA accelerates local registration pathways for precision-tailored carbohydrate structures. Yangtze River Delta chemical parks host the largest concentration of chitosan processing facilities outside Southeast Asia.
Germany
Hospital procurement coalitions across Bavaria and North Rhine-Westphalia consolidate chitosan wound dressing purchases. EMA's MDR framework elevates biocompatibility documentation burdens that favor established polysaccharide matrix suppliers. Cologne-Düsseldorf industrial corridor houses specialized analytical laboratories for glycosidic linkage characterization.
India
Contract fermentation capacity under the PLI scheme attracts export-oriented pharmaceutical clients seeking dual-source security. CDSCO streamlined pathways for microbial oligosaccharide APIs redirect investment toward Hyderabad and Bengaluru biotech parks. Gujarat's specialty chemical zones develop precision carbohydrate manufacturing infrastructure.
Japan
Aging demographics expand senior dietary product formulations incorporating prebiotic fibers. PMDA maintains stringent purity specifications for pharmaceutical-grade polysaccharides that exceed regional benchmarks. Osaka-Kobe industrial region concentrates hyaluronic acid derivative production for cosmetic and medical device applications.
Polysaccharides and Oligosaccharides Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in raw material and precision synthesis niches. The vendor base stratifies between multinational hydrocolloid portfolios and regional fermentation specialists. Three archetypes dominate: agricultural commodity processors with wet milling infrastructure, precision biotech platforms with enzymatic synthesis capabilities, and crustacean processing cooperatives with chitin extraction expertise. Capacity expansion and strategic partnerships represent the primary competitive vectors as manufacturers seek geographic diversification.
Among North American agricultural processors, Cargill and Ingredion occupy positions anchored by corn wet milling networks, while Tate & Lyle exemplifies the specialty fiber and modified starch archetype tailored to clean-label reformulation. European ingredient platforms including BENEO and FrieslandCampina represent the prebiotic and functional carbohydrate specialization tier, with CP Kelco sitting within the hydrocolloid precision space.
| Leading Market Players |
|---|
| Tate & Lyle |
| BENEO |
| Cargill |
| IFF |
| CP Kelco |
| DuPont |
| FrieslandCampina |
| Ingredion |
| Archer Daniels Midland |
| Others |
Value Chain & Pricing Dynamics
Southeast Asian shrimp processing clusters concentrate chitosan feedstock supply, anchoring margin pools in pharmaceutical-grade purification and EMA MDR-compliant documentation tiers downstream. Corn wet milling infrastructure across Iowa and Illinois locks modified starch pricing to agricultural commodity cycles, while microbial fermentation capacity in India and China commands formulation premiums for precision oligosaccharide structures.
Pricing Analysis
Volume-discount tiering structures separate pharmaceutical excipient grades from industrial hydrocolloid contracts, with three-tier pricing stratification across premium biomedical certification, standard food-grade, and economy industrial bulk levels. Price differentiation hinges on glycosidic linkage purity documentation and FDA Emerging Technology Program qualification status. Cost compression runs through modified starch derivatives as cellulose ethers capture clean-label reformulation contracts. Hospital procurement coalitions exhibit lowest price sensitivity; commodity food manufacturers face highest.
Supply Chain Analysis
Extended payment terms from 90 to 120 days characterize supplier-financing arrangements for chitosan processors purchasing crustacean shell feedstock. Upstream supply draws from Thailand, Vietnam, and Indonesia for raw chitin; precision fermentation capacity clusters in India, China, and Germany. Single-source vulnerability concentrates in Southeast Asian aquaculture harvests exposed to disease outbreaks. Distribution runs through Rotterdam liquid bulk terminals for European hydrocolloid flows and Ningbo-Zhoushan for Asian chitosan feedstock.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polysaccharide and oligosaccharide applications sit in early-cycle expansion as pharmaceutical pipelines absorb novel excipients and wound-healing devices multiply under tightened biocompatibility standards.
For Market Incumbents: Entrench position through backward integration into microbial fermentation capacity in India's PLI scheme zones and certification investment for EMA MDR documentation tiers. Cellulose ether substitution threatens modified starch contracts; channel control through direct GPO relationships defends parenteral nutrition formulation share against distributor erosion. For New Entrants and Emerging Players: Pursue white-space targets in precision enzymatic synthesis for controlled-release oral dosage matrices and chitosan wound dressings for German hospital procurement coalitions. Microbial-sourced prebiotic oligosaccharides for Chinese infant nutrition present the most penetrable segment. Go-to-market leverage through CDSCO streamlined pathways accelerates qualification timelines versus FDA routes. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across precision fermentation infrastructure as enzymatic synthesis platforms displace chemical modification. Five-to-ten year viability favors acquisition targets with dual-source geographic footprint and established EMA notified body testing partnerships. Signal to watch: NMPA registration timeline compression for microbial oligosaccharides redirecting capacity investment toward Yangtze River Delta chemical parks.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Capacity Expansion | Microbial oligosaccharide structures command formulation premiums as plant feedstock volatility pressures hydrocolloid cost structures. |
| EMA MDR Documentation Investment | Extended cytotoxicity dossiers favor established chitosan matrix suppliers in German and French hospital procurement channels. |
| Dual-Source Supplier Qualification | North American food manufacturers derisk concentrated Asian hydrocolloid sourcing through secondary fermentation capacity in India. |
| Enzymatic Synthesis Platform Development | Site-specific glycosidic bond formation unlocks pharmacokinetic profiles unattainable through chemical modification routes. |
| Direct GPO Relationship Formation | Hospital purchasing alliances consolidating parenteral nutrition excipient supply displace traditional distributor networks. |
Study Parameters
Initial hypotheses were tested against primary input from pharmaceutical formulation scientists, hospital procurement managers, hydrocolloid plant managers, and regulatory affairs directors and refined through secondary validation against FDA Emerging Technology Program guidance documents, EMA MDR biocompatibility standards, NMPA registration databases, and customs trade flow data. Bottom-up fermentation capacity assessments triangulated with top-down excipient demand modeling across food, pharmaceutical, and personal care end-uses.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product chemistry tier, sourcing biology, application vertical, and regional regulatory cluster. CAGRs were derived through growth driver decomposition and constraint boundary analysis. Forecast inputs incorporated NMPA registration pathway velocity, EMA notified body testing capacity constraints, and wet milling facility retrofit capital requirements.
Macroeconomic conditions sit as an overlay; deviation in agricultural commodity indices, aquaculture harvest yields, or biopharma R&D expenditure would shift the trajectory. Forecasts reflect documented assumptions around regulatory pathway timelines and fermentation technology maturation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Zinc Dialkyldithiophosphates Additive Market
Additives
Friction Modifier Additives Market
Additives
Humectants Market
Additives
Nucleating Agents Market
Additives
Spain Anti Caking Market
Additives
Global UV Absorbers Market
Additives
Sodium Potassium Tartrate Market
Additives
Canada Water Enhancer Market
Additives
Guanylic Acid Market
Additives
Tocopheryl Acetate Market
Additives
Stabilizers Market
Additives
Global Butyric Acid Derivatives Market
Additives
Cassia Gum Market
Additives
Lauroyl Methyl Glucamide Market
Additives
Benzoates Market
Additives
Global Caprylhydroxamic Acid Market