
 Global Security Robots Market | 2026-2036
Global Security Robots Market Size, Share, and Industry Trends Forecast 2026-2036
Global Security Robots Market Intelligence
Modular design in security robot platforms is expanding buyer options, allowing for customized sensor and payload configurations. This shift enables end-users to tailor systems for specific threats without full platform replacement. Knightscope Inc. specializes in autonomous data machines for public spaces, focusing on a subscription-based model. In contrast, Northrop Grumman Corporation leverages its extensive defense-sector experience to deliver integrated, high-assurance robotic systems for government and military clients.
Security robots are autonomous or remotely operated machines designed for surveillance, patrol, and response in secured environments. These systems integrate technologies like LiDAR and computer vision to navigate complex terrains and identify anomalies or threats without human intervention. Within robot types, Autonomous Mobile Units dominate deployments for ground-level perimeter surveillance in commercial complexes and energy plants. However, aerial drones represent the fastest-growing category, offering rapid response capabilities for large-area monitoring.
Regulatory frameworks directly shape market access and product design. In the United States, FAA regulations govern the use of aerial drones for surveillance, while the EU AI Act imposes risk-based requirements on autonomous systems. Concurrently, China's GB standards mandate specific performance and data security protocols for robotic devices. Consequently, vendors must navigate a fragmented compliance landscape to achieve scale across different geographies.
Market Dynamics
The imperative to secure expansive critical infrastructure against evolving threats, coupled with a persistent shortage of human security personnel, establishes the central dynamic. This pressure accelerates the replacement of static surveillance with autonomous mobile platforms capable of persistent patrol and data collection.
Growth Catalysts
- Advanced Sensor Payloads:The fusion of LiDAR, thermal imaging, and high-definition optical sensors enables reliable navigation and threat detection in adverse weather and low-light conditions, expanding operational viability for energy sector and transportation clients.
- Government Security Mandates:Heightened security protocols for government facilities and critical infrastructure in the United States and Europe are specifying needs for automated surveillance and response, creating a clear demand signal for compliant robotic systems.
- Logistics and Warehousing Expansion:The rapid growth of large-scale distribution centers creates vast, complex perimeters that are economically and operationally challenging to secure with human patrols alone, driving adoption of ground-based autonomous units.
Market Restraints
- High Initial Capital Expenditure:The significant upfront investment for sophisticated autonomous security robots, compared to traditional CCTV systems or manpower costs, remains a primary adoption barrier for small to medium-sized enterprises.
- Regulatory Fragmentation:Navigating disparate rules, such as FAA regulations for aerial drones in the United States and data privacy stipulations under the EU's GDPR, complicates product design and limits scalable deployment across regions.
- Operational Environment Limitations:Performance of autonomous navigation systems can degrade significantly in highly dynamic, unstructured public spaces with unpredictable human interaction, limiting effective use cases to more controlled environments like corporate campuses.
Strategic Opportunities
- Indoor and Vertical Patrol:Expanding applications beyond perimeter security to include indoor patrols in multi-story commercial buildings, data centers, and hospitals represents a significant area for market growth and product specialization.
- 5G and Edge AI Convergence:The integration of 5G connectivity with on-board edge AI processing enables real-time, low-latency video analysis and collaborative behaviors between multiple robots, creating opportunities for advanced swarm security solutions.
- Service-Based Model Expansion:Offering Robotics-as-a-Service (RaaS) subscriptions lowers the initial financial barrier for customers, opening the market to organizations that lack the capital for an outright purchase or the expertise for in-house maintenance.
Industry Challenges
- System Integration Complexity:Ensuring seamless interoperability between new robotic platforms and an organization's existing legacy security infrastructure, including video management systems (VMS) and access control, is a major technical and implementation hurdle.
- Specialized Talent Scarcity:A shortage of technicians and engineers with combined expertise in robotics, AI software, and cybersecurity hinders the deployment, maintenance, and effective operation of advanced security robot fleets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Security Robots Market |
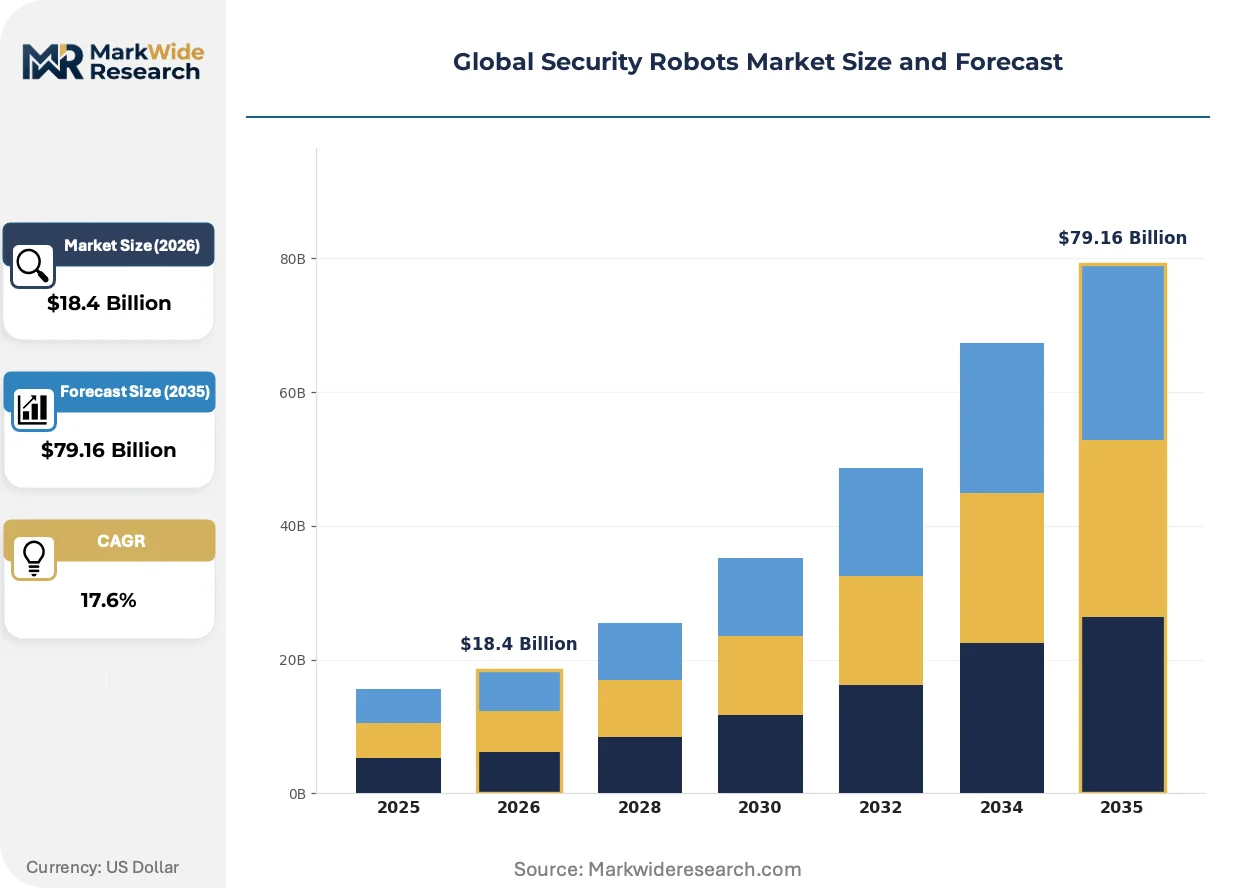
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $79.16 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Robot Type: Autonomous Mobile Units, Humanoid Systems, Aerial Drones, Stationary Surveillance Bots, Hybrid Models Technology: Computer Vision, Machine Learning, Infrared Sensors, LiDAR, Acoustic Detection Application: Perimeter Surveillance, Crowd Monitoring, Asset Protection, Emergency Response, Intrusion Detection End User Industry: Commercial Complexes, Government Facilities, Transportation Hubs, Energy Plants, Educational Campuses |
| Companies Covered | Lockheed Martin Corporation, BAE Systems, Northrop Grumman Corporation, AeroVironment Inc., Knightscope Inc., Recon Robotics Inc., Thales Group, Boston Dynamics, Elbit Systems Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Security Robots Market Strategic Shifts & Innovations
Autonomous capability is the defining theme, as the market moves beyond remotely-piloted drones toward intelligent systems that perform data collection, analysis, and threat identification with minimal human oversight. This evolution depends on advancements in on-board processing and machine learning algorithms.
Edge computing allows for on-device processing of sensor data, reducing latency and reliance on network connectivity. Data centers and logistics facilities are early adopters, seeking immediate anomaly detection without transmitting vast amounts of raw video to the cloud. This trend is integrating powerful analytical capabilities directly into the robot, enabling faster decision-making at the point of incident and improving operational autonomy in sensitive or remote locations.
Regulatory frameworks like the EU AI Act are reshaping design priorities by introducing risk-based compliance obligations. The legislation mandates stringent requirements for transparency, data governance, and human oversight for systems deemed high-risk, such as those used for surveillance in public spaces. Vendors targeting the European market are most affected, embedding auditable logs and "explainable AI" features into their platforms to demonstrate compliance.
A transition from capital expenditure purchases to subscription-based service models is altering procurement patterns. This Robotics-as-a-Service (RaaS) approach allows end-users to pay a recurring fee for hardware, software, maintenance, and support, disrupting the traditional security integrator channel. The model is gaining significant traction for securing large commercial properties and industrial campuses in North America, where it aligns with operational expense budgets.
Global Security Robots Market Segmentation
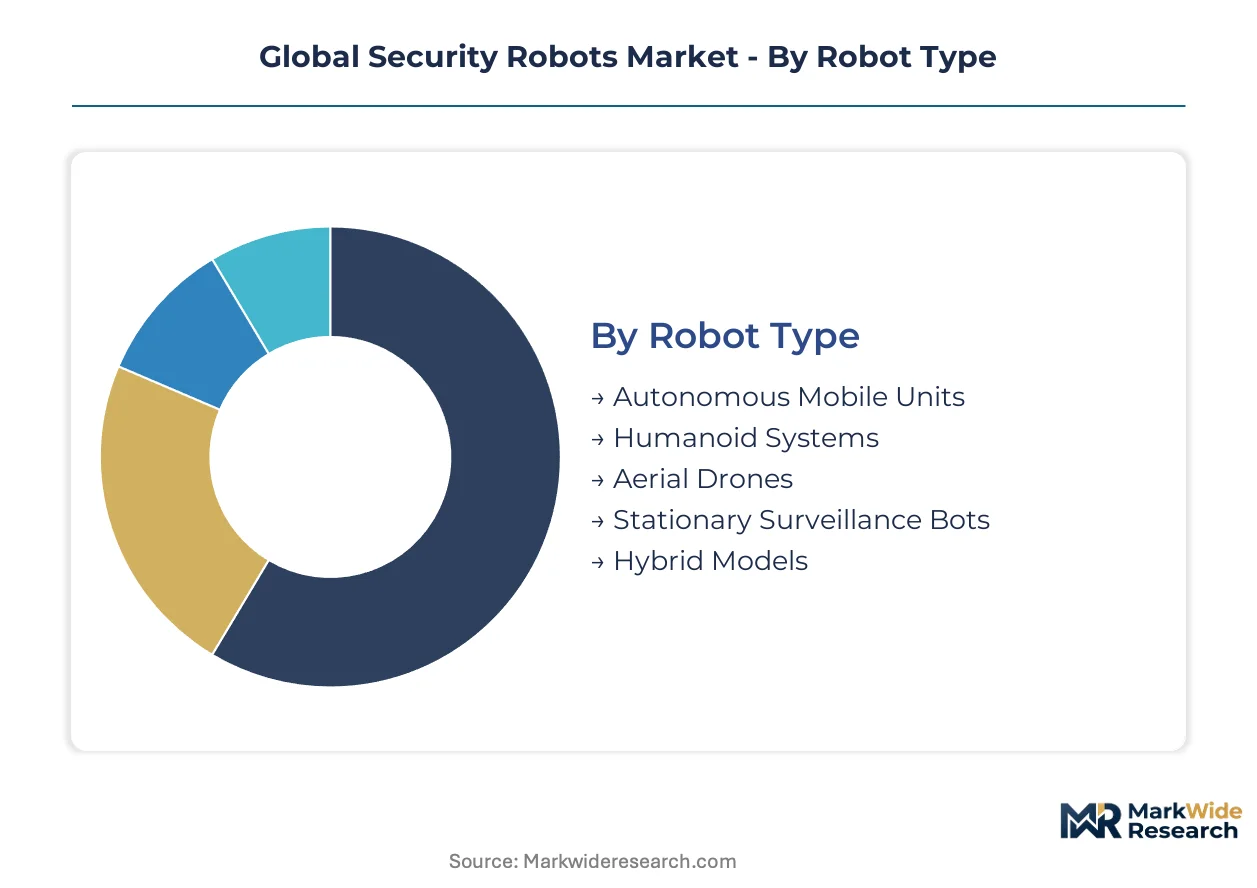
The Global Security Robots Market is segmented to provide a granular view of demand drivers and technological preferences across various operational contexts. Understanding these distinct segments helps vendors tailor product development and market strategies to specific end-user requirements and regulatory landscapes.
Robot Type:
Buyer options for security robots often hinge on the operational mobility required for surveillance and response across diverse environments.
- Autonomous Mobile Units:These ground-based robots navigate independently to patrol large areas, integrating sensors for persistent surveillance and anomaly detection. Demand from commercial complexes and logistics facilities drives their deployment for perimeter security in North America.
- Aerial Drones:Unmanned aerial vehicles offer rapid deployment and elevated perspectives for wide-area monitoring, critical infrastructure inspection, and emergency response. Their adoption is expanding quickly in the energy sector and for border security applications globally.
- Humanoid Systems:These robots are designed with human-like forms and dexterity, often intended for complex indoor navigation and interaction in public spaces. Their development focuses on advanced AI for nuanced threat assessment.
- Stationary Surveillance Bots:Fixed-position robotic platforms integrate advanced sensors and cameras for continuous monitoring of specific high-value assets or entry points. Data centers and secure government facilities utilize these for localized threat detection.
- Hybrid Models:Systems combining capabilities from different robot types, such as ground units deploying small aerial drones for expanded situational awareness. These models offer enhanced flexibility for complex security scenarios.
Autonomous Mobile Units lead on scale; Aerial Drones lead on momentum.
Technology:
The effectiveness of security robot deployments is directly influenced by the sophistication of integrated sensing and analytical technologies.
- Computer Vision:Utilizes cameras and machine learning algorithms to interpret visual data for object recognition, facial detection, and behavioral anomaly identification. This technology is critical for surveillance in public spaces and commercial properties.
- LiDAR:Employs pulsed laser light to measure distances and create precise 3D maps of environments, enabling accurate navigation and obstacle avoidance in complex terrains. Energy plants and transportation hubs rely on LiDAR for robust outdoor operations.
- Machine Learning:Powers the robot's ability to learn from data, improving threat detection accuracy, predictive analytics, and autonomous decision-making over time. This underpins intelligent response capabilities.
- Infrared Sensors:Detect heat signatures, allowing for effective surveillance and threat detection in low-light conditions, adverse weather, or through smoke. These sensors are vital for industrial sites and defense applications.
- Acoustic Detection:Analyzes sound patterns to identify specific threats such as gunshots, breaking glass, or unusual vocalizations. This augments visual surveillance in noisy or obscured environments.
Advancements in LiDAR and computer vision drive the continuous expansion of robotic perception capabilities.
Application:
Organizations prioritize security robot applications based on the primary threat vectors and the scale of assets requiring protection.
- Perimeter Surveillance:Involves continuous monitoring of boundaries and external areas to detect unauthorized entry or suspicious activity. This is a primary function for large industrial campuses and critical infrastructure.
- Intrusion Detection:Focuses on identifying and alerting security personnel to unauthorized presence within defined secure zones. Data centers and government facilities prioritize this for real-time threat response.
- Crowd Monitoring:Utilizes robotic systems to observe and analyze crowd dynamics, identify unusual behavior, or manage large gatherings. Public event venues and urban centers deploy these for safety management.
- Asset Protection:Involves guarding specific high-value assets or sensitive equipment from theft, damage, or unauthorized access. Warehouses and manufacturing plants use robots for this specialized task.
- Emergency Response:Deploys robots to assess hazardous situations, deliver critical information, or assist human responders during crises without endangering personnel. This application is gaining traction in disaster management.
Perimeter surveillance applications remain fundamental, while intrusion detection capabilities expand the scope of autonomous response.
End User Industry:
End-user industries select security robot solutions based on the criticality of their infrastructure and the unique security challenges presented by their operational environments.
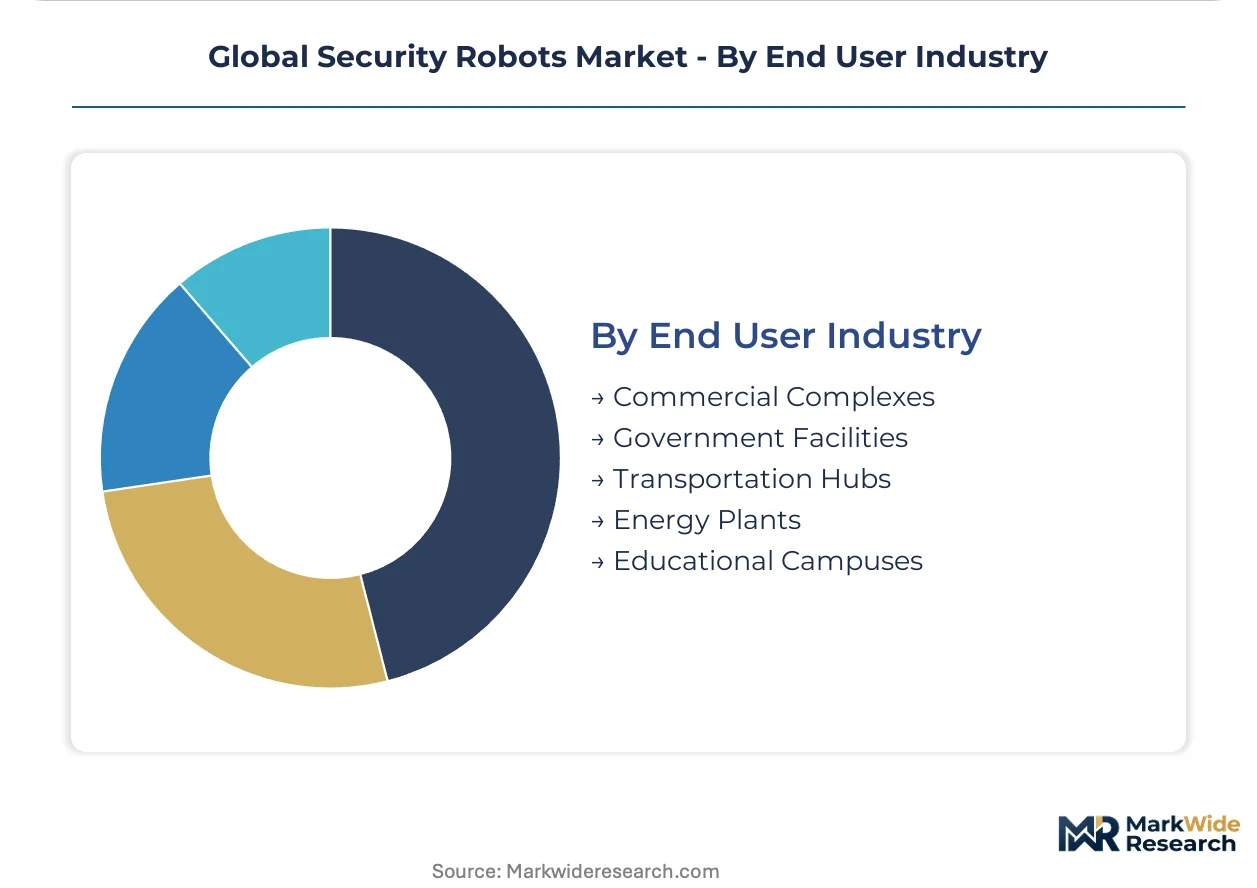
- Government Facilities:Includes military bases, embassies, and administrative buildings requiring stringent security protocols for national security and data protection. The United States government is a significant procurer for these systems.
- Energy Plants:Encompasses power generation facilities, oil refineries, and pipelines that demand robust security against physical attacks and sabotage. These sites often operate in remote or harsh environments, benefiting from autonomous patrols.
- Commercial Complexes:Covers office buildings, shopping malls, and corporate campuses where security robots enhance human patrols and provide continuous surveillance. North American commercial properties are adopting service-based models.
- Transportation Hubs:Includes airports, seaports, and railway stations that require extensive surveillance for passenger safety and cargo security. Robots assist in monitoring large, dynamic areas.
- Educational Campuses:Universities and schools deploy security robots for patrol, emergency response, and monitoring of large grounds and facilities. These systems contribute to a safer learning environment.
Government facilities and energy plants drive demand for high-assurance systems, reflecting their stringent security requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The security robot industry initially scaled within defense and critical infrastructure sectors, with early deployments concentrated in nations investing heavily in autonomous systems for national security. This foundational development established key operational paradigms for surveillance and response.
United States
Demand for securing extensive critical infrastructure and government facilities drives procurement in the United States. FAA regulations govern aerial drone usage for surveillance, influencing product design and operational parameters. Major defense contractors in California and Texas continue to lead innovation in high-assurance robotic systems.
Germany
Germany's market concentrates on industrial security and public safety applications, leveraging its advanced manufacturing base. The EU AI Act imposes stringent risk-based requirements on autonomous systems, shaping vendor compliance strategies. Robotics clusters in Bavaria and Baden-Württemberg foster research and development for intelligent security platforms.
China
China's security robot market is expanding rapidly, supported by state-backed initiatives for urban surveillance and industrial automation. GB standards mandate specific performance and data security protocols for robotic devices, influencing local product development. Shenzhen and other Guangdong province cities serve as manufacturing and deployment hubs for security robots.
Japan
Japan exhibits strong demand for security robots in public spaces and critical infrastructure, partly driven by an aging workforce. METI initiatives encourage robotics innovation and deployment across various sectors, including security. The Tokyo and Nagoya regions are centers for advanced robotics research and commercialization.
United Kingdom
The United Kingdom focuses on securing critical national infrastructure and urban environments against evolving threats. Data privacy stipulations under the EU's GDPR, post-Brexit, continue to influence data handling for security systems. London and Cambridge tech hubs are developing advanced AI and robotics for integrated security solutions.
Global Security Robots Market Key Industry Players
Premium-margin players sit above commodity-margin players across product sophistication and integration capabilities. The market structure exhibits a tiered approach, with established defense contractors and specialized robotics firms occupying distinct niches. Strategic archetypes include high-assurance system integrators, autonomous platform developers, and AI-driven analytics providers. Strategic partnerships for technology licensing and targeted mergers and acquisitions remain dominant competitive moves.
On the premium-tier vector, Lockheed Martin Corporation and Northrop Grumman Corporation exemplify large defense contractors offering integrated, high-assurance robotic systems for government and military clients. These companies leverage extensive defense-sector experience to deliver robust solutions. Knightscope Inc., conversely, represents a specialized robotics firm focusing on autonomous data machines for public spaces, often employing a subscription-based model to lower customer acquisition barriers.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| BAE Systems |
| Northrop Grumman Corporation |
| AeroVironment Inc. |
| Knightscope Inc. |
| Recon Robotics Inc. |
| Thales Group |
| Boston Dynamics |
| Elbit Systems Ltd. |
| Others |
Cost & Logistics Intelligence
The clear bifurcation between high-assurance, defense-grade robotic systems and commercial-grade autonomous units creates distinct pricing models and influences the geographic concentration of specialized component suppliers. This divergence shapes procurement patterns and vendor strategies across the security robots market.
Pricing Analysis
The subscription-based Robotics-as-a-Service (RaaS) model dominates commercial deployments, lowering initial capital expenditure for end-users. Price differentiation stems from the customization level for specialized sensors like LiDAR and thermal imaging, alongside compliance with specific regulatory frameworks such as the EU AI Act. Pricing softness in the commercial segment stems from increased competition and the expansion of RaaS models. Small to medium-sized enterprises are highly price-sensitive, preferring RaaS, while government facilities prioritize performance and compliance over initial cost.
Supply Chain Analysis
Dual-sourcing requirements for critical robotic components mitigate risks associated with geopolitical tensions and single-supplier dependencies. Geographic supply concentrates in China for sensors and basic components, the United States for advanced AI and defense-grade systems, and Germany for precision engineering. Key dependencies include advanced semiconductors, specialized LiDAR units, and high-resolution cameras. Geopolitical tensions impacting semiconductor availability from Taiwan represent a structural supply chain risk. Distribution runs through direct sales channels for large government contracts, integrator networks for commercial deployments, and direct-to-consumer for smaller RaaS clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The security robots market presents a geographic-arbitrage opportunity, as manufacturing and assembly in China offer cost advantages for commercial units, while regulatory compliance needs for the EU AI Act drive specialized R&D in Europe.
For Market Incumbents: Cement long-term government contracts through high-assurance system development and deepen vertical integration into critical component manufacturing. The emergence of lower-cost, commercial-grade platforms from Asian manufacturers poses a threat to traditional defense contractors. Invest in R&D for advanced AI and cybersecurity features to meet stringent government security mandates, ensuring system robustness and data integrity.
For New Entrants and Emerging Players: Online marketplaces and direct-to-consumer digital platforms offer efficient channels to target white-space opportunities. Focus on indoor and vertical patrol applications in multi-story commercial buildings, leveraging cloud-based platforms for remote management. Small to medium-sized commercial complexes in North America represent a penetrable segment underserved by traditional security providers. Offer flexible, low-commitment RaaS subscriptions with transparent pricing and rapid deployment to attract these clients.
For Investors and Strategic Acquirers: Consolidation pressure builds where smaller players lack the capital or technological breadth to compete effectively, particularly in the fragmented commercial-grade segment. The market shows strong long-term viability, driven by persistent human security personnel shortages and the imperative to secure critical infrastructure. Vertically integrated mid-cap specialists with strong RaaS penetration or unique AI/sensor technology represent attractive acquisition targets. The rate of regulatory harmonization across major economies for autonomous system deployment is a key signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Robotics-as-a-Service (RaaS) Portfolio | Lowers customer entry barriers and aligns with operational expenditure budgets for commercial clients in North America. |
| Deepen AI and Edge Computing R&D | Enables faster on-device threat detection and reduces reliance on network connectivity for critical deployments. |
| Pursue Regulatory Compliance Certifications | Unlocks market access in regulated geographies like Europe under the EU AI Act, ensuring product viability. |
| Form Technology Licensing Partnerships | Accelerates integration of specialized sensors (LiDAR, thermal imaging) and advanced navigation capabilities. |
| Target Indoor and Vertical Patrol Applications | Expands market beyond perimeter security into multi-story commercial buildings and data centers. |
Research Approach
Bottom-up end-user adoption modeling reconciled against top-down component supply tracking forms the analytical core, drawing insights from primary interviews and secondary validation. Stakeholder roles include security directors, robotics engineers, government procurement officers, and commercial property managers. Secondary data sources encompass FAA regulations, EU AI Act official documents, national defense spending reports, and industry association publications, ensuring comprehensive market understanding.
An input-output matrix maps specific market drivers to their quantitative impact on volume and value across the analysis window. Segmentation dimensions modeled include robot type, technology, application, end-user industry, and regional regulatory compliance. Compound Annual Growth Rates (CAGRs) were derived from historical growth trends and projected future demand drivers, including critical infrastructure investment and human security personnel shortages.
The model assumes a particular technology adoption path; alternative pathways for AI-driven autonomous decision-making would alter the outlook significantly. Forecasts reflect assumptions regarding regulatory stability and market acceptance, but are subject to change. Deviation in government security spending or public sentiment would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Autonomous Mobile Manipulator Robots (AMMR) Market
Robotics and Automation
Smart Curtain Robot Market
Robotics and Automation
SLAM Robots Market
Robotics and Automation
Dispensing Robots Market
Robotics and Automation
Clean Room Robot Market
Robotics and Automation
Global Educational Robots Market
Robotics and Automation
South America Agricultural Robots and Mechatronics Market
Robotics and Automation
Hospital Robots Market
Robotics and Automation
Autonomous Drilling Robots Market
Robotics and Automation
China Autonomous Mobile Robot Market
Robotics and Automation
Virtual 3D Nanorobots Market
Robotics and Automation
Europe Agricultural Robots and Mechatronics Market
Robotics and Automation
South America AUV and ROV Market
Robotics and Automation
AGV Software Market
Robotics and Automation
Industrial Robots Market
Robotics and Automation
SCARA Robots Market