
 Global Educational Robots Market | 2026-2036
Global Educational Robots Market Size, Share, and Industry Trends Forecast 2026-2036
Global Educational Robots Market Analysis
CE marking under the EU Machinery Directive is redrawing competitive boundaries for classroom robotics vendors. LEGO Systems A/S leverages its established brick-based ecosystem to sustain curriculum integration across primary education. SoftBank Robotics Group anchors its position through humanoid platforms designed for social-interaction learning modules. FANUC competes by extending its industrial automation expertise into vocational training systems for secondary and tertiary institutions.
Educational robots are electromechanical systems integrating sensors, actuators, and programmable controllers to execute pedagogical tasks ranging from basic movement sequences to adaptive tutoring interactions. These platforms typically operate on battery-powered chassis with embedded microcontrollers supporting Wi-Fi or Bluetooth connectivity for tablet-based command interfaces. Humanoid robots command premium positioning in interactive learning applications where social engagement drives subscription-based content revenue. Kit-based robots dominate volume in after-school programs where modular assembly sustains repeat purchase cycles across progressive skill levels. Artificial Intelligence-enabled platforms represent the fastest-expanding technology segment as natural language processing capabilities displace static coding-only instruction.
The U.S. Consumer Product Safety Commission and the EU's CE marking framework govern physical safety standards for classroom-deployed robotics, while China's SAMR enforces network security protocols for connected educational devices. Compliance with these overlapping regimes shapes regional product roadmaps and creates divergent certification costs for multinational suppliers. Stakeholders must monitor how evolving AI governance in the European Union and United States reshapes liability frameworks for autonomous tutoring functions before committing to platform architectures.
Market Dynamics
The Global Educational Robots Market is experiencing structural pressure from the EU AI Act's algorithmic transparency mandates, which force vendors to redesign firmware architectures for classroom-deployed systems. This regulatory compression is cascading through product development cycles faster than hardware refresh timelines can absorb.
Growth Catalysts
- EU AI Act compliance deadlines:European K-12 institutions face mandatory procurement specifications for explainable AI in tutoring functions, accelerating replacement of opaque legacy platforms.
- Natural language processing integration:Conversational interfaces are expanding addressable demand beyond coding-centric curricula into language arts and social-emotional learning modules.
- South Korea's AI Digital Textbook initiative:Government-funded deployment targets are creating concentrated demand spikes for humanoid platforms in Seoul metropolitan schools.
Market Restraints
- Lithium-ion battery supply concentration:Classroom robot manufacturers depend on cylindrical cell formats sourced predominantly from Chinese suppliers, exposing procurement to export control volatility.
- CE marking certification costs:The EU Machinery Directive's updated safety requirements for autonomous movement systems impose six-figure compliance burdens on mid-tier vendors.
- Tablet-based substitutes:Simulation software running on existing school hardware offers lower per-student cost for basic programming instruction, compressing entry-level robot demand.
Strategic Opportunities
- Vocational training in Germany:FANUC's industrial automation curricula demonstrate unmet demand for precision robotics instruction in secondary technical schools.
- Subscription content monetization:Humanoid platforms with cloud-based lesson libraries can capture recurring revenue from districts seeking reduced curriculum development overhead.
- India's National Education Policy:Computational thinking mandates in government schools create regulatory tailwinds for affordable kit-based robot suppliers.
Industry Challenges
- Embedded systems engineering talent scarcity:Vendors struggle to hire firmware developers capable of integrating sensor fusion with real-time safety protocols.
- Multi-jurisdiction certification timelines:Simultaneous FCC, CE, and SAMR approvals delay product launches by 14-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Educational Robots Market |
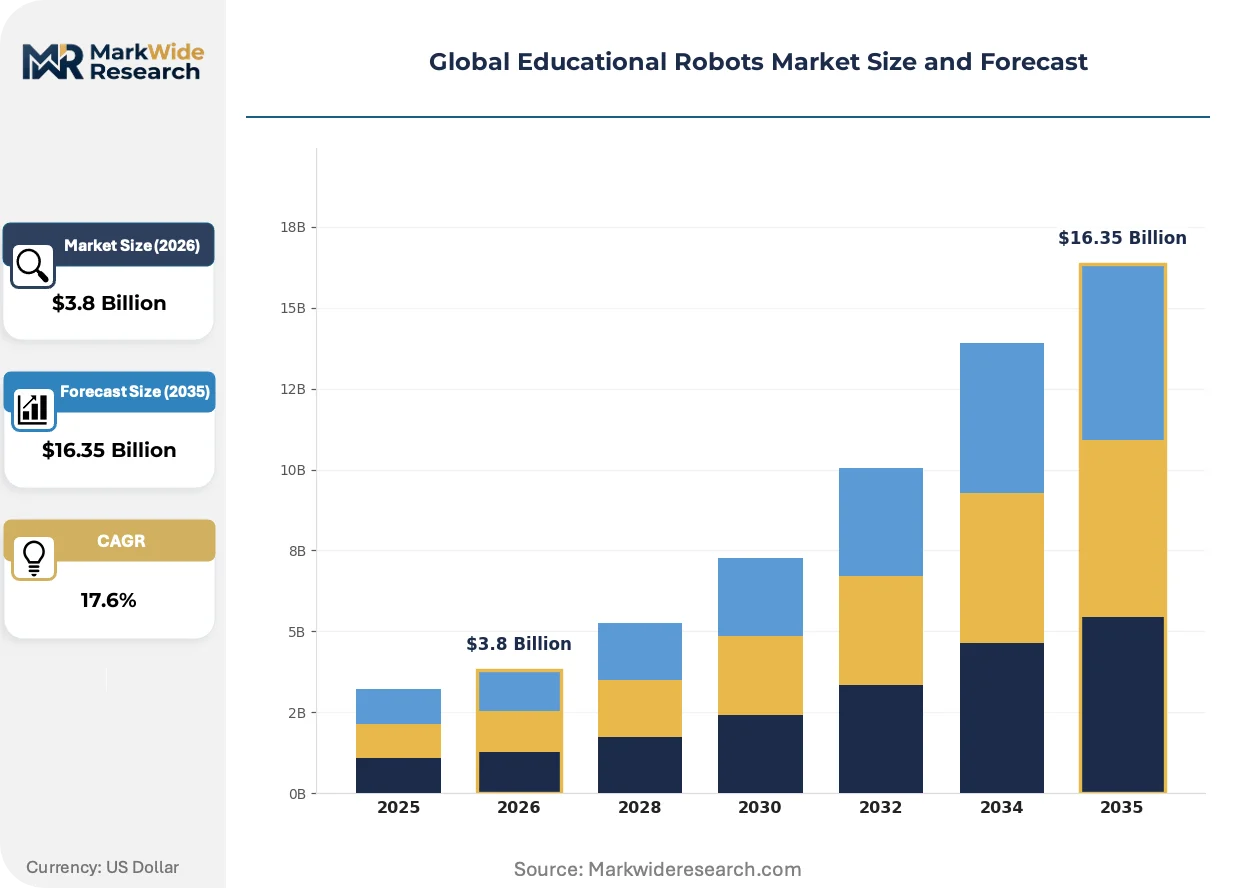
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $16.35 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Humanoid Robots, Programmable Bots, Kit-based Robots, Advanced Robotics End User: Schools, Universities, Training Centers, Individual Learners Technology: Artificial Intelligence, Machine Learning, Internet of Things, Basic Coding Application: STEM Education, Robotics Competitions, After School Programs, Interactive Learning |
| Companies Covered | ABB, FANUC, SoftBank Robotics Group, ROBOTIS, LEGO Systems A/S, Universal Robots, YASKAWA, KUKA, PAL Robotics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Educational Robots Market Emerging Trajectories
Generative AI capabilities are restructuring how educational robots generate personalized feedback, compressing the traditional content development cycle from months to hours. This capability shift is redrawing competitive boundaries between hardware-centric and software-centric vendors.
Edge-based neural inference is decomposing the traditional cloud-dependent architecture for classroom robotics. Local processing of student speech and gesture data eliminates latency in tutoring interactions. Primary schools with restricted internet connectivity are adopting these platforms fastest. The technology is compressing the addressable market for purely cloud-based competitors.
REACH substance restrictions are forcing redesign of plastic chassis and cable insulation in European-bound products. The regulation's updated SVHC candidate list now covers several flame retardants common in consumer electronics. Vendors are accelerating migration to bio-based polymer alternatives ahead of 2025 enforcement windows. Secondary schools represent the most affected segment due to longer procurement cycles.
District-level bulk purchasing consortia are consolidating procurement authority previously held by individual schools. This concentration shifts negotiation leverage toward standardized specifications and away from customized deployments. The pattern is most visible in Texas and California where state-level cooperative purchasing agreements cover thousands of institutions simultaneously.
Global Educational Robots Market Segmentation
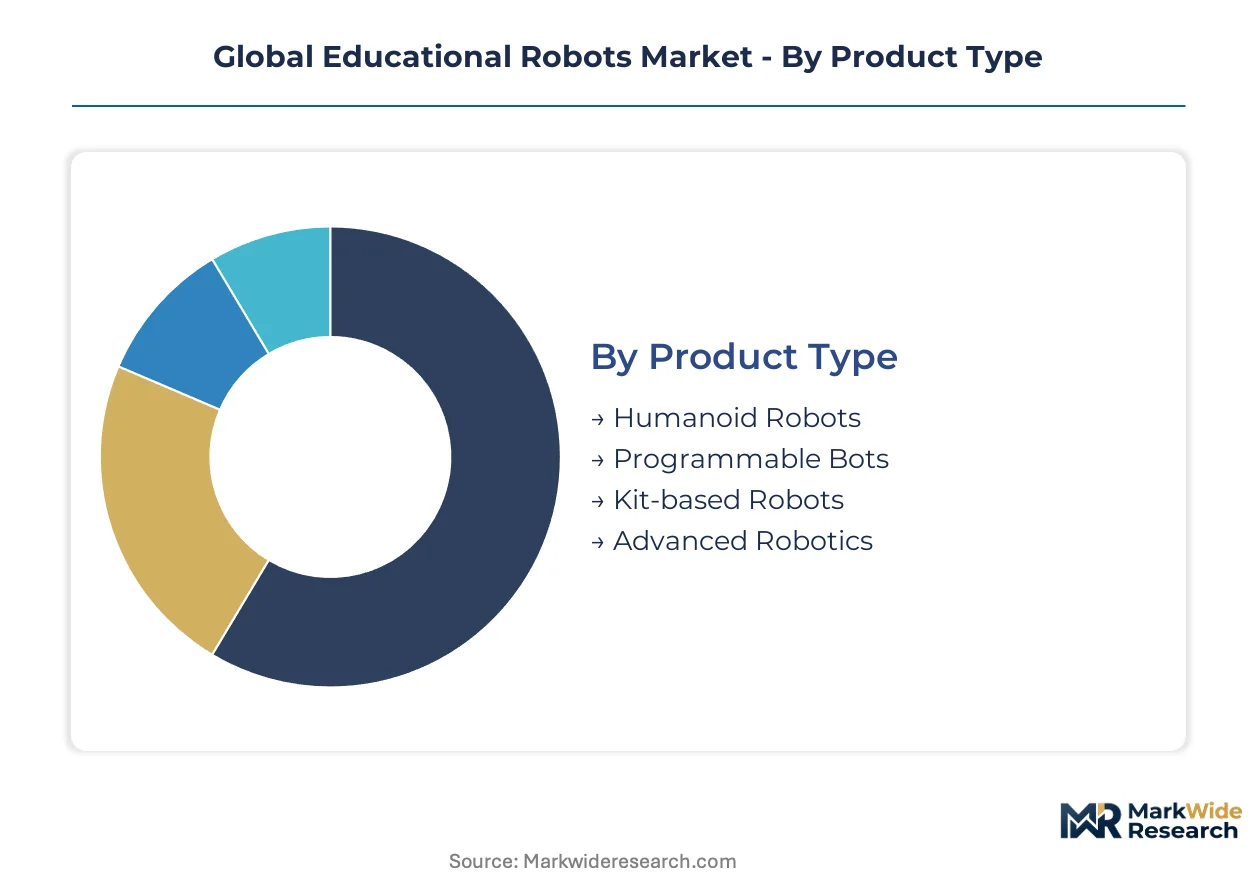
Educational robots serve divergent pedagogical missions across institutional and consumer channels. Channel economics differ sharply between district-level bulk procurement and direct-to-learner retail. Understanding segment-channel alignment clarifies where vendors must build curriculum partnerships versus self-service distribution.
Product Type:
Humanoid platforms flow through specialized education distributors with curriculum integration services, while kit-based systems dominate e-commerce and after-school retail channels.
- Humanoid Robots:Bipedal or wheeled platforms with social-interaction capabilities, voice recognition, and emotive displays. Seoul metropolitan schools under South Korea's AI Digital Textbook initiative drive concentrated procurement of these units for language arts modules.
- Programmable Bots:Pre-assembled wheeled or tracked chassis with embedded sensors and block-based coding interfaces. North American K-5 STEM curricula favor these for district-wide standardization, though tablet-based simulation software erodes entry-level demand.
- Kit-based Robots:Modular assembly systems with reusable mechanical components and progressive skill ladders. India's National Education Policy computational thinking mandates are expanding addressable demand for affordable kit suppliers in government schools.
- Advanced Robotics:Industrial-grade manipulators and precision motion platforms for vocational certification. German secondary technical schools under the dual education system represent the primary channel for FANUC's automation training systems.
Programmable bots dominate installed base. Humanoid robots are where expansion concentrates.
End User:
Cost tier stratification separates institutional procurement with multi-year depreciation schedules from individual purchases with immediate payback expectations.
- Schools:Primary and secondary institutions with centralized IT budgets and compliance-driven procurement cycles. EU AI Act explainability mandates are accelerating replacement of legacy platforms in European K-12 systems.
- Universities:Tertiary institutions with research funding and interdisciplinary robotics laboratories. These buyers prioritize open-source firmware architectures and ROS compatibility for graduate research integration.
- Training Centers:Private vocational facilities and corporate re-skilling programs with outcome-based certification requirements. Germany's industrial automation training centers demonstrate concentrated demand for precision robotics instruction.
- Individual Learners:Home users and hobbyists purchasing through direct-to-consumer channels. Parental subsidy of after-school STEM enrichment sustains repeat purchase cycles across progressive kit difficulty levels.
Schools anchor volume procurement. Training centers are climbing the fastest as workforce re-skilling accelerates.
Technology:
Maturity gradients separate proven instruction methods from emerging capabilities requiring firmware architecture redesigns.
- Artificial Intelligence:Natural language processing and adaptive tutoring algorithms enabling conversational instruction. Edge-based neural inference is displacing cloud-dependent architectures in primary schools with restricted connectivity.
- Machine Learning:Pattern recognition systems for gesture interpretation and personalized feedback generation. Generative AI capabilities are compressing content development cycles from months to hours for lesson library vendors.
- Internet of Things:Sensor networks and connected device ecosystems for collaborative robotics exercises. China's SAMR network security protocols for connected educational devices create compliance barriers for foreign platform suppliers.
- Basic Coding:Static instruction sequences without adaptive or conversational capabilities. Tablet-based substitutes running simulation software offer lower per-student cost, compressing demand for hardware-dependent basic coding platforms.
Basic coding retains the largest installed base. Artificial intelligence is gaining share fastest as natural language interfaces expand beyond STEM into language arts.
Application:
Margin structure varies between one-time hardware sales and recurring content subscription revenue.
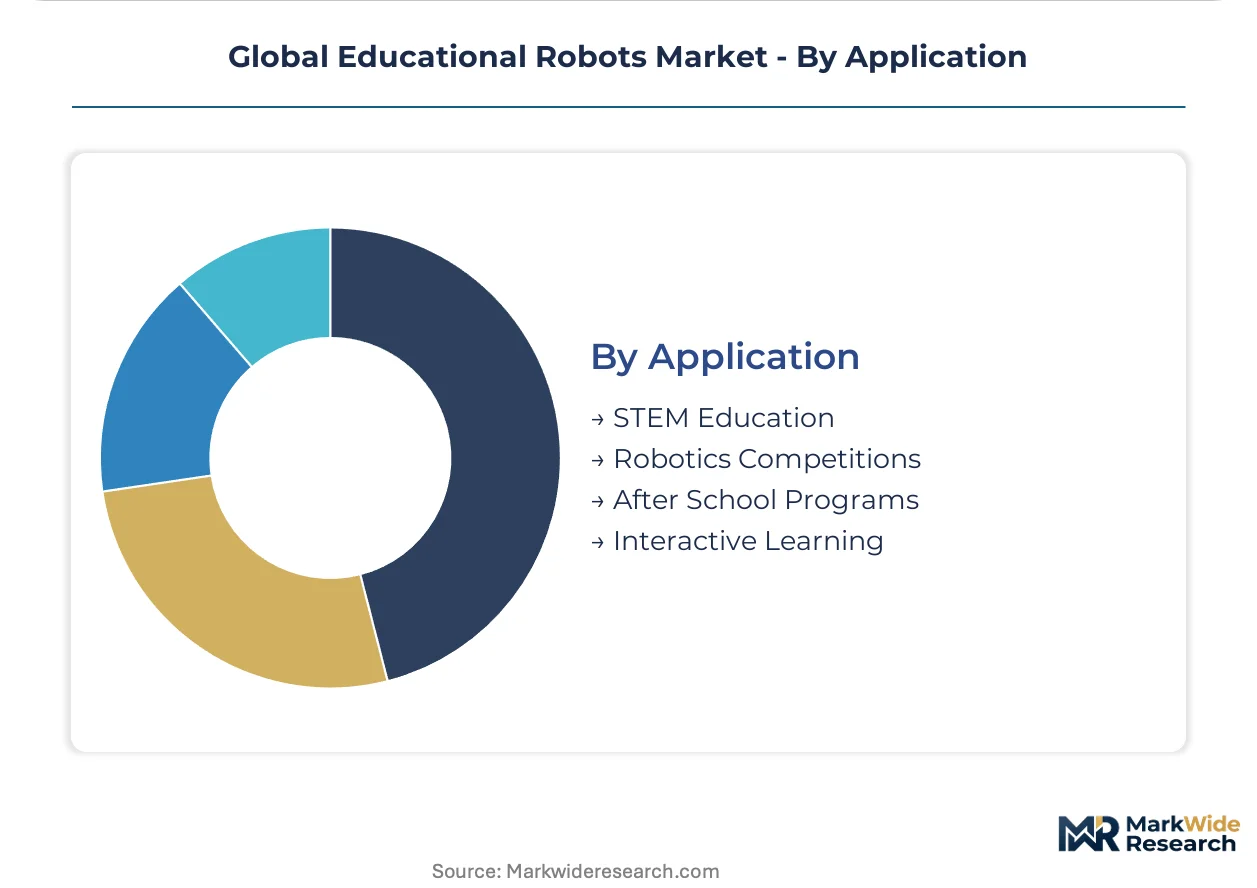
- STEM Education:Formal curriculum integration across science, technology, engineering, and mathematics instruction. Texas and California cooperative purchasing agreements are consolidating procurement authority previously held by individual schools.
- Robotics Competitions:Tournament-oriented platforms with standardized specifications for competitive events. These applications sustain aftermarket parts demand and seasonal upgrade cycles.
- After School Programs:Supplementary enrichment activities outside formal instructional hours. Modular kit-based robots dominate this channel where progressive assembly sustains repeat purchase cycles.
- Interactive Learning:Social-emotional and language arts applications requiring humanoid form factors. Subscription content monetization from cloud-based lesson libraries captures recurring revenue from districts seeking reduced curriculum development overhead.
STEM education commands the largest hardware volume. Interactive learning is where subscription revenue expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government-funded digital education initiatives are redrawing procurement geography across the Global Educational Robots Market. South Korea's AI Digital Textbook program and China's computational thinking mandates are accelerating classroom deployment faster than hardware refresh cycles in mature markets can absorb.
United States
District-level bulk purchasing consortia in Texas and California are consolidating procurement authority previously held by individual schools. The U.S. Consumer Product Safety Commission governs physical safety standards for classroom-deployed robotics. Greater Boston's edtech cluster hosts multiple firmware developers integrating sensor fusion with real-time safety protocols for primary education platforms.
China
State-funded digital education initiatives are driving concentrated demand for connected educational devices across government school systems. SAMR enforces network security protocols that create compliance barriers for foreign platform suppliers. The Yangtze River Delta manufacturing corridor supplies cylindrical lithium-ion cell formats that classroom robot manufacturers depend on for battery-powered chassis.
Germany
The dual education system generates sustained demand for precision robotics instruction in secondary technical schools. REACH substance restrictions are forcing redesign of plastic chassis and cable insulation ahead of 2025 enforcement windows. Bavaria's industrial automation training centers demonstrate concentrated procurement of vocational certification systems for workforce re-skilling programs.
South Korea
Seoul metropolitan schools under the AI Digital Textbook initiative drive concentrated procurement of humanoid platforms for language arts modules. National AI literacy mandates are accelerating compliance requirements for explainable tutoring functions. The Daejeon-Sejong corridor hosts multiple embedded systems engineering firms developing edge-based neural inference architectures for restricted connectivity environments.
India
Computational thinking mandates in government schools are expanding addressable demand for affordable kit-based robot suppliers. The National Education Policy creates regulatory tailwinds for modular assembly systems with progressive skill ladders. Karnataka's Bangalore-Tumkur electronics manufacturing cluster is emerging as a secondary sourcing hub for microcontroller-integrated chassis components.
Global Educational Robots Market Vendor Landscape
Player mix skews toward diversified industrial automation conglomerates with education divisions alongside pure-play edtech specialists. Market structure exhibits tiered consolidation with premium humanoid platforms commanding distinct positioning from volume kit suppliers. Strategic archetypes include brick-based ecosystem builders, industrial vocational trainers, and social-interaction platform developers. Competitive moves center on curriculum partnership formation and subscription content library expansion rather than hardware specification races.
Within the industrial-to-education extension tier, FANUC and ABB represent archetypes of precision automation expertise repurposed for vocational certification systems. Among pure-play humanoid developers, SoftBank Robotics Group and PAL Robotics occupy positions emphasizing social-interaction learning modules with emotive display capabilities. LEGO Systems A/S anchors the brick-based ecosystem archetype where modular assembly sustains repeat purchase cycles across progressive skill levels in after-school channels.
| Leading Market Players |
|---|
| ABB |
| FANUC |
| SoftBank Robotics Group |
| ROBOTIS |
| LEGO Systems A/S |
| Universal Robots |
| YASKAWA |
| KUKA |
| PAL Robotics |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at Yangtze River Delta cylindrical cell plants shapes both supply concentration and price floors for battery-powered chassis. Scale economies in Chinese lithium-ion production compress component costs for entry-level programmable bots while premium humanoid platforms absorb CE marking certification premiums through subscription bundling.
Pricing Analysis
Certification level (CE/FCC/SAMR-grade) creates the primary spread between premium humanoid platforms and economy kit-based systems. Subscription content monetization dominates revenue architecture for social-interaction robots, while transactional per-unit sales govern after-school retail channels. Pricing pressure stems from tablet-based simulation software eroding entry-level hardware demand. District-level bulk purchasing consortia exhibit highest price sensitivity; vocational training centers with certification requirements show lowest.
Supply Chain Analysis
Strait of Malacca transit underwrites cylindrical lithium-ion cell flows from Chinese suppliers to assembly plants across South Korea and Vietnam. Classroom robot manufacturing draws from concentrated sources in China for battery cells, Taiwan for microcontroller-integrated chassis, and Germany for precision motion components. Single-source vulnerability concentrates in Yangtze River Delta cell production exposed to export control volatility. Distribution runs through specialized education distributors for institutional procurement and e-commerce platforms for direct-to-consumer retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as EU AI Act compliance deadlines fragment procurement specifications across member states, creating niche openings for specialized firmware developers and regional curriculum integrators.
For Market Incumbents: Secure firmware architecture lock-in through edge-based neural inference investments before cloud-dependent competitors adapt. Deepen curriculum partnerships with Texas and California cooperative purchasing consortia to defend against tablet-based substitutes. Prioritize REACH-compliant bio-based polymer sourcing to preempt 2025 enforcement windows. For New Entrants and Emerging Players: Curriculum integration services for mid-tier European schools represent the most penetrable white-space where incumbents under-serve explainable AI mandates. Target India's government school computational thinking procurement under National Education Policy directives. Pursue white-label kit assembly partnerships with Karnataka electronics clusters as entry vector. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors edge-AI firmware specialists with embedded systems engineering depth over cloud-platform aggregators. Long-term viability hinges on subscription content library scale and district-level procurement relationship durability. Watch Seoul metropolitan school deployment completion rates as inflection indicator for humanoid platform demand saturation.| Strategic Initiative | Industry Significance |
|---|---|
| Edge AI Firmware Development | Local neural inference eliminates latency in EU schools with restricted connectivity mandates. |
| Curriculum Partnership Formation | District-level standardization in Texas and California consolidates procurement authority behind integrated vendors. |
| REACH-Compliant Material Transition | Bio-based polymer migration ahead of 2025 enforcement protects European market access for chassis suppliers. |
| Subscription Content Library Expansion | Cloud-based lesson repositories capture recurring revenue from districts seeking reduced curriculum development overhead. |
| Vocational Certification System Integration | German dual education system procurement creates durable demand for precision robotics training platforms. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with K-12 curriculum directors, embedded systems engineering leads, district procurement officers, and education distributor channel managers; and secondary validation against EU AI Act regulatory filings, SAMR network security protocols, SEC edtech company disclosures, and national digital education initiative budgets. Bottom-up unit shipment estimates triangulated against top-down education technology expenditure forecasts.
Across the projection horizon, the analytical framework modeled segmentation across product type, end-user institution tier, technology maturity gradient, and application revenue architecture. CAGRs derived from enrollment-driven replacement cycles, government-funded deployment targets, and firmware refresh timelines. Edge-based neural inference adoption curves and generative AI content development compression informed technology segment trajectories.
Underlying assumptions cover stable lithium-ion cell supply from Chinese sources, with deviation risk concentrated in export control volatility and REACH substance restriction acceleration. Practitioners should keep alternative scenarios live as EU AI Act enforcement interpretation and South Korea AI Digital Textbook deployment pacing evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Asia-Pacific Medical Robots Market
Robotics and Automation
Hotel Robot Market
Robotics and Automation
Robotic Lawn Mower Market
Robotics and Automation
Articulated Robots for Injection Molding Machine Market
Robotics and Automation
Japan Agricultural Robot Market
Robotics and Automation
Spain Cloud Robotics Market
Robotics and Automation
Italy Cloud Robotics Market
Robotics and Automation
South America AUV and ROV Market
Robotics and Automation
Europe Automated Liquid Handling Market
Robotics and Automation
Cordless Router Market
Robotics and Automation
Asia-Pacific Logistics Robotics Market
Robotics and Automation
Commercial Security Robots Market
Robotics and Automation
Autonomous Robot Market
Robotics and Automation
Underwater Drone Market
Robotics and Automation
Gimbal Stabilizers Market
Robotics and Automation
United States Agricultural Robots Market