
 SCARA Robots Market | 2026-2036
SCARA Robots Market Size, Share, and Industry Trends Forecast 2026-2036
SCARA Robots Market Analytics
Direct sales channels for SCARA robots is rewriting how Japanese and European manufacturers reach automotive and electronics buyers. FANUC Corporation leverages its captive servo-motor production to control cost structures across Asia-Pacific deployments. Seiko Epson Corporation specializes in compact, high-speed precision variants for micro-assembly tasks in camera and wearable device plants. KUKA AG anchors its European installed base through deep integration with German automotive OEM production lines.
SCARA robots are selective compliance articulated robotic arms with four degrees of freedom, typically offering repeatability of ±0.02 mm and cycle times under 0.4 seconds for pick-and-place operations. Their parallel-joint architecture permits rigid vertical motion combined with flexible horizontal positioning, purpose-built for high-speed assembly and material handling in confined workspaces. Standard robots dominate unit shipments across general manufacturing, while precision robots command margin pools in semiconductor and medical device assembly where tolerance thresholds tighten. Electronics end users represent the fastest-expanding demand segment, driven by miniaturization trends in consumer devices and battery module production.
ISO 10218 safety standards and the EU Machinery Directive constrain robot design, mandating collaborative speed limits and protective stop functions that shape R&D allocation across European and export-oriented manufacturers. China's GB standards and MIIT industrial robot certification requirements create parallel compliance pathways for vendors targeting domestic automation upgrades. Stakeholders must monitor divergence between regional safety regimes and the pace of visual guidance technology maturation to calibrate platform development bets.
Market Dynamics
Visual guidance systems and force-sensing end-effectors are compressing deployment timelines for SCARA robots in electronics assembly, reducing commissioning cycles from weeks to days and reshaping how integrators bid for automotive and medical device contracts.
Growth Catalysts
- EU Machinery Directive compliance mandates:European electronics manufacturers accelerate robot replacement cycles to meet protective stop and collaborative speed requirements ahead of certification deadlines.
- Micro-assembly tolerance demands:Camera module and wearable device plants in Vietnam and Thailand deploy precision SCARA variants for sub-millimeter component placement in battery and sensor integration.
- Guangdong Province automation subsidies:China's MIIT industrial robot certification program reduces import duty burdens for domestically certified equipment, channeling procurement toward local integration partners.
Market Restraints
- Harmonic drive supply concentration:Japanese and German precision gear suppliers control critical torque transmission components, exposing lead times to single-source geographic risk.
- ISO 10218 certification friction:Divergent interpretation of collaborative robot speed limits between EU notified bodies and Asian test houses extends type-approval timelines for export-oriented vendors.
- Linear motor substitution in high-speed pick-and-place:Cartesian gantry systems with direct-drive actuation capture throughput-sensitive applications above 120 cycles per minute in flat-panel display handling.
Strategic Opportunities
- India PLI scheme for electronics manufacturing:Contract manufacturers establishing smartphone assembly in Uttar Pradesh and Tamil Nadu represent greenfield robot deployment with limited incumbent vendor relationships.
- Force-torque sensor convergence with SCARA kinematics:Tactile feedback integration enables peg-in-hole operations in medical device assembly previously reserved for six-axis articulated arms.
- Direct OEM sales channel expansion:Japanese manufacturers bypass traditional distributor networks in Mexico and Eastern Europe to capture margin and accelerate technical support response.
Industry Challenges
- Robot programmer certification gaps:Shortage of technicians qualified in ISO 10218 safety parameter configuration and PLC integration extends commissioning timelines in Southeast Asian contract electronics plants.
- Legacy SCARA fleet interoperability:Proprietary communication protocols from 1990s-era installations obstruct data extraction for predictive maintenance retrofits in German automotive supplier parks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | SCARA Robots Market |
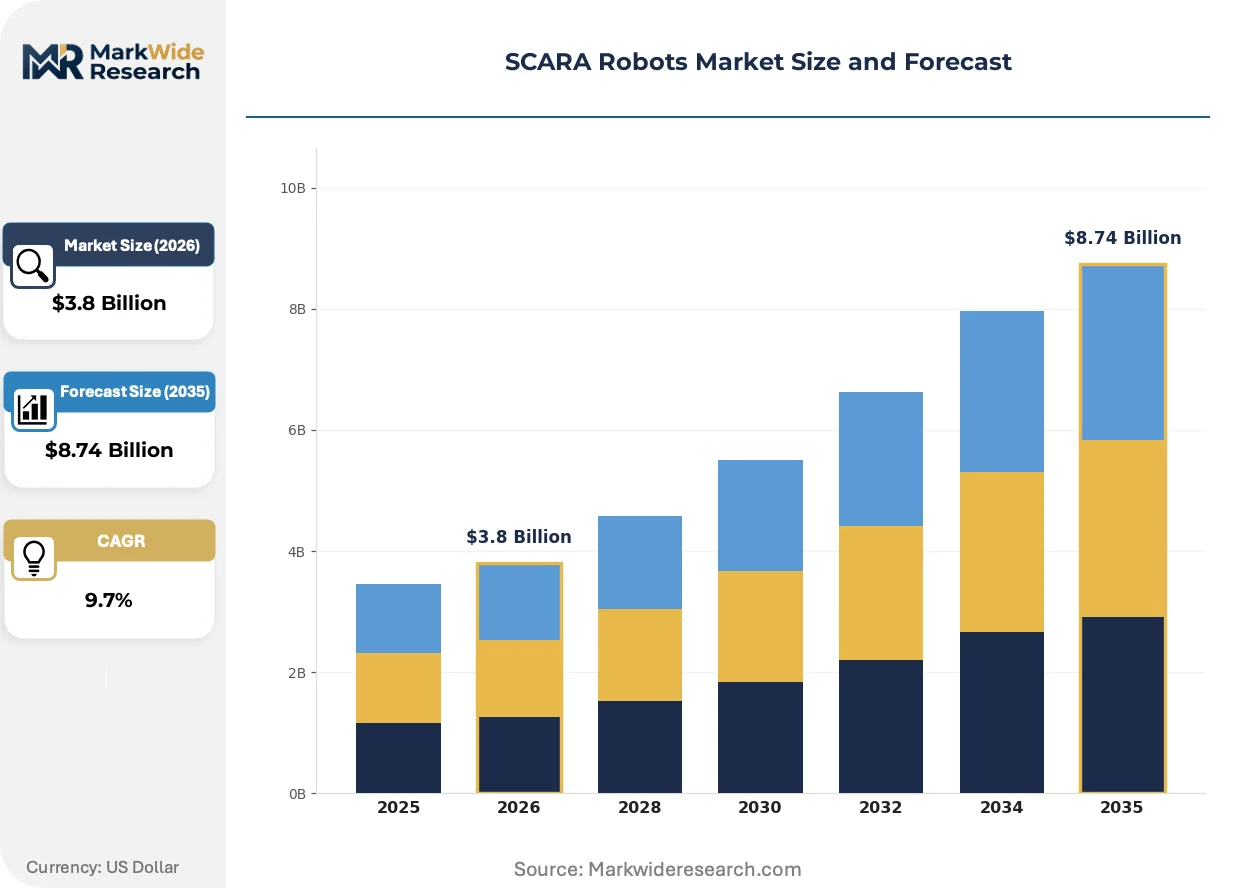
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Robots, High-Speed Robots, Precision Robots, Modular Robots End User: Manufacturing, Electronics, Automotive, Food & Beverage Application: Assembly, Pick and Place, Packaging, Material Handling Technology: Visual Guidance, Force Control, Motion Control, Sensor Integration |
| Companies Covered | ABB Ltd., FANUC Corporation, Yaskawa Electric Corporation, KUKA AG, Seiko Epson Corporation, DENSO Corporation, Omron Corporation, Kawasaki Heavy Industries Ltd., Delta Electronics Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
SCARA Robots Market Evolving Landscape
Machine vision integration and edge computing architectures are redefining SCARA robot capability boundaries, shifting competitive differentiation from mechanical precision to software-defined adaptability in mixed-model production environments.
Vision-guided SCARA systems are migrating from fixed-calibration setups to adaptive part-recognition platforms. Electronics contract manufacturers in Malaysia and Mexico deploy these for rapid changeover between smartphone and tablet assembly configurations. The technology is compressing integration service revenue pools as end-users internalize programming capabilities.
China's GB standards for collaborative robot safety are diverging from ISO 10218-1 speed and force thresholds. Domestic vendors optimize control algorithms for these local parameters, creating certification bifurcation for multinational manufacturers serving both export and domestic Chinese demand. European and Japanese suppliers maintain dual firmware branches to preserve market access.
After-sales service unbundling is fragmenting traditional robot vendor revenue models. Automotive tier-one suppliers in Hungary and the Czech Republic now procure maintenance contracts from third-party integrators rather than original equipment manufacturers. This shift concentrates spare parts procurement power with regional distributors and erodes manufacturer margin capture in Central European installed bases.
SCARA Robots Market Segmentation
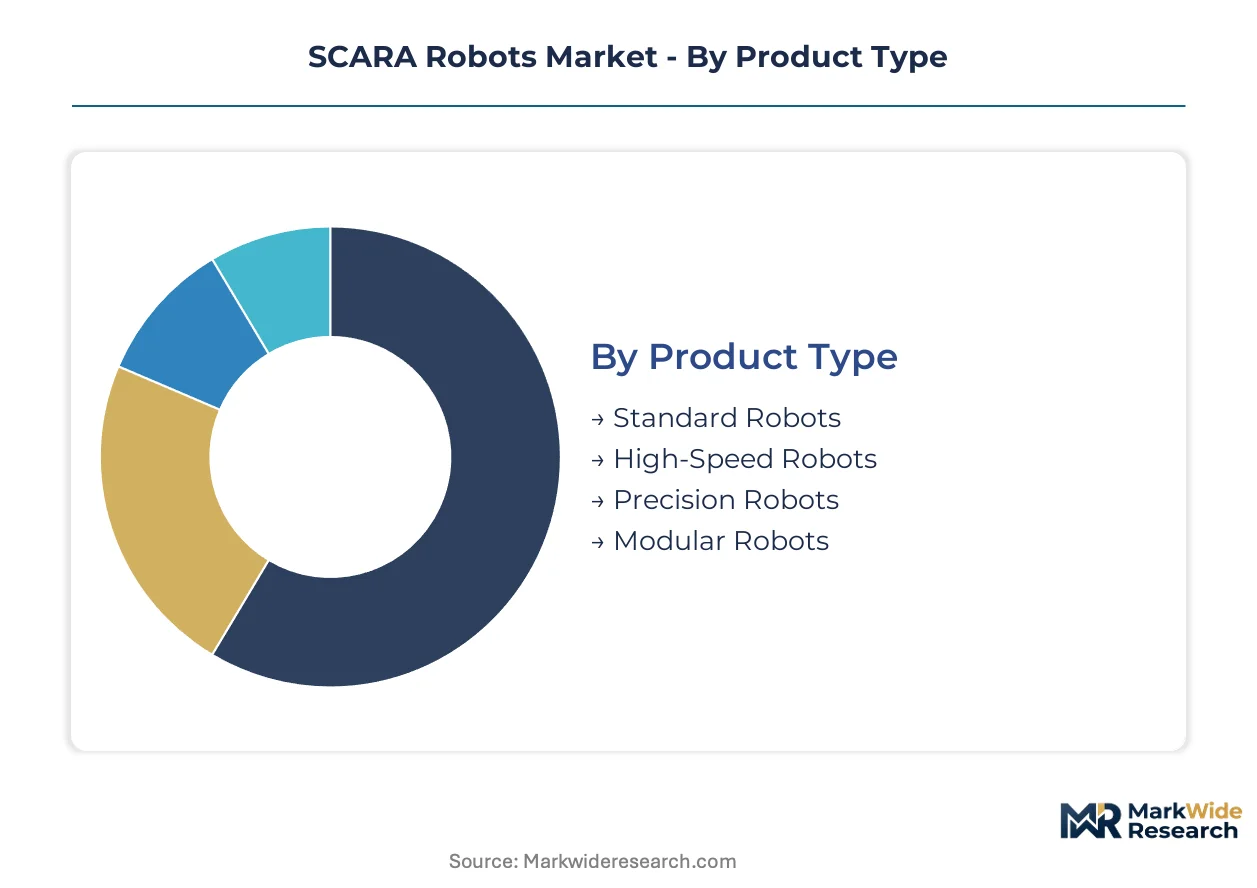
SCARA robot segmentation reflects divergent technical specifications across assembly tolerances, cycle speeds, and workspace constraints. Electronics manufacturers in Vietnam and Thailand drive demand fragmentation as micro-assembly tasks multiply. Procurement patterns split between high-volume standard deployments and precision variants for semiconductor packaging.
Product Type:
The use-case spectrum spans general manufacturing throughput to sub-millimeter placement accuracy in medical device cleanrooms.
- Standard Robots:Four-axis architecture with ±0.05 mm repeatability and payload capacity up to 20 kg dominates automotive component handling and general material transfer. Guangdong Province contract electronics manufacturers deploy these for battery module assembly where cycle consistency outweighs absolute precision.
- Precision Robots:Hardened mechanical linkages and harmonic drive configurations achieve ±0.02 mm repeatability for camera module alignment and wearable sensor integration. Malaysia's optoelectronics cluster sources these variants for lens barrel assembly where defect rates below 50 ppm justify unit cost premiums.
- High-Speed Robots:Optimized servo loops and reduced arm mass enable cycle times below 0.3 seconds in high-volume consumer electronics pick-and-place.
- Modular Robots:Reconfigurable joint modules and interchangeable end-effector interfaces support mixed-model production lines in Mexican automotive tier-one plants.
The dominant share belongs to Standard Robots, while Precision Robots is closing the gap fastest.
End User:
Cost tier differentiation separates high-automation electronics fabs from labor-augmented food processing lines.
- Electronics:Smartphone, tablet, and battery manufacturers in Uttar Pradesh and Tamil Nadu drive greenfield SCARA procurement under India's PLI scheme. Miniaturization trends in TWS earbud and smartwatch assembly push tolerance requirements below 0.05 mm for component placement.
- Automotive:Powertrain component handling and ECU assembly in Hungarian and Czech supplier parks demand ISO 10218-compliant collaborative variants with force-limiting functions.
- Manufacturing:General industrial automation spans metal fabrication, plastics processing, and secondary packaging across Eastern European industrial zones.
- Food & Beverage:Washdown-rated SCARA variants with IP65 protection handle primary packaging and tray loading in dairy and confectionery plants.
Electronics commands the largest procurement volume, with Automotive expanding most quickly as electric vehicle battery module assembly scales.
Application:
Volume concentration favors high-frequency pick-and-place cycles over intermittent material handling tasks.
- Pick and Place:Continuous component transfer between conveyor belts and fixture stations accounts for the majority of SCARA operating hours. Thailand's hard disk drive manufacturers optimize these motions for sub-0.4 second cycle times in read/write head assembly.
- Assembly:Screw driving, adhesive dispensing, and press-fit operations in medical device plants leverage force-torque feedback for compliant part mating.
- Packaging:End-of-line case packing and palletizing in beverage facilities exploit SCARA horizontal reach for layer formation.
- Material Handling:Machine tending and bin picking applications in metalworking shops utilize vision guidance for unstructured part presentation.
Pick and Place holds the dominant operational share, while Assembly gains share fastest as force-controlled peg-in-hole tasks migrate from six-axis arms.
Technology:
Margin pools concentrate in sensor fusion architectures that compress commissioning timelines and reduce integrator dependency.
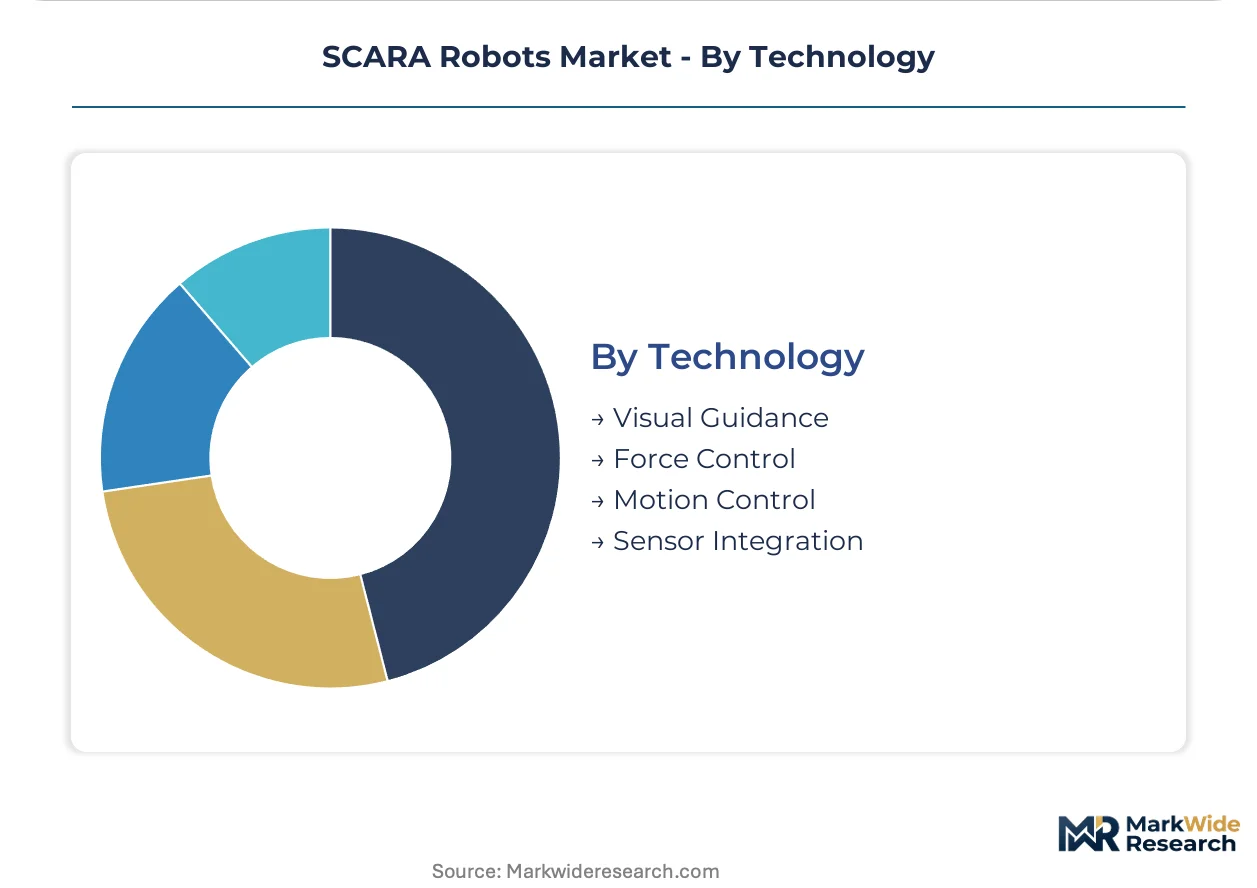
- Visual Guidance:2D and 3D machine vision systems with adaptive calibration enable rapid changeover between smartphone and tablet configurations in Mexican contract manufacturing. Edge computing architectures process part recognition locally, reducing PLC communication latency.
- Force Control:Six-axis force-torque sensors at the wrist enable compliant insertion of delicate medical device components previously requiring manual assembly.
- Motion Control:Advanced servo algorithms and vibration suppression improve settling times for high-speed precision applications.
- Sensor Integration:Combined vision, force, and proximity sensing creates multimodal feedback for unstructured environments.
Visual Guidance captures the dominant technology investment, with Force Control climbing the fastest as medical device assembly tolerances tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT's industrial robot certification program anchors China's procurement framework, while ISO 10218 compliance mandates reshape European replacement cycles. Guangdong Province subsidies channel investment toward domestic integration partners.
China
Guangdong Province contract electronics manufacturers drive precision SCARA procurement for battery module assembly. MIIT certification requirements reduce import duty burdens for domestically certified equipment, favoring local integration partnerships. Shenzhen and Dongguan industrial clusters host the densest concentration of smartphone and wearable device automation lines.
Japan
Harmonic drive and precision gear suppliers concentrate torque transmission component production in Nagano and Yamanashi prefectures. METI industrial policy supports next-generation robot R&D through subsidy programs targeting SME automation adoption. Kanto region manufacturers supply servo-motor and controller subsystems to Asia-Pacific integrators.
Germany
Automotive tier-one suppliers in Bavaria and Baden-Württemberg demand ISO 10218-compliant collaborative variants with force-limiting functions. KBA and EU Machinery Directive enforcement accelerates robot replacement cycles ahead of certification deadlines. Stuttgart supplier parks maintain Europe's largest installed base of precision assembly automation.
United States
OSHA workplace safety guidelines and NHTSA automotive quality standards shape SCARA deployment in Michigan and Ohio manufacturing corridors. Electronics reshoring initiatives in Texas and Arizona drive greenfield automation investment for semiconductor packaging. Mexican maquiladora partnerships concentrate final assembly capacity in border states.
India
PLI scheme incentives attract contract manufacturers to Uttar Pradesh and Tamil Nadu smartphone assembly facilities. BIS certification requirements for industrial equipment create compliance pathways for imported robot systems. Karnataka's electronics manufacturing clusters in Bengaluru represent emerging demand for micro-assembly precision variants.
SCARA Robots Market Competitive Landscape
Integrated conglomerates and specialized precision manufacturers split the market along vertical integration fault lines. Japanese and European vendors control harmonic drive supply chains through captive production or long-term supplier relationships. Three archetypes dominate: servo-motor integrators with component cost advantages, precision gear specialists with tolerance leadership, and software-centric vendors betting on vision-guided adaptability. Capacity expansion in Southeast Asian service hubs and strategic partnerships with regional integrators constitute the dominant competitive moves.
Among Japanese precision manufacturers, FANUC Corporation and Seiko Epson Corporation exemplify divergent specialization strategies. FANUC leverages in-house servo-motor production to manage cost structures across high-volume deployments. Seiko Epson occupies a position centered on compact kinematics for sub-millimeter assembly tasks. European vendor KUKA AG anchors collaborative robot certification expertise within German automotive supply chains. These three represent distinct archetype positions rather than direct product competition.
| Leading Market Players |
|---|
| ABB Ltd. |
| FANUC Corporation |
| Yaskawa Electric Corporation |
| KUKA AG |
| Seiko Epson Corporation |
| DENSO Corporation |
| Omron Corporation |
| Kawasaki Heavy Industries Ltd. |
| Delta Electronics Inc. |
| Others |
Value Network & Pricing Analysis
Harmonic drive supply concentration in Nagano and Yamanashi prefectures creates single-source vulnerability that compresses margin pools at the precision tier while inflating standard robot price spreads. Japanese and German gear suppliers command 18-24 month order backlogs, forcing SCARA vendors to absorb cost volatility or pass through to electronics contract manufacturers in Guangdong and Vietnam.
Pricing Analysis
Configured-to-order precision variants command 40-60% premiums over standard catalog configurations due to harmonic drive customization and ISO 10218-1 collaborative certification tiering. Three-tier pricing structure across premium, standard, and economy levels stratifies by repeatability grade, with ±0.02 mm tolerance robots priced distinctly from ±0.05 mm general manufacturing units. Pricing pressure stems from Chinese domestic vendors optimizing for GB standard collaborative parameters, eroding Japanese and European margin capture in Shenzhen and Dongguan procurement. Electronics contract manufacturers in Vietnam exhibit highest price sensitivity, while German automotive tier-one suppliers prioritize force-limiting certification over unit cost.
Supply Chain Analysis
Export-control restrictions on precision motion control firmware constrain cross-border technology flows between Japanese servo-motor suppliers and Chinese system integrators. Critical torque transmission components concentrate in Japan and Germany, with secondary controller assembly in China and Taiwan. Supply chains draw from rare-earth magnet suppliers in Inner Mongolia, precision bearing manufacturers in Thuringia, and servo-drive semiconductor foundries in South Korea. Single-source vulnerability concentrates in harmonic drive gearing, where Nabtesco and Harmonic Drive Systems anchor global capacity. Distribution runs through regional integrator networks in Guangdong, Bavaria, and Michigan rather than direct OEM channels for sub-50 unit deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
SCARA robot vendors operate within a defensive moat constructed around regulatory certification entrenchment and customer switching costs tied to production line integration. ISO 10218 and GB standard dual-compliance investments create sticky relationships with automotive and electronics manufacturers.
For Market Incumbents: Pre-empt Chinese domestic vendor expansion by accelerating MIIT certification partnerships with Guangdong integration specialists before subsidy windows narrow. Lock in harmonic drive supply through multi-year offtake agreements with Nagano suppliers to neutralize emerging entrants' component access. Defend against Cartesian gantry substitution in flat-panel display handling by embedding vision-guided SCARA platforms in Korean and Taiwanese OLED equipment specifications.
For New Entrants and Emerging Players: Uttar Pradesh and Tamil Nadu smartphone assembly corridors offer white-space deployment with limited incumbent service infrastructure. Target medical device precision assembly in Karnataka's Bengaluru cluster where force-torque sensor integration creates differentiation against standard electronics-focused portfolios. Establish direct technical support presence in India's PLI scheme zones rather than distributor-dependent models that Japanese vendors employ.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors precision gear specialists with captive servo-motor integration. Long-term viability hinges on software-defined adaptability margins overtaking mechanical precision premiums. Acquisition targets should demonstrate visual guidance platform maturity and edge computing architectures for mixed-model production. Monitor divergence between EU Machinery Directive enforcement timelines and Chinese GB standard evolution as the signal for certification arbitrage opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Harmonic Drive Supply Agreement | Secures torque transmission component access from Nagano suppliers for 24-month production visibility. |
| Dual Firmware Branch Development | Maintains ISO 10218 and GB standard compliance to preserve market access across European and Chinese demand. |
| India Technical Support Hub | Establishes direct service presence in Tamil Nadu to capture PLI scheme procurement before incumbent distributor lock-in. |
| Vision-Guided Platform Launch | Compresses commissioning timelines from weeks to days for Mexican and Malaysian contract electronics manufacturers. |
| Force-Torque Sensor Integration | Enables medical device peg-in-hole operations previously reserved for six-axis articulated arms in Stuttgart supplier parks. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC filings, MIIT industrial robot certification databases, and EU Machinery Directive notification records. Primary interviews engaged plant engineers at Guangdong contract electronics manufacturers, procurement leads at German automotive tier-one suppliers, and aftermarket service heads at Japanese precision gear vendors. Secondary validation drew from customs trade data for SCARA robot imports, IHS Markit industrial automation equipment registries, and ISO 10218 test house certification timelines. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions across precision and standard robot tiers.
Forecast inputs span robot kinematics architecture, end-use industry automation intensity, and regional regulatory compliance divergence. Segmentation dimensions modeled include product type precision grade, electronics versus automotive end-use concentration, and visual guidance technology adoption curves. CAGRs derived from regression analysis of historical shipment data against MIIT subsidy disbursement patterns and EU Machinery Directive replacement cycle assumptions. Supply-side constraints incorporated harmonic drive capacity utilization and servo-motor semiconductor lead time volatility.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese domestic vendors or accelerated GB standard divergence would shift outcomes. Material shifts in EU-China regulatory harmonization negotiations or harmonic drive supply disruption would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Global Agriculture Robots Market
Robotics and Automation
Global Mobile Robots Market
Robotics and Automation
AI Assisted Robots Market
Robotics and Automation
Global Programmable Robots Market
Robotics and Automation
Autonomous Robot Market
Robotics and Automation
Smart Personal Assistance Devices Market
Robotics and Automation
Robotic Waste Sorting System Market
Robotics and Automation
Europe Agricultural Robot Market
Robotics and Automation
Middle East and Africa Underwater Robotics Market
Robotics and Automation
Global Robot Teach Pendant Market
Robotics and Automation
Foundry and Forging Robots Market
Robotics and Automation
Autonomous Mobile Manipulator Robots (AMMR) Market
Robotics and Automation
LAMEA Demolition Robot Market
Robotics and Automation
Robot Fleet Management Software Market
Robotics and Automation
Global AI Based Surgical Robots Market
Robotics and Automation
Latin America Cloud Robotics Market