
 Autonomous Security Robots Market | 2026-2036
Autonomous Security Robots Market Size, Share, and Industry Trends Forecast 2026-2036
Autonomous Security Robots Market Insights
Direct-to-facility sales channels is reconfiguring how autonomous security robots reach end users, bypassing traditional security integrators and shortening deployment timelines. Knightscope, Inc. controls proprietary manufacturing of its ASR units in Silicon Valley, enabling rapid hardware iteration and direct service relationships with corporate campuses. Cobalt Robotics specializes in indoor patrol automation for technology offices, leveraging a subscription-based deployment model that reduces upfront capital barriers. Boston Dynamics anchors premium quadruped mobility platforms for tactical security scenarios, sustaining defense-adjacent pricing power through advanced locomotion engineering.
Autonomous security robots are self-navigating electromechanical systems integrating lidar arrays, thermal cameras, and edge-computing processors to execute patrol, detection, and alert functions without continuous human operator input. These platforms typically operate on battery-electric powertrains with four-to-eight-hour endurance cycles and communicate via encrypted 4G or private 5G networks to centralized monitoring stations. Ground robots dominate current procurement volumes due to lower unit costs and established regulatory pathways for sidewalk and roadway traversal in urban environments. Aerial drones command premium positioning within the technology segment as computer vision algorithms enable real-time anomaly recognition across expansive perimeters where fixed sensors prove inadequate. Warehousing operators represent the fastest-expanding end user category, driven by inventory protection requirements and integration with existing warehouse management systems.
FAA regulations govern commercial drone operations below four hundred feet in the United States, creating certification bottlenecks that slow aerial platform deployment but also erect competitive moats for compliant vendors. The EU AI Act's high-risk system classification for autonomous security applications mandates conformity assessments and human oversight protocols, reshaping product development roadmaps for vendors targeting European government agencies. ISO 13482 safety standards for personal care robots increasingly inform liability frameworks for ground-based security units operating in pedestrian-dense environments. Stakeholders must weigh regulatory compliance investments against the fragmentation of national approval pathways as procurement scales from pilot programs to fleet-wide deployments.
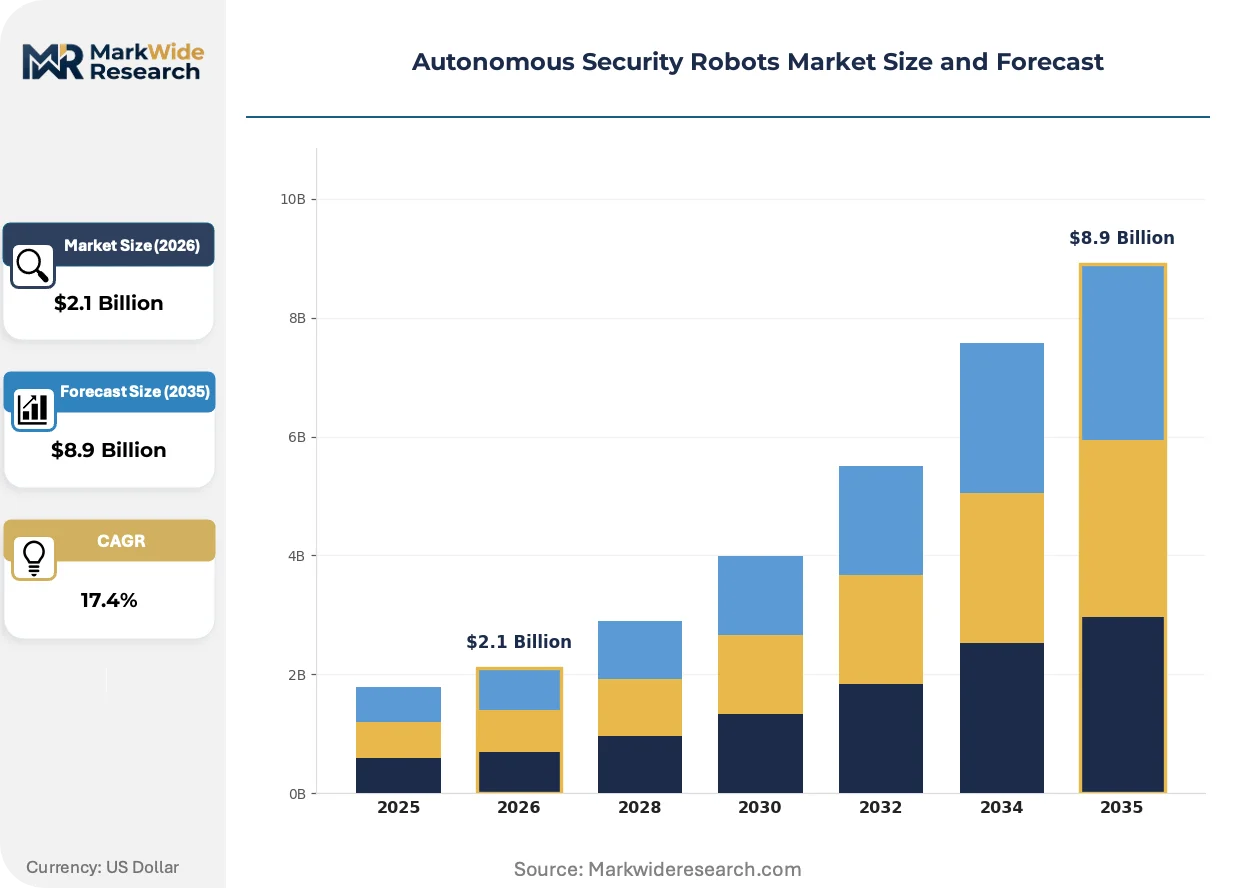
Market Dynamics
The Autonomous Security Robots Market is being fundamentally restructured by the EU AI Act's high-risk system classification, which mandates conformity assessments and human oversight protocols that reshape product development roadmaps and compliance investments across all vendors targeting European government agencies.
Growth Catalysts
- Smart city infrastructure mandates:China's domestic sensor supply chains enable rapid fleet deployment across transportation hubs and industrial zones, compressing procurement cycles for municipal buyers.
- Labor cost escalation:Commercial facilities in the United States are expanding procurement of autonomous patrol units as around-the-clock coverage requirements tighten and security staffing costs rise.
- Edge-computing processor maturation:Thermal camera and lidar integration with onboard AI inference engines reduces latency for real-time anomaly detection without continuous cloud connectivity.
Market Restraints
- Lithium-ion battery supply concentration:Cathode material processing and cell manufacturing gravity centers on East Asian suppliers, exposing fleet operators to input cost volatility and logistics bottlenecks.
- FAA certification bottlenecks:Commercial drone operations below four hundred feet require extensive airworthiness documentation and pilot licensing, slowing aerial platform deployment timelines in the United States.
- Fixed sensor substitution:Perimeter camera networks with AI-enabled video analytics offer lower capital outlays for facilities with predictable boundaries, constraining ground robot penetration in static environments.
Strategic Opportunities
- Warehouse management system integration:Warehousing operators represent an emerging end-use category where inventory protection requirements align with existing automation infrastructure and WMS APIs.
- Subscription-based deployment models:Technology offices are adopting indoor patrol automation through recurring revenue arrangements that reduce upfront capital barriers and accelerate vendor-customer relationships.
- Private 5G network infrastructure:Telecommunications carriers are building dedicated campus networks that enable encrypted, low-latency robot-to-control-station communication for defense-adjacent and critical infrastructure sites.
Industry Challenges
- ISO 13482 safety standard interpretation:Liability frameworks for ground-based units operating in pedestrian-dense environments remain unsettled as insurers and courts apply personal care robot precedents to security applications.
- Legacy access control integration:Physical security departments struggle to synchronize autonomous patrol data with existing badge systems and alarm management platforms, extending deployment timelines.
- Mechatronics talent scarcity:The convergence of robotics hardware, embedded software, and cybersecurity expertise creates recruitment bottlenecks for engineering teams developing field-ready platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Autonomous Security Robots Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $8.9 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Robot Type: Ground Robots, Aerial Drones, Hybrid Robots, Stationary Robots Technology: Computer Vision, Lidar, Radar, Infrared Sensors, Ultraviolet Sensors Application: Perimeter Surveillance, Crowd Monitoring, Asset Protection, Intrusion Detection End User: Commercial Facilities, Government Agencies, Warehousing Operators, Event Management Firms |
| Companies Covered | Knightscope, Inc., Boston Dynamics, AeroVironment, Inc., Lockheed Martin Corporation, Northrop Grumman Corporation, BAE Systems, Elbit Systems Ltd., ReconRobotics, Cobalt Robotics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Autonomous Security Robots Market Trends and Innovations
Digital twin architectures are virtualizing how security operations centers monitor and optimize robot fleets, compressing the feedback loop between field deployment and algorithm refinement while reducing the need for physical prototyping.
Lidar array manufacturers are integrating solid-state beam steering with silicon photonics to eliminate mechanical scanning components. Warehouse operators and logistics campuses are adopting these compact sensors for indoor navigation where vibration tolerance and form factor constraints dominate. This hardware consolidation is virtualizing the traditional sensor fusion stack by pushing more processing to specialized ASICs rather than general-purpose edge computers.
The EU AI Act's risk classification framework for autonomous security applications now mandates documented conformity assessments and human oversight protocols for systems deployed in public spaces. European manufacturers are restructuring engineering workflows to embed explainability features and kill-switch mechanisms at the architecture stage rather than retrofitting compliance. Government agency procurement in Germany, France, and the Netherlands now requires third-party audit trails for algorithmic decision-making, favoring vendors with pre-certified platforms.
Facility security directors are unbundling hardware ownership from operational service, preferring robot-as-a-service contracts where vendors retain asset risk and performance accountability. Corporate campuses in California and Texas are leading this transition, replacing capital budgets with operational expenditure lines that scale with patrol coverage hours. This financing restructuring is concentrating vendor relationships around uptime guarantees and incident response SLAs rather than equipment specifications alone.
Autonomous Security Robots Market Segmentation
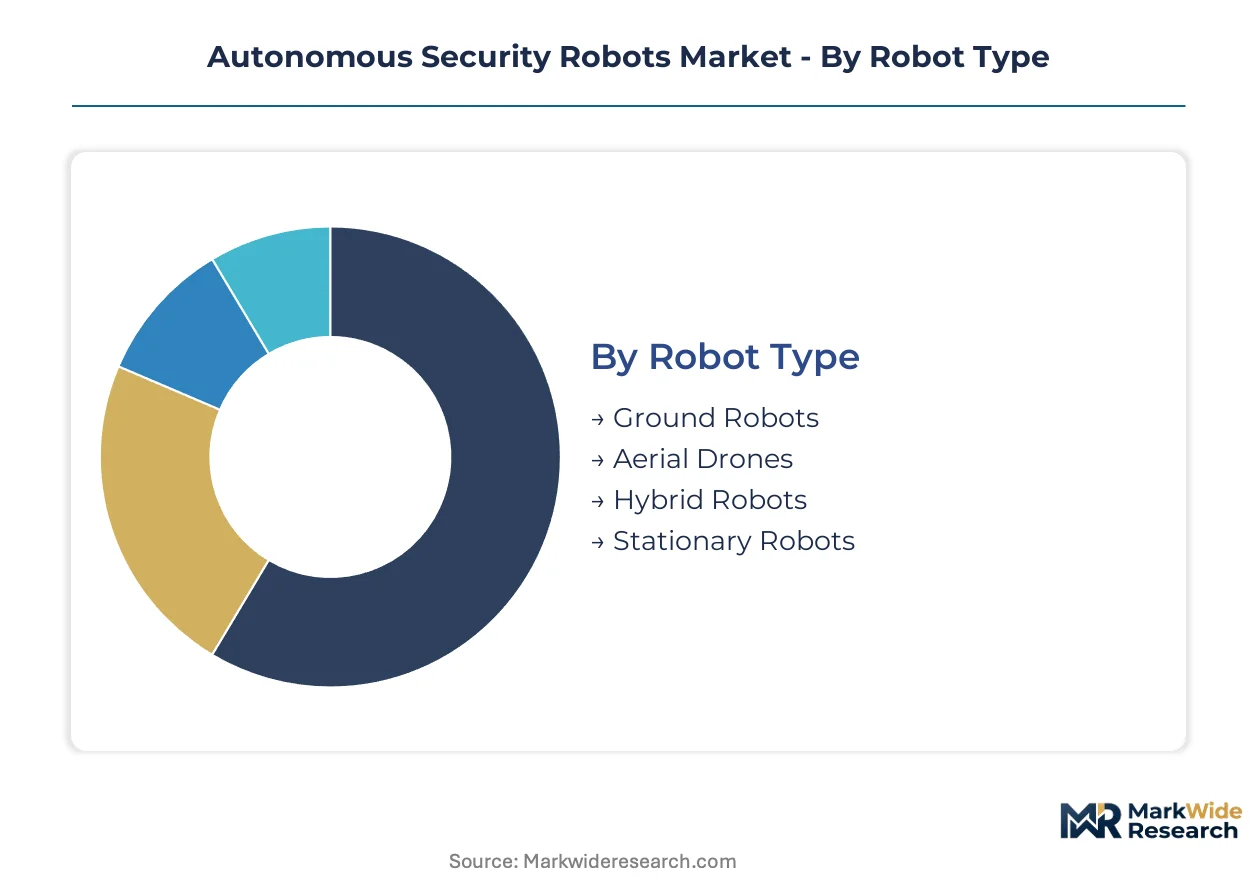
Autonomous security robots serve divergent operational requirements across mobility platforms, sensing architectures, deployment scenarios, and buyer categories. Segmentation reveals how hardware specifications, software capabilities, and procurement patterns cluster around distinct risk profiles and coverage mandates.
Robot Type:
Mobility architecture determines unit economics, regulatory pathway complexity, and operational envelope for autonomous security platforms.
- Ground Robots:Wheeled and tracked electromechanical platforms integrate lidar arrays with thermal cameras for sidewalk and roadway traversal. Municipal buyers in the United States prioritize these units for 24-hour patrol coverage where labor cost escalation strains security budgets.
- Aerial Drones:Rotary-wing and fixed-wing unmanned aircraft carry computer vision payloads for expansive perimeter monitoring where terrain obstacles block ground access. FAA certification requirements below four hundred feet create competitive moats for compliant vendors while slowing deployment timelines.
- Hybrid Robots:Amphibious and transformable platforms switch between terrestrial and aerial locomotion modes for disaster response and critical infrastructure protection.
- Stationary Robots:Fixed-position sensor pods with pan-tilt-zoom capabilities and embedded AI processors guard entry points and chokepoints without navigation systems.
Ground robots command the established base. The steepest expansion runs through aerial drones as computer vision algorithms mature for real-time anomaly recognition.
Technology:
Sensing modality selection shapes detection accuracy, environmental robustness, and integration complexity with existing security infrastructure.
- Computer Vision:Deep learning algorithms process visible-spectrum camera feeds for object classification and behavioral analysis. Technology offices in California deploy these systems for indoor crowd monitoring where lighting conditions remain controlled.
- Lidar:Solid-state and mechanical scanning systems generate three-dimensional point clouds for navigation and intruder tracking. Warehouse operators favor compact silicon photonics variants for vibration tolerance in logistics environments.
- Radar:Millimeter-wave and doppler systems penetrate fog, dust, and precipitation for perimeter surveillance in adverse weather conditions.
- Infrared Sensors:Thermal imaging cores detect heat signatures for night operations and concealed object identification without active illumination.
- Ultraviolet Sensors:Specialized detectors identify chemical and biological agent fluorescence for defense-adjacent and critical infrastructure applications.
Lidar and computer vision anchor current procurement volumes. Ultraviolet sensors are climbing the fastest as dual-use security-chemical detection requirements spread from military to civilian critical infrastructure.
Application:
Deployment scenario dictates sensor payload configuration, patrol pattern algorithms, and human oversight intensity.
- Perimeter Surveillance:Continuous boundary monitoring using overlapping sensor fields and autonomous patrol routing. Transportation hubs in China integrate these systems with smart city infrastructure for passenger safety and intrusion prevention.
- Crowd Monitoring:Density estimation and anomaly detection in pedestrian-dense environments. Event management firms deploy computer vision platforms for flow optimization and emergency response triggering.
- Asset Protection:Inventory and equipment safeguarding through proximity sensing and access control integration. Warehousing operators represent the fastest-expanding demand category as e-commerce fulfillment centers scale automation.
- Intrusion Detection:Unauthorized entry identification and alert generation for high-security facilities. Government agencies mandate human oversight protocols under EU AI Act high-risk system classifications.
Perimeter surveillance holds the revenue base. Asset protection is gaining share fastest as warehouse management system APIs enable seamless robot-fleet integration.
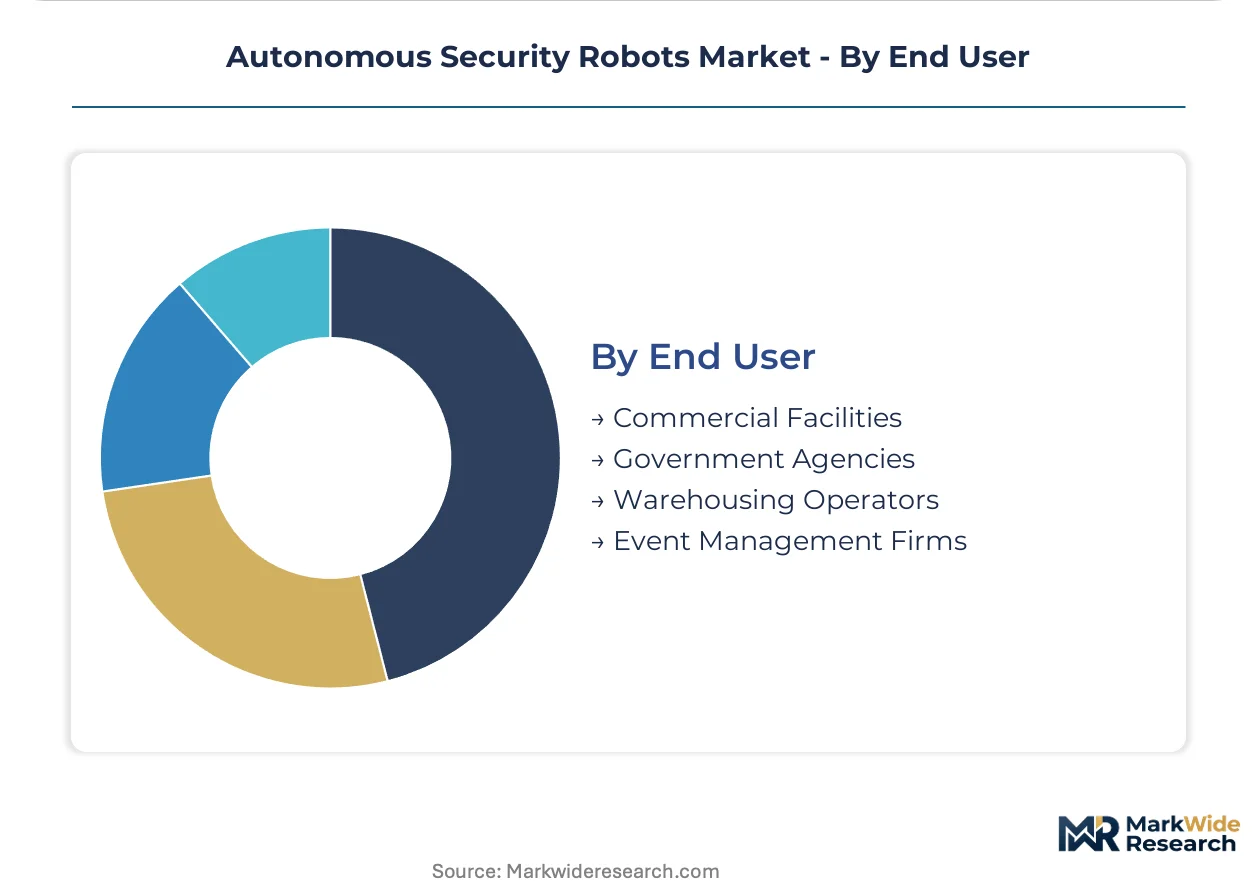
End User:
Buyer category determines procurement channel preference, financing structure, and compliance burden intensity.
- Commercial Facilities:Corporate campuses and retail complexes purchase patrol automation to reduce security staffing costs. Texas and California facilities lead adoption of robot-as-a-service contracts replacing capital expenditure with operational scaling.
- Government Agencies:Municipal, state, and federal buyers require documented conformity assessments and algorithmic audit trails. European procurement in Germany, France, and Netherlands now mandates third-party certification under EU AI Act frameworks.
- Warehousing Operators:Logistics and distribution centers prioritize inventory protection and integration with existing automation infrastructure.
- Event Management Firms:Temporary deployment specialists rent aerial and ground units for crowd control at sporting venues and entertainment gatherings.
Commercial facilities command the established base. Warehousing operators show the steepest expansion trajectory as e-commerce fulfillment automation accelerates fleet deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Unit pricing for autonomous security robots in the United States runs 35-45% above comparable deployments in China, reflecting divergent labor cost baselines and regulatory compliance burdens. This asymmetry concentrates manufacturing investment in Chinese sensor supply chains while US procurement favors higher-specification platforms with extended service contracts.
United States
Commercial campuses in Texas and California are replacing capital budgets with robot-as-a-service contracts that scale patrol coverage hours. FAA regulations below four hundred feet create certification bottlenecks for aerial platforms, erecting competitive moats for compliant vendors. Knightscope maintains proprietary manufacturing in Silicon Valley, enabling rapid hardware iteration for corporate security departments.
China
Smart city infrastructure programs are compressing procurement cycles for municipal buyers across transportation hubs and industrial zones. Domestic sensor supply chains enable rapid fleet deployment with reduced import dependency. The Yangtze River Delta and Pearl River Delta regions concentrate manufacturing gravity for lidar arrays and edge-computing processors.
Germany
Government agency procurement now mandates third-party audit trails for algorithmic decision-making under EU AI Act frameworks. Conformity assessments and human oversight protocols are reshaping product development roadmaps for vendors targeting European markets. Industrial security applications in Bavaria and North Rhine-Westphalia favor ground-based units with documented safety certifications.
Japan
Warehousing operators are integrating autonomous patrol units with existing warehouse management system APIs for inventory protection. METI guidelines on autonomous systems in industrial environments are accelerating standardization efforts. The Kanto region around Tokyo anchors demand from e-commerce fulfillment centers scaling automation infrastructure.
United Kingdom
Corporate facilities in London and the Southeast are adopting subscription-based deployment models to reduce upfront capital barriers. GDPR compliance requirements intersect with AI Act risk classifications for security applications processing biometric data. The Midlands region shows emerging demand from logistics campuses requiring perimeter surveillance integration.
Autonomous Security Robots Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying lidar arrays, thermal cores, and edge processors. The vendor base clusters around three strategic archetypes: defense-adjacent contractors leveraging existing government relationships, Silicon Valley hardware startups with direct-to-facility sales channels, and industrial automation incumbents extending into security applications. Dominant competitive moves include strategic partnerships with telecommunications carriers for private 5G integration and portfolio diversification into warehouse management system APIs.
Within the defense-adjacent tier, Lockheed Martin Corporation and Northrop Grumman Corporation exemplify contractors with established government procurement pathways. Knightscope, Inc. represents the direct-to-facility model with proprietary manufacturing and corporate campus relationships. Cobalt Robotics occupies a position exemplifying subscription-based indoor patrol automation for technology offices, reducing capital barriers through recurring revenue structures.
| Leading Market Players |
|---|
| Knightscope, Inc. |
| Boston Dynamics |
| AeroVironment, Inc. |
| Lockheed Martin Corporation |
| Northrop Grumman Corporation |
| BAE Systems |
| Elbit Systems Ltd. |
| ReconRobotics |
| Cobalt Robotics |
| Others |
Pricing and Supply Chain Analysis
The Yangtze River Delta's concentration of lidar array and edge-computing processor capacity grants Chinese manufacturers substantial downstream pricing leverage against US and European competitors. This geographic asymmetry compresses procurement cycles for domestic buyers while forcing importers to absorb logistics premiums and tariff exposure.
Pricing Analysis
The customization-premium spread separates standard ground patrol units from configured-to-order platforms with specialized sensor payloads. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with EU AI Act-compliant systems commanding substantial premiums over baseline configurations. Pricing pressure stems from lithium-ion battery cathode material volatility and East Asian cell manufacturing concentration. Warehousing operators exhibit the highest price sensitivity due to thin logistics margins, while defense-adjacent buyers prioritize performance specifications over unit economics.
Supply Chain Analysis
Foxconn, Pegatron, and Jabil Electronics anchor contract-manufacturing capacity for electromechanical assemblies and edge-computing modules. Component sourcing draws from China's domestic sensor supply chains for lidar arrays, South Korean memory foundries for onboard storage, and Taiwanese semiconductor fabs for AI inference processors. Single-source vulnerability concentrates in solid-state lidar beam-steering ASICs where silicon photonics expertise remains geographically clustered. Distribution runs through direct-to-facility sales channels that bypass traditional security integrators, shortening deployment timelines for corporate campus buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward warehousing operators and municipal procurement departments as fleet-scale deployments consolidate demand around fewer volume purchasers. This concentration pressures vendors to absorb performance risk through robot-as-a-service structures.
For Market Incumbents: Pre-empt subscription-based entrants by embedding kill-switch mechanisms and explainability features at the architecture stage rather than retrofitting EU AI Act compliance. Knightscope's proprietary Silicon Valley manufacturing model offers a template for rapid hardware iteration that contract-manufacturing-dependent rivals cannot replicate. Capacity addition in the Yangtze River Delta region would reduce exposure to cross-Pacific logistics chokepoints. For New Entrants and Emerging Players: Build out indoor patrol automation for technology offices where Cobalt Robotics has validated subscription economics but not yet saturated geographic coverage. The most penetrable segment lies in mid-size warehousing operators outside California and Texas who lack capital budgets but face inventory protection mandates. A go-to-market angle through warehouse management system API partnerships accelerates technical validation without requiring direct security industry relationships. For Investors and Strategic Acquirers: Carve-out targets emerge from defense contractors with dormant commercial security divisions and industrial automation incumbents holding underutilized robotics IP. Long-term viability hinges on regulatory pre-certification assets that compound competitive moats across the analysis window. The signal to watch is FAA certification queue depth for aerial platforms, as clearance bottlenecks indicate sustainable pricing power for compliant vendors.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Pre-Certification Investment | Third-party audit trails for algorithmic decision-making unlock German, French, and Dutch government agency procurement. |
| Private 5G Network Partnership | Telecommunications carrier alliances enable encrypted, low-latency communication for defense-adjacent and critical infrastructure sites. |
| Warehouse Management System API Integration | Seamless robot-fleet connectivity with existing automation infrastructure accelerates warehousing operator adoption. |
| Silicon Photonics Lidar Consolidation | Solid-state beam steering eliminates mechanical scanning components, reducing form factor constraints for indoor logistics navigation. |
| Robot-as-a-Service Financing Restructure | Operational expenditure scaling replaces capital budgets, concentrating vendor relationships around uptime guarantees and incident response SLAs. |
Research Methodology
A standing panel of security operations center directors, robotics engineering leads, municipal procurement officers, and warehouse automation managers provided ongoing calibration across the study period. Primary interviews with these stakeholders combined with secondary validation against FAA certification databases, EU AI Act conformity assessment registries, SEC 10-K filings from listed vendors, and smart city infrastructure procurement disclosures. Bottom-up unit deployment estimates triangulated against top-down market sizing from sensor supply chain bill-of-materials analysis.
Scenario-bracketing framed volume and value outputs across the projection horizon, with segmentation dimensions spanning mobility platform architecture, sensing modality configuration, deployment scenario risk classification, and buyer category compliance burden intensity. CAGRs derived from logistic diffusion curves fitted to early-adopter penetration patterns and fleet replacement cycles. Industry-specific forecast inputs included lithium-ion battery cost trajectories and private 5G network deployment timelines.
Sensitivities concentrate around FAA regulatory acceleration or deceleration, EU AI Act enforcement uniformity across member states, and lithium supply contract renegotiations. Forecasts reflect documented assumptions regarding edge-computing processor performance improvements and solid-state lidar manufacturing yield curves. Quarterly review of municipal procurement pipeline depth and warehousing operator automation capex intentions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Global Exoskeleton Market
Robotics and Automation
Modular Robotics Market
Robotics and Automation
Medical Robotics Market
Robotics and Automation
Industrial Robots Market
Robotics and Automation
Healthcare Robots Market
Robotics and Automation
Cognitive Robotics Market
Robotics and Automation
Motion Control Software in Robotics Market
Robotics and Automation
Biaxial Mobile Phone Stabilizer Market
Robotics and Automation
Autonomous Mobile Manipulator Robots (AMMR) Market
Robotics and Automation
Canada Cloud Robotics Market
Robotics and Automation
AGV & AMR in Logistics Market
Robotics and Automation
Self-Driving Floor Scrubbers Market
Robotics and Automation
Asia-Pacific Service Robotics Market
Robotics and Automation
Restaurant Delivery Robot Market
Robotics and Automation
Global Medical Robotic Systems Market
Robotics and Automation
Latin America Cloud Robotics Market