
 Europe Agricultural Robots and Mechatronics Market | 2026-2036
Europe Agricultural Robots and Mechatronics Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Agricultural Robots and Mechatronics Market Foresight
France is reshaping European agricultural robotics capacity through dedicated test zones and public-private innovation clusters around Bordeaux and Toulouse. AGCO Corporation leverages its Fendt brand manufacturing footprint to anchor autonomous guidance systems for arable crop producers. CNH Industrial competes through Raven Industries integration, sustaining precision control technologies across its Case IH and New Holland lineups. DeLaval dominates dairy automation, extending robotic milking installations into mid-sized cooperative farms across Northern Europe.
Agricultural robots and mechatronics encompass electro-mechanical systems integrating sensors, actuators, and control algorithms to perform crop cultivation, animal husbandry, and field management tasks with minimal human intervention. These systems typically operate through GNSS positioning, LiDAR obstacle detection, and hydraulic or electric drive trains rated for continuous outdoor duty cycles exceeding 16 hours. Harvesting robots and autonomous tractors command the largest installed base, though spraying systems incorporating machine learning for weed discrimination represent the fastest-expanding margin pool. Sensor technology and artificial intelligence integration now determine product differentiation, with commercial farms as the primary procurement channel absorbing over half of new unit placements annually.
The EU Green Deal, CE marking requirements under the Machinery Directive, and the F-Gas Regulation collectively mandate emissions reductions and safety certification that filter non-compliant equipment from European market access. EFSA guidelines on pesticide application precision further shape spraying robot validation protocols, while national regulators in Germany and the Netherlands enforce stricter soil compaction standards for autonomous heavy machinery. Stakeholders must monitor how the EU AI Act classification rules will apply to decision-making algorithms in crop treatment robots, as compliance timelines could restructure vendor competitive hierarchies before the forecast horizon closes.
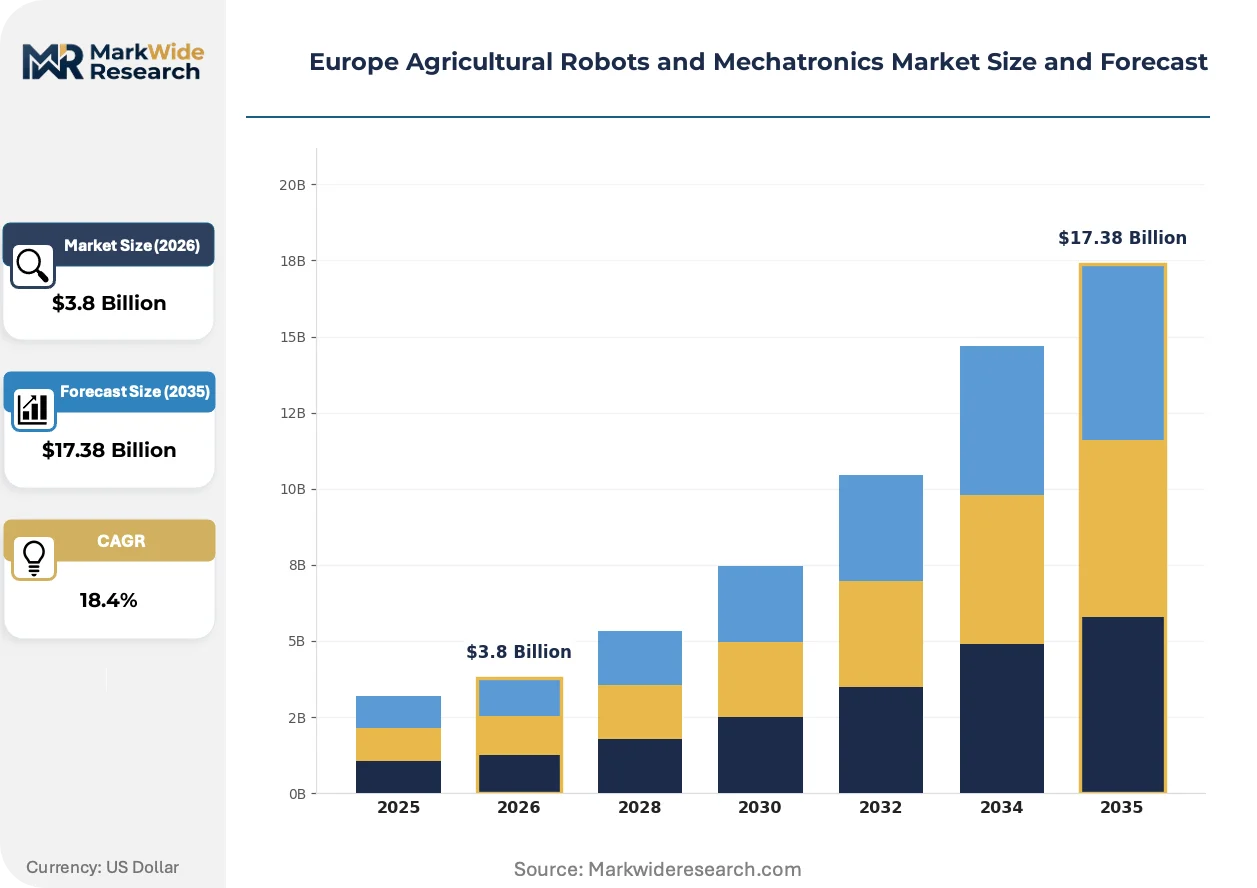
Market Dynamics
Labor scarcity across European viticulture and arable farming is accelerating autonomous fleet deployments, while the EU Green Deal's electrification mandates are restructuring powertrain supply chains toward battery-electric and hydrogen fuel cell architectures.
Growth Catalysts
- CE marking under the Machinery Directive:Harmonized safety certification enables cross-border equipment mobility, reducing vendor compliance duplication across Germany, France, and the Netherlands.
- Greenhouse horticulture in the Netherlands:High-value protected cropping justifies precision robotics investments for crop monitoring, grafting, and selective harvesting in climate-controlled environments.
- LiDAR and computer vision convergence:Sensor fusion for real-time obstacle detection and crop-weed discrimination is expanding autonomous tractor operational envelopes in unstructured vineyard terrain.
Market Restraints
- Lithium-ion battery supply concentration:Cell manufacturing capacity constraints in East Asia create procurement bottlenecks for electric drivetrain modules rated for 16-hour agricultural duty cycles.
- F-Gas Regulation phase-down schedules:Restrictions on hydrofluorocarbon refrigerants complicate thermal management system design for autonomous vehicle electronics enclosures.
- Soil compaction technical thresholds:Germany's KBA and Dutch regulators enforce axle load limits that constrain battery pack sizing for heavy autonomous field machinery.
Strategic Opportunities
- Poland and Romania arable expansion:Large-scale cereal and oilseed operations in these member states remain underpenetrated by autonomous guidance systems relative to Western European adoption rates.
- EU AI Act algorithmic transparency requirements:Early compliance with decision-log documentation standards for crop treatment robots creates vendor differentiation ahead of mandatory classification timelines.
- Robotics-as-a-service distribution:Cooperative purchasing platforms and seasonal leasing models lower capital barriers for mid-sized French and Spanish vineyard operators.
Industry Challenges
- Agricultural mechatronics engineering talent:Cross-disciplinary expertise combining hydraulics, GNSS positioning, and machine learning remains scarce across European technical universities and vocational institutes.
- ISO 12100 machinery safety certification timelines:Extended validation protocols for autonomous decision-making systems delay product launch windows by 12-18 months relative to conventional equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Agricultural Robots and Mechatronics Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.38 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Autonomous Tractors, Harvesting Robots, Seeding Robots, Spraying Systems Application: Crop Management, Soil Analysis, Precision Agriculture, Livestock Feeding Technology: Artificial Intelligence, Machine Learning, Sensor Technology, Automation End User: Commercial Farms, Research Institutions, Agricultural Cooperatives, Government Agencies |
| Companies Covered | AGCO Corporation, CNH Industrial, CLAAS, Lely International, Autonomous Solutions, GEA Group, DeLaval, Trimble, Naïo Technologies, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Agricultural Robots and Mechatronics Market Shifts & Advancements
Electrification and edge computing are converging to redefine machine architecture, while regulatory pressure on chemical inputs is redirecting R&D investment toward precision application technologies.
Electric drivetrains rated for continuous field operation are collapsing the total cost of ownership gap with diesel equivalents in high-utilization scenarios. Dutch greenhouse operators and French cereal cooperatives are specifying battery-electric platforms for tasks exceeding 2,000 annual operating hours. This transition is compressing maintenance revenue pools traditionally captured through engine servicing contracts.
The F-Gas Regulation's refrigerant phase-down is compelling thermal management redesigns for autonomous vehicle electronics. Vendors must substitute heat pump architectures or liquid cooling loops for conventional vapor compression systems. Spraying robot manufacturers face particular exposure, as sealed electronics enclosures in outdoor duty cycles demand reliable temperature control across ambient ranges from -15°C to 45°C.
Cooperative procurement platforms are aggregating demand from mid-sized farms into consolidated equipment orders. French viticulture cooperatives in Bordeaux and Burgundy are negotiating autonomous tractor fleet purchases through shared buying consortia, displacing individual farm capital expenditure decisions. This concentration is visible across Northern European dairy automation, where robotic milking system acquisitions increasingly route through processor-affiliated financing vehicles.
Europe Agricultural Robots and Mechatronics Market Segmentation
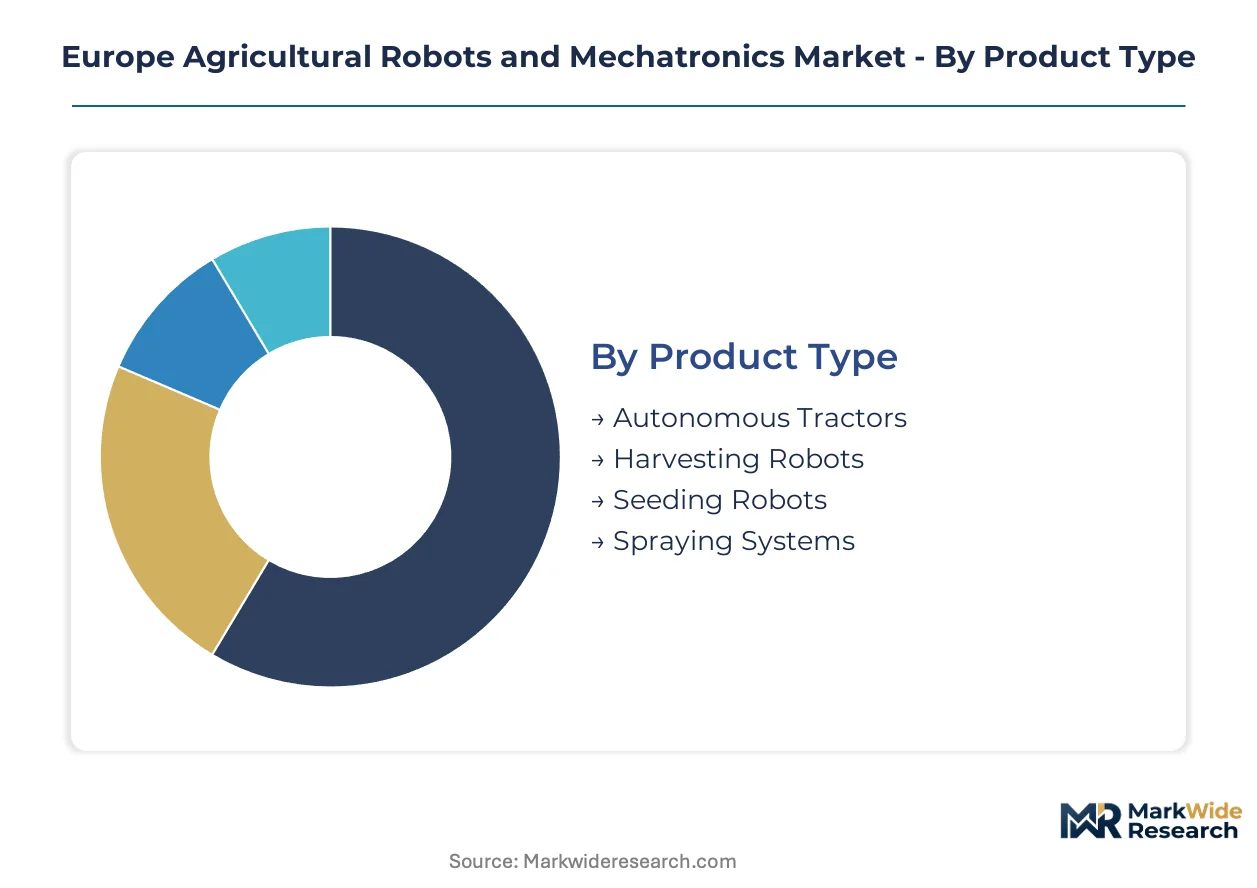
Segmentation in European agricultural robotics reveals how capital intensity, regulatory compliance, and crop-specific labor economics reshape procurement patterns across member states. Understanding these dimensions exposes where electrification mandates and precision agriculture investments concentrate purchasing power.
Product Type:
Use-case spectrum spans heavy field machinery through selective harvesting platforms, with electrification feasibility varying dramatically by duty cycle and payload requirements.
- Autonomous Tractors:GNSS-guided platforms with electro-hydraulic implements rated for 16-hour continuous operation. French cereal cooperatives in Île-de-France and Spanish arable operations in Castilla-La Mancha are consolidating fleet orders through procurement consortia to absorb battery-electric premium pricing.
- Harvesting Robots:Vision-guided manipulator systems with end-effectors calibrated for crop-specific bruise thresholds. Dutch greenhouse tomato operations and Italian fresh-produce cooperatives justify capital deployment where manual labor costs exceed robotic amortization within 36-month payback windows.
- Seeding Robots:Precision planting platforms integrating soil moisture sensors with variable-rate seed metering.
- Spraying Systems:Machine learning-enabled spot-application units discriminating crop from weed canopy in real time.
The dominant share belongs to Autonomous Tractors, while Harvesting Robots is closing the gap fastest.
Application:
Cost-tier stratification separates high-value protected cropping applications from broadacre commodity operations where margin compression constrains technology adoption.
- Crop Management:Integrated platforms combining canopy monitoring, selective pruning, and yield prediction algorithms. Netherlands greenhouse clusters around Westland and Belgian vegetable cooperatives deploy these systems where crop value density exceeds €50 per square meter annually.
- Precision Agriculture:Variable-rate input application guided by real-time soil and plant health mapping. German arable farms in Lower Saxony adopt these technologies to satisfy Fertilizer Ordinance documentation requirements while reducing nitrogen surplus penalties.
- Soil Analysis:Autonomous soil sampling platforms with onboard spectroscopic nutrient detection.
- Livestock Feeding:Robotic feed pushers and automated ration mixing systems for dairy operations.
Crop Management commands the largest installed base, yet Precision Agriculture is expanding most quickly under regulatory compliance pressure.
Technology:
Volume concentration in sensor hardware reflects the foundational requirement for environmental perception across all autonomous agricultural platforms.
- Sensor Technology:LiDAR, multispectral cameras, and soil moisture probes forming the perceptual layer for autonomous decision-making. French vineyard robotics developers around Bordeaux prioritize solid-state LiDAR for dust-resistant obstacle detection in unstructured terrain.
- Artificial Intelligence:Edge-deployed neural networks for real-time crop-weed classification and path planning. Dutch agricultural technology clusters integrate these capabilities to meet EU AI Act transparency requirements ahead of mandatory classification timelines.
- Machine Learning:Supervised learning pipelines trained on annotated crop damage datasets for predictive maintenance.
- Automation:Electro-mechanical control systems executing pre-programmed motion sequences without adaptive decision-making.
Sensor Technology anchors current procurement volumes, though Artificial Intelligence is gaining share fastest as algorithmic transparency standards mature.
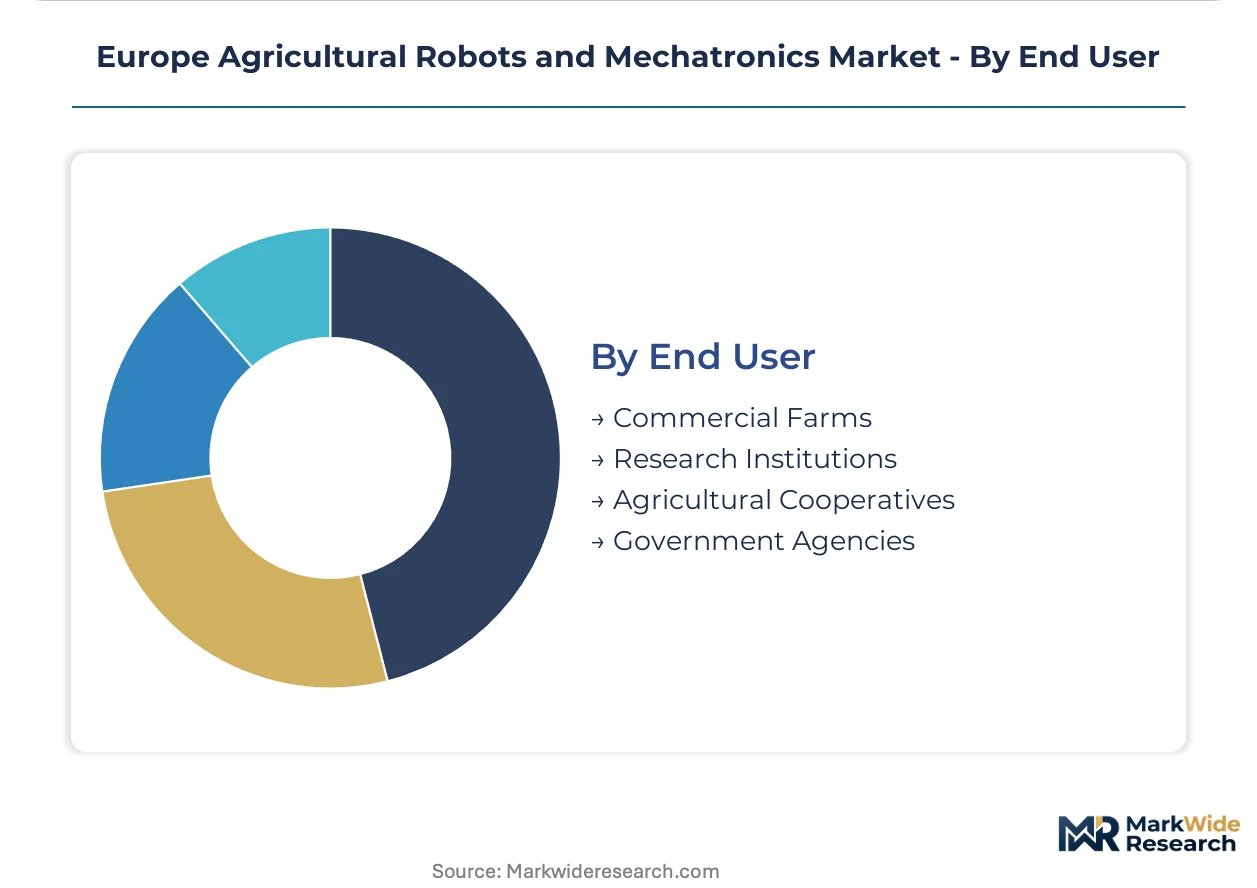
End User:
Customer-type differentiation reflects capital access disparity between consolidated commercial operations and fragmented cooperative structures.
- Commercial Farms:Privately held enterprises with balance sheet capacity for direct equipment acquisition and dedicated technical staff. Large cereal operations in Denmark and Poland deploy autonomous fleets exceeding 10 units to capture scale economies in precision input application.
- Agricultural Cooperatives:Member-owned purchasing consortia aggregating demand across mid-sized holdings. French viticulture cooperatives in Burgundy negotiate shared autonomous tractor fleets, distributing capital burden through seasonal usage scheduling.
- Research Institutions:University agricultural faculties and applied research stations validating robotic systems under controlled conditions.
- Government Agencies:National agricultural ministries and regional development authorities funding demonstration projects.
Commercial Farms retain the dominant procurement position, while Agricultural Cooperatives is climbing the fastest as shared-ownership models proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Scheldt-Meuse delta port complex anchors European agricultural robotics distribution, channeling precision components from Eindhoven and Rotterdam into assembly facilities across the Low Countries and northern France.
Germany
Lower Saxony's arable belt and Bavarian dairy cooperatives drive autonomous tractor procurement, with the KBA enforcing axle load limits that constrain battery sizing for heavy field machinery. The EU Green Deal's electrification mandates intersect with national Fertilizer Ordinance documentation requirements, pushing precision agriculture adoption. Stuttgart's industrial automation cluster hosts drivetrain engineering centers developing electric powertrains rated for continuous agricultural duty cycles.
Netherlands
Westland greenhouse horticulture justifies capital-intensive robotics where crop value density exceeds €50 per square meter annually, while the F-Gas Regulation accelerates thermal management redesigns for autonomous vehicle electronics. Eindhoven's high-tech systems sector supplies LiDAR and sensor fusion components to vineyard robotics developers. Wageningen University's research corridor validates machine learning algorithms for crop-weed discrimination ahead of EU AI Act implementation timelines.
France
Bordeaux and Burgundy viticulture cooperatives consolidate autonomous tractor orders through shared procurement consortia to absorb battery-electric premium pricing. The country's national agricultural regulator enforces CE marking compliance under the Machinery Directive, filtering non-compliant equipment from market access. Toulouse's aerospace engineering heritage migrates into agricultural mechatronics through public-private innovation clusters testing solid-state LiDAR in unstructured vineyard terrain.
Spain
Castilla-La Mancha arable operations and Catalan greenhouse complexes expand autonomous fleet deployments to address chronic seasonal labor shortages in fruit harvesting. EFSA guidelines on pesticide application precision shape spraying robot validation protocols for Spanish fresh-produce exporters. Valencia's automation engineering sector develops edge-computing architectures for real-time crop monitoring in protected cropping environments.
Italy
Emilia-Romagna fresh-produce cooperatives and Lombardy cereal operations deploy precision agriculture technologies where manual labor costs exceed robotic amortization within 36-month payback windows. The EU AI Act's algorithmic transparency requirements are prompting early compliance investments among Italian agricultural technology developers. Bologna's industrial automation corridor integrates computer vision systems for selective harvesting platforms serving Mediterranean specialty crop producers.
Europe Agricultural Robots and Mechatronics Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying sensor modules, electric drivetrains, and control algorithms. The European agricultural robotics sector exhibits tiered consolidation, with established agricultural machinery conglomerates anchoring volume production while specialized robotics ventures capture niche applications. Three archetypes dominate: legacy equipment manufacturers retooling for electrification, precision agriculture technology pure-plays, and dairy automation specialists extending into adjacent livestock segments. Competitive dynamics center on strategic partnerships for battery supply security and acquisitions of machine learning competencies for crop-weed discrimination.
Among Netherlands-based dairy automation specialists, Lely International and DeLaval exemplify the livestock-focused archetype, while France's Naïo Technologies represents the vineyard robotics pure-play segment. These entities occupy distinct competitive positions without overlapping core application domains, reflecting how crop-specific labor economics and terrain constraints fragment addressable markets across European agricultural systems.
| Leading Market Players |
|---|
| AGCO Corporation |
| CNH Industrial |
| CLAAS |
| Lely International |
| Autonomous Solutions |
| GEA Group |
| DeLaval |
| Trimble |
| Naïo Technologies |
| Others |
Supply & Pricing Matrix
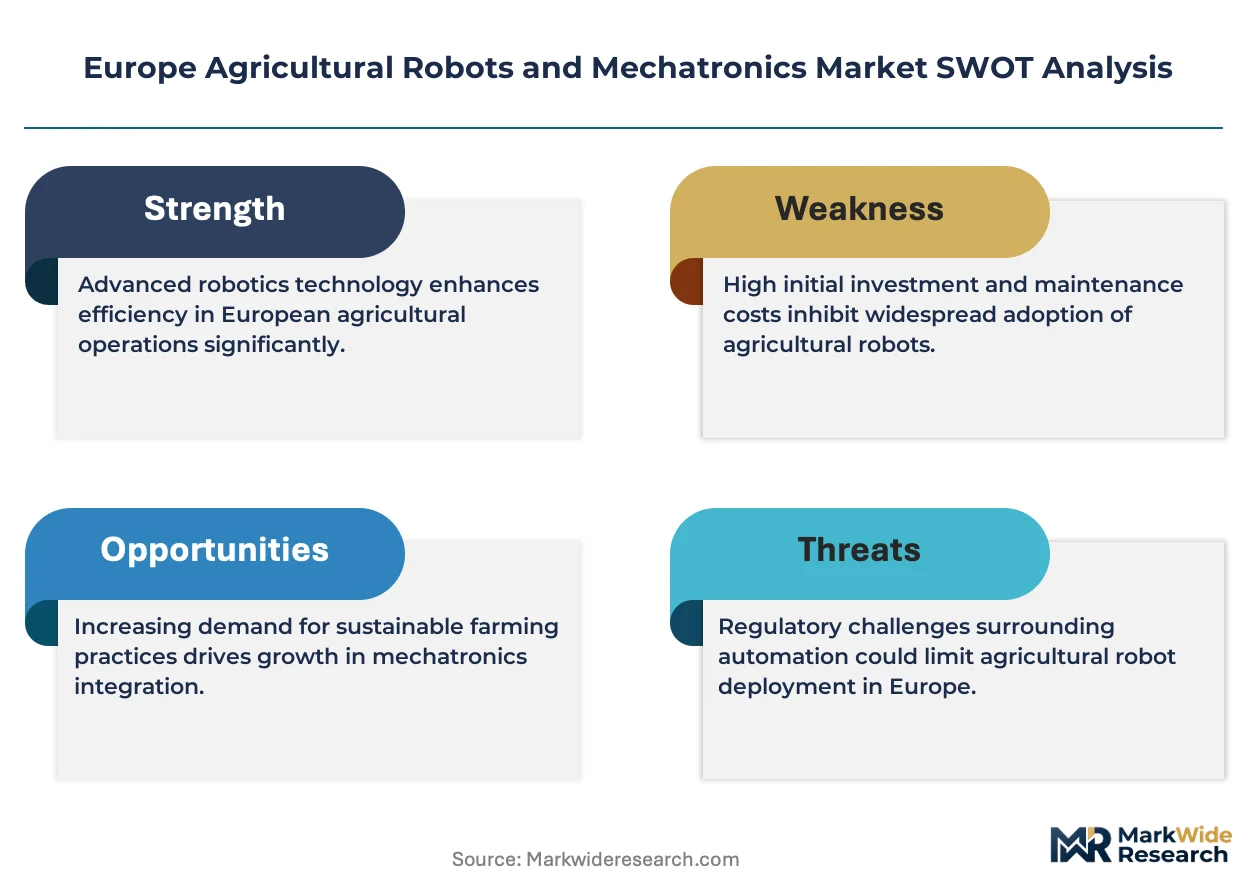
Lithium-ion cell supply concentration in East Asia creates procurement bottlenecks that determine both pricing tier spreads and supply chain shape across European agricultural robotics manufacturing. Battery pack cost differentials between premium solid-state configurations and standard cylindrical cell architectures now exceed the margin thresholds that separate cooperative buyers from commercial farm direct purchasers.
Pricing Analysis
Volume-discount tiering structures dominate procurement negotiations, with French cereal cooperatives and Dutch greenhouse consortia capturing 15-20% unit cost reductions through consolidated fleet orders above ten units. Price differentiation rests on battery chemistry grade and CE marking certification tier, with automotive-grade cell suppliers commanding premiums over consumer-electronics sourced alternatives. Cost compression in mid-tier autonomous tractors is intensifying because German KBA axle load regulations constrain battery pack sizing, forcing vendors to absorb thermal management redesign expenses. Cooperative buyers exhibit highest price sensitivity, while large commercial operations prioritize performance specifications over capital outlay minimization.
Supply Chain Analysis
Extended payment terms from East Asian cell manufacturers now stretch to 120 days for European agricultural robotics assemblers, compressing working capital cycles throughout the tier. Geographic supply concentration centers on China, South Korea, and Japan for lithium-ion cells, with Germany and the Netherlands hosting final assembly and sensor integration. Raw material dependencies include lithium carbonate, nickel sulfate, and rare-earth permanent magnets for electric drivetrains. Single-source vulnerability in solid-state LiDAR modules from specific Eindhoven-based suppliers creates chokepoint exposure. Distribution runs through Rotterdam port logistics clusters into regional equipment dealer networks serving Île-de-France and Lower Saxony farming belts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern competitive advantage as interoperability standards for autonomous fleet management systems consolidate purchasing power among cooperative buyers. The ISO 11783 communications protocol shift toward plug-and-play implement compatibility represents the decisive ecosystem inflection.
For Market Incumbents: Pre-empt cooperative procurement platform aggregation by embedding proprietary fleet management software into hardware sales, neutralizing the threat of third-party robotics-as-a-service intermediaries. Anchor battery supply security through offtake agreements with South Korean cell manufacturers, securing capacity ahead of EU Green Deal electrification mandates. Prioritize CE marking pre-certification under evolving EU AI Act algorithmic transparency requirements to filter non-compliant emerging competitors from tender processes. For New Entrants and Emerging Players: Mid-sized vineyard operations in Spain's Castilla-La Mancha region represent the most penetrable entry point, where labor shortage severity exceeds autonomous guidance system penetration rates. Polish arable cooperatives running cereal operations above 500 hectares offer second-mover advantage in precision agriculture retrofit kits. Establish go-to-market positioning through seasonal leasing models rather than capital sales, aligning revenue recognition with harvest cash flow cycles of target buyers. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors precision agriculture technology pure-plays with validated crop-weed discrimination algorithms. Long-term viability over the next decade hinges on regulatory compliance moats rather than hardware cost curves. Target acquisition archetypes include Dutch sensor fusion specialists and French vineyard robotics developers with established CE marking pathways. Monitor EU AI Act implementation timelines as the critical inflection signal for vendor competitive hierarchy restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Locks cell capacity from South Korean manufacturers ahead of EU electrification mandates. |
| CE Marking Pre-Certification | Accelerates EU AI Act compliance timelines for algorithmic transparency in crop treatment robots. |
| Robotics-as-a-Service Platform | Aggregates cooperative demand through seasonal leasing models in French viticulture regions. |
| Sensor Fusion Acquisition | Integrates solid-state LiDAR capabilities for dust-resistant vineyard obstacle detection. |
| Thermal Management Redesign | Substitutes heat pump architectures for F-Gas Regulation compliance in electronics enclosures. |
Research Methodology
A spread of perspectives from agricultural robotics engineering directors, cooperative procurement managers, CE marking compliance consultants, and precision agriculture technology developers converged on the working assumptions underlying demand quantification. Primary field engagement combined structured interviews with secondary validation against EU regulatory filings, Machinery Directive technical documentation, and customs records for agricultural equipment imports. Bottom-up unit shipment estimates from French and German dealer networks were triangulated against top-down addressable market calculations based on arable land under autonomous cultivation.
Demand-supply-balance framing anchored the analytical approach across the projection horizon, with segmentation modeling spanning product type, application intensity, technology maturity tier, and end-user capital access. CAGRs were derived from fitted growth curves calibrated to electrification mandate implementation schedules and labor cost inflation trajectories. Industry-specific forecast inputs included F-Gas Regulation phase-down compliance costs and EU AI Act algorithmic documentation requirements.
Macroeconomic conditions sit as an overlay; deviation in agricultural commodity prices, interest rate environments affecting cooperative financing capacity, or lithium supply disruption would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory implementation timelines and technology cost curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Exoskeleton Systems Market
Robotics and Automation
Social Robots Market
Robotics and Automation
Smart Machines Market
Robotics and Automation
Telepresence Robot Market
Robotics and Automation
Autonomous Robot Market
Robotics and Automation
Micro Robots Market
Robotics and Automation
Laboratory Robotics Market
Robotics and Automation
Global Robotic Grippers Market
Robotics and Automation
Cleaning Robot Market
Robotics and Automation
Asia Pacific Industrial Robots Market
Robotics and Automation
Delta Robots Market
Robotics and Automation
Robotic Welding Market
Robotics and Automation
Gimbal Stabilizers Market
Robotics and Automation
Global Agriculture Robots Market
Robotics and Automation
Logistics Robotics Market
Robotics and Automation
Latin America Cloud Robotics Market