
 China Autonomous Mobile Robot Market | 2026-2036
China Autonomous Mobile Robot Market Size, Share, and Industry Trends Forecast 2026-2036
China Autonomous Mobile Robot Market Insights
Industrial-grade SLAM precision is unwinding legacy navigation limitations across China's AMR sector. Geek+ leverages its Beijing manufacturing base to sustain high-volume warehouse automation contracts. Hai Robotics differentiates through its proprietary container-handling architecture for dense storage environments.
Autonomous mobile robots integrate sensors, actuators, and onboard computing to execute material transport without fixed infrastructure, typically achieving positioning accuracy within millimeters through fused LIDAR-visual odometry. Their primary purpose centers on eliminating human transit time in repetitive logistics loops. Delivery robots and cleaning robots capture divergent margin structures, with the former commanding premium pricing from e-commerce fulfillment networks while the latter scales through municipal service contracts. Visual navigation and AI-based Control segments are pulling R&D investment away from legacy magnetic-tape dependencies.
MIIT, SAMR, and GB standard committees collectively shape product compliance pathways, with MIIT's robotics industry development plans directly channeling subsidy eligibility toward domestically certified platforms. The country's national standardization regulator continuously tightens electromagnetic compatibility and safety interlock requirements, forcing firmware upgrades across installed bases. Stakeholders must track which certification tier unlocks public-sector procurement eligibility versus private logistics contracts.
Market Dynamics
MIIT's intelligent manufacturing directives are compressing product certification timelines while warehouse operators across Guangdong Province accelerate procurement to address acute labor shortages. This regulatory acceleration is restructuring competitive entry barriers.
Growth Catalysts
- GB Standards Modernization:SAMR's upgraded electromagnetic compatibility requirements are shortening firmware validation cycles for domestically certified platforms, unlocking public-sector procurement eligibility.
- Container-Handling Architecture:Dense storage environments in Yangtze River Delta fulfillment centers are driving demand for proprietary vertical-lifting AMR configurations.
- Guangdong Labor Shortages:Warehouse operators facing acute workforce gaps are automating repetitive logistics loops through delivery robot deployment at scale.
Market Restraints
- High-Precision Sensor Costs:Fused LIDAR-visual odometry systems carry premium input costs that compress margins in municipal cleaning robot contracts.
- Subsidized Domestic Concentration:MIIT subsidy eligibility channels toward domestically certified platforms, limiting foreign vendor participation in tier-one deployments.
- Magnetic-Tape Legacy Inertia:Installed warehouse automation bases retain tape-dependent navigation, creating technical friction during SLAM migration.
Strategic Opportunities
- AI-Based Control Convergence:Visual navigation systems integrating edge-computing inference are opening white space in dynamic obstacle-avoidance applications.
- Shenzhen Testing Clusters:The city's concentrated R&D infrastructure enables rapid prototype-to-deployment pipelines for emerging AMR form factors.
- Municipal Service Contracts:Cleaning robot procurement through city-level maintenance budgets represents underpenetrated recurring revenue streams outside e-commerce fulfillment.
Industry Challenges
- Certification Timeline Compression:GB standard committees' continuous safety interlock updates force firmware upgrades across installed bases, straining engineering bandwidth.
- SLAM Integration Complexity:Millimeter-grade positioning accuracy requirements create friction when retrofitting legacy warehouse management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Autonomous Mobile Robot Market |
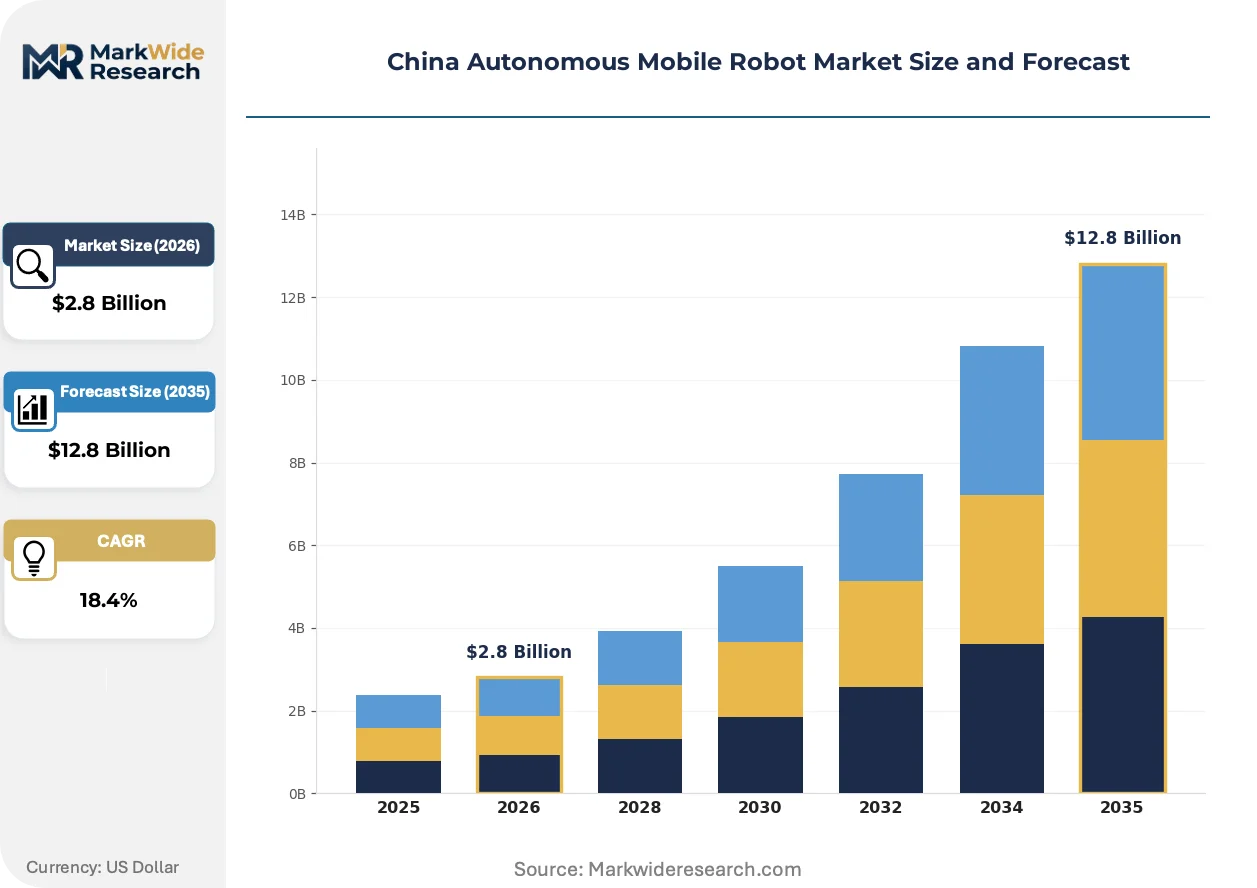
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $12.8 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Utility Robots, Delivery Robots, Surveillance Robots, Cleaning Robots End User: Healthcare Facilities, Warehouses, Retail Stores, Manufacturing Plants Technology: Visual Navigation, LIDAR, SLAM, AI-based Control Application: Logistics, Emergency Response, Surveillance, Cleaning |
| Companies Covered | Unitree Robotics, Quicktron, Hai Robotics, Enovix Robotics, Vector Robotics, Geek+, UBTECH Robotics, Seer Robotics, Fdata Robot, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Autonomous Mobile Robot Market Trends and Innovations
Industrial-grade SLAM precision is actively unwinding legacy navigation dependencies across China's AMR sector. Three concurrent developments are reshaping competitive positioning and procurement patterns.
Fused LIDAR-visual odometry is supplanting magnetic-tape guidance in high-throughput fulfillment environments. E-commerce operators in Shenzhen and Shanghai are adopting these systems within compressed validation windows. The technology is enabling dynamic path replanning that eliminates fixed infrastructure installation costs.
MIIT's robotics industry development plans are channeling subsidy eligibility toward platforms meeting upgraded electromagnetic compatibility thresholds. Domestic vendors are reconfiguring supply chains to capture this regulatory tailwind. The policy most directly affects mid-cap manufacturers seeking public-sector cleaning robot contracts.
Outcome-based maintenance agreements are displacing capital-intensive equipment purchases among Yangtze River Delta warehouse operators. Third-party logistics providers now prefer per-pick pricing models that transfer utilization risk to AMR vendors. This shift is most visible in Guangdong Province's contract fulfillment networks.
China Autonomous Mobile Robot Market Segmentation
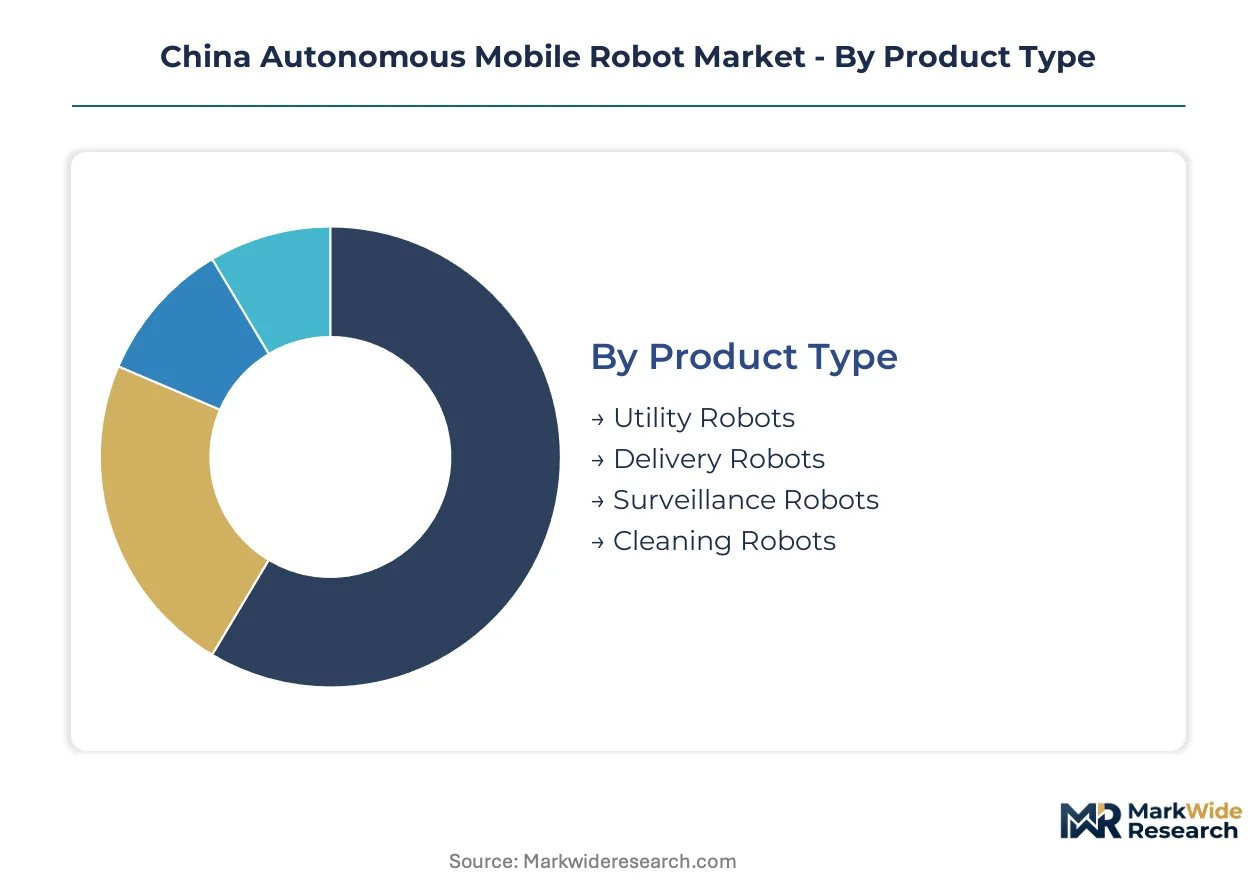
Segmentation reveals where procurement budgets concentrate across China's AMR landscape. Product type and technology choices determine subsidy eligibility under MIIT directives, while end-user selection dictates whether vendors pursue public-sector certification or private logistics contracts.
Product Type:
Delivery robots face the most acute substitution pressure from manual warehouse labor, while cleaning robots confront municipal budget constraints and legacy service provider incumbency.
- Utility Robots:Multi-function platforms integrate modular payloads for material handling, environmental sensing, and facility maintenance within single chassis architectures. Guangdong Province warehouse operators deploy these for flexible task reassignment during seasonal demand spikes. MIIT intelligent manufacturing directives favor their domestic certification pathways.
- Delivery Robots:Purpose-built units achieve millimeter-grade positioning through fused LIDAR-visual odometry in high-throughput fulfillment loops. Yangtze River Delta e-commerce networks command premium pricing for these systems, compressing validation windows through Shenzhen testing clusters.
- Surveillance Robots:Patrol platforms combine thermal imaging with autonomous routing for perimeter security applications.
- Cleaning Robots:Scrubber-dryer and vacuum configurations scale through municipal service contracts, though sensor costs compress margins outside premium commercial deployments.
Delivery robots retain volume leadership; utility robots hold the steepest expansion curve.
End User:
Cost tier stratification separates capital-intensive manufacturing deployments from operational-expense-driven municipal and retail procurement.
- Healthcare Facilities:Sterile-environment AMRs transport pharmaceuticals and linen through HEPA-filtered corridors with contamination-avoidance protocols. Shanghai hospital networks specify electromagnetic compatibility certification under upgraded GB standards for patient-safety critical applications.
- Warehouses:Dense storage environments in Shenzhen and Shanghai fulfillment centers drive demand for vertical-lifting configurations that maximize cubic utilization. Outcome-based maintenance agreements are displacing capital purchases among third-party logistics providers.
- Retail Stores:Inventory-scanning and customer-assistance units navigate dynamic floor plans with edge-computing obstacle avoidance.
- Manufacturing Plants:Heavy-payload AMRs integrate with production scheduling systems for just-in-time component delivery to assembly lines.
Warehouses dominate current procurement volume; healthcare facilities are climbing the fastest as GB certification timelines compress.
Technology:
Application maturity separates navigation systems with proven SLAM deployment from emerging AI-based control architectures still in prototype-to-deployment pipelines.
- Visual Navigation:Camera-array systems process fiducial markers and natural feature recognition for cost-sensitive indoor applications. Retail and cleaning robot vendors favor these for margin preservation in municipal contract bidding.
- LIDAR:Laser-ranging sensors generate dense point clouds for centimeter-grade localization in dynamic obstacle environments. Yangtze River Delta warehouse operators specify these for collision avoidance in human-robot collaborative zones.
- SLAM:Simultaneous localization and mapping algorithms eliminate fixed infrastructure dependencies through real-time environment reconstruction.
- AI-based Control:Deep-learning inference engines enable predictive path planning and anomaly detection at the network edge.
LIDAR retains installed-base dominance; AI-based Control is gaining share fastest through Shenzhen R&D cluster outputs.
Application:
Geographic concentration within China separates logistics demand anchored in coastal fulfillment hubs from surveillance and emergency response procurement distributed across interior provincial capitals.
- Logistics:Material transport applications eliminate human transit time in repetitive pick-and-place loops across Guangdong Province warehouse networks. MIIT subsidy eligibility channels toward domestically certified platforms in this segment.
- Emergency Response:Hazardous-environment reconnaissance units deploy chemical sensors and thermal imaging for disaster site assessment. Procurement concentrates through provincial emergency management bureaus with distinct certification requirements from commercial logistics.
- Surveillance:Perimeter patrol and crowd-monitoring functions integrate with existing security infrastructure.
- Cleaning:Automated scrubbing and vacuuming operations scale through city-level maintenance budgets as recurring revenue streams outside e-commerce fulfillment cycles.
Logistics commands current revenue concentration; emergency response shows the steepest trajectory as provincial safety budgets expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's AMR sector exhibits pronounced coastal-inland asymmetry, with import dependency concentrated in high-precision sensor components while domestic assembly and software integration dominate export volumes. The Yangtze River Delta and Pearl River Delta function as dual export engines, shipping finished systems to Southeast Asian logistics networks.
Yangtze River Delta
Suzhou and Shanghai warehouse operators deploy vertical-lifting AMRs for dense storage fulfillment under compressed validation timelines. MIIT intelligent manufacturing directives channel subsidy eligibility toward domestically certified platforms in this corridor. The region's concentrated R&D infrastructure enables rapid prototype-to-deployment pipelines for emerging form factors.
Pearl River Delta
Guangdong Province faces acute warehouse labor shortages, accelerating delivery robot procurement at scale across Shenzhen and Dongguan fulfillment centers. SAMR's upgraded electromagnetic compatibility requirements shorten firmware validation cycles for platforms seeking public-sector eligibility. Local testing clusters compress product certification timelines through concentrated technical infrastructure.
Beijing-Tianjin-Hebei
Healthcare facility networks in Beijing specify HEPA-filtered AMR configurations for pharmaceutical transport with contamination-avoidance protocols. GB standard committees continuously tighten safety interlock requirements, forcing firmware upgrades across installed hospital bases. The capital's regulatory proximity shapes national compliance pathway precedents.
Sichuan-Chongqing
Emergency response procurement through provincial safety budgets drives hazardous-environment reconnaissance unit deployment in Chengdu. Distinct certification requirements from commercial logistics create specialized vendor qualification pathways. The western hub functions as interior distribution anchor for systems assembled on the coast.
China Autonomous Mobile Robot Market Competitive Landscape
Concentration sits with integrated hardware-software vendors possessing domestic certification pathways under MIIT directives. The vendor base stratifies across three tiers: Beijing-headquartered platforms with manufacturing scale, Shenzhen-based specialists in dense storage configurations, and municipal-service-focused cleaning robot providers. Strategic moves center on backward integration into sensor supply chains and outcome-based maintenance agreement structures that transfer utilization risk.
Within the integrated-platform tier, Geek+ and Hai Robotics occupy positions exemplifying divergent specialization vectors. Quicktron and Seer Robotics represent the mid-cap manufacturing segment pursuing public-sector eligibility through accelerated GB compliance. Unitree Robotics anchors the mobility-focused archetype with quadruped-adjacent navigation expertise. UBTECH Robotics sits within the humanoid-interaction extension space, leveraging consumer electronics supply chain relationships.
| Leading Market Players |
|---|
| Unitree Robotics |
| Quicktron |
| Hai Robotics |
| Enovix Robotics |
| Vector Robotics |
| Geek+ |
| UBTECH Robotics |
| Seer Robotics |
| Fdata Robot |
| Others |
Pricing and Supply Chain Analysis
Outcome-based maintenance agreements lock in multi-year utilization commitments between Yangtze River Delta warehouse operators and AMR vendors, binding price visibility to guaranteed uptime performance while securing priority access to firmware upgrade pipelines under MIIT certification timelines.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in China's AMR sector. Price differentiation separates domestically certified platforms eligible for MIIT subsidies from uncertified imports and legacy magnetic-tape retrofits. Cost compression in municipal cleaning robot contracts is intensifying because fused LIDAR-visual odometry sensors carry premium input costs. Third-party logistics providers show highest price sensitivity through per-pick pricing demands, while healthcare facilities demonstrate lowest sensitivity due to patient-safety critical specifications.
Supply Chain Analysis
Strategic stockpile preferences dominate high-precision sensor procurement as warehouse operators buffer against GB standard committee firmware validation delays. Component supply concentrates in Japan, South Korea, and Germany for LIDAR emitters, visual odometry chipsets, and electromagnetic compatibility testing equipment. Raw material dependencies span rare-earth magnets for actuator motors, high-purity silicon for edge-computing inference engines, and specialized optical glass for camera arrays. Single-source vulnerability in LIDAR emitter supply creates exposure to export control fluctuations. Distribution runs through Shenzhen and Shanghai testing clusters before inland deployment to Sichuan-Chongqing emergency response networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's AMR sector operates as a regulatory entrenchment story where MIIT certification pathways and GB standard compliance create switching costs that cement incumbent positions across public-sector procurement channels.
For Market Incumbents: Secure backward integration into LIDAR and visual odometry sensor supply chains to defend margin position against high-precision input cost inflation. Expand firmware engineering capacity in Beijing-Tianjin-Hebei to absorb GB safety interlock update cycles without deployment delays. Certification investment remains the critical lever as SAMR continuously tightens electromagnetic compatibility thresholds. For New Entrants and Emerging Players: Municipal service contract white space in interior provincial capitals offers lowest competitive density as incumbents concentrate on Yangtze River Delta fulfillment networks. Cleaning robot deployment through city-level maintenance budgets represents the most penetrable segment given compressed margins that deter scaled platform vendors. Outcome-based maintenance partnerships with under-capitalized city service departments provide the strongest go-to-market angle. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vendors offering firmware-subscription bundles tied to continuous GB compliance updates. Long-term viability across the projection horizon rests on regulatory entrenchment depth rather than hardware differentiation alone. Acquisition targets should display concentrated MIIT subsidy eligibility and installed bases in healthcare or emergency response applications. Watch for inflection when provincial safety budget expansion accelerates hazardous-environment reconnaissance unit procurement beyond current coastal concentration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Supply | Captive LIDAR sourcing insulates margin from Japan-South Korea export volatility. |
| GB Certification Fast-Track Investment | Accelerated SAMR electromagnetic compatibility approval unlocks public-sector eligibility. |
| Outcome-Based Maintenance Launch | Per-pick pricing transfers utilization risk to vendors while locking in Yangtze Delta warehouse volume. |
| Shenzhen R&D Cluster Expansion | Proximity to concentrated testing infrastructure compresses prototype-to-deployment timelines. |
| Municipal Service Contract Vertical | City-level cleaning robot procurement builds recurring revenue outside e-commerce fulfillment cycles. |
Research Methodology
A spread of perspectives from warehouse operations directors, MIIT policy researchers, GB standard committee technical leads, and third-party logistics procurement managers converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation against SAMR regulatory filings, MIIT intelligent manufacturing directive texts, customs trade data for high-precision sensor imports, and Shenzhen testing cluster disclosure records. Bottom-up unit economics from individual deployment contracts triangulated against top-down sector sizing from provincial automation budget allocations.
Segmentation dimensions modeled span product type, end-user vertical, navigation technology architecture, and application function across the projection horizon. CAGRs were derived from installed base growth trajectories, replacement cycle compression, and subsidy eligibility expansion rather than simple linear extrapolation. Forecast inputs incorporated MIIT robotics industry development plan funding trajectories and GB standard committee publication schedules for electromagnetic compatibility and safety interlock requirements.
Underlying assumptions cover continuous MIIT subsidy channeling toward domestically certified platforms, with deviation risk concentrated in abrupt SAMR regulatory timeline acceleration or export control tightening on LIDAR emitters. Forecasts reflect these conditions holding within historical variance bands. Revision becomes warranted when provincial safety budget expansion crosses thresholds that reallocate procurement concentration from logistics to emergency response applications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Aerospace Service Robotics Market
Robotics and Automation
Global Robotic Process Automation in Healthcare Market
Robotics and Automation
Robotics Software Platforms Market
Robotics and Automation
Hospitality Robots Market
Robotics and Automation
Middle East Cloud Robotics Market
Robotics and Automation
Deep Sea Robot Market
Robotics and Automation
Asia-Pacific AUV and ROV Market
Robotics and Automation
SCARA Robots Market
Robotics and Automation
Healthcare Assistive Robot Market
Robotics and Automation
Autonomous Mobile Manipulator Robots (AMMR) Market
Robotics and Automation
Underwater Exploration Robots Market
Robotics and Automation
Cybersecurity in Robotics Market
Robotics and Automation
Pharmaceutical Collaborative Robots Market
Robotics and Automation
Mobile Robotics Software Market
Robotics and Automation
Automated Liquid Handling Technologies Market
Robotics and Automation
Autonomous Security Robots Market