
 Dispensing Robots Market | 2026-2036
Dispensing Robots Market Size, Share, and Industry Trends Forecast 2026-2036
Dispensing Robots Market Outlook
The capital-intensity divergence between precision-engineering specialists and assembly-integrators is reorganizing competitive tiers in dispensing automation. ABB leverages its servo-motion heritage to dominate high-throughput pharmaceutical lines. Yaskawa Electric Corporation anchors Asian manufacturing demand with localized production networks. Nordson Corporation differentiates through fluid-dispensing expertise that extends into semiconductor packaging applications.
Dispensing robots are programmable articulated systems that apply adhesives, sealants, medications, or coatings with positional accuracy measured in microns, typically operating at repeatability tolerances below 0.1 millimeter for critical dosing applications. Their primary purpose is eliminating human variability in volume-critical processes across regulated industries. Robotic arms command the largest installed base due to established integration protocols, while collaborative robots represent the fastest-expanding category as safety-certified force-limiting designs penetrate mid-volume electronics and cosmetics assembly. Vision Systems technology concentrates margin pools where real-time defect rejection justifies premium system pricing.
FDA cGMP requirements and EMA Annex 1 sterile manufacturing guidelines compel pharmaceutical adopters to validate dispensing traceability down to individual dose records. EPA VOC emission rules and REACH substance restrictions reshape adhesive and coating formulations, forcing robot OEMs to recalibrate dispensing parameters for reformulated chemistries. Stakeholders must monitor how EU AI Act risk-classification thresholds affect machine-learning dispensing optimization in European healthcare deployments.
Market Dynamics
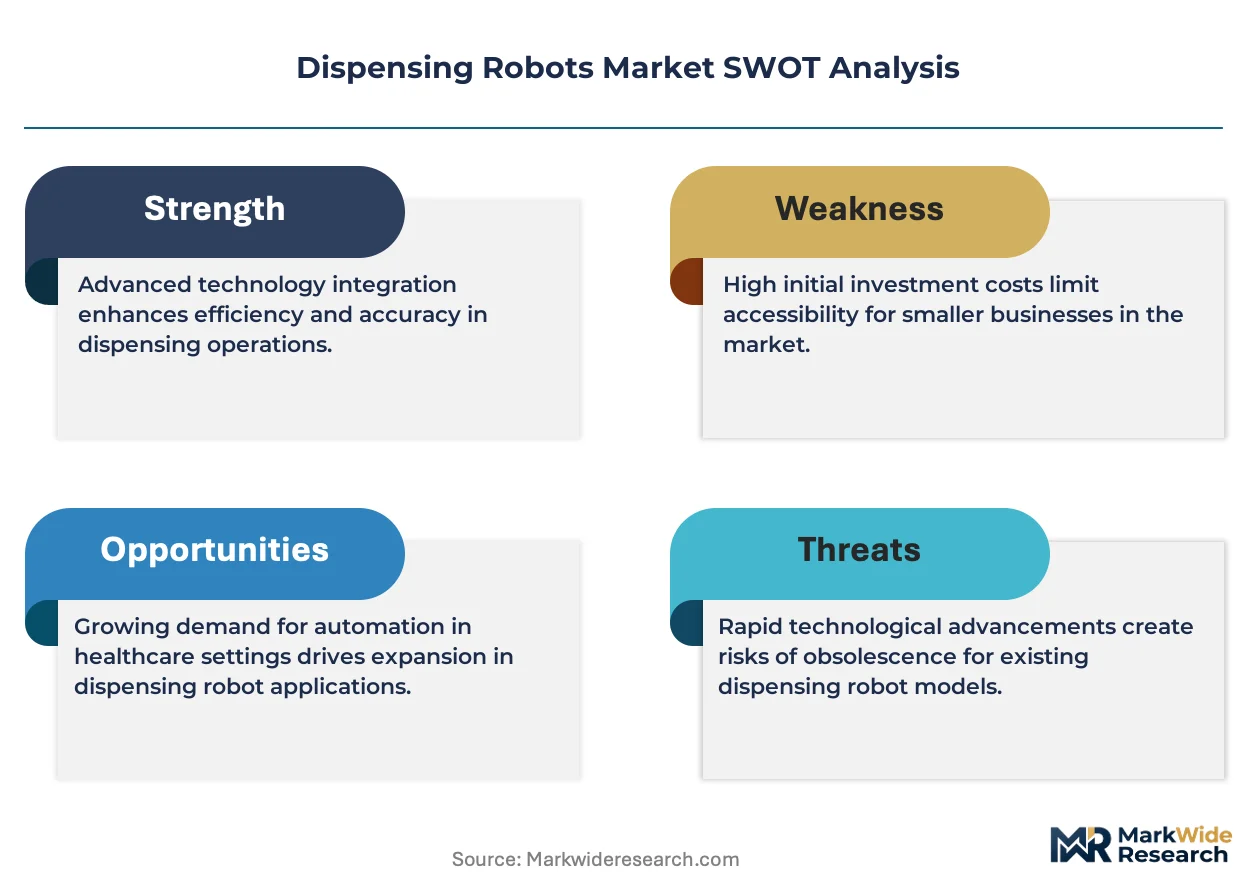
Precision-engineering capability scarcity is compressing competitive tiers, as pharmaceutical traceability mandates under FDA cGMP and EMA Annex 1 sterilize manufacturing guidelines force adopters toward validated robotic dosing systems with micron-level repeatability.
Growth Catalysts
- FDA cGMP traceability mandates:Pharmaceutical manufacturers must validate individual dose records, compelling line upgrades to servo-driven dispensing robots with embedded vision verification.
- Semiconductor packaging demand:Advanced packaging architectures require fluid-dispensing accuracy below 50 microns for underfill and encapsulation processes.
- Germany's automation corridor:Automotive-tier precision engineering capabilities transfer directly into medical device and electronics dispensing applications, concentrating technical talent pools.
Market Restraints
- Specialized servo motor supply concentration:High-precision harmonic drives and direct-drive motors concentrate among Japanese and German component specialists, creating input bottlenecks.
- EPA VOC emission compliance costs:Reformulated adhesive and coating chemistries require extensive robot parameter recalibration, extending validation timelines.
- Collaborative robot force-limiting constraints:Safety-certified designs sacrifice payload and speed, limiting penetration in high-throughput pharmaceutical lines.
Strategic Opportunities
- EU AI Act risk-classification thresholds:Machine-learning dispensing optimization in European healthcare deployments faces lighter compliance burdens at lower risk tiers, enabling algorithmic adoption.
- Cosmetics assembly automation:Mid-volume personal care manufacturers seek collaborative robot solutions for batch-flexible filling and capping operations.
- Vision-guided defect rejection convergence:Real-time spectral imaging integrated with robotic dispensing creates premium system pricing power in semiconductor and medical device packaging.
Industry Challenges
- Multi-axis calibration expertise scarcity:Pharmaceutical and semiconductor fabs struggle to source technicians capable of maintaining sub-100-micron repeatability across six-degree-of-freedom articulated arms.
- Legacy SCADA integration complexity:Brownfield manufacturing lines require custom protocol bridges to connect modern dispensing robots with existing batch management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dispensing Robots Market |
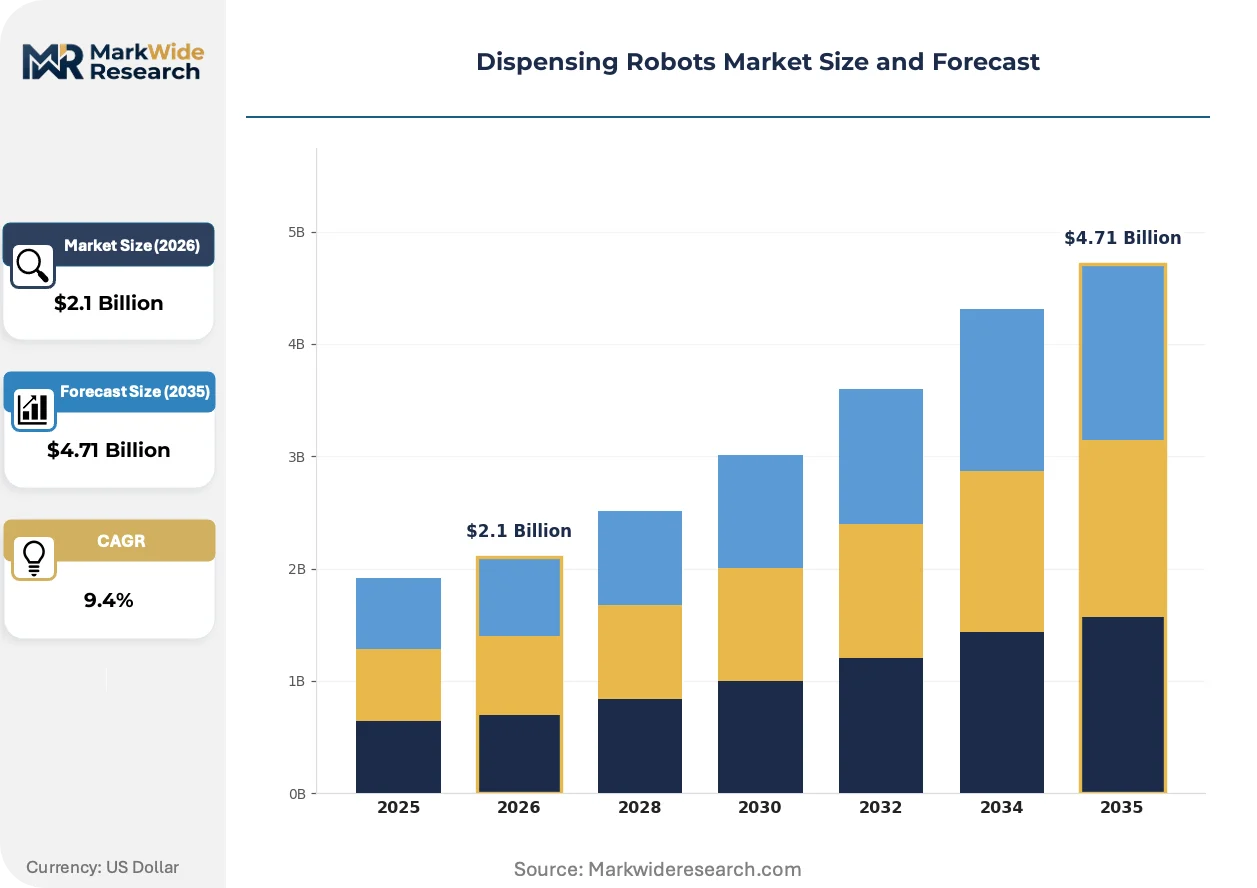
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.71 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Robotic Arms, Automated Guided Vehicles, Collaborative Robots, Fixed Robots Application: Pharmaceuticals, Food & Beverage, Electronics, Cosmetics End User: Manufacturers, Warehousing Solutions, Healthcare Providers, Retail Stores Technology: Artificial Intelligence, Machine Learning, Vision Systems, Sensor Technologies |
| Companies Covered | Omnicell Inc., Yaskawa Electric Corporation, Panasonic Corporation, ABB, Fanuc, Nordson Corporation, ScriptPro LLC, Swisslog Healthcare, Becton, Dickinson and Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dispensing Robots Market Strategic Shifts
Force-limiting collaborative architectures are penetrating regulated manufacturing environments as safety certification standards mature, while real-time vision feedback loops compress defect detection latency from seconds to milliseconds.
Collaborative robots with certified power and force limiting are displacing traditional caged industrial arms in mid-volume electronics and cosmetics assembly. Contract manufacturers in Taiwan and South Korea adopt these systems for smartphone component dispensing where batch sizes shift frequently. The displacement is compressing minimum efficient scale for automated lines, enabling shorter production runs without line reconfiguration downtime.
EMA Annex 1 sterile manufacturing guidelines now mandate continuous viable particle monitoring in Grade A filling zones. Aseptic dispensing robot deployments in Ireland and Switzerland incorporate isolator-integrated hydrogen peroxide vapor bio-decontamination cycles. Pharmaceutical OEMs respond by specifying stainless steel robot constructions with sealed cable management rated for repeated sterilization exposure.
Electronics assemblers now unbundle after-sales service contracts from initial capital purchases, selecting third-party maintenance providers based on mean-time-to-repair guarantees rather than OEM affiliation. This procurement fragmentation is most pronounced in Shenzhen and Dongguan manufacturing clusters, where independent service organizations stock critical servo drive spare parts locally. Component-level repair competes with complete robot replacement, extending asset depreciation schedules.
Dispensing Robots Market Segmentation
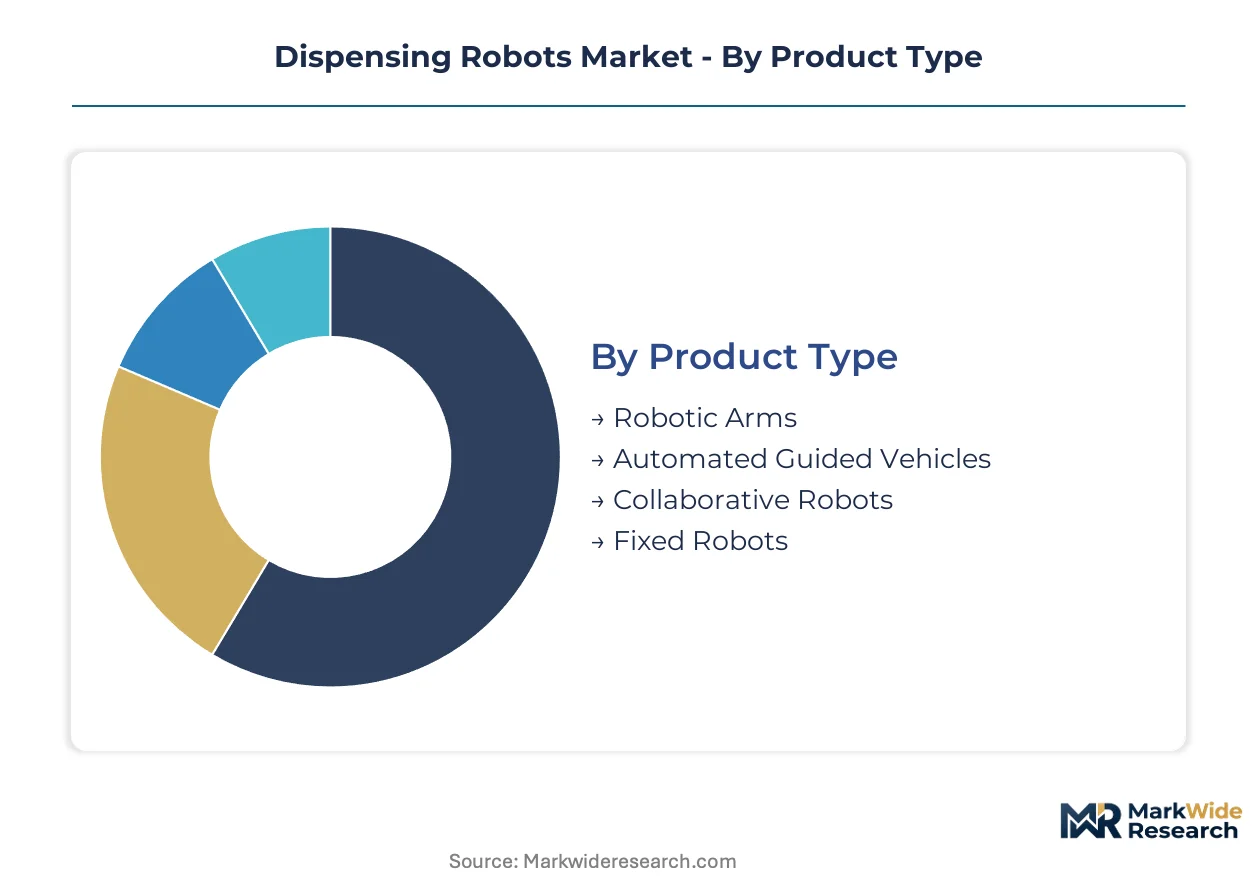
Dispensing robot segmentation reveals how technical specifications align with regulatory intensity across end-use industries. Product architecture choices directly determine which compliance frameworks apply and which geographies dominate procurement.
Product Type:
Domestic production concentrates articulated arm systems in Germany and Japan, while collaborative robot demand spreads through export-led channels into mid-volume manufacturing clusters.
- Robotic Arms:Six-degree-of-freedom articulated systems deliver sub-100-micron repeatability through servo-harmonic drive combinations. FDA cGMP pharmaceutical lines in Ireland and Switzerland specify stainless steel constructions with sealed cable management for repeated sterilization cycles.
- Collaborative Robots:Force-limiting designs with certified power and force limiting penetrate electronics and cosmetics assembly where batch flexibility outweighs throughput. Taiwan and South Korean contract manufacturers deploy these for smartphone component dispensing with frequent batch size shifts.
- Automated Guided Vehicles:Mobile dispensing platforms integrate with warehouse management systems for pharmaceutical distribution centers.
- Fixed Robots:Stationary Cartesian configurations serve high-volume adhesive and sealant applications in automotive-tier supplier plants.
Robotic arms command the established base. The steepest expansion runs through collaborative robots.
Application:
Cost tier stratification separates validated pharmaceutical systems from standard industrial configurations, with premium pricing justified by embedded vision verification and batch record integration.
- Pharmaceuticals:Aseptic dispensing under EMA Annex 1 Grade A guidelines demands continuous viable particle monitoring and hydrogen peroxide vapor bio-decontamination compatibility. Swiss and Irish filling zones drive specifications for isolator-integrated robot deployments.
- Electronics:Advanced packaging architectures require fluid-dispensing accuracy below 50 microns for underfill and encapsulation processes. Shenzhen and Dongguan clusters unbundle after-sales service contracts from capital purchases, selecting third-party maintenance based on mean-time-to-repair guarantees.
- Food & Beverage:Hygienic design robots with IP69K ratings handle viscous product dosing in dairy and sauce applications.
- Cosmetics:Mid-volume personal care manufacturers seek batch-flexible filling and capping solutions for SKU proliferation.
Pharmaceuticals anchor premium system pricing. Electronics generates the highest unit volume throughput.
End User:
Customer type determines integration complexity, with brownfield manufacturers facing legacy SCADA protocol bridges while greenfield sites specify native connectivity.
- Manufacturers:Original equipment manufacturers and contract manufacturers across pharmaceutical, electronics, and automotive sectors deploy dispensing robots for volume-critical processes with full batch traceability requirements.
- Warehousing Solutions:Distribution centers integrate dispensing AGVs with WMS platforms for pharmaceutical order fulfillment.
- Healthcare Providers:Hospital pharmacies and compounding facilities adopt robotic dispensing for unit-dose medication preparation under national pharmacy regulations.
- Retail Stores:Limited deployment in high-volume cosmetics and personal care retail for on-demand product customization.
Manufacturers absorb the dominant share of system procurement. Healthcare providers are climbing the fastest adoption curve.
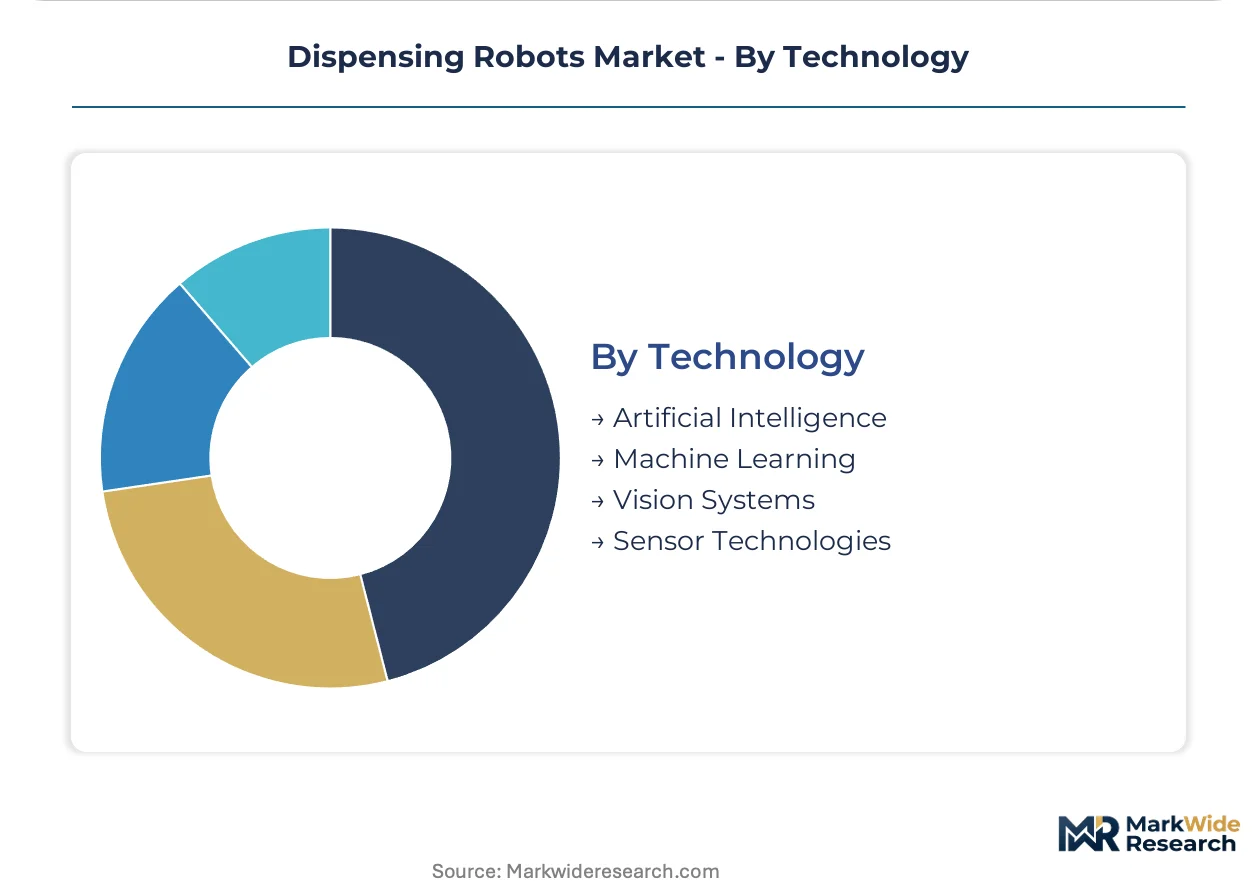
Technology:
Margin concentration pools where real-time spectral imaging enables defect rejection at millisecond latency, justifying premium system pricing in semiconductor and medical device packaging.
- Vision Systems:Real-time spectral imaging integrated with robotic dispensing creates premium pricing power. Machine-learning optimization faces lighter EU AI Act compliance burdens at lower risk tiers, enabling algorithmic adoption in European healthcare deployments.
- Artificial Intelligence:Predictive maintenance algorithms reduce unplanned downtime in high-throughput pharmaceutical lines.
- Machine Learning:Adaptive dispensing parameter optimization responds to reformulated adhesive and coating chemistries under EPA VOC emission rules.
- Sensor Technologies:Force-torque and proximity sensors enable collaborative safety certification and precision feedback control.
Vision systems capture the highest margin premiums. Machine learning is expanding most quickly through regulatory-compliant healthcare applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies. Swiss and Irish pharmaceutical buyers absorb premium system costs for EMA Annex 1 compliance, while Taiwanese electronics contract manufacturers prioritize unit economics and third-party maintenance contracts.
Germany
Automotive-tier precision engineering capabilities transfer directly into medical device dispensing applications. KBA safety standards and EMA-aligned state pharmaceutical regulations push manufacturers toward validated robotic systems. The Stuttgart-Munich industrial corridor concentrates technical talent pools serving both automotive and medical OEMs.
United States
FDA cGMP traceability mandates compel pharmaceutical line upgrades to servo-driven dispensing robots with embedded vision. EPA VOC emission rules force extensive parameter recalibration for reformulated adhesive chemistries. Massachusetts and North Carolina biotech clusters drive specifications for isolator-integrated aseptic filling systems.
Japan
METI industrial automation incentives support domestic robot OEM expansion into semiconductor packaging applications. PMDA pharmaceutical manufacturing guidelines align with international traceability standards. The Nagoya-Tokyo manufacturing belt concentrates harmonic drive and direct-drive motor component specialists.
Switzerland
Swissmedic sterile manufacturing requirements exceed baseline EMA Annex 1 guidelines for Grade A filling zones. Federal precision manufacturing subsidies sustain high-value medical device automation investments. The Basel-Zurich corridor anchors European demand for stainless steel robot constructions with sealed cable management.
South Korea
MFDS pharmaceutical traceability rules and national smart factory initiatives accelerate dispensing robot adoption. Samsung and SK Hynix advanced packaging architectures drive sub-50-micron fluid-dispensing accuracy requirements. The Suwon-Giung semiconductor cluster sources collaborative robots for batch-flexible smartphone component assembly.
Dispensing Robots Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Precision-engineering specialists command premium pricing in pharmaceutical and semiconductor applications, while assembly-integrators compete on deployment speed and service flexibility. The market separates into three strategic archetypes: motion-control heritage players, fluid-dispensing specialists, and healthcare-focused automation providers. Dominant competitive moves include geographic expansion through localized production networks and technology licensing partnerships to access regulated healthcare markets.
Among motion-control heritage players, ABB and Yaskawa Electric Corporation occupy positions reflecting decades of servo-motion engineering. Nordson Corporation exemplifies the fluid-dispensing specialist archetype, leveraging application expertise that extends across adhesive, sealant, and coating chemistries. These three anchors represent distinct competitive vectors—European industrial automation depth, Asian manufacturing scale, and process-specific technical specialization—without any single archetype commanding uniform cross-sector dominance.
| Leading Market Players |
|---|
| Omnicell Inc. |
| Yaskawa Electric Corporation |
| Panasonic Corporation |
| ABB |
| Fanuc |
| Nordson Corporation |
| ScriptPro LLC |
| Swisslog Healthcare |
| Becton, Dickinson and Company |
| Others |
Value Chain & Pricing Dynamics
FDA cGMP and EMA Annex 1 validation requirements gate both supplier qualification and price differentiation simultaneously, compelling pharmaceutical buyers to absorb premium costs for certified systems while electronics assemblers drive commoditization through unbundled service procurement.
Pricing Analysis
After-sales revenue tiers spanning spare servo drives, field calibration contracts, and extended warranty coverage drive lifetime value in dispensing automation. Three-tier pricing structure across premium pharmaceutical-validated systems, standard industrial configurations, and economy collaborative units separates FDA-certified stainless steel constructions from general-purpose assemblies. Cost compression in economy tiers intensifies because Taiwanese contract manufacturers source third-party maintenance based on mean-time-to-repair guarantees rather than OEM affiliation. Electronics assemblers exhibit highest price sensitivity; Swiss pharmaceutical filling zones show lowest.
Supply Chain Analysis
Harmonic drive and direct-drive motor supply from Japanese and German component specialists creates a chokepoint constraining throughput for high-precision pharmaceutical and semiconductor lines. Robot OEMs draw from Taiwan for vision system sensors, Germany for servo controllers, and Japan for precision reducers. Single-source vulnerability concentrates in harmonic drive manufacturing where two Japanese suppliers anchor global capacity. Distribution runs through OEM-direct channels for validated pharmaceutical systems and independent service organizations for electronics clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Manual dispensing labor and semi-automated benchtop systems pose substitution threats that robotic incumbents must neutralize through compliance automation and total cost-of-ownership messaging.
For Market Incumbents: Fortify certification moats by accelerating FDA and EMA validation documentation for next-generation collaborative architectures. Deepen backward integration into harmonic drive supply through captive production partnerships with Nagoya-Tokyo component specialists. Counter emerging Asian assembly-integrators by embedding vision verification as standard rather than premium configuration.
For New Entrants and Emerging Players: CE marking fast-track for collaborative robot safety certification unlocks mid-volume cosmetics and personal care assembly where batch flexibility requirements outstrip incumbent response speed. Target South Korean smartphone component contract manufacturers seeking shorter lead times than Yaskawa or ABB can deliver. Lead with algorithmic dispensing optimization as a software-layer wedge rather than hardware displacement.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across collaborative robot sub-segments as component standardization reduces minimum efficient scale. Long-term viability favors precision-engineering specialists with embedded vision capabilities over pure-play integrators. Watch EU AI Act risk-classification threshold adjustments as the signal indicating whether algorithmic dispensing optimization faces expanded compliance burdens or lighter adoption pathways.
| Strategic Initiative | Industry Significance |
|---|---|
| EMA Annex 1 Validation Pathway | Swiss and Irish pharmaceutical filling zones mandate isolator-integrated stainless steel constructions with sealed cable management. |
| Vision System Integration Partnership | Real-time spectral imaging embedded in robotic arms commands premium pricing in semiconductor underfill applications. |
| Harmonic Drive Supply Agreement | Japanese component specialist partnerships secure sub-100-micron repeatability for high-throughput pharmaceutical lines. |
| Third-Party Service Network Expansion | Shenzhen and Dongguan electronics clusters unbundle maintenance contracts based on mean-time-to-repair guarantees. |
| Collaborative Robot Safety Certification | Force-limiting designs penetrate cosmetics assembly where batch flexibility outweighs throughput requirements. |
Study Parameters
Operator-level perspectives from pharmaceutical plant engineers, electronics contract manufacturing procurement leads, automotive Tier 1 maintenance directors, and vision system integration specialists anchored the qualitative base. Primary interviews combined with secondary validation from FDA 483 inspection observations, EMA GMP inspection databases, METI industrial automation incentive disclosures, and SEC 10-K filings from listed robot OEMs. Bottom-up unit deployment estimates triangulated against top-down industry absorption capacity across the analysis window.
Sensitivity analysis tested forecast robustness across alternative regulatory enforcement scenarios and component supply disruption assumptions. Segmentation dimensions modeled include robot architecture type, application industry, end-user integration complexity, and technology layer. CAGRs derived from logistic adoption curves fitted to validated deployment timelines. Forecast inputs incorporated PMDA pharmaceutical manufacturing guideline alignment patterns and EPA VOC emission rule implementation trajectories.
The analysis sits within stated boundaries; outcomes outside sustained EMA Annex 1 enforcement intensity or semiconductor packaging architecture stability would require recalibration. Forecasts reflect documented assumptions regarding regulatory trajectory and component supply continuity. Practitioners should keep alternative scenarios live as EU AI Act risk-classification thresholds and REACH substance restriction expansions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Europe Robotics and Automation Actuators Market
Robotics and Automation
Self-Driving Delivery Robot Market
Robotics and Automation
Intelligent Vending Machines Market
Robotics and Automation
Consumer and Office Robot Market
Robotics and Automation
Robot Label Applicators Market
Robotics and Automation
Robotic Lawn Mower Market
Robotics and Automation
Japan Cloud Robotics Market
Robotics and Automation
Global Medical Robotic Systems Market
Robotics and Automation
Cordless Router Market
Robotics and Automation
Global Robot Teach Pendant Market
Robotics and Automation
Autonomous Mobile Manipulator Robots (AMMR) Market
Robotics and Automation
Asrs and Ruos Market
Robotics and Automation
Singapore Cloud Robotics Market
Robotics and Automation
Cleaning Robot Market
Robotics and Automation
Warehouse Robotics Market
Robotics and Automation
Service Robotics Market