
 Autonomous Drilling Robots Market | 2026-2036
Autonomous Drilling Robots Market Size, Share, and Industry Trends Forecast 2026-2036
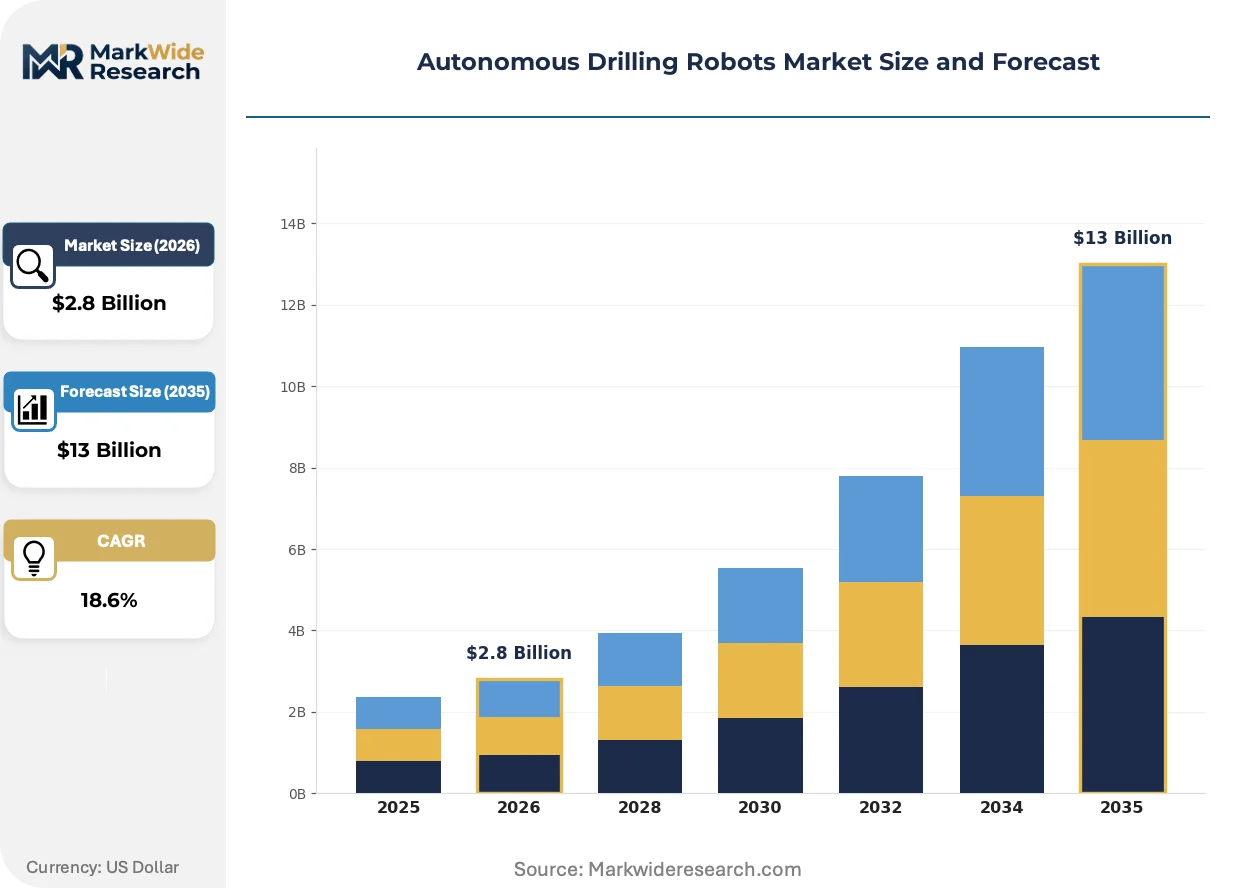
Autonomous Drilling Robots Market Outlook
Tungsten carbide insert bit materials is rebalancing total cost of ownership for autonomous drill string components against traditional PDC cutters in abrasive formations. Epiroc AB leverages its established underground mining automation architecture to anchor robotic drill deployments across Scandinavian hard-rock operations. Sandvik AB competes through integrated drill-and-blast automation workflows that extend from planning software to machine execution. Nabors Industries (Canrig Drilling Technology) dominates land-based autonomous rig markets in North American shale plays through its proprietary rig operating system.
Autonomous drilling robots are self-propelled, sensor-guided machines capable of executing borehole programs without continuous human operator presence, typically incorporating LiDAR-based collision avoidance, real-time downhole telemetry, and machine-learning-driven trajectory correction to deliver repeatable hole geometry in construction, mining, and hydrocarbon extraction. Directional drillers command the largest value share as extended-reach laterals in unconventional oil and gas demand precise azimuth and inclination control without round-the-clock directional drillers on the rig floor. Trenchless drillers represent the fastest-expanding product category as fiber-to-the-home mandates and urban utility rehabilitation drive horizontal directional drilling automation beneath congested infrastructure corridors.
FAA regulations govern beyond-visual-line-of-sight drone surveys that increasingly precede autonomous ground drilling in remote exploration sites, while OSHA and MSHA standards dictate emergency-stop protocols and exclusion zones for robotic equipment operating alongside residual human crews. The EU Machinery Directive and CE marking requirements shape export compliance for drill robot OEMs seeking European mining and civil engineering contracts. Stakeholders must monitor how evolving interoperability standards between competing automation platforms affect fleet procurement decisions and long-term vendor lock-in risk.
Market Dynamics
MSHA's 2023 powered haulage and drilling safety mandates are compressing replacement cycles for manned drill rigs across surface mining operations, forcing capital allocation toward robotic platforms before end-of-life depreciation schedules complete.
Growth Catalysts
- Underground hard-rock automation:Scandinavian mine operators are retrofitting existing drill fleets with autonomous tramming and rod-handling systems to address chronic labor shortages in remote ore bodies.
- FAA Part 107 waiver expansion:Beyond-visual-line-of-sight drone surveys now precede autonomous ground drilling at remote exploration sites, reducing pre-drilling site preparation from weeks to days.
- Tungsten carbide insert durability:Abrasive formation drilling in Pilbara iron ore operations is extending bit life metrics sufficiently to justify full-fleet autonomous conversion.
Market Restraints
- Capital intensity of retrofit programs:Brownfield autonomous conversions require 60-80% of greenfield system costs without matching productivity guarantees, freezing mid-tier operator commitments.
- LiDAR sensor supply concentration:Industrial-grade scanning components for collision avoidance remain concentrated among German and Japanese component suppliers, exposing fleet rollouts to 18-24 month lead times.
- Downhole telemetry bandwidth limits:Real-time trajectory correction in deep vertical holes exceeds current mud-pulse data transmission rates, constraining autonomous effectiveness below 4,000 meters.
Strategic Opportunities
- EU Green Deal mining provisions:Critical raw materials extraction incentives are opening autonomous drill procurement channels for lithium and rare earth projects in Portugal and Finland.
- Converged drill-blast-load workflows:Integration of autonomous drilling with automated explosive loading and haulage dispatch is compressing stope cycle times in Canadian underground operations.
- Horizontal directional drilling automation:Fiber-to-the-home mandates in Germany and France are creating dedicated trenchless drill robot demand beneath urban infrastructure corridors.
Industry Challenges
- Autonomous systems engineering talent scarcity:Mining equipment OEMs compete with automotive and logistics robotics firms for control software specialists, extending commissioning timelines.
- Interoperability certification delays:Lack of unified machine-to-machine communication standards between competing automation platforms forces single-vendor fleet commitments.
- Legacy fleet integration complexity:Mixed autonomous-manual operations require redesigned exclusion zones and emergency-stop architectures that disrupt existing shift patterns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Autonomous Drilling Robots Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Trenchless Drillers, Surface Drillers, Directional Drillers, Mini Drillers Technology: Electric, Hydraulic, Pneumatic, Robotic End User: Construction, Mining, Oil & Gas, Telecommunications Application: Infrastructure Development, Resource Extraction, Utility Installation, Geological Surveys |
| Companies Covered | Nabors Industries (Canrig Drilling Technology), Epiroc AB, NOV (National Oilwell Varco), August Robotics, DEWALT (Stanley Black & Decker), Schlumberger Limited, Sandvik AB, Weatherford International, Halliburton Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Autonomous Drilling Robots Market Strategic Shifts
Edge-computing architectures are relocating trajectory optimization from remote data centers to drill rig-mounted processors, compressing latency for real-time borehole steering decisions in bandwidth-constrained environments.
Machine-learning-based downhole vibration analysis is decentralizing geological interpretation from centralized geology departments to individual drill platforms. Major iron ore producers in Western Australia are deploying these systems across Pilbara blasthole fleets. The technology is decentralizing subsurface modeling authority and compressing geological update cycles from shift-based to continuous.
OSHA's forthcoming robotic equipment safety standards for construction and mining applications are mandating redundant emergency-stop architectures and defined human-robot collaboration zones. Equipment manufacturers are redesigning drill cab enclosures and perimeter sensing systems to preempt compliance deadlines. North American shale operators are accelerating procurement to lock in pre-standard pricing before certification costs embed.
Service contract unbundling is separating autonomous drilling software subscriptions from hardware maintenance agreements. Large mining houses in Chile and Peru are negotiating direct platform licensing with automation software vendors, bypassing traditional OEM service packages. This restructuring is most visible among copper concentrator operators seeking operational technology independence from single-source equipment suppliers.
Autonomous Drilling Robots Market Segmentation
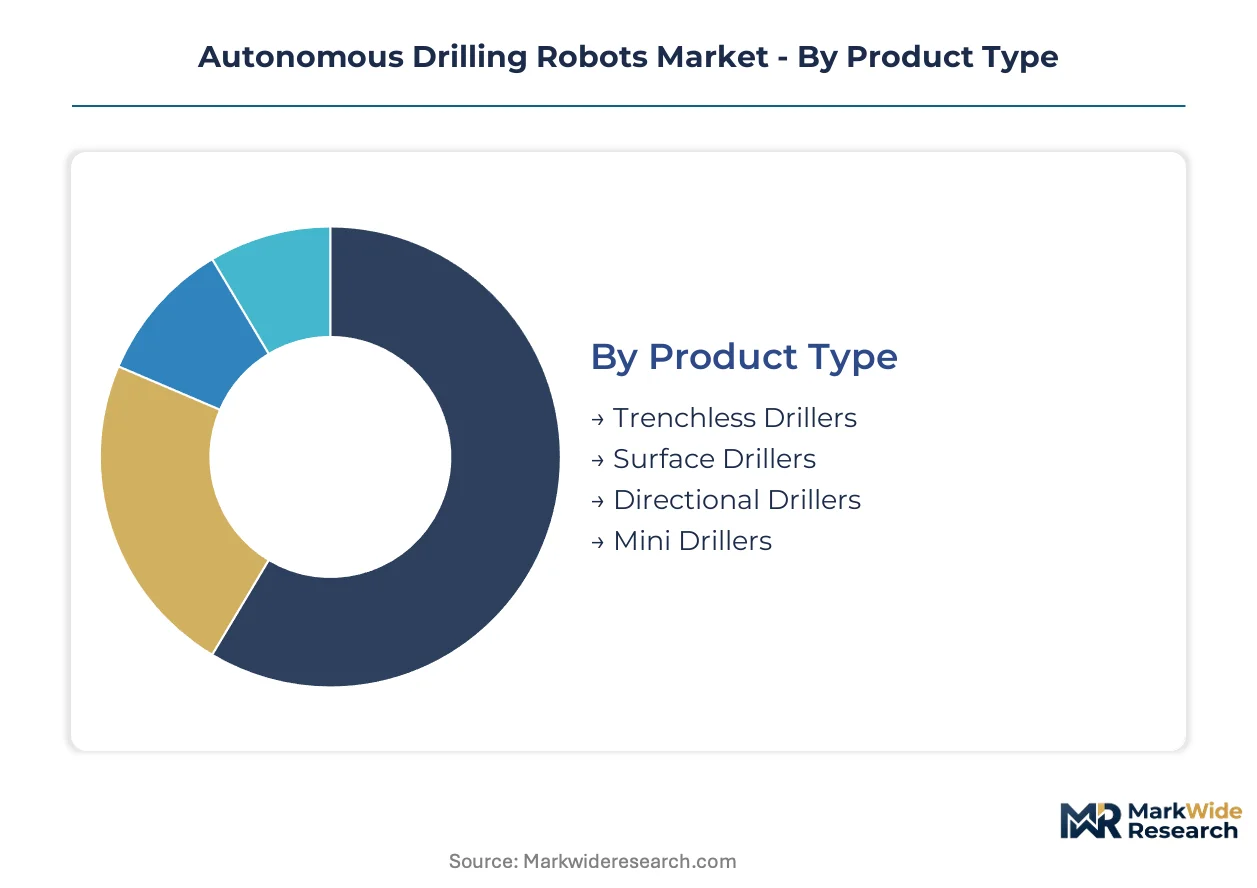
Autonomous drilling robot procurement patterns diverge sharply across operating environments, with surface mining and underground hydrocarbon extraction driving fundamentally different sensor and mobility specifications. Fleet managers weigh tramming autonomy against precision steering when matching equipment categories to geological conditions.
Product Type:
Replacement cycles for manned drill rigs are compressing as MSHA mandates accelerate capital redeployment toward robotic platforms, with upgrade economics varying substantially by machine category.
- Directional Drillers:Extended-reach lateral drilling in unconventional shale formations demands precise azimuth and inclination control without continuous human presence on the rig floor. Permian Basin operators in Texas and North Sea projects in Norway are standardizing these systems for complex well geometries.
- Trenchless Drillers:Horizontal directional drilling beneath congested urban corridors requires compact, steerable machines with real-time pullback monitoring. German fiber-to-the-home mandates and French utility rehabilitation programs are expanding deployment of these units beneath existing infrastructure.
- Surface Drillers:Pilbara iron ore operations in Australia deploy autonomous blasthole fleets for repetitive pattern drilling in abrasive formations.
- Mini Drillers:Confined-space geotechnical investigation and limited-access construction sites utilize reduced-footprint machines with simplified rod-handling systems.
Volume placements concentrate in Directional Drillers; the faster expansion belongs to Trenchless Drillers.
Technology:
Powertrain selection determines maintenance intervals and underground emissions compliance, with electric architectures gaining favor in ventilation-constrained operations.
- Electric:Battery-electric and tethered electric drive systems eliminate diesel particulate exposure in underground Scandinavian hard-rock mines. Epiroc's zero-emission tramming platforms are retrofitting existing drill fleets across Swedish and Finnish ore bodies.
- Robotic:Fully integrated autonomous platforms incorporate LiDAR collision avoidance, machine-learning trajectory correction, and rod-handling automation without human cab occupancy. Australian surface mining operations are standardizing these configurations for 24-hour continuous drilling programs.
- Hydraulic:Conventional fluid power systems persist in heavy-duty surface applications requiring high torque at low rotational speeds.
- Pneumatic:Compressed-air drive remains economical for shallow blasthole drilling in soft-to-medium rock formations with limited automation requirements.
Procurement volumes favor Electric systems in underground environments; Robotic configurations are climbing the fastest in greenfield surface operations.
End User:
Customer capital intensity and safety regulatory exposure create distinct purchasing patterns across extractive and civil engineering sectors.
- Mining:Surface and underground hard-rock operations face MSHA, Australian Work Health and Safety, and Canadian provincial mandates for powered equipment automation. Rio Tinto and BHP have deployed autonomous blasthole fleets across Western Australian Pilbara iron ore sites.
- Oil & Gas:Land-based shale operators and offshore platform managers seek reduced crew exposure during extended-reach drilling campaigns. Nabors Industries dominates North American shale plays through proprietary rig operating systems.
- Construction:Urban infrastructure and foundation drilling contractors adopt semi-autonomous systems for piling and geotechnical work.
- Telecommunications:Fiber network deployers require compact trenchless units for last-mile connectivity beneath roadways and residential areas.
Equipment placements concentrate in Mining; steepest expansion trajectory belongs to Telecommunications as broadband mandates proliferate.
Application:
Project duration and geological uncertainty influence the degree of autonomy specified, with long-life resource extraction justifying full robotic integration.
- Resource Extraction:Continuous production drilling in established ore bodies or hydrocarbon reservoirs demands full automation with minimal human intervention. Canadian underground operations are converging drill-blast-load workflows to compress stope cycle times.
- Utility Installation:Horizontal directional drilling for pipelines, power cables, and fiber optics requires precise steering through variable subsurface conditions beneath existing infrastructure.
- Infrastructure Development:Foundation piling, tunnel boring preparation, and geotechnical investigation utilize semi-autonomous systems with operator oversight.
- Geological Surveys:Exploration drilling programs combine FAA Part 107 drone surveys with autonomous ground drilling to compress site preparation timelines at remote locations.
Deployment volumes concentrate in Resource Extraction; Utility Installation is gaining share fastest as urban trenchless mandates expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pilbara mining concessions and Norwegian continental shelf licensing zones concentrate autonomous drilling procurement through accelerated depreciation schedules and state-backed automation incentives. Resource extraction economics favor capital-intensive robotic fleets where labor scarcity and safety exposure costs compound.
Australia
Rio Tinto and BHP have deployed autonomous blasthole drill fleets across Western Australian Pilbara iron ore operations. Australian Work Health and Safety mandates compress replacement cycles for manned surface rigs. Perth-based automation engineering clusters support 24-hour continuous drilling programs with remote operation centers.
United States
Permian Basin operators in Texas and New Mexico standardize self-directed directional drillers for extended-reach laterals in unconventional shale formations. FAA Part 107 waiver expansion enables drone surveys preceding autonomous ground drilling at remote exploration sites. Houston and Midland-Odessa anchor land-based autonomous rig procurement channels.
Norway
North Sea offshore projects demand precise azimuth control without round-the-clock directional drillers on platform floors. Petroleumstilsynet safety regulations accelerate substitution of manned drill rigs with robotic platforms. Stavanger and Bergen harbor subsea automation engineering concentrations serving harsh-environment hydrocarbon extraction.
Sweden
Scandinavian hard-rock mine operators retrofit existing drill fleets with autonomous tramming and rod-handling systems. Epiroc leverages established underground mining automation architecture across Swedish ore bodies. Kiruna and Malmberget anchor zero-emission battery-electric drill platform deployments in ventilation-constrained operations.
Canada
Canadian provincial mandates for powered equipment automation drive underground hard-rock conversions in Ontario and Quebec. Converged drill-blast-load workflows compress stope cycle times in Canadian Shield operations. Sudbury and Val-d'Or concentrate autonomous mining equipment engineering and commissioning expertise.
Autonomous Drilling Robots Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated mining equipment OEMs commanding premium positioning in underground automation while oilfield service conglomerates dominate land-based hydrocarbon extraction. The vendor base concentrates among three strategic archetypes: diversified mining technology conglomerates, oilfield drilling contractors with proprietary operating systems, and industrial tool manufacturers extending into robotic platforms. Competitive dynamics center on M&A consolidation of automation software capabilities and geographic expansion through regional service partnerships.
Among diversified mining technology conglomerates, Epiroc AB and Sandvik AB exemplify integrated automation platform providers spanning drill-and-blast workflows from planning software to machine execution. Nabors Industries anchors the oilfield drilling contractor archetype through proprietary rig operating systems standardized across North American shale plays. These three companies represent contrasting strategic positions: mining-focused underground automation, converged surface-underground portfolios, and hydrocarbon extraction specialization.
| Leading Market Players |
|---|
| Nabors Industries (Canrig Drilling Technology) |
| Epiroc AB |
| NOV (National Oilwell Varco) |
| August Robotics |
| DEWALT (Stanley Black & Decker) |
| Schlumberger Limited |
| Sandvik AB |
| Weatherford International |
| Halliburton Company |
| Others |
Value Chain & Pricing Dynamics
Performance-tier bifurcation between CE-marked robotic platforms and uncertified retrofit kits manifests in divergent procurement economics across European mining contracts and North American shale operations. Premium-tier autonomous drill systems command sustained pricing power through integrated software-hardware bundles, while commodity retrofit assemblies face margin compression from component cost volatility and buyer consolidation.
Pricing Analysis
Volume placements concentrate in mid-tier electric tramming systems, while margins accrue to fully integrated robotic platforms with proprietary operating systems. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and after-sales service bundling. Pricing pressure stems from LiDAR sensor supply concentration among German and Japanese component suppliers extending procurement lead times. Mid-tier mining operators exhibit highest price sensitivity, deferring autonomous conversions pending depreciation cycle completion, whereas supermajor oil and gas producers prioritize safety compliance over unit economics.
Supply Chain Analysis
CE marking and MSHA certification requirements gate market access for automation software vendors and component suppliers, compressing qualified supplier pools. Manufacturing concentration centers on Sweden, Germany, and Japan for industrial-grade LiDAR and downhole telemetry modules. Raw material dependencies include tungsten carbide for drill bit inserts, rare earth elements for electric drivetrain magnets, and high-grade steel for drill string components. Single-source vulnerability persists in industrial scanning components, exposing fleet rollouts to extended lead times. Distribution runs through OEM-direct channels for large mining houses and regional equipment dealers for mid-tier operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Autonomous drilling robotics represents a consolidation play where MSHA mandate acceleration and capital intensity barriers force weaker automation software vendors toward acquisition or exit. Scale advantages in integrated drill-blast-load workflows favor established mining equipment conglomerates with proprietary platform architectures.
For Market Incumbents: Extend automation software licensing models to unbundle recurring revenue from hardware maintenance agreements, mirroring Chilean copper concentrator procurement patterns. Secure backward integration into LiDAR sensor supply through strategic partnerships with German and Japanese component specialists, reducing exposure to 18-24 month lead time volatility. Prioritize interoperability certification investments to preempt vendor lock-in concerns freezing mid-tier operator commitments. For New Entrants and Emerging Players: The premium-to-economy price-point gap in trenchless horizontal directional drilling equipment offers white-space entry beneath congested urban infrastructure corridors in Germany and France. Target telecommunications fiber-to-the-home deployers with compact, steerable units featuring simplified rod-handling systems and real-time pullback monitoring. Pursue go-to-market partnerships with regional utility rehabilitation contractors lacking in-house automation expertise. For Investors and Strategic Acquirers: Re-rating potential sits with automation software specialists holding platform-agnostic interoperability credentials given EU Machinery Directive compliance deadlines compressing procurement decision timelines. Long-term viability favors vendors with demonstrated integration across drill-blast-load workflows in Canadian underground operations. The signal to watch is FAA Part 107 waiver expansion enabling converged drone-survey and ground-drilling service offerings at remote exploration sites.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Licensing Unbundling | Separates software subscriptions from hardware maintenance, addressing Chilean copper operator demands for operational technology independence. |
| LiDAR Supply Partnership | Reduces lead time exposure from German and Japanese component concentration constraining fleet rollout schedules. |
| Interoperability Certification | Preempts vendor lock-in concerns freezing mid-tier mining operator procurement commitments across competing automation architectures. |
| Trenchless Equipment Miniaturization | Captures German and French fiber-to-the-home mandate demand beneath congested urban utility corridors. |
| Converged Drone-Ground Workflow | Compresses remote exploration site preparation from weeks to days through FAA Part 107 waiver expansion. |
Study Parameters
Trade publications, MSHA regulatory filings, and SEC equipment manufacturer disclosures formed the secondary backbone for market sizing and competitive positioning assessment. Primary interviews with mine automation directors, oilfield drilling superintendents, OEM procurement managers, and underground safety compliance officers validated demand assumptions and replacement cycle timelines. Bottom-up triangulation across product category placements and top-down reconciliation against capital expenditure disclosures from Rio Tinto, BHP, and Permian Basin operators ensured cross-verified volume estimates.
Analytical lens combined bottom-up unit economics with top-down industry capex trajectory assessment across the projection horizon. Segmentation modeling incorporated product type, powertrain technology, end-use sector, and application intensity dimensions. CAGRs derived from regression analysis against historical fleet deployment patterns, adjusted for regulatory mandate acceleration effects. Industry-specific forecast inputs included MSHA compliance deadline phasing and FAA Part 107 waiver expansion timelines for drone-integrated exploration workflows.
Underlying measurement precision varies by segment; surface mining blasthole deployments carry tighter precision than emerging trenchless telecommunications applications given established fleet reporting practices. Forecasts reflect assumptions around regulatory enforcement consistency and component supply normalization. A model refresh is warranted upon material change in LiDAR sensor supply concentration or EU Machinery Directive interoperability standard finalization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Automated Plate Handlers Market
Robotics and Automation
Piece Picking Robots Market
Robotics and Automation
Italy Cloud Robotics Market
Robotics and Automation
Global Indoor Robots Market
Robotics and Automation
Global Robotics Parking System Market
Robotics and Automation
Tool Tethering Market
Robotics and Automation
Robotic Drilling Market
Robotics and Automation
Data Center Robotics Market
Robotics and Automation
Underwater Exploration Robots Market
Robotics and Automation
Social Robots Market
Robotics and Automation
Bot Services Market
Robotics and Automation
Autonomous Mobile Manipulator Robots (AMMR) Market
Robotics and Automation
Virtual 3D Nanorobots Market
Robotics and Automation
Japan Agricultural Robot Market
Robotics and Automation
Smart Curtain Robot Market
Robotics and Automation
Harvesting Robot Market