
 BPO Business Analytics Market | 2026-2036
BPO Business Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
BPO Business Analytics Market Intelligence
Enterprise sales channels for analytics outsourcing is fragmenting as direct-to-client digital platforms, systems integrator partnerships, and cloud marketplace listings compete for contract origination. Accenture leverages its consulting heritage to anchor premium engagements with Fortune 500 clients. Genpact sustains dominance in finance and accounting analytics through deep domain workflows. IBM competes via Watson-powered cognitive analytics embedded in hybrid cloud architectures.
BPO Business Analytics encompasses the contracted delivery of statistical modeling, data visualization, and predictive forecasting services performed by third-party providers on behalf of client organizations. These services integrate structured and unstructured data pipelines, apply machine learning algorithms, and generate actionable intelligence for revenue optimization and risk mitigation. Cloud-based deployment leads segment value as enterprises abandon capital-intensive server farms for elastic consumption models. Predictive analytics represents the fastest-expanding service type, with financial institutions and retailers deploying demand forecasting and churn detection at scale. On-premise solutions retain relevance in regulated healthcare environments where data residency requirements constrain off-premise processing.
FDA oversight of healthcare data integrity and HIPAA privacy mandates shape analytics contracting terms for patient-facing applications. The EU AI Act and GDPR cross-border transfer restrictions complicate multi-jurisdictional delivery models for European clients. Stakeholders must monitor evolving algorithmic accountability standards as regulators in the United States and European Union tighten disclosure requirements for automated decision systems.
Market Dynamics
Cloud-native analytics architectures are compressing contract timelines and eroding the premium pricing power of legacy on-premise integrators. Healthcare providers and financial institutions now demand elastic consumption models that bypass capital-intensive infrastructure commitments.
Growth Catalysts
- HIPAA-compliant cloud frameworks:United States healthcare systems are migrating patient analytics to HIPAA-certified cloud environments, unlocking outsourced processing of claims data and clinical outcomes.
- EU AI Act algorithmic accountability:European enterprises are contracting third-party analytics providers to implement audit-ready automated decision systems ahead of enforcement deadlines.
- Real-time supply chain forecasting:Retailers are deploying predictive demand models to compress inventory cycles and reduce working capital requirements.
Market Restraints
- Cross-border data localization:GDPR transfer restrictions fragment analytics delivery across European jurisdictions, forcing redundant infrastructure deployment.
- Specialized data science talent scarcity:Machine learning engineering and healthcare informatics expertise concentrates in United States and Western European labor markets, inflating service costs.
- Hybrid integration complexity:Enterprises maintaining on-premise legacy systems face protracted timelines for cloud migration, delaying full outsourcing transitions.
Strategic Opportunities
- India-based delivery centers:Analytics providers are establishing captive centers in Bangalore and Hyderabad to access statistical modeling talent at lower cost structures.
- ISO 27001 certification differentiation:Providers achieving information security management certification are capturing contracts from risk-averse financial services buyers.
- Edge analytics convergence:Integration of IoT sensor streams with cloud-based predictive models enables real-time operational intelligence for manufacturing clients.
Industry Challenges
- Interpretable machine learning expertise:Regulatory disclosure requirements for automated credit and healthcare decisions demand specialized talent in explainable AI techniques.
- Legacy ERP system integration:SAP and Oracle environments require custom API development to feed data into modern analytics pipelines, extending project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | BPO Business Analytics Market |
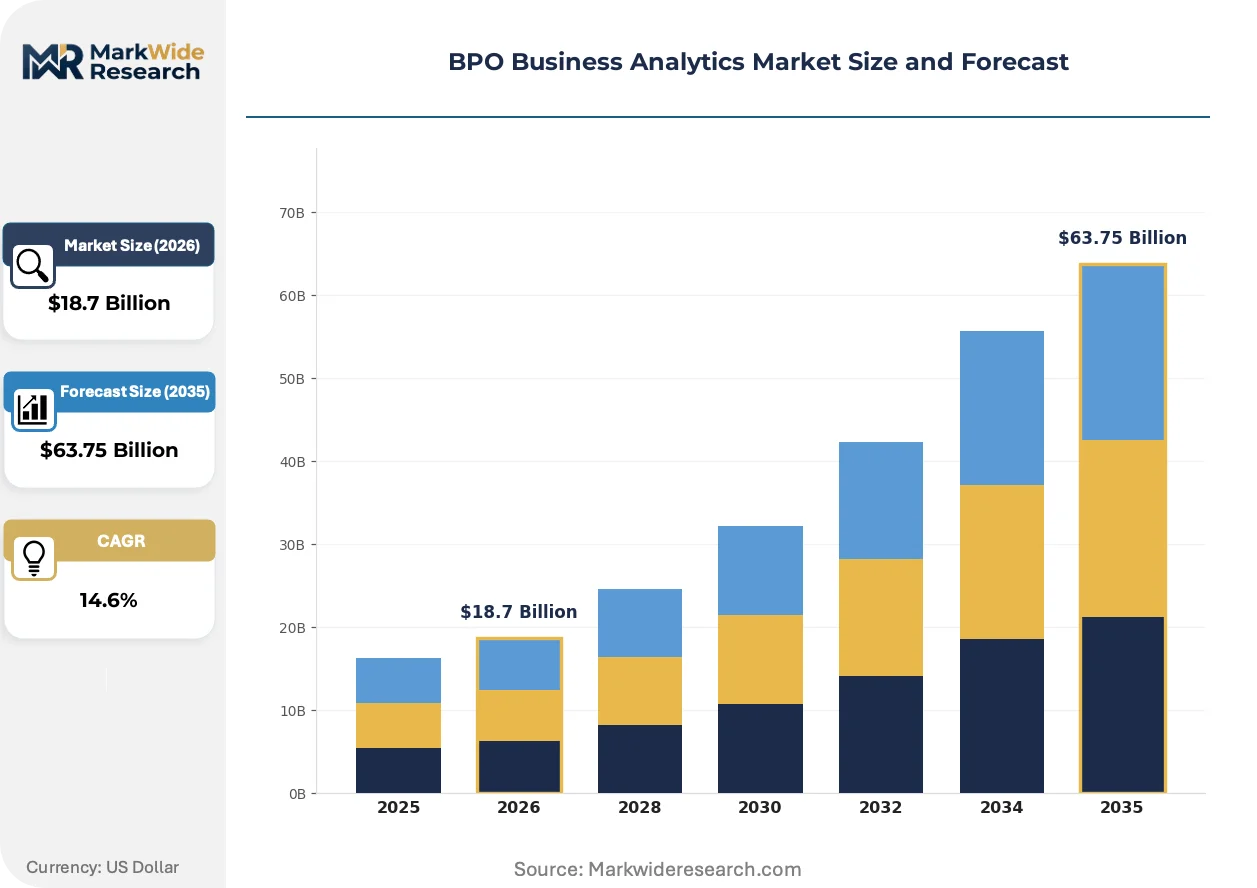
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $63.75 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Data Analysis, Reporting, Performance Management, Predictive Analytics Deployment: On-Premise, Cloud-Based, Hybrid, SaaS End User: Finance, Retail, Healthcare, Telecommunications Solution: Business Intelligence, Dashboarding Tools, Data Mining, Reporting Software |
| Companies Covered | Accenture, IBM, Genpact, Cognizant, Wipro, TCS, Capgemini, Infosys, EXL Service, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
BPO Business Analytics Market Strategic Shifts & Innovations
Automated machine learning platforms are compressing the analytics value chain from data preparation to model deployment. Providers and clients alike are reconfiguring delivery models around self-service interfaces and embedded intelligence.
Serverless analytics architectures are rendering obsolete the traditional extract-transform-load pipelines that required dedicated data engineering teams. Mid-market retailers and regional healthcare networks are adopting these platforms within six-month implementation cycles. The shift is compressing margins for providers dependent on hourly professional services billing.
The EU AI Act risk classification framework is mandating conformity assessments for high-risk automated decision systems deployed in credit scoring and recruitment analytics. European BPO providers are embedding algorithmic audit trails and human-in-the-loop protocols into service delivery. Financial institutions in Germany and France are delaying full automation rollouts pending regulatory clarity on liability allocation.
Subscription-based consumption models are displacing fixed-fee outsourcing contracts across the analytics services landscape. Enterprise buyers in the United States are unbundling descriptive reporting from predictive modeling to optimize spend allocation. Healthcare providers in California and Texas are piloting usage-based pricing for population health analytics, paying per patient record processed rather than annual retainer.
BPO Business Analytics Market Segmentation
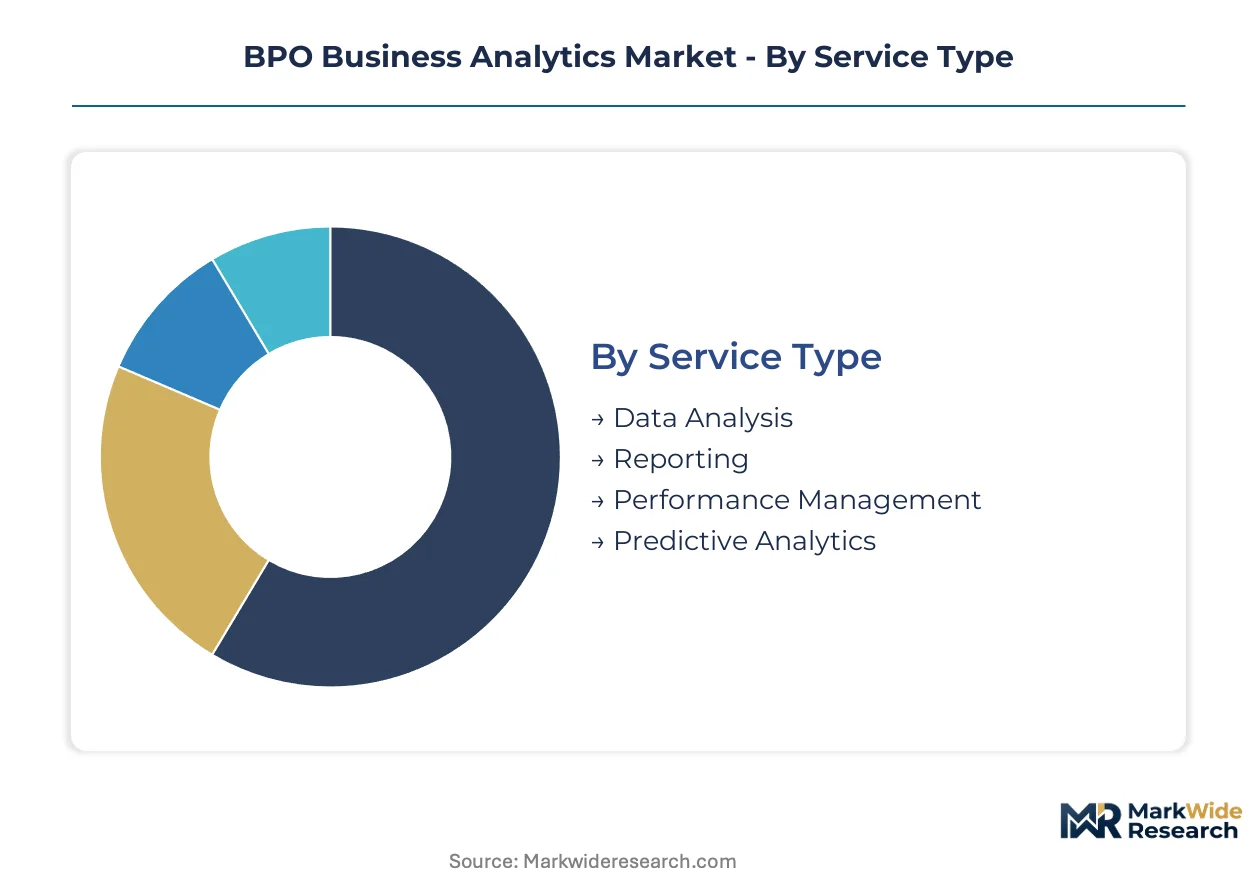
Segmentation in BPO Business Analytics reveals divergent contract renewal cycles and margin structures. Cloud-native services turn over quarterly while on-premise engagements extend across multi-year horizons. Understanding these velocity differences shapes provider resource allocation and client negotiation strategies.
Service Type:
Predictive analytics contracts refresh fastest as models require continuous retraining on new data streams. Reporting services exhibit the longest tenures, with multi-year master service agreements locking in standardized deliverables.
- Predictive Analytics:Machine learning models deployed for demand forecasting, churn detection, and risk scoring require monthly recalibration. Financial institutions in the United States and retail chains in Germany drive contract velocity through iterative model refinement cycles.
- Data Analysis:Statistical examination of structured and unstructured datasets supports operational decision-making. Healthcare providers in California and Texas concentrate demand for claims analysis and clinical outcome measurement.
- Reporting:Standardized dashboards and periodic performance summaries delivered under fixed-scope agreements. Enterprises prioritize cost predictability over analytical depth.
- Performance Management:KPI tracking and balanced scorecard implementations align workforce incentives with strategic objectives. Manufacturing clients in Japan deploy these for operational excellence programs.
Reporting dominates installed base. Predictive Analytics is where expansion concentrates.
Deployment:
Cost tier stratification separates capital-intensive infrastructure from elastic consumption models. SaaS offerings command premium per-seat pricing while hybrid deployments absorb the highest professional services fees.
- Cloud-Based:Elastic compute resources provisioned via HIPAA-certified and ISO 27001-compliant environments. United States healthcare systems and European financial institutions prioritize scalability over data residency controls.
- SaaS:Pre-configured analytics platforms with self-service interfaces and embedded machine learning. Mid-market retailers in France and regional healthcare networks in Texas adopt these within compressed implementation timelines.
- Hybrid:Split architectures maintaining sensitive data on-premise while pushing compute-intensive workloads to cloud infrastructure. Regulated industries facing GDPR cross-border restrictions favor this model.
- On-Premise:Dedicated server installations for environments with strict data localization mandates. German automotive suppliers and Japanese pharmaceutical manufacturers retain these for intellectual property protection.
On-Premise retains legacy footprint. Cloud-Based is climbing the fastest.
End User:
Application intensity varies by sector data maturity and regulatory exposure. Financial services generate the highest analytics spend per employee while healthcare lags in automation penetration.
- Finance:Credit scoring, fraud detection, and algorithmic trading analytics subject to SEC disclosure requirements and EU AI Act accountability mandates. Investment banks in New York and asset managers in London concentrate demand.
- Healthcare:Population health management, clinical decision support, and revenue cycle analytics operating under HIPAA and FDA data integrity oversight. Hospital systems in California and Texas lead outsourcing adoption.
- Retail:Demand forecasting, customer segmentation, and supply chain optimization. Omnichannel operators in Germany and France deploy real-time inventory models.
- Telecommunications:Network performance analytics and subscriber churn prediction. Mobile operators in Japan and South Korea leverage these for competitive retention.
Finance commands revenue concentration. Healthcare is gaining share fastest.
Solution:
Margin structure differentiates platform licensing from custom development. Dashboarding Tools extract recurring subscription revenue while Data Mining engagements bill hourly for specialized expertise.
- Business Intelligence:Enterprise-wide analytics platforms integrating multiple data sources for executive decision support. Fortune 500 manufacturers in Japan and Germany anchor deployments.
- Dashboarding Tools:Self-service visualization interfaces enabling business users to construct reports without IT intervention. Regional healthcare networks and mid-market retailers standardize on these for cost containment.
- Data Mining:Pattern recognition and anomaly detection across large-scale datasets requiring statistical expertise. Financial institutions deploy these for anti-money laundering and credit risk segmentation.
- Reporting Software:Automated generation of standardized financial, operational, and regulatory reports. Compliance-driven buyers in healthcare and banking prioritize audit trail functionality.
Reporting Software saturates mid-market penetration. Business Intelligence is where provider investment concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in United States healthcare and financial services contracts, while Indian delivery centers compress margins through lower-cost statistical modeling talent. European regulatory complexity around GDPR and the EU AI Act fragments contract structures across jurisdictions.
United States
Hospital systems in California and Texas drive HIPAA-compliant cloud analytics adoption for population health management. FDA oversight of clinical decision support tools shapes contracting terms for patient-facing applications. New York investment banks and asset managers concentrate demand for algorithmic trading and fraud detection analytics.
Germany
Automotive suppliers in Bavaria and Baden-Württemberg retain on-premise analytics for intellectual property protection alongside supply chain forecasting. The EU AI Act risk classification framework mandates conformity assessments for credit scoring automation. Frankfurt financial institutions delay full automation pending regulatory clarity on liability allocation.
United Kingdom
London-based asset managers and investment banks generate concentrated demand for SEC-disclosure-compliant risk analytics. GDPR cross-border transfer restrictions complicate multi-jurisdictional delivery models for European operations. The city's fintech cluster pilots real-time regulatory reporting automation.
India
Bangalore and Hyderabad delivery centers supply statistical modeling talent at cost structures below Western markets. Domestic IT services firms leverage this base for finance and accounting analytics exports. Mumbai financial services clients increasingly source predictive modeling through these captive centers.
Japan
Tokyo manufacturers deploy performance management analytics for operational excellence programs. METI industrial policy encourages cloud migration for mid-market enterprises. Osaka-based pharmaceutical manufacturers maintain hybrid architectures for data residency compliance.
BPO Business Analytics Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in data engineering and statistical modeling. The vendor base stratifies across consulting-led engagements, domain-specific workflow providers, and cloud-native platform vendors. Three archetypes dominate: heritage consultancies anchoring premium Fortune 500 contracts, India-originated IT services firms scaling through delivery center networks, and technology vendors embedding cognitive capabilities in hybrid architectures. Competitive moves concentrate on M&A for specialized data science talent and strategic partnerships for HIPAA-certified cloud infrastructure.
Within the heritage consultancy tier, Accenture leverages its consulting origins to anchor premium engagements. Genpact occupies a position exemplifying domain-specific workflow dominance in finance and accounting analytics. IBM represents the technology-embedded archetype through Watson-powered cognitive analytics integrated into hybrid cloud architectures. These three firms illustrate the competitive positioning spectrum without exhausting the vendor landscape.
| Leading Market Players |
|---|
| Accenture |
| IBM |
| Genpact |
| Cognizant |
| Wipro |
| TCS |
| Capgemini |
| Infosys |
| EXL Service |
| Others |
Cost & Logistics Intelligence
Undercapacity in HIPAA-certified cloud infrastructure across United States healthcare corridors is compressing project timelines and inflating configured-service premiums. Providers with idle GPU clusters in Bangalore and Hyderabad capture margin expansion while domestic buyers absorb scarcity-driven cost escalation.
Pricing Analysis
The customization-premium spread separates standard SaaS dashboarding from bespoke predictive modeling engagements. Subscription tiers stratify across self-service, managed analytics, and white-glove consulting bundles. ISO 27001 certification commands 15-25 percent premiums in financial services procurement. Price erosion runs through reporting software as automated platforms displace hourly professional services. Mid-market retailers exhibit highest price sensitivity; investment banks in New York and London demonstrate lowest.
Supply Chain Analysis
Extended payment terms from Fortune 500 buyers are forcing supply-chain finance facilities upon mid-tier analytics providers. Talent concentration in India, the United States, and Germany anchors delivery capacity. Cloud compute resources draw from hyperscaler infrastructure; proprietary model development rests on specialized GPU hardware; regulatory compliance tooling feeds from certification body partnerships. Single-source vulnerability concentrates in NVIDIA chip supply for training workloads. Distribution runs through direct enterprise sales, systems integrator partnerships, and cloud marketplace listings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent analytics providers face substitution pressure from automated machine learning platforms that compress the value chain from data preparation to deployment. Self-service interfaces threaten traditional hourly billing models.
For Market Incumbents: Pre-empt platform commoditization by embedding domain-specific workflows for HIPAA-compliant healthcare analytics and SEC-disclosure-grade financial risk modeling. Acquire specialized talent in explainable AI techniques to meet EU AI Act algorithmic accountability mandates. Anchor premium positioning through captive delivery centers in Bangalore and Hyderabad.
For New Entrants and Emerging Players: Pursue white-space opportunity in mid-market healthcare networks across Texas and California seeking usage-based population health analytics. Target regional retailers in France and Germany requiring real-time supply chain forecasting without enterprise-scale infrastructure commitments. Lead with serverless architectures that compress implementation cycles below six months.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native deployment models as serverless architectures eliminate dedicated data engineering overhead. Target acquisition profiles should emphasize providers with ISO 27001 certification and established HIPAA-compliant cloud frameworks. Monitor EU AI Act enforcement timelines as inflection indicator for European contract velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| HIPAA-Certified Cloud Infrastructure Partnership | Unlocks outsourced processing of patient claims data for United States hospital systems. |
| Acquisition of Explainable AI Specialist | Addresses EU AI Act audit requirements for automated credit and healthcare decisions. |
| Serverless Analytics Platform Launch | Compresses implementation timelines for mid-market retailers below traditional ETL pipelines. |
| India Delivery Center Expansion | Captures statistical modeling talent at cost structures below Western labor markets. |
| ISO 27001 Certification Investment | Differentiates providers for risk-averse financial services buyers in New York and London. |
Research Approach
A standing panel of chief data officers, healthcare informatics directors, financial services risk executives, and cloud procurement officers provided ongoing calibration across the study period. Primary fieldwork combined structured interviews with secondary validation from SEC filings, HIPAA enforcement actions, EU regulatory databases, and hyperscaler capex disclosures. Bottom-up contract value aggregation triangulated against top-down market sizing from industry association reports.
Scenario bracketing bounded projections across regulatory enforcement intensity and cloud adoption velocity variations. Segmentation dimensions modeled deployment architecture, service type complexity, end-user industry, and geographic regulatory cluster. CAGRs derived from fitted growth curves anchored to disclosed contract values and vendor revenue disclosures. Forecast inputs incorporated HIPAA migration timelines and EU AI Act implementation schedules.
Macroeconomic conditions sit as an overlay; deviation in interest rate trajectories or enterprise IT budget cycles would shift the trajectory. Forecasts reflect documented assumptions around regulatory enforcement timelines and cloud infrastructure availability. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Business Process Outsourcing (BPO)
Call Center Outsourcing Market
Business Process Outsourcing (BPO)
Payroll Outsourcing Services Market
Business Process Outsourcing (BPO)
Document Outsourcing Services Market
Business Process Outsourcing (BPO)
Global Contact and Call Center Outsourcing Market
Business Process Outsourcing (BPO)
Global IT Outsourcing Services Market
Business Process Outsourcing (BPO)
IT Outsourcing Market
Business Process Outsourcing (BPO)
Desktop Outsourcing Market
Business Process Outsourcing (BPO)
US Managed Print Services Market
Business Process Outsourcing (BPO)
Global Cloud Bpo Market
Business Process Outsourcing (BPO)
Business Process Automation (BPA) Market
Business Process Outsourcing (BPO)
Data Entry Service Market
Business Process Outsourcing (BPO)
United States IT Outsourcing Market
Business Process Outsourcing (BPO)
Cloud Based BPO Market
Business Process Outsourcing (BPO)
Life Sciences BPO Market
Business Process Outsourcing (BPO)
Global Outsourced Sales Service Market
Business Process Outsourcing (BPO)
Asia-Pacific Business Process As a Service (Bpaas) Market