
 South America AUV and ROV Market | 2026-2036
South America AUV and ROV Market Size, Share, and Industry Trends Forecast 2026-2036
South America AUV and ROV Market Analytics
Service contractor networks across Brazil, Guyana, and Argentina are reshaping how underwater vehicle fleets reach end users. DOF Subsea AS leverages its integrated vessel and robotics fleet to control project delivery from port to seabed. Fugro NV anchors its position through specialized geophysical survey capabilities and permanent reservoir monitoring installations. Subsea 7 SA competes by bundling ROV services within larger SURF contracts, reducing client procurement complexity.
Autonomous underwater vehicles and remotely operated vehicles are self-propelled or tethered subsea systems operating at depths from shallow coastal zones to beyond 3,000 meters, equipped with sonar arrays, manipulator arms, and high-definition imaging payloads for seabed intervention and data collection. The primary commercial purpose centers on inspecting, maintaining, and installing subsea infrastructure without deploying human divers. ROV systems dominate current revenue owing to their established role in offshore oil and gas intervention work, while autonomous navigation technology represents the fastest-expanding capability segment as operators seek to reduce vessel-day costs and surface support requirements. Energy companies constitute the deepest end-user pool, though environmental monitoring applications are gaining structural importance as regulatory disclosure obligations expand across the continent.
Brazil's ANP imposes mandatory pipeline inspection protocols that directly stimulate ROV utilization rates, while Guyana's emerging petroleum regulator applies international subsea safety standards adapted from the US Gulf of Mexico framework. ANVISA in Brazil and equivalent functional regulators in neighboring jurisdictions shape equipment certification pathways for instruments contacting marine ecosystems. Stakeholders must monitor how autonomous navigation regulations evolve, as permitting frameworks for fully untethered operations remain undefined across most South American maritime jurisdictions and will determine competitive positioning for next-generation system deployments.
Market Dynamics
ANP inspection mandates are compressing project timelines for Brazil's pre-salt operators, forcing faster ROV mobilization cycles and accelerating autonomous system trials as vessel-day costs become unsustainable at current intervention frequencies.
Growth Catalysts
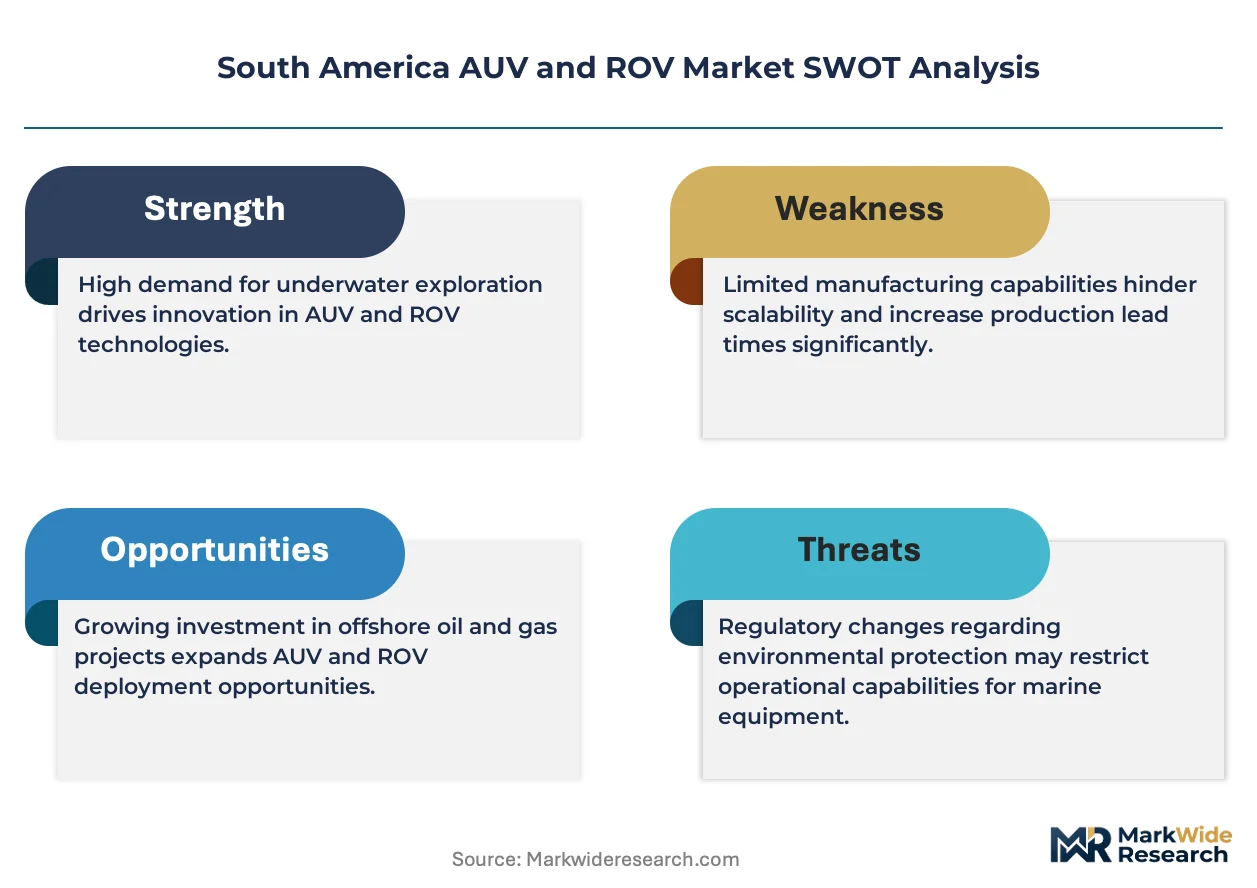
- Pre-salt basin complexity:Brazil's ultra-deepwater fields require persistent seabed intervention that exceeds human diver limits, creating structural dependency on tethered and autonomous systems for integrity management.
- Guyana's regulatory framework:The emerging petroleum authority applies Gulf of Mexico-derived subsea safety standards that mandate continuous infrastructure monitoring, directly stimulating ROV fleet expansion.
- Autonomous navigation maturation:Lithium-polymer energy density improvements and acoustic positioning refinement enable untethered operations that slash surface support requirements for pipeline survey campaigns.
Market Restraints
- Specialized vessel scarcity:Brazil controls fewer than twelve dynamically positioned support vessels capable of launching work-class ROVs below 2,000 meters, concentrating project scheduling power with integrated service contractors.
- Titanium alloy supply concentration:Pressure-resistant housings for full-ocean-depth systems depend on forgings from a limited supplier base in East Asia, exposing procurement timelines to geopolitical friction.
- Permitting ambiguity for autonomous operations:ANP has not issued formal guidelines for unsupervised AUV transit through active production corridors, creating liability uncertainty that delays fleet investment.
Strategic Opportunities
- Argentine offshore frontier:The North Malvinas basin remains underexplored with minimal existing subsea infrastructure, offering first-mover positioning for inspection service providers as exploration licensing accelerates.
- Environmental disclosure mandates:Brazil's ICMBio and equivalent agencies in Colombia and Peru are expanding marine impact reporting requirements, opening recurring revenue streams for benthic monitoring AUV deployments.
- Resident vehicle architectures:Seabed docking stations paired with autonomous charging systems enable continuous presence without surface vessel tethering, converging robotics and subsea infrastructure design disciplines.
Industry Challenges
- Subsea robotics technician shortage:Brazil's technical institutes produce fewer than eighty certified ROV pilots annually, creating recruitment bottlenecks as pre-salt activity intensifies.
- ANVISA marine equipment certification:Biocide-treated umbilicals and pressure-compensated electronics face eighteen-month approval timelines that delay project commissioning.
- Legacy vessel integration:Older Brazilian support ships lack sufficient deck power and crane capacity for next-generation electric work-class systems, forcing costly retrofits or charter substitutions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America AUV and ROV Market |
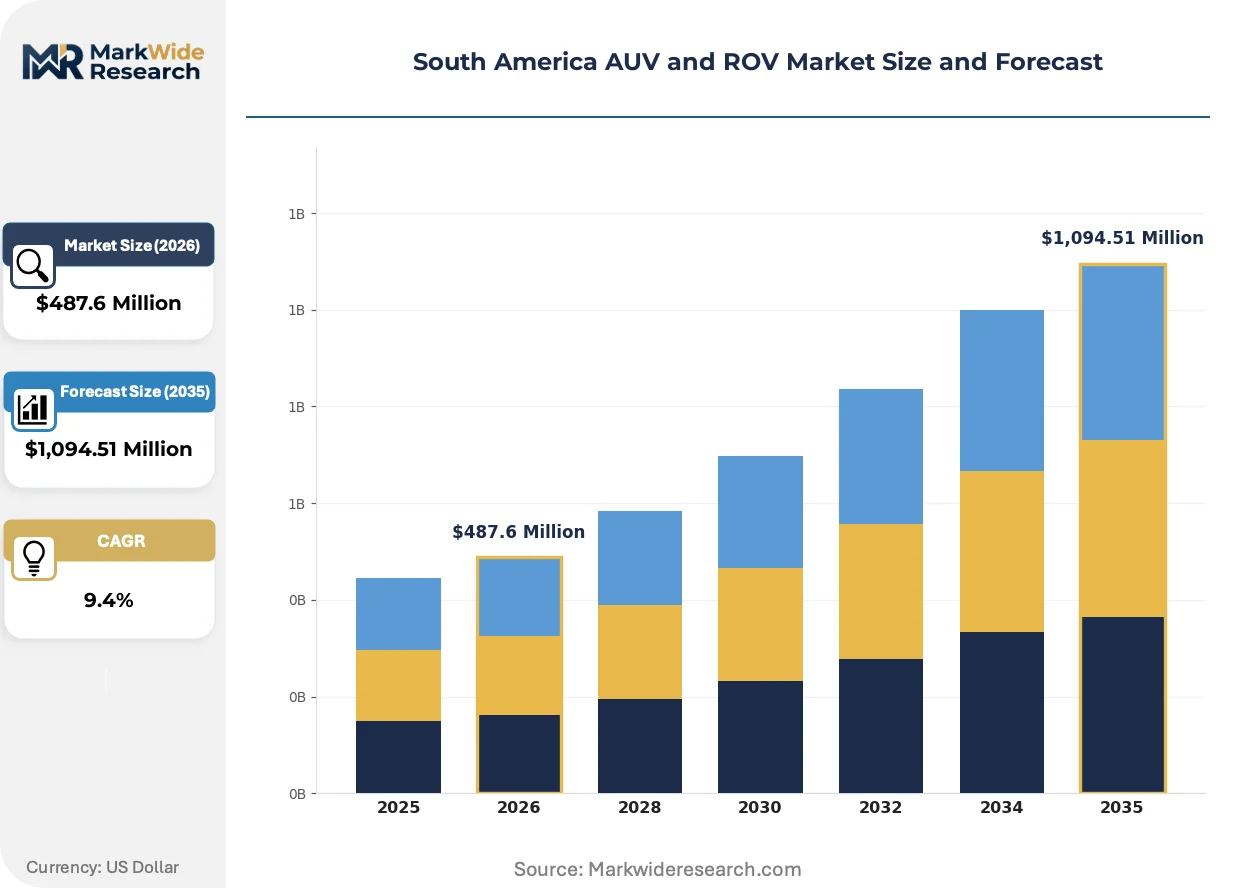
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,094.51 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AUV, ROV, Mini-ROV, Inspection Class ROV Application: Oil & Gas, Aquaculture, Environmental Monitoring, Defense End User: Government, Research Institutions, Marine Contractors, Energy Companies Technology: Autonomous Navigation, Remote Control, Sonar Systems, Imaging Technology |
| Companies Covered | DOF Subsea AS, Fugro NV, Subsea 7 SA, Saipem SpA, Oceaneering International Inc., TechnipFMC PLC, DeepOcean AS, Helix Energy Solutions Group Inc., Bourbon, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America AUV and ROV Market Evolving Landscape
Autonomous docking infrastructure and AI-driven acoustic analytics are separating inspection economics from vessel-dependency, while regulatory pressure on continuous monitoring compresses the viable window between manual interventions.
Hybrid autonomous-tethered architectures combine resident seabed docking stations with fiber-optic tethers for high-bandwidth intervention tasks, enabling selective human oversight without permanent surface presence. Petrobras and ExxonMobil Guyana are piloting these configurations for pre-salt wellhead monitoring. The technology is rendering obsolete the traditional model of vessel-tethered ROV operations for routine visual inspection cycles.
ANP's 2024 technical bulletin on pipeline integrity management tightens maximum allowable inspection intervals for high-pressure gas export lines, effectively mandating continuous or near-continuous monitoring capability. Operators must now demonstrate real-time anomaly detection or face production curtailment. Brazil's pre-salt cluster faces the steepest compliance cost escalation, driving capital allocation toward autonomous resident systems over vessel-based campaigns.
Service contract unbundling is fragmenting procurement as national oil companies separate ROV services from integrated SURF packages to capture transparency on day-rate economics. This disintermediation favors specialized robotics contractors with direct vessel relationships over construction-heavy conglomerates. The shift is most pronounced in Guyana, where the petroleum regulator requires line-item cost disclosure for all subsea service contracts.
South America AUV and ROV Market Segmentation
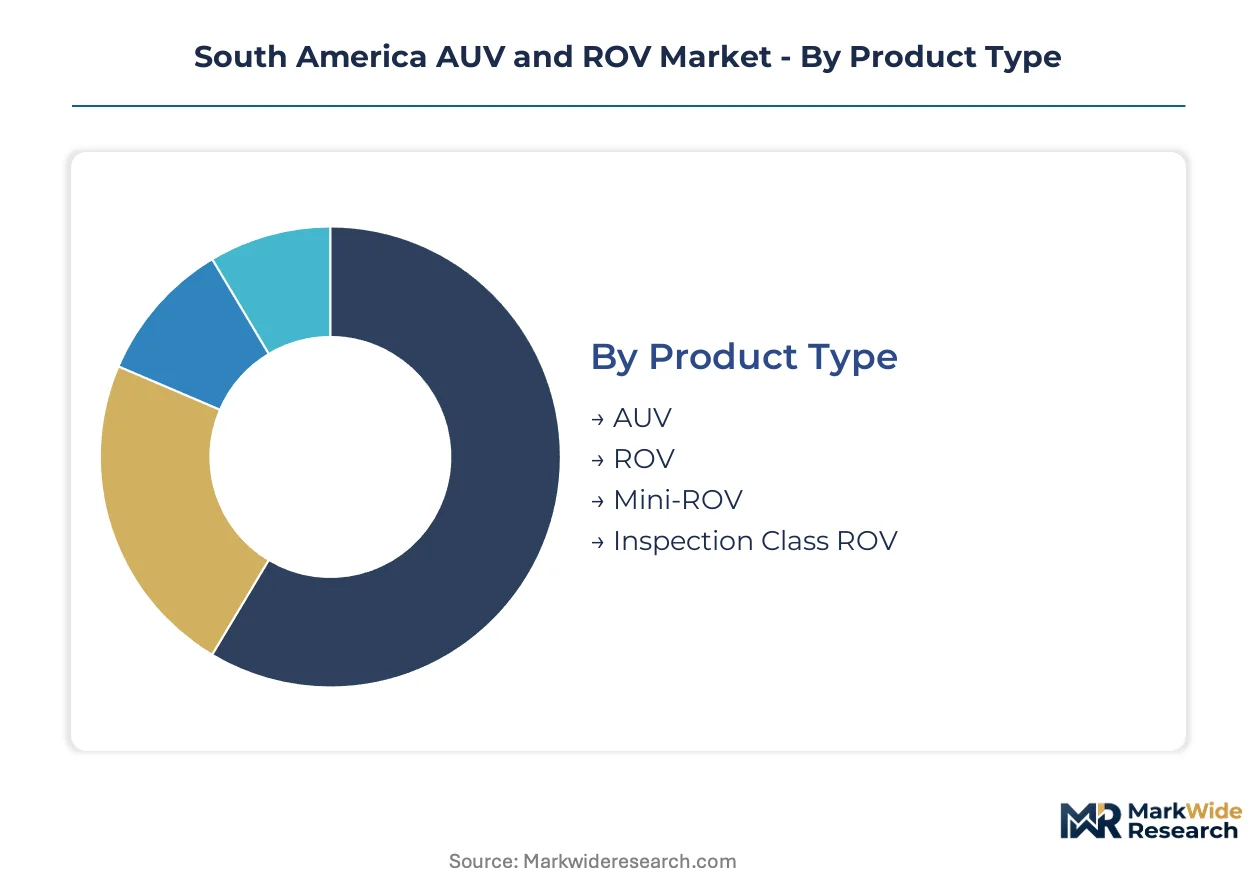
Segmentation reveals how divergent technical requirements and regulatory pressures fragment procurement patterns across South America's subsea service economy. Understanding these divides explains why integrated contractors and specialized robotics firms pursue fundamentally different fleet strategies.
Product Type:
Mature tethered systems dominate current revenue while autonomous architectures reshape long-term capital planning for pre-salt operators.
- ROV:Tethered work-class systems with hydraulic manipulators and 3000-meter depth ratings anchor Brazil's pipeline inspection mandates. Petrobras and ExxonMobil Guyana deploy these for wellhead intervention where real-time human control remains non-negotiable under ANP safety protocols.
- AUV:Untethered lithium-polymer platforms with synthetic aperture sonar slash vessel-day requirements for corridor surveys. Pre-salt operators trial these for repetitive pipeline monitoring where autonomous navigation reduces surface support costs below economically viable thresholds for tethered alternatives.
- Mini-ROV:Portable electric systems under 50 kilograms serve aquaculture net inspection and shallow environmental baseline studies where mobilization speed outweighs depth capability.
- Inspection Class ROV:Light work-class configurations balance observation payload capacity with reduced deck footprint for marginal field campaigns in Argentina's North Malvinas basin.
ROV retains volume leadership; AUV holds the steepest expansion curve.
Application:
Cost tier differentiation separates capital-intensive energy infrastructure from recurring service contracts in environmental compliance.
- Oil & Gas:Subsea installation, intervention, and decommissioning absorb the majority of work-class ROV utilization. Brazil's pre-salt cluster and Guyana's Stabroek block generate concentrated demand for ultra-deepwater capable systems where day rates justify specialized vessel charter.
- Environmental Monitoring:Benthic habitat mapping and discharge compliance surveys expand AUV deployment as ICMBio and regional agencies tighten marine impact disclosure requirements. Recurring survey obligations create subscription-like revenue streams distinct from project-based oilfield contracting.
- Aquaculture:Net integrity inspection and predator monitoring in Chilean salmon operations utilize mini-ROV systems with simplified pilot certification requirements.
- Defense:Mine countermeasures and harbor security applications remain nascent across South American navies with limited procurement budgets for underwater robotics.
Oil & Gas commands premium pricing; Environmental Monitoring is gaining share fastest.
End User:
Customer type determines procurement complexity, with state-owned energy companies imposing vendor qualification burdens that exclude smaller robotics specialists.
- Energy Companies:Integrated operators like Petrobras and consortium partners in Guyana specify equipment standards, pilot certification, and vessel integration requirements that shape contractor fleet investment decisions. Their bundled SURF contracts historically absorbed ROV services, though unbundling trends now separate robotics procurement.
- Marine Contractors:DOF Subsea and specialized inspection firms operate as service intermediaries, controlling vessel access and technician labor pools that determine project execution capacity.
- Government:Naval and environmental agencies drive standardized procurement with extended tender timelines and local content requirements that favor established suppliers with Brazilian-registered entities.
- Research Institutions:Universities and oceanographic centers deploy AUVs for academic surveys with funding cycles and equipment specifications distinct from commercial oilfield standards.
Energy Companies retain volume leadership; Marine Contractors hold the steepest expansion curve.
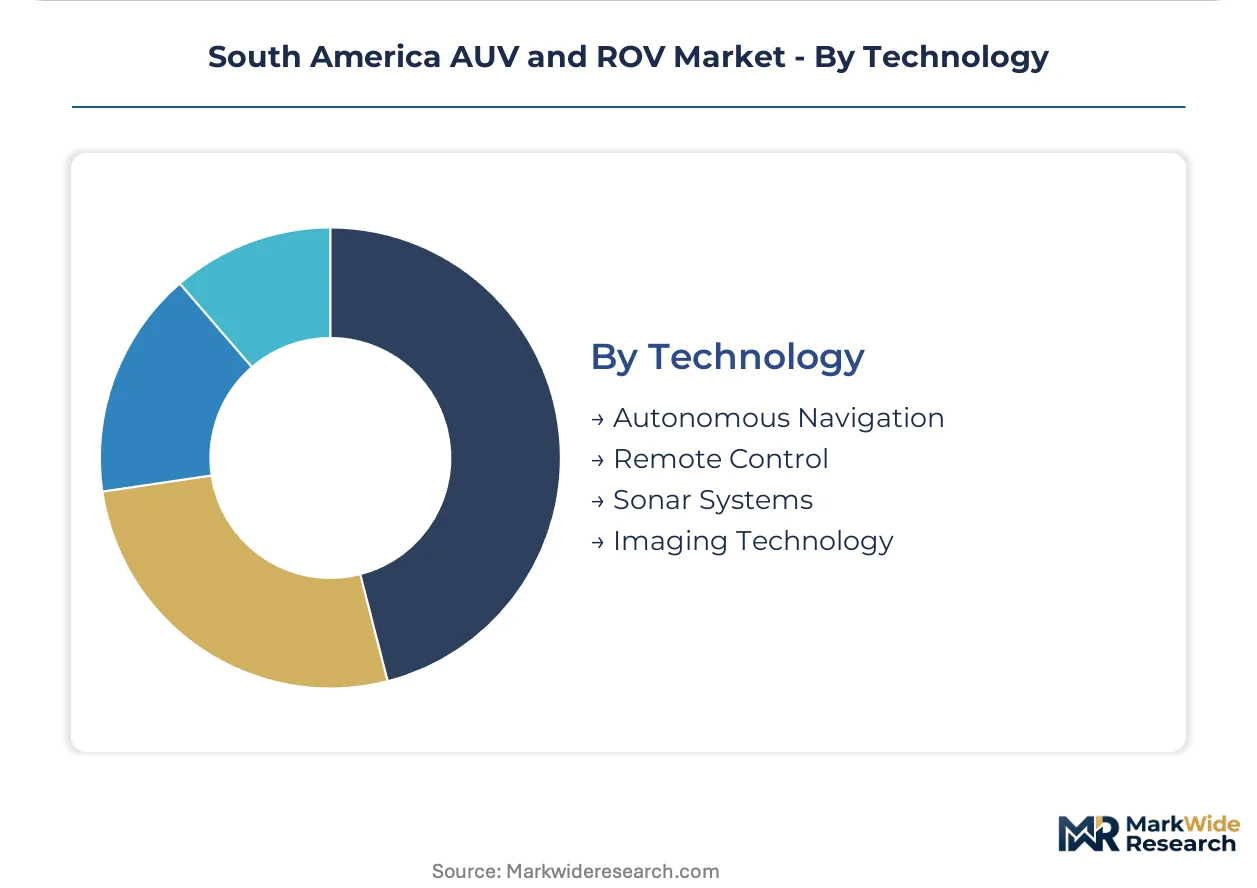
Technology:
Supply concentration in acoustic positioning and imaging subsystems creates vendor lock-in for critical navigation and perception components.
- Autonomous Navigation:Inertial measurement units fused with Doppler velocity logs enable dead-reckoning positioning where GPS surface fixes are unavailable. ANP permitting ambiguity for unsupervised transit through active production corridors delays fleet-scale deployment despite technical maturation.
- Imaging Technology:4K video and laser line scanning deliver inspection data quality that satisfies pipeline integrity assessment standards. Petrobras specifies minimum resolution and lighting thresholds that drive payload specification across contractor fleets.
- Sonar Systems:Multibeam and side-scan configurations provide bathymetric and seabed characterization for route surveys and debris clearance.
- Remote Control:Fiber-optic tether telemetry and pilot interface systems remain the default for intervention tasks requiring real-time manipulator operation.
Remote Control retains volume leadership; Autonomous Navigation holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ANP regulatory mandates and Guyana's emerging petroleum authority are redistributing subsea robotics demand across South American maritime zones. National inspection protocols and basin-specific depth requirements fragment procurement patterns between established pre-salt operators and frontier exploration blocks.
Brazil
Pre-salt basin complexity drives structural demand for ultra-deepwater ROV systems at depths exceeding 2,000 meters. ANP pipeline integrity protocols compress inspection intervals for high-pressure gas export lines. Rio de Janeiro anchors contractor fleet concentration, with integrated service providers controlling dynamically positioned vessel access for Petrobras campaigns.
Guyana
Stabroek block development generates concentrated demand for work-class intervention systems as production infrastructure scales. The petroleum regulator applies Gulf of Mexico-derived subsea safety standards mandating continuous infrastructure monitoring. Georgetown serves as logistics coordination hub for ExxonMobil-led consortium robotics procurement.
Argentina
North Malvinas basin exploration licensing accelerates frontier inspection requirements with minimal existing subsea infrastructure. The national hydrocarbons regulator imposes environmental baseline survey obligations for offshore drilling permits. Buenos Aires province concentrates marine contractor technical staffing for southern basin campaigns.
Chile
Aquaculture net inspection and shallow environmental monitoring create mini-ROV demand distinct from oilfield contracting. Subsecretaría de Pesca y Acuicultura mandates periodic containment integrity verification for salmon farming concessions. Los Lagos region clusters aquaculture robotics deployment for coastal lease operations.
Colombia
Caribbean offshore exploration revives as licensing rounds attract international operators to deepwater blocks. ANLA environmental licensing requirements mandate benthic impact assessment prior to drilling authorization. Cartagena hosts service contractor staging for Caribbean basin survey campaigns.
South America AUV and ROV Market Competitive Landscape
On the supply side, the industry is consolidating around integrated vessel operators with captive robotics fleets and specialized geophysical contractors with permanent reservoir monitoring capabilities. Three archetypes dominate: construction-heavy conglomerates bundling ROV services within SURF contracts, independent subsea service specialists controlling vessel access and technician labor pools, and geophysical survey firms anchoring position through seabed data analytics. Competitive moves concentrate on fleet standardization around electric work-class systems and strategic partnerships to secure dynamically positioned vessel capacity.
Among Norway-based integrated operators, DOF Subsea AS and DeepOcean AS exemplify the vessel-anchored archetype controlling project delivery from port to seabed. Netherlands-headquartered Fugro NV occupies a distinct position within geophysical specialization, representing the survey-centric competitive vector. These three entities illustrate how supply-side configuration fragments between construction-integrated bundling and independent service provision.
| Leading Market Players |
|---|
| DOF Subsea AS |
| Fugro NV |
| Subsea 7 SA |
| Saipem SpA |
| Oceaneering International Inc. |
| TechnipFMC PLC |
| DeepOcean AS |
| Helix Energy Solutions Group Inc. |
| Bourbon |
| Others |
Value Network & Pricing Analysis
Rio de Janeiro's concentration of dynamically positioned support vessels concentrates scheduling leverage among integrated contractors, translating port-access scarcity into premium day-rate positioning for ultra-deepwater ROV campaigns. ANP-mandated inspection frequency compresses project timelines, amplifying vessel-availability premiums and forcing operators toward autonomous alternatives as tethered economics become unsustainable.
Pricing Analysis
Certification level (ANVISA-grade marine equipment approval) creates the primary spread between premium and standard tiers, with eighteen-month approval timelines for pressure-compensated electronics justifying substantial markups over non-certified alternatives. Project-based contracting dominates, bundling vessel, technician, and robotics deployment into single-source arrangements that obscure line-item transparency. Cost compression in standard work-class ROV tiers is intensifying as service contract unbundling exposes day-rate economics to competitive scrutiny. National oil companies exhibit lowest price sensitivity due to regulatory compliance mandates, while independent marine contractors face acute margin pressure from vessel charter obligations.
Supply Chain Analysis
Export-control restrictions on acoustic positioning systems and inertial measurement units limit technology flows from US and European defense-linked suppliers to South American end users. Manufacturing concentration in Norway, the Netherlands, and Singapore for work-class ROV platforms draws from titanium alloy forgings, lithium-polymer battery cells, and synthetic aperture sonar arrays. Single-source vulnerability in East Asian titanium forging capacity exposes procurement timelines to geopolitical friction. Distribution runs through integrated vessel operators controlling port-to-seabed project delivery rather than equipment resale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The South America AUV and ROV market is recovering from cyclical lows as pre-salt basin development and Guyanese offshore expansion reactivate capital deployment. Brazilian ANP mandates for pipeline integrity assessment provide the cyclical floor, institutionalizing robotics utilization regardless of oil price volatility.
For Market Incumbents: Build technical labor moats by expanding captive ROV pilot training programs beyond Brazil's current output of fewer than eighty certified technicians annually. Acquire Argentine-registered entities to secure first-mover positioning in North Malvinas basin licensing rounds. ANVISA certification bottlenecks threaten margin compression; backward integration into pressure-housing fabrication reduces forgings procurement exposure.
For New Entrants and Emerging Players: Build out environmental monitoring service capabilities targeting ICMBio-mandated benthic surveys as the most penetrable segment outside oilfield contracting. Chilean aquaculture mini-ROV inspection offers recurring revenue with simplified pilot certification requirements. Partner with regional universities for AUV research program sponsorships that convert to commercial procurement relationships.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized geophysical contractors with permanent reservoir monitoring installations over construction-heavy conglomerates. Long-term viability hinges on autonomous navigation maturation and permitting clarity from ANP. Watch for ANP formal guidelines on unsupervised AUV transit through active production corridors as the inflection signal for fleet-scale capital deployment.
| Strategic Initiative | Industry Significance |
|---|---|
| Autonomous Docking Infrastructure Deployment | Seabed charging stations enable continuous resident vehicle presence without surface vessel tethering. |
| Electric Work-Class Fleet Standardization | Next-generation electric systems reduce deck power requirements and extend operational depth ratings. |
| Argentine Entity Establishment | North Malvinas basin licensing acceleration demands locally registered service providers. |
| ANVISA Certification Pipeline Investment | Eighteen-month approval timelines for marine equipment create competitive moats for prepared filers. |
| Environmental Monitoring Service Expansion | ICMBio disclosure mandates generate recurring benthic survey contracts distinct from oilfield project cycles. |
Research Methodology
Initial hypotheses were tested against primary input from ROV operations managers, subsea robotics technicians, ANP regulatory affairs specialists, and integrated vessel chartering executives, then refined through secondary validation across SEC filings from listed service contractors, ANP technical bulletins on pipeline integrity protocols, Brazilian customs data on robotics equipment imports, and academic publications on autonomous underwater navigation. Bottom-up demand modeling from individual pre-salt field inspection schedules was triangulated against top-down market sizing from vessel fleet utilization rates.
Demand-supply balance dynamics across the analysis window were modeled through segmentation by product architecture (tethered work-class, autonomous lithium-polymer, mini-ROV), application intensity (oil and gas intervention versus environmental compliance), and end-user procurement complexity (state-owned energy companies versus independent contractors). CAGRs were derived from regression analysis of historical vessel-day pricing and projected autonomous system penetration curves, incorporating ANP regulatory mandate timelines and Guyana petroleum authority framework adoption rates as industry-specific demand drivers.
Stress conditions across titanium alloy supply disruption, ANP permitting delays for autonomous operations, and Brazilian vessel availability constraints were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and lithium-polymer energy density improvement trajectories. Material shifts in ANP autonomous navigation guidelines or East Asian export control expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Smart Sweeper Market
Robotics and Automation
Automated Facade Contact Cleaning Robot Market
Robotics and Automation
Robotic Lawn Mower Market
Robotics and Automation
Cognitive Robotics Market
Robotics and Automation
Household Cleaning Robotics Market
Robotics and Automation
Global Entertainment Robots Market
Robotics and Automation
Cordless Router Market
Robotics and Automation
Global Automotive Gesture Recognition System Market
Robotics and Automation
Mobile Cobots Market
Robotics and Automation
Cloud Robotics Market
Robotics and Automation
Lab Robotics Market
Robotics and Automation
Global IT Robotic Automation Market
Robotics and Automation
Service Robotics Market
Robotics and Automation
Micro Robots Market
Robotics and Automation
AGV Dispatch Management Platforms Market
Robotics and Automation
Africa Cloud Robotics Market